
 Saudi Arabia PE Pipes Market | 2026-2036
Saudi Arabia PE Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia PE Pipes Market Intelligence
Modular pipe bundling with pre-assembled fittings and joint systems is broadening procurement options for EPC contractors. Saudi Arabian Amiantit Company leverages integrated manufacturing across pipe and fitting lines to sustain project delivery timelines. Alwasail Industrial Company anchors its position through specialized high-density polyethylene production for water transmission networks. Arabian Gulf Manufacturers Ltd. competes on geographic proximity to Jubail industrial cluster demand.
Polyethylene pipes are thermoplastic conduits extruded from high-density or medium-density polyethylene resins, typically rated by standard dimension ratio and pressure class for fluid conveyance. Their fusion-welded joints deliver leak-free performance across buried water, sewage, and gas distribution infrastructure. Pressure Pipes command the dominant share due to potable water network specifications under Saudi Vision 2030, while Microducts represent the fastest-expanding category from telecom fiber deployment. Gravity Pipes retain mature demand in municipal sewage collection where trench installation methods prevail.
SASO technical regulations mandate polyethylene pipe compliance with specific density and hydrostatic strength benchmarks for construction material approval. SFDA oversight extends to potable water contact applications, reinforcing barrier-layer requirements that shape product formulation decisions. Municipalities and contractors must monitor evolving SASO standards alignment with international ISO protocols to ensure continued market access.
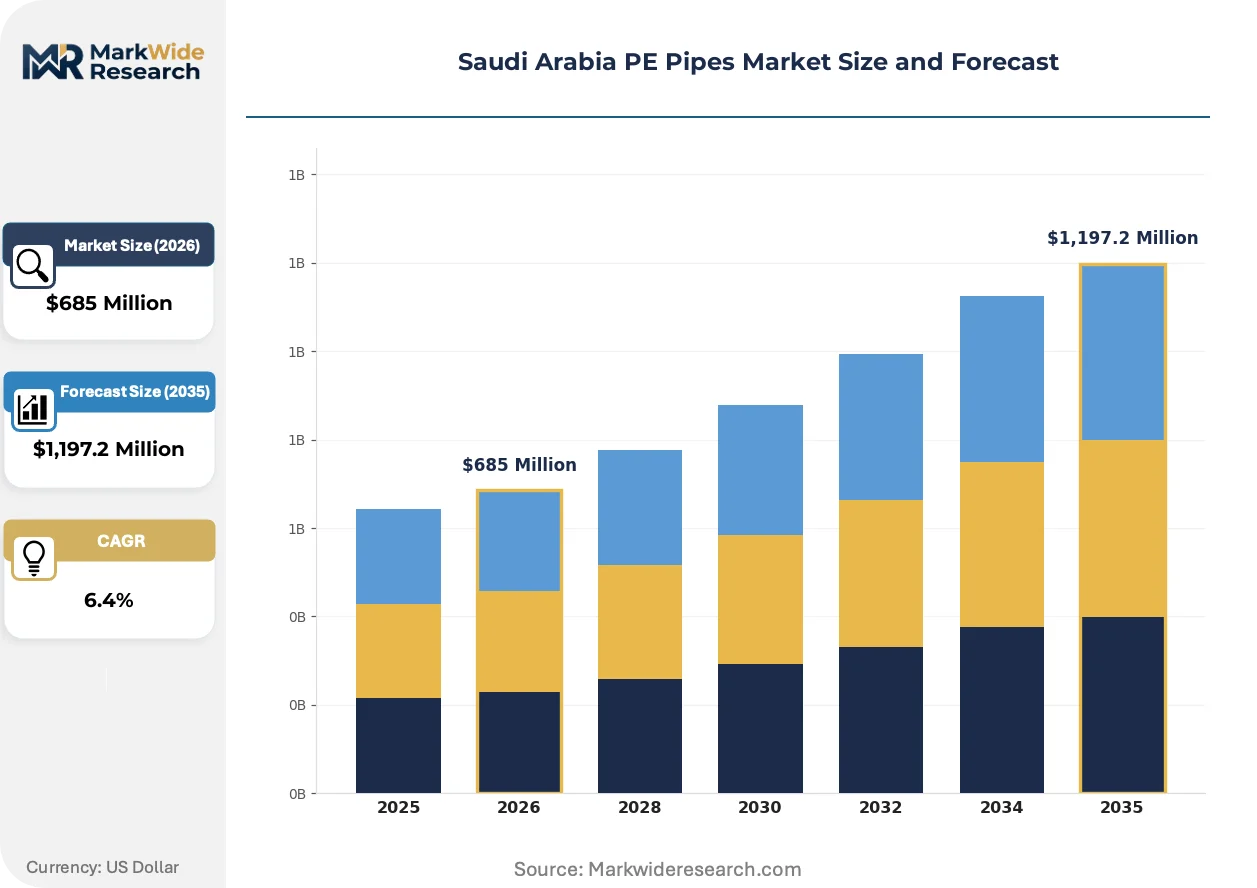
Market Dynamics
SASO technical regulations and SFDA potable water mandates are compressing product certification timelines while Vision 2030 infrastructure commitments pull volume forward. This regulatory-demand tension defines current competitive positioning.
Growth Catalysts
- Water infrastructure mandates:Saudi Vision 2030 potable water network expansion creates sustained procurement pull for pressure-rated polyethylene systems across municipal transmission projects.
- SFDA barrier-layer requirements:Potable water contact regulations tighten material formulation standards, favoring producers with integrated compound-to-pipe manufacturing control.
- Eastern Province cluster concentration:Jubail industrial zone proximity to mega-project sites reduces logistics friction for large-diameter pipe deliveries.
Market Restraints
- Ethylene feedstock volatility:Crude-linked naphtha and ethane pricing swings compress margin predictability for domestic extrusion operations.
- HDPE resin supply concentration:Regional polymer production centers in Jubail and Yanbu create geographic dependency for high-density grades.
- Trenchless installation technical limits:Horizontal directional drilling specifications cap pipe diameter adoption in dense urban Riyadh corridors.
Strategic Opportunities
- NEOM linear city development:The giga-project's integrated utility corridors demand specialized microduct and pressure pipe bundles for smart city infrastructure.
- Telecom fiber convergence:5G backbone deployment is fusing traditional water pipe procurement with communications conduit specifications.
- SASO-ISO alignment:Standards harmonization creates export pathway expansion for Saudi-certified producers into GCC neighboring markets.
Industry Challenges
- Butt-fusion technician certification:SASO-mandated welder qualification timelines extend project mobilization periods for EPC contractors.
- Legacy asbestos-cement replacement:Municipal reticulation system upgrades require pipe diameter matching and flow rate recalculation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia PE Pipes Market |
| Market Size in 2026 | $685 Million |
| Market Size in 2035 | $1,197.2 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Pipes, Gravity Pipes, Microducts, Fittings End User: Construction, Agriculture, Water Supply, Industrial Application: Potable Water Distribution, Sewage Systems, Irrigation, Gas Distribution Size: 25mm, 32mm, 63mm, 110mm |
| Companies Covered | Al Jubail Sanitary Pipe Factory, Arabian Gulf Manufacturers Ltd., Saudi Plastic Products Company Ltd. (SAPPCO), IKK Group, Al Tamam Modern Plastic Factory, Saudi Arabian Amiantit Company, Saudi Hepco LLC, Al-Munif Factory Company, Alwasail Industrial Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia PE Pipes Market Strategic Shifts & Innovations
Material science advances and installation method evolution are compressing project delivery cycles while regulatory alignment is opening cross-border certification pathways. These forces are restructuring how specifications travel from engineer to site.
Co-extruded barrier-layer HDPE is rewriting potable water pipe construction. Municipal water authorities in Riyadh and Jeddah are specifying five-layer structures for transmission mains. This material architecture is compressing the competitive set to compounders with in-house multilayer extrusion capability.
SASO's 2024 technical regulation alignment with ISO 4427 is tightening hydrostatic strength testing protocols. Domestic manufacturers must retest existing product lines against revised long-term performance benchmarks. Pressure pipe grades face the steepest recertification burden, with some producers accelerating compound reformulation to maintain construction material approval status.
EPC contractors are unbundling pipe-fitting-joint packages into component-level procurement. This disaggregation is compressing traditional bundled supply relationships. The Eastern Province mega-project corridor shows the most visible shift, with contractors sourcing fittings separately to optimize inventory turns across phased construction schedules.
Saudi Arabia PE Pipes Market Segmentation
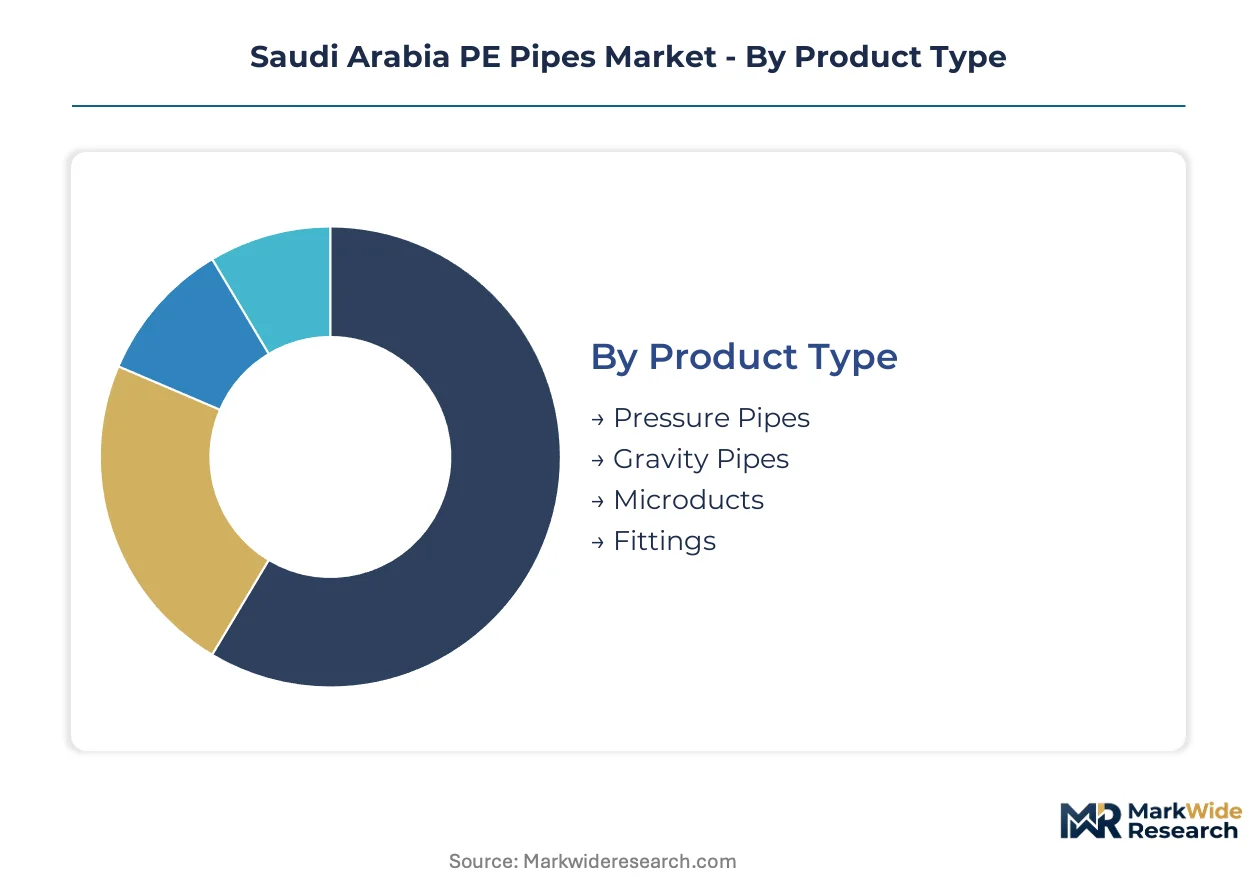
Segmentation in the Saudi PE pipes market reflects how procurement specifications diverge across infrastructure mandates, installation methods, and pressure requirements. Buyers prioritize different performance attributes depending on whether they serve municipal water authorities, agricultural cooperatives, or industrial zone developers.
Product Type:
Contractors distinguish procurement by pressure rating and joint complexity, with fusion-welded systems commanding premium specifications over push-fit alternatives.
- Pressure Pipes:Engineered from HDPE resins with standard dimension ratios optimized for sustained internal pressure, these systems dominate municipal transmission mains under Saudi Vision 2030 water infrastructure commitments. Riyadh municipality specifications favor SDR 11 and SDR 17 grades for buried distribution networks where leak-free performance is non-negotiable.
- Microducts:Small-diameter HDPE conduits designed for fiber optic cable protection, these products are expanding most quickly from NEOM and Red Sea Project telecom backbone deployments. The giga-projects' integrated utility corridors bundle microducts with water pipes, creating combined procurement specifications that favor manufacturers with co-extrusion flexibility.
- Gravity Pipes:Non-pressure PE systems for sewage collection where trench installation and ring stiffness govern specification.
- Fittings:Injection-molded or fabricated joint components including elbows, tees, and reducers that complete fusion-welded systems.
Pressure Pipes leads volumes today; Microducts is gaining share fastest.
End User:
Volume concentration varies sharply by customer capital deployment cycles and project pipeline visibility.
- Water Supply:Municipal transmission and distribution authorities in Riyadh, Jeddah, and the Eastern Province constitute the anchor demand pool, with SASO-certified pressure systems specified for potable water contact under SFDA oversight. These buyers operate on multi-year procurement frameworks tied to Vision 2030 network expansion targets.
- Construction:EPC contractors executing mega-projects across NEOM, Qiddiya, and Red Sea developments source bundled pipe-fitting packages where delivery reliability outweighs unit cost optimization.
- Agriculture:Farm cooperatives and irrigation districts in Al-Qassim and Tabuk regions specify medium-density PE for buried drip irrigation laterals.
- Industrial:Jubail and Yanbu petrochemical complexes procure specialized PE systems for process water and cooling circuits.
Water Supply dominates procurement value; Construction is expanding most quickly.
Application:
Fluid conveyed and regulatory contact requirements determine material formulation and barrier-layer specifications.
- Potable Water Distribution:SFDA-mandated barrier-layer HDPE systems with five-layer co-extruded construction prevent contaminant migration in Riyadh and Jeddah transmission mains. These applications face the steepest recertification burden under SASO's alignment with ISO 4427 protocols.
- Sewage Systems:Gravity-flow collection networks in dense urban corridors specify corrugated or solid-wall PE where trench installation methods prevail and ring stiffness ratings govern selection.
- Irrigation:Agricultural water conveyance in central and northern regions employs medium-density PE where pressure ratings are modest and cost efficiency dominates.
- Gas Distribution:PE100 and PE80 grades for buried natural gas reticulation, subject to separate SASO technical regulations for hydrocarbon service.
Potable Water Distribution leads specification complexity today; Sewage Systems is climbing the fastest from legacy asbestos-cement replacement programs.
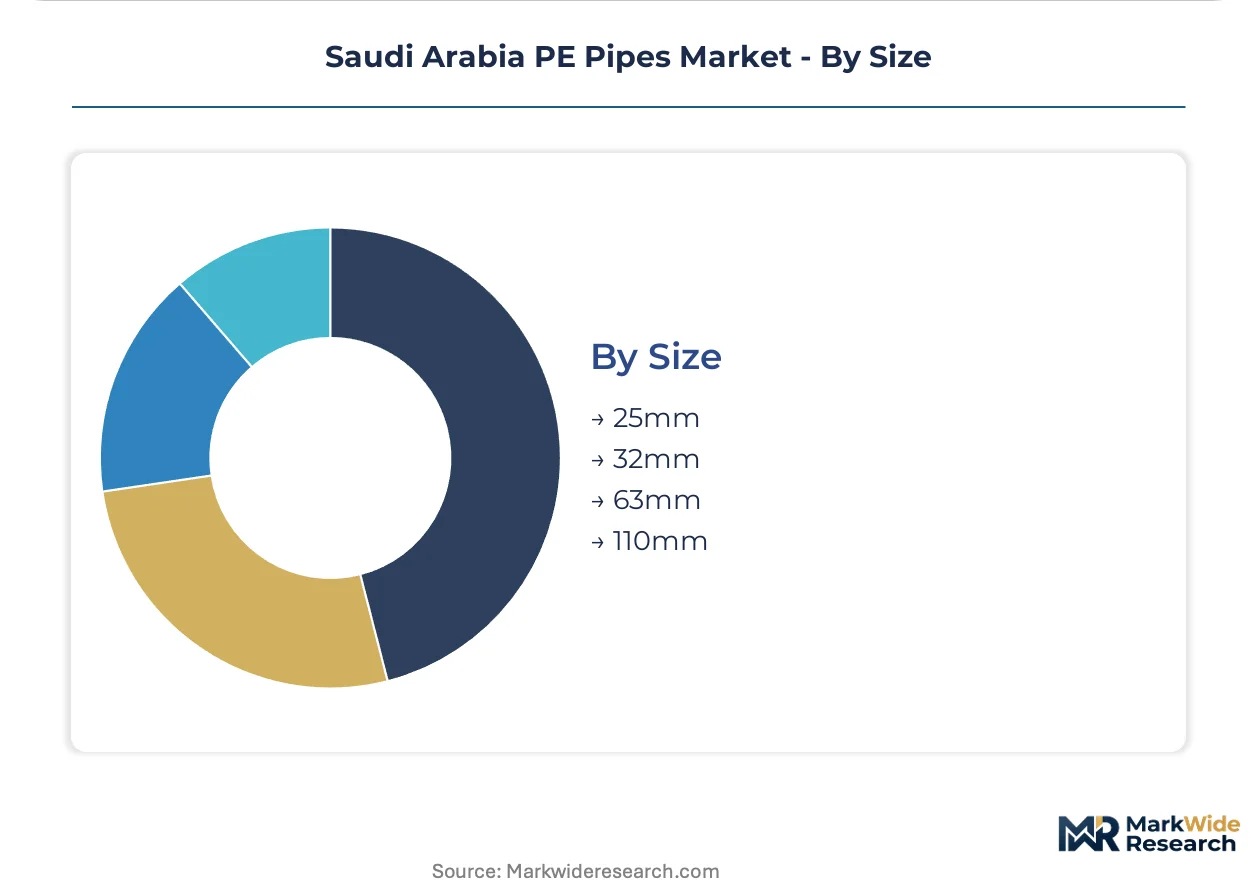
Size:
Diameter selection tracks pressure requirements, flow rate calculations, and installation method constraints across project types.
- 110mm:Large-diameter transmission mains for municipal water supply networks where fusion-jointed HDPE replaces ductile iron in Riyadh and Eastern Province corridors. These sizes face logistics friction from resin supply concentration in Jubail and Yanbu.
- 63mm:Distribution laterals and medium-pressure branches serving residential and commercial connections, with demand concentrated in new urban development zones.
- 32mm:Service connections and small-bore irrigation lines where coil packaging reduces joint count and installation labor.
- 25mm:Micro-ducting, house connections, and specialized conduit applications where flexibility and ease of handling outweigh flow capacity.
110mm leads absolute volume today; 63mm is expanding most quickly from residential distribution network buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene pipe manufacturing in Saudi Arabia traces its origins to the Jubail industrial cluster development in the 1970s, when state-led petrochemical integration created captive resin supply for downstream extrusion operations. This foundation established the Kingdom as the Gulf's dominant PE pipe production center.
Riyadh
Municipal water transmission network expansion drives procurement of SDR 11 and SDR 17 pressure pipes across the capital's buried distribution infrastructure. SASO-certified systems face mandatory SFDA barrier-layer compliance for potable water contact applications. The Riyadh metro construction corridors concentrate demand for large-diameter fusion-welded systems where trenchless installation constraints limit diameter selection.
Eastern Province
Jubail and Yanbu petrochemical complexes anchor domestic HDPE resin supply for regional extrusion operations, creating geographic concentration in feedstock access. Mega-project construction across industrial zones pulls volume for process water and cooling circuit specifications. Proximity to giga-project sites reduces logistics friction for bundled pipe-fitting deliveries to EPC contractors.
Western Region
Jeddah municipality specifications favor five-layer co-extruded barrier construction for potable water transmission mains replacing legacy asbestos-cement infrastructure. Red Sea Project development generates combined procurement specifications bundling microducts with pressure pipes for integrated utility corridors. The coastal corridor's saline groundwater conditions accelerate specification of enhanced barrier-layer formulations.
NEOM Northwest
The linear city's smart infrastructure mandates demand specialized microduct and pressure pipe bundles for telecom-water convergence applications. Giga-project procurement frameworks prioritize manufacturers with co-extrusion flexibility across product categories. Integrated utility corridor designs compress traditional specification boundaries between water transmission and communications conduit systems.
Central Region
Al-Qassim and Tabuk agricultural cooperatives specify medium-density PE for buried drip irrigation laterals where cost efficiency dominates procurement criteria. Farm cooperative buying patterns favor coil-packaged 32mm and 63mm diameters reducing joint count and installation labor. Irrigation district procurement operates on seasonal cycles distinct from municipal multi-year frameworks.
Saudi Arabia PE Pipes Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and compound-to-pipe integration levels. The vendor base organizes into three tiers: integrated resin-to-pipe manufacturers with captive feedstock, specialized extrusion houses with multilayer capability, and regional distributors with fabrication-only operations. Strategic archetypes include compounders controlling formulation, extruders with fitting integration, and project-focused bundlers. Dominant competitive moves center on SASO recertification acceleration and NEOM giga-project qualification.
Among domestic integrated manufacturers, Saudi Arabian Amiantit Company and Alwasail Industrial Company exemplify the compound-to-pipe archetype with captive control over barrier-layer formulation. Arabian Gulf Manufacturers Ltd. occupies a position anchored by geographic proximity to Jubail industrial cluster demand. These three represent the competitive set most visible in Eastern Province mega-project procurement, though the broader field includes specialized extrusion houses and regional fabrication operations serving municipal maintenance segments.
| Leading Market Players |
|---|
| Al Jubail Sanitary Pipe Factory |
| Arabian Gulf Manufacturers Ltd. |
| Saudi Plastic Products Company Ltd. (SAPPCO) |
| IKK Group |
| Al Tamam Modern Plastic Factory |
| Saudi Arabian Amiantit Company |
| Saudi Hepco LLC |
| Al-Munif Factory Company |
| Alwasail Industrial Company |
| Others |
Cost & Logistics Intelligence
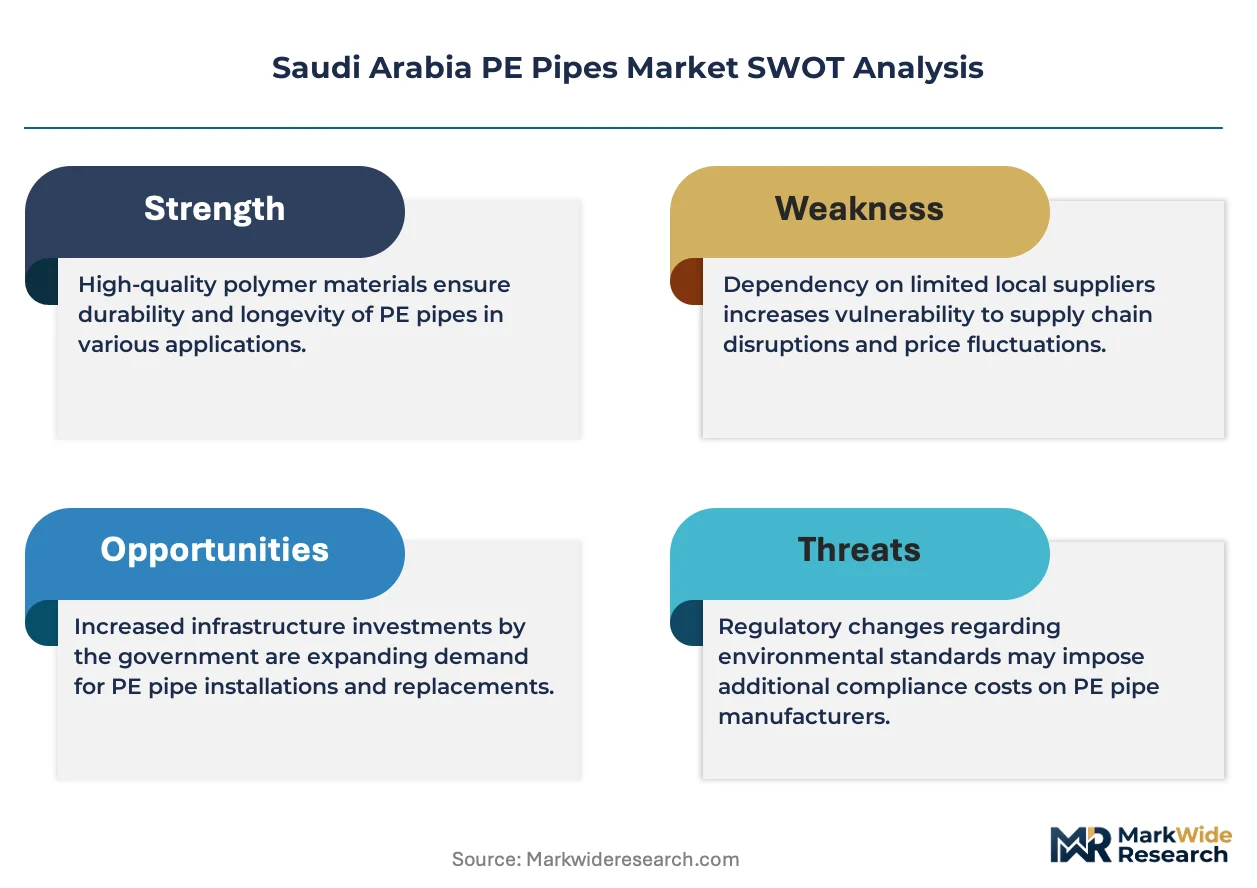
Municipal water authority procurement frameworks in Riyadh and the Eastern Province operate on multi-year bundled contracts, anchoring project-based pricing models where SASO certification tiers separate premium barrier-layer producers from standard-grade competitors. This buyer concentration compresses margin negotiation leverage for extruders lacking integrated compound-to-pipe capability.
Pricing Analysis
Three-tier pricing structure across premium certified, standard compliant, and economy grades governs municipal transmission contracts. Price differentiation rests on SFDA barrier-layer compliance and SASO hydrostatic test benchmarks, with certified producers commanding 15-25% premiums over commodity extruders. Pricing pressure stems from ethylene feedstock volatility linked to naphtha and ethane pricing swings. Agricultural cooperatives in Al-Qassim exhibit highest price sensitivity, while NEOM giga-project EPC contractors prioritize delivery reliability over unit cost optimization.
Supply Chain Analysis
Direct-to-EPC channels handle mega-project demand across NEOM and Red Sea developments, while distributor networks serve municipal maintenance segments. Geographic supply concentrates in Saudi Arabia's Jubail and Yanbu petrochemical complexes, with secondary extrusion capacity in UAE and limited Egyptian imports. Raw material dependencies center on HDPE resin grades, masterbatch compounds, and co-extrusion barrier-layer polymers. Single-source vulnerability runs through Jubail resin supply concentration. Distribution runs through specialized pipe distributors with fabrication capabilities in Riyadh and Dammam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's PE pipes market functions as a geographic-arbitrage play where domestic resin integration advantages over GCC importers create structural margin capture opportunities for local producers.
For Market Incumbents: Hedge against ethylene feedstock volatility through long-term supply agreements with SABIC and derivative producers. Accelerate SASO-ISO 4427 recertification timelines to defend construction material approval status against emerging extruders with multilayer capability. Prioritize backward integration into masterbatch compounding to control barrier-layer formulation costs.
For New Entrants and Emerging Players: EPC contractor procurement teams represent the most accessible channel partner type for qualification. White-space targets include microduct bundling for NEOM telecom-water convergence specifications and legacy asbestos-cement replacement programs in Jeddah's sewage collection networks. A technical-service-led go-to-market approach emphasizing butt-fusion technician training partnerships differentiates against established distributors.
For Investors and Strategic Acquirers: Regional petrochemical conglomerates seeking downstream integration represent the most active acquirer category in this space. Long-term viability hinges on compound-to-pipe integration depth and giga-project qualification status. Acquisition target archetypes include specialized extrusion houses with SASO-certified multilayer capability. The signal to watch is NEOM procurement framework announcements specifying bundled utility corridor suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HDPE Compounding | Captive barrier-layer formulation control reduces SFDA compliance costs and recertification timelines. |
| Multilayer Co-extrusion Capacity Expansion | Five-layer potable water pipe construction separates premium producers from commodity extruders in Riyadh tenders. |
| NEOM Giga-project Qualification | Integrated utility corridor specifications bundle microduct and pressure pipe procurement for smart city infrastructure. |
| Butt-fusion Technician Certification Programs | SASO-mandated welder training partnerships accelerate EPC contractor mobilization and project capture. |
| SASO-ISO Standards Harmonization | Export pathway expansion into UAE, Kuwait, and Bahrain markets for Saudi-certified producers. |
Research Approach
Multiple input streams — primary interviews with EPC procurement managers, municipal water authority engineers, and petrochemical distribution executives; secondary validation through SASO technical regulations, SFDA potable water mandates, and SABIC resin supply disclosures — were reconciled through bottom-up project pipeline enumeration and top-down petrochemical consumption modeling.
Segment-level projections across pressure pipes, microducts, gravity pipes, and fittings were stress-tested against Saudi Vision 2030 infrastructure commitment timelines and NEOM development phasing. CAGRs were derived from regression analysis linking historical extrusion capacity utilization to municipal transmission main installation rates. Industry-specific forecast inputs included ethylene derivative pricing correlations and horizontal directional drilling technical specifications limiting diameter adoption in dense urban corridors.
Revisions become necessary when SFDA barrier-layer requirements tighten, SASO testing protocols shift, or giga-project procurement frameworks alter specification bundling. Forecasts reflect assumptions about resin supply continuity from Jubail and Yanbu complexes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
Thermoplastic Pipe Market
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
Composite Pipes Market
Pipes and Tubes
Hydrogen Tube Skids Market
Pipes and Tubes
Germany Acid Proof Lining Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
Gas Pipe Fittings Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
HDPE Pipes Market