
 Paper Dry Strength Agents Market | 2026-2036
Paper Dry Strength Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Dry Strength Agents Market Outlook
Performance-based chemical management contracts are recalibrating how paper mills procure dry strength agents, shifting capital from outright chemical purchases to guaranteed runnability outcomes. Kemira leverages its Nordic pulp mill heritage to anchor long-term supply agreements across Northern European containerboard producers. BASF SE competes through backward integration into acrylamide monomer production, sustaining cost discipline amid volatile petrochemical feedstock cycles. Solenis differentiates via digital process control platforms that tie additive dosing to real-time strength testing at the dry end.
Paper dry strength agents comprise water-soluble polymers and modified starches engineered to boost tensile, burst, and ring crush indices without added grammage, typically dosed at 0.5–2.0% on dry fiber at the wet end of the paper machine. Their primary commercial purpose is to enable lightweighting of packaging grades and furnish flexibility toward lower-cost recycled pulp. Modified starch occupies the largest volume share as mills exploit native starch grafting with cationic chemistries for cost-efficient bond formation. Synthetic polymers, particularly polyacrylamide copolymers, represent the fastest-expanding margin pool where high-performance containerboard and tissue producers demand predictable strength-to-dose ratios. Sustainable technologies are gaining traction as wet-end additive systems integrate enzymatic starch conversion to reduce cooking energy and effluent biological oxygen demand.
REACH registrations and the EU F-Gas Regulation constrain fluorinated and certain quaternary ammonium chemistries in European mill systems, redirecting formulation R&D toward bio-based polyvinyl alcohol and cellulose derivatives. The EPA's effluent limitation guidelines under the Clean Water Act shape North American mill decisions on additive biodegradability and aquatic toxicity profiles. China's MEE enforcement of dual carbon goals tightens energy intensity benchmarks for starch cooking and polymer synthesis operations. Stakeholders must monitor how fragmented pulp furnish quality—driven by OCC collection contamination—shifts dosing specifications and service contract structures before committing to fixed-price multi-year supply agreements.
Market Dynamics
Containerboard lightweighting mandates and OCC furnish degradation are compressing dosing tolerance windows, forcing mills to adopt precision wet-end control systems that tie additive chemistry to real-time strength testing rather than fixed recipes.
Growth Catalysts
- EU Green Deal packaging rules:Mandatory recycled content quotas in corrugated packaging accelerate demand for modified starch systems that recover strength from degraded fiber furnish without virgin pulp addition.
- Enzymatic starch conversion:Wet-end enzyme systems reduce cooking energy intensity and effluent BOD, aligning mill operations with MEE dual carbon enforcement in China's packaging belt.
- German containerboard retrofit wave:Precision dosing infrastructure investments across Baden-Württemberg and Bavaria create pull for polymer-starch hybrid formulations with predictable strength-to-dose ratios.
Market Restraints
- Acrylamide monomer volatility:Synthetic polymer costs fluctuate with propylene feedstock cycles, compressing margin pools for copolymer suppliers without backward integration into monomer production.
- REACH chemical restrictions:ECHA registration requirements and F-Gas Regulation constraints block fluorinated and certain quaternary ammonium chemistries from European mill systems.
- Native starch supply concentration:Corn and tapioca sourcing clusters in the US Midwest and Southeast Asia expose formulators to agricultural yield variability and trade flow disruptions.
Strategic Opportunities
- India packaging expansion:BIS standards adoption and FSSAI food-contact approvals for modified starch create entry pathways for wet-end additive suppliers targeting domestic corrugated capacity growth.
- Digital process control convergence:Integration of machine learning dosing algorithms with online strength sensors enables predictive chemistry management at high-speed linerboard machines.
- Bio-based polyvinyl alcohol R&D:Cellulose derivative formulations bypass petrochemical dependency while meeting EPA effluent limitation guidelines for aquatic toxicity profiles.
Industry Challenges
- Wet-end chemistry integration:Retrofitting legacy Fourdrinier and gap-former machines with closed-loop additive control requires substantial capital and extended commissioning timelines.
- Furnish quality forecasting:OCC collection contamination variability complicates fixed-price multi-year supply agreements, pushing mills toward performance-based chemical management contracts with indexed dosing specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Dry Strength Agents Market |
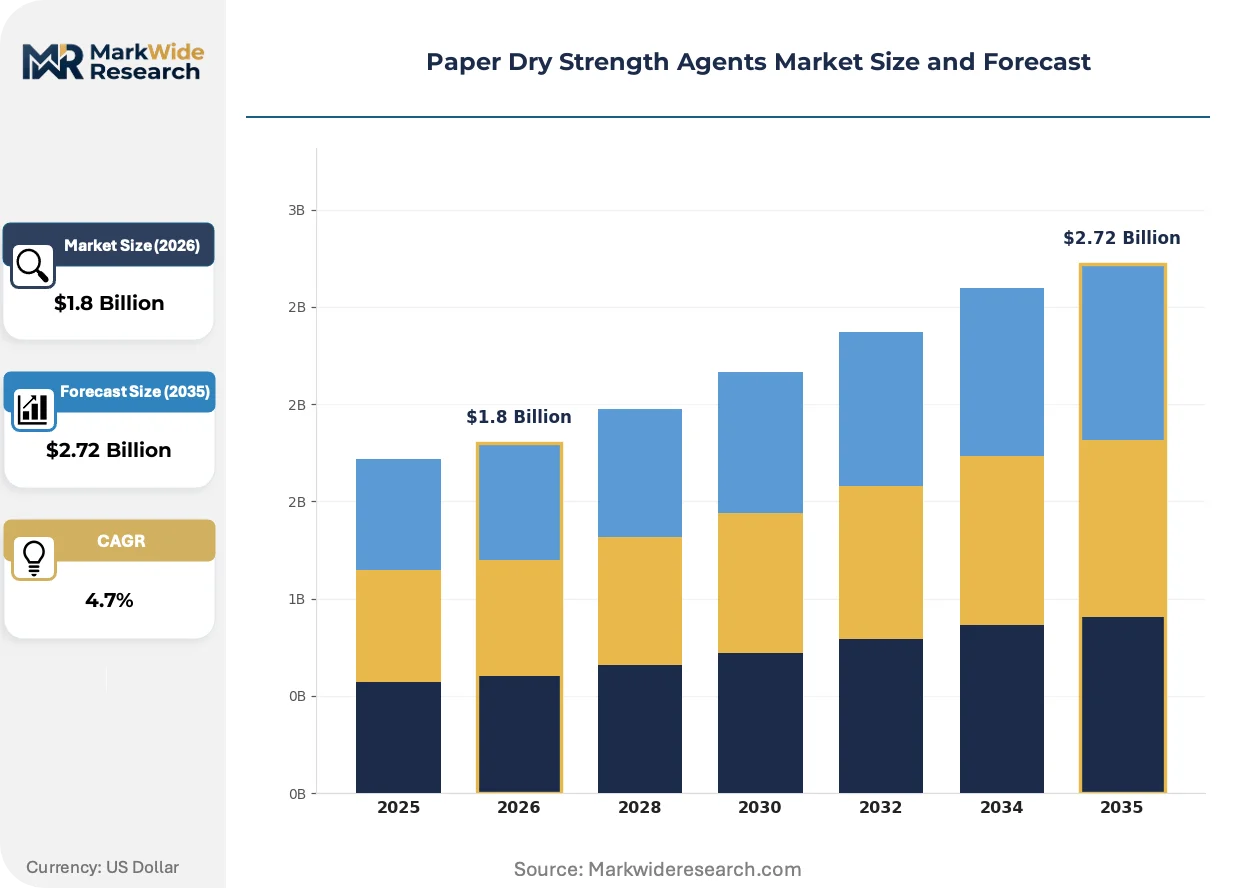
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Alcohol, Modified Starch, Synthetic Polymers, Cellulose Application: Copy Paper, Containerboard, Tissue Paper, Corrugated Board End User: Pulp Mill, Paper Mill, Packaging Industry, Printing Industry Technology: Wet End Additives, Dry End Additives, Sustainable Technologies, Conventional Processes |
| Companies Covered | SNF Group, Ecolab, BASF SE, Harima Chemicals Group, Buckman, Solenis, Ashland, Applied Chemicals International Group, Kemira, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Dry Strength Agents Market Strategic Shifts
Digitalization of wet-end chemistry and bio-based formulation R&D are compressing the traditional separation between additive supply and machine operation, creating integrated service models that guarantee runnability outcomes.
Enzymatic starch conversion technology is modularizing wet-end additive systems by decoupling starch cooking from centralized mill utilities. High-speed containerboard producers in Germany and the Netherlands adopt skid-mounted enzyme units that reduce steam demand by one-third. This distributed architecture is modularizing capital deployment and enabling smaller mills to access precision chemistry without centralized infrastructure investment.
REACH registrations and the EU F-Gas Regulation constrain fluorinated chemistries in European mill systems. ECHA's authorization requirements redirect formulation R&D toward bio-based polyvinyl alcohol and cellulose derivatives that maintain strength performance without restricted substances. Containerboard producers in France and Italy accelerate qualification timelines for these substitute chemistries to secure operating permits.
Performance-based chemical management contracts displace traditional tonnage-based procurement in Northern European packaging. Mills in Sweden and Finland now pay for guaranteed ring crush and burst indices rather than liters of polymer delivered, transferring dosing optimization risk to additive suppliers. This model concentrates in integrated pulp-to-packaging sites with continuous online strength measurement infrastructure.
Paper Dry Strength Agents Market Segmentation
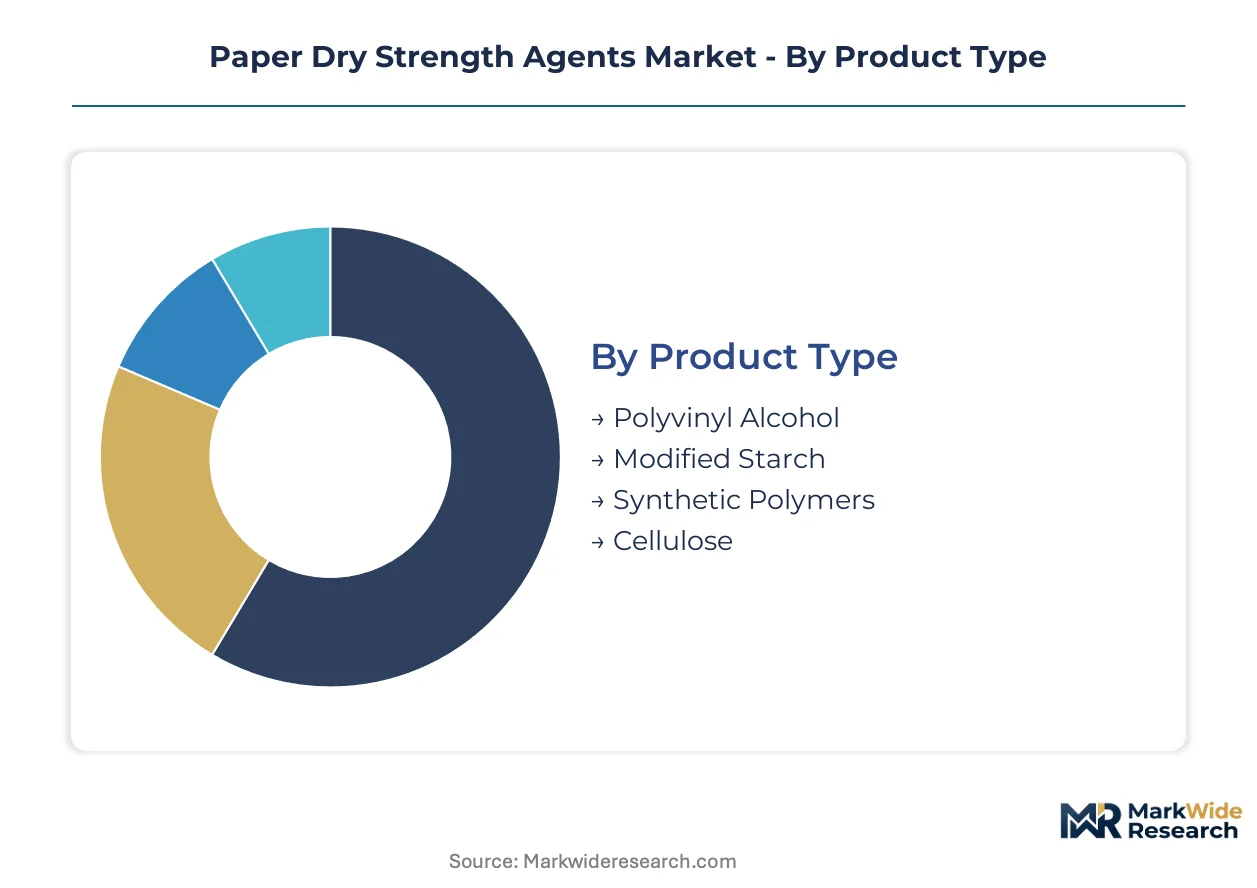
Paper dry strength agents segment along chemical composition, application grade, and integration point within the paper machine. Each axis carries distinct margin structures and technical service requirements that reshape supplier positioning.
Product Type:
Technical specification defines performance ceilings and regulatory compliance pathways across the four polymer categories.
- Modified Starch:Cationic grafting of native corn or tapioca starch creates cost-efficient hydrogen bonding with cellulose fibers. Containerboard producers in Germany's Baden-Württemberg region deploy these systems to recover strength from degraded OCC furnish without virgin pulp addition.
- Synthetic Polymers:Polyacrylamide copolymers deliver predictable strength-to-dose ratios with dosing precision below 0.5% on fiber. High-speed linerboard machines in the Netherlands specify these formulations where ring crush tolerances compress below 5% variance.
- Polyvinyl Alcohol:Water-soluble synthetic resin with film-forming characteristics for surface sizing applications.
- Cellulose:Derivative chemistries including carboxymethyl cellulose for bio-based strength enhancement in food-contact packaging grades.
Modified starch leads on scale; synthetic polymers lead on momentum.
Application:
End-use grade determines dosing specification, furnish flexibility requirements, and lightweighting intensity.
- Containerboard:Testliner and fluting grades demand maximum tensile recovery from 100% recycled furnish. EU Green Deal recycled content quotas accelerate specification of enzymatic starch systems that reduce cooking energy intensity while maintaining ring crush indices.
- Corrugated Board:Double-wall and triple-wall constructions require burst strength maintenance across humidity cycles. Packaging converters in Bavaria retrofit precision dosing infrastructure to tie additive chemistry to real-time strength testing at the dry end.
- Tissue Paper:Softness-strength tradeoffs limit polymer loading in premium towel and napkin grades.
- Copy Paper:Office paper specifications favor surface sizing over wet-end addition for ink holdout and stiffness.
Containerboard dominates procurement volume; corrugated board shows the steepest expansion trajectory.
End User:
Customer type shapes contract structure, technical service intensity, and integration depth with mill operations.
- Paper Mill:Integrated pulp-to-paper sites in Sweden and Finland adopt performance-based chemical management contracts paying for guaranteed burst indices rather than liters delivered. Solenis digital process control platforms enable predictive dosing optimization at these continuous-operation facilities.
- Packaging Industry:Independent corrugated converters in India source modified starch under BIS standards and FSSAI food-contact approvals as domestic containerboard capacity expands.
- Pulp Mill:Market pulp producers specify dry strength agents for wet-lap bale integrity during ocean freight.
- Printing Industry:Specialty paper merchants require surface strength additives for high-speed offset and inkjet compatibility.
Paper mills concentrate procurement value; packaging industry captures the fastest share gains.
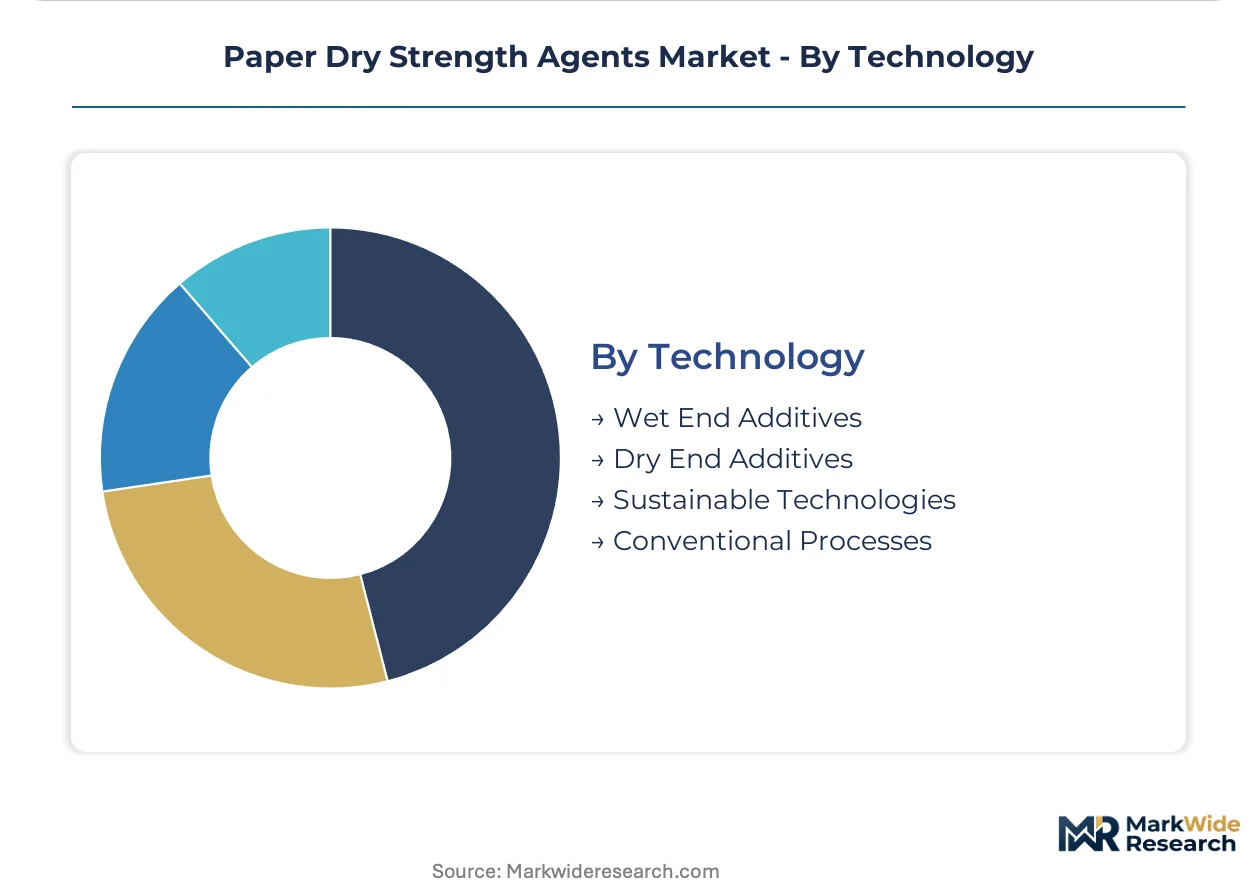
Technology:
Integration point and sustainability profile determine capital deployment and energy intensity.
- Wet End Additives:In-machine addition at the fan pump or headbox requires rapid adsorption kinetics. Precision dosing systems tie polymer-starch hybrid formulations to furnish variability in German retrofit installations.
- Sustainable Technologies:Enzymatic starch conversion decouples cooking from centralized utilities, reducing steam demand by one-third at skid-mounted units in the Netherlands.
- Dry End Additives:Surface application through size press or film press enables post-formation strength adjustment.
- Conventional Processes:Batch-cooked starch and fixed-recipe polymer dosing persist at legacy Fourdrinier machines without closed-loop control.
Wet end additives anchor installed base; sustainable technologies command the steepest investment growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's containerboard retrofit wave contrasts with China's MEE enforcement intensity, revealing how divergent regulatory frameworks reshape procurement patterns across major paper-producing economies.
Germany
Precision dosing infrastructure investments across Baden-Württemberg and Bavaria drive specification of polymer-starch hybrid formulations. The EU Green Deal packaging rules mandate recycled content quotas that accelerate enzymatic starch system adoption. Containerboard producers in the Stuttgart metropolitan area retrofit mills with closed-loop additive control tied to real-time strength testing.
China
Packaging belt expansion in the Yangtze River Delta and Pearl River Delta sustains wet-end additive demand despite furnish quality degradation. MEE dual carbon enforcement tightens energy intensity benchmarks for starch cooking operations. Mills in Jiangsu province deploy skid-mounted enzyme units to reduce steam demand while maintaining compliance with national emission standards.
United States
OCC collection contamination variability complicates fixed-price supply agreements across Southeast and Midwest paper clusters. EPA effluent limitation guidelines under the Clean Water Act shape mill decisions on additive biodegradability profiles. Containerboard producers in Wisconsin and Georgia adopt performance-based chemical management contracts with indexed dosing specifications.
India
Domestic corrugated capacity expansion in Maharashtra and Gujarat creates entry pathways for modified starch suppliers. BIS standards adoption and FSSAI food-contact approvals establish regulatory compliance baselines for wet-end additives. Packaging converters in the Mumbai-Pune industrial corridor source cationic starch systems under multi-year procurement frameworks.
Sweden
Integrated pulp-to-packaging sites in Norrland and Svealand pioneer outcome-based procurement models paying for guaranteed burst indices. REACH registration requirements constrain fluorinated chemistry use in mill systems. Producers along the Baltic coast deploy digital process control platforms enabling predictive dosing optimization at continuous-operation facilities.
Paper Dry Strength Agents Market Competitive Environment
Top-tier vendors anchor long-term supply agreements with integrated pulp-to-paper sites, while mid-tier specialists compete on regional service density and application-specific formulation expertise. The vendor base stratifies across three archetypes: Nordic heritage suppliers leveraging wet-end chemistry heritage, German chemical conglomerates with backward integration into monomer production, and North American service-oriented platforms emphasizing digital process control. Competitive dynamics center on strategic partnerships for precision dosing infrastructure and portfolio diversification toward bio-based cellulose derivatives.
Among Nordic heritage suppliers, Kemira exemplifies the long-term supply agreement archetype across Northern European containerboard producers. BASF SE occupies a position reflecting captive acrylamide monomer production and cost discipline amid volatile petrochemical cycles. Solenis represents the digital convergence vector, with process control platforms tying additive dosing to real-time strength measurement infrastructure.
| Leading Market Players |
|---|
| SNF Group |
| Ecolab |
| BASF SE |
| Harima Chemicals Group |
| Buckman |
| Solenis |
| Ashland |
| Applied Chemicals International Group |
| Kemira |
| Others |
Value Chain & Pricing Dynamics
Enzymatic starch conversion technology is compressing cost economics while fragmenting supply concentration across wet-end additive systems. This production-method transition enables smaller mills to bypass centralized cooking infrastructure, redistributing procurement power toward regional enzyme unit suppliers and away from legacy starch processors.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for polymer-starch hybrid formulations as precision dosing infrastructure investments concentrate procurement volume. Three-tier pricing structure across premium, standard, and economy levels differentiates by dosing precision capability and after-sales technical service intensity. Pricing pressure stems from acrylamide monomer volatility tied to propylene feedstock cycles. Independent corrugated converters in India exhibit highest price sensitivity, while integrated pulp-to-packaging sites in Sweden prioritize runnability guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from major containerboard producers mandate multi-supplier qualification for both modified starch and synthetic polymer categories. Corn and tapioca feedstock concentration in the United States Midwest and Southeast Asia anchors raw material sourcing, while polymer synthesis clusters in Germany and China shape synthetic supply. Single-source vulnerability runs through acrylamide monomer production where backward integration remains limited. Distribution runs through regional chemical distributors with technical service capabilities serving paper mill clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Paper Dry Strength Agents Market functions as a stable compounder anchored by EU Green Deal packaging mandates that institutionalize recurring demand for lightweighting chemistry.
For Market Incumbents: Deploy performance-based contracting mechanisms to lock in integrated pulp-to-paper sites before digital process control platforms commoditize dosing optimization. Deepen captive acrylamide production to insulate margin pools from propylene volatility. Counter emerging bio-based cellulose derivative substitutes by accelerating REACH-compliant formulation qualification timelines. For New Entrants and Emerging Players: Begin with skid-mounted enzymatic starch conversion units targeting mid-tier containerboard mills in India's Maharashtra and Gujarat corridor lacking centralized cooking infrastructure. White-space concentration sits in precision dosing retrofit services for legacy Fourdrinier machines. Pursue BIS standards certification and FSSAI food-contact approvals as mandatory gating items for domestic procurement frameworks. For Investors and Strategic Acquirers: Roll-up economics work for regional wet-end additive distributors with embedded technical service relationships because paper mill procurement committees prioritize runnability assurance over supplier switching. Five-to-ten year viability rests on consolidation of fragmented mid-tier formulators lacking backward integration. Monitor MEE dual carbon enforcement intensity in China's Jiangsu province as inflection indicator for enzymatic system adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acrylamide production insulates BASF and SNF from propylene feedstock volatility cycles. |
| Green Manufacturing Transition | Enzymatic starch conversion aligns German mills with EU Green Deal energy intensity benchmarks. |
| Long-term Supply Agreement | Kemira anchors Nordic containerboard procurement through performance-based chemical management contracts. |
| Joint Venture | Precision dosing infrastructure partnerships in Baden-Württemberg reduce commissioning risk for retrofits. |
| Capacity Expansion | Skid-mounted enzyme unit deployment in the Netherlands modularizes capital for smaller mills. |
Study Parameters
Coverage spans Germany, China, the United States, India, and Sweden, with primary inputs from each market informing supply-side and demand-side calibration. Primary interviews with paper mill technical directors, wet-end additive procurement managers, starch processing plant engineers, and corrugated converter operations heads combined with secondary validation from customs trade data, Cefic chemical industry reports, SEC 10-K filings, and EPA effluent limitation guidelines. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Rate-of-change decomposition separates volume growth from price realization effects across the projection horizon. Segmentation dimensions modeled include chemical composition tier, application grade intensity, end-user contract structure, and technology integration point. CAGRs derive from weighted average of historical capacity utilization trends and forward-looking regulatory enforcement schedules. Industry-specific inputs incorporate OCC furnish quality degradation curves and enzymatic conversion adoption elasticity.
Several conditions sit outside the modeled scope, including abrupt REACH substance restrictions beyond currently registered chemistries and trade flow disruptions in corn and tapioca feedstock channels. Forecasts reflect assumptions on MEE enforcement continuity and EU Green Deal implementation timelines. Deviation in acrylamide monomer supply concentration or enzymatic starch conversion cost curves would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Based Laminates Market
Paper Products
BPA Free Thermal Paper Market
Paper Products
High-Speed Production Inkjet Printer Paper Market
Paper Products
Ceramic Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Overlay Paper Market
Paper Products
Sawn Wood Market
Paper Products
Loose Leaf Paper Market
Paper Products
Global Cellulose Sponge Market
Paper Products
Pulp and Paper Market
Paper Products
Semi Chemical Wood Pulp Market
Paper Products
Paper Machine Systems Market
Paper Products
Europe Medium-Density Fiberboard Market
Paper Products
Thermal Paper Market
Paper Products
Europe and MENA Pulp Market
Paper Products
Carbonless Paper Market