
 FEP Tubing Products Market | 2026-2036
FEP Tubing Products Market Size, Share, and Industry Trends Forecast 2026-2036
FEP Tubing Products Market Insights
Buyer concentration among medical device OEMs is consolidating as large manufacturers reduce qualified supplier lists to cut validation costs. Saint-Gobain leverages its fluoropolymer compounding expertise to anchor European catheter supply chains. Zeus Industrial Products specializes in precision extrusions for neurovascular and cardiac applications, sustaining R&D intensity above industry norms. Parker Hannifin competes through backward integration into resin sourcing and captive polymerization capacity.
Fluorinated ethylene propylene tubing consists of a fully fluorinated copolymer with a melting point near 260°C and exceptional chemical resistance across pH extremes from 0 to 14. Manufacturers employ ram extrusion or paste extrusion to achieve thin-walled geometries down to 0.005 inches for fluid transfer in corrosive process streams. Flexible tubing dominates volume shipments due to its compatibility with peristaltic pumps and catheter routing systems, while multi-layer tubing captures premium pricing from barrier-layer configurations in pharmaceutical packaging. Custom tubing grows fastest as OEMs specify proprietary dimensions, colors, and radiopaque fillers for device traceability.
US FDA enforces biocompatibility testing under ISO 10993 for medical-grade FEP tubing in chronic implant applications, raising compliance barriers for new entrants. REACH and RoHS in Europe restrict perfluorooctanoic acid residuals and heavy metal additives in fluoropolymer formulations, forcing reformulation investments. China's NMPA now requires domestic clinical data for imported tubing in Class III medical devices, complicating market access for foreign suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redundant certification spending.
Market Dynamics
Medical device OEMs are consolidating supplier qualifications around fluoropolymer tubing manufacturers holding ISO 13485 certification and validated US FDA Master Files, compressing the vendor base while raising technical barriers for new entrants.
Growth Catalysts
- Extrusion coextrusion advances:Sub-millimeter wall thickness capabilities now enable neurovascular catheter designs previously unmanufacturable, pulling demand from cardiac rhythm management OEMs.
- REACH and RoHS compliance:European reformulation mandates for PFOA-free FEP grades are accelerating supplier R&D investment and creating first-mover advantages for compliant compounders.
- Semiconductor fabrication clusters:Chemical delivery systems in the United States, Germany, and China require high-purity tubing for corrosive process chemistries, sustaining industrial volume.
Market Restraints
- Resin supply concentration:Virgin FEP polymer production concentrates among three global chemical conglomerates, exposing converters to allocation risk during feedstock disruptions.
- Biocompatibility validation costs:ISO 10993 testing protocols for chronic implant applications require $200K-$400K per device family, freezing out mid-tier tubing specialists.
- Peristaltic pump elastomer substitution:Platinum-cured silicone tubing competes for pharmaceutical fluid transfer where flexibility outweighs chemical resistance requirements.
Strategic Opportunities
- India medical device manufacturing:CDSCO regulatory harmonization with ISO 13485 and PLI scheme incentives for domestic catheter production create greenfield demand for qualified FEP suppliers.
- Radiopaque filler integration:Barium sulfate and bismuth trioxide compounding expertise enables device traceability under fluoroscopy, commanding 40-60% price premiums over standard grades.
- Pharmaceutical barrier packaging:Multi-layer tubing configurations with EVOH or cyclic olefin copolymer interlayers address oxygen and moisture ingress for biologic drug stability.
Industry Challenges
- Polymer processing expertise scarcity:Paste extrusion operators with 10+ years of fluoropolymer rheology experience command premium wages and limited geographic mobility.
- Cleanroom capacity constraints:ISO Class 7 manufacturing space for medical-grade tubing requires $15M-$25M facility investments with 18-24 month qualification timelines.
- Legacy resin inventory stranding:PFOA-containing FEP grades accumulated before REACH deadlines face write-down risks as European medical OEMs reject non-reformulated materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FEP Tubing Products Market |
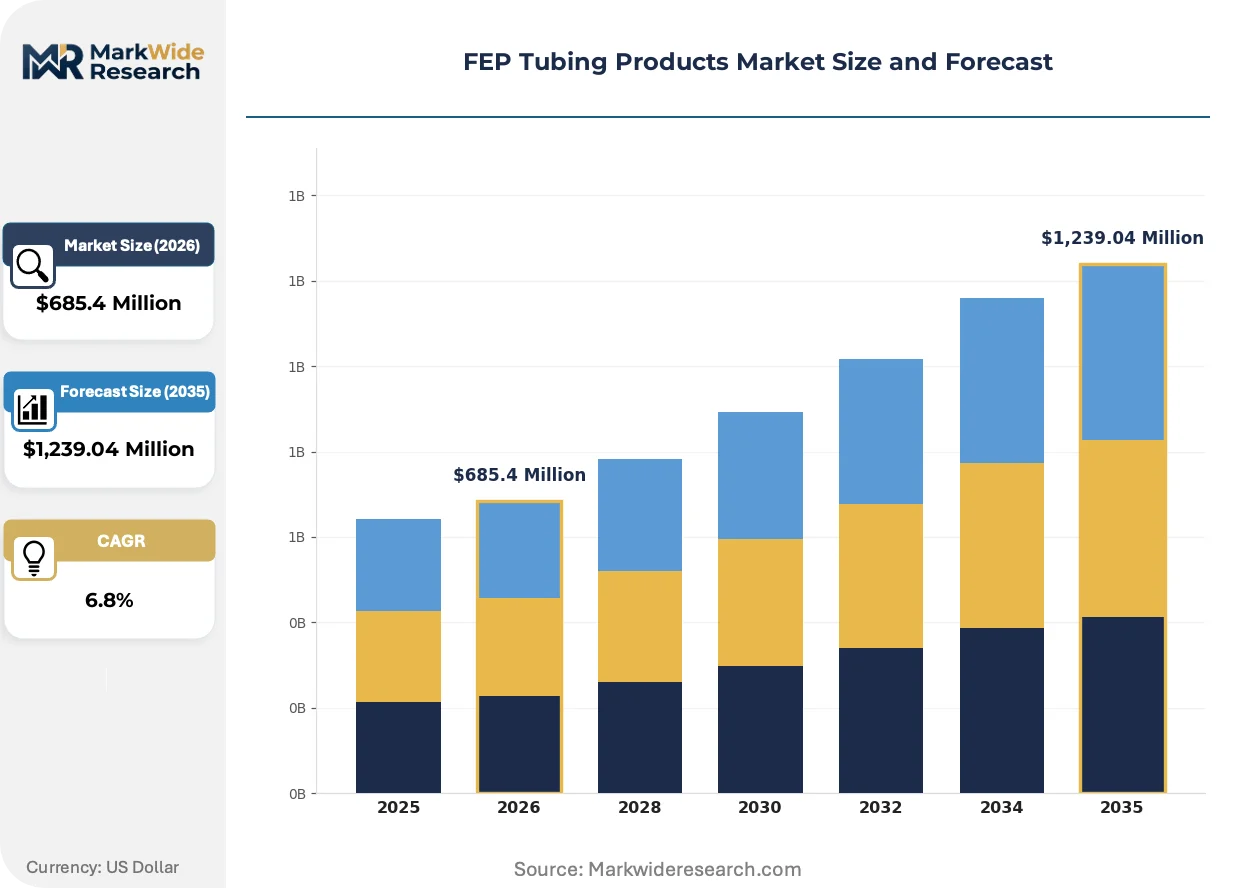
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Tubing, Rigid Tubing, Multi-Layer Tubing, Custom Tubing Application: Medical Devices, Chemical Processing, Food & Beverage, Electronics End User: OEM Manufacturers, Laboratories, Healthcare Providers, Industrial Users Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Saint-Gobain, Zeus Industrial Products, Teleflex, Optinova, Adtech Polymer Engineering, Parker Hannifin, TE Connectivity, Daikin Industries, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FEP Tubing Products Market Trends and Innovations
Extrusion technology advances and regulatory chemistry restrictions are converging to redefine competitive advantage in fluoropolymer tubing, separating compounders with captive polymerization capabilities from converters dependent on merchant resin.
Multi-layer coextrusion with tie-layer adhesion chemistry is rewriting performance benchmarks for pharmaceutical and semiconductor applications. Catheter OEMs specify five-layer constructions combining FEP chemical inertness with polyurethane flexibility and radiopaque visualization. The technology is compressing lead times for complex geometries while disqualifying single-layer specialists from premium tenders.
REACH Annex XVII restrictions on perfluorinated substances are forcing reformulation of legacy FEP grades across European supply chains. ECHA evaluations of PFAS restriction proposals are accelerating supplier transitions to PFOA-free polymerization catalysts. Medical device manufacturers serving the EU market are demanding full material disclosure documentation to preempt downstream liability exposure.
Buyer consolidation among top-tier medical device OEMs is compressing supplier margins through volume aggregation and sole-source negotiations. Cardinal Health, Medtronic, and Boston Scientific procurement teams now mandate multi-year price caps in exchange for qualified supplier status. United States catheter manufacturers are responding by qualifying secondary tubing sources in Mexico and Costa Rica to retain leverage in contract renegotiations.
FEP Tubing Products Market Segmentation
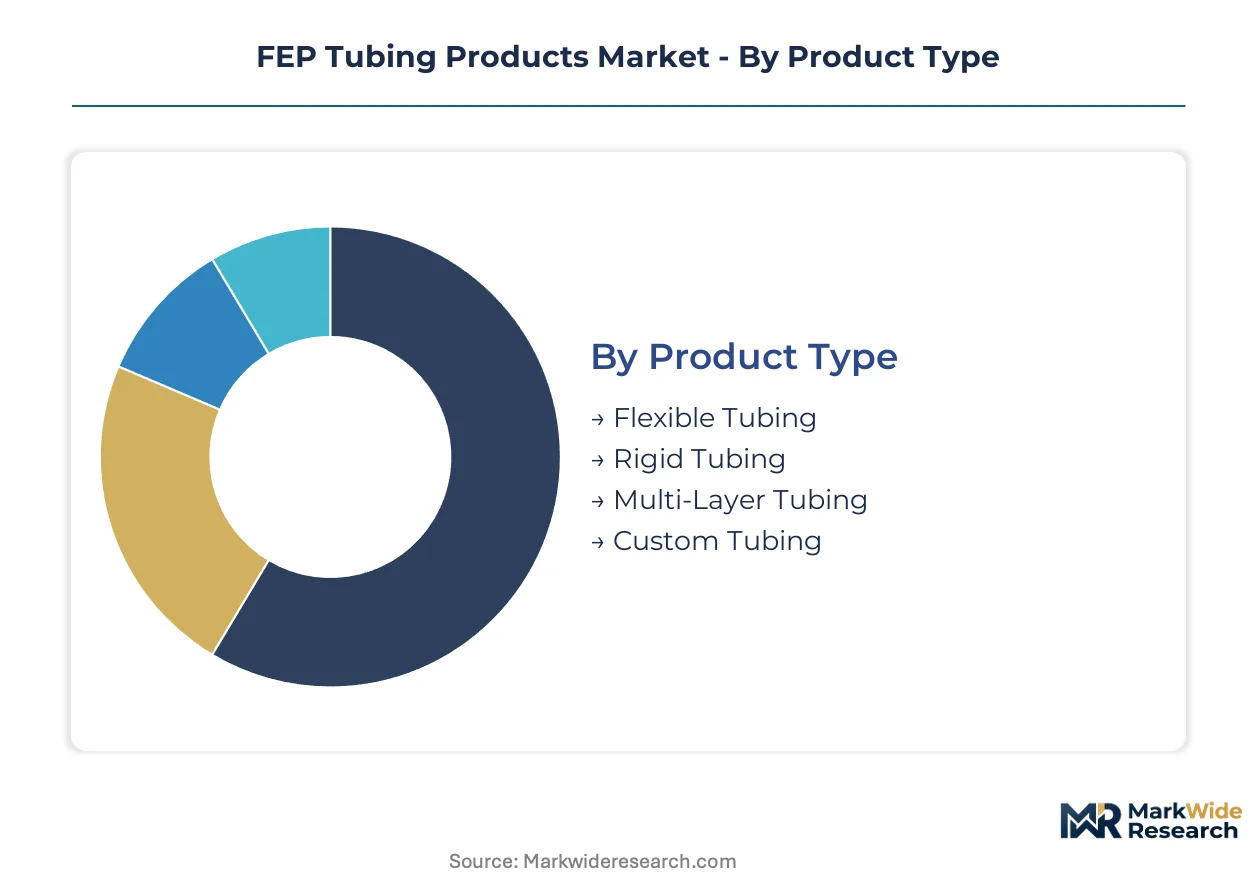
Segmentation in FEP tubing reveals divergent margin structures across product architectures and end-use specifications. Medical-grade configurations command substantial premiums over industrial commodity grades, while distribution channel selection directly shapes customer acquisition economics and technical service intensity.
Product Type:
Flexible tubing dominates volume shipments, yet multi-layer and custom configurations capture disproportionate value through technical differentiation.
- Flexible Tubing:Extruded in continuous coils with wall thicknesses down to 0.005 inches, this format serves peristaltic pump circuits and catheter routing where bend radius compliance is critical. Demand concentrates among pharmaceutical OEMs in Germany and the United States, driven by single-use bioprocessing expansion and chronic implant device volumes.
- Multi-Layer Tubing:Five-layer coextrusions integrate FEP chemical barriers with polyurethane flexibility layers and radiopaque visualization cores. Neurovascular catheter OEMs in Boston and Minneapolis specify these constructions for procedures requiring simultaneous chemical inertness and fluoroscopic traceability.
- Rigid Tubing:Semi-crystalline FEP extrusions with thicker walls for structural fluid containment in semiconductor chemical delivery systems.
- Custom Tubing:Proprietary dimensions, colorants, and filler loadings specified by device OEMs for traceability and brand differentiation; expanding most quickly as procurement consolidates around qualified suppliers capable of validated Master Files.
Today's leader: Flexible Tubing. Tomorrow's challenger: Custom Tubing.
Application:
Medical device applications anchor premium pricing, while chemical processing sustains baseline industrial volume through fab expansion cycles.
- Medical Devices:Catheters, guidewires, and fluid management systems requiring ISO 10993 biocompatibility validation and US FDA Master File documentation. Cardiac rhythm management OEMs in Ireland and Minnesota drive specification intensity for chronic implantable applications.
- Chemical Processing:High-purity tubing for corrosive reagent delivery in semiconductor fabrication clusters across Arizona, Saxony, and Hubei Province. Tool OEMs specify FEP for sulfuric acid and hydrogen peroxide handling where metallic alternatives fail.
- Food & Beverage:FDA-compliant extrusions for sanitary fluid transfer in dairy and beverage processing equipment.
- Electronics:Insulation and protective sleeving for high-temperature wiring harnesses in aerospace and telecommunications infrastructure.
Medical Devices command the steepest price premiums; Chemical Processing provides the volume foundation.
End User:
OEM Manufacturers concentrate procurement power, while Laboratories and Healthcare Providers fragment demand across lower-volume, higher-service requirements.
- OEM Manufacturers:Medical device and semiconductor tool builders with consolidated supplier qualification programs, multi-year supply agreements, and technical audit requirements. Boston Scientific, Medtronic, and Applied Materials procurement teams drive specification standardization.
- Laboratories:Research institutions and analytical instrumentation builders requiring small-batch custom extrusions with rapid prototyping turnaround.
- Healthcare Providers:Hospital systems and ambulatory surgery centers sourcing sterile-packed tubing for procedural kits and disposable device assemblies.
- Industrial Users:Chemical plants, food processors, and electronics manufacturers with maintenance-repair-operations purchasing patterns and price-sensitive volume buying.
OEM Manufacturers set industry specifications; Laboratories generate innovation pull for next-generation geometries.
Distribution Channel:
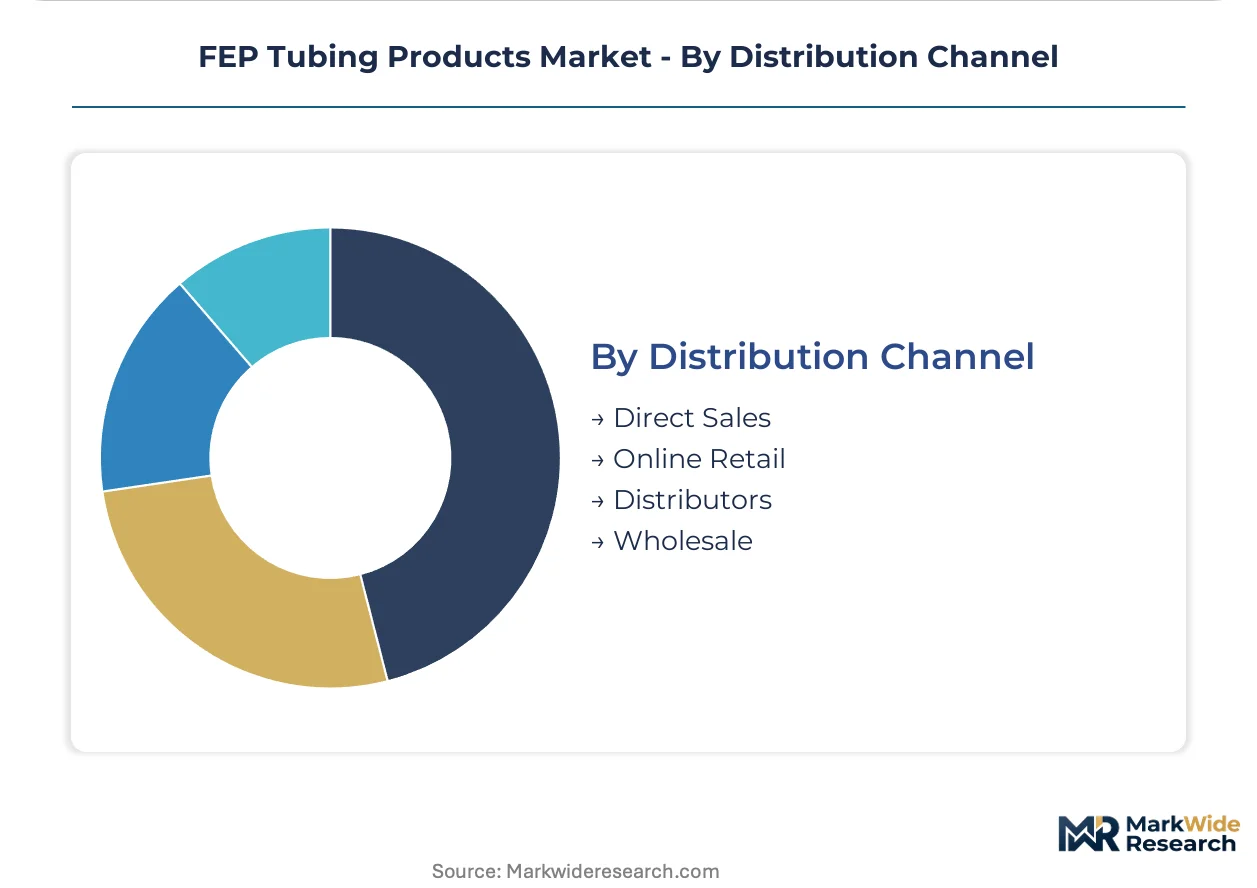
Direct sales relationships dominate technical applications, while distributors capture fragmented industrial demand through inventory aggregation.
- Direct Sales:Manufacturer-employed technical sales engineers managing OEM qualification programs, audit coordination, and collaborative design-for-manufacturing engagements. Saint-Gobain and Zeus Industrial Products deploy field teams for catheter development partnerships.
- Distributors:Specialized fluid handling and medical device component distributors stocking standard sizes for MRO and small-batch production requirements.
- Online Retail:E-commerce platforms serving research laboratories and prototype shops with catalog-standard dimensions and rapid fulfillment.
- Wholesale:Volume aggregators supplying industrial processors with commodity-grade extrusions on consignment or blanket order arrangements.
Direct Sales capture the margin; Distributors capture the reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium medical-grade volumes while China scales fabrication capacity for semiconductor tool OEMs. Germany anchors European fluoropolymer compounding expertise. India emerges as a catheter manufacturing relocation target. Japan sustains precision extrusion leadership for electronics applications.
United States
Cardiac rhythm management OEMs in Minnesota and neurovascular device clusters in Massachusetts drive specification intensity for chronic implant tubing. FDA biocompatibility validation under ISO 10993 creates compliance barriers that favor incumbent suppliers with established Master Files. Arizona semiconductor fabrication facilities sustain industrial demand for high-purity chemical delivery systems.
Germany
Catheter OEMs in Baden-Württemberg and pharmaceutical packaging specialists in Bavaria anchor European medical-grade consumption. REACH Annex XVII restrictions on perfluorinated substances are accelerating transitions to PFOA-free polymerization catalysts across Saxony chemical processing clusters. Industrial tubing demand concentrates in Frankfurt-Rhine-Main semiconductor tool supply chains.
China
Domestic catheter manufacturers in Jiangsu and Zhejiang provinces are qualifying local fluoropolymer tubing sources to reduce import dependency. NMPA requirements for domestic clinical data on Class III medical devices complicate market access for foreign suppliers. Wuhan and Hefei semiconductor fabrication clusters sustain high-purity tubing demand for corrosive reagent handling.
India
CDSCO regulatory harmonization with ISO 13485 and PLI scheme incentives for domestic catheter production are attracting contract manufacturers to Maharashtra and Karnataka. Medical device OEMs in Chennai and Hyderabad are qualifying fluoropolymer tubing suppliers for export-oriented production. Bangalore precision manufacturing clusters generate prototype demand for custom extrusions.
Japan
Electronics OEMs in Tokyo-Osaka corridor sustain demand for thin-wall insulation in telecommunications infrastructure. METI industrial standards for high-purity materials support semiconductor chemical delivery applications in Kyushu fabrication facilities. Yokohama medical device specialists specify fluoropolymer tubing for minimally invasive surgical instruments.
FEP Tubing Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. Chemical conglomerates with captive resin polymerization anchor upstream supply security. Precision extrusion specialists command premium positioning in neurovascular and cardiac catheter segments. Industrial distributors aggregate fragmented demand for commodity-grade configurations. Consolidation pressure from OEM procurement teams is compressing qualified supplier lists while raising technical audit requirements.
Among diversified material science conglomerates, Saint-Gobain and Daikin Industries exemplify integrated players with fluoropolymer compounding heritage. Parker Hannifin represents industrial conglomerates with backward integration into resin sourcing. At the pure-play precision extrusion tier, Zeus Industrial Products occupies a specialist position. TE Connectivity and Teleflex exemplify medical device OEMs with captive tubing capabilities.
| Leading Market Players |
|---|
| Saint-Gobain |
| Zeus Industrial Products |
| Teleflex |
| Optinova |
| Adtech Polymer Engineering |
| Parker Hannifin |
| TE Connectivity |
| Daikin Industries |
| 3M Company |
| Others |
Pricing and Supply Chain Analysis
Virgin FEP resin indices from Chemours and Daikin anchor contract pricing tiers across converter supply chains, compressing margins when feedstock allocations tighten and amplifying premium capture for compounders with captive polymerization.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade extrusions while medical-grade premiums widen. Three-tier pricing structure across medical-certified, industrial-performance, and commodity-grade levels separates ISO 13485-validated supply from merchant resin conversions. Pricing pressure stems from OEM procurement consolidation mandating multi-year price caps. Contract manufacturers in Mexico and Costa Rica exhibit highest price sensitivity; neurovascular catheter OEMs in Massachusetts show least.
Supply Chain Analysis
Regional distribution centers in Ohio, Baden-Württemberg, and Jiangsu Province coordinate hub-and-spoke fulfillment for just-in-time catheter manufacturers. Virgin polymer production concentrates in the United States, Japan, and China. Converter operations draw from fluoropolymer compounding expertise in France and Germany. Single-source vulnerability runs through three global resin conglomerates. Distribution runs through direct technical sales for medical OEMs and specialized fluid-handling distributors for industrial MRO.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CDSCO harmonization with ISO 13485 in India offers 30-40% cost reduction against US FDA validation timelines.
For Market Incumbents: Lock in resin supply security through backward integration or long-term offtake agreements with Chemours and Daikin. Defend qualified supplier status by accelerating PFOA-free grade transitions ahead of REACH enforcement. Channel control through dedicated technical sales teams in Minneapolis and Boston catheter clusters offsets margin compression from sole-source negotiations.
For New Entrants and Emerging Players: The 40-60% premium gap between radiopaque-filled custom tubing and standard flexible grades offers entry traction. Target pharmaceutical barrier packaging in Bavaria and Hubei where multi-layer coextrusion demand outpaces qualified supply. Pursue rapid prototyping partnerships with Bangalore precision manufacturing clusters to establish Master File credibility.
For Investors and Strategic Acquirers: Consolidation pressure builds where paste extrusion expertise scarcity intersects with cleanroom capacity constraints. Five-to-ten year viability favors compounders with captive resin polymerization and validated FDA submissions. Acquire mid-tier converters with ISO 13485 infrastructure and underutilized extrusion lines. Monitor ECHA PFAS restriction proposals as inflection signal for reformulation capex requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| PFOA-Free Polymerization Transition | REACH Annex XVII compliance secures European medical OEM access and preempts inventory stranding. |
| Multi-Layer Coextrusion Capacity Expansion | Five-layer barrier configurations command premium positioning in neurovascular catheter tenders. |
| Radiopaque Filler Integration | Barium sulfate and bismuth trioxide compounding enables 40-60% price premiums for fluoroscopic traceability. |
| India Manufacturing Qualification | CDSCO harmonization and PLI incentives create export-oriented catheter production hubs in Maharashtra. |
| Cleanroom Facility Investment | ISO Class 7 manufacturing space addresses capacity constraints and qualifies suppliers for chronic implant applications. |
Research Methodology
Multiple input streams — extrusion technology assessments, regulatory filing reviews, and procurement pattern analysis — were reconciled through structured primary engagement with fluoropolymer compounders, catheter OEM procurement leads, and semiconductor tool chemical delivery engineers. Secondary validation drew from FDA 510(k) databases, ECHA restriction proposals, and customs trade flows. Bottom-up tubing volume estimates and top-down resin consumption figures were triangulated for consistency.
Cross-referencing historical extrusion capacity expansion patterns against panel input from medical device supply chain directors shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, application severity tier, end-user procurement scale, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to validated baseline volumes, with semiconductor fab buildout cycles and catheter procedure growth rates as key industry-specific inputs.
Caveats apply where REACH PFAS restriction scope, NMPA import data requirements, or resin allocation disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global CPVC Pipes and Fittings Market
Pipes and Tubes
Pipes and Fittings Market
Pipes and Tubes
Metal Pipe Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
PVC Pipes and Fittings Market
Pipes and Tubes
Europe PVC Pipes Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
Saudi Arabia PPR Pipes Market
Pipes and Tubes
Multiflex Tubes Market