
 Hydrogen Tube Skids Market | 2026-2036
Hydrogen Tube Skids Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Tube Skids Market Insights
Single-source procurement of high-pressure hydrogen containment systems is restructuring into multi-source qualification programs across major energy infrastructure projects. Baker Hughes Company leverages its rotating equipment heritage to anchor large-scale compression-integrated skid packages for hydrogen hubs. Hexagon Purus specializes in lightweight composite cylinder technology, differentiating its mobile skids for transport applications where payload efficiency governs total cost of ownership. CIMC Enric Holdings Limited dominates manufacturing scale, sustaining cost advantages through captive production of pressure vessels and manifold assemblies in Asia-Pacific supply corridors.
Hydrogen tube skids are engineered pressure-vessel assemblies mounted on structural frames, typically rated for service pressures exceeding 350 bar and constructed from chromium-molybdenum steel or carbon-fiber-reinforced polymer liners, designed to store, transport, or dispense gaseous hydrogen in industrial and mobility applications. Standard skids occupy the mature volume tier where price competition compresses margins, while custom skids command premium positioning for site-specific integration with existing refinery or power-to-gas infrastructure. Mobile skids represent the fastest-expanding application segment, driven by hydrogen delivery logistics to off-grid industrial users lacking pipeline connectivity.
ISO 19881 and ISO 19882 standards govern cylinder design and skid system safety, while the EU AI Act and Machinery Directive impose conformity assessment burdens on automated refueling interfaces. The EPA and OSHA in the United States enforce parallel pressure vessel and workplace exposure protocols that shape product certification roadmaps for cross-border suppliers. Stakeholders must monitor evolving harmonization between regional pressure equipment directives and emerging hydrogen purity specifications that will determine qualification timelines for next-generation tube skid deployments.
Market Dynamics
The transition from single-source to multi-source qualification programs for high-pressure hydrogen containment systems is restructuring procurement patterns across major energy infrastructure deployments. This shift reflects buyer risk mitigation against supply concentration and certification bottlenecks.
Growth Catalysts
- Ruhr Industrial Corridor Conversion:Steelmakers and chemical producers in Germany's industrial heartland are converting to hydrogen feedstocks, creating concentrated demand for tube skid systems rated for 350+ bar service pressures.
- EU Green Deal Mandates:The European Union's hydrogen strategy and certified pressure equipment standards are compelling fleet operators and industrial users to accelerate refueling infrastructure procurement timelines.
- Mobile Delivery Logistics:Off-grid industrial users lacking pipeline connectivity are scaling hydrogen delivery via road-transportable tube skids, expanding the addressable market beyond stationary installations.
Market Restraints
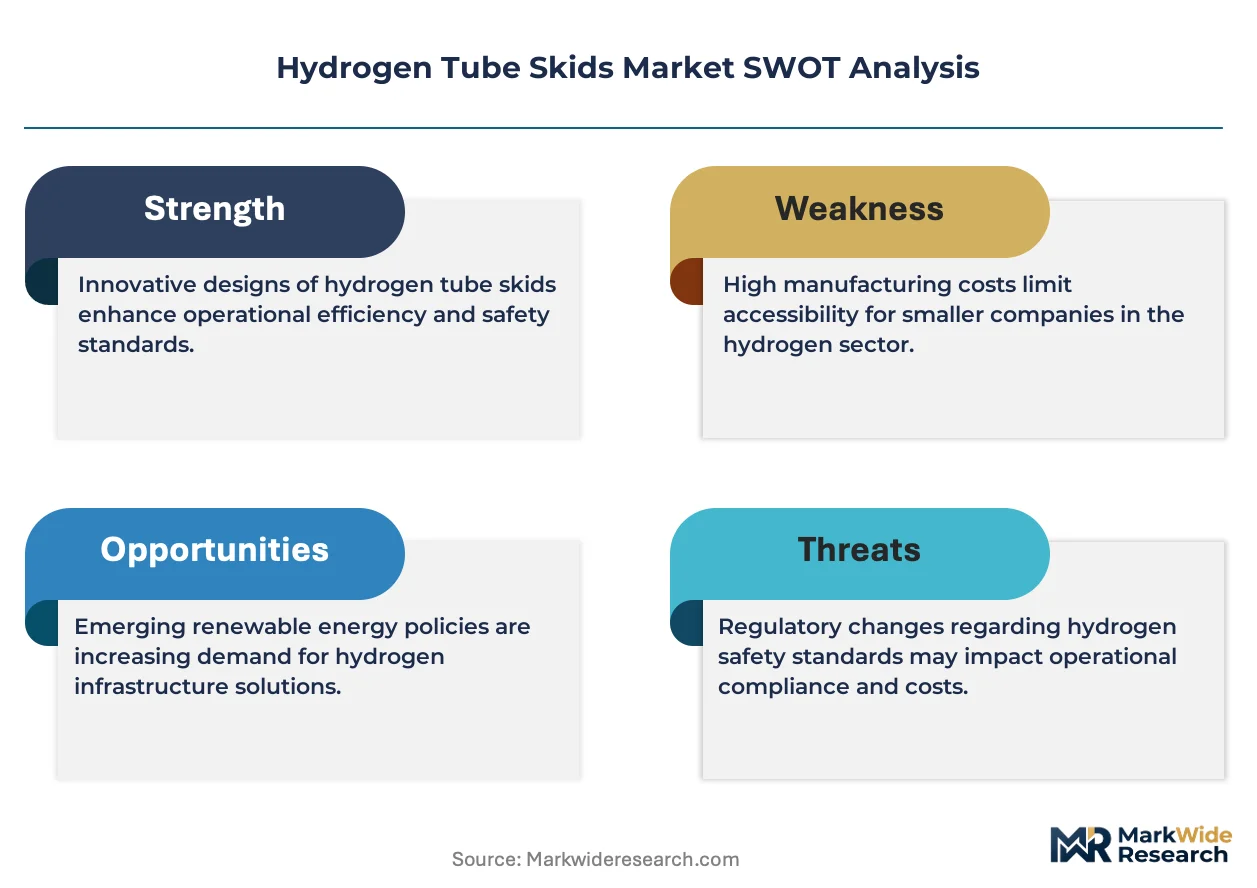
- Chromium-Molybdenum Steel Price Volatility:Input cost fluctuations for high-grade pressure vessel alloys compress margins on standard skid configurations and complicate long-term project budgeting.
- Asia-Pacific Manufacturing Concentration:Captive production of pressure vessels and manifold assemblies in concentrated supply corridors creates geographic risk exposure for buyers seeking supply assurance.
- ISO 19881 Certification Burden:Cylinder design qualification timelines and testing protocols extend deployment schedules, particularly for novel composite liner configurations.
Strategic Opportunities
- Netherlands Hydrogen Backbone:National hydrogen strategy implementation and port infrastructure development at Rotterdam create demand for large-scale compression-integrated skid packages.
- Composite-Steel Hybrid Convergence:Integration of carbon-fiber-reinforced polymer liners with conventional steel manifold systems enables weight reduction without sacrificing pressure ratings.
- Automated Refueling Interface Channel:The EU AI Act and Machinery Directive are creating compliance-driven demand for certified automated dispensing systems, opening aftermarket service revenue streams.
Industry Challenges
- Pressure Equipment Inspector Scarcity:Qualified personnel for ASME and PED certification inspections are in short supply, extending commissioning timelines for complex skid installations.
- Legacy Refinery Integration Complexity:Site-specific engineering requirements for connecting tube skids to existing hydrogen purification and distribution infrastructure demand bespoke design capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Tube Skids Market |
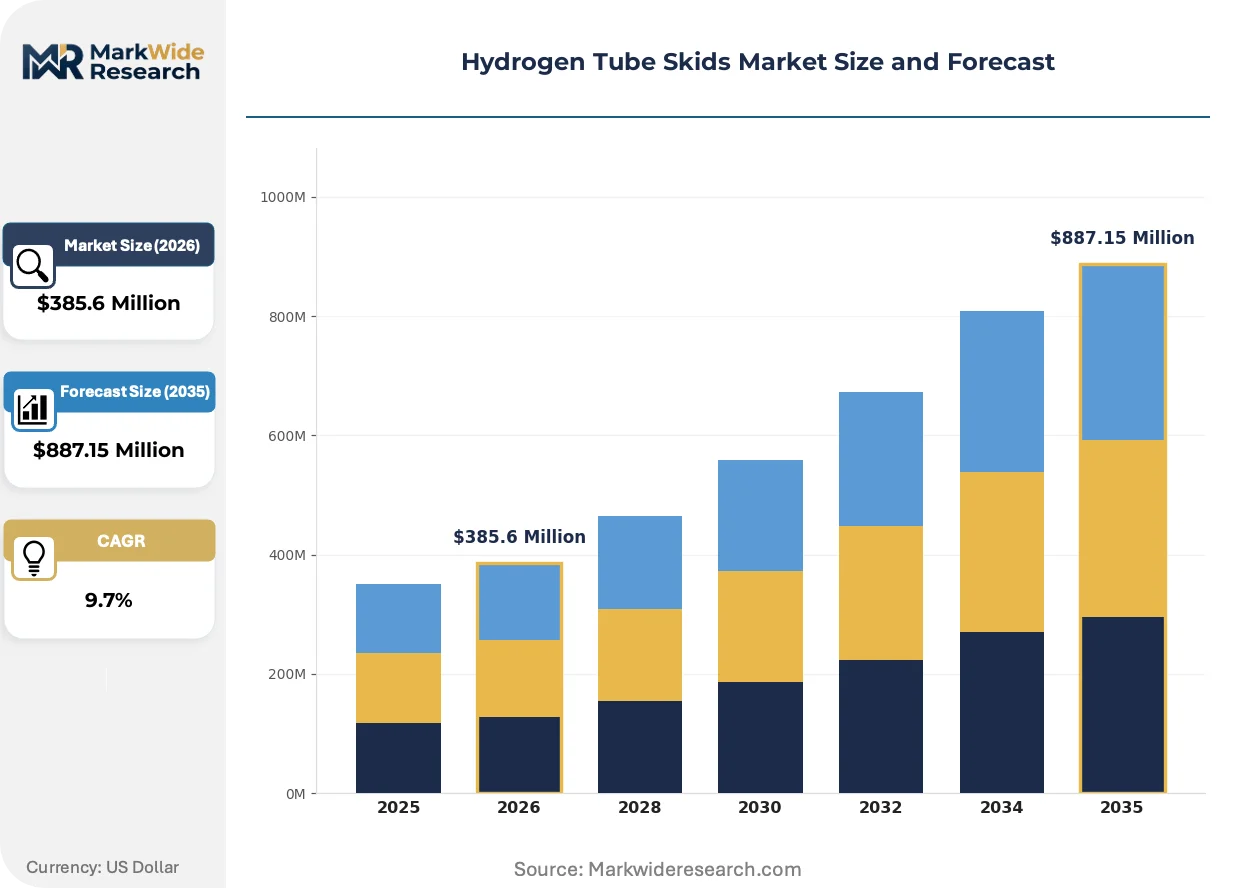
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $887.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Skids, Custom Skids, Mobile Skids, Modular Skids Application: Storage, Transport, Distribution, Refueling Technology: Compression, Cryogenic, Electrical, Mechanical End User: Energy Producers, Industrial Users, Research Institutions, Others |
| Companies Covered | SRISEN ENERGY, Linde Engineering, Hexagon Purus, Baker Hughes Company, SANY Hydrogen Energy Co., Ltd., CIMC Enric Holdings Limited, Beijing SinoCleansky Technologies Corp., Ariel Corporation, Shandong Hydroid Chemical Co., Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Tube Skids Market Trends and Innovations
Modular architecture is displacing monolithic skid designs across hydrogen infrastructure, enabling phased capacity expansion and reducing upfront capital commitment for project developers.
Composite cylinder technology is modularizing hydrogen storage configurations for transport applications. Fleet operators in heavy-duty logistics are adopting lightweight mobile skids to maximize payload efficiency. This structural shift is compressing total cost of ownership differentials between road and rail hydrogen delivery modes.
The EU AI Act conformity assessment requirements are reshaping automated refueling interface design. Industrial consequence includes mandatory third-party verification of sensor and control systems. Mobile skid suppliers targeting the Netherlands and Germany are accelerating software certification roadmaps to maintain market access.
Buyer qualification behavior is fragmenting procurement volumes across multiple approved vendors. Heavy-duty transport fleet operators are unbundling compression, storage, and dispensing system awards to mitigate single-source risk. This pattern is most visible in German hydrogen hub procurements where multi-source frameworks dominate.
Hydrogen Tube Skids Market Segmentation
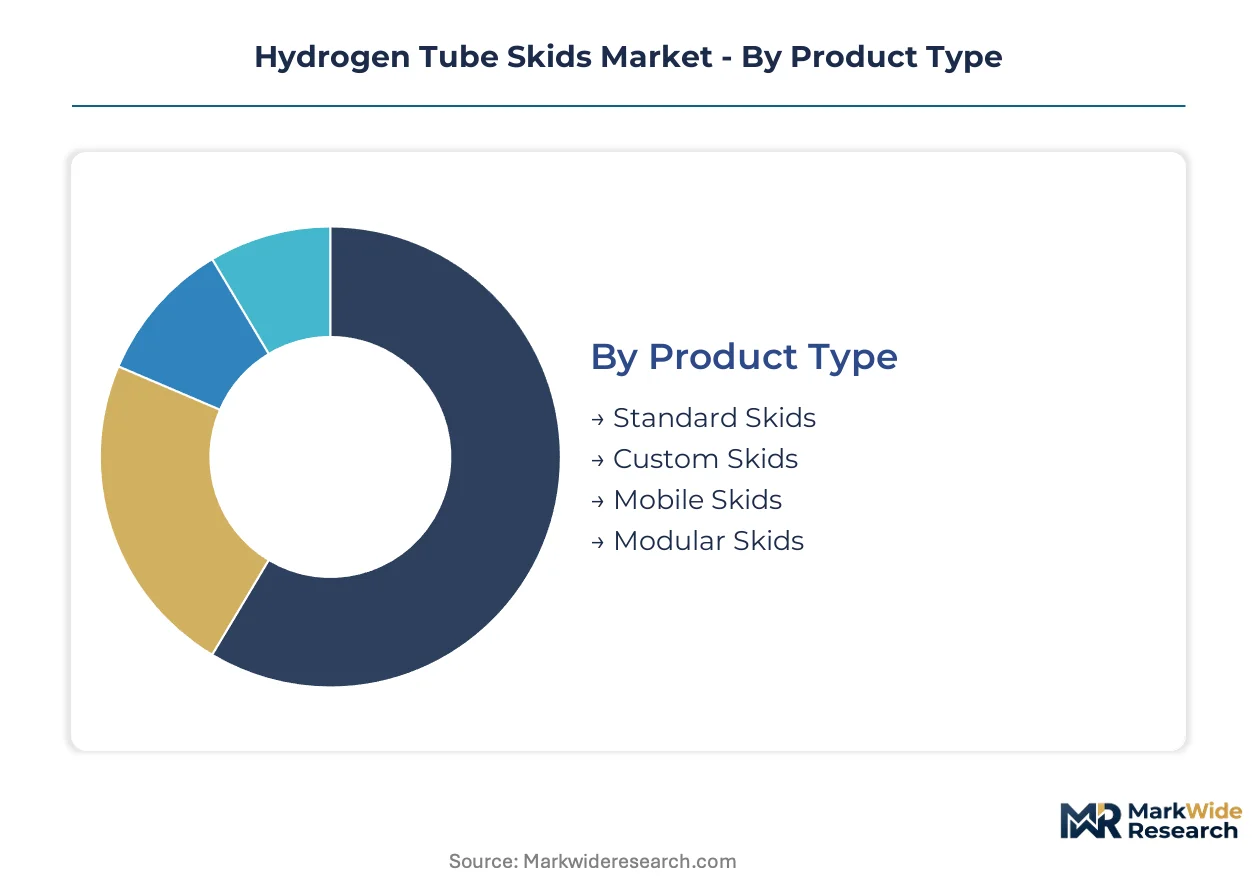
Segmentation in hydrogen tube skids reflects divergent pressure specifications, mobility requirements, and integration complexity across industrial hydrogen value chains. Procurement patterns vary sharply between stationary storage installations and road-transportable delivery systems.
Product Type:
Upgrade cycles diverge substantially between mature standard configurations and emerging modular architectures, with replacement timelines stretching from 15-year pressure vessel recertification intervals to 5-year technology refresh schedules for mobile fleets.
- Standard Skids:Factory-built pressure vessel assemblies rated for 350-700 bar service, constructed from chromium-molybdenum steel with fixed manifold configurations. Demand concentrates in German steelmaking and chemical corridors where Ruhr-region industrial users require certified equipment for hydrogen feedstock conversion under EU Green Deal procurement frameworks.
- Mobile Skids:Road-transportable configurations mounted on ISO container frames or dedicated trailer chassis, optimized for payload efficiency through composite cylinder technology. Off-grid industrial sites in the Netherlands and France lacking pipeline connectivity are scaling procurement for delivery logistics to hydrogen valleys and port clusters.
- Custom Skids:Site-engineered pressure vessel arrays integrating with existing refinery hydrogen purification and distribution infrastructure. Baker Hughes and Hexagon Purus dominate engineering-intensive projects requiring bespoke manifold routing and compression integration.
- Modular Skids:Phased-capacity architectures enabling incremental deployment without full system replacement. Project developers at Rotterdam port hydrogen hubs favor this approach to align capital outlays with offtake contract ramp schedules.
Standard skids sit at the top of the volume ranking, with mobile skids climbing the fastest as road delivery networks expand beyond pipeline-connected industrial zones.
Application:
Cost tier separation between capital-intensive stationary infrastructure and operating-expense-heavy logistics services shapes buyer decision criteria and vendor pricing structures.
- Storage:Stationary tube arrays for buffer inventory and grid-balancing hydrogen reserves. German chemical producers around Leverkusen and Ludwigshafen deploy 48-hour storage buffers to manage electrolyzer output variability.
- Transport:Over-the-road and rail-carriage systems for hydrogen delivery to dispersed industrial users. French heavy-duty fleet operators are scaling procurement of 500+ bar transport skids for depot-to-depot hydrogen logistics.
- Distribution:Hub-and-spoke manifold systems connecting production facilities to multiple downstream offtakers. Netherlands hydrogen backbone developers at Groningen and Zeeland specify distribution skids with automated pressure regulation.
- Refueling:High-flow dispensing systems for heavy-duty transport fleets. German KBA certification requirements for 350-bar and 700-bar interfaces are extending qualification timelines for automated refueling skids.
Storage commands the largest installed base, while refueling applications are gaining share fastest as hydrogen mobility corridors activate across the Benelux-Germany corridor.
Technology:
Application context determines technology selection, with compression-integrated systems commanding premium positioning against passive storage configurations.
- Compression:Skid-mounted reciprocating or diaphragm compressors boosting hydrogen from production pressure to 350-700 bar dispensing levels. Rotterdam port hydrogen hub developers specify compression-integrated packages to minimize footprint at constrained marine terminal sites.
- Cryogenic:Liquid hydrogen storage and vaporization systems for high-density transport applications. French aerospace and maritime hydrogen projects are piloting cryogenic tube skids for extended-range fuel cell propulsion.
- Electrical:Electrically actuated valve manifolds and pressure control systems. EU AI Act conformity assessment requirements are mandating third-party verification of sensor and control architectures.
- Mechanical:Pneumatic and hydraulic pressure regulation without electronic control systems. Industrial users in Germany's Ruhr region specify mechanical systems for explosion-risk environments where electrical certification burdens are prohibitive.
Compression technology leads by revenue contribution, with cryogenic configurations showing steepest expansion trajectory as liquid hydrogen supply chains mature.
End User:
Customer type segmentation reveals divergent procurement sophistication, with energy infrastructure developers unbundling system awards against industrial buyers seeking turnkey integration.
- Energy Producers:Electrolyzer operators and hydrogen hub developers procuring large-scale storage and compression skids. German national hydrogen strategy implementation is concentrating demand among RWE, Uniper, and Shell for 100+ ton per day capacity installations.
- Industrial Users:Steelmakers, chemical producers, and refineries converting feedstock and fuel systems to hydrogen. ThyssenKrupp and BASF procurement specifications are driving ISO 19881 certification requirements for 700-bar steel cylinder arrays.
- Research Institutions:Universities and national laboratories testing novel materials and safety protocols. Dutch TNO and German Fraunhofer institutes operate pilot skids for composite liner validation and refueling interface development.
- Others:Maritime operators, aviation fueling consortia, and backup power system integrators. Port of Rotterdam aviation hydrogen initiatives are emerging as a discrete demand segment.
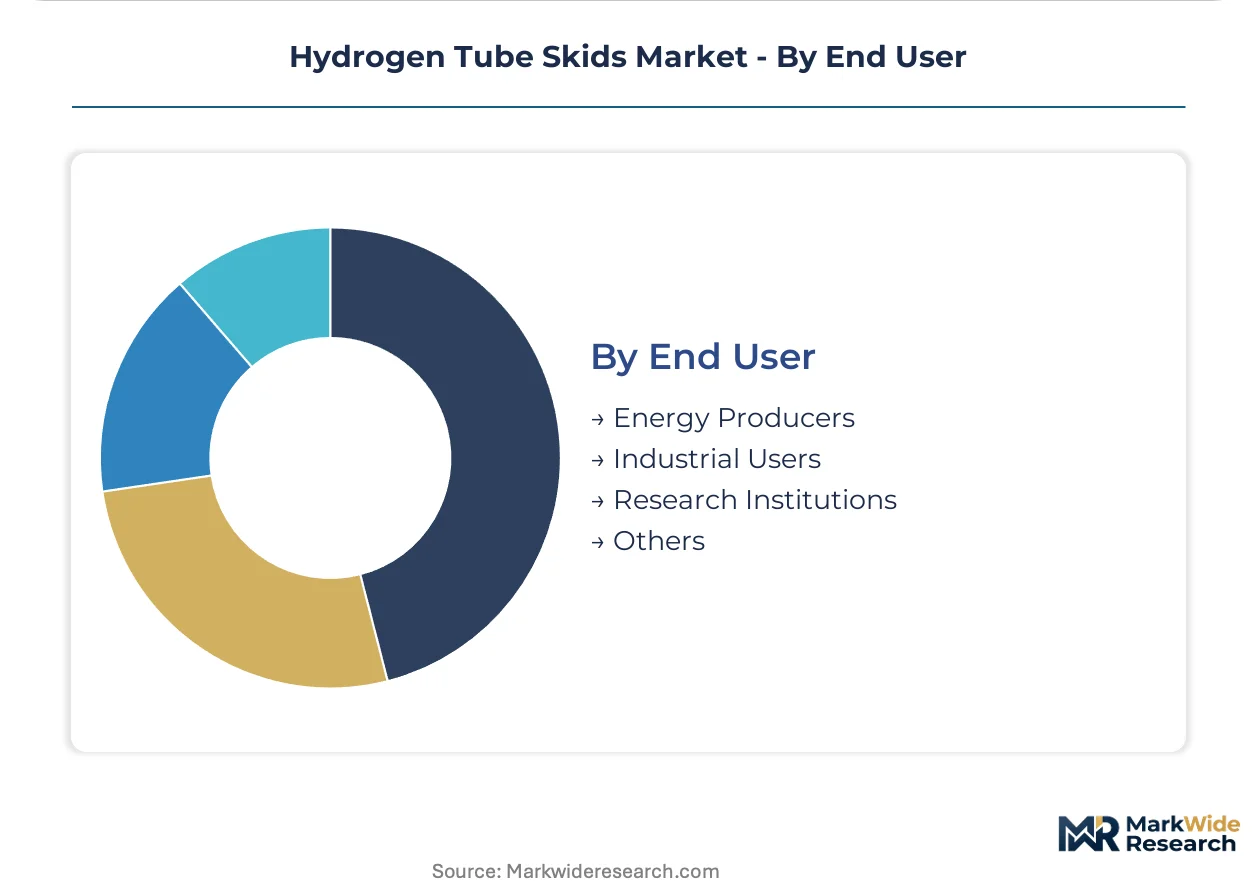
Industrial users dominate current procurement volumes, with energy producers positioned for fastest growth as green hydrogen production scales toward 2030 targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial corridor conversion projects concentrate procurement of 350+ bar tube skid systems among German steelmakers and chemical producers. National hydrogen strategies across Western Europe are mandating certified pressure equipment standards that reshape vendor qualification timelines.
Germany
Steelmakers ThyssenKrupp and chemical giant BASF are converting Ruhr-region facilities to hydrogen feedstocks, driving demand for ISO 19881-certified steel cylinder arrays. KBA certification requirements for 700-bar refueling interfaces extend deployment schedules for automated dispensing systems. Industrial clusters around Leverkusen and Ludwigshafen deploy 48-hour storage buffers to manage electrolyzer output variability.
Netherlands
Port of Rotterdam hydrogen hub developers specify compression-integrated skid packages to minimize footprint at constrained marine terminal sites. National hydrogen backbone implementation at Groningen and Zeeland creates demand for distribution skids with automated pressure regulation. Rotterdam port aviation hydrogen initiatives are emerging as a discrete demand segment for cryogenic tube skid pilots.
France
Heavy-duty fleet operators are scaling procurement of 500+ bar transport skids for depot-to-depot hydrogen logistics across the Benelux-Germany corridor. ANSM conformity assessment protocols govern pressure equipment safety verification for automated refueling interfaces. French aerospace and maritime hydrogen projects are piloting cryogenic tube skids for extended-range fuel cell propulsion systems.
United States
EPA and OSHA enforcement of parallel pressure vessel and workplace exposure protocols shapes product certification roadmaps for cross-border suppliers. Heavy-duty transport fleet operators are unbundling compression, storage, and dispensing system awards to mitigate single-source risk. Industrial hydrogen users in Texas and California Gulf Coast corridors specify mechanical pressure regulation systems for explosion-risk environments.
China
MIIT standards and GB pressure vessel codes govern domestic manufacturing certification for tube skid exports to European markets. CIMC Enric Holdings sustains cost advantages through captive production of pressure vessels and manifold assemblies in Asia-Pacific supply corridors. Shandong and Jiangsu province industrial zones concentrate fabrication capacity for chromium-molybdenum steel cylinder arrays.
Hydrogen Tube Skids Market Competitive Landscape
Global majors compete with regional champions across certification-intensive procurement programs for hydrogen infrastructure. The vendor base separates into three tiers: integrated energy technology conglomerates, specialized composite pressure vessel manufacturers, and scale-driven Asian fabricators. Baker Hughes anchors large-scale compression-integrated packages. Hexagon Purus occupies lightweight mobile skid positioning. CIMC Enric dominates manufacturing scale. Competitive moves concentrate on multi-source qualification compliance and backward integration into pressure vessel forging capacity.
Among engineering-intensive specialists, Baker Hughes Company and Hexagon Purus exemplify divergent archetype strategies. Baker Hughes leverages rotating equipment heritage to anchor hydrogen hub projects requiring bespoke manifold routing and compression integration. Hexagon Purus represents the composite-cylinder specialization vector, occupying positioning for transport applications where payload efficiency governs total cost of ownership. At the manufacturing-scale end, CIMC Enric Holdings Limited sits within the Asia-Pacific fabrication tier, sustaining cost positioning through in-house production of pressure vessels and manifold assemblies. Ariel Corporation and SANY Hydrogen Energy Co., Ltd. represent regional champions from the United States and China respectively, serving domestic procurement frameworks with localized certification compliance.
| Leading Market Players |
|---|
| SRISEN ENERGY |
| Linde Engineering |
| Hexagon Purus |
| Baker Hughes Company |
| SANY Hydrogen Energy Co., Ltd. |
| CIMC Enric Holdings Limited |
| Beijing SinoCleansky Technologies Corp. |
| Ariel Corporation |
| Shandong Hydroid Chemical Co., Limited |
| Others |
Pricing and Supply Chain Analysis
Chromium-molybdenum steel alloy costs cascade through three distinct pricing tiers for hydrogen tube skids, with Ruhr-region industrial buyers absorbing premium markups for ISO 19881-certified arrays while standard configurations face margin compression from Asia-Pacific fabrication competition.
Pricing Analysis
Input-cost pass-through from chromium-molybdenum steel volatility governs pricing trajectories across standard, mobile, and custom skid configurations. Three-tier pricing structure across premium, standard, and economy levels separates ISO 19881-certified custom arrays from factory-built standard units and basic mechanical-regulation skids. Price differentiation hinges on certification grade and volume scale, with 700-bar KBA-certified refueling systems commanding substantial premiums over 350-bar industrial storage units. Cost compression in standard skids is intensifying because CIMC Enric's captive Asian production feeds aggressive pricing into European procurement tenders. Heavy-duty fleet operators exhibit highest price sensitivity, while Rotterdam hydrogen hub developers prioritize compression-integrated packages with minimal footprint over unit economics.
Supply Chain Analysis
Certification and qualification gating through ISO 19881 and EU AI Act conformity assessments constrain supplier entry, concentrating pressure vessel fabrication in China, Germany, and the Netherlands. Raw material dependencies center on chromium-molybdenum steel forgings, carbon-fiber-reinforced polymer liners, and high-pressure valve manifolds. Single-source vulnerability pervades composite cylinder supply, where Hexagon Purus's specialized liner technology creates bottleneck risk for lightweight mobile skid procurement. Distribution runs through EPC contractors and hydrogen hub developers rather than direct OEM sales, with Baker Hughes and Linde Engineering anchoring large-project channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen tube skids function as a stable compounder anchored by EU Green Deal procurement mandates that institutionalize demand across Germany's industrial corridor conversion.
For Market Incumbents: Acquire in-house pressure vessel forging capacity to offset Asia-Pacific supply concentration risk. Baker Hughes and Hexagon Purus should secure captive chromium-molybdenum steel supply agreements to defend margins against CIMC Enric's integrated cost position. ISO 19881 certification investment represents the priority defensive lever as qualification timelines extend for novel composite configurations. For New Entrants and Emerging Players: Enter via cryogenic tube skid pilots for French aerospace and maritime hydrogen projects, where incumbents lack established positioning. Netherlands hydrogen backbone distribution skids with automated pressure regulation present the most penetrable white space. A go-to-market angle anchored in EU AI Act software compliance for automated refueling interfaces bypasses compression-integrated incumbent strongholds. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-source qualification programs fragment procurement volumes across vendors lacking scale. Long-term viability favors backward-integrated fabricators with captive cylinder production and certified installation capabilities. Target acquisition profile centers on regional champions with KBA or ANSM certification track records and established EPC contractor relationships. The signal to watch is German hydrogen hub tender unbundling patterns that separate compression, storage, and dispensing awards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pressure Vessel Forging | Captive chromium-molybdenum steel supply secures margin defense against Asia-Pacific cost pressure. |
| ISO 19881 Certification Acceleration | Compressed qualification timelines unlock German Ruhr industrial corridor procurement windows. |
| Cryogenic Tube Skid Development | French aerospace and maritime pilots create first-mover positioning in liquid hydrogen logistics. |
| EU AI Act Software Compliance Investment | Automated refueling interface certification opens aftermarket service revenue at Rotterdam and Groningen hubs. |
| Multi-Source Qualification Program Participation | Unbundled hydrogen hub tenders at German national strategy sites expand addressable contract scope. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with hydrogen hub project developers, EPC contractors, pressure equipment procurement managers, and aftermarket service directors combined with secondary validation from EU hydrogen strategy implementation reports, KBA certification databases, and SEC filings from listed energy infrastructure conglomerates. Trade data from German Federal Statistical Office and Dutch Customs Administration anchored regional demand quantification.
Historical trendline analysis across electrolyzer deployment schedules and industrial feedstock conversion timelines established baseline growth parameters. Segmentation dimensions modeled include product architecture, application function, pressure rating tier, and end-user procurement sophistication. CAGRs were derived from installed base replacement cycles and green hydrogen production capacity buildout trajectories. Forecast inputs incorporated EU Green Deal funding allocation patterns and national hydrogen strategy procurement calendars.
Inputs from regulatory filing databases and EPC contractor project pipelines were available through the study window; gaps in composite cylinder failure-rate data introduce uncertainty bands around mobile skid adoption projections. Forecasts reflect documented assumptions regarding certification timeline standardization and chromium-molybdenum steel price stabilization. A model refresh is warranted upon material change in EU AI Act implementation schedules or German KBA 700-bar interface certification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
OCTG Pipe Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
Stainless Steel Welded Pipes Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
Polyethylene Pipes Market
Pipes and Tubes
Thermoplastic Pipe Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
North America Hydraulic Fluid Connectors Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
Europe Pipe Market
Pipes and Tubes
Aluminium Tubes for OPC Drum Market
Pipes and Tubes
Compressed Air Pipe Market
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market