
 Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market | 2026-2036
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market Analysis
A capital-intensity divergence between integrated resin producers and downstream fabricators is rotating competitive advantage toward companies with captive chlorination capacity. The Lubrizol Corporation leverages its backward integration into CPVC resin production to sustain margin control across volatile feedstock cycles. Sekisui Chemical Co., Ltd. anchors its position through proprietary continuous chlorination technology that dominates high-pressure Schedule 80 specifications in Asian industrial markets.
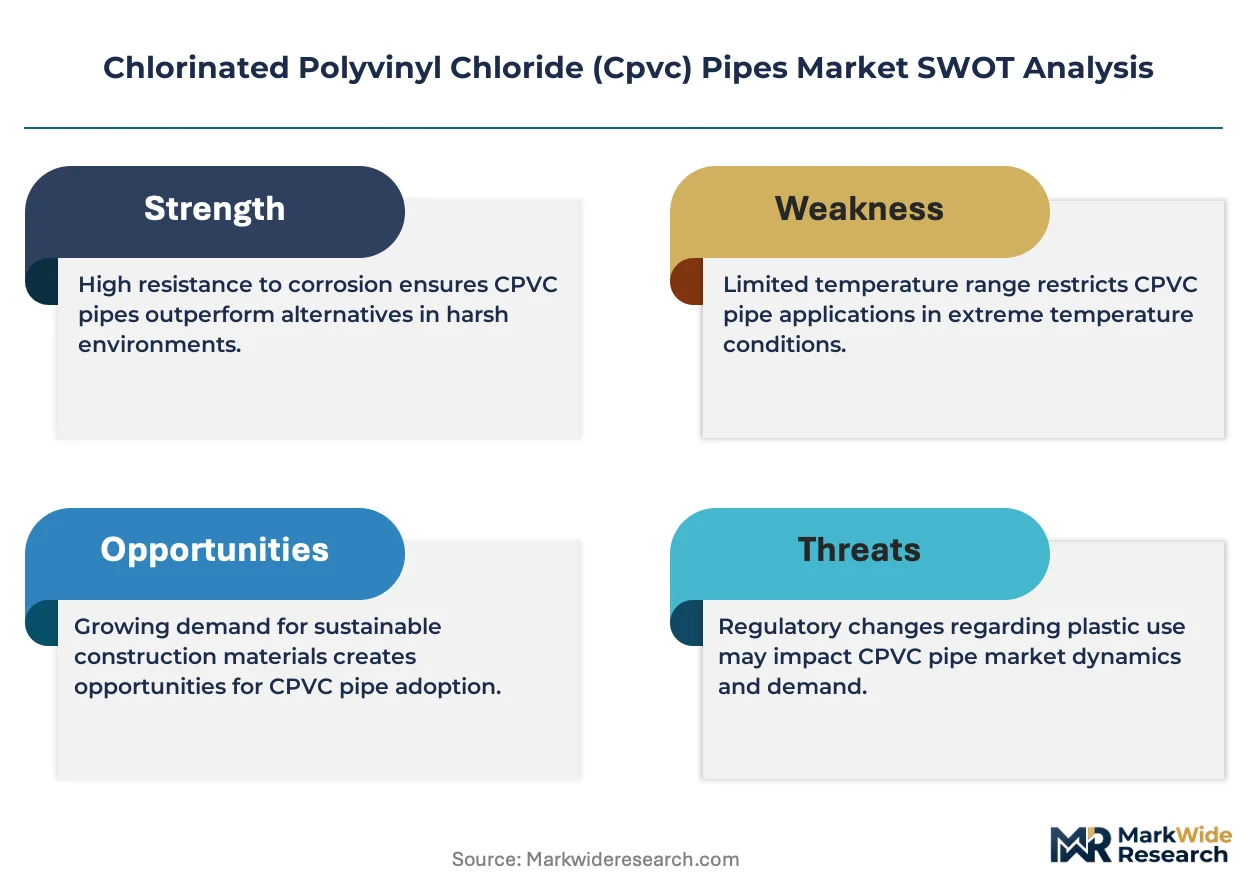
Chlorinated polyvinyl chloride pipes are thermoplastic conduits manufactured by post-chlorination of PVC resin to achieve 67-74% chlorine content, yielding enhanced heat resistance up to 200°F and superior flame-retardant properties for pressurized fluid transport. Plumbing applications command the largest volume share due to universal residential and commercial hot-water distribution requirements, while fire protection systems represent the fastest-growing segment as building codes mandate non-combustible sprinkler networks in mid-rise structures. Schedule 40 specifications occupy the mainstream pricing tier, though Schedule 80 products capture disproportionate margin pools in chemical processing environments where corrosion resistance justifies premium positioning.
ASTM International governs dimensional and performance standards for CPVC pressure piping in the United States, while NSF/ANSI 61 regulates potable water contact compliance; India's BIS certification mandates IS 15778 adherence for domestic plumbing installations. These frameworks elevate barriers for uncertified imports while directing procurement toward established testing protocols. Stakeholders must monitor evolving lead-free mandates and fire-safety code expansions that will reshape specification requirements across municipal and industrial bid packages.
Market Dynamics
The CPVC pipes market is experiencing a structural squeeze between chlorinated resin supply concentration and building-code mandates for fire-resistant plumbing systems. Chlor-alkali feedstock volatility and captive chlorination capacity advantages are redrawing competitive boundaries among pipe fabricators.
Growth Catalysts
- India's Jal Jeevan Mission:The national rural piped water program is specifying CPVC for hot-water distribution networks in millions of household connections, creating sustained volume demand through 2035.
- NFPA 13R sprinkler mandates:US building codes now require non-combustible residential fire suppression in mid-rise structures, accelerating specification of Schedule 80 CPVC for concealed piping systems.
- Continuous chlorination advances:Proprietary reactor designs are reducing residual stress in high-pressure pipe walls, enabling thinner-wall Schedule 40 products to meet industrial chemical resistance standards.
Market Restraints
- Ethylene dichloride cost volatility:Feedstock prices swing with chlorine and ethylene spot markets, compressing margins for non-integrated compounders who lack captive chlor-alkali operations.
- China resin supply dominance:Concentration of bulk CPVC resin production in Shandong and Jiangsu provinces creates geographic supply risk for Southeast Asian fabricators dependent on imported compound.
- PPR thermal expansion advantage:Polypropylene random copolymer pipes offer superior flexibility in freeze-thaw cycles, displacing CPVC in cold-climate residential retrofits across Nordic markets.
Strategic Opportunities
- Vietnam infrastructure buildout:The country's water supply masterplan through 2030 lacks established material preferences, creating a contestable specification window for CPVC against incumbent PVC and metal systems.
- Data center liquid cooling:Hyperscale facilities are evaluating CPVC for secondary cooling loops due to its dielectric properties and flame resistance, opening an industrial segment beyond traditional plumbing.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated refrigerants are pushing HVAC manufacturers toward hydrofluoroolefin systems compatible with CPVC piping rated for moderate pressure-temperature conditions.
Industry Challenges
- NSF/ANSI 61 certification timelines:Potable water contact testing requires 90-day extraction protocols that delay new compound formulations from reaching bid packages, constraining product development velocity.
- Solvent cement installer certification:Proper joint formation demands trained applicators, and contractor skill gaps in emerging markets produce field failures that damage material reputation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market |
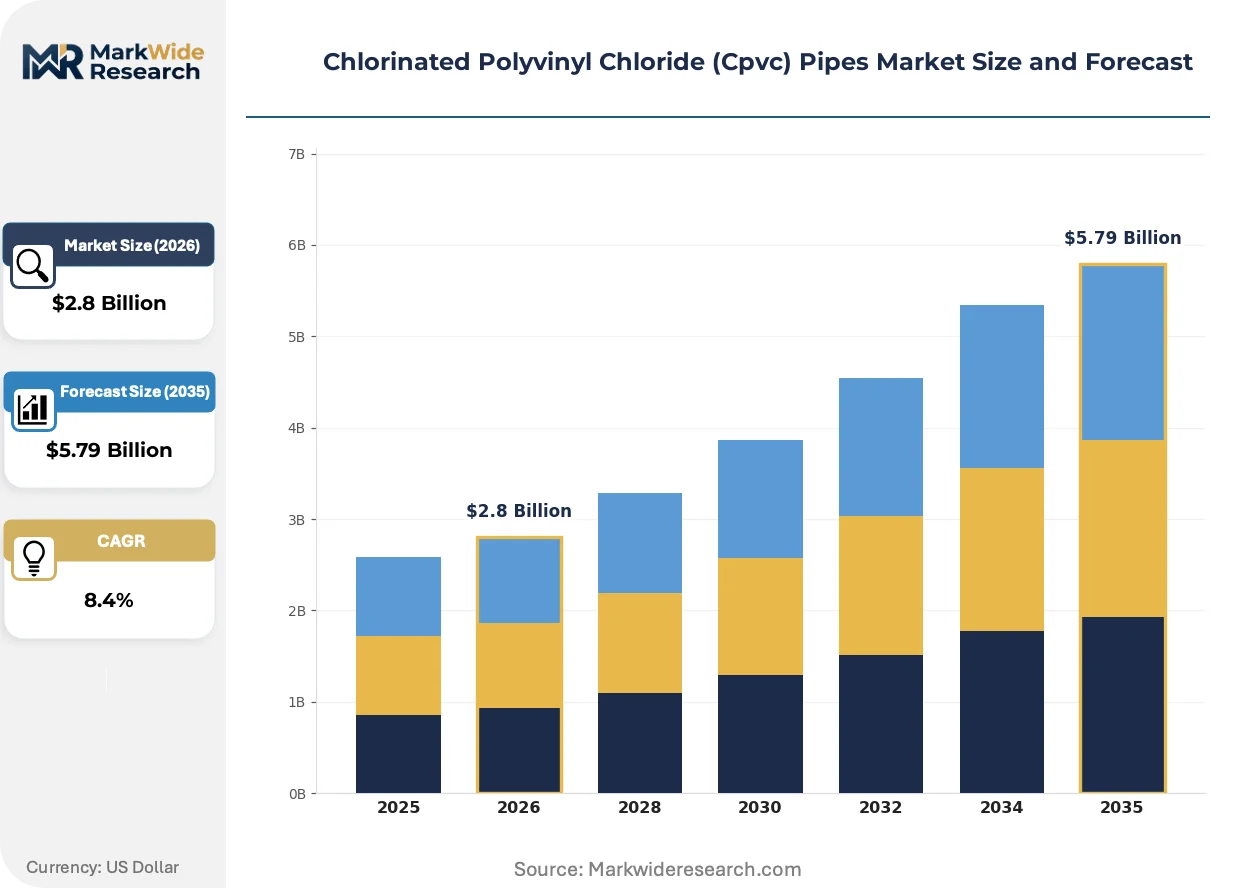
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Schedule 40, Schedule 80, Pipe Fittings, Valves Application: Industrial, Plumbing, Fire Protection, Chemical Processing End User: Construction, Manufacturing, Utilities, Agriculture Distribution Channel: Direct Sales, Wholesale, Retail, Online |
| Companies Covered | The Lubrizol Corporation, Sekisui Chemical Co., Ltd., Charlotte Pipe and Foundry, Astral Limited, Aliaxis Group S.A., Finolex Industries Limited, Prince Pipes and Fittings, IPEX Inc., Ashirvad Pipes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market Emerging Trajectories
Material science advances and code harmonization efforts are compressing specification cycles while opening new performance tiers. Three developments are actively restructuring how CPVC competes against incumbent thermoplastics and metal systems.
Cellular-core CPVC technology is miniaturizing pipe wall thickness without sacrificing pressure ratings. Municipal water utilities in Texas and Florida are specifying these lightweight products for trenchless rehabilitation projects where handling efficiency outweighs material cost premiums. The structural consequence is a compression of the traditional Schedule 40/80 dichotomy, as intermediate-performance products capture mid-market specifications.
REACH Annex XVII restrictions on lead stabilizers are forcing compound reformulation across European supply chains. Manufacturers are accelerating calcium-zinc and organotin alternative testing to maintain CE marking validity for pressure piping applications. Germany's KBA and France's ANSM are coordinating transitional guidance, but the segment most affected—potable water fittings—faces 18-month recertification backlogs.
Specification authority is migrating from general contractors to MEP engineers with direct liability exposure. Design-build firms in California and New York are unbundling material selection from installation bids, creating direct manufacturer-to-engineer channels that bypass traditional distribution markups. This pattern is most visible in high-rise residential towers where fire-performance documentation requirements exceed distributor technical capabilities.
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market Segmentation
CPVC pipe procurement channels fragment across project scales and technical complexity. Specification authority shifts between MEP engineers, municipal procurement officers, and maintenance contractors depending on segment characteristics.
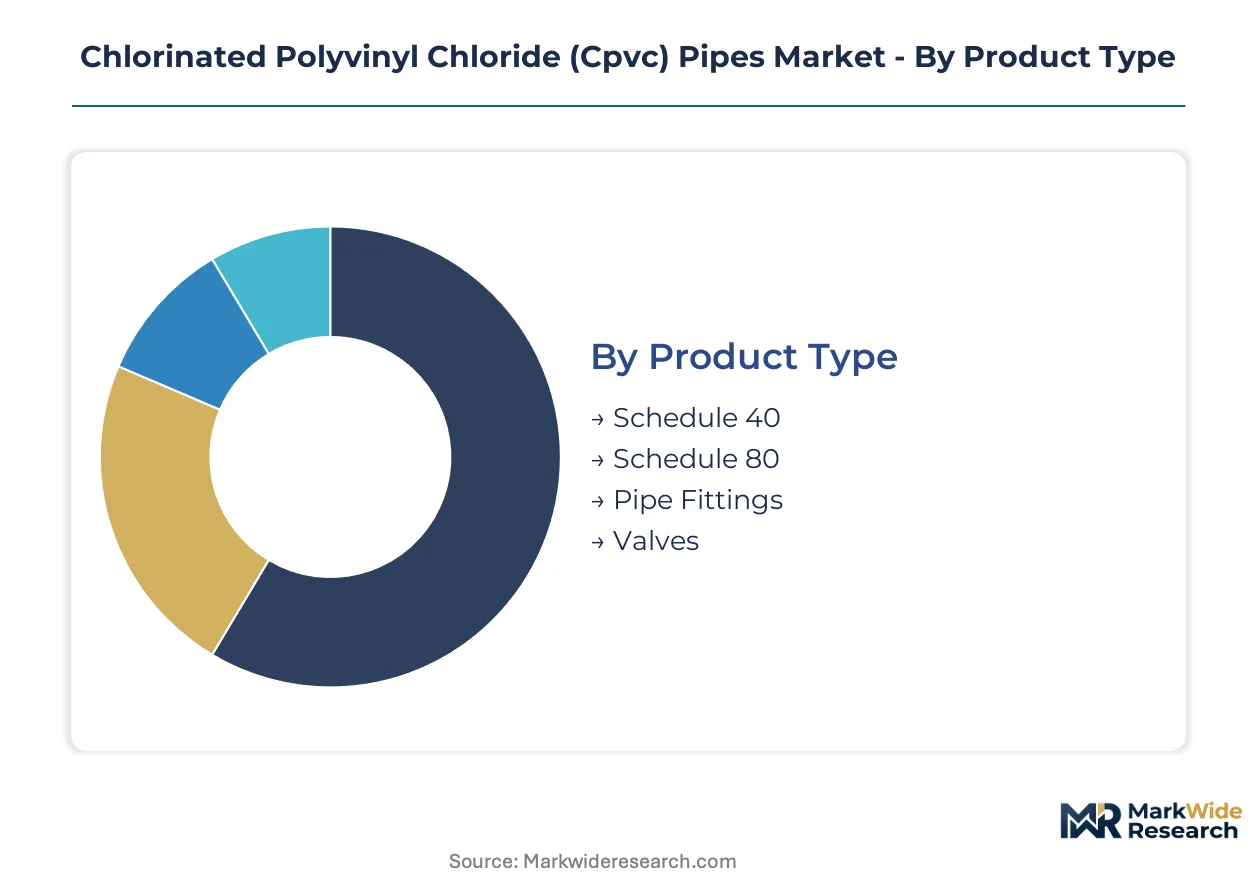
Product Type:
Schedule 40 products move primarily through wholesale plumbing distributors serving residential retrofits. Schedule 80 specifications route through industrial supply houses with certified welding and solvent cement capabilities.
- Schedule 40:Thinner-wall pressure piping rated for 120-150 psi operating conditions dominates residential hot-water distribution. Texas and Florida municipal utilities specify cellular-core variants for trenchless rehabilitation projects where handling efficiency reduces labor costs.
- Schedule 80:Heavy-wall construction with 200+ psi ratings commands industrial chemical processing and high-rise fire suppression applications. Sekisui Chemical's proprietary continuous chlorination technology dominates this tier in Asian industrial markets.
- Pipe Fittings:Elbow, tee, and coupling configurations in CTS (Copper Tube Size) dimensions interface with legacy copper plumbing retrofits.
- Valves:Ball and butterfly configurations with CPVC wetted surfaces serve corrosive fluid isolation in chemical processing environments.
By volume, Schedule 40 leads. By growth pace, Schedule 80 is climbing the fastest.
Application:
Cost tiers separate commodity plumbing from engineered fire protection and chemical processing systems. Premium specifications demand extended NSF/ANSI 61 extraction testing and third-party fire-performance documentation.
- Industrial:Process cooling and chemical transfer lines in semiconductor fabrication and metal finishing facilities. Corrosion resistance justifies material premiums against stainless steel alternatives.
- Plumbing:Residential and commercial hot-water distribution networks. India's Jal Jeevan Mission specifies CPVC for millions of rural household connections.
- Fire Protection:NFPA 13R-mandated residential sprinkler systems in mid-rise structures. Concealed piping specifications favor CPVC's non-combustible properties over thermoplastic alternatives.
- Chemical Processing:Acid and caustic transport in battery manufacturing and electroplating operations. ASTM F441 compliance separates qualified suppliers from commodity entrants.
Plumbing commands the largest volume share. Fire protection is gaining share fastest.
End User:
Customer sophistication determines specification control. Design-build contractors bundle material selection for construction clients, while utilities maintain independent engineering review.
- Construction:General contractors and MEP subcontractors select materials for greenfield and retrofit projects. California and New York design-build firms unbundle specification from installation bids.
- Manufacturing:Industrial facility owners direct procurement for process piping replacement cycles. Chemical resistance documentation exceeds distributor technical capabilities.
- Utilities:Municipal water departments specify materials for distribution network rehabilitation. Texas utilities pilot cellular-core CPVC for trenchless insertion.
- Agriculture:Irrigation system installers favor lightweight handling for field deployment. Freeze-thaw performance limitations constrain adoption in northern climates.
Construction generates the highest transaction volume. Manufacturing shows the steepest specification upgrade trajectory.
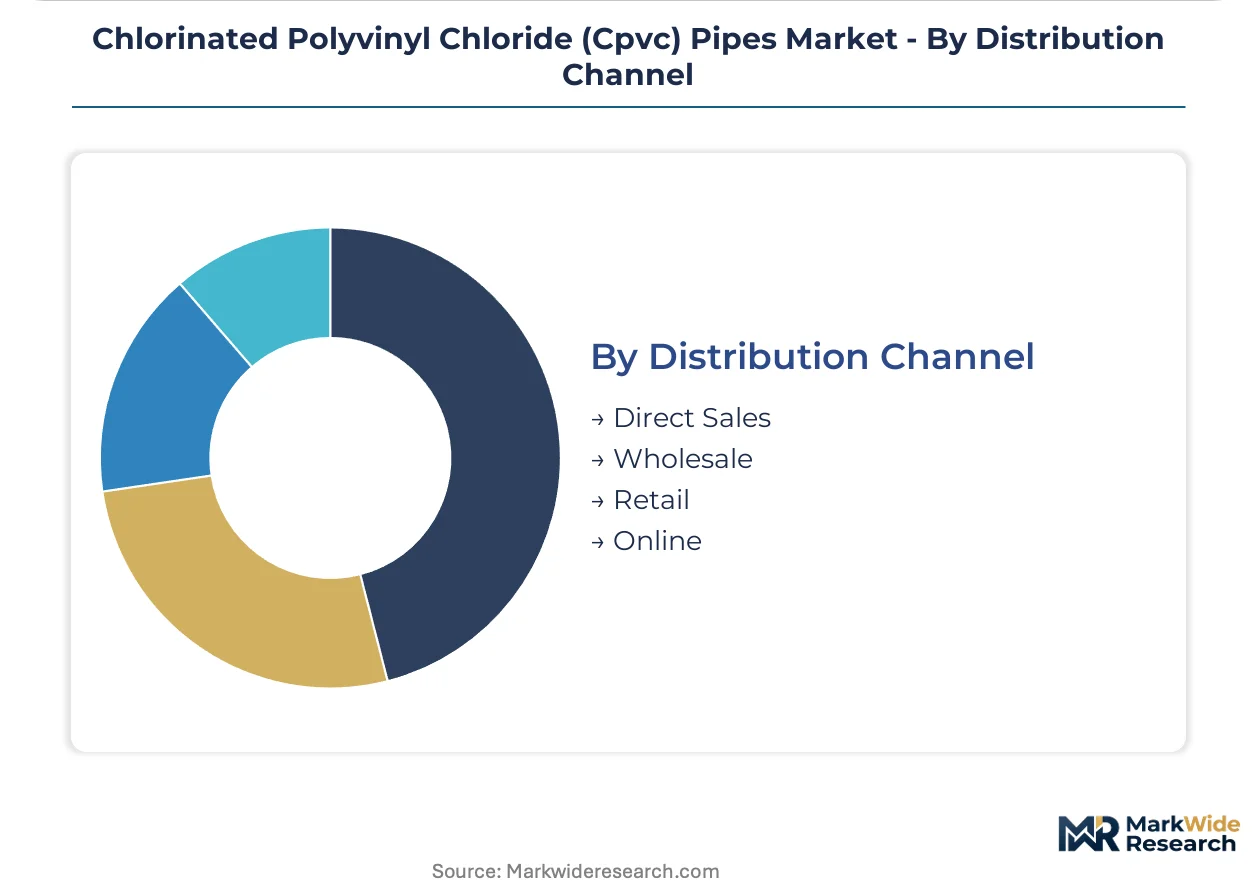
Distribution Channel:
Channel selection tracks project scale and technical service requirements. Large industrial orders bypass distribution markups through direct manufacturer engagement.
- Direct Sales:Manufacturer-to-engineer relationships for high-rise and industrial specifications. Fire-performance documentation and custom fabrication capabilities justify direct engagement.
- Wholesale:Regional plumbing and industrial distributors stock Schedule 40 and standard fittings. Inventory breadth and same-day availability drive contractor loyalty.
- Retail:Big-box home improvement channels serve residential repair and small-scale renovation. Limited to CTS-dimension fittings and repair couplings.
- Online:Specialized industrial marketplaces extend geographic reach for certified Schedule 80 and chemical-grade specifications. NSF/ANSI 61 certification filtering reduces search friction.
Wholesale moves the highest unit volume. Direct sales is expanding most quickly in engineered applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian buyers exhibit the highest price elasticity as government tenders prioritize volume procurement, while US specification engineers demonstrate minimal price sensitivity when fire-performance documentation carries liability exposure.
United States
Residential sprinkler mandates under NFPA 13R drive specification of Schedule 80 products in mid-rise construction. ASTM F441 and NSF/ANSI 61 certifications create compliance barriers for imported alternatives. Texas municipal utilities pilot cellular-core CPVC for trenchless water main rehabilitation in Houston and Dallas-Fort Worth corridors.
India
The Jal Jeevan Mission specifies CPVC for hot-water distribution across millions of rural household connections. BIS certification under IS 15778 mandates domestic testing protocols that favor established compounders. Maharashtra and Gujarat industrial belts concentrate fabrication capacity serving western and southern infrastructure corridors.
China
Shandong and Jiangsu provinces dominate bulk CPVC resin production, supplying Southeast Asian fabricators. GB standards govern pressure piping specifications for domestic chemical processing applications. Yangtze River Delta manufacturing clusters integrate chlor-alkali operations with downstream pipe extrusion.
Germany
REACH Annex XVII lead stabilizer restrictions force compound reformulation across European supply chains. KBA coordinates transitional guidance for pressure piping CE marking validity. North Rhine-Westphalia chemical processing hubs specify corrosion-resistant alternatives to stainless steel infrastructure.
Vietnam
National water supply masterplan through 2030 lacks established material preferences, creating specification contestability. Urban infrastructure buildout in Ho Chi Minh City and Hanoi metro areas drives procurement volume. Foreign fabricators establish local compounding operations to bypass resin import dependency.
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the CPVC pipes market. Captive chlorination capacity separates resin producers from downstream fabricators exposed to feedstock volatility. Three archetypes define competitive positioning: integrated resin-to-pipe compounders, regional fabrication specialists, and diversified thermoplastic distributors. Capacity expansion in high-pressure Schedule 80 specifications and backward integration into chlor-alkali operations constitute the dominant competitive vectors reshaping tier boundaries.
Among integrated resin producers, The Lubrizol Corporation and Sekisui Chemical Co., Ltd. exemplify the captive chlorination archetype that insulates margin structures from ethylene dichloride spot volatility. Charlotte Pipe and Foundry occupies a position within the North American fabrication specialist tier, representing regional scale advantages in ASTM-certified pressure piping. These three anchors illustrate how competitive advantage rotates toward upstream control over chlorinated compound supply.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| Sekisui Chemical Co., Ltd. |
| Charlotte Pipe and Foundry |
| Astral Limited |
| Aliaxis Group S.A. |
| Finolex Industries Limited |
| Prince Pipes and Fittings |
| IPEX Inc. |
| Ashirvad Pipes |
| Others |
Supply Flow & Price Mechanics
Captive chlorination capacity at integrated resin producers establishes scale economies that compress price floors for downstream fabricators lacking backward integration into chlor-alkali operations. This concentration dynamic concentrates margin control among compounders with in-house ethylene dichloride supply while exposing non-integrated pipe extruders to feedstock volatility that erodes competitive positioning.
Pricing Analysis
After-sales service revenue from solvent cement certification programs and installer training contracts drives lifetime value beyond unit pipe sales. Three-tier pricing structure across Schedule 80 premium, Schedule 40 standard, and cellular-core economy levels separates ASTM F441-certified industrial specifications from municipal utility tiers. Cost compression in Schedule 40 residential segments is intensifying because Indian government tenders prioritize volume procurement over performance premiums. Specification engineers in US fire protection applications demonstrate minimal price sensitivity when NFPA 13R compliance documentation carries liability exposure, while rural procurement officers in emerging markets exhibit acute price elasticity.
Supply Chain Analysis
China and India anchor bulk CPVC resin production, with Shandong and Jiangsu provinces supplying Southeast Asian fabricators while Maharashtra and Gujarat industrial belts serve domestic Indian demand. Feedstock draws from chlor-alkali operations, ethylene dichloride spot markets, and calcium-zinc stabilizer alternatives forced by REACH Annex XVII restrictions. Single-source vulnerability concentrates in Shandong resin corridors where geographic disruption would cascade through Asian pipe extrusion networks. Distribution runs through wholesale plumbing distributors for residential Schedule 40 volumes and direct manufacturer-to-engineer channels for high-rise fire protection specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward MEP engineers and municipal procurement officers as specification authority unbundles from general contractor bundles, fragmenting traditional distributor control over material selection.
For Market Incumbents: Shield margin structures by deepening captive chlorination capacity and accelerating NSF/ANSI 61 certification investments that exceed distributor technical capabilities. PPR thermal expansion advantages in Nordic freeze-thaw cycles threaten residential retrofit positioning, requiring defensive capacity addition in Schedule 80 fire protection specifications where code mandates create stickier demand. For New Entrants and Emerging Players: Anchor in Vietnam's water supply masterplan through 2030, where material preferences remain contestable and foreign fabricators can establish local compounding operations to bypass Chinese resin import dependency. Cellular-core trenchless rehabilitation products for Texas and Florida municipal utilities represent the most penetrable white-space segment, accessible through direct engagement with utility engineering departments rather than wholesale channel dependence. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated resin-to-pipe compounders with demonstrated chlor-alkali cost control and established BIS/ASTM certification portfolios. Long-term viability rests on exposure to India's Jal Jeevan Mission volume commitments and US NFPA 13R code expansion trajectories. The signal to watch is cellular-core product adoption rates among municipal utilities, which would indicate specification migration toward lighter-wall performance tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Captive ethylene dichloride supply insulates margin structures from feedstock spot volatility. |
| NSF/ANSI 61 Certification Investment | Potable water compliance creates bid-package barriers against uncertified import competitors. |
| Cellular-Core Product Development | Trenchless rehabilitation specifications in Texas utilities open municipal procurement channels. |
| Direct Manufacturer-to-Engineer Engagement | Bypasses distributor markups in high-rise fire protection where liability documentation exceeds channel capabilities. |
| Local Compounding in Vietnam | Avoids Chinese resin supply concentration while contesting material specification in infrastructure buildout. |
Methodological Framework
Cross-validation between primary interviews with resin plant managers, MEP specification engineers, municipal procurement officers, and wholesale distribution heads anchors the qualitative findings against secondary validation from customs trade data, BIS certification registries, SEC 10-K filings of integrated compounders, and NFPA code documentation. Bottom-up triangulation across pipe extrusion capacity and top-down reconciliation against chlor-alkali feedstock demand curves stress-test volume assumptions.
Sensitivity analysis across the projection horizon models product type segmentation by Schedule 40/80/fittings tiers, application splits across plumbing/fire protection/industrial channels, and end-user differentiation between construction contractors and utility direct procurement. CAGRs derive from regression against Jal Jeevan Mission deployment trajectories and NFPA 13R adoption curves in mid-rise residential construction. Forecast inputs include ethylene dichloride price elasticity coefficients and cellular-core product penetration rates among municipal rehabilitation programs.
Material uncertainties — chlor-alkali feedstock volatility, REACH Annex XVII recertification timelines, and PPR displacement in cold-climate retrofits — sit outside the modeled envelope. Forecasts reflect assumptions about code harmonization and installer certification penetration that could shift with regulatory acceleration or contractor skill gap remediation. Recalibration cycles align with material shifts in ASTM F441 revision schedules and BIS IS 15778 amendment trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Plastic Pipe Market
Pipes and Tubes
Pneumatic Fittings Market
Pipes and Tubes
Thermoplastic Pipe Market
Pipes and Tubes
Saudi Arabia PPR Pipes Market
Pipes and Tubes
North America PVC Pipes Market
Pipes and Tubes
Global Lance Tubes Market
Pipes and Tubes
FRP Pipes and Tanks Market
Pipes and Tubes
Seamless Pipe Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
ESR Tubes Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
Multiflex Tubes Market
Pipes and Tubes
Gas Fittings and Components Market