
 Global Host Cell Contaminant Testing Market | 2026-2036
Global Host Cell Contaminant Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Host Cell Contaminant Testing Market Foresight
Project finance for biologics manufacturing facilities is tilting competitive dynamics toward capital-rich incumbents that can underwrite dedicated testing infrastructure. Thermo Fisher Scientific leverages its chromatography platform breadth to anchor long-term service contracts with multi-product biologics sites. Bio-Rad Laboratories sustains its position through specialized ELISA kit portfolios calibrated to Chinese hamster ovary host cell protein detection. Merck KGaA dominates analytical consumables for monoclonal antibody workflows across European and North American manufacturing hubs.
Host cell contaminant testing encompasses analytical methods that detect residual DNA, proteins, and endotoxins introduced during biopharmaceutical production using bacterial, yeast, or mammalian expression systems. These methods typically achieve sensitivity thresholds below one part per million to ensure patient safety and batch consistency for injectable therapeutics. ELISA kits remain the workhorse format for host cell protein quantification, though mass spectrometry is displacing legacy methods in next-generation gene therapy applications where novel vector constructs demand broader protein coverage. Biopharmaceutical manufacturers constitute the largest end-user segment by value, while contract research organizations are expanding fastest as virtual biotech firms outsource analytical development.
The FDA enforces residual DNA limits through Points to Consider guidance documents, compelling manufacturers to validate quantitative PCR assays for each production cell line. The EMA's Annex 1 revision on sterile manufacturing and the ICH Q5B-Q5D quality guidelines collectively elevate documentation burdens for contaminant testing protocols. Stakeholders must monitor how emerging gene therapy modalities with non-traditional host systems reshape regulatory expectations for orthogonal detection methods.
Market Dynamics
Automated process analytical technology platforms are compressing testing timelines from weeks to hours, forcing contract testing organizations to restructure service architectures around real-time data delivery rather than batch-release documentation.
Growth Catalysts
- Gene therapy pipeline expansion:Viral vector manufacturing in the United States and Germany requires orthogonal detection methods for novel host systems beyond Chinese hamster ovary cells.
- FDA process analytical technology guidelines:The agency's 2004 PAT framework and subsequent QbD enforcement are mandating in-line monitoring for continuous bioprocessing.
- Mass spectrometry sensitivity advances:Orbitrap and Q-TOF platforms now detect host cell proteins below 1 ppm thresholds demanded by ICH Q6B specifications.
Market Restraints
- Reference standard scarcity:Purified host cell protein libraries for Chinese hamster ovary and HEK293 systems command prices exceeding analytical instrument leases.
- Specialized workforce concentration:Skilled mass spectrometrists cluster in Boston, Basel, and Singapore, creating recruitment bottlenecks for secondary manufacturing hubs.
- Platform lock-in effects:Biopharmaceutical firms face switching costs exceeding validation timelines when migrating from ELISA to mass spectrometry workflows.
Strategic Opportunities
- Indian biologics manufacturing emergence:CDSCO's streamlined biosimilar approval pathways are attracting contract manufacturing investment requiring localized testing infrastructure.
- Cell therapy autologous workflows:Patient-specific manufacturing demands rapid contaminant turnaround that automated PCR platforms can address.
- AI-driven spectral interpretation:Machine learning classification of mass spectrometry data is reducing analyst time per sample by an order of magnitude.
Industry Challenges
- Cross-platform correlation deficits:ELISA and mass spectrometry quantification discrepancies for identical host cell protein panels complicate method bridging studies.
- Vector-specific assay development:Adeno-associated virus and lentiviral production systems each require bespoke residual DNA and protein detection protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Host Cell Contaminant Testing Market |
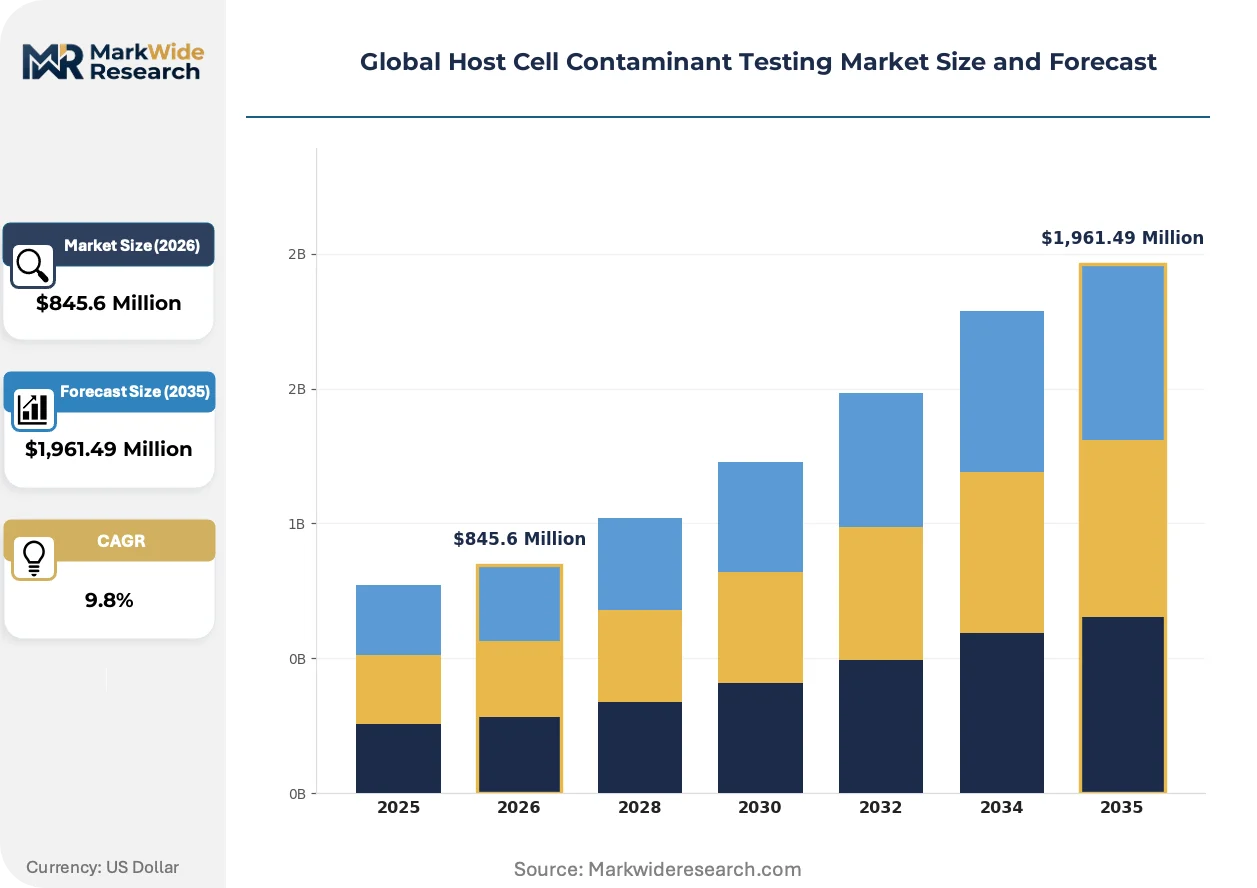
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,961.49 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography Kits, ELISA Kits, PCR Assays, Immunoassays, Flow Cytometry Reagents Technology: Mass Spectrometry, Western Blotting, High-Performance Liquid Chromatography, Capillary Electrophoresis, Enzyme-Linked Immunosorbent Assay End User: Biopharmaceutical Manufacturers, Contract Research Organizations, Quality Control Laboratories, Academic Research Centers, Bioprocessing Facilities Application: Vaccine Development, Monoclonal Antibody Purification, Gene Therapy, Cell Therapy, Protein Therapeutics |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Merck KGaA, Lonza Group, Cygnus Technologies, Charles River Laboratories, Sartorius AG, Danaher Corporation, Enzo Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Host Cell Contaminant Testing Market Shifts & Advancements
Detection methodologies are converging with data architecture investments, creating pressure to consolidate fragmented analytical workflows into unified platforms that serve both quality control and process development functions.
Mass spectrometry is hybridizing with liquid chromatography separation to enable untargeted host cell protein profiling. Gene therapy developers in Massachusetts and North Carolina are adopting these platforms for first-in-human batches. The technology is hybridizing method development timelines, collapsing six-month ELISA optimization cycles into weeks of spectral library generation.
EMA's Annex 1 revision on sterile manufacturing mandates environmental monitoring integration with product testing protocols. European monoclonal antibody facilities must now demonstrate closed-system processing through enhanced endotoxin and bioburden detection. German and Swiss manufacturing clusters are responding by consolidating quality control laboratories into centralized analytical hubs serving multiple production sites.
Biopharmaceutical procurement is fragmenting across virtual development models. Small gene therapy developers without captive manufacturing are unbundling testing services from contract manufacturing organizations, creating direct relationships with specialized analytical providers. This pattern is most pronounced in Cambridge, Massachusetts and Research Triangle Park, where dedicated testing-only contracts now outnumber bundled service agreements.
Global Host Cell Contaminant Testing Market Segmentation
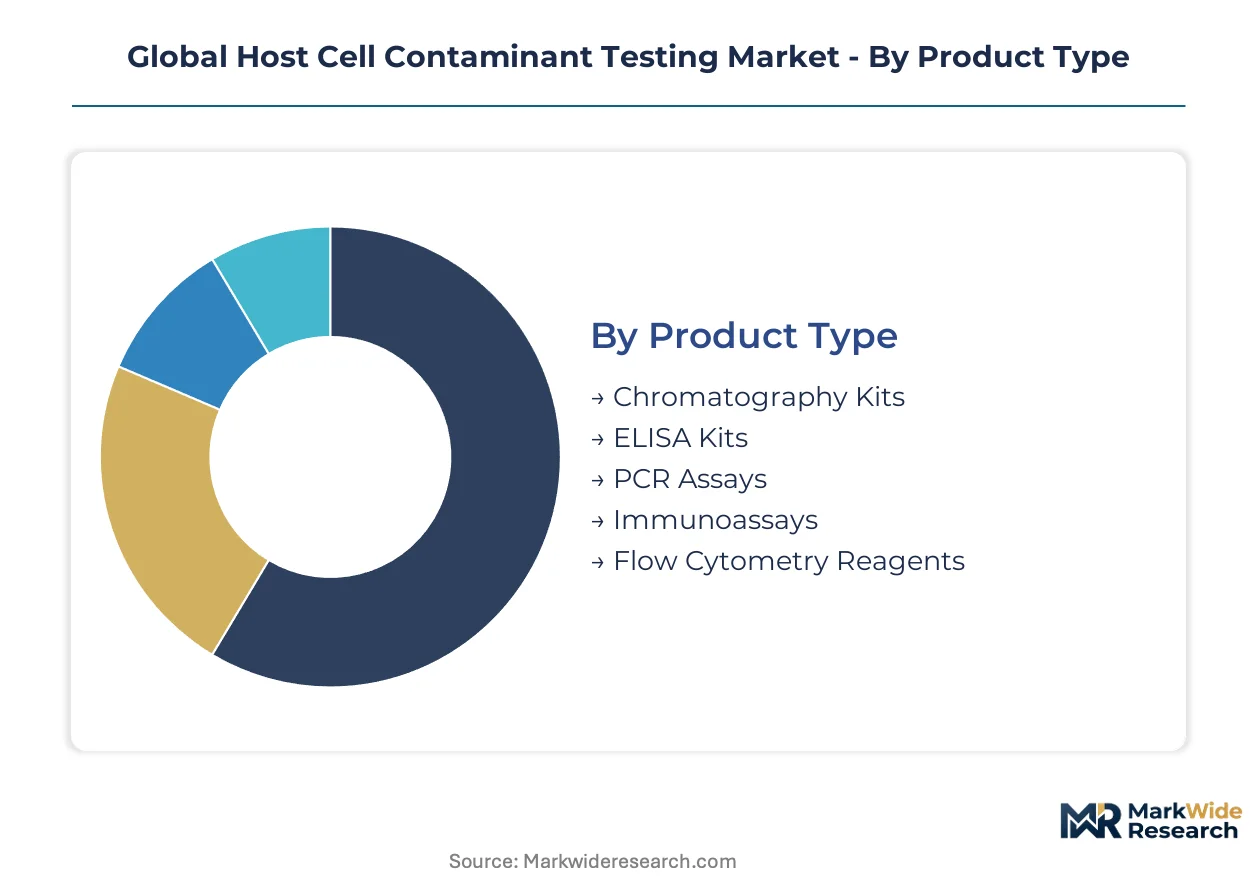
Host cell contaminant testing segments align with distinct stages of biopharmaceutical manufacturing workflows, from upstream expression to downstream purification. Product format selection determines sensitivity thresholds and regulatory compliance pathways for each therapeutic modality.
Product Type:
Cost tier structures differentiate consumable formats based on assay complexity, calibration requirements, and per-test economics across manufacturing scales.
- ELISA Kits:Enzyme-linked immunosorbent assay platforms deliver standardized host cell protein quantification through antibody-antigen binding detection. Biopharmaceutical manufacturers in Massachusetts and North Carolina deploy these kits for routine batch release testing of monoclonal antibody products where validated protocols exist.
- PCR Assays:Quantitative polymerase chain reaction systems amplify residual DNA sequences with femtogram sensitivity for gene therapy vectors. Demand concentrates among viral vector manufacturers facing FDA residual DNA limits, though reference standard scarcity inflates per-assay costs.
- Chromatography Kits:Separation media for contaminant isolation prior to detection.
- Immunoassays:Alternative antibody-based detection formats for specialized protein panels.
- Flow Cytometry Reagents:Fluorescent probes for cell-based contaminant enumeration in cell therapy applications.
ELISA formats command the established base. The steepest expansion runs through PCR assays.
Technology:
Application requirements drive technology selection, with sensitivity demands and protein coverage breadth determining platform economics.
- Mass Spectrometry:Orbitrap and Q-TOF platforms enable untargeted host cell protein profiling with sub-ppm detection limits. Gene therapy developers in Germany and Switzerland adopt these systems for novel vector constructs where ELISA coverage proves insufficient.
- Enzyme-Linked Immunosorbent Assay:Conventional antibody-based quantification remains dominant for established Chinese hamster ovary workflows. Biopharmaceutical manufacturers prioritize this technology for validated monoclonal antibody programs where regulatory pathways are streamlined.
- Western Blotting:Semi-quantitative protein detection for confirmatory testing.
- High-Performance Liquid Chromatography:Separation technology integrated with mass spectrometry or UV detection.
- Capillary Electrophoresis:High-resolution separation for nucleic acid contaminant sizing.
Enzyme-linked immunosorbent assay maintains the largest installed base. Mass spectrometry is climbing the fastest as gene therapy pipelines mature.
End User:
Customer type segmentation reflects organizational scale, captive manufacturing presence, and outsourcing strategy for analytical development.
- Biopharmaceutical Manufacturers:Integrated firms with captive production facilities operate dedicated quality control laboratories. Large-scale monoclonal antibody sites in the United States and Germany consume the highest testing volumes per manufacturing campaign.
- Contract Research Organizations:External analytical providers serve virtual biotech firms without in-house manufacturing infrastructure. Cambridge, Massachusetts and Research Triangle Park host the densest concentrations of specialized testing-only contracts.
- Quality Control Laboratories:Centralized analytical hubs serving multiple production sites.
- Academic Research Centers:Early-stage method development and reference standard generation.
- Bioprocessing Facilities:Contract manufacturing organizations with integrated testing capabilities.
Biopharmaceutical manufacturers anchor volume concentration. Contract research organizations are gaining share fastest as unbundling accelerates.
Application:
Maturity curves and regulatory stringency differentiate therapeutic segments, with novel modalities demanding bespoke assay development.
- Gene Therapy:Viral vector manufacturing requires orthogonal detection methods for HEK293 and Sf9 host systems beyond traditional Chinese hamster ovary workflows. Developers in the United States face the most complex validation burdens as the FDA enforces evolving guidance for adeno-associated virus products.
- Monoclonal Antibody Purification:Established manufacturing templates with standardized host cell protein panels and validated ELISA protocols. European and North American facilities leverage decades of regulatory precedent for batch consistency documentation.
- Vaccine Development:Diverse expression systems including bacterial and yeast platforms with distinct contaminant profiles.
- Cell Therapy:Autologous workflows demand rapid turnaround testing for patient-specific manufacturing.
- Protein Therapeutics:Recombinant protein products requiring residual DNA and endotoxin detection.
Monoclonal antibody purification represents the largest revenue base. Gene therapy shows the steepest expansion trajectory as pipelines advance to commercial scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA process analytical technology guidelines and EMA Annex 1 revisions are redirecting capital toward automated testing infrastructure in established biopharmaceutical manufacturing clusters. National regulators are tightening residual DNA and host cell protein specifications, compelling manufacturers to validate orthogonal detection methods for each production cell line.
United States
Viral vector manufacturing for gene therapy pipelines is intensifying demand for HEK293 and Sf9 host system detection. FDA Points to Consider guidance documents enforce residual DNA limits through quantitative PCR assay validation. The Massachusetts and North Carolina manufacturing corridors command premium testing services as cell and gene therapy developers unbundle analytical contracts from manufacturing organizations.
Germany
Monoclonal antibody production facilities are consolidating quality control laboratories into centralized analytical hubs serving multiple sites. EMA Annex 1 revision mandates environmental monitoring integration with product testing protocols for sterile manufacturing. The Basel-Lörrach biotech cluster spans German and Swiss territory, anchoring European demand for chromatography consumables and mass spectrometry platforms.
Switzerland
Swissmedic oversight of biologics manufacturing elevates documentation burdens for contaminant testing protocols across monoclonal antibody workflows. The country's dual-track regulatory alignment with both EMA and FDA standards attracts multi-territory product development. Basel hosts dense concentrations of analytical instrument deployment for next-generation protein therapeutic manufacturing.
India
CDSCO streamlined biosimilar approval pathways are attracting contract manufacturing investment requiring localized host cell protein testing infrastructure. The central drug regulator's harmonization with ICH Q5B-Q5D quality guidelines accelerates validation requirements for residual DNA detection. Maharashtra and Gujarat biologics manufacturing zones are emerging as secondary hubs for ELISA kit consumption and PCR assay development.
Singapore
Skilled mass spectrometrist concentration is creating recruitment competition for biopharmaceutical analytical development roles. The national pharmaceutical regulator enforces ICH-aligned specifications for injectable therapeutic batch release. Bioprocessing facilities in Tuas and one-north are deploying automated process analytical technology platforms to compress testing timelines for regional export markets.
Global Host Cell Contaminant Testing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Life science conglomerates with chromatography platform breadth anchor long-term service contracts through integrated consumable and instrument offerings. Specialized immunoassay developers sustain positions through calibrated kit portfolios for Chinese hamster ovary host cell protein detection. Analytical consumables suppliers dominate monoclonal antibody workflows through regional manufacturing hub proximity. Competitive moves concentrate on strategic partnerships for automated platform deployment and geographic expansion into emerging biologics manufacturing zones.
Among diversified life science conglomerates, Thermo Fisher Scientific, Danaher Corporation, and Merck KGaA occupy positions spanning chromatography, mass spectrometry, and immunoassay formats. These entities exemplify channel-controlling archetypes that underwrite dedicated testing infrastructure through multi-year service agreements. Bio-Rad Laboratories and Sartorius AG represent product-specialist players with concentrated expertise in ELISA workflows and bioprocess analytical tools respectively. Lonza Group and Charles River Laboratories sit within the contract research tier, capturing unbundled testing demand from virtual biotech firms without captive manufacturing infrastructure.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Merck KGaA |
| Lonza Group |
| Cygnus Technologies |
| Charles River Laboratories |
| Sartorius AG |
| Danaher Corporation |
| Enzo Life Sciences |
| Others |
Supply & Pricing Matrix
The Rotterdam-Basel pharmaceutical freight corridor shapes cost dynamics across the host cell contaminant testing supply chain, with its congestion surcharges compressing margins for European distributors while amplifying price premiums for rapid-turnaround PCR reagents. This logistics pressure concentrates pricing power among integrated suppliers with captive manufacturing in Germany and Switzerland, forcing smaller kit providers toward economy-tier positioning.
Pricing Analysis
Certification level creates the primary spread across the pricing spectrum, with FDA-grade ELISA kits commanding substantial premiums over research-use-only alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation depth and documentation burden. Cost compression in the economy tier is intensifying because Indian biosimilar manufacturers are driving volume procurement of non-validated screening formats. Contract research organizations exhibit the highest price sensitivity due to unbundled service economics, while gene therapy developers show relative inelasticity given regulatory non-negotiability.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for antibody reagent sourcing. Manufacturing concentrates in Germany, the United States, and Singapore, with critical dependencies on Chinese-sourced polystyrene microplates, Irish-produced recombinant antibodies, and Japanese fluorescent probe chemistries. Single-source vulnerability pervades the reference standard segment, where purified host cell protein libraries rely on a limited network of academic generators. Distribution runs through authorized distributor networks serving biopharmaceutical clusters, with direct procurement emerging among large-scale monoclonal antibody manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbents through multi-year validation timelines that new entrants cannot compress. Switching costs exceed eighteen months for method transfers between detection platforms.
For Market Incumbents: Pre-empt displacement by mass spectrometry through hybrid platform offerings that preserve ELISA validation pathways while enabling spectral method bridging. Anchor long-term service contracts with multi-site biopharmaceutical manufacturers through integrated consumable and instrument bundling. Prioritize certification investment in CDSCO-aligned assay formats to capture Indian biosimilar manufacturing expansion before localized competitors entrench. For New Entrants and Emerging Players: Automated PCR platforms for cell therapy autologous workflows represent the most penetrable entry point, given rapid turnaround requirements that incumbent ELISA specialists cannot address. AI-driven spectral interpretation tools for mass spectrometry data classification offer a second white-space target, with machine learning capabilities reducing analyst time per sample by an order of magnitude. A go-to-market angle emphasizing direct relationships with virtual biotech firms in Cambridge and Research Triangle Park bypasses established CMO bundling relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors analytical consumables suppliers with gene therapy assay development capabilities over legacy monoclonal antibody-focused kit providers. The five-to-ten year viability window rewards acquisition targets possessing orthogonal detection method expertise spanning both ELISA and mass spectrometry workflows. The signal to watch is FDA guidance evolution for adeno-associated virus residual DNA limits, which would accelerate platform migration and revalue method-agnostic testing service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | CDSCO alignment with ICH Q5B-Q5D accelerates Indian biosimilar testing infrastructure deployment. |
| Manufacturing Scale-Up | Centralized analytical hubs in Germany consolidate quality control for multiple monoclonal antibody sites. |
| Strategic Partnership | Mass spectrometry platform integration with liquid chromatography enables untargeted host cell protein profiling. |
| Geographic Expansion | Singapore bioprocessing facilities deploy automated PAT platforms for regional export market compression. |
| Acquisition of Specialist Firm | Gene therapy assay developers capture unbundled demand from virtual biotech firms without captive manufacturing. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with biopharmaceutical quality control directors, regulatory affairs specialists, contract research organization procurement leads, and mass spectrometry platform engineers; and secondary validation against FDA Points to Consider guidance documents, EMA Annex 1 revision texts, CDSCO biosimilar approval pathway records, and ICH Q-series quality guidelines. Bottom-up segmentation modeling triangulated against top-down market sizing from instrument installation base analysis and consumable throughput estimates.
Forecast inputs considered gene therapy pipeline maturation, monoclonal antibody manufacturing capacity expansion, and regulatory enforcement intensity across the analysis window. Segmentation dimensions spanned product type, technology platform, end-user category, and therapeutic application modality. CAGRs derived from weighted scenario analysis incorporating probability-adjusted regulatory timeline assumptions and manufacturing investment cycle phasing. Industry-specific inputs included reference standard availability constraints and skilled mass spectrometrist labor market tightness.
Macroeconomic conditions sit as an overlay; deviation in biopharmaceutical capital expenditure cycles or trade policy affecting reagent tariffs would shift the trajectory. Forecasts reflect assumptions about regulatory harmonization pace and gene therapy commercialization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Environmental Testing Equipment Market
Testing Equipment
Global Life Science and Chemical Instrumentation Market
Testing Equipment
Salt Spray Chamber Market
Testing Equipment
Paper Moisture Meter Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
Materials Testing Equipment Market
Testing Equipment
Solar Testing Equipment Market
Testing Equipment
Water Analysis Instruments Market
Testing Equipment
Chromatography Systems Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Geochemical Services Market
Testing Equipment
Laboratory Filtration Equipment and Supplies Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
Binary High Pressure Gradient Liquid Chromatography System Market
Testing Equipment
Rheology Controller Market
Testing Equipment
Membrane Osmometer Market