
 GCC CPVC Pipes Market | 2026-2036
GCC CPVC Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
GCC CPVC Pipes Market Intelligence
Saudi Arabia's petrochemical feedstock base is pivoting toward downstream chlorinated polymer production, creating localized resin supply advantages for pipe extrusion. IKK Group leverages its integrated distribution network across Riyadh and Jeddah to anchor project-level procurement contracts. Georg Fischer Harvel sustains premium positioning through specialized Schedule 80 formulations for industrial chemical handling. Ashirvad Pipes competes aggressively on residential water supply specifications, while SAPPCO dominates local specification standards through deep contractor relationships in the Eastern Province.
Chlorinated polyvinyl chloride pipe systems incorporate 63-69% chlorine content by weight, delivering superior temperature resistance up to 93°C compared to standard PVC, which suits pressurized hot water distribution and corrosive fluid conveyance. Schedule 40 configurations occupy the volume core of residential and commercial water supply installations across Gulf markets, while Schedule 80 wall thickness specifications command margin premiums in industrial chemical processing applications where pressure ratings and mechanical durability determine procurement decisions. Threaded CPVC jointing systems are gaining specification share in maintenance-intensive environments where solvent cement curing constraints disrupt operational continuity.
Saudi Standards, Metrology and Quality Organization (SASO) and the UAE's Emirates Authority for Standardization and Metrology (ESMA) enforce chlorinated polymer compliance protocols that govern pressure rating certifications and potable water contact approvals across Gulf markets. The Gulf Standardization Organization (GSO) harmonization framework reduces cross-border product requalification burdens, though individual member states retain authority over local installation code enforcement. Stakeholders must monitor evolving building energy efficiency mandates that increasingly specify material longevity metrics as lifecycle cost determinants in public infrastructure tenders.
Market Dynamics
Saudi Arabia's municipal water infrastructure replacement cycle is forcing specification upgrades across contractor networks, with SASO pressure-rating mandates accelerating displacement of legacy metal distribution systems.
Growth Catalysts
- SASO Pressure-Rating Mandates:Saudi Standards, Metrology and Quality Organization certification requirements for potable water contact are eliminating non-compliant metal alternatives from public infrastructure tenders.
- High-Rise Construction Codes:UAE plumbing regulations mandating corrosion-resistant materials in vertical buildings are reshaping material specifications across Dubai and Abu Dhabi contractor portfolios.
- Chlorinated Polymer Feedstock Pivot:Saudi petrochemical downstream expansion into localized resin production is reducing import dependency for pipe extrusion operations.
Market Restraints
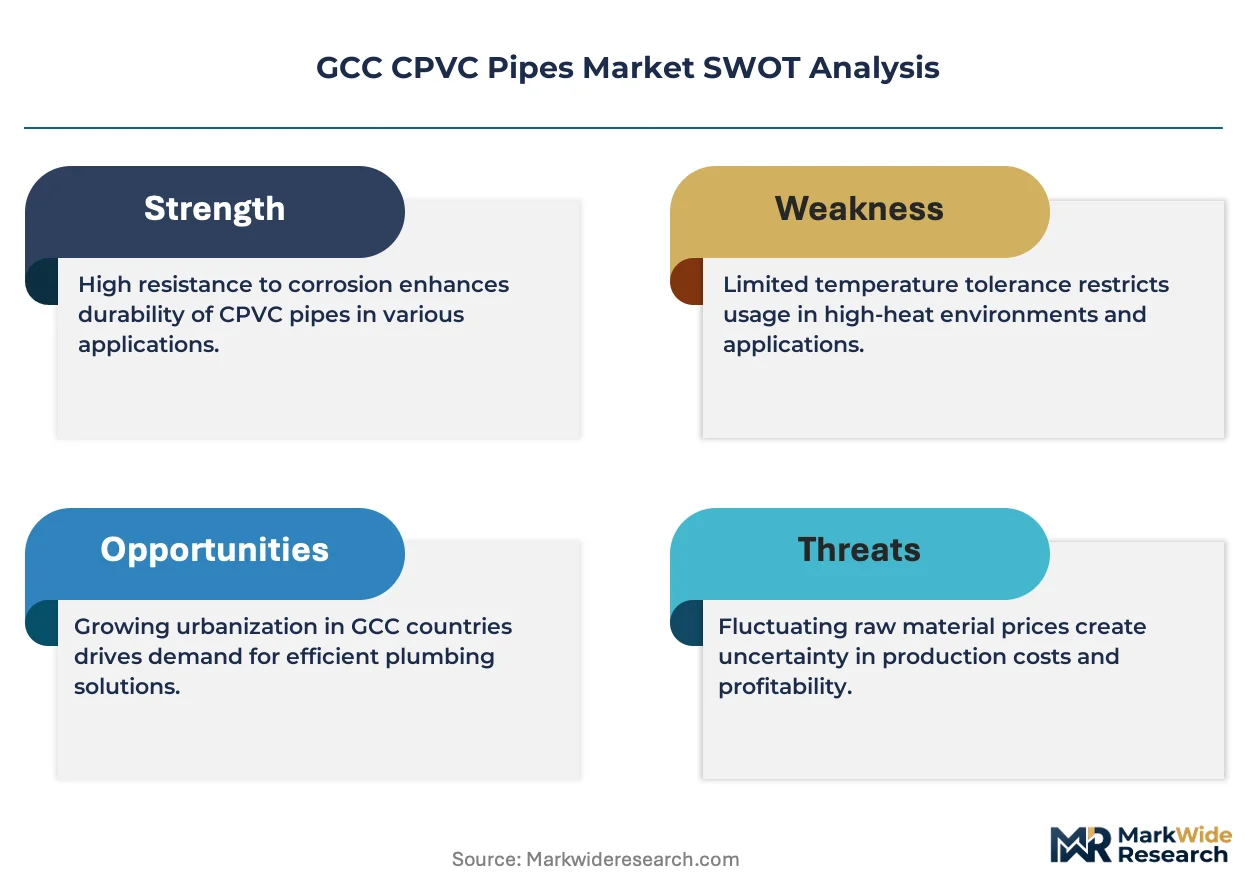
- Chlorine Feedstock Volatility:Electrolytic chlorine production costs fluctuate with regional electricity tariffs, compressing margin predictability for CPVC compounders.
- Specialty Resin Concentration:Global chlorinated PVC resin supply concentrates among limited specialty polymer producers, exposing Gulf converters to allocation risk during demand surges.
- Temperature Ceiling Limitation:CPVC's 93°C operational maximum excludes specification from high-temperature industrial process streams where metal or fluoropolymer alternatives dominate.
Strategic Opportunities
- Industrial Chemical Processing:Schedule 80 wall-thickness specifications for corrosive fluid conveyance remain underpenetrated across Saudi Arabia's Eastern Province petrochemical corridor.
- Threaded Jointing Systems:Maintenance-intensive environments are adopting mechanical jointing to bypass solvent cement curing constraints, opening specification in operational retrofit markets.
- GSO Harmonization Leverage:Gulf Standardization Organization cross-border certification reciprocity reduces requalification costs for multi-territory project bids.
Industry Challenges
- Solvent Cement Installation Certification:Specialized applicator training requirements for pressure-rated joint integrity create bottlenecks in contractor workforce scaling.
- Legacy Metal System Integration:Transition interfaces between existing galvanized distribution networks and new polymer trunk lines demand custom fabrication and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC CPVC Pipes Market |
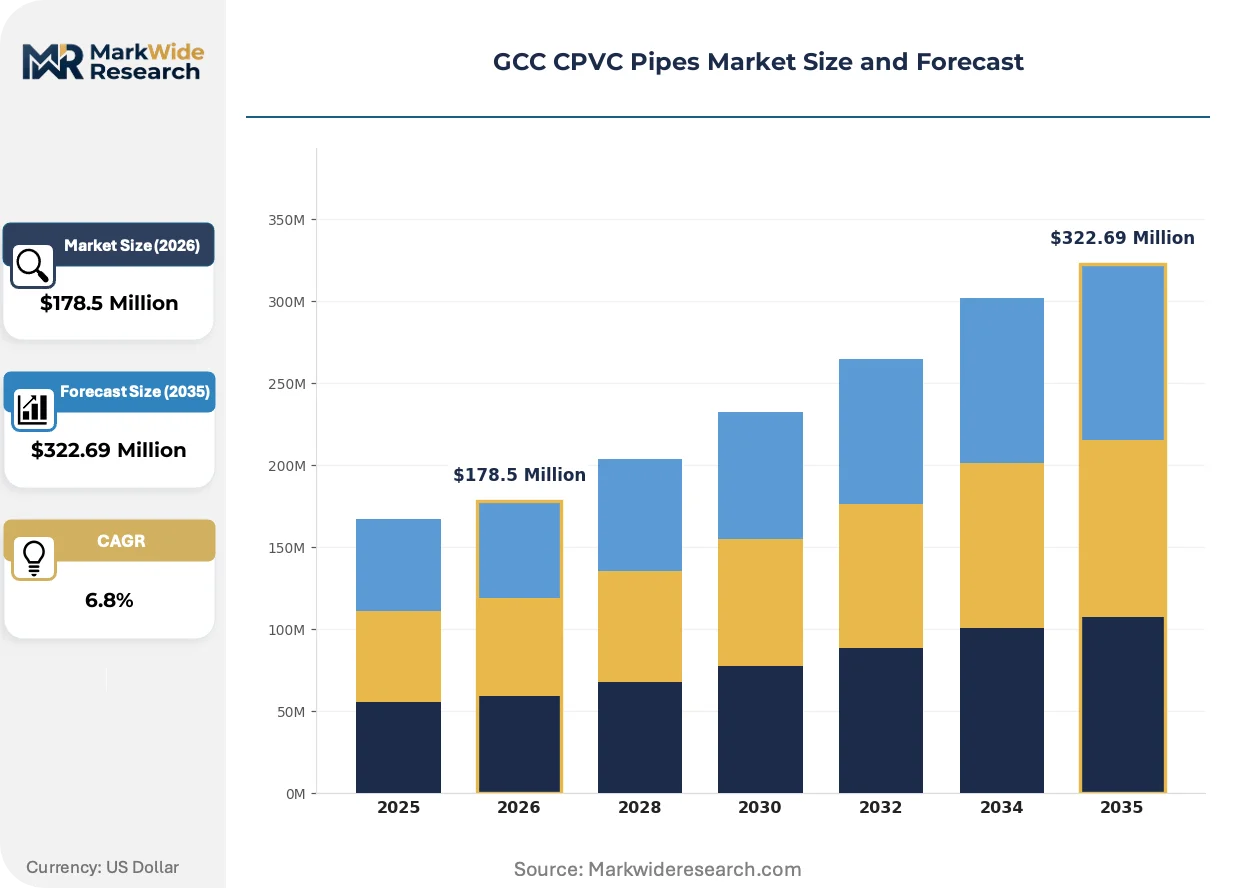
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $322.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Schedule 40, Schedule 80, Threaded CPVC, CPVC Solvent Cement Application: Water Supply, Chemical Processing, Waste Water, Irrigation End User: Residential, Commercial, Industrial, Institutional Installation Type: Above Ground, Underground, Prefabricated, Custom Installation |
| Companies Covered | MMT Group, NIBCO, IKK Group, Fluidra Group, IPEX, AGM, Georg Fischer Harvel, Ashirvad Pipes, SAPPCO, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC CPVC Pipes Market Strategic Shifts & Innovations
Material specification protocols across Gulf construction markets are converging on lifecycle durability metrics, with building energy efficiency mandates recasting procurement evaluation criteria beyond first-cost comparisons.
Multi-layer CPVC formulations with embedded fiberglass reinforcement are unifying pressure performance and thermal expansion control in a single specification. Large-scale residential developers in Riyadh's government-backed housing zones are specifying these composites for high-rise hot water risers. This unification is compressing the traditional segmentation between Schedule 40 residential and Schedule 80 industrial product tiers.
ESMA's updated chlorinated polymer compliance protocols in the UAE are mandating third-party potable water contact certification for all imported pipe stock. Industrial distributors must now maintain batch-traceable documentation from resin source through extrusion. High-rise MEP contractors in Dubai are responding by consolidating supplier relationships with vertically integrated manufacturers capable of end-to-end certification.
Specification authority is migrating from general contractors to specialist MEP consultants who control material submittal approvals. Traditional merchant distributor networks face disintermediation as these consultants develop direct specification relationships with compounders. This shift is most pronounced in Saudi Arabia's Eastern Province, where Aramco-affiliated engineering firms dominate infrastructure project design authority.
GCC CPVC Pipes Market Segmentation
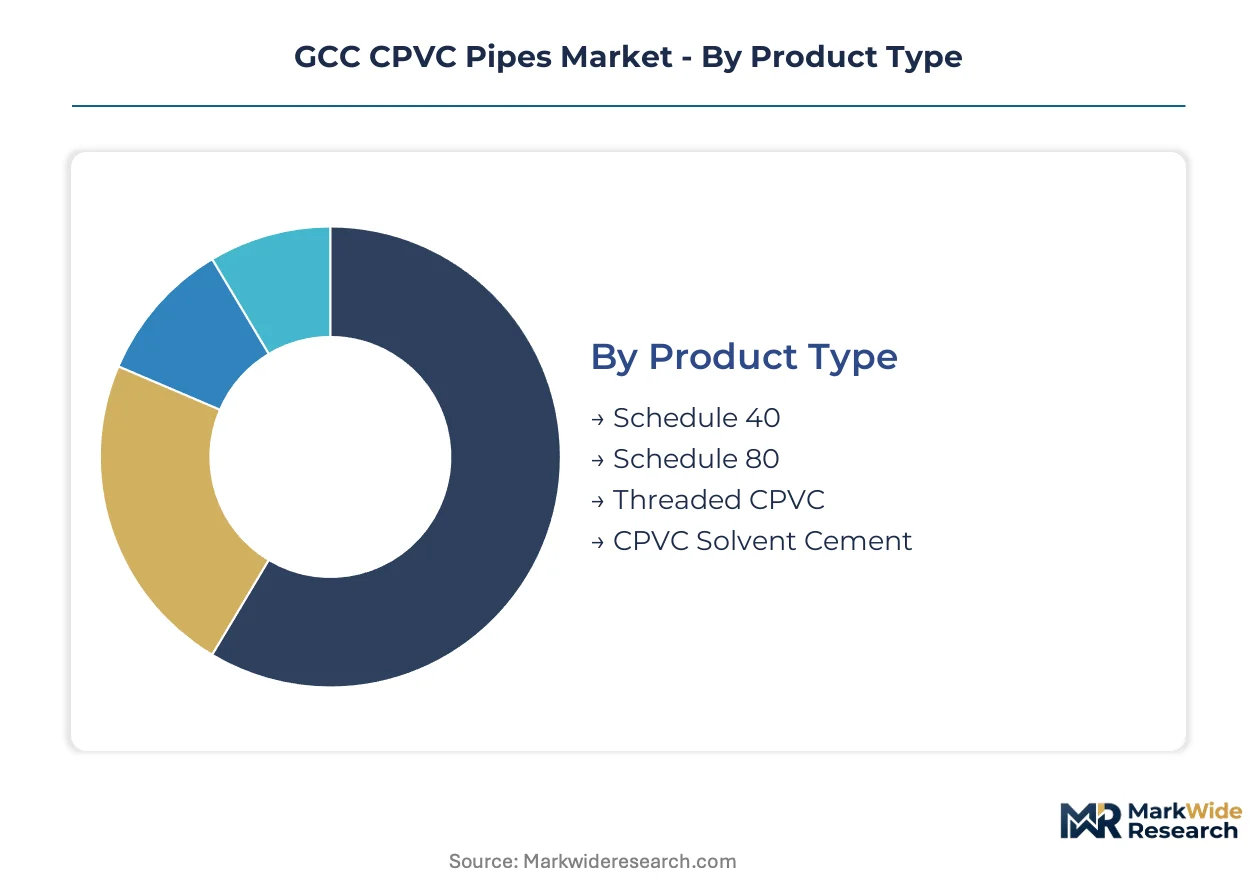
CPVC pipe specification patterns across Gulf markets diverge sharply by pressure rating, installation environment, and end-use thermal demands. Contractors in Saudi Arabia and the UAE select product tiers based on SASO pressure mandates and high-rise plumbing code requirements rather than first-cost considerations alone.
Product Type:
Wall thickness and jointing technology define the specification hierarchy across municipal and industrial procurement channels.
- Schedule 40:Standard wall thickness rated for 150 psi at 23°C serves residential and commercial cold water distribution across Saudi Arabia's government housing zones. Riyadh developers specify this tier for high-rise riser installations where cost efficiency outweighs industrial pressure demands.
- Schedule 80:Heavy-wall construction rated for 230 psi at 23°C dominates corrosive fluid handling in Jubail's petrochemical corridor. Eastern Province processors specify Schedule 80 for acid waste and chemical transfer lines where mechanical durability overrides material cost premiums.
- Threaded CPVC:Mechanical jointing systems bypass solvent cement curing constraints in Dubai maintenance retrofit environments. High-rise MEP contractors specify threaded configurations for operational continuity during system upgrades.
- CPVC Solvent Cement:Chemical fusion jointing remains the default for new construction across Gulf residential markets. Applicator certification requirements under SASO protocols create workforce bottlenecks in rapid-deployment housing projects.
Schedule 40 leads on scale; Threaded CPVC leads on momentum.
Application:
Fluid conveyance requirements segment demand across temperature, pressure, and chemical resistance axes.
- Water Supply:Potable distribution accounts for volume concentration across Saudi Arabia's municipal replacement cycle. SASO potable water contact certifications filter non-compliant imports from Eastern Province infrastructure tenders.
- Chemical Processing:Acid and caustic handling in Jubail and Yanbu industrial zones demands Schedule 80 specifications. Petrochemical operators specify CPVC for secondary containment and process drainage where metal corrosion accelerates maintenance costs.
- Waste Water:Corrosive effluent conveyance in Abu Dhabi commercial districts drives specification for chlorinated polymer drainage. High-rise building codes mandate corrosion-resistant materials for vertical waste stacks.
- Irrigation:Agricultural distribution in Saudi Arabia's central Qassim region adopts CPVC for hot climate durability. Government-backed farm modernization programs sustain procurement volume for pressure-rated irrigation laterals.
Water Supply dominates absolute volume; Chemical Processing commands margin premiums.
End User:
Customer scale and project type determine procurement channel access and specification authority.
- Residential:Government-backed housing programs in Riyadh and Jeddah sustain high-volume Schedule 40 procurement. National developers consolidate supplier relationships to secure batch-traceable SASO certification.
- Commercial:High-rise construction in Dubai and Abu Dhabi reshapes MEP consultant specification authority. ESMA compliance protocols force distributor consolidation toward vertically integrated manufacturers.
- Industrial:Petrochemical and desalination operators in Saudi Arabia's Eastern Province specify Schedule 80 for process reliability. Aramco-affiliated engineering firms control material submittal approvals through direct compounder relationships.
- Institutional:Hospital and university projects across the UAE specify CPVC for hot water distribution longevity. Lifecycle cost evaluation under energy efficiency mandates favors material durability over first-cost savings.
Residential anchors procurement volume; Industrial drives specification complexity.
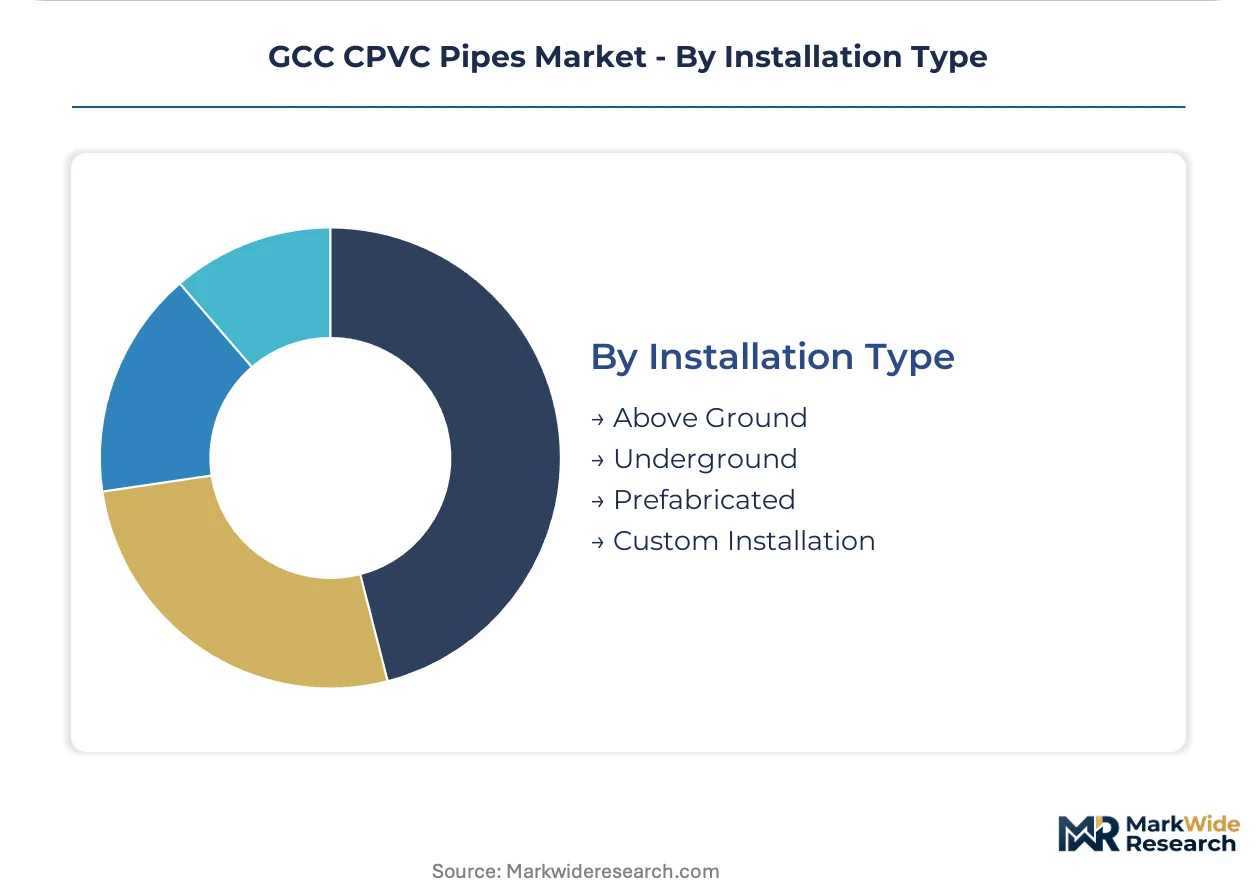
Installation Type:
Deployment environment dictates jointing method, thermal expansion accommodation, and access for maintenance.
- Above Ground:Exposed riser installations in high-rise buildings require UV-stabilized formulations and expansion joint spacing. Dubai contractors specify above-ground configurations for MEP shaft accessibility.
- Underground:Buried municipal distribution in Saudi Arabia demands bedding specifications and thrust block engineering. SASO mandates pressure testing protocols for trench-installed trunk lines replacing legacy metal networks.
- Prefabricated:Modular skid-mounted systems for industrial chemical processing concentrate fabrication in Jubail specialist workshops. Off-site assembly reduces solvent cement curing delays in operational environments.
- Custom Installation:Retrofit interfaces between CPVC and legacy metal systems require custom fabrication for galvanic isolation. Eastern Province contractors extend commissioning timelines for mixed-material transitions.
Underground leads on project scale; Prefabricated expands most quickly in industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlorinated polymer pipe production is concentrating where petrochemical feedstock access lowers resin conversion costs. SASO and ESMA compliance protocols create regulatory arbitrage opportunities for Gulf-based compounders versus import-dependent distributors.
Saudi Arabia
Riyadh's government-backed housing programs sustain high-volume Schedule 40 procurement for residential water distribution. SASO pressure-rating mandates accelerate displacement of legacy galvanized networks in municipal tenders. Eastern Province petrochemical operators specify Schedule 80 configurations for acid waste handling in Jubail industrial zones.
United Arab Emirates
Dubai high-rise construction codes mandate corrosion-resistant materials for vertical plumbing stacks in commercial towers. ESMA third-party potable water certification requirements filter non-compliant imports from distributor portfolios. Abu Dhabi institutional projects specify CPVC for hospital hot water longevity under lifecycle cost mandates.
Qatar
Lusail City development and World Cup legacy infrastructure sustain specification volume for pressurized distribution systems. Qatar General Organization for Standardization chlorinated polymer protocols align with GSO harmonization frameworks. Doha-based MEP consultants consolidate supplier relationships toward vertically integrated manufacturers with batch-traceable documentation.
Kuwait
Ministry of Public Works water network modernization drives procurement for corrosion-resistant trunk line replacement. Kuwait Authority for Conformity Assessment enforces pressure vessel compliance protocols for potable contact applications. Ahmadi industrial corridor processors specify Schedule 80 for chemical drainage in refinery maintenance cycles.
Oman
Special Economic Zone at Duqm petrochemical downstream investments create localized resin supply potential for pipe extrusion operations. Ministry of Commerce, Industry and Investment Promotion standards harmonization reduces import requalification burdens. Muscat residential developers adopt CPVC for high-rise hot water distribution as building codes update toward Gulf norms.
GCC CPVC Pipes Market Key Industry Players
Gulf-based producers anchor one tier through petrochemical feedstock integration; European and North American specialists hold premium positioning through formulation expertise and certification depth. The vendor base stratifies across three tiers: integrated resin-to-pipe compounders, regional extrusion specialists, and import-dependent merchant distributors. Two strategic archetypes dominate: backward-integrated petrochemical players leveraging captive chlorine supply, and specification-focused technical compounders commanding margin premiums in industrial applications. Competitive moves concentrate on SASO/ESMA certification pre-qualification and MEP consultant direct relationship development.
Within the integrated distribution tier, IKK Group anchors project-level procurement across Riyadh and Jeddah contractor networks. Georg Fischer Harvel exemplifies premium-tier positioning through specialized industrial formulations. Ashirvad Pipes occupies aggressive residential specification territory, while SAPPCO represents local standards dominance through Eastern Province contractor relationships. These four names illustrate the competitive spectrum from volume-driven housing procurement to margin-protected chemical processing applications.
| Leading Market Players |
|---|
| MMT Group |
| NIBCO |
| IKK Group |
| Fluidra Group |
| IPEX |
| AGM |
| Georg Fischer Harvel |
| Ashirvad Pipes |
| SAPPCO |
| Others |
Cost & Logistics Intelligence
Certified solvent cement applicator pools in Saudi Arabia's Eastern Province create labor-cost differentials that widen pricing-tier spreads between standard Schedule 40 residential specifications and premium Schedule 80 industrial formulations. SASO-mandated installer qualifications compress margins for rapid-deployment housing projects while sustaining premium capture in petrochemical corridor maintenance contracts.
Pricing Analysis
Distributor margin layers stratify pricing across three tiers: merchant distributors extract 15-20 point markups on imported Schedule 40 stock, while direct-to-project sales by integrated compounders bypass middlemen for large Eastern Province tenders. Price differentiation hinges on certification depth and volume scale, with batch-traceable SASO documentation commanding 8-12 point premiums over non-compliant imports. Pricing pressure stems from chlorine feedstock volatility tied to Saudi electricity tariff fluctuations, compressing compounder margins during peak summer demand. Residential developers in Riyadh's government housing zones exhibit highest price sensitivity, while Jubail petrochemical operators prioritize mechanical durability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and U.S. specialty resin producers who dominate global chlorinated PVC polymer supply. Raw material dependencies center on electrolytic chlorine, ethylene feedstock, and specialty stabilizer packages sourced from Saudi petrochemical complexes and Asian additive specialists. Tariff exposure looms for Gulf converters dependent on Far East resin shipments through Strait of Hormuz chokepoints. Distribution runs through project-level procurement contracts anchored by IKK Group's Riyadh-Jeddah network and direct compounder relationships with Aramco-affiliated engineering firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC CPVC pipes market functions as a stable compounder, with municipal infrastructure replacement cycles and high-rise construction code mandates generating predictable specification volume across the analysis window.
For Market Incumbents: Anticipate disintermediation pressure from MEP consultant direct specification relationships by deepening captive chlorine supply integration and securing batch-traceable SASO certification for entire product portfolios. Defend position against emerging fiberglass-reinforced composite entrants through Schedule 80 formulation specialization for Jubail petrochemical maintenance cycles. Prioritize certification investment in threaded jointing systems to capture retrofit market share where solvent cement curing constraints exclude traditional offerings. For New Entrants and Emerging Players: Mechanical jointing technology offers a technology-first wedge into Dubai high-rise maintenance retrofit environments where operational continuity demands bypass solvent cement curing delays. Target underpenetrated Schedule 80 specifications in Saudi Arabia's Eastern Province acid waste handling applications, where incumbent concentration remains lowest. Pursue direct MEP consultant engagement as primary go-to-market angle, bypassing traditional merchant distributor gatekeepers who face specification authority erosion. For Investors and Strategic Acquirers: Valuations sit cheapest among regional extrusion specialists lacking backward integration into resin production but holding established contractor relationships in Riyadh and Jeddah. Long-term viability framing centers on Gulf petrochemical downstream expansion creating localized supply advantages that displace import-dependent competitors. Watch for GSO harmonization enforcement acceleration as inflection indicator signaling cross-border certification reciprocity value capture for multi-territory compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Saudi petrochemical feedstock pivot enables captive chlorine supply control for Eastern Province extrusion operations. |
| SASO Certification Pre-Qualification | Batch-traceable potable water contact documentation filters non-compliant imports from government housing tenders. |
| Threaded Jointing System Development | Mechanical jointing bypasses solvent cement curing constraints in Dubai high-rise maintenance retrofit environments. |
| MEP Consultant Direct Relationship | Specification authority migration from general contractors demands compounder-level technical engagement in Aramco-affiliated engineering firms. |
| Multi-Territory GSO Harmonization Leverage | Cross-border certification reciprocity reduces requalification costs for Saudi-UAE-Qatar project bids. |
Research Approach
Coverage spans Saudi Arabia, UAE, Qatar, Kuwait, and Oman, with primary inputs from each territory's contractor networks and regulatory bodies. Primary interviews with MEP consultants, plant engineers at Jubail petrochemical facilities, procurement leads at national housing developers, and distribution channel partners combined with secondary validation from SASO technical bulletins, GSO harmonization frameworks, customs and trade data, and SEC filings from listed compounders. Bottom-up project pipeline tracking and top-down petrochemical capacity analysis provided triangulation.
Rate-of-change decomposition structured the analytical framework across the projection horizon, with volume and value outputs reflecting segmented modeling across pressure rating tier, end-use application, and installation environment dimensions. CAGRs derived from regression against municipal infrastructure spend forecasts and high-rise construction permit flows. Industry-specific inputs included chlorine feedstock cost curves and SASO enforcement timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GSO harmonization implementation pace and Saudi electricity tariff restructuring. Forecasts reflect documented assumptions regarding petrochemical downstream investment continuity and high-rise plumbing code adoption timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Industrial Tubes Market
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market
Pipes and Tubes
Global Municipal Pipes Market
Pipes and Tubes
Cryogenic Pipes Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
ESR Tubes Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
Kuwait PVC Pipes Market
Pipes and Tubes
Oman PVC Pipes Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market
Pipes and Tubes
Composite Pipes Market