
 Co-Extruded Rubber Profiles Market | 2026-2036
Co-Extruded Rubber Profiles Market Size, Share, and Industry Trends Forecast 2026-2036
Co-Extruded Rubber Profiles Market Insights
Southeast Asian compounders is decoupling from traditional EPDM sourcing patterns as regional polymer capacity expands. Cooper Standard leverages backward integration into custom mixing operations across North American plants. Hutchinson SA anchors European supply through its France-based extrusion network serving Renault and Stellantis. ContiTech AG dominates industrial hose-grade co-extrusion with captive rubber compounding in Germany.
Co-extruded rubber profiles are multi-layer elastomeric sections manufactured through simultaneous extrusion of two or more rubber compounds with distinct hardness, chemical resistance, or thermal properties into a unified cross-section, typically achieving Shore A durometer differentials of 20-40 points between core and skin layers. These profiles function as integrated sealing, damping, or fluid-conveyance elements where a single homogeneous material would fail under combined mechanical, thermal, and chemical stress. EPDM-silicone combinations command premium positioning in aerospace gasket applications where ozone and temperature extremes coincide. Sealing strips remain the volume anchor across building and construction, though weatherstrips for transportation OEMs represent the fastest-expanding margin pool as electric vehicle architectures demand novel sealing geometries around battery enclosures and thermal management circuits.
REACH compliance through ECHA governs chemical migration limits in European automotive interior applications, while EPA standards under the Clean Air Act regulate volatile organic compound emissions from rubber extrusion facilities in the United States. China's GB standards through SAMR mandate flame-retardant specifications for electrical insulation profiles deployed in rail and grid infrastructure. Stakeholders must monitor evolving battery-electric vehicle platform architectures that will redefine sealing load cases, compression set requirements, and multi-material bonding specifications before committing to dedicated capacity investments.
Market Dynamics
Vehicle electrification is rewriting sealing load cases across automotive platforms, forcing compounders to engineer multi-material profiles that manage thermal runaway containment alongside traditional weatherproofing duties.
Growth Catalysts
- REACH chemical migration limits:ECHA restrictions on plasticizer chemistries in European automotive interiors are accelerating EPDM formulation adoption as OEMs seek compliant sealing alternatives.
- Battery enclosure sealing:Electric vehicle architectures demand novel gasket geometries around thermal management circuits and high-voltage compartments.
- Stuttgart-Wolfsburg supplier clustering:German automotive tier concentration creates dense procurement networks for multi-layer extrusion systems serving premium OEM platforms.
Market Restraints
- EPDM feedstock volatility:Ethylene and propylene monomer pricing swings compress compounder margins and destabilize long-term supply agreements.
- Custom mixing concentration:Backward-integrated North American producers control captive compound supply, limiting independent profile extruders' sourcing flexibility.
- Thermoplastic vulcanizate substitution:TPV materials encroach on medium-duty sealing applications where compression set requirements have relaxed.
Strategic Opportunities
- GB flame-retardant rail standards:SAMR mandates for electrical insulation profiles in Chinese grid infrastructure create specification-driven demand for halogen-free co-extruded compounds.
- Aerospace ozone-temperature convergence:EPDM-silicone combinations command premium positioning where extreme altitude conditions meet FAA certification requirements.
- Direct OEM technical partnerships:Bypassing traditional distribution, compounders are embedding design engineers within battery platform development teams.
Industry Challenges
- Multi-material bonding expertise:Shore A differentials of 20-40 points between core and skin layers require process engineers with rare co-extrusion die calibration skills.
- Battery platform certification timelines:OEM validation cycles for new sealing geometries extend 18-36 months, straining R&D amortization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Co-Extruded Rubber Profiles Market |
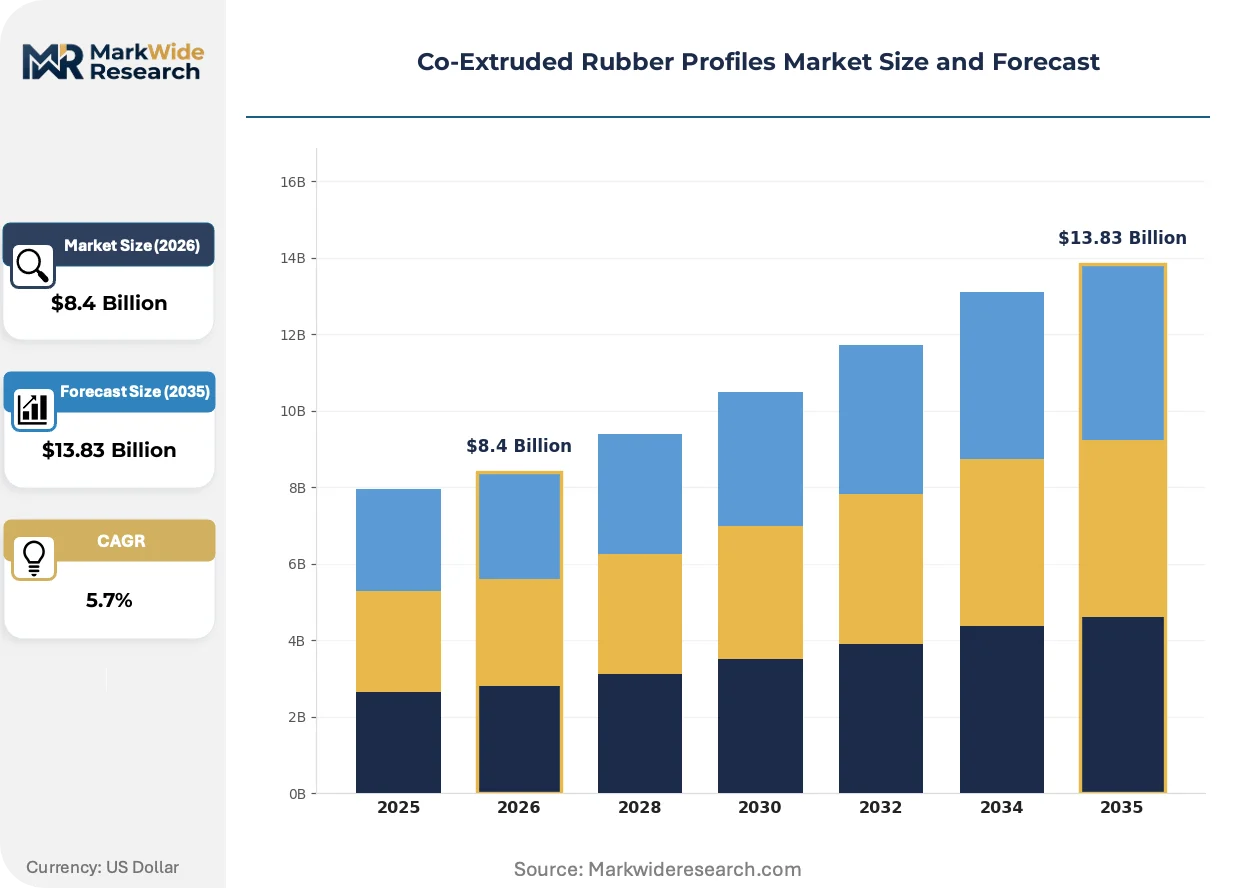
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealing Strips, Weatherstrips, Gaskets, Hoses, Tubing Material Composition: Natural Rubber, EPDM, Neoprene, Nitrile, Silicone, Butyl Application: Building & Construction, Transportation OEMs, Electrical Insulation, Consumer Appliances End Use Industry: Oil & Gas, Marine Equipment, Aerospace, Agricultural Machinery |
| Companies Covered | Cooper Standard, Hutchinson SA, ContiTech AG, Magna International, Toyoda Gosei Co., Ltd., Trim-Lok, Minor Rubber Company, Datwyler, Central Rubber Extrusions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Co-Extruded Rubber Profiles Market Trends and Innovations
Extrusion technology and regulatory chemistry are converging to redefine what constitutes a competitive rubber profile, with performance specifications now written around thermal management and chemical migration rather than mechanical durability alone.
Multi-layer die technology is rewriting manufacturing economics for complex cross-sections. Advanced co-extrusion heads now simultaneously process EPDM cores with silicone skins at throughputs previously achievable only with homogeneous compounds. Tier suppliers serving Stellantis and Renault platforms are retrofitting French extrusion lines with these systems. The technology is compressing minimum efficient scale for custom profile production.
REACH authorization procedures through ECHA are tightening migration limits for phthalate plasticizers in vehicle interiors. Compounders must reformulate legacy recipes or surrender automotive interior market access. German tier suppliers around Wolfsburg are accelerating EPDM-NBR hybrid development to maintain specification compliance without sacrificing low-temperature flexibility.
Buyer consolidation among electric vehicle OEMs is compressing supplier negotiation cycles. Procurement teams at battery platform specialists now bundle sealing, damping, and thermal interface contracts into single-source agreements. This pattern is most visible in German automotive clusters where Stuttgart-based OEMs have reduced qualified compounder pools by half.
Co-Extruded Rubber Profiles Market Segmentation
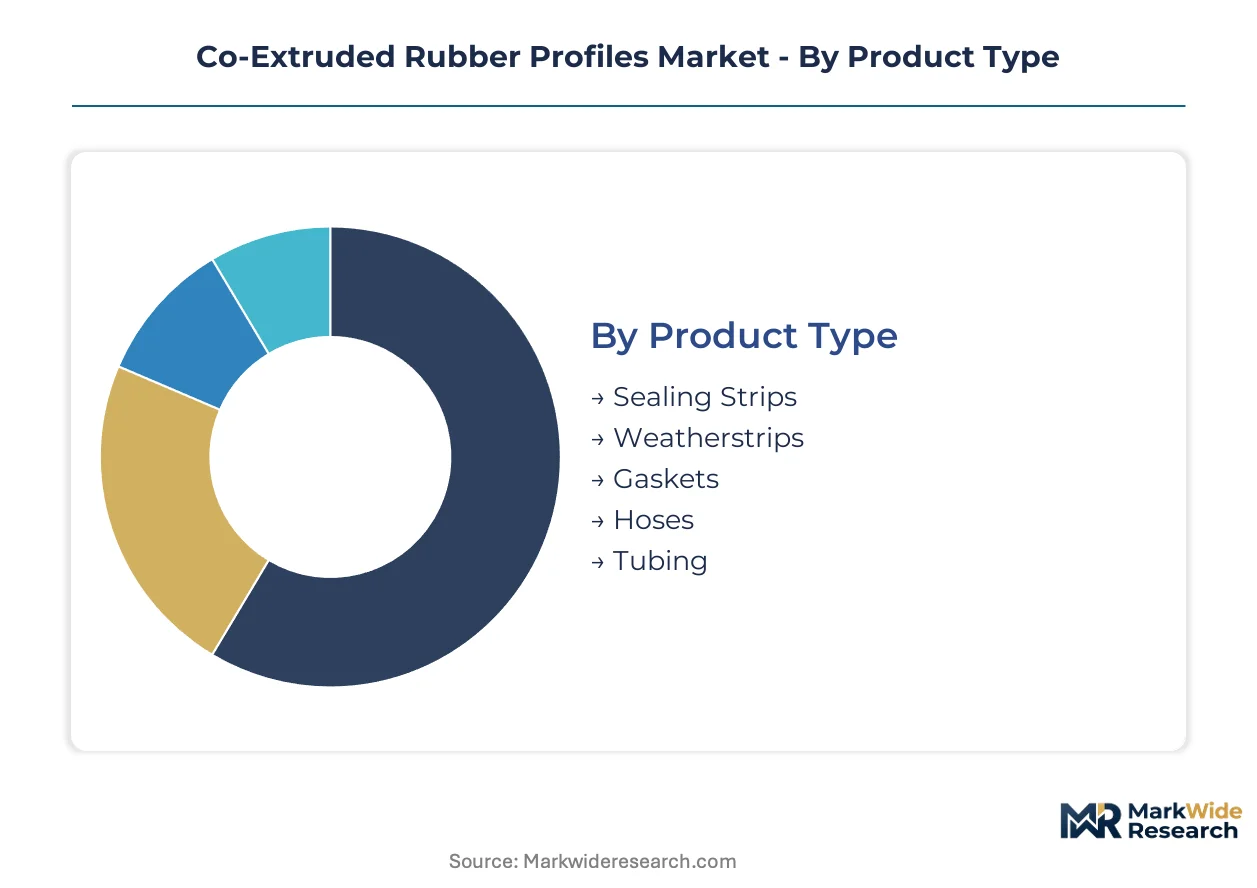
Co-extruded rubber profiles serve radically different performance envelopes across end uses, from static building seals to dynamic aerospace gaskets. Segmentation reveals how material selection and geometry complexity map to margin tiers, with transportation electrification redrawing traditional boundaries between commodity and specification-grade demand.
Product Type:
Volume anchors the sealing strip and weatherstrip segments, while premium positioning concentrates in multi-layer gaskets and specialized fluid conveyance.
- Sealing Strips:Single or dual-layer EPDM profiles with Shore A 50-70 hardness ranges dominate building envelope applications. German construction material distributors around Stuttgart and Wolfsburg cluster procurement for high-volume residential and commercial glazing systems, with REACH-compliant formulations now mandatory for interior exposure.
- Weatherstrips:Dynamic compression seals combining dense EPDM cores with micro-cellular skins manage door and hatch sealing across temperature cycles. Transportation OEMs in Germany are expanding technical specifications to include battery enclosure sealing, forcing compounders to engineer thermal runaway containment geometries alongside traditional weatherproofing duties.
- Gaskets:Precision-molded co-extrusions with metal or fabric reinforcement handle fluid and pressure containment in industrial equipment.
- Hoses:Multi-layer constructions with nitrile or neoprene inner tubes and EPDM covers serve fluid transfer in automotive and agricultural machinery.
- Tubing:Thin-wall co-extruded sections for pneumatic and low-pressure chemical conveyance in manufacturing automation.
Mature deployment sits with sealing strips. Newer deployment is concentrated in weatherstrips.
Material Composition:
EPDM formulations command the transportation and construction volume base, while specialty elastomers capture specification-driven niches where chemical resistance or temperature extremes dominate.
- EPDM:Ethylene-propylene-diene terpolymer delivers ozone resistance, thermal stability, and electrical insulation across -50°C to 150°C service windows. ECHA restrictions on phthalate plasticizers in European automotive interiors are accelerating EPDM adoption as OEMs reformulate legacy interior sealing recipes to maintain specification compliance.
- Silicone:VMQ and FVMQ grades handle extreme temperature excursions from -60°C to 230°C with minimal compression set. Aerospace gasket applications where ozone and temperature extremes coincide command premium positioning for EPDM-silicone combinations, particularly around FAA certification requirements for altitude-exposed sealing systems.
- Natural Rubber:High resilience and tear strength in dynamic applications with moderate chemical exposure.
- Neoprene:Chloroprene polymers balancing oil resistance with weathering performance in marine and industrial settings.
- Nitrile:NBR compounds with acrylonitrile content tuned for petroleum fluid resistance in oil and gas equipment.
- Butyl:Isobutylene-isoprene polymers with exceptional gas impermeability for tire inner liners and pneumatic seals.
Specification-grade deployment clusters in silicone. Volume-scale deployment concentrates in EPDM.
Application:
Building and construction absorbs homogeneous EPDM profiles at scale, while transportation OEMs drive multi-layer complexity and fastest specification evolution.
- Transportation OEMs:Electric vehicle architectures demand novel gasket geometries around battery enclosures, thermal management circuits, and high-voltage compartments. German automotive clusters have compressed qualified compounder pools by half as procurement teams bundle sealing, damping, and thermal interface contracts into single-source agreements.
- Building & Construction:Window and door sealing, curtain wall gaskets, and expansion joint covers utilize standard EPDM formulations with established die geometries. The segment remains the volume anchor across residential and commercial construction, though margin compression intensifies as Chinese manufacturers expand export capacity.
- Electrical Insulation:Flame-retardant co-extruded profiles for cable management and switchgear sealing.
- Consumer Appliances:Gasket and damping elements for refrigeration, dishwashing, and laundry equipment.
Standardized deployment dominates building and construction. Specification evolution is accelerating in transportation OEMs.
End Use Industry:
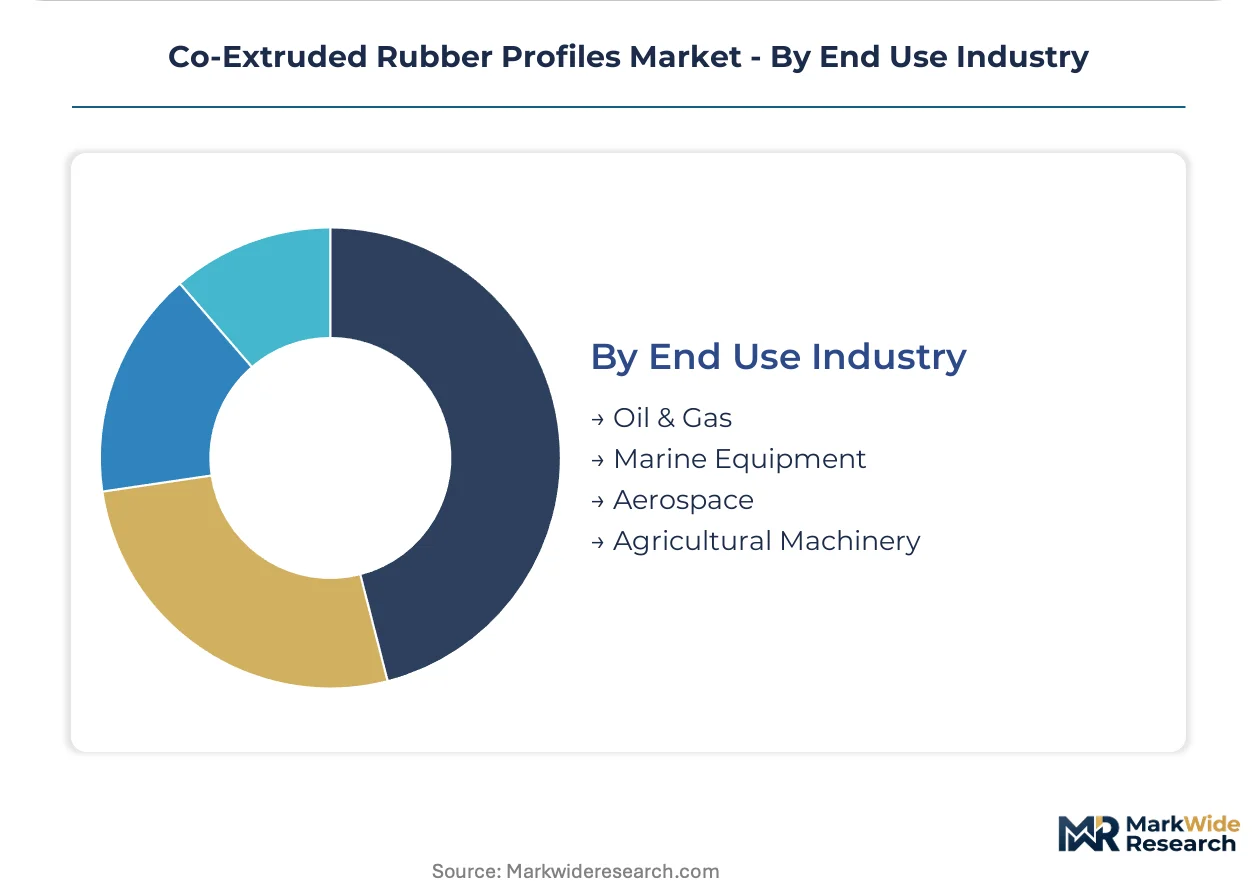
Industrial equipment segments operate on mature specification cycles, while aerospace and emerging energy applications drive premium material development.
- Aerospace:EPDM-silicone and fluorosilicone combinations manage extreme altitude conditions where ozone concentration, temperature cycling, and FAA certification requirements converge. Component suppliers serving European airframe manufacturers anchor demand through France-based extrusion networks with dedicated cleanroom compounding capabilities.
- Oil & Gas:Nitrile and HNBR co-extrusions handle downhole pressure, sour gas exposure, and subsea connector sealing. The segment demands compounders with API specification expertise and batch traceability systems for safety-critical blowout preventer and wellhead applications.
- Marine Equipment:Neoprene and EPDM profiles resisting saltwater corrosion and UV degradation in deck sealing and hatch systems.
- Agricultural Machinery:Cost-optimized EPDM and natural rubber compounds for engine compartment sealing and hydraulic hose covers.
Volume deployment concentrates in oil and gas. Technology evolution is advancing fastest in aerospace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene and propylene feedstock availability in the US Gulf Coast anchors Western Hemisphere compound supply. German automotive clusters drive premium formulation demand. Southeast Asian polymer capacity expansion is rewriting traditional sourcing geography.
United States
Transportation OEMs in Detroit and Southern California are expanding procurement of multi-layer sealing systems as vehicle electrification intensifies. EPA standards under the Clean Air Act regulate volatile organic compound emissions from rubber extrusion facilities. Cooper Standard leverages backward integration into custom mixing operations across North American plants serving battery platform specialists.
Germany
Automotive tier suppliers cluster around Stuttgart and Wolfsburg, creating dense procurement networks for multi-layer extrusion systems serving premium OEM platforms. ECHA restrictions on phthalate plasticizers through REACH authorization procedures are accelerating EPDM formulation adoption for interior sealing compliance. ContiTech AG dominates industrial hose-grade co-extrusion with captive rubber compounding in Lower Saxony.
France
Hutchinson SA anchors European supply through its France-based extrusion network serving Renault and Stellantis platforms with dedicated cleanroom capabilities. ECHA chemical migration limits govern automotive interior applications, forcing reformulation of legacy sealing recipes. Auvergne-Rhône-Alpes hosts precision extrusion facilities supplying aerospace gasket applications where EPDM-silicone combinations command premium positioning.
China
GB standards through SAMR mandate flame-retardant specifications for electrical insulation profiles deployed in rail and grid infrastructure across the Yangtze River Delta. Regional polymer capacity expansion allows Southeast Asian compounders to decouple from traditional EPDM sourcing patterns. Zhengzhou and Shanghai extrusion hubs are retrofitting lines for halogen-free co-extruded compounds serving state grid procurement.
Japan
Toyoda Gosei Co., Ltd. exemplifies the integrated supplier archetype serving domestic transportation OEMs with specification-grade weatherstrip systems. METI industrial standards shape material selection for automotive sealing applications in the Kanto region. Nagoya-area compounders are embedding design engineers within battery platform development teams to bypass traditional distribution channels.
Co-Extruded Rubber Profiles Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in thermal management and battery enclosure sealing. The vendor base organizes around three strategic archetypes: backward-integrated automotive suppliers with captive compounding, independent profile extruders serving specification-grade niches, and regional fabricators competing on volume-scale construction applications. Dominant competitive moves include direct OEM technical partnerships that embed compounders within platform development teams, and retrofitting of extrusion lines with multi-layer die technology to compress minimum efficient scale.
Within the integrated supplier tier, Cooper Standard and ContiTech AG exemplify the backward-integrated archetype controlling captive compound supply across North American and German manufacturing footprints. Hutchinson SA occupies a position representing the European extrusion network specialist serving premium automotive platforms through France-based facilities. Toyoda Gosei Co., Ltd. anchors the Asia-Pacific integrated supplier segment. These three named entities collectively represent the competitive structure without implying specific market share positions or strategic initiatives beyond their visible operational patterns.
| Leading Market Players |
|---|
| Cooper Standard |
| Hutchinson SA |
| ContiTech AG |
| Magna International |
| Toyoda Gosei Co., Ltd. |
| Trim-Lok |
| Minor Rubber Company |
| Datwyler |
| Central Rubber Extrusions |
| Others |
Pricing and Supply Chain Analysis
Backward integration into captive rubber compounding anchors supply positioning and pricing power for tier-one compounders serving battery platform specialists, while independent profile extruders face sourcing constraints that compress margin flexibility.
Pricing Analysis
Technical service bundling separates premium compounders from commodity suppliers, with design engineering support and 18-36 month validation cycle management included in contract structures. Three-tier pricing structure across specification-grade, automotive-qualified, and construction-volume levels tracks certification complexity and Shore A differential precision. Cost compression in construction-grade EPDM sealing strips is intensifying because Chinese manufacturers expand export capacity. Building material distributors exhibit highest price sensitivity; aerospace OEMs purchasing EPDM-silicone combinations show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart-based procurement teams bundling sealing and thermal interface contracts. Raw material sourcing concentrates in Germany, the United States, and China, with ethylene and propylene monomer supply anchored in the US Gulf Coast and German chemical corridors. Feedstock volatility in ethylene-propylene-diene terpolymer production creates margin instability for non-integrated compounders. Distribution runs through automotive tier networks in Wolfsburg-Stuttgart clusters, industrial hose channels served by ContiTech AG, and construction material distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Co-extrusion die calibration expertise functions as the binding capacity constraint, with process engineers capable of managing 20-40 point Shore A differentials commanding premium placement that props pricing across specification-grade tiers.
For Market Incumbents: Deploy captive compounding capacity additions in Lower Saxony and Michigan to defend against thermoplastic vulcanizate substitution in medium-duty sealing. Lock long-term EPDM offtake agreements with Saudi Aramco and Dow to neutralize ethylene-propylene feedstock volatility. Accelerate EPDM-NBR hybrid certification under ECHA REACH migration limits to maintain automotive interior access.
For New Entrants and Emerging Players: Launch via direct technical partnerships with battery platform development teams in Nagoya and Shanghai, bypassing traditional distribution channels. Target GB flame-retardant rail standards in Zhengzhou and Yangtze River Delta grid infrastructure as the most penetrable specification-driven segment. Pursue halogen-free co-extruded compound development for SAMR-compliant electrical insulation profiles.
For Investors and Strategic Acquirers: Exit pathways concentrate in backward-integrated automotive suppliers with captive mixing operations and cleanroom extrusion capabilities. Five-to-ten year viability favors compounders embedding design engineers within OEM platform teams rather than arms-length suppliers. Monitor ECHA authorization procedure timelines for phthalate plasticizer restrictions as the inflection signal for EPDM formulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer Die Technology Retrofit | Advanced co-extrusion heads compress minimum efficient scale for custom profile production serving Stellantis. |
| Backward Integration into Custom Mixing | Captive rubber compounding secures EPDM supply against ethylene-propylene monomer pricing swings. |
| Direct OEM Technical Partnership | Embedding design engineers within battery platform teams bypasses traditional distribution channels. |
| REACH-Compliant Formulation Development | EPDM-NBR hybrid recipes maintain automotive interior market access under ECHA migration limits. |
| Halogen-Free Compound Certification | GB standards compliance unlocks SAMR-mandated rail and grid infrastructure procurement in China. |
Research Methodology
Document review covered SEC 10-K filings from rubber compounders, ECHA REACH authorization databases, and IHS Markit vehicle production data, complemented by interviews with Tier 1 supplier procurement managers, OEM platform engineers, and extrusion plant managers. Primary fieldwork included technical discussions with compounders serving Renault and Stellantis platforms, validated against customs trade data and German automotive industry association reports. Bottom-up volume builds and top-down market sizing triangulated segment-level outputs.
Segmentation-level projections across material composition, product type, and end-use industry generated value and volume trajectories across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating battery-electric vehicle platform penetration, EPDM substitution rates for phthalate-restricted applications, and multi-layer die technology adoption curves. Forecast inputs included OEM validation cycle durations, REACH authorization procedure timelines, and regional polymer capacity expansion schedules.
The model assumes a particular technology adoption path for multi-layer co-extrusion systems; alternative pathways for thermoplastic vulcanizate material substitution would alter the outlook for medium-duty sealing demand. Forecasts reflect base-case assumptions regarding ECHA enforcement intensity and Chinese state grid procurement volumes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Rubber Additives Market
Rubber
Global Cast Elastomers Market
Rubber
Acrylic Rubber Market
Rubber
Global Rubber Market
Rubber
Rubber Valve Stem Market
Rubber
Rubber Plated Hose Market
Rubber
Rubber Wear Liners Market
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
Silica for S-SBR Market
Rubber
Rubber Reinforcing Chemicals Market
Rubber
Reclaimed Rubber Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
Rubber Coatings Market
Rubber
Rubber Color Masterbatch Market
Rubber
Global Thermoplastic Vulcanizate (TPV) Market