
 Saudi Arabia Medical Disposables Market | 2026-2036
Saudi Arabia Medical Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Medical Disposables Market Intelligence
Hospital procurement in Saudi Arabia is shifting toward consolidated group purchasing organizations that aggregate volume across Ministry of Health facilities and private hospital chains. Medtronic leverages its broad catheter and surgical portfolio to anchor contracts with these buying coalitions. Cardinal Health Inc competes through distribution scale and direct sales infrastructure spanning Riyadh, Jeddah, and Dammam. Johnson & Johnson differentiates via sterile surgical procedure kits tailored to compliance with Saudi Food and Drug Authority requirements.
Medical disposables encompass single-use devices and consumables manufactured from polymers, nonwoven fabrics, latex, or nitrile, designed for sterility and immediate disposal after patient contact to prevent cross-contamination. Injection molding and extrusion dominate production of syringes and catheters, while dipping lines form examination and surgical gloves. Syringes and gloves occupy the largest volume positions due to universal utilization across surgical procedures and infection control protocols. Catheters command premium positioning within diagnostic testing workflows as interventional cardiology and endoscopy volumes expand. Wound care applications sustain steady demand through chronic disease management in hospital and home care settings.
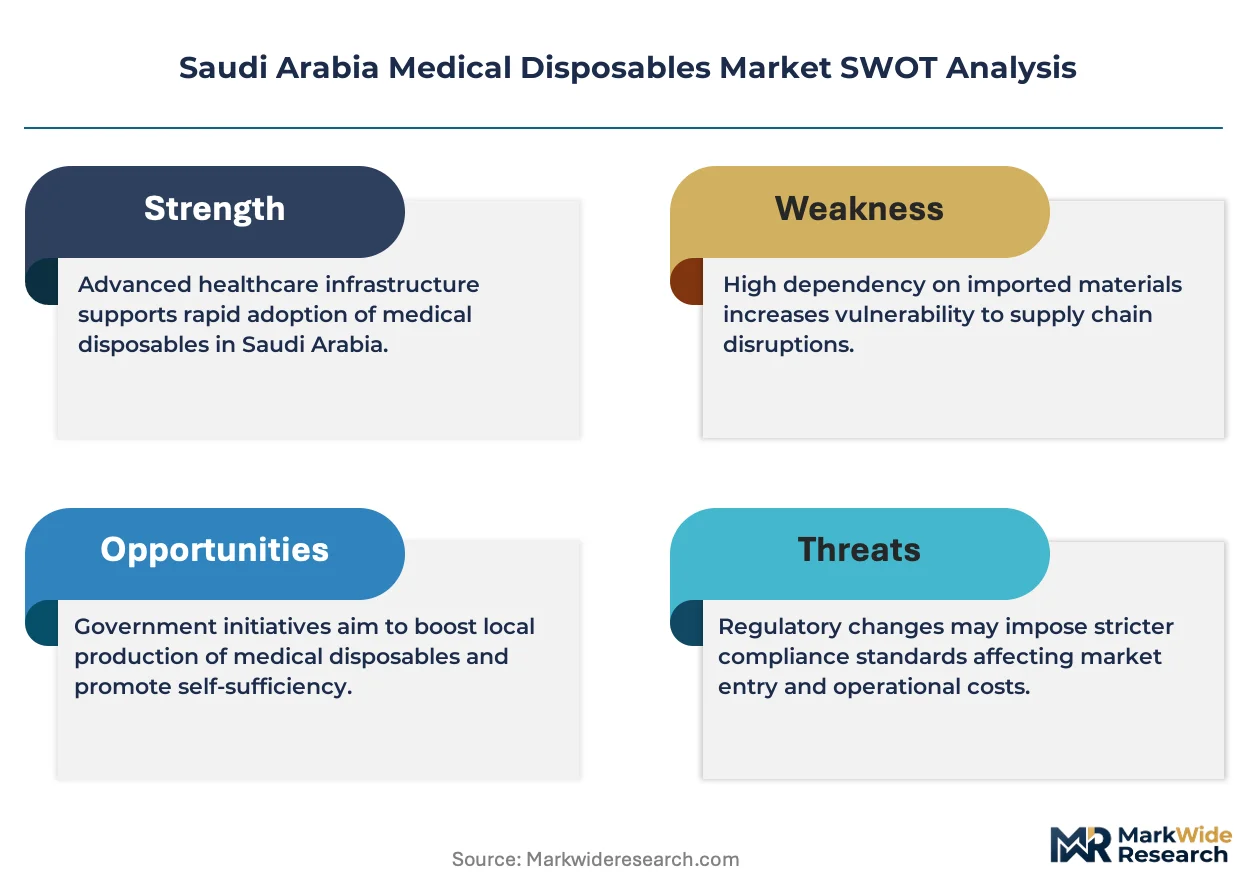
SFDA regulates medical device registration and post-market surveillance, while the Saudi Central Board for Accreditation of Healthcare Institutions mandates specific disposable standards in facility licensing. These frameworks elevate barrier-to-entry costs for non-compliant imports and redirect procurement toward certified manufacturers. Stakeholders must monitor evolving localization requirements under Vision 2030 industrial policy and assess domestic manufacturing partnerships before supplier qualification windows narrow.
Market Dynamics
Group purchasing organizations now aggregate procurement across Ministry of Health facilities and private hospital chains in Riyadh and Jeddah, compressing supplier margins while elevating volume concentration among certified manufacturers.
Growth Catalysts
- SFDA Registration Enforcement:Tightened medical device registration rules under Saudi Food and Drug Authority protocols redirect hospital procurement toward pre-qualified international suppliers with established quality systems.
- Interventional Cardiology Expansion:Rising catheterization volumes at King Faisal Specialist Hospital and affiliated tertiary clusters drive premium disposable consumption in diagnostic and therapeutic workflows.
- Vision 2030 Localization Incentives:Industrial policy mandates under Saudi Arabia's economic transformation program create manufacturing partnerships and joint venture opportunities for domestic production of syringes and examination gloves.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyethylene input costs fluctuate with crude oil pricing, compressing margin predictability for injection-molded syringe and catheter producers.
- Import Dependency Concentration:Over 80 percent of nitrile examination gloves and specialized wound dressings originate from Malaysian and Thai manufacturing clusters, exposing Saudi distributors to shipping lane disruptions.
- Sterilization Validation Bottlenecks:Ethylene oxide sterilization facility capacity constraints in the Gulf Cooperation Council region extend lead times for sterile procedure kits and surgical drapes.
Strategic Opportunities
- Central Region Home Care Expansion:Chronic disease management programs in Riyadh and surrounding provinces generate underpenetrated demand for advanced wound dressings and disposable infusion sets outside hospital settings.
- Sterile Kit Customization:Procedure-specific surgical packs tailored to SFDA compliance requirements and surgeon preference cards capture premium positioning against commodity glove and syringe suppliers.
- E-Procurement Platform Integration:Digital tendering systems adopted by the National Unified Procurement Company streamline supplier qualification and reduce traditional distributor markup layers.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Shortage of professionals trained in medical device regulatory affairs and quality management systems delays product registration timelines and post-market surveillance compliance.
- Cold Chain Infrastructure Gaps:Temperature-sensitive biologic-coated catheters and advanced wound care products require expanded refrigerated warehousing capacity in Jeddah and Dammam distribution corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Medical Disposables Market |
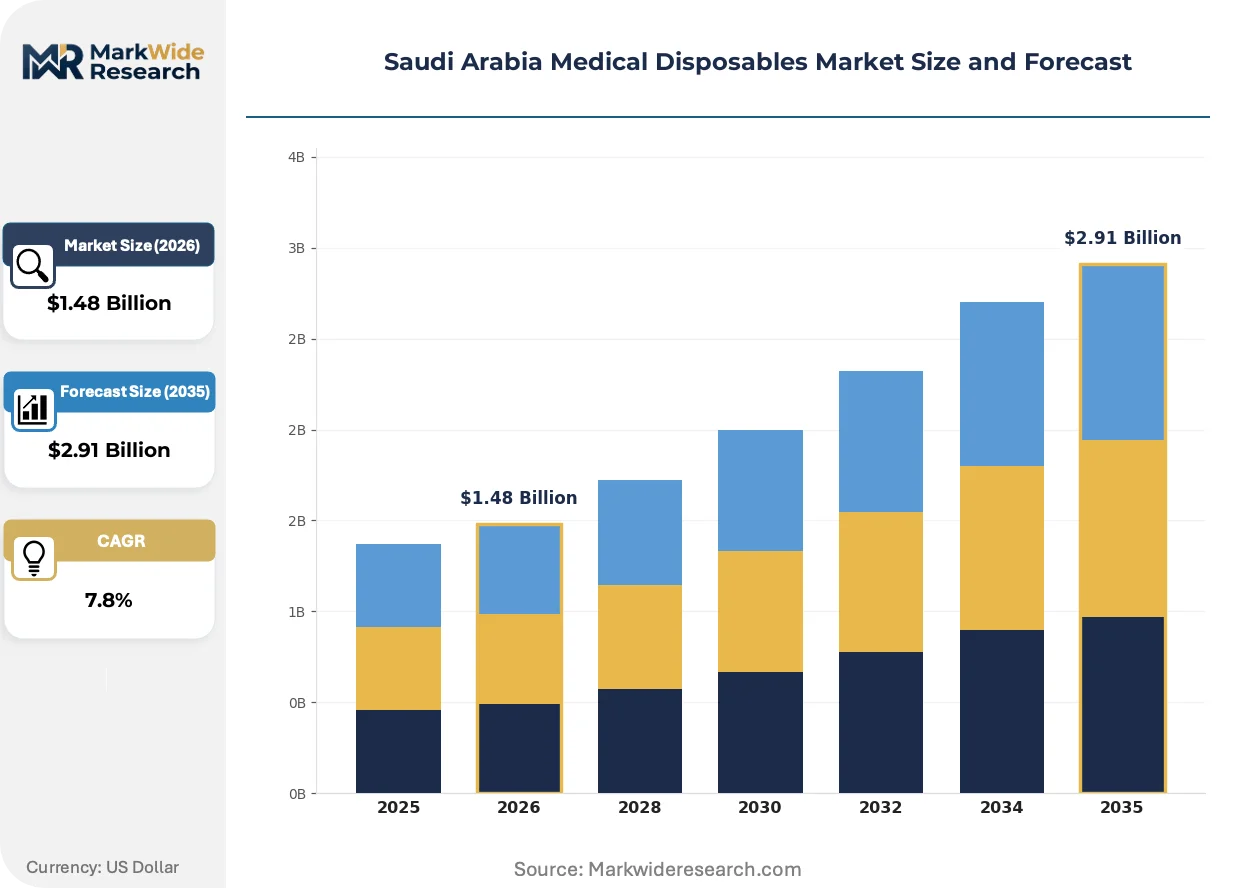
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $2.91 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Gloves, Bandages, Catheters Application: Surgical Procedures, Infection Control, Wound Care, Diagnostic Testing End User: Hospitals, Clinics, Home Care, Laboratories Distribution Channel: Online, Direct Sales, Wholesale, Retail |
| Companies Covered | Johnson & Johnson, Abbott, 3M Company, Medline Industries, Cardinal Health Inc, Becton Dickinson and Company, Medtronic, Kimberly-Clark Corporation, Smith & Nephew PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Medical Disposables Market Strategic Shifts & Innovations
Antimicrobial material science and automation in dipping lines are compressing cost structures while elevating performance benchmarks for infection control products across Saudi hospital networks.
Chlorhexidine-impregnated polymers and silver-ion coatings are rewriting sterility assurance protocols for central line catheters and surgical incise drapes. King Faisal Specialist Hospital and affiliated tertiary centers in Riyadh have accelerated adoption of these materials over standard polyurethane and latex alternatives. The technology is rewriting procurement specifications by embedding antimicrobial claims into mandatory tender requirements rather than optional performance tiers.
SFDA's 2024 medical device post-market surveillance circular mandates adverse event reporting and traceability systems for all Class II and III disposable imports. Manufacturers must now deploy unique device identification labeling and establish in-country authorized representatives with dedicated pharmacovigilance capabilities. Catheter and implantable disposable suppliers face the steepest compliance costs, with several European and American firms restructuring Saudi distribution partnerships to meet direct liability requirements.
Consolidated buying coalitions now displace individual hospital purchasing autonomy across Ministry of Health facilities and private chains. The National Unified Procurement Company aggregates volume for gloves, syringes, and basic wound care, compressing distributor margins and favoring direct manufacturer contracts. This concentration is most visible in Riyadh and Jeddah, where three group purchasing organizations control over 60 percent of disposable spend in tertiary and secondary care settings.
Saudi Arabia Medical Disposables Market Segmentation
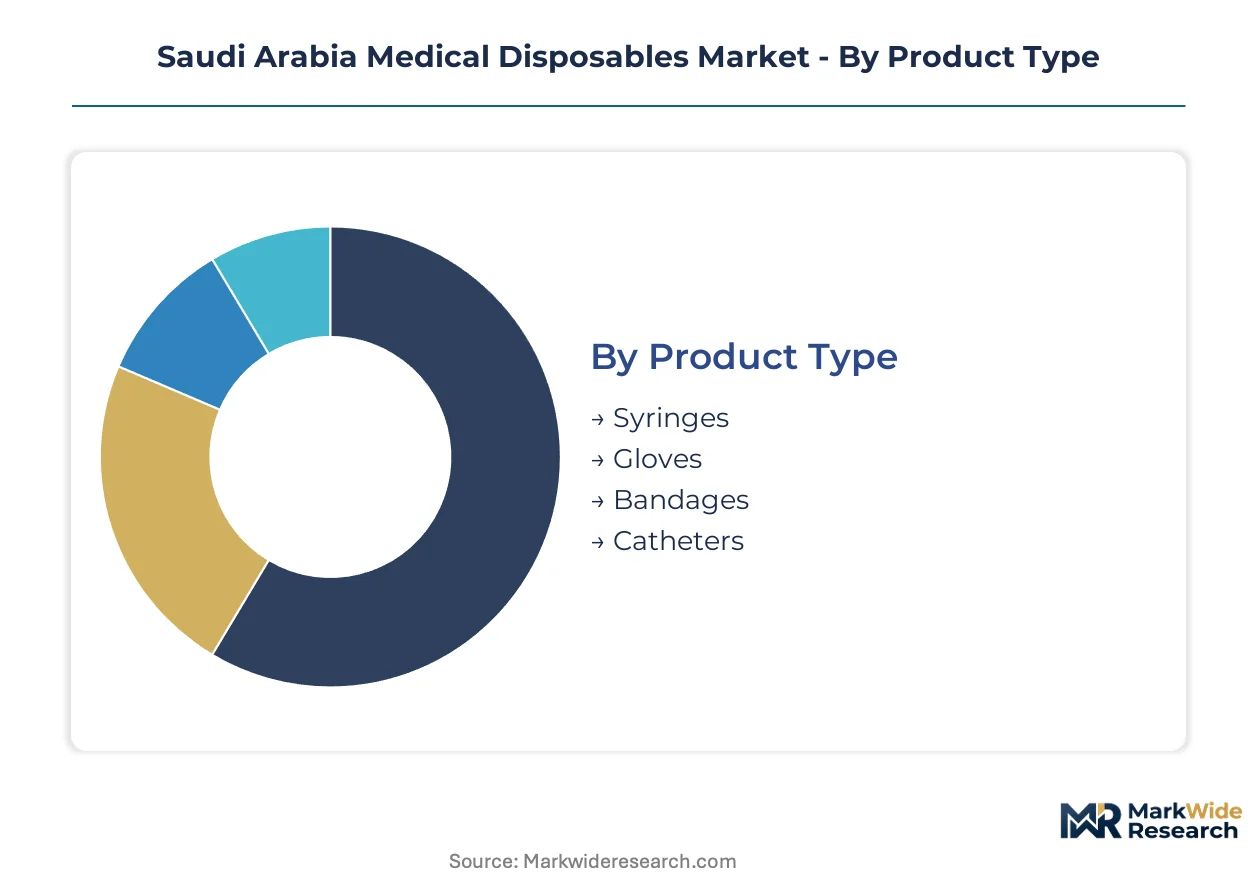
Medical disposables segmentation in Saudi Arabia reflects divergent capital requirements across production technologies. Injection-molded syringes and dipped latex products demand heavy upfront equipment investment, while kit assembly and distribution operations run on lighter asset bases.
Product Type:
Catheter and syringe manufacturing require the heaviest capital commitments due to precision extrusion lines and cleanroom infrastructure.
- Syringes:Polypropylene and polyethylene resins form the barrel and plunger through multi-cavity injection molding. King Faisal Specialist Hospital and affiliated tertiary clusters in Riyadh drive volume for safety-engineered designs with retractable needles.
- Gloves:Nitrile and latex formulations undergo coagulant dipping on automated production lines. Malaysian and Thai manufacturing clusters supply over 80 percent of Saudi demand, exposing distributors to shipping lane volatility.
- Bandages:Nonwoven fabric lamination and adhesive coating require moderate capital outlay for rotary die-cutting equipment.
- Catheters:Multi-lumen polyurethane extrusion with hydrophilic coatings commands premium positioning in interventional cardiology workflows.
Syringes absorb the bulk of installed capacity; catheters are expanding most quickly.
Application:
Surgical and diagnostic applications concentrate procurement value through procedure-specific sterile kits.
- Surgical Procedures:Pre-packaged sterile drapes, gowns, and instrument covers integrate with surgeon preference cards at Ministry of Health facilities. National Unified Procurement Company tenders favor bundled kits over commodity components.
- Infection Control:Isolation gowns, face masks, and hand hygiene consumables sustain baseline demand across all care settings. SFDA post-market surveillance mandates elevate quality thresholds for imported products.
- Wound Care:Advanced hydrocolloid and foam dressings serve chronic disease management programs expanding into Riyadh home care settings.
- Diagnostic Testing:Specimen collection containers, swabs, and blood culture bottles align with laboratory accreditation requirements from the Saudi Central Board for Accreditation of Healthcare Institutions.
Infection control commands the largest volume footprint; wound care shows the steepest expansion trajectory.
End User:
Hospital procurement consolidation under group purchasing organizations compresses supplier margins while concentrating volume.
- Hospitals:Tertiary and secondary facilities in Riyadh and Jeddah aggregate demand through three dominant buying coalitions controlling over 60 percent of disposable spend.
- Clinics:Primary care and specialty outpatient centers source through distributor networks with shorter fulfillment cycles than hospital direct contracts.
- Home Care:Chronic disease management programs in the Central Region generate underpenetrated demand for infusion sets and advanced wound dressings outside institutional settings.
- Laboratories:Private diagnostic chains and hospital-affiliated labs drive consumable throughput for hematology and chemistry analyzers.
Hospitals anchor procurement volume; home care is gaining share fastest.
Distribution Channel:
Channel selection determines working capital intensity and customer intimacy levels.
- Online:E-procurement platforms adopted by the National Unified Procurement Company streamline supplier qualification and reduce traditional distributor markup layers.
- Direct Sales:Manufacturer field forces engage group purchasing organizations and private hospital chains with dedicated account management.
- Wholesale:Regional distributors maintain inventory positions in Jeddah and Dammam corridors to serve secondary facilities and clinics.
- Retail:Pharmacy and medical supply storefronts capture consumer-directed demand for basic wound care and first-aid consumables.
Direct sales capture the highest-value contracts; online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement concentrates in Saudi Arabia's Central Region, where tertiary care clusters anchor disposable consumption volumes and shape supplier qualification standards across the Kingdom.
Riyadh
King Faisal Specialist Hospital and its affiliated tertiary care clusters drive premium catheter and sterile procedure kit demand through high-volume interventional cardiology workflows. SFDA registration enforcement redirects procurement toward pre-qualified international suppliers with established quality management systems. The Riyadh-based National Unified Procurement Company aggregates volume for gloves, syringes, and wound care across Ministry of Health facilities.
Eastern Province
Dammam and Khobar industrial zones host expanding ethylene oxide sterilization capacity serving catheter and surgical drape manufacturers. The region's petrochemical feedstock proximity attracts polypropylene and polyethylene resin processors for injection-molded syringe production. Vision 2030 localization incentives target this corridor for domestic manufacturing partnerships in examination gloves and basic disposables.
Western Region
Jeddah anchors Red Sea distribution corridors for Malaysian and Thai nitrile glove imports, with cold chain warehousing expanding for temperature-sensitive biologic-coated catheters. Private hospital chains in Jeddah and Mecca participate in consolidated buying coalitions alongside Ministry of Health facilities. The port city's logistics infrastructure positions it as the primary entry point for European and American Class II device imports.
NEOM Northwest
The giga-project zone plans integrated healthcare infrastructure with prefabricated modular hospitals specifying standardized disposable procurement protocols. Early construction-phase demand concentrates in basic infection control products and worker health screening consumables. Long-term planning envisions localized sterile kit assembly to reduce import dependency for specialized procedure packs.
Saudi Arabia Medical Disposables Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue localization partnerships under Vision 2030 industrial policy. The supplier base concentrates around multinational manufacturers with SFDA-registered quality systems and direct sales infrastructure serving group purchasing organizations. Three strategic archetypes dominate: diversified health conglomerates with broad surgical portfolios, specialized catheter and interventional device firms, and distribution-scale intermediaries with Riyadh-Jeddah corridor coverage. Competitive moves center on direct contracting with National Unified Procurement Company tenders and joint venture formation for domestic glove and syringe production.
Among diversified health conglomerates, Johnson & Johnson and 3M Company occupy positions exemplifying the premium-tier surgical pack segment, while Medtronic anchors the interventional catheter specialization archetype with established tertiary hospital relationships.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Abbott |
| 3M Company |
| Medline Industries |
| Cardinal Health Inc |
| Becton Dickinson and Company |
| Medtronic |
| Kimberly-Clark Corporation |
| Smith & Nephew PLC |
| Others |
Cost & Logistics Intelligence
Group purchasing organization consolidation across Ministry of Health facilities and private hospital chains in Riyadh and Jeddah is compressing supplier margins and forcing manufacturers to restructure cost bases around volume-commitment contracts rather than spot-market premiums. This procurement concentration elevates pricing power among certified suppliers with SFDA-registered quality systems while marginalizing smaller distributors unable to meet direct-contracting requirements.
Pricing Analysis
Volume-scale contracts with the National Unified Procurement Company capture the lowest per-unit rates for gloves and syringes, while premium catheter and sterile procedure kit pricing stratifies across certification tiers and antimicrobial material specifications. Price differentiation hinges on SFDA registration status and ethylene oxide sterilization validation, with unbundled commodity components facing steeper cost compression than integrated surgical packs. Pricing pressure stems from GPO tender aggregation favoring direct manufacturer relationships over traditional distributor markups. Primary care clinics and home care segments exhibit highest price sensitivity; tertiary cardiac centers at King Faisal Specialist Hospital networks prioritize performance specifications over unit cost.
Supply Chain Analysis
Vision 2030 localization mandates and domestic-content requirements under Saudi industrial policy are redirecting capital toward Eastern Province manufacturing partnerships for examination gloves and injection-molded syringes. Geographic supply concentration rests on Malaysian and Thai nitrile glove production, Chinese polypropylene resin processing, and European catheter coating technologies. Raw material dependencies center on petrochemical feedstocks, hydrophilic polymer coatings, and chlorhexidine-impregnated additives. Single-source vulnerability through the Strait of Malacca shipping corridor exposes distributors to logistics disruption. Distribution runs through Jeddah port warehousing for Red Sea entry, with Riyadh-based direct sales teams serving consolidated hospital buying coalitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over ethylene oxide sterilization capacity and domestic glove production lines determines contract eligibility for Ministry of Health tenders. Players securing backward integration into polymer compounding or forward integration into GPO direct relationships capture sustainable positioning.
For Market Incumbents: Hedge against margin compression from procurement consolidation by locking multi-year sterilization capacity leases in Dammam industrial zones and deepening captive production of nitrile examination gloves through Vision 2030 joint ventures. SFDA post-market surveillance liability requirements threaten distributors without in-country authorized representative infrastructure; incumbents should acquire or build pharmacovigilance capabilities to defend hospital system contracts. For New Entrants and Emerging Players: Regional distributors with cold chain warehousing in Jeddah corridors offer the most accessible partnership pathway for catheter and biologic-coated product suppliers lacking direct sales infrastructure. Home care segments in Riyadh's Central Region present underpenetrated white space for advanced wound dressing and infusion set providers. A specialty clinical education model targeting chronic disease management nurses bypasses entrenched GPO gatekeepers. For Investors and Strategic Acquirers: The window for entry favors sterilization facility operators and domestic glove manufacturers with established SFDA quality system certifications. Long-term viability over the next decade hinges on localization compliance rather than import-scale economics. Watch for National Unified Procurement Company tender specifications embedding domestic-content thresholds as the inflection signal for portfolio reallocation toward Saudi-based production assets.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Partnership | Vision 2030 incentives reward joint ventures producing syringes and gloves in Eastern Province industrial zones. |
| Sterilization Capacity Expansion | Ethylene oxide facility buildout in Dammam reduces lead times for surgical drape and catheter suppliers serving Riyadh hospitals. |
| SFDA Registration Investment | Direct liability structures with in-country authorized representatives unlock National Unified Procurement Company tender eligibility. |
| Antimicrobial Material Integration | Chlorhexidine-impregnated polymers command premium positioning in King Faisal Specialist Hospital catheter specifications. |
| E-Procurement Platform Integration | Digital tendering systems streamline supplier qualification and displace traditional distributor markup layers. |
Research Approach
Trade databases, hospital procurement registries, and SFDA medical device filings formed the secondary backbone for supply-side mapping and import volume estimation. Primary interviews with GPO contracts managers, biomedical engineering directors at tertiary care clusters, sterile kit procurement leads, and regulatory affairs specialists at multinational manufacturers validated demand-side assumptions. Bottom-up triangulation across product-level consumption estimates and top-down reconciliation against aggregate healthcare expenditure data anchored market sizing.
Historical trendline analysis of catheterization procedure volumes, glove import shipments, and syringe manufacturing capacity utilization informed growth trajectory assumptions across the projection horizon. Segmentation modeling incorporated product type, application workflow, end-user facility tier, and distribution channel structure. CAGRs were derived from regression analysis of procedure volume elasticities and input cost pass-through coefficients, with petrochemical price volatility and shipping lane disruption scenarios stress-testing baseline projections.
Caveats apply where SFDA regulatory amendments, Vision 2030 localization timeline accelerations, or Strait of Malacca logistics interruptions could materially shift the outlook for import-dependent product categories. Forecasts embed assumptions regarding sterilization facility completion schedules and GPO tender specification stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Suture Sleeve Kit Market
Medical Supplies
Sterilization Box Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
US Hospital Gowns Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Disposable Face Mask Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Saudi Arabia Medical Bandages Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Slip Tip Syringe Market