
 Global Dried Blood Spot Collection Cards Market | 2026-2036
Global Dried Blood Spot Collection Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dried Blood Spot Collection Cards Market Foresight
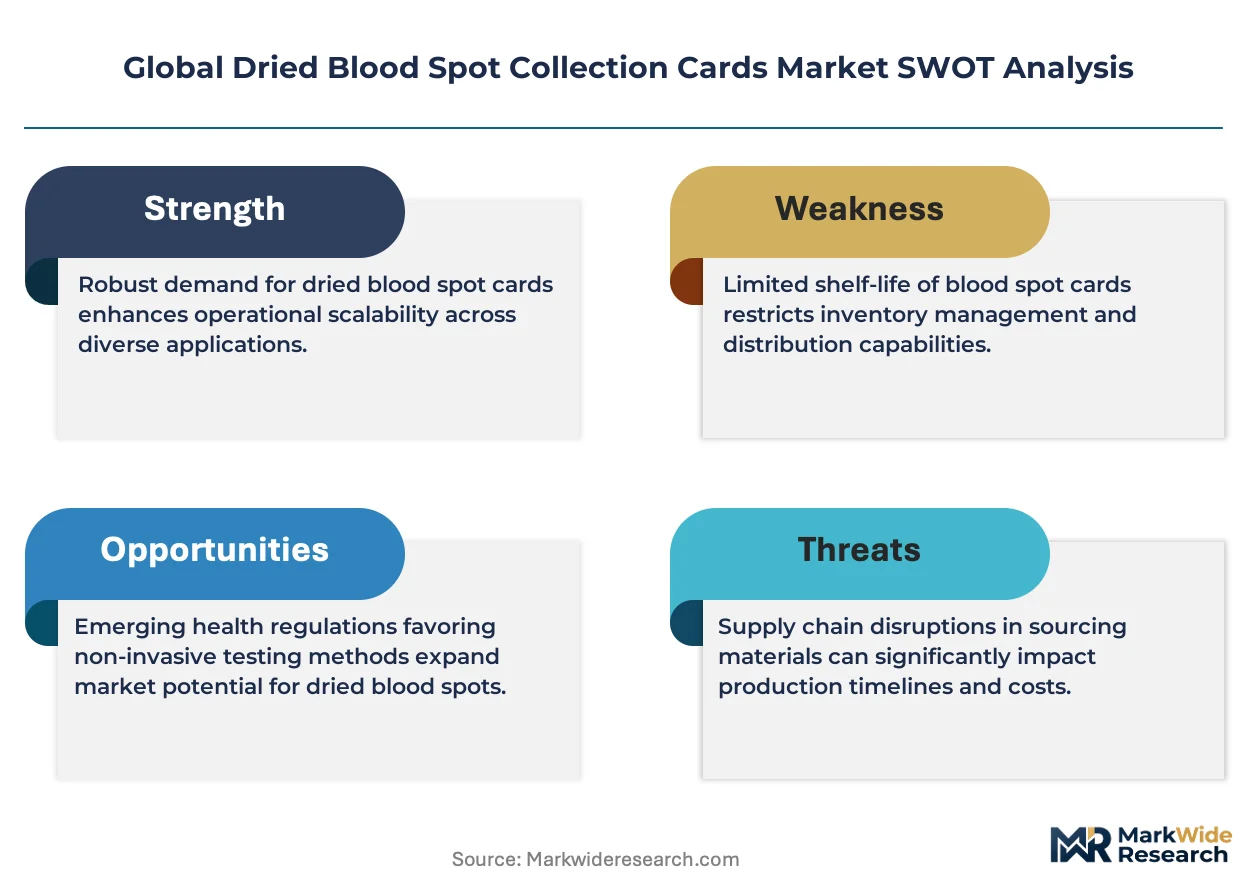
The EU In Vitro Diagnostic Regulation is broadening the cost-of-entry calculus for dried blood spot collection card manufacturers seeking CE-marked access. F. Hoffmann-La Roche Ltd leverages its diagnostic platform integration to sustain premium positioning across European clinical workflows. QIAGEN anchors its presence through sample preparation technology leadership that extends into downstream molecular applications. PerkinElmer competes by dominating newborn screening program supply relationships in North America and Asia-Pacific.
Dried blood spot collection cards are specialized absorbent substrates, typically cellulose or chemically modified paper matrices, engineered to preserve capillary blood samples for laboratory analysis through controlled drying and stabilized analyte retention. Their primary commercial purpose centers on enabling remote specimen collection, reducing cold-chain dependency, and supporting high-throughput screening at lower logistical cost than venipuncture. Cellulose-based cards occupy the largest volume share due to decades of clinical validation and standardized manufacturing, while modified paper cards represent the fastest-growing category as manufacturers embed stabilizing chemistries for nucleic acid and protein preservation. Clinical laboratories command the dominant end-user share, though research institutes are expanding fastest as translational genomics and environmental epidemiology adopt decentralized sampling protocols.
FDA oversight of Class I and Class II medical devices governs U.S. market entry, while the EMA and notified bodies under the IVDR framework enforce escalating conformity requirements across Europe. China's NMPA has tightened registration pathways for imported specimen collection devices, adding testing documentation burdens that favor domestic manufacturers with established GB-standard compliance. Stakeholders must monitor divergence between regional analytical performance standards and harmonization efforts through ISO 15189 and CLSI guidelines to avoid redundant validation investments.
Market Dynamics
The EU In Vitro Diagnostic Regulation is compressing manufacturer margins while simultaneously elevating analytical performance requirements across specimen collection workflows. This regulatory recalibration is forcing capital reallocation toward quality management systems and notified body engagement.
Growth Catalysts
- Neonatal screening mandates:Public health systems in Brazil and Saudi Arabia are institutionalizing dried blood spot protocols for metabolic disorder detection, expanding addressable specimen volumes beyond traditional North American and European bases.
- REACH-compliant stabilizing chemistries:Modified cellulose matrices embedded with nucleic acid preservatives are enabling ambient-temperature biobanking, reducing cold-chain infrastructure requirements for decentralized clinical trials.
- Remote patient monitoring protocols:Home-based therapeutic drug monitoring for immunosuppressants and antiepileptics is creating recurring demand for patient-administered capillary sampling in Germany and Japan.
Market Restraints
- Cellulose pulp price volatility:Fluctuations in Nordic forestry supply and energy-intensive chemical processing are compressing gross margins for substrate manufacturers.
- IVDR conformity assessment bottlenecks:Notified body capacity constraints in the EU are extending time-to-market for new card formats, privileging incumbents with existing CE-marked portfolios.
- Liquid biopsy alternatives:Cell-free DNA collection tubes and microsampling devices are capturing share in oncology monitoring applications where analyte sensitivity requirements exceed dried matrix capabilities.
Strategic Opportunities
- India's CDSCO streamlined pathways:Recent harmonization with ISO 13485 is accelerating registration timelines for imported collection devices, opening access to government-funded anemia and sickle cell screening programs.
- Environmental epidemiology cohorts:Longitudinal exposure studies linking pesticide metabolites to developmental outcomes are adopting dried blood spots for field-deployable biomarker archiving.
- Integrated diagnostic platforms:Convergence of microfluidic sample processing with point-of-care nucleic acid amplification is creating demand for pre-treated cards that eliminate manual extraction steps.
Industry Challenges
- Analytical validation expertise scarcity:Clinical laboratories face recruitment gaps for mass spectrometry method development specialists capable of harmonizing dried matrix assays with venipuncture reference ranges.
- Legacy LIMS integration friction:Disparate data formats between card-based specimen tracking systems and established laboratory information management platforms are delaying workflow automation deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dried Blood Spot Collection Cards Market |
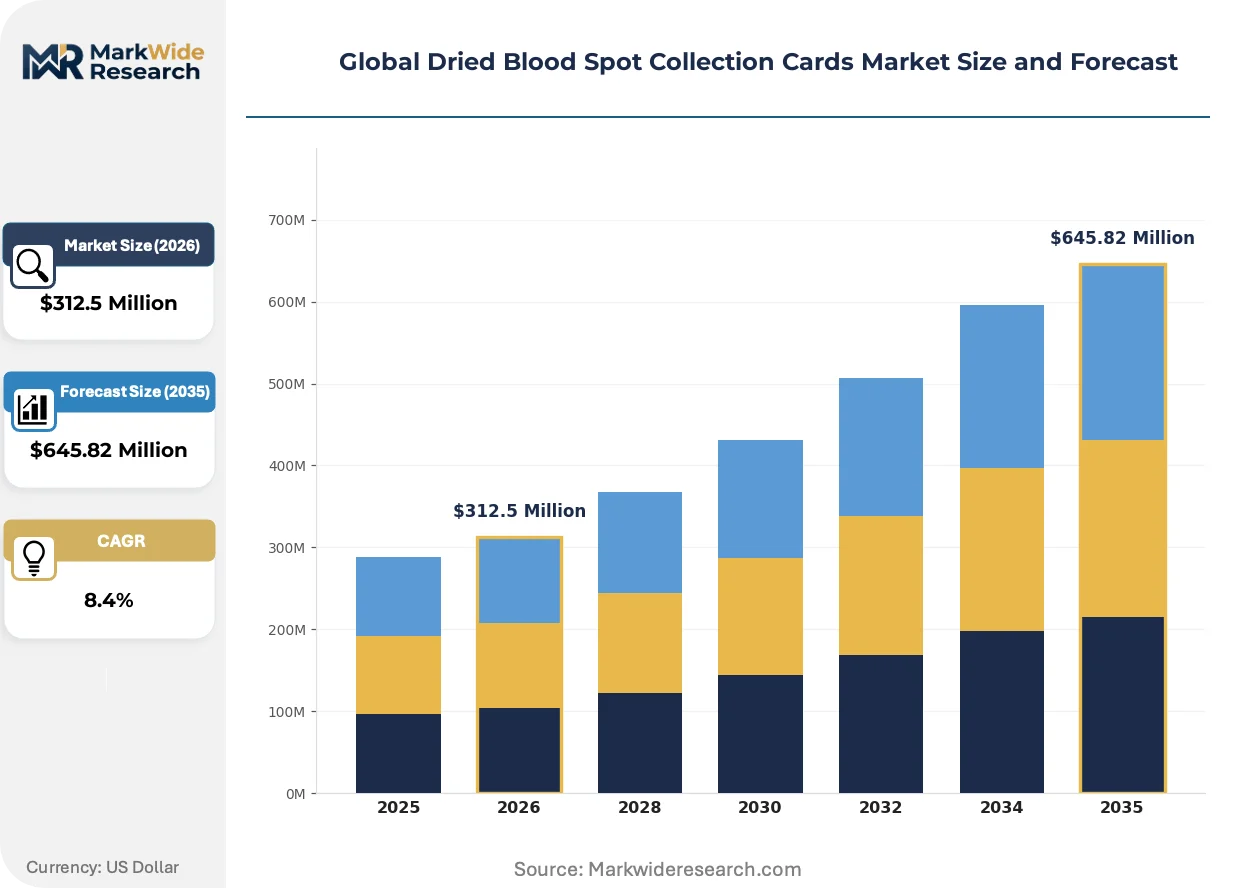
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose-Based Cards, Fiberglass-Based Cards, Polyester-Based Cards, Modified Paper Cards Application: Neonatal Screening, Infectious Disease Testing, Therapeutic Drug Monitoring, Genetic Analysis, Environmental Studies End User: Clinical Laboratories, Research Institutes, Blood Banks, Diagnostic Centers, Academic Institutions Packaging Type: Individual Packs, Bulk Packs, Sterile Packs, Vacuum-Sealed Packs |
| Companies Covered | F. Hoffmann-La Roche Ltd, QIAGEN, PerkinElmer, Ahlstrom-Munksjö, Eastern Business Forms, Inc., Shimadzu Corporation, Pall Corporation, ARCHIMED Life Science GmbH, CENTOGENE N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dried Blood Spot Collection Cards Market Shifts & Advancements
Specimen preservation chemistry and regulatory data integrity requirements are converging to redefine product differentiation beyond substrate absorbency metrics. Manufacturers are embedding functional capabilities that extend sample stability windows while automating chain-of-custody documentation.
Modified paper matrices incorporating colorimetric hematocrit indicators and nuclease inhibitors are expanding into pharmacokinetic studies where multi-analyte quantification demands standardized spotting volumes. Contract research organizations in the United States and Switzerland are adopting these formats to reduce protocol deviations in multi-site trials. The technology is expanding into therapeutic areas previously reserved for wet plasma collection, including biologic drug immunogenicity testing.
EMA's intensified scrutiny of analytical performance claims under IVDR Article 56 is compelling manufacturers to generate clinical evidence packages that demonstrate equivalence to liquid specimen methods. This documentation burden favors organizations with established clinical laboratory partnerships capable of generating real-world performance data. Card formats targeting neonatal screening applications face the steepest evidentiary requirements given the irreversible nature of diagnostic decisions in this population.
Hospital procurement consortia are consolidating supplier relationships around vendors offering integrated reagent-card-analyzer bundles, displacing standalone card purchasing. Academic medical centers in Germany and the Netherlands are piloting outcome-based contracting models that tie payment to screening program sensitivity metrics rather than unit volumes. This restructuring concentrates purchasing authority within centralized supply chain functions and privileges manufacturers with full workflow capabilities over substrate specialists.
Global Dried Blood Spot Collection Cards Market Segmentation
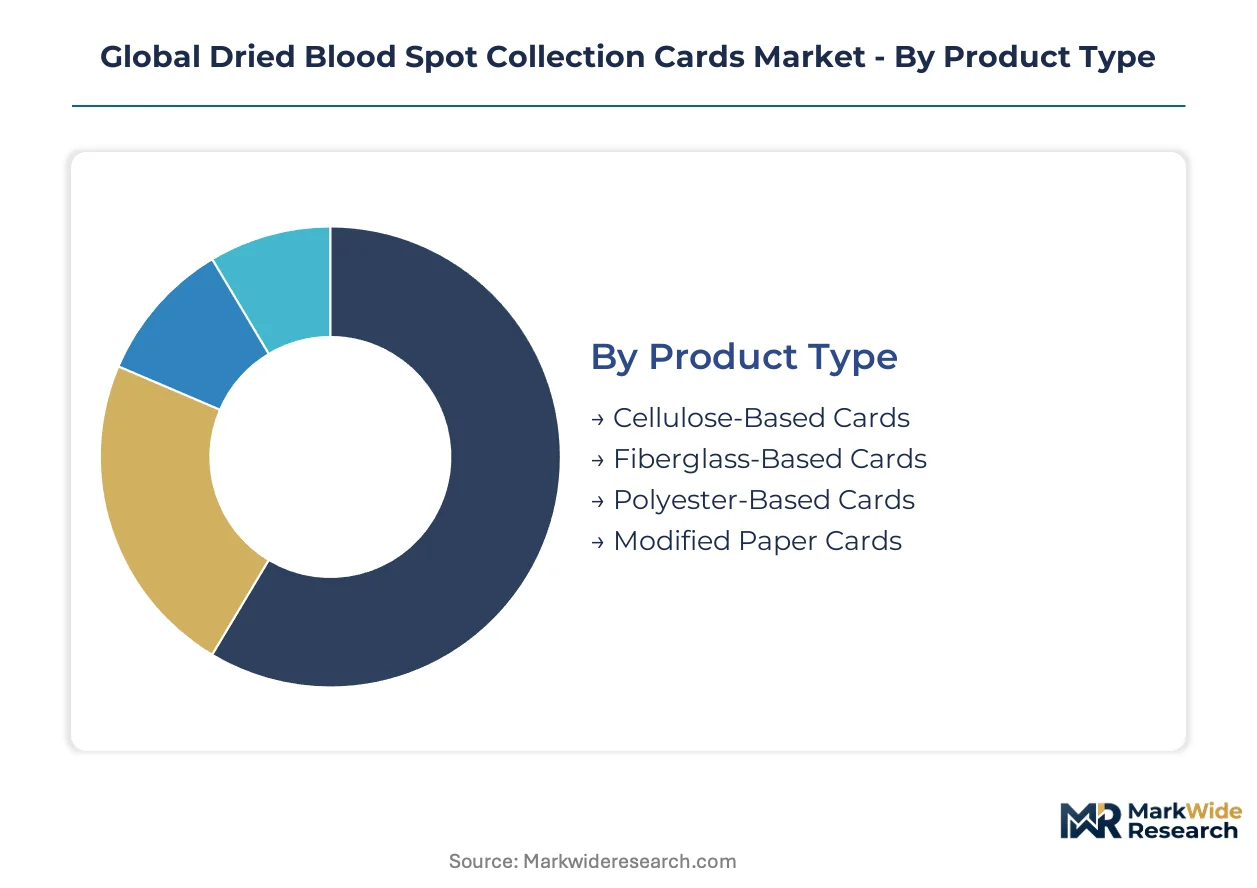
Segmentation in dried blood spot collection cards determines regulatory pathway complexity and manufacturing scale economics. Substrate chemistry, application specificity, and packaging sterility each impose distinct conformity requirements under FDA and IVDR frameworks. Procurement patterns diverge sharply between high-volume neonatal screening programs and low-volume research cohorts.
Product Type:
IVDR Article 56 and FDA Class I/II device classifications apply unevenly across substrate technologies, with modified matrices facing steeper analytical validation burdens than legacy cellulose formats.
- Cellulose-Based Cards:Standardized cotton-linter or wood-pulp matrices with defined absorbency ratings dominate newborn screening workflows. Germany's clinical laboratory network and Saudi Arabia's expanding public health programs anchor volume demand for these historically validated substrates.
- Modified Paper Cards:Chemically treated substrates embedding nucleic acid stabilizers or protein protectants command premium positioning. REACH-compliant preservative chemistries from Nordic suppliers enable ambient-temperature biobanking for decentralized clinical trials in Switzerland and the United States.
- Fiberglass-Based Cards:Synthetic non-woven matrices offer superior dimensional stability for automated handling systems. Diagnostic centers in Japan prioritize these formats for high-throughput infectious disease testing workflows.
- Polyester-Based Cards:Hydrophobic synthetic substrates engineered for precise volume control serve specialized pharmacokinetic applications. Contract research organizations in the United States specify these for multi-site therapeutic drug monitoring studies.
Leading the category by volume: Cellulose-Based Cards. Growing fastest: Modified Paper Cards.
Application:
Application segments map directly to reimbursement codes and public health budget allocations, with neonatal screening commanding dedicated procurement streams distinct from discretionary research spending.
- Neonatal Screening:Metabolic disorder detection programs in Brazil and India require high-volume, low-cost card supplies with harmonized analyte recovery specifications. Government tenders in these markets prioritize suppliers with WHO-prequalified manufacturing facilities.
- Therapeutic Drug Monitoring:Immunosuppressant and antiepileptic level assessment drives recurring demand from Germany's hospital outpatient services and Japan's home healthcare providers. Remote patient protocols favor pre-printed patient identification formats.
- Infectious Disease Testing:HIV viral load and hepatitis C screening applications concentrate in South Africa's public health infrastructure and India's government-funded diagnostic networks. Specimen stability requirements vary by target analyte class.
- Genetic Analysis:Pharmacogenomics and carrier screening applications expand through academic medical centers in the Netherlands and direct-to-consumer testing channels in the United States. Nucleic acid preservation chemistries dominate substrate selection criteria.
- Environmental Studies:Longitudinal exposure assessment cohorts in Denmark and the United States adopt dried blood spots for field-deployable pesticide metabolite archiving. Modified paper cards with extended stability windows serve these non-clinical applications.
Neonatal Screening generates the largest absolute specimen volumes. Therapeutic Drug Monitoring demonstrates the steepest expansion trajectory as home-based protocols proliferate.
End User:
End-user categories reflect divergent supply chain configurations, with clinical laboratories demanding just-in-time inventory systems while research institutes tolerate longer lead times for specialized formats.
- Clinical Laboratories:High-throughput screening facilities in Germany, Japan, and Brazil require standardized card dimensions compatible with automated punch-and-extract systems. Integrated reagent-card-analyzer bundling concentrates purchasing authority.
- Research Institutes:Translational genomics and environmental epidemiology centers in Switzerland and the United States drive demand for modified matrices with embedded stabilizers. Flexible lot sizing and custom printing accommodate protocol heterogeneity.
- Diagnostic Centers:Point-of-care and near-patient testing facilities in India and South Africa prioritize individual packaging and ambient storage stability. CDSCO and local regulatory registrations filter supplier eligibility.
- Blood Banks:Transfusion service networks in the United States and France utilize dried blood spots for donor pathogen screening backup protocols. Sterile packaging and chain-of-custody documentation dominate procurement specifications.
- Academic Institutions:University-affiliated research hospitals in the Netherlands and Denmark pilot outcome-based contracting models. Payment terms increasingly tie to screening sensitivity metrics rather than unit volumes.
Clinical Laboratories anchor category demand. Research Institutes expand most quickly as decentralized sampling protocols proliferate across environmental and genomic cohorts.
Packaging Type:
Packaging configurations determine shelf-life claims and distribution economics, with sterile and vacuum-sealed formats commanding manufacturing investments distinct from bulk commodity production.
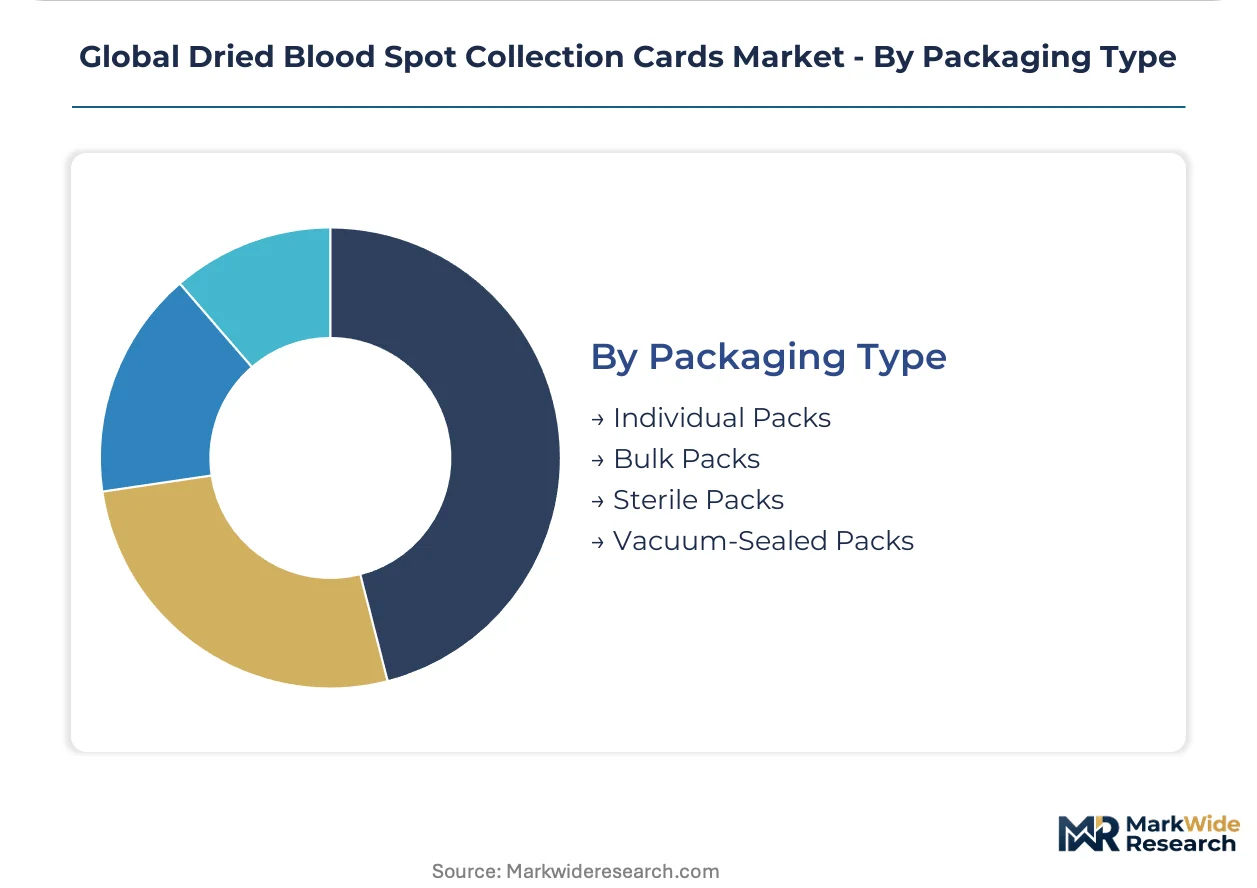
- Individual Packs:Single-card pouches with desiccant and humidity indicators serve home-based therapeutic drug monitoring and remote specimen collection. Patient-administered applications in Germany and Japan specify tamper-evident seals.
- Bulk Packs:Multi-card cartons without individual barrier packaging dominate high-volume neonatal screening procurement in Brazil and India. Cost minimization priorities override extended stability requirements.
- Sterile Packs:Gamma-irradiated or ethylene oxide-sterilized formats serve neonatal intensive care and immunocompromised patient applications. Blood banks in France and the United States mandate these for specific screening workflows.
- Vacuum-Sealed Packs:Oxygen and moisture barrier packaging extends analyte stability for nucleic acid preservation in genetic analysis and environmental studies. Research institutes in Switzerland and the United States specify these for longitudinal biobanking.
Bulk Packs lead by shipment volume. Vacuum-Sealed Packs gain share fastest as ambient-temperature nucleic acid preservation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the Netherlands and Switzerland concentrate European distribution infrastructure for dried blood spot collection cards. Manufacturing investments follow regulatory stringency gradients. Procurement patterns diverge sharply between publicly funded screening programs and private laboratory networks.
United States
FDA Class I and Class II medical device oversight governs market entry for cellulose and modified paper substrates. The agency's 510(k) pathway favors predicate device referencing for legacy card formats. Boston's academic medical center cluster pilots outcome-based contracting for neonatal screening bundles.
Germany
IVDR Article 56 conformity assessments through notified bodies extend time-to-market for new card formats. The country's statutory health insurance system mandates dried blood spot protocols for metabolic disorder screening. Munich's clinical laboratory network anchors volume demand for standardized cellulose substrates.
India
CDSCO harmonization with ISO 13485 accelerates registration timelines for imported collection devices. Government-funded anemia and sickle cell screening programs expand addressable specimen volumes. Maharashtra's diagnostic manufacturing corridor attracts contract packaging investments for regional distribution.
Japan
PMDA quality management system inspections govern manufacturing site approval for foreign suppliers. Home healthcare reimbursement codes support remote therapeutic drug monitoring protocols. Osaka's precision manufacturing base supplies automated punch-and-extract systems for high-throughput laboratories.
Brazil
ANVISA resolution RDC 830/2023 tightens import licensing for in vitro diagnostic collection devices. The national newborn screening program mandates dried blood spot protocols for metabolic disorder detection. São Paulo's public health procurement consortium consolidates supplier relationships around volume tenders.
Global Dried Blood Spot Collection Cards Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate chemistry and downstream diagnostic integration. Market structure tilts toward consolidation as hospital procurement consortia bundle reagent-card-analyzer offerings. Three archetypes dominate: vertically integrated diagnostic platform operators, substrate chemistry specialists, and contract manufacturing organizations. Capacity expansion and strategic partnerships represent the primary competitive vectors as manufacturers secure notified body capacity and clinical laboratory validation data.
Among Swiss and German diagnostic conglomerates, F. Hoffmann-La Roche Ltd and QIAGEN occupy positions anchored by platform integration and sample preparation technology leadership respectively. PerkinElmer exemplifies the newborn screening program supply relationship archetype across North American and Asia-Pacific public health systems. These three represent distinct strategic postures: Roche leverages diagnostic workflow integration, QIAGEN extends into downstream molecular applications, and PerkinElmer concentrates on high-volume programmatic supply contracts.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| QIAGEN |
| PerkinElmer |
| Ahlstrom-Munksjö |
| Eastern Business Forms, Inc. |
| Shimadzu Corporation |
| Pall Corporation |
| ARCHIMED Life Science GmbH |
| CENTOGENE N.V. |
| Others |
Supply & Pricing Matrix
Modified paper cards with embedded stabilizing chemistries command substantial premiums over commodity cellulose substrates, a bifurcation that concentrates manufacturing investments in Nordic specialty chemical suppliers while pushing standard-grade production toward cost-optimized Nordic and Brazilian pulp processors. This tier divergence manifests in procurement patterns where neonatal screening programs in Brazil and India negotiate volume-driven bulk contracts, while genetic analysis cohorts in Switzerland and the United States absorb 40-60% markups for REACH-compliant preservative matrices with extended ambient stability claims.
Pricing Analysis
Short lead-time premiums dominate pricing architecture, with just-in-time delivery to Germany's clinical laboratory network commanding 15-25% surcharges over quarterly contract volumes. Three-tier pricing structure across premium, standard, and economy levels maps to certification intensity: IVDR Article 56-compliant formats with notified body documentation anchor the premium band, FDA 510(k) cleared cellulose cards occupy the standard tier, and non-validated bulk packs serve research institutes with price sensitivity. Cost compression in the economy tier is intensifying because Brazilian and Indian government tenders prioritize unit cost over performance documentation. Blood banks in France and the United States demonstrate least price sensitivity due to sterile packaging mandates and patient safety protocols.
Supply Chain Analysis
Cellulose pulp supply rests on Nordic forestry operations in Sweden and Finland, with specialty chemical treatments for nucleic acid preservation drawing from German and Swiss precision chemical manufacturers. Raw material dependencies span cotton-linter pulp, ethylene oxide sterilization capacity, and desiccant packaging films. Single-source vulnerability concentrates in notified body capacity for IVDR conformity assessments, where bottlenecks extend lead times for new market entrants. Distribution runs through free trade zones in the Netherlands and Switzerland, with regional packaging investments in Maharashtra's diagnostic corridor serving Indian government screening programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over stabilizing chemistry formulation and clinical validation data generation determines margin capture. Players are pursuing backward integration into REACH-compliant preservative manufacturing to escape commodity cellulose pricing traps.
For Market Incumbents: Extend platform bundling strategies by integrating reagent-card-analyzer offerings that lock hospital procurement consortia into multi-year contracts. Acquire or partner with notified bodies to secure IVDR conformity assessment capacity and compress time-to-market for modified paper formats. Liquid biopsy alternatives and microsampling devices threaten oncology monitoring share, demanding defensive R&D investment in multi-analyte quantification capabilities. For New Entrants and Emerging Players: CDSCO harmonization with ISO 13485 in India opens a window for imported collection devices to access government-funded anemia and sickle cell screening programs with streamlined registration timelines. Target environmental epidemiology cohorts in Denmark and the United States where modified paper cards with extended stability windows face limited incumbent specialization. Deploy direct academic medical center sales models that bypass consolidated hospital procurement consortia and emphasize custom protocol development. For Investors and Strategic Acquirers: Re-rating potential sits with substrate chemistry specialists possessing REACH-compliant preservative portfolios given EMA's intensified analytical performance scrutiny under IVDR Article 56. Long-term viability over a 5-10 year horizon favors organizations with demonstrated clinical laboratory partnerships capable of generating real-world equivalence data. Watch notified body capacity expansion announcements as the primary inflection indicator for new entrant viability and incumbent margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership | Secures IVDR Article 56 conformity capacity for modified paper card launches in Germany. |
| REACH-Compliant Chemistry Acquisition | Captures Nordic specialty chemical suppliers anchoring ambient-temperature biobanking demand. |
| Integrated Reagent-Card Bundle | Locks Munich's clinical laboratory network into multi-year screening program contracts. |
| CDSCO Registration Acceleration | Opens Maharashtra government tender access for anemia and sickle cell screening volumes. |
| Academic Medical Center Pilot | Generates IVDR-compliant clinical evidence packages for neonatal screening equivalence claims. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with clinical laboratory directors, hospital procurement managers, GPO contracts specialists, and biomedical engineers at academic medical centers in Germany, the United States, and the Netherlands. FDA 510(k) databases, EMA IVDR submission records, CDSCO registration filings, and ISO 13485 certification registries provided device-specific validation timelines. Bottom-up shipment estimates by substrate chemistry and application were cross-referenced against top-down public health budget allocations for neonatal screening programs.
Granularity-level modeling disaggregated volume and value outputs across substrate type, application specificity, end-user category, and packaging configuration throughout the forecast period. CAGRs were derived from regression analysis of historical specimen volumes against public health expenditure trends and regulatory implementation timelines. Forecast inputs incorporated REACH compliance cost trajectories, notified body capacity expansion schedules, and substitution elasticity estimates for liquid biopsy alternatives in oncology monitoring.
Caveats apply where IVDR notified body capacity constraints, cellulose pulp price volatility, or liquid biopsy technology advances could materially shift the outlook. Forecasts reflect assumptions regarding regulatory harmonization progress, public health budget continuity, and clinical laboratory automation adoption rates. A small set of triggers—EMA enforcement intensity, Brazilian ANVISA resolution implementation, and Nordic forestry supply disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Blood Preparation Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Emergency Transfer Vacuum Mattress Market
Medical Supplies
Cell Culture Media Storage Containers Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Polymer Exam Gloves Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
China Hospital Supplies Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
Cryoboxes Market