
 Disposable Specimen Container Market | 2026-2036
Disposable Specimen Container Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Specimen Container Market Outlook
Biodegradable polymer formulations is rewriting manufacturing priorities across the disposable specimen container supply chain. Cardinal Health leverages its distribution network to sustain hospital system contracts across North America. BD anchors its position through R&D intensity in blood collection tube innovation. Thermo Fisher Scientific specializes in transport vial systems for research and clinical diagnostics.
Disposable specimen containers are single-use vessels engineered from polypropylene, polyethylene, or polystyrene with leak-resistant seals and graduated volumetric markings, manufactured via injection molding or blow-molding processes to maintain sterility during biological sample collection, storage, and transport. Blood collection tubes occupy the largest revenue pool due to routine diagnostic testing volumes, while pathology containers represent the fastest-growing segment as oncology screening programs expand. Polypropylene dominates material selection for its chemical resistance and autoclave compatibility, though polyethylene gains share in cost-sensitive educational and research settings.
FDA enforces Class II medical device standards for specimen containers, while EPA regulates clinical waste disposal pathways that shape end-of-life container requirements. ISO 13485 quality management systems and CLSI specimen handling guidelines further constrain product design and manufacturing protocols. Stakeholders must monitor evolving state-level biosafety regulations and polymer sustainability mandates that will reshape material specifications and supplier qualification criteria.
Market Dynamics
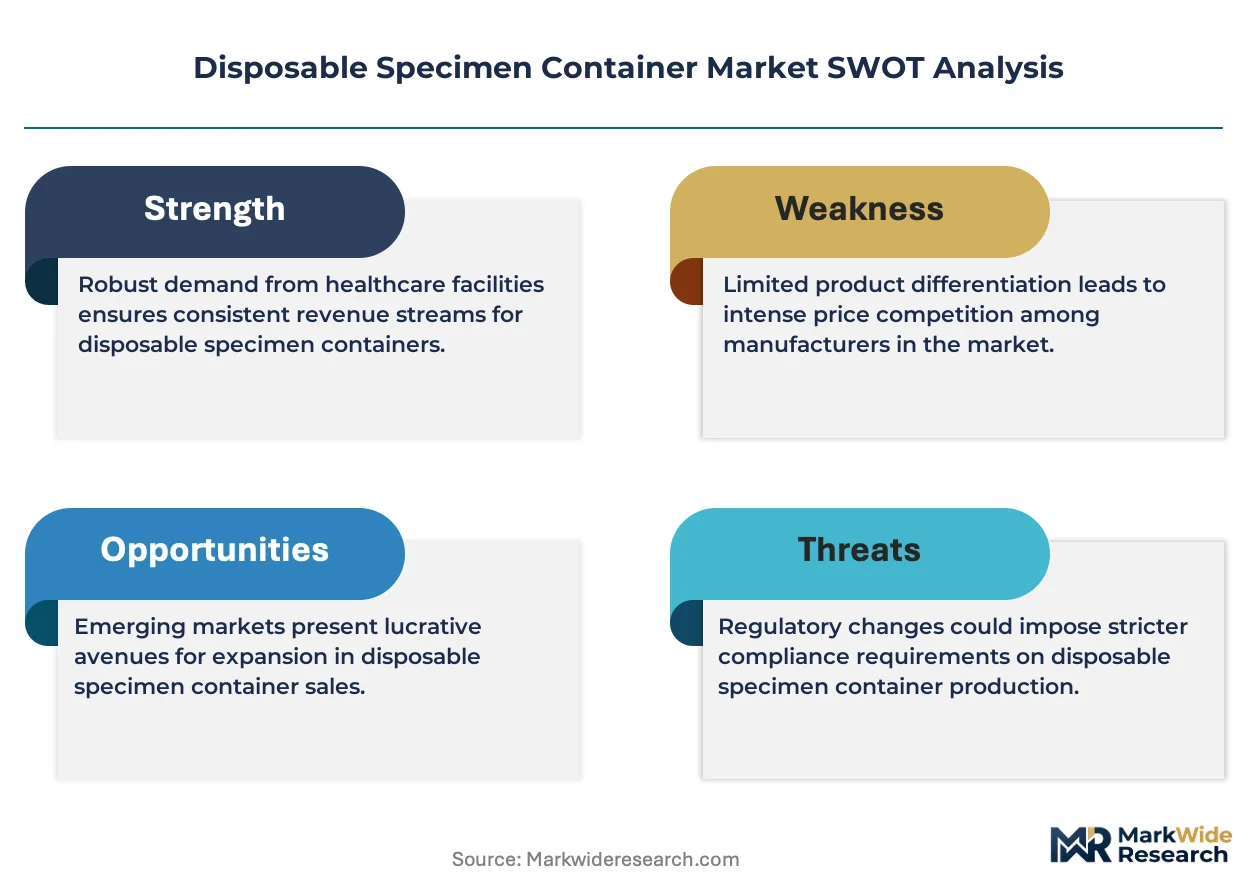
Biodegradable polymer formulations are forcing manufacturers to reconfigure material specifications across the disposable specimen container supply chain. FDA material safety standards and EPA clinical waste disposal pathways are tightening concurrently, compressing design flexibility while elevating compliance costs for sterile single-use vessel production.
Growth Catalysts
- ISO 13485 quality management systems:Certification mandates from diagnostic laboratories are accelerating procurement of validated sterile containers with documented chain-of-custody protocols.
- Oncology screening programs:Hospital networks in the United States are expanding pathology container volumes to support precision diagnostic workflows and liquid biopsy processing.
- Polypropylene chemical resistance:Autoclave-compatible formulations enable multi-modal sterilization cycles that reduce cross-contamination risk in reference laboratory settings.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil indices, compressing margin stability for injection-molding operations.
- Supply concentration in US hospital networks:Group purchasing organizations consolidate buying power, squeezing price realization for container manufacturers without scale.
- Technical limitation in biodegradable seals:Leak-resistant closure mechanisms using polylactic acid degrade before shelf-life expiration in humid transport conditions.
Strategic Opportunities
- Point-of-care testing expansion:Retail clinic chains and urgent care facilities are adopting compact specimen collection kits for decentralized diagnostic workflows.
- EU Green Deal polymer sustainability mandates:REACH-compliant bio-based formulations create qualification pathways for European market entry against incumbent suppliers.
- Telehealth sample collection kits:Direct-to-patient distribution channels bypass traditional hospital procurement for chronic disease monitoring applications.
Industry Challenges
- CLSI specimen handling guideline updates:Revised pre-analytical standards require container redesign cycles that extend product validation timelines by 12-18 months.
- Cleanroom manufacturing capex intensity:ISO Class 7 injection molding facilities demand capital deployment exceeding $15 million per production line.
- Legacy laboratory information system integration:Barcode and RFID-enabled containers face interoperability friction with entrenched hospital IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Specimen Container Market |
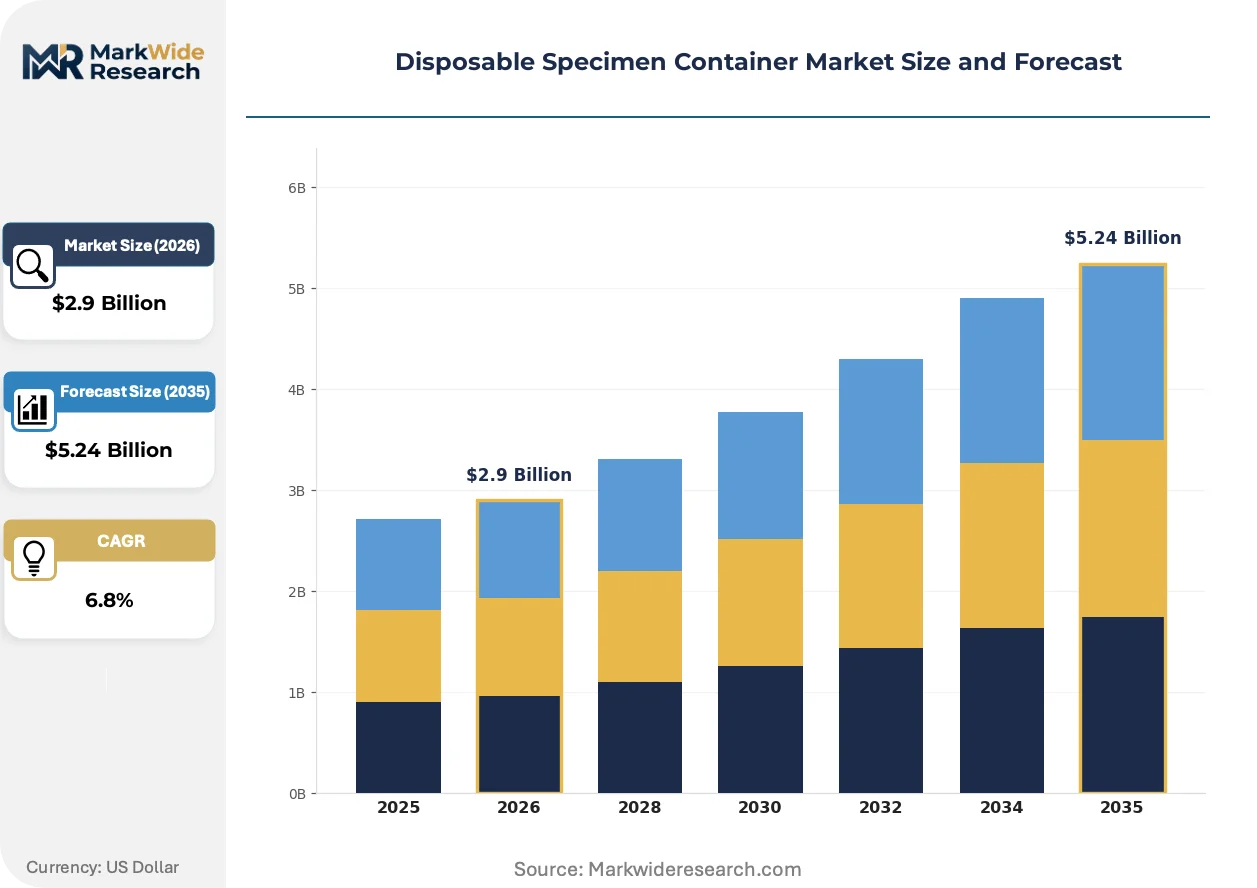
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.24 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urine Containers, Blood Collection Tubes, Pathology Containers, Transport Vials Material: Polypropylene, Polyethylene, Glass, Polystyrene End User: Hospitals, Diagnostic Laboratories, Research Institutes, Educational Facilities Distribution Channel: Direct Sales, Online Retail, Wholesalers, Medical Supply Stores |
| Companies Covered | Cardinal Health, BD, Thermo Fisher Scientific Inc., SARSTEDT AG & Co. KG, Sterimed, Kartell P.I., FL MEDICAL s.r.l., Dynarex Corporation, Vernacare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Specimen Container Market Strategic Shifts
Smart container technologies and sustainable material science are converging to reshape sterile specimen handling. These developments compress traditional manufacturing paradigms while opening new qualification pathways for differentiated products.
RFID-embedded specimen containers is digitizing chain-of-custody documentation across diagnostic laboratory networks. Reference labs in the United States are deploying these systems to eliminate manual tracking errors during high-volume processing. The technology is digitizing audit trails that previously required parallel paper-based verification systems.
EPA clinical waste disposal regulations are mandating container end-of-life traceability for infectious material containment. Manufacturers must now engineer products compatible with both autoclave sterilization and approved incineration pathways. Blood collection tube suppliers face the steepest compliance burden as volume throughput generates the highest waste tonnage.
Hospital procurement departments are consolidating vendor panels around full-line distributors capable of sterile container plus complementary consumable bundling. Independent manufacturers without logistics scale are losing shelf position to integrated supply chain operators. This concentration is most visible in the southeastern United States where health system mergers have compressed supplier counts by half.
Disposable Specimen Container Market Segmentation
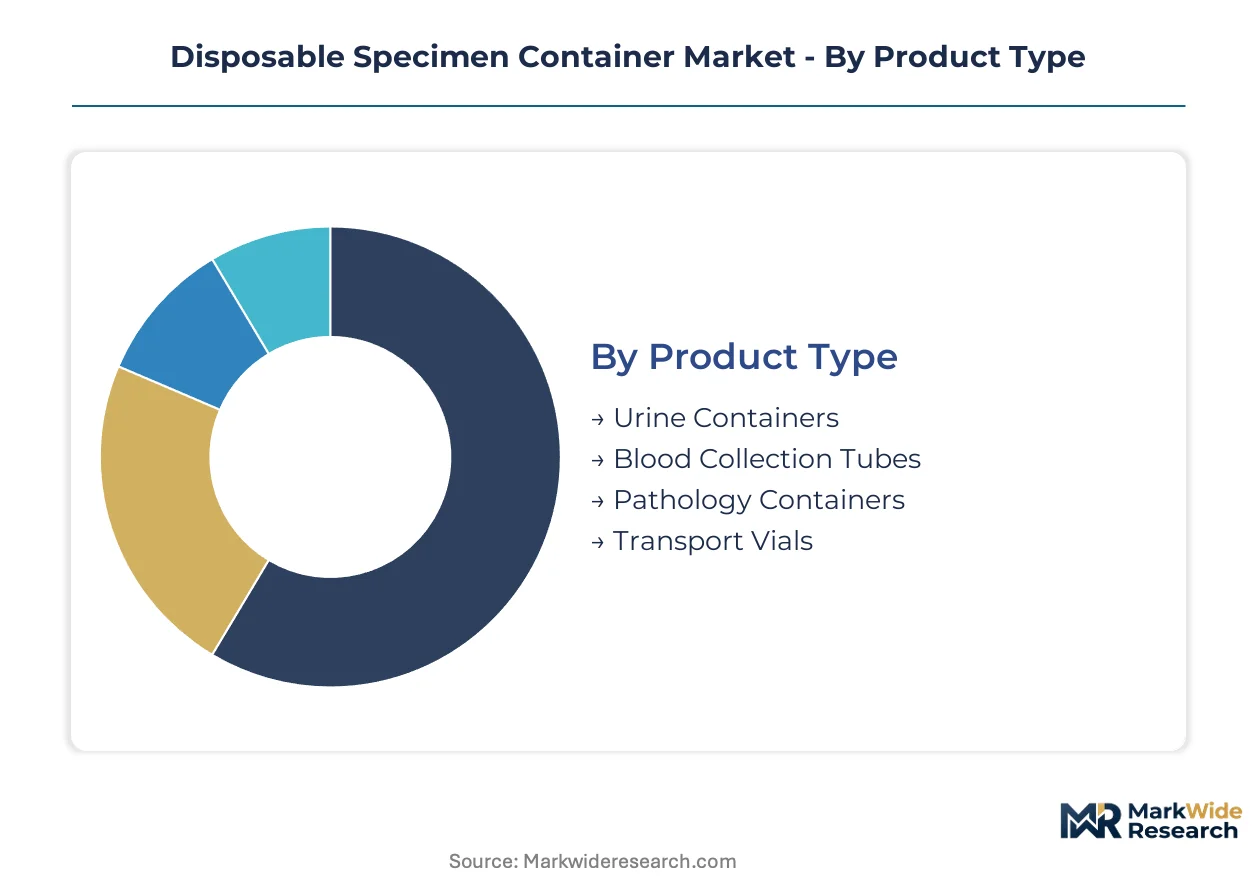
Segmentation in the disposable specimen container market reveals how procurement patterns diverge across clinical workflows, material science capabilities, and supply chain configurations. Each dimension carries distinct margin structures and regulatory burdens that reshape competitive positioning.
Product Type:
Use-case spectrum spans routine urinalysis through precision oncology diagnostics, with each vessel category demanding specialized closure integrity and volumetric accuracy specifications.
- Blood Collection Tubes:Vacuum-sealed borosilicate or plastic tubes with additive coatings (EDTA, heparin, serum separators) engineered for phlebotomy workflows. Demand concentrates in United States hospital networks where high-throughput diagnostic laboratories process millions of specimens annually, constrained by FDA Class II device validation requirements.
- Pathology Containers:Wide-mouth vessels with formalin-compatible seals designed for tissue biopsy preservation and transport. Oncology screening programs in California and Texas health systems are expanding procurement volumes fastest as precision diagnostic protocols proliferate.
- Urine Containers:Sterile leak-resistant cups with temperature-stable seals for drug screening and metabolic panel collection.
- Transport Vials:Compact cylindrical vessels optimized for courier-based specimen logistics between collection sites and reference laboratories.
The dominant share belongs to Blood Collection Tubes, while Pathology Containers are closing the gap fastest.
Material:
Cost tier stratification separates premium autoclave-compatible formulations from economy-grade alternatives in research and educational settings.
- Polypropylene:Thermoplastic polymer with exceptional chemical resistance and autoclave compatibility up to 121°C. Diagnostic laboratories in Massachusetts and Illinois specify this material for multi-modal sterilization cycles that reduce cross-contamination risk in high-complexity testing environments.
- Polyethylene:Lower-density thermoplastic with reduced thermal tolerance but favorable cost profile. Research institutes and educational facilities in cost-sensitive procurement categories favor this material for non-sterile teaching applications.
- Glass:Borosilicate formulations for specialized coagulation studies and volatile compound containment.
- Polystyrene:Rigid amorphous polymer for optical clarity in visual inspection workflows.
Polypropylene commands the volume leadership position, though Polyethylene is gaining share fastest in budget-constrained institutional segments.
End User:
Customer type concentration determines packaging configurations, with hospital procurement departments demanding bulk palletization versus research institutes requiring mixed-SKU flexibility.
- Hospitals:Integrated health systems with centralized supply chain operations negotiating multi-year contracts for sterile container bundles. United States hospital networks in the Southeast—Florida, Georgia, North Carolina—are consolidating vendor panels around full-line distributors.
- Diagnostic Laboratories:Reference labs and independent testing facilities with specialized cold-chain and chain-of-custody requirements. Quest Diagnostics and LabCorp-scale operations in California and New Jersey drive specification standards for barcode-enabled container integration.
- Research Institutes:Academic medical centers and biotechnology research facilities with custom formulation needs.
- Educational Facilities:University laboratories and training programs with cost-optimized procurement thresholds.
Hospitals retain the dominant procurement volume, while Diagnostic Laboratories are expanding their share fastest through reference lab network consolidation.
Distribution Channel:
Supply concentration in group purchasing organizations and integrated distributors is displacing independent wholesale relationships.
- Direct Sales:Manufacturer-to-institution contracts for high-volume hospital networks and national laboratory chains. Cardinal Health and McKesson-scale distributors in Texas and Ohio leverage logistics infrastructure to lock in multi-year sterile container agreements.
- Medical Supply Stores:Regional distributors serving independent physician practices and outpatient clinics. California and New York metropolitan areas sustain dense networks of specialty surgical supply retailers.
- Online Retail:E-commerce platforms for small-quantity research and educational procurement.
- Wholesalers:Traditional distribution intermediaries losing share to integrated supply chain operators.
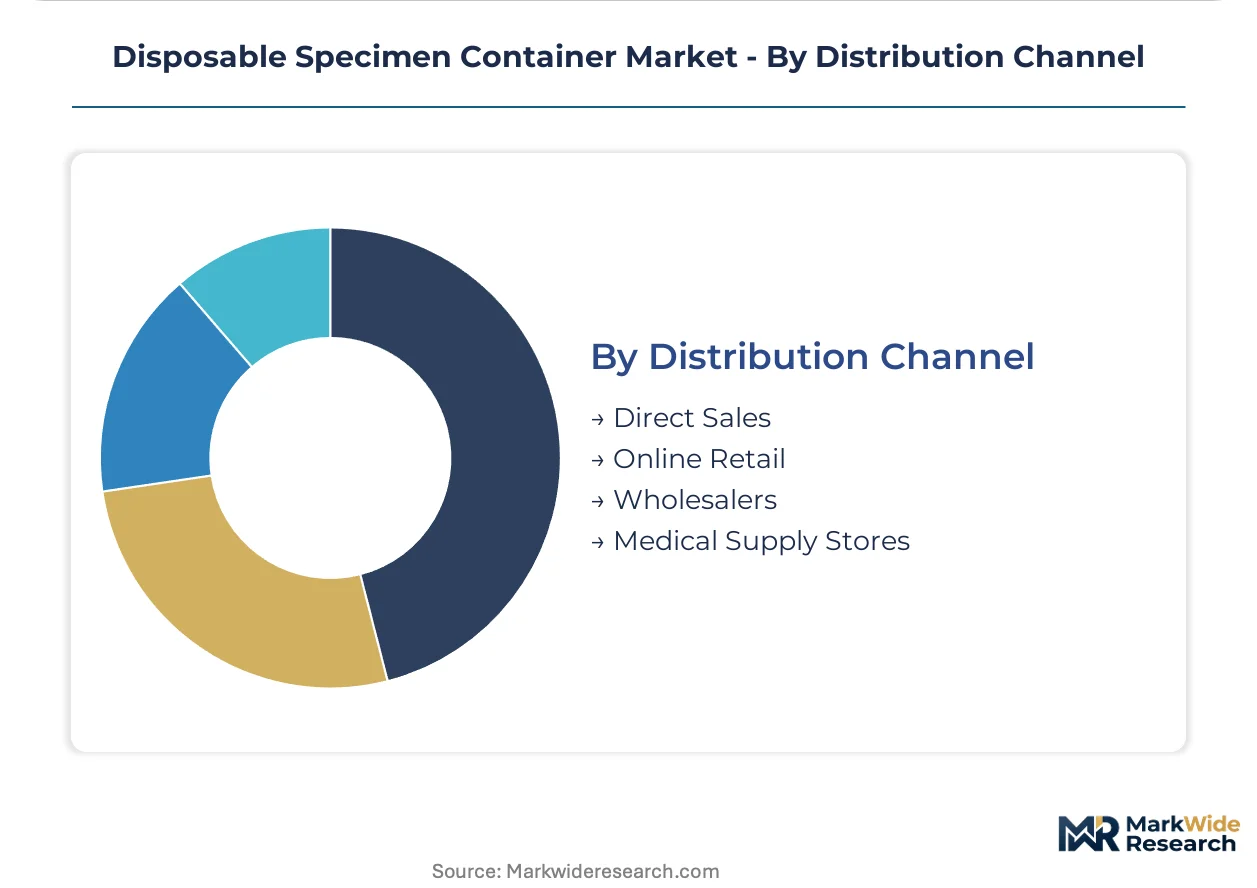
Direct Sales captures the dominant channel share, while Medical Supply Stores are stabilizing fastest in outpatient clinic expansion zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based manufacturers export sterile specimen containers to diagnostic laboratory networks across Canada and Mexico, consolidating North American procurement corridors around FDA-validated supply chains. This trade pattern reflects broader concentration in North American healthcare infrastructure.
United States
Hospital networks in Florida and Texas are expanding pathology container procurement to support precision oncology workflows. FDA Class II device standards enforce stringent sterilization validation protocols for all clinical waste containment products. California's reference laboratory clusters in San Diego and the Bay Area drive specification standards for barcode-enabled container integration with legacy IT systems.
Germany
Diagnostic laboratories in Bavaria and North Rhine-Westphalia are adopting REACH-compliant bio-based polymer formulations for sustainable specimen handling. ECHA polymer sustainability mandates under the EU Green Deal are reshaping material qualification requirements for clinical waste products. The Stuttgart industrial corridor hosts specialized injection-molding operations serving Central European hospital procurement networks.
China
Research institutes in Shanghai and Beijing are scaling procurement of cost-optimized polyethylene containers for non-clinical applications. NMPA medical device registration pathways are tightening quality management system requirements for sterile single-use vessels. The Yangtze River Delta manufacturing belt supplies domestic diagnostic chains while building export capacity for Southeast Asian markets.
India
Hospital networks in Maharashtra and Karnataka are expanding sterile container procurement as CDSCO strengthens medical device quality surveillance. The PLI scheme for medical devices is attracting domestic manufacturing investment in high-complexity polymer molding. Hyderabad's pharmaceutical research corridor generates specialized demand for transport vial systems in clinical trial logistics.
Japan
Reference laboratories in Tokyo and Osaka are deploying RFID-embedded specimen containers for digitized chain-of-custody documentation. PMDA quality system regulations align with ISO 13485 standards for sterile single-use device manufacturing. The Kansai industrial region maintains precision molding capabilities serving domestic diagnostic networks with limited import dependency.
Disposable Specimen Container Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement categories, creating a bifurcated structure where logistics scale determines hospital network access. The vendor base separates into full-line distributors with integrated supply chains, polymer-focused manufacturers with material science depth, and regional fabricators serving cost-sensitive institutional segments. Two strategic archetypes dominate: distributors bundling sterile containers with complementary consumables, and specialists engineering proprietary closure systems for high-integrity transport applications. Competitive moves center on vendor panel consolidation through multi-year hospital contracts and backward integration into polymer compounding to secure resin supply stability.
Within the distributor archetype, Cardinal Health exemplifies channel-control positioning through North American logistics infrastructure, while BD occupies a specialist role anchored in blood collection innovation. Thermo Fisher Scientific represents the research-clinical hybrid tier, bridging diagnostic laboratory and biotechnology research demand. These three companies illustrate how scale, specialization, and portfolio breadth create distinct competitive positions without overlapping strategic territory.
| Leading Market Players |
|---|
| Cardinal Health |
| BD |
| Thermo Fisher Scientific Inc. |
| SARSTEDT AG & Co. KG |
| Sterimed |
| Kartell P.I. |
| FL MEDICAL s.r.l. |
| Dynarex Corporation |
| Vernacare |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta manufacturing belt anchors polypropylene resin conversion capacity for sterile specimen containers, with injection-molding output fluctuations in Shanghai and Suzhou transmitting directly to North American hospital procurement pricing power. This geographic concentration enables volume-tier contract leverage for integrated distributors while squeezing margin flexibility for independent manufacturers without captive resin supply.
Pricing Analysis
RFID-enabled next-generation containers command substantial premiums over standard barcode-labeled current-generation vessels, while economy-grade polyethylene alternatives without sterilization validation occupy the lowest pricing tier. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification status and autoclave compatibility grade. Cost compression in the standard tier is intensifying because group purchasing organizations consolidate hospital network buying power. Research institutes and educational facilities exhibit the highest price sensitivity, while reference laboratories prioritizing chain-of-custody integrity demonstrate the lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for polypropylene resin and injection-molding equipment imports. Manufacturing concentrates in China, the United States, and Germany, with the latter serving European diagnostic laboratory demand through REACH-compliant production. Raw material supply draws from petrochemical feedstock streams, medical-grade polymer compounding operations, and sterilization validation services. Single-source vulnerability in borosilicate glass tubing for specialized blood collection applications constrains product line breadth. Distribution runs through integrated healthcare distributors with hospital system contract lock-in.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable specimen container demand follows cyclical recovery patterns tied to hospital capital expenditure cycles, with deferred procurement from pandemic-era budget freezes now releasing as health system mergers consolidate purchasing authority.
For Market Incumbents: Insulate market position through backward integration into polymer compounding operations that secure resin cost stability against petrochemical volatility. Cardinal Health-scale distributors should deepen hospital system contract bundling with complementary sterile consumables to raise switching costs for procurement committees. FDA material safety standard tightening poses the primary regulatory threat requiring proactive validation investment. For New Entrants and Emerging Players: Establish a beachhead in telehealth sample collection kits for direct-to-patient distribution channels that bypass entrenched group purchasing organization gatekeepers. Point-of-care testing expansion in retail clinic chains offers the most penetrable entry vector given lower certification barriers and fragmented buyer concentration. A go-to-market angle emphasizing biodegradable polymer formulations with documented shelf-life performance addresses sustainability procurement mandates without incumbent legacy product cannibalization constraints. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized medical device divisions lacking ISO 13485 certification depth. Long-term viability over the projection horizon rests on regulatory compliance infrastructure and hospital network contract tenure rather than manufacturing scale alone. The signal to watch as inflection indicator is state-level biosafety regulation adoption velocity, particularly polymer sustainability mandates that reshape material qualification requirements and supplier panels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin supply insulates margin stability against crude oil index volatility for injection-molding operations. |
| RFID-Enabled Container Development | Smart specimen tracking addresses Quest Diagnostics-scale reference laboratory chain-of-custody digitization requirements. |
| REACH-Compliant Bio-Based Formulation | Sustainable polymer qualification opens European market entry pathways against incumbent suppliers under EU Green Deal mandates. |
| Telehealth Sample Collection Kit Launch | Direct-to-patient distribution bypasses traditional hospital procurement for chronic disease monitoring applications. |
| Hospital System Partnership Consolidation | Multi-year sterile container bundling contracts with Florida and Texas health networks raise competitive switching costs. |
Study Parameters
A spread of perspectives from hospital procurement managers, diagnostic laboratory operations directors, biomedical engineers, and group purchasing organization contract specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EPA clinical waste disposal pathway documentation, hospital procurement databases, and ISO 13485 certification registries. Bottom-up demand modeling from end-user segments triangulated against top-down supply-side capacity assessments across the projection horizon.
Demand-supply-balance dynamics anchored the analytical framework, with segmentation across product type, material formulation, end-user category, and distribution channel informing volume and value outputs. Blood collection tube demand, pathology container growth, and transport vial adoption patterns were modeled separately before aggregation. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and health system consolidation events. Forecast inputs incorporated polymer resin price indices, hospital merger activity, and oncology screening program expansion rates.
Stress conditions across petrochemical feedstock volatility, FDA validation timeline extensions, and group purchasing organization contract renewal concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sterile container procurement cycle normalization and biodegradable seal technical performance improvement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Colostomy Bags Market
Medical Supplies
Catgut Sutures Market
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
Europe Amniotic Membrane Market
Medical Supplies
Asia-Pacific Syringe Market
Medical Supplies
Skin Traction Kits Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Bladder Liners Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Lab Trays Market