
 Tattoo Needles Market | 2026-2036
Tattoo Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Tattoo Needles Market Analysis
China is tilting toward large-scale tattoo needle manufacturing with upgraded stainless steel processing clusters in Zhejiang and Guangdong provinces. Cheyenne Professional Tattoo Equipment anchors its European footprint with precision-machined cartridge systems manufactured in Germany. Kwadron leverages its Polish production base to supply premium textured needles across Central and Eastern European studios. Dragonhawk competes aggressively on cost through vertically controlled Chinese supply chains serving entry-level artists globally.
Tattoo needles are precision-engineered instruments, typically constructed from 316L stainless steel or nickel-plated carbon steel, with needle groupings soldered to a central bar at specified taper angles to control ink flow and skin penetration depth. Their primary commercial purpose is depositing pigment into the dermis layer for permanent body art, cosmetic pigmentation, and select medical marking applications. Round liner configurations dominate procedural volume in professional studios due to their versatility for outlining and detailed work. Pre-sterilized single-use cartridges command expanding share as health authorities mandate disposable protocols, while multi-use configurations retreat to specialized traditional markets with stringent autoclave compliance.
FDA device regulations classify tattoo needles alongside body-art equipment, requiring sterility validation and biocompatibility documentation for US market access. EU MDR and REACH frameworks govern nickel release limits and chemical composition disclosure, forcing material substitutions across European supply chains. South Korea's MFDS enforces KFDA-equivalent sterilization standards that block non-compliant imports. Stakeholders must monitor evolving classification debates that could reclassify tattoo needles from general consumables to regulated medical devices in key jurisdictions.
Market Dynamics
Pre-sterilized single-use cartridges are compressing multi-use needle configurations as FDA and EU MDR enforcement tightens across licensed studio networks, forcing capital reallocation toward disposable manufacturing lines.
Growth Catalysts
- EU MDR sterilization mandates:Disposable protocols now govern body-art equipment classification, accelerating cartridge adoption across German and French studio chains.
- Cosmetic tattooing clinics:Permanent makeup procedures for eyebrows and lips expand needle consumption beyond traditional body art into medical-adjacent applications.
- 316L stainless steel processing:Zhejiang and Guangdong clusters upgrade precision machining capabilities, lowering unit costs for premium needle configurations.
Market Restraints
- Nickel release limits under REACH:Material substitution requirements raise raw material costs for European manufacturers sourcing compliant alloys.
- Supply concentration in East Asian forging:Dependency on Chinese stainless steel bar stock creates input volatility during trade policy shifts.
- Autoclave compliance burden:Traditional multi-use configurations face shrinking addressable market as studio licensing boards mandate disposable-only protocols.
Strategic Opportunities
- Brazilian regulatory opening:ANVISA's evolving medical device classification framework may create first-mover advantage for pre-sterilized cartridge suppliers.
- Paramedical marking applications:Radiation therapy positioning tattoos and surgical site marking extend needle utility into hospital procurement channels.
- Direct-to-studio e-commerce:Bypassing distributor markups through specialized supply platforms captures margin from fragmented artist purchasing.
Industry Challenges
- Cleanroom certification timelines:ISO 13485 compliance for cartridge assembly facilities extends facility validation periods by 12-18 months.
- Needle taper angle standardization:Absence of unified dimensional specifications forces manufacturers to maintain redundant SKUs across export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tattoo Needles Market |
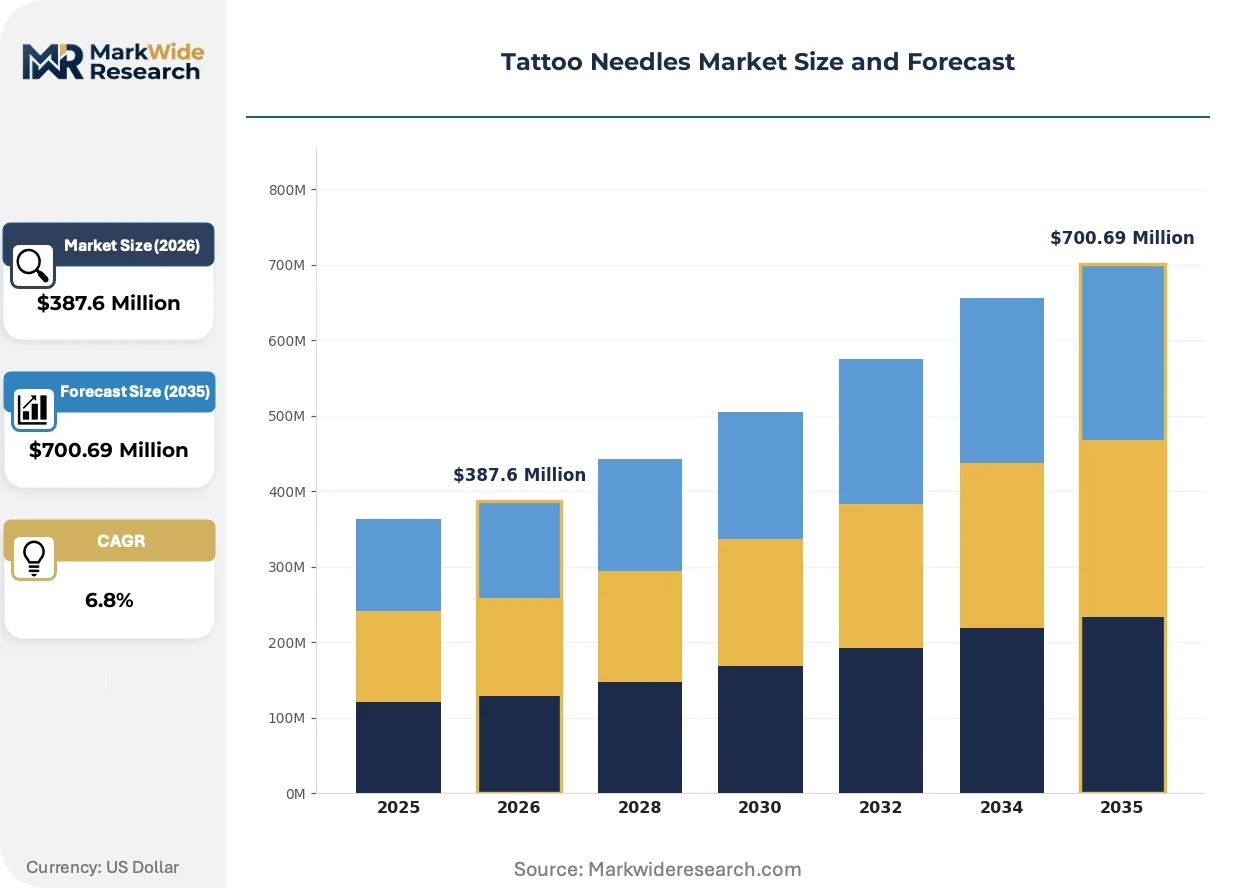
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Liner, Round Shader, Magnum, Flat Material: Stainless Steel, Nickel-Plated, Disposable, Carbon Steel Configuration: Single Use, Multi-Use, Pre-Sterilized, Custom End User: Tattoo Studios, Freelance Artists, Cosmetic Tattooing, Medical Professionals |
| Companies Covered | Dynamic Color, Cheyenne Professional Tattoo Equipment, Inkjecta, Kwadron, Eternal Ink, Dragonhawk, CNC, Bishop, JCONLY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tattoo Needles Market Emerging Trajectories
Cartridge system architecture is fragmenting into modular subcomponents as manufacturers compete on swap speed, ink retention, and vibration dampening for extended session comfort.
Membrane-sealed cartridge technology is hybridizing traditional needle bar mechanics with disposable housing economics. Premium studios in South Korea and Germany adopt these systems for their elimination of cross-contamination risk between color changes. The convergence is compressing demand for standalone needle bars and reusable grips.
EU MDR Annex XVI classification expansion is redefining tattoo equipment as borderline medical devices in multiple member states. Manufacturers must now submit biocompatibility documentation and post-market surveillance plans. Smaller Polish and Italian suppliers face compliance costs that favor scaled German producers with existing quality management systems.
Artist purchasing collectives are aggregating demand across independent studios to negotiate volume pricing directly with manufacturers. These buying groups bypass traditional tattoo supply distributors in the United States and United Kingdom. The disintermediation is most pronounced among mid-career artists operating private studios outside major metropolitan licensing districts.
Tattoo Needles Market Segmentation
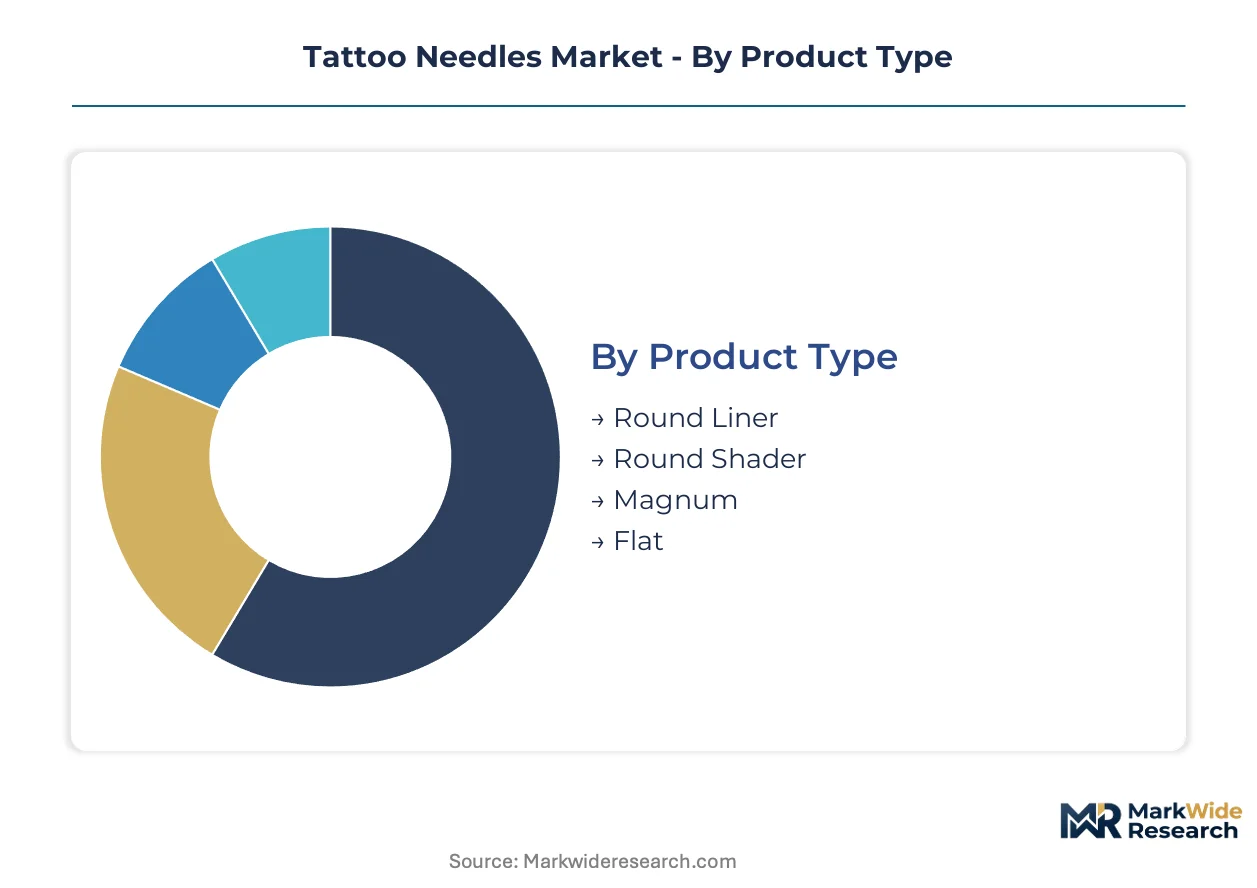
Tattoo needle segmentation reflects divergent technical requirements across body art, cosmetic pigmentation, and medical marking applications. Configuration choices directly impact regulatory compliance costs and sterilization protocols in licensed markets.
Product Type:
Needle geometry determines ink flow dynamics and skin penetration characteristics for specific artistic techniques.
- Round Liner:Tapered needles clustered in circular formations deposit concentrated pigment lines. German and South Korean studios specify these configurations for 70% of outlining procedures due to precision control.
- Round Shader:Looser needle groupings with rounded tips enable soft shading and color packing. Demand concentrates in cosmetic tattooing clinics across France and Italy where eyebrow microblading requires graduated tone application.
- Magnum:Two rows of needles in flat or curved arrangements cover large surface areas efficiently. Traditional Japanese tebori practitioners and American realism specialists favor these for background fills.
- Flat:Single-row straight configurations deliver sharp edges and geometric precision. Geometric and tribal specialists in Brazil and Mexico specify flat needles for clean line saturation.
Round Liner commands the established base. The steepest expansion runs through Magnum configurations as large-format tattooing gains commercial traction.
Material:
Raw material selection governs corrosion resistance, nickel leaching compliance, and unit economics across manufacturing clusters.
- Stainless Steel:316L surgical grade dominates premium cartridge production. Zhejiang forging facilities supply this material to Cheyenne and Kwadron for EU MDR-compliant configurations.
- Nickel-Plated:Carbon steel substrates with electroplated nickel coatings face REACH substitution pressure. Polish manufacturers are phasing these out ahead of ECHA nickel release limit enforcement.
- Disposable:Polymer-based needle alternatives serve allergy-sensitive clients in Japanese and Australian markets.
- Carbon Steel:Uncoated variants persist in traditional hand-poke markets where artists source raw wire for custom fabrication.
Stainless Steel retains volume leadership. The steepest expansion trajectory belongs to Disposable materials as biocompatibility certification requirements intensify.
Configuration:
Usage protocols separate regulated professional markets from traditional practitioner segments with divergent compliance burdens.
- Single Use:Pre-sterilized cartridges eliminate cross-contamination risk entirely. FDA device regulations and EU MDR Annex XVI classification mandate these across licensed United States and German studio networks.
- Multi-Use:Autoclave-compatible needle bars require capital equipment investment. These configurations retreat to specialized markets in Thailand and Indonesia where licensing enforcement remains fragmented.
- Pre-Sterilized:Gamma-irradiated or EO-sterilized packaging commands premium pricing in hospital procurement channels for radiation therapy marking.
- Custom:Bespoke taper angles and grouping densities serve celebrity artists with proprietary techniques. Los Angeles and London studios commission these through direct manufacturer relationships.
Single Use configurations dominate professional procurement. The steepest expansion runs through Pre-Sterilized variants as medical-adjacent applications multiply.
End User:
Customer type segmentation maps divergent purchasing power, volume scale, and regulatory exposure across market tiers.
- Tattoo Studios:Licensed establishments with health department oversight purchase through verified distributors. These entities in New York, Berlin, and Seoul drive cartridge standardization through collective procurement.
- Freelance Artists:Independent practitioners operating outside studio systems favor direct-to-consumer e-commerce platforms. This segment in São Paulo and Mexico City exhibits price sensitivity and brand fragmentation.
- Cosmetic Tattooing:Medical-adjacent clinics performing permanent makeup require higher sterility documentation. South Korean MFDS registration blocks non-compliant imports for these users.
- Medical Professionals:Radiation oncologists and surgical teams utilize tattoo needles for positioning marks. Hospital procurement channels in Canada and Switzerland demand ISO 13485 supplier certification.
Tattoo Studios command the established base. The steepest expansion runs through Medical Professionals as paramedical marking protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA device regulations governing sterility validation anchor the United States as the dominant geography for pre-sterilized cartridge adoption. Licensed studio density in New York, Los Angeles, and Miami drives procurement volume. Divergent regulatory frameworks across Germany, South Korea, China, and Brazil shape distinct market development trajectories.
United States
Licensed tattoo studios in New York, Los Angeles, and Miami constitute the primary demand base for pre-sterilized single-use cartridges. FDA device regulations mandate sterility validation and biocompatibility documentation for all body-art equipment imports. California's health department oversight enforces disposable-only protocols in Los Angeles County, compressing multi-use needle configurations to fringe traditional markets.
Germany
Cheyenne Professional Tattoo Equipment anchors European precision manufacturing from its German production base for cartridge systems. EU MDR Annex XVI classification redefines tattoo equipment as borderline medical devices, requiring post-market surveillance plans from manufacturers. Berlin and Hamburg studio chains drive standardization through collective procurement agreements that favor MDR-compliant suppliers.
South Korea
Cosmetic tattooing clinics in Seoul expand needle consumption beyond traditional body art into permanent makeup applications. MFDS enforces KFDA-equivalent sterilization standards that block non-compliant imports for medical-adjacent users. Busan-Ulsan manufacturing clusters supply premium textured needles to domestic studios and export markets across East Asia.
China
Zhejiang and Guangdong provinces upgraded stainless steel processing capabilities to serve global OEM demand for 316L surgical grade configurations. Dragonhawk competes on cost through vertically controlled supply chains serving entry-level artists internationally. SAMR oversight of medical device classifications creates compliance preparation costs for exporters targeting regulated jurisdictions.
Brazil
Geometric and tribal specialists in São Paulo and Rio de Janeiro specify flat needle configurations for clean line saturation in large-format work. ANVISA's evolving medical device classification framework may create first-mover advantage for pre-sterilized cartridge suppliers. São Paulo studio licensing boards increasingly mandate disposable protocols, mirroring North American and European standards.
Tattoo Needles Market Vendor Landscape
Precision-engineering specialists and cost-optimized volume manufacturers split the market into divergent value capture tiers. German and Polish producers command premium positioning through MDR-compliant quality systems, while Chinese supply chains dominate entry-level price points. Three archetypes define competitive positioning: European precision manufacturers with medical-grade certifications, East Asian volume producers with captive forging capacity, and specialist suppliers serving cosmetic tattooing niches. Capacity expansion in Zhejiang clusters and MDR compliance investments by German producers represent the dominant competitive moves reshaping supply structure.
Among European precision manufacturers, Cheyenne Professional Tattoo Equipment GmbH and Kwadron occupy positions exemplifying the medical-grade certification archetype. Dragonhawk sits within the cost-optimized tier, representing East Asian volume production capabilities. These three anchors illustrate the geographic and strategic bifurcation structuring competitive dynamics across regulated and price-sensitive market segments.
| Leading Market Players |
|---|
| Dynamic Color |
| Cheyenne Professional Tattoo Equipment |
| Inkjecta |
| Kwadron |
| Eternal Ink |
| Dragonhawk |
| CNC |
| Bishop |
| JCONLY |
| Others |
Supply Flow & Price Mechanics
Zhejiang and Guangdong stainless steel forging clusters concentrate upstream input supply, anchoring cost structures for downstream cartridge manufacturers while EU MDR compliance investments in Germany and Poland capture premium margin pools through medical-grade certification tiers.
Pricing Analysis
Geographic price spreads separate German-manufactured MDR-compliant cartridges from Chinese volume-tier supplies by certification-grade premiums rather than raw material differentials alone. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status, sterilization protocol validation, and brand positioning in licensed studio procurement channels. Cost compression in entry-level configurations intensifies as Dragonhawk and CNC expand Zhejiang forging capacity. Freelance artists in São Paulo and Mexico City exhibit acute price sensitivity, while hospital procurement channels in Canada and Switzerland prioritize compliance documentation over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize distributor financing relationships as manufacturers bridge working capital gaps between Zhejiang forging and European assembly facilities. Supply concentrates in China for 316L stainless steel bar stock, Germany for precision cartridge machining, and Poland for textured needle finishing. Raw material dependencies center on surgical-grade steel alloys, gamma-irradiation sterilization services, and medical-grade polymer housings. Single-source vulnerability in East Asian forging creates tariff exposure during trade policy shifts. Distribution runs through verified distributor networks for licensed studios, direct-to-studio e-commerce platforms for independent artists, and hospital procurement systems for medical-adjacent applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against polymer-based disposable alternatives and membrane-sealed cartridge substitutes that threaten traditional needle bar economics across regulated jurisdictions.
For Market Incumbents: Build regulatory certification moats through EU MDR Annex XVI compliance investments and ISO 13485 quality system accreditation. Defend against membrane-sealed cartridge substitutes by accelerating sterile barrier technology R&D. Deepen backward integration into Zhejiang forging capacity to secure 316L supply amid REACH nickel substitution mandates. Channel control through direct-to-studio platforms captures margin from disintermediating traditional distributors. For New Entrants and Emerging Players: Build out white-space presence in Brazilian ANVISA-regulated markets before medical device classification solidifies. Target São Paulo geometric tattoo specialists with flat needle configurations optimized for large-format tribal work. Penetrate cosmetic tattooing clinics in Seoul through MFDS-sterilization-equivalent documentation. Pursue artist purchasing collectives in the United States and United Kingdom as go-to-market anchors bypassing entrenched distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward precision-manufacturing specialists with existing MDR quality systems and cleanroom assembly infrastructure. Long-term viability across the projection horizon hinges on regulatory compliance scalability rather than volume scale alone. Watch for EU MDR reclassification debates that could elevate tattoo needles to regulated medical device status as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Investment | EU MDR Annex XVI documentation unlocks German and French studio chain procurement contracts. |
| Backward Integration into Forging | Zhejiang 316L steel processing captive supply insulates against REACH nickel substitution cost volatility. |
| Direct-to-Studio E-Commerce Launch | Specialized supply platforms capture distributor margin from fragmented artist purchasing in São Paulo. |
| Membrane-Sealed Cartridge Development | Sterile barrier technology eliminates cross-contamination risk for South Korean cosmetic tattooing clinics. |
| Hospital Procurement Channel Entry | ISO 13485 certification opens radiation therapy marking contracts with Canadian oncology departments. |
Methodological Framework
The analysis maps round liner, magnum, and cosmetic pigmentation configurations, each validated through tattoo studio owners, cartridge manufacturing engineers, health department licensing officials, and hospital procurement managers. Primary interviews with Cheyenne, Kwadron, and Dragonhawk distribution executives combined with secondary validation from FDA device classification databases, EU MDR Annex XVI guidance documents, ANVISA regulatory filings, and MFDS sterilization standards. Bottom-up demand modeling across studio density metrics triangulates with top-down trade flow analysis from Chinese customs records and German industrial production indices.
Assumptions held regulatory classification frameworks constant while varying sterilization protocol adoption rates and cosmetic tattooing penetration across geographies. The analytical framework segments by needle geometry, material grade, usage configuration, and end-user type across the analysis window. CAGRs derive from installed base replacement cycles, studio licensing growth trajectories, and paramedical application expansion. Forecast inputs incorporate 316L steel processing capacity additions in Zhejiang and EU MDR compliance timeline delays for Polish and Italian suppliers.
Stress conditions across REACH nickel release limit enforcement, FDA reclassification debates, and Brazilian ANVISA medical device framework evolution were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic contraction in discretionary body art spending, regulatory reclassification to medical device status in additional jurisdictions, or breakthrough polymer needle biocompatibility certification would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cell Culture Media Bags Market
Medical Supplies
North America Insulin Syringe Market
Medical Supplies
Drosophila Bottles Market
Medical Supplies
Hospital Gowns Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Anaesthesia Conduction Kits Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Safety Box for Syringe Market
Medical Supplies
Intraosseous Infusion Kits Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Arterial Blood Collection Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Global Needles Market
Medical Supplies
United States Intravenous Solutions Market