
 Suture Sleeve Kit Market | 2026-2036
Suture Sleeve Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Suture Sleeve Kit Market Analytics
Market Context
CE marking under the EU Medical Device Regulation is pivoting the cost-of-entry calculus for suture sleeve kit manufacturers seeking European market access. Abbott leverages its integrated structural heart portfolio to anchor premium positioning across hospital procurement networks. Medtronic sustains manufacturing scale advantages through captive silicone molding operations in Costa Rica. Boston Scientific Corporation differentiates via specialized cardiac rhythm management accessory lines that navigate complex reimbursement pathways.
Technical Definition and Segment Structure
A suture sleeve kit comprises sterile, biocompatible sleeves—typically silicone or polyethylene—that secure and strain-relieve lead wires at the implantation site in cardiac and neuromodulation devices, manufactured via injection molding and gamma sterilization to maintain ISO 10993 compliance. Conventional sleeves dominate current hospital purchasing volumes due to established clinician familiarity and lower per-unit cost, while adjustable sleeves capture expanding margin pools as minimally invasive techniques require finer lead tension control. Silicone material formulations lead the material segmentation because of established biocompatibility profiles, though polyethylene competes aggressively in cost-sensitive ambulatory surgical center channels.
Regulatory Framework
The FDA enforces 510(k) premarket notification requirements for suture sleeve kits classified as cardiovascular accessories, while ISO 14155 governs clinical investigation standards across major markets and Japan's PMDA mandates additional biocompatibility documentation for imported silicone components. These frameworks shape demand by lengthening product development timelines and concentrating procurement authority among vendors with established regulatory dossiers. Stakeholders must monitor evolving MDR technical documentation requirements in Europe and assess whether in-house sterilization capabilities or contract partnerships offer superior compliance economics.
Market Dynamics
FDA's tightened 510(k) validation requirements for cardiovascular accessories are compressing the vendor base and forcing cardiac rhythm management device manufacturers to consolidate procurement relationships with regulatory-dossier holders.
Growth Catalysts
- Minimally invasive lead placement techniques:Finer tension control requirements in catheter-based procedures are pulling adjustable sleeve configurations into standard implant workflows.
- ISO 10993 biocompatibility frameworks:Harmonized international standards are reducing redundant testing burdens for manufacturers with multi-region dossiers.
- United States hospital procurement standardization:Integrated delivery networks are consolidating suture sleeve purchasing under single-source contracts with full accessory portfolios.
Market Restraints
- Medical-grade silicone supply concentration:Captive molding operations in Central America create geographic single-source risk for non-vertically integrated kit assemblers.
- EU MDR technical documentation burden:CE marking pivot under the Medical Device Regulation is extending product registration timelines and freezing new entrant pipelines.
- Established clinician familiarity with conventional sleeves:Low switching incentive among tenured electrophysiologists limits premium pricing capture for adjustable configurations.
Strategic Opportunities
- Ambulatory surgical center channel expansion:Polyethylene material variants priced for cost-sensitive outpatient settings are opening volume pools outside tertiary hospital systems.
- Neuromodulation device applications:Spinal cord and deep brain stimulation implants are replicating cardiac lead securement protocols and creating accessory pull-through demand.
- In-house gamma sterilization capabilities:Vertical control over terminal sterilization is compressing compliance economics and accelerating regulatory submission cycles.
Industry Challenges
- ISO 14155 clinical investigation execution:Cardiovascular accessory trials require specialized electrophysiology site networks that concentrate investigator access among incumbent sponsors.
- Legacy sterilization validation backlog:Contract gamma facilities face scheduling congestion that delays new product commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suture Sleeve Kit Market |
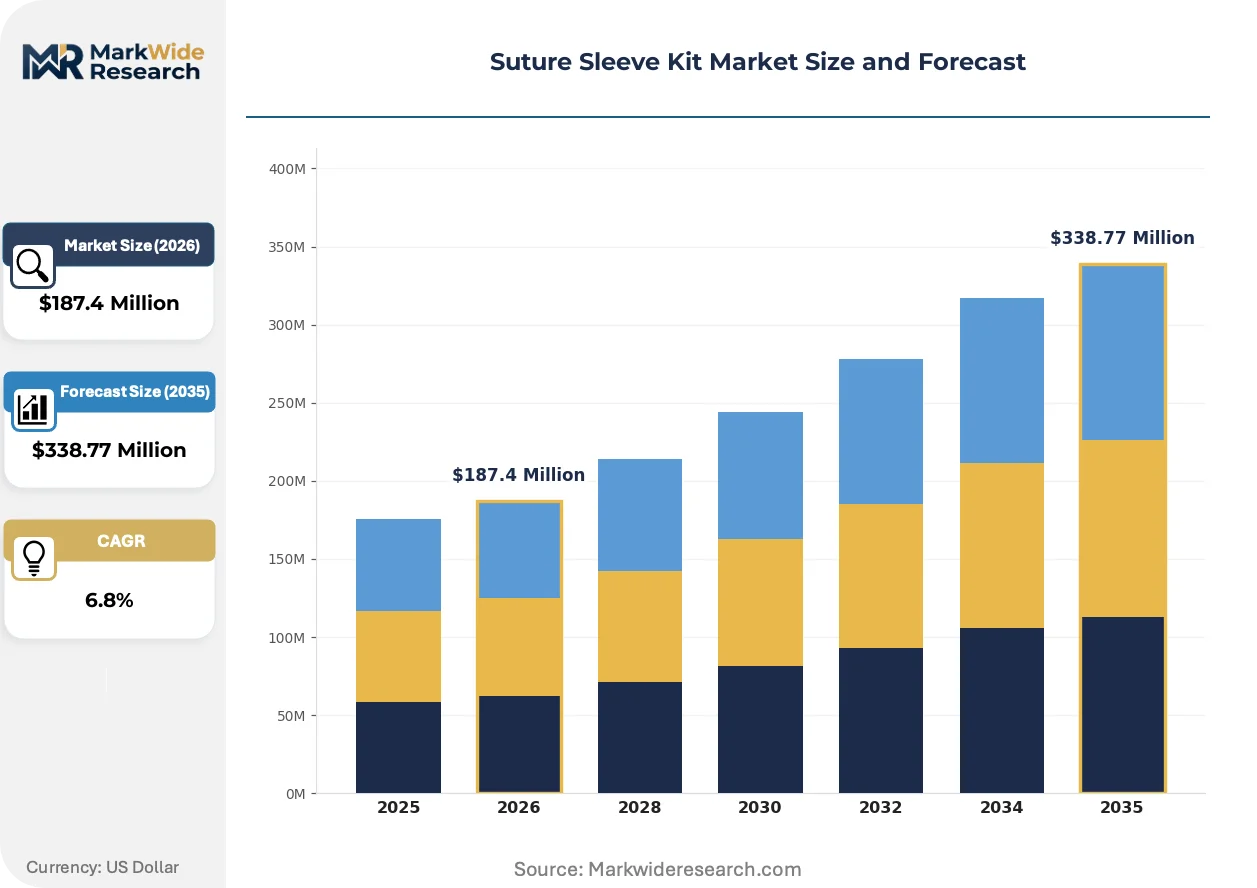
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Sleeves, Adjustable Sleeves, Disposable Sleeves, Sterile Sleeves Application: Wound Closure, Surgical Procedures, Cosmetic Surgery, Trauma Treatment Material: Silicone, Polyethylene, Latex, Non-Woven Fabric End User: Hospitals, Ambulatory Surgical Centers, Clinics, Homecare Settings |
| Companies Covered | NMS Co. Ltd, Medical Model Manufacture, Medic Trainer, FAUX Medical Canada, Strategic Operations Inc, OSCOR Inc, Abbott, Boston Scientific Corporation, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suture Sleeve Kit Market Evolving Landscape
Material science convergence with procedural technique evolution is redefining performance benchmarks for lead securement accessories across implantable device categories.
Silicone-polyethylene hybrid formulations are expanding into cardiac rhythm management accessory lines. Electrophysiology labs in integrated delivery networks are piloting these materials for dual-property performance. The technology is expanding into premium positioning strategies that justify per-unit cost premiums over conventional single-material sleeves.
Japan's PMDA biocompatibility documentation mandates for imported silicone components are tightening import inspection protocols. Foreign manufacturers must now submit expanded cytotoxicity and sensitization data packages. Cardiac device assemblers sourcing Japanese-market kits are responding by qualifying domestic sterilization partners to bypass cross-border documentation friction.
Hospital procurement committees are consolidating suture sleeve purchasing under structural heart device master agreements. Bundled contracting is displacing standalone accessory procurement through distributor channels. This concentration is most visible in United States integrated delivery networks where Abbott and Medtronic field teams negotiate comprehensive implant portfolios.
Suture Sleeve Kit Market Segmentation
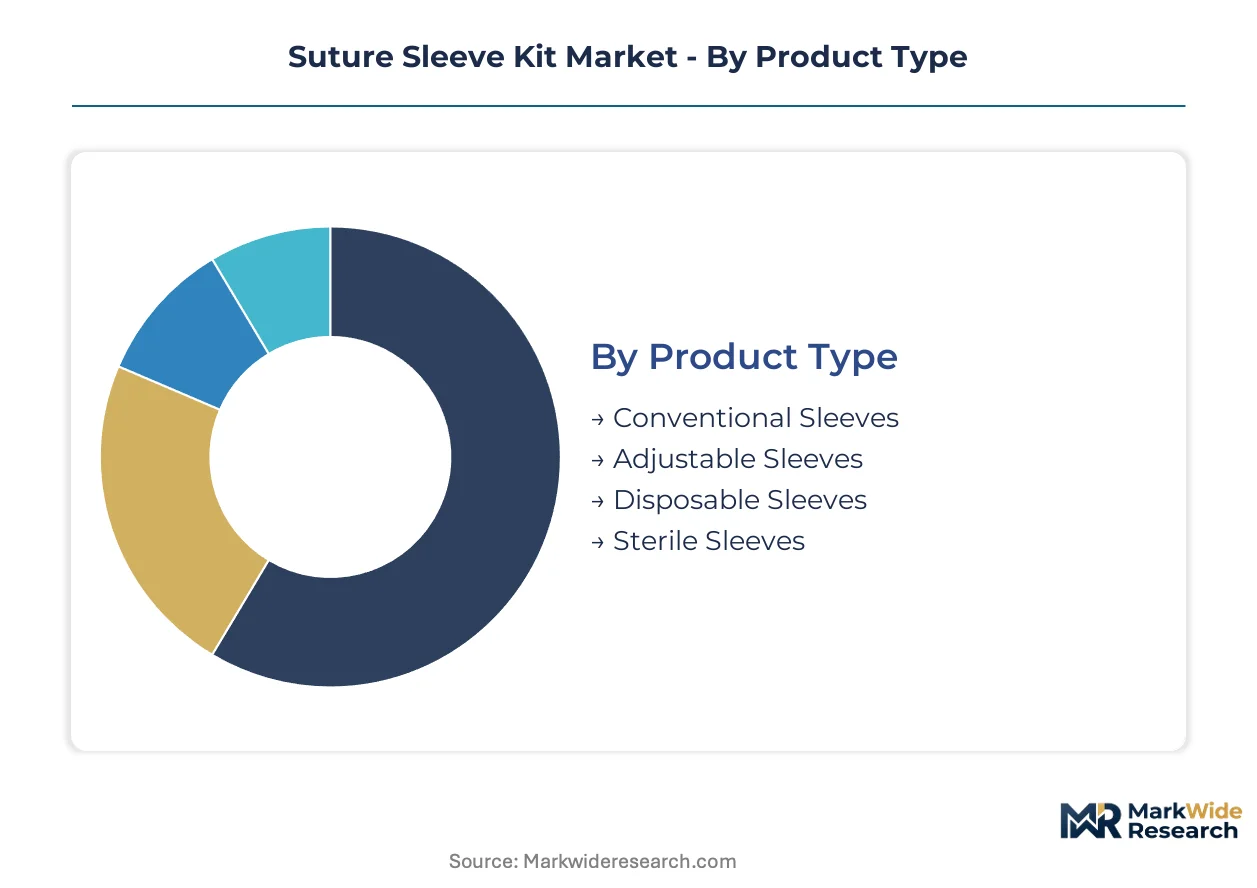
Segmentation in suture sleeve kits determines which regulatory pathways manufacturers must navigate and which procurement channels they can access. Material composition and sterilization status dictate FDA 510(k) classification tiers, while end-user type shapes pricing architecture and distribution strategy.
Product Type:
FDA 510(k) requirements vary sharply across this category, with sterile and disposable configurations demanding more extensive validation dossiers than reusable alternatives.
- Conventional Sleeves:Fixed-diameter silicone or polyethylene constructions dominate hospital purchasing volumes through established clinician familiarity. United States integrated delivery networks standardize procurement around these configurations due to predictable reimbursement coding and lower per-unit cost structures.
- Adjustable Sleeves:Ratcheting or sliding mechanisms enable dynamic lead tension control during catheter-based implant procedures. Minimally invasive techniques in cardiac rhythm management are accelerating demand as electrophysiologists require finer intraoperative adjustability.
- Disposable Sleeves:Single-use configurations eliminate reprocessing validation burdens for ambulatory surgical centers. These products carry gamma sterilization costs that compress margins unless volume scales justify dedicated production lines.
- Sterile Sleeves:Terminal sterilization with cobalt-60 or electron beam irradiation meets ISO 11137 standards for implantable device accessories. Japanese PMDA import protocols impose additional biocompatibility documentation that extends registration timelines for foreign suppliers.
Conventional sleeves sit at the top of the volume ranking, with adjustable sleeves climbing the fastest.
Application:
Reimbursement pathway complexity separates high-margin hospital segments from cost-sensitive outpatient channels.
- Wound Closure:Suture securement in soft tissue applications outside cardiac implantation. Demand concentrates in general surgery wards where lead management protocols from electrophysiology have limited direct transferability.
- Surgical Procedures:Cardiac rhythm management device implantation represents the core revenue pool, with structural heart procedures driving bundled procurement contracts. United States hospital committees negotiate master agreements that lock in accessory pricing across multi-year terms.
- Cosmetic Surgery:Aesthetic applications require smaller-diameter configurations with enhanced flexibility profiles. These products compete on material feel and cosmetic outcomes rather than biocompatibility certification depth.
- Trauma Treatment:Emergency settings prioritize rapid deployment and universal sizing over precision tension control. Polyethylene variants priced for single-use disposal dominate this channel.
Surgical procedures generate the steepest margin contribution, while trauma treatment expands most quickly in military and disaster-response procurement.
Material:
Supply chain geography and sterilization compatibility differentiate material tiers for multi-region manufacturers.
- Silicone:Medical-grade platinum-cured formulations meet ISO 10993 cytotoxicity and sensitization standards for long-term implantation. Costa Rica and Central American captive molding operations supply major cardiac device manufacturers with vertically integrated cost advantages.
- Polyethylene:Lower material cost and simplified sterilization validation enable aggressive pricing for ambulatory surgical center channels. These products bypass some biocompatibility testing tiers required for permanent implant-grade silicones.
- Latex:Natural rubber alternatives persist in cost-constrained markets despite allergen concerns. Regulatory pressure from FDA and EU ECHA is compressing approved indications.
- Non-Woven Fabric:Absorbable or semi-absorbable constructions for temporary securement applications. Limited overlap with permanent cardiac lead management protocols.
Silicone commands premium positioning in cardiac applications, with polyethylene gaining share fastest in outpatient settings.
End User:
Procurement authority concentration determines whether manufacturers sell through distributor networks or direct field teams.
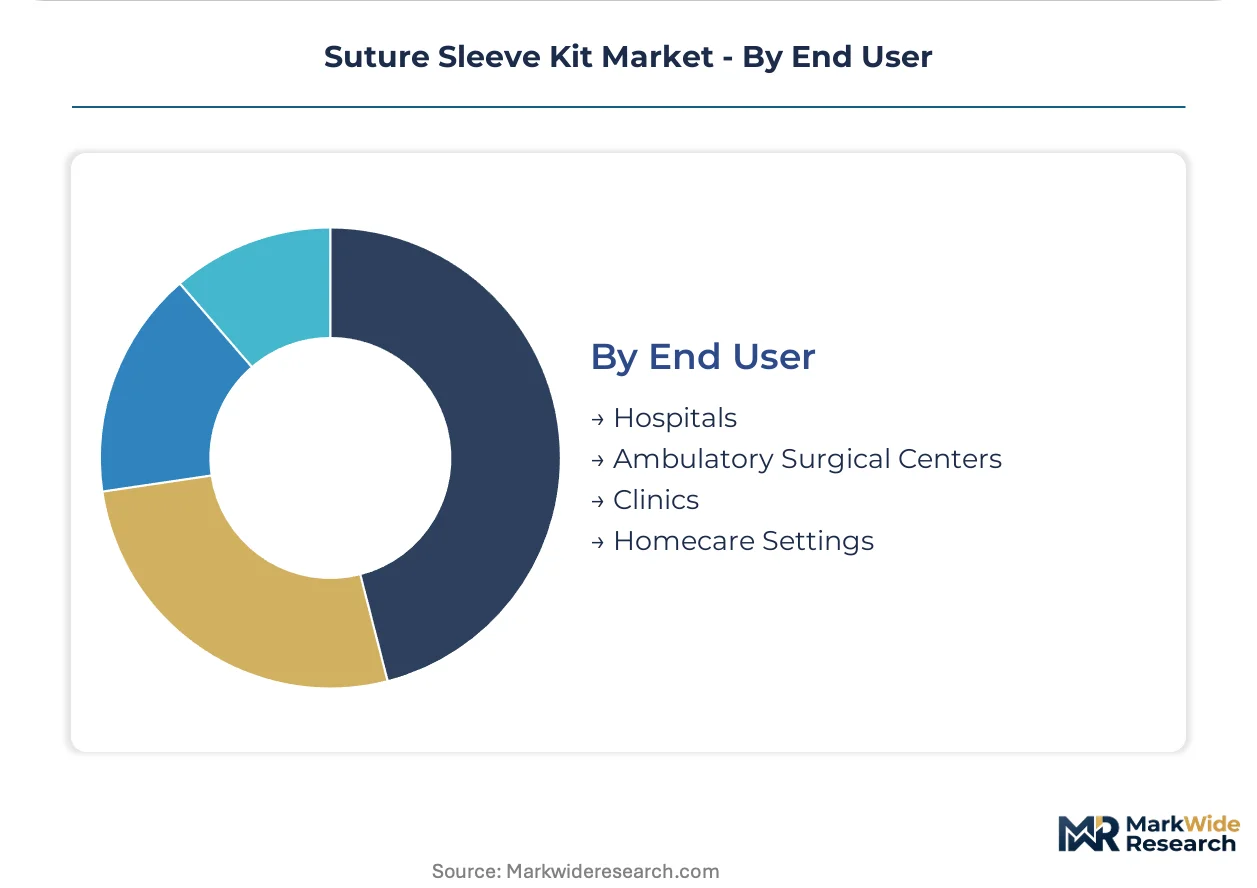
- Hospitals:Tertiary cardiac centers with electrophysiology labs drive specification standards through integrated delivery network contracting. Abbott and Medtronic field organizations negotiate comprehensive implant portfolios that bundle suture sleeves with lead and generator sales.
- Ambulatory Surgical Centers:Outpatient settings prioritize polyethylene variants and disposable configurations to minimize reprocessing overhead. These buyers respond to simplified pricing and rapid turnaround logistics.
- Clinics:Smaller-volume purchasers dependent on distributor relationships for inventory management. Limited direct manufacturer engagement due to transaction size thresholds.
- Homecare Settings:Emerging channel for post-acute wound management with suture securement needs. Regulatory classification uncertainty around sterile versus non-sterile requirements constrains product development investment.
Hospitals anchor current revenue concentration, with ambulatory surgical centers expanding most quickly as cardiac procedures migrate outpatient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophysiology specialists and cardiac device engineers concentrate in the United States, Germany, Japan, China, and Switzerland, anchoring regional demand patterns for suture sleeve kits.
United States
Integrated delivery networks in Texas and Florida drive procurement standardization for cardiac rhythm management accessories. FDA's tightened 510(k) validation requirements compress the vendor base and favor established regulatory dossier holders. Minneapolis and Boston field organizations negotiate bundled implant portfolios that lock in multi-year suture sleeve contracts.
Germany
Structural heart centers in Baden-Württemberg and Bavaria specify premium silicone configurations for precision lead tension control. EU MDR technical documentation requirements extend CE marking timelines and freeze new entrant pipelines. The Tübingen-Stuttgart medical technology cluster hosts sterilization validation facilities serving Central European kit assemblers.
Japan
PMDA biocompatibility documentation mandates for imported silicone components tighten cross-border supply chains. Tokyo and Osaka electrophysiology labs replicate cardiac lead securement protocols for emerging neuromodulation applications. Domestic sterilization partnerships in Kansai bypass import inspection friction for foreign manufacturers.
China
NMPA classification standards for cardiovascular accessories are harmonizing with ISO 10993 frameworks to accelerate multi-region dossier approvals. Shanghai and Beijing hospital procurement committees consolidate purchasing under structural heart device master agreements. Yangtze River Delta molding operations supply cost-sensitive polyethylene variants for ambulatory channels.
Switzerland
Swissmedic oversight of implantable device accessories maintains stringent biocompatibility certification depth for premium market positioning. Geneva and Zurich cardiac centers prioritize adjustable sleeve configurations for minimally invasive catheter-based procedures. The Basel-Zürich medtech corridor anchors European regulatory strategy for silicone-polyethylene hybrid formulations.
Suture Sleeve Kit Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Three structural archetypes dominate: integrated cardiac device manufacturers with captive accessory portfolios, independent component suppliers serving multiple OEMs, and regional sterilization service providers. Consolidation pressure from FDA validation tightening and EU MDR documentation burdens favors players with established regulatory dossiers and in-house gamma sterilization capabilities.
Among diversified medical technology conglomerates, Abbott, Medtronic, and Boston Scientific Corporation exemplify the integrated-manufacturer archetype. These entities occupy positions where structural heart and cardiac rhythm management portfolios bundle suture sleeves with lead and generator sales. Abbott anchors premium positioning through integrated delivery network contracting. Medtronic leverages Costa Rica-based molding operations for manufacturing scale. Boston Scientific navigates complex reimbursement pathways through specialized cardiac rhythm management accessory lines. Independent specialists and regional service providers sit within adjacent tiers, supplying non-integrated kit assemblers and ambulatory surgical center channels.
| Leading Market Players |
|---|
| NMS Co. Ltd |
| Medical Model Manufacture |
| Medic Trainer |
| FAUX Medical Canada |
| Strategic Operations Inc |
| OSCOR Inc |
| Abbott |
| Boston Scientific Corporation |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone spot price indices cascade through suture sleeve kit manufacturing tiers, compressing margins for non-vertically integrated assemblers while amplifying pricing power for captive molders in Costa Rica. This raw material cost pressure stratifies procurement economics across hospital networks and ambulatory surgical centers.
Pricing Analysis
Bundled implant portfolio contracts dominate hospital procurement, while standalone accessory pricing persists in ambulatory surgical center channels. Three-tier pricing structure across premium silicone, standard polyethylene, and economy latex configurations reflects ISO 10993 certification depth and sterilization validation burden. Cost compression in polyethylene tiers is intensifying because Yangtze River Delta molders are flooding outpatient channels with unbranded alternatives. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks anchored by Abbott and Medtronic field teams show lowest.
Supply Chain Analysis
Regional distribution centers in Minneapolis, Boston, and San Diego anchor hub-and-spoke patterns for United States hospital networks. Manufacturing gravity centers on Costa Rica, China, and Germany for silicone molding, polyethylene extrusion, and sterilization validation respectively. Raw material feeds draw from platinum-cured silicone suppliers in Wacker Chemie AG's German operations, medical-grade polyethylene from SABIC's Saudi facilities, and cobalt-60 isotopes from Nordion's Canadian irradiation sources. Single-source vulnerability concentrates in Central American captive molding operations. Distribution runs through GPO-aligned distributors for hospital systems and direct-to-ASC logistics for outpatient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The suture sleeve kit market represents a late-cycle quality story as adjustable sleeve specifications displace conventional configurations in minimally invasive cardiac procedures. This specification upgrade favors manufacturers with ISO 14155 clinical investigation capabilities and established regulatory dossiers.
For Market Incumbents: Anticipate FDA 510(k) validation tightening by consolidating sterilization partnerships and freezing distributor relationships with integrated delivery networks. Threat vectors include neuromodulation device manufacturers internalizing accessory supply and polyethylene variants eroding silicone premium tiers. Priority levers center on backward integration into gamma sterilization and Costa Rica capacity expansion. For New Entrants and Emerging Players: Launch via direct-to-ambulatory surgical center distribution models bypassing GPO contract lock-in. White-space targets include trauma treatment channels for military procurement and homecare settings with regulatory classification clarity. Most penetrable segment: polyethylene disposable sleeves in cost-sensitive outpatient settings. For Investors and Strategic Acquirers: Asymmetric upside sits with sterilization service providers possessing ISO 11137 validation and PMDA import pathway expertise. Long-term viability frames around 5-10 year regulatory dossier amortization windows. Acquisition target archetype: regional gamma sterilization facilities with cardiovascular accessory validation backlog clearance capacity. Signal to watch: EU MDR technical documentation approval velocity as new entrant pipeline unfreezing indicator.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR technical documentation capabilities unlock European hospital procurement access for adjustable sleeve configurations. |
| Hospital System Partnership | Integrated delivery network master agreements bundle suture sleeves with cardiac rhythm management device portfolios. |
| Gamma Sterilization Capacity Expansion | In-house cobalt-60 terminal sterilization compresses FDA 510(k) submission cycles and compliance economics. |
| Silicone-Polyethylene Hybrid Formulation Launch | Dual-property materials capture premium positioning in catheter-based electrophysiology procedures. |
| Neuromodulation Application Extension | Spinal cord and deep brain stimulation protocols replicate cardiac lead securement accessory demand. |
Research Methodology
Bottom-up electrophysiology procedure volume modeling reconciled against top-down cardiovascular accessory manufacturing tracking forms the analytical core. Primary interviews with cardiac device procurement managers, GPO contracts directors, biomedical engineers, and sterilization validation specialists combined with secondary validation against FDA 510(k) filings, CMS Medicare procedure databases, hospital procurement records, and ISO certification registries. Triangulation across bottom-up demand estimation and top-down supply verification ensures cross-referenced accuracy.
Historical trendline analysis of implantable device procedure volumes and accessory pricing trajectories informed projection frameworks. Segmentation dimensions modeled include product type, material composition, sterilization status, end-user channel, and regional regulatory cluster. CAGRs derive from weighted average growth across these dimensions calibrated to procedure migration patterns and procurement standardization trends. Industry-specific forecast inputs incorporate PMDA import inspection protocol changes and EU MDR technical documentation approval timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA 510(k) validation rule changes or medical-grade silicone supply disruptions. Forecasts reflect assumptions about procedural technique evolution and regulatory harmonization velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Arthroscopy Fluid Management Disposables Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
US Hospital Gowns Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Lavage Kits Market
Medical Supplies
North America Insulin Syringe Market
Medical Supplies
Veterinary Syringes Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Surgical Sealant and Adhesive Market
Medical Supplies
Global Swab Market
Medical Supplies
Medical Instruments Disinfection Market