
 Global Veterinary Hematology Analyzers Market | 2026-2036
Global Veterinary Hematology Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Hematology Analyzers Market Foresight
Multi-source component procurement is decoupling from legacy single-vendor service contracts across the veterinary diagnostics supply base. IDEXX Laboratories leverages captive reagent production to lock in recurring revenue streams. Zoetis anchors its position through deep channel partnerships with corporate veterinary groups. Heska Corporation differentiates by bundling instruments with cloud-based practice management software.
Veterinary hematology analyzers are automated or semi-automated diagnostic instruments that quantify blood cell populations in animal samples using impedance, optical, or flow cytometric methods, typically processing 20-100 samples per hour with species-specific calibration matrices. Their primary purpose is enabling rapid clinical decision-making in veterinary settings where species-specific reference ranges differ substantially from human medicine. Automated hematology analyzers command the largest installed base due to throughput advantages in high-volume practices, while laser-based systems represent the fastest-expanding category as veterinary reference laboratories adopt human-diagnostic precision standards. The application split favors veterinary clinics for instrument placement volume, though diagnostic laboratories concentrate the highest-margin reagent pull-through.
The FDA's Center for Veterinary Medicine regulates analyzer safety and efficacy claims for US commercialization, while the EU IVDR reclassification has elevated clinical evidence requirements for in-vitro diagnostic devices including veterinary hematology systems. Japan's PMDA maintains distinct pharmaceutical and medical device approval tracks that importers must navigate for market access. Stakeholders must monitor how regional regulatory divergence affects instrument certification costs and reagent registration timelines.
Market Dynamics
The veterinary hematology analyzer sector is experiencing structural pressure from the EU IVDR reclassification, which has elevated clinical evidence requirements and forced manufacturers to rebuild certification dossiers for instruments previously cleared under lighter directives.
Growth Catalysts
- Companion Animal Diagnostics:Pet insurance penetration in the United States and Germany is accelerating routine bloodwork frequency in small animal practices, expanding instrument placement volume.
- EU IVDR Framework:The tightened quality standards for in-vitro diagnostic devices are filtering substandard equipment from the European market, consolidating demand around compliant suppliers.
- Laser-Based Flow Cytometry:Veterinary reference laboratories are adopting optical detection methods that deliver human-diagnostic precision standards for species-specific cellular analysis.
Market Restraints
- Reagent Cost Volatility:Proprietary consumables for closed-system analyzers create recurring cost burdens that independent clinics struggle to absorb amid reimbursement compression.
- Regulatory Divergence:Japan's PMDA maintains distinct pharmaceutical and medical device approval tracks that extend market access timelines for importers unfamiliar with dual-track navigation.
- Technical Limitation:Species-specific calibration matrices require continuous algorithm updates, limiting the utility of human-diagnostic platforms in veterinary settings without substantial re-engineering.
Strategic Opportunities
- Cloud-Integrated Practice Management:Bundling hematology instruments with software platforms creates sticky revenue relationships with corporate veterinary groups seeking operational standardization.
- Point-of-Care Expansion:Brazil's underpenetrated companion animal sector presents first-mover advantages for portable analyzer manufacturers targeting emerging middle-class pet ownership.
- Livestock Biosecurity Mandates:Japan's national disease surveillance programs are mandating on-farm diagnostic capabilities, opening instrument demand in production animal segments previously served by centralized laboratories.
Industry Challenges
- Cross-Species Algorithm Development:Veterinary hematology requires species-specific reference range databases that demand extensive validation cohorts across exotic, companion, and production animals.
- Legacy System Integration:Cloud-based analyzers face interoperability friction with practice management software architectures prevalent in established clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Hematology Analyzers Market |
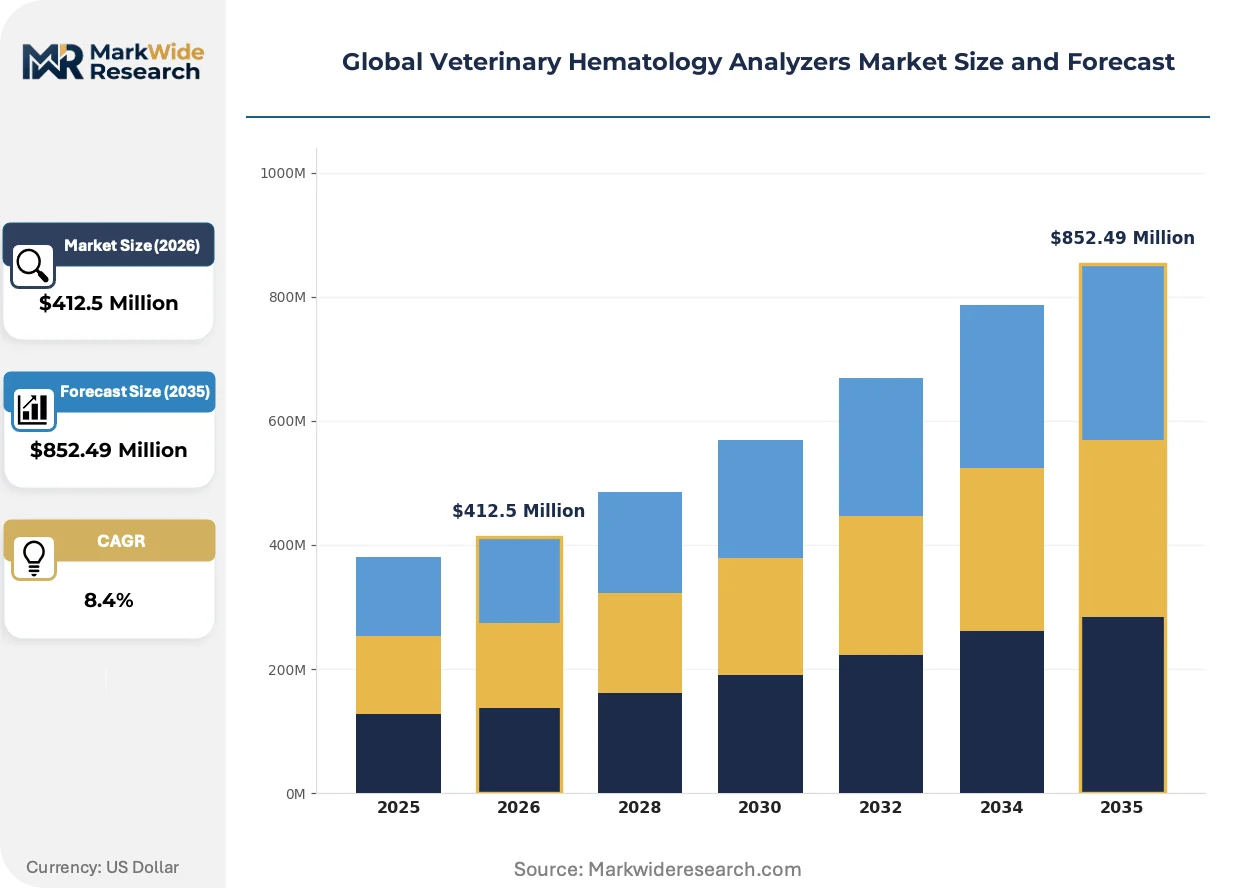
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
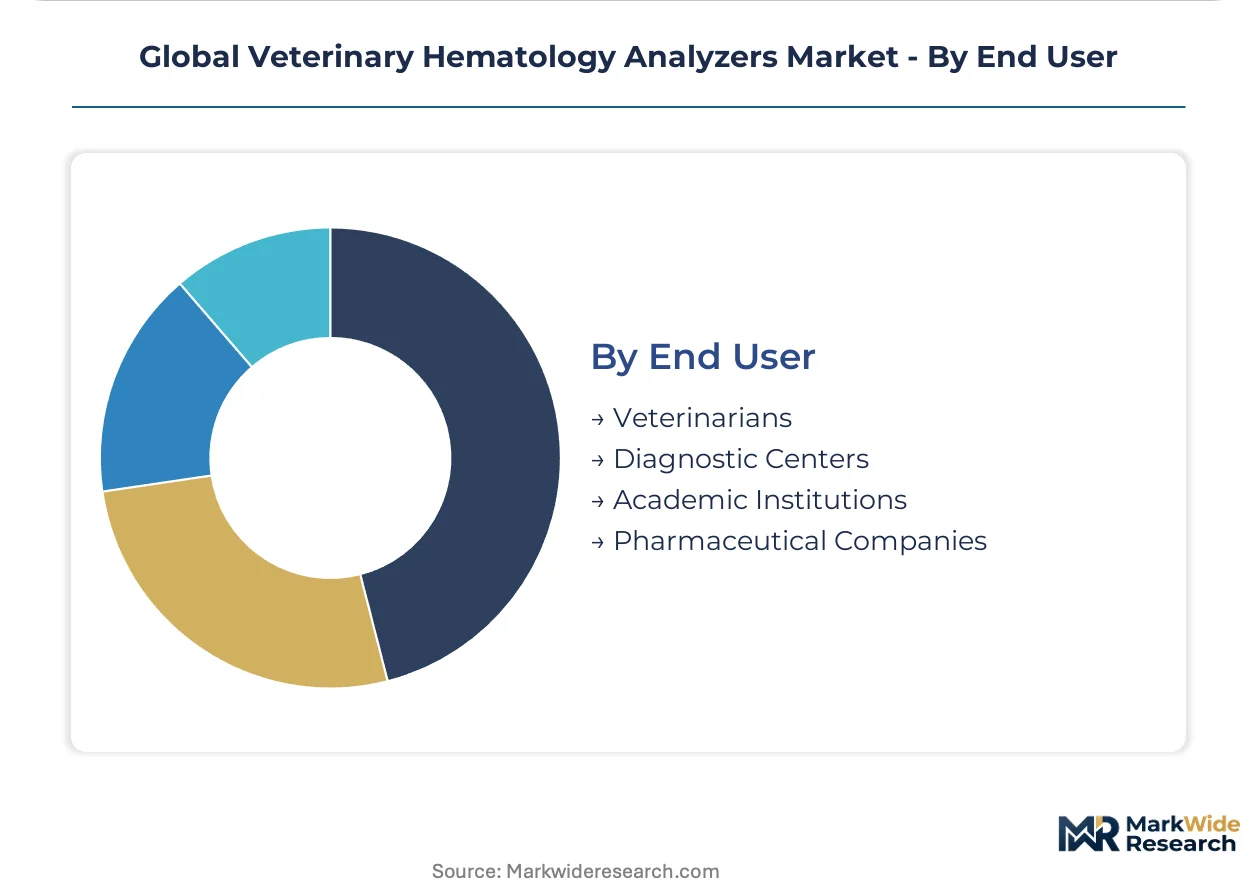
| Segmentation | Product Type: Manual Hematology Analyzers, Automated Hematology Analyzers, Laser-Based Hematology Analyzers, Fluorescence Hematology Analyzers Technology: Impedance Technology, Flow Cytometry, Spectrophotometry, Digital Imaging, Optical Cytometry Application: Veterinary Clinics, Animal Research Centers, Livestock Health Monitoring, Zoos, Diagnostic Laboratories End User: Veterinarians, Diagnostic Centers, Academic Institutions, Pharmaceutical Companies |
| Companies Covered | IDEXX Laboratories, Inc., Zoetis Inc., Heska Corporation, HORIBA Medical, Mindray, Boule Medical AB, Sysmex Corporation, scil animal care, Drew Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Hematology Analyzers Market Shifts & Advancements
Diagnostic precision standards are migrating from human medicine into veterinary practice, compressing the performance gap between species-specific and human-adapted platforms while reshaping procurement criteria across clinic networks.
Artificial intelligence-assisted cell classification is unifying morphological assessment with automated enumeration in next-generation analyzers. High-volume reference laboratories in Germany and the United States are piloting these systems to reduce manual differential review. The technology is unifying diagnostic workflows that previously required separate manual microscopy steps, compressing turnaround times for complex cases.
The EU IVDR reclassification has recast veterinary hematology systems as Class B or C devices requiring notified body intervention. Manufacturers serving European markets must now submit clinical performance studies that were unnecessary under the prior IVD directive. Small instrument producers without dedicated regulatory affairs functions are exiting the region rather than absorbing compliance costs.
Corporate veterinary groups are consolidating instrument purchasing decisions at the network level, displacing the practice-level autonomy that historically drove fragmented procurement. Independent distributors in the United States are losing access to high-volume accounts as IDEXX and Zoetis establish direct service relationships with national clinic chains. This concentration is most visible in metropolitan markets where corporate ownership exceeds sixty percent of small animal capacity.
Global Veterinary Hematology Analyzers Market Segmentation

Veterinary hematology analyzers segment across multiple dimensions that determine instrument specification, regulatory pathway, and service intensity. Product architecture and detection technology define capital requirements, while application setting shapes throughput needs and software integration demands.
Product Type:
The customization-to-standardization spectrum runs from technician-dependent manual systems to fully automated platforms with locked reagent protocols.
- Automated Hematology Analyzers:These platforms process 20-100 samples per hour with minimal operator intervention using impedance or optical counting methods. Demand concentrates in high-volume veterinary clinics across the United States and Germany where pet insurance penetration drives routine bloodwork frequency.
- Laser-Based Hematology Analyzers:Flow cytometric detection delivers human-diagnostic precision standards for species-specific cellular analysis. Veterinary reference laboratories in Japan and Germany are adopting these systems to reduce manual differential review and compress turnaround times for complex cases.
- Manual Hematology Analyzers:Basic counting chambers and centrifugation systems requiring trained technician operation.
- Fluorescence Hematology Analyzers:Specialized platforms using fluorescent dyes for reticulocyte enumeration and platelet activation studies.
Most installed capacity flows through Automated Hematology Analyzers. Expansion is steepest in Laser-Based Hematology Analyzers.
Technology:
Detection methodology determines sensitivity thresholds and the breadth of species-specific algorithms each platform can support.
- Impedance Technology:Coulter principle-based counting measures electrical resistance changes as cells pass through an aperture. This mature technology dominates installed bases in price-sensitive markets and production animal diagnostics where basic CBC parameters suffice.
- Flow Cytometry:Laser-based optical detection captures light scatter and fluorescence signals for multi-parameter cellular analysis. Reference laboratories in the United States and Germany are piloting AI-assisted classification modules that unify morphological assessment with automated enumeration.
- Spectrophotometry:Absorbance-based hemoglobinometry and plasma protein quantification.
- Digital Imaging:Automated microscopy with computational cell recognition.
- Optical Cytometry:Combined light scatter and absorbance detection without fluidics.
Impedance Technology carries the largest legacy installed base. Flow Cytometry is climbing the fastest as precision standards migrate from human diagnostics.
Application:
Setting determines throughput requirements, species mix, and the depth of practice management software integration needed.
- Veterinary Clinics:Point-of-care placement in small animal and mixed practices demands compact footprints and rapid turnaround. Corporate veterinary groups in the United States are consolidating purchasing decisions at the network level, favoring platforms with cloud-based practice management bundling.
- Diagnostic Laboratories:Centralized reference facilities process high sample volumes across multiple species with standardized quality protocols. These facilities concentrate the highest-margin reagent pull-through and drive adoption of laser-based precision systems.
- Animal Research Centers:GLP-compliant environments requiring audit trails and validation documentation.
- Livestock Health Monitoring:On-farm and centralized testing for production animal biosecurity programs.
- Zoos:Exotic species diagnostics requiring extensive custom algorithm development.
Veterinary Clinics account for the greatest instrument placement volume. Diagnostic Laboratories are expanding most quickly as corporate consolidation shifts testing away from in-house platforms.
End User:
Procurement authority and technical sophistication vary sharply across user categories, shaping sales channel strategy and service contract structure.
- Veterinarians:Licensed practitioners in private practice or corporate employment make placement decisions based on patient volume, species focus, and reimbursement economics. The FDA's Center for Veterinary Medicine regulates analyzer safety claims for US commercialization, while the EU IVDR reclassification has elevated clinical evidence requirements.
- Diagnostic Centers:Independent reference laboratories and hospital-affiliated pathology services prioritize throughput and multi-species capability.
- Academic Institutions:Veterinary schools and research universities requiring teaching platforms and research-grade precision.
- Pharmaceutical Companies:Preclinical toxicology and field trial support with stringent validation requirements.
Veterinarians represent the largest addressable user base. Diagnostic Centers are gaining share fastest as testing consolidates away from individual practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates the largest installed base of veterinary hematology analyzers, with corporate clinic networks driving standardization toward automated platforms with cloud connectivity.
United States
Pet insurance penetration exceeding thirty percent in metropolitan markets accelerates routine bloodwork frequency across small animal practices. The FDA's Center for Veterinary Medicine maintains distinct approval tracks for diagnostic devices, requiring clinical validation studies for new analyzer platforms. Corporate veterinary groups in California, Texas, and Florida are consolidating purchasing decisions at network headquarters, displacing independent distributor relationships.
Germany
Reference laboratories in Bavaria and North Rhine-Westphalia are adopting laser-based flow cytometry systems to meet human-diagnostic precision standards. The EU IVDR reclassification has elevated clinical evidence requirements, filtering substandard equipment from the European market. Munich and Berlin host the continent's densest concentration of veterinary diagnostic service providers, with corporate groups standardizing on multi-parameter cellular analysis platforms.
Japan
National livestock biosecurity mandates are expanding on-farm diagnostic capabilities beyond traditional centralized laboratory models. The PMDA maintains dual pharmaceutical and medical device approval tracks that extend market access timelines for unfamiliar importers. Tokyo and Osaka veterinary medical centers are piloting AI-assisted cell classification modules to reduce manual differential review.
Brazil
Emerging middle-class pet ownership in São Paulo and Rio de Janeiro is creating first-mover opportunities for portable analyzer manufacturers. ANVISA regulates in-vitro diagnostic devices under consolidated health surveillance frameworks that harmonize with Mercosur technical standards. São Paulo's corporate veterinary chains are replicating US procurement consolidation patterns, favoring bundled instrument-software platforms.
United Kingdom
Post-Brexit regulatory divergence from EU IVDR frameworks is creating parallel certification requirements for manufacturers serving British markets. The Veterinary Medicines Directorate coordinates with MHRA on diagnostic device oversight, maintaining CE marking recognition while developing UKCA transition pathways. London and Southeast England concentrate the highest diagnostic laboratory density, with reference facilities adopting optical detection methods for species-specific cellular analysis.
Global Veterinary Hematology Analyzers Market Competitive Landscape
Global majors compete with regional champions across reagent supply and service infrastructure, producing a tiered structure where scale-driven players anchor high-volume accounts while specialists occupy niche species segments. The vendor base clusters around three strategic archetypes: integrated diagnostics conglomerates with captive reagent production, instrument-focused manufacturers bundling software platforms, and regional service providers with deep technical support networks. Dominant competitive moves include vertical integration into consumables manufacturing and direct channel establishment with consolidated corporate veterinary groups.
Within the integrated diagnostics tier, IDEXX Laboratories and Zoetis exemplify scale-driven positioning through locked reagent protocols and direct corporate account relationships. Heska Corporation occupies a distinct position bundling instruments with cloud-based practice management software, targeting operational standardization demands from multi-site clinic networks. Sysmex Corporation and HORIBA Medical represent precision-oriented Japanese and French industrial champions respectively, with HORIBA Medical anchoring European reference laboratory adoption of optical detection platforms.
| Leading Market Players |
|---|
| IDEXX Laboratories, Inc. |
| Zoetis Inc. |
| Heska Corporation |
| HORIBA Medical |
| Mindray |
| Boule Medical AB |
| Sysmex Corporation |
| scil animal care |
| Drew Scientific Inc. |
| Others |
Supply & Pricing Matrix
Laser-based precision tiers command substantial premiums over impedance-based platforms, with this performance bifurcation creating parallel supply chains: captive reagent ecosystems for closed-system analyzers versus open-architecture consumables for price-sensitive clinics. The divergence concentrates margin capture among integrated diagnostics conglomerates while fragmenting procurement authority across independent veterinary practices.
Pricing Analysis
Input-cost pass-through from proprietary reagent manufacturing anchors pricing power for closed-system vendors. Pricing stratifies across premium laser-based, standard automated, and economy manual tiers, with differentiation driven by optical detection capability and EU IVDR certification status. Cost compression in the economy tier is intensifying because Brazilian and Indian clinics resist subscription bundling. Independent small-animal practices exhibit highest price sensitivity, while corporate veterinary groups absorb premium pricing for cloud-integrated platforms.
Supply Chain Analysis
Direct-to-corporate channels handle high-volume instrument placements, while independent distributors serve fragmented clinic networks. Component manufacturing concentrates in Germany, Japan, and the United States, with precision optical assemblies drawing from Japanese industrial champions and fluidics systems resting on German engineering. Laser diodes, specialized reagents, and species-specific calibration matrices constitute critical input dependencies. Single-source vulnerability in laser diode supply creates exposure to export control restrictions. Distribution runs through manufacturer-direct service arms for corporate accounts and regional distributors for independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in reagent pull-through optimization and premium-tier consolidation, with cloud-integrated platforms capturing pricing power from operational standardization mandates across corporate clinic networks.
For Market Incumbents: Lock in recurring revenue through captive reagent protocols that resist third-party consumable substitution. Deepen direct service relationships with consolidated corporate veterinary groups to displace independent distributor access. The threat of AI-assisted cell classification modules from human-diagnostics specialists demands accelerated R&D investment in species-specific algorithm development. Channel control represents the priority defensive lever. For New Entrants and Emerging Players: The price-point gap between premium laser-based systems and economy manual analyzers creates white-space opportunity for mid-tier automated platforms with modular software integration. Brazil's underpenetrated companion animal sector offers the most penetrable geography, with São Paulo corporate chains replicating US procurement consolidation patterns. A go-to-market angle bundling portable hardware with ANVISA-compliant reagent supply contracts bypasses incumbent service infrastructure advantages. For Investors and Strategic Acquirers: Asymmetric upside sits with regional service providers possessing deep technical support networks and exotic species algorithm libraries. Long-term viability hinges on regulatory compliance capabilities across FDA, EU IVDR, and PMDA frameworks as certification costs filter subscale competitors. Acquisition targets should demonstrate installed base density in underconsolidated markets. The signal to watch is corporate veterinary group purchasing decision centralization accelerating beyond metropolitan saturation thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Practice Management Integration | Heska Corporation's bundling approach creates sticky revenue relationships with multi-site clinic networks seeking operational standardization. |
| EU IVDR Certification Investment | Elevated clinical evidence requirements filter substandard equipment from European markets, consolidating demand around compliant suppliers. |
| Direct Corporate Account Establishment | IDEXX and Zoetis bypass independent distributors to capture high-volume accounts as corporate ownership exceeds sixty percent of small animal capacity. |
| AI-Assisted Cell Classification Development | German and US reference laboratories pilot unified morphological assessment to compress turnaround times for complex cases. |
| Emerging Market Portable Platform Launch | Brazil's ANVISA framework harmonizes with Mercosur standards, enabling first-mover positioning in underpenetrated middle-class pet ownership segments. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing demand calibration. The approach combines structured interviews with veterinary practice managers, diagnostic laboratory directors, regulatory affairs specialists at device manufacturers, and procurement leads at corporate clinic groups with secondary validation. Secondary sources include FDA Center for Veterinary Medicine filings, EU IVDR notified body documentation, PMDA approval track records, and veterinary trade association procurement surveys. Bottom-up instrument placement estimates triangulate against top-down market value reconstruction.
Rate-of-change decomposition separates volume expansion from mix-shift and pricing components across the projection horizon. The analytical framework models segmentation across product architecture, detection technology, application setting, and end-user procurement authority. Species-specific algorithm development intensity and cloud-software bundling penetration constitute veterinary-specific forecast inputs. CAGRs derive from fitted growth curves anchored to observable placement trajectories in comparable diagnostic device categories.
Caveats apply where regulatory divergence between FDA, EU IVDR, and PMDA frameworks could materially shift the outlook for multi-regional vendors. Forecasts reflect assumptions regarding pet insurance penetration trajectories, corporate clinic consolidation velocity, and reagent cost pass-through elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Global Veterinary Drugs Market
Veterinary
Veterinary and Animal Healthcare Logistics Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Veterinary Ultrasound Market
Veterinary
OTC Cat Medicines Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
Global Livestock Vaccines Market
Veterinary
Otc Pet Medication Market
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
US Surgical Pet Collar Market
Veterinary
Veterinary Antibiotics Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Animal Microchip Implant Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Veterinary Immunodiagnostics Market