
 Bile Collection Bags Market | 2026-2036
Bile Collection Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Bile Collection Bags Market Outlook
Asset-light leasing and third-party sterilization service contracts are fragmenting capital deployment across the bile collection bags supply chain. Fresenius Medical Care AG & Co. leverages its dialysis-centric logistics network to extend into post-surgical drainage logistics. B. Braun Melsungen AG anchors German-speaking European markets through captive polymer compounding and in-house extrusion of medical-grade PVC. Cook Medical competes on procedural specialization, sustaining deep catalog penetration in interventional gastroenterology suites across North American academic medical centers.
Bile collection bags are closed drainage receptacles, typically fabricated from medical-grade PVC or silicone with graduated volume markings and anti-reflux valves, designed to receive and quantify biliary fluid output following hepatobiliary surgery or percutaneous drainage catheter placement. The product category serves a critical infection-control function by maintaining sterile isolation between patient and external environment. Single-use configurations dominate hospital procurement due to cross-contamination protocols, while silicone material grades command premium positioning in long-term indwelling applications where biocompatibility tolerance limits determine dwell time. Home care end-user channels are expanding fastest as ambulatory surgery and early discharge protocols shift monitoring responsibility to patients and visiting nurses.
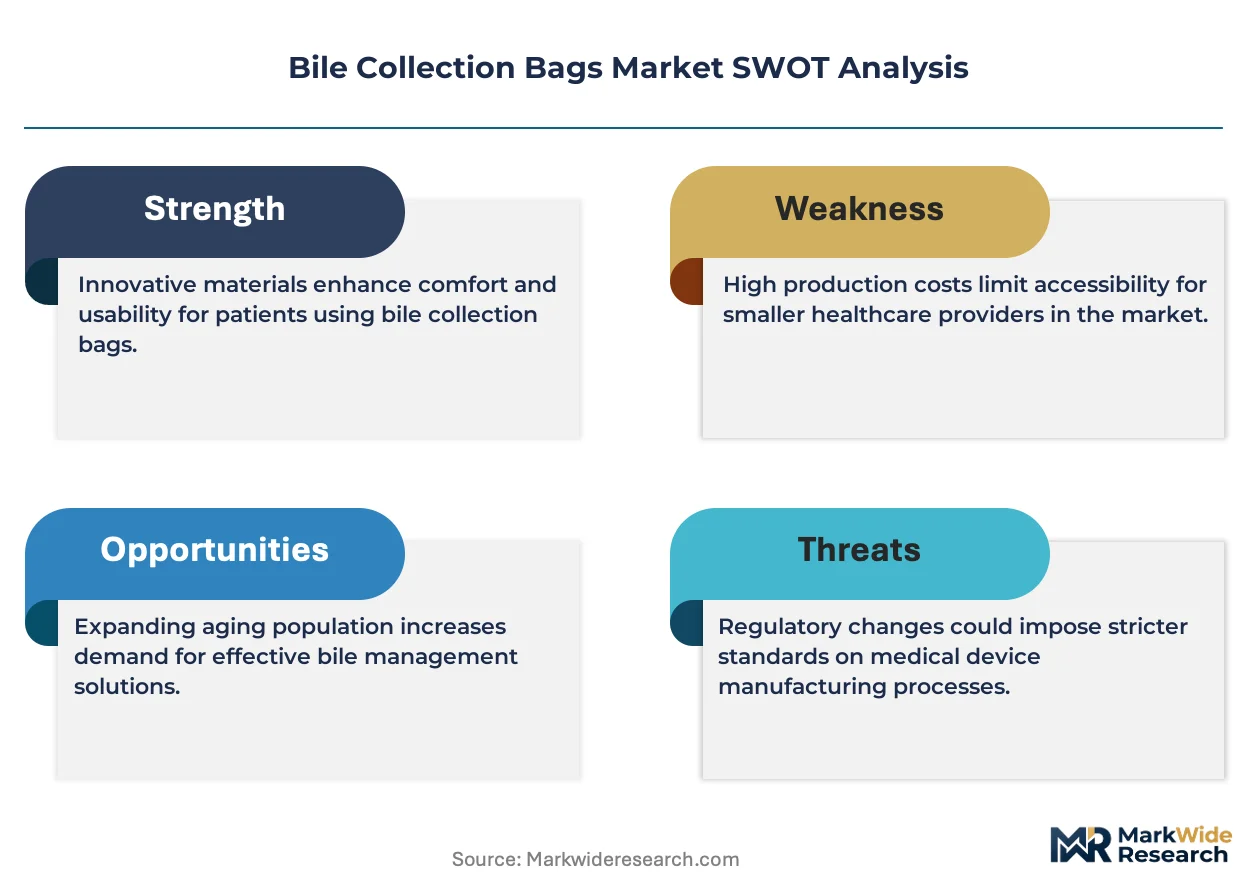
FDA 510(k) clearance pathways and ISO 13485 quality management requirements govern market access for manufacturers targeting the United States, while EMA-coordinated Medical Device Regulation (MDR) conformity assessments reshape European competitive thresholds through enhanced clinical evidence demands. Japan's PMDA enforces JIS T 0601 electrical safety and biocompatibility testing standards that add certification layers for imported drainage systems. Stakeholders must monitor how evolving sterile barrier testing protocols and single-use plastics reduction mandates in multiple jurisdictions will recalibrate material selection and end-of-life disposal economics across their product portfolios.
Market Dynamics
Post-operative ambulatory discharge protocols are compressing inpatient monitoring windows and forcing manufacturers to redesign bile collection bags for patient-managed home settings without sacrificing sterile isolation integrity.
Growth Catalysts
- Early discharge mandates:Medicare bundled payment models in the United States penalize extended hospital stays and accelerate procurement of closed drainage systems suitable for home nursing oversight.
- ISO 13485 certification expansion:Quality management standardization across Eastern European manufacturing hubs is unlocking EU MDR-compliant supply capacity for Western European hospital networks.
- Silicone biocompatibility advances:Extended indwelling durations enabled by improved medical-grade silicone formulations are opening long-term palliative care applications previously served by percutaneous alternatives.
Market Restraints
- Medical-grade PVC feedstock volatility:Petrochemical input costs and EU REACH authorization burdens for plasticizer compounds are squeezing margin structures for standard-grade product lines.
- Sterilization service concentration:Third-party gamma and ethylene oxide sterilization capacity clusters in Germany and the United States create geographic bottlenecks for just-in-time hospital replenishment.
- Catheter-based drainage substitution:Percutaneous transhepatic biliary drainage systems with integrated external collection are capturing select high-acuity cases in interventional radiology suites.
Strategic Opportunities
- Japanese home care infrastructure:METI-funded aging-in-place initiatives and PMDA streamlined Class II reviews are creating entry pathways for closed drainage systems designed for patient self-management.
- Biodegradable polymer convergence:Integration of polylactic acid blends with existing extrusion equipment addresses emerging single-use plastics reduction mandates in France and Italy.
- Telehealth-integrated volume monitoring:Bluetooth-enabled graduated markings paired with remote nursing platforms serve early discharge protocols in North American accountable care organizations.
Industry Challenges
- ISO 10993 biocompatibility testing timelines:Extended cytotoxicity and sensitization study durations for novel silicone formulations delay product launches by 12-18 months.
- Legacy hospital inventory system integration:Barcode and RFID compatibility requirements for automated supply chain management in tertiary hospitals demand redundant SKU configurations.
- Ethylene oxide sterilization residue compliance:Tightening EPA ambient air standards and residual gas limits are forcing capital-intensive facility upgrades or supplier switches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bile Collection Bags Market |
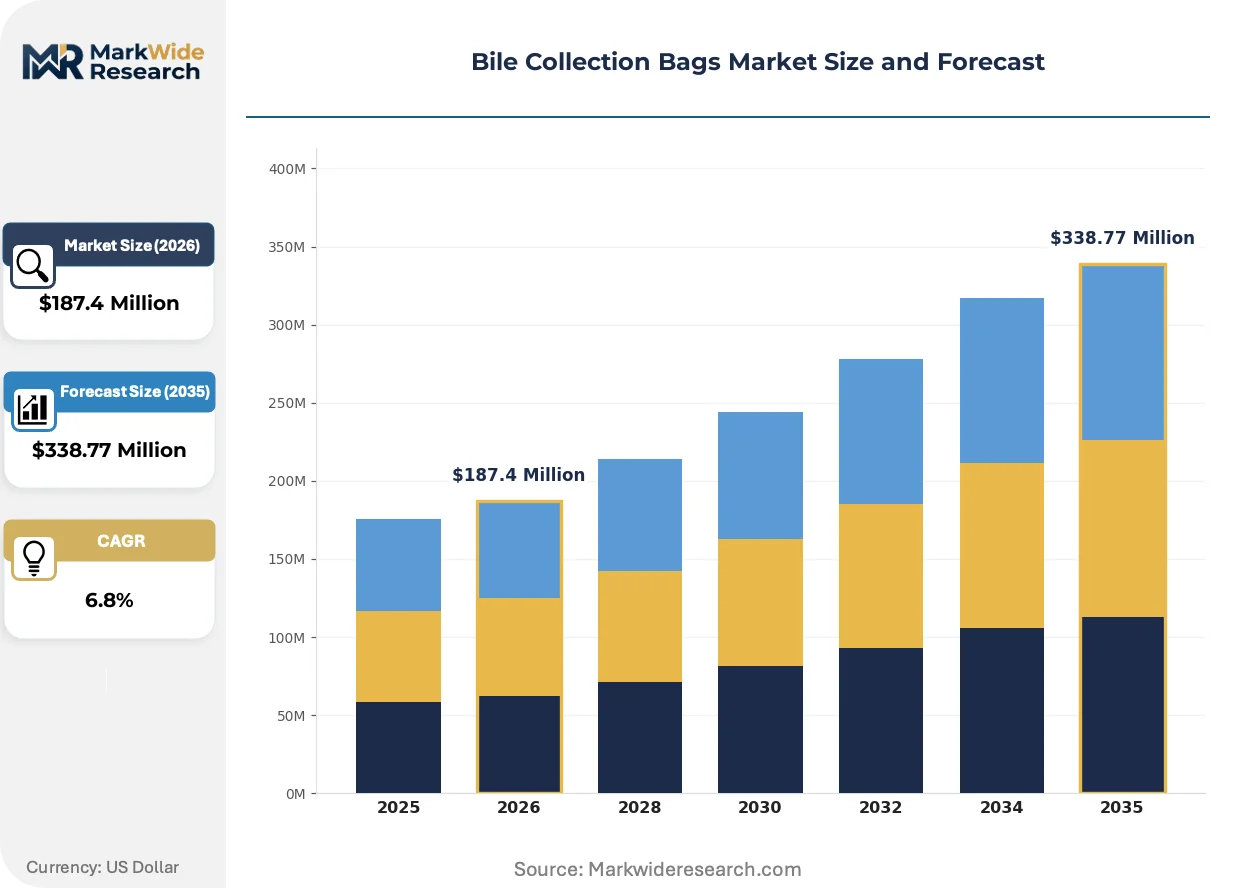
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use, Reusable, Sterile, Non-sterile Material: Polyethylene, PVC, Silicone, Rubber End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Application: Post-operative Care, Liver Disease Treatment, Palliative Care, Gastroenterology |
| Companies Covered | Medline Industries, Inc., C. R. Bard, Inc., Fresenius Medical Care AG & Co., Redax, B. Braun Melsungen AG, Hollister Incorporated, Cook Medical, Teleflex Incorporated, ConvaTec Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bile Collection Bags Market Strategic Shifts
Material science breakthroughs and regulatory recalibration of sterile barrier standards are simultaneously enabling product differentiation and compressing compliance timelines for new market entrants.
Anti-reflux valve mechanisms employing silicone membrane technology are collapsing the performance gap between premium long-dwell and standard acute-care configurations. Academic medical centers in Germany and Japan are piloting these unified designs to reduce SKU complexity and sterilization validation overhead. The consolidation is eliminating tiered pricing architectures previously justified by dwell-time segmentation.
EU MDR Annex I general safety and performance requirements are mandating enhanced clinical evidence for closed drainage systems previously cleared under passive equivalence pathways. Notified bodies in Germany and the Netherlands are demanding biocompatibility data packages that exceed legacy MEDDEV guidance. Mid-sized manufacturers without captive clinical affairs teams are outsourcing post-market surveillance to specialized CROs in Ireland and Switzerland.
Hospital procurement departments are unbundling after-sales technical support from device pricing and negotiating standalone service agreements with third-party sterilization logistics providers. GPOs in the United States are consolidating vendor panels and demanding real-time inventory visibility through EDI integration. The shift is most pronounced in multi-hospital systems across Texas and Florida where centralized supply chain control rooms manage distributed drainage kit replenishment.
Bile Collection Bags Market Segmentation
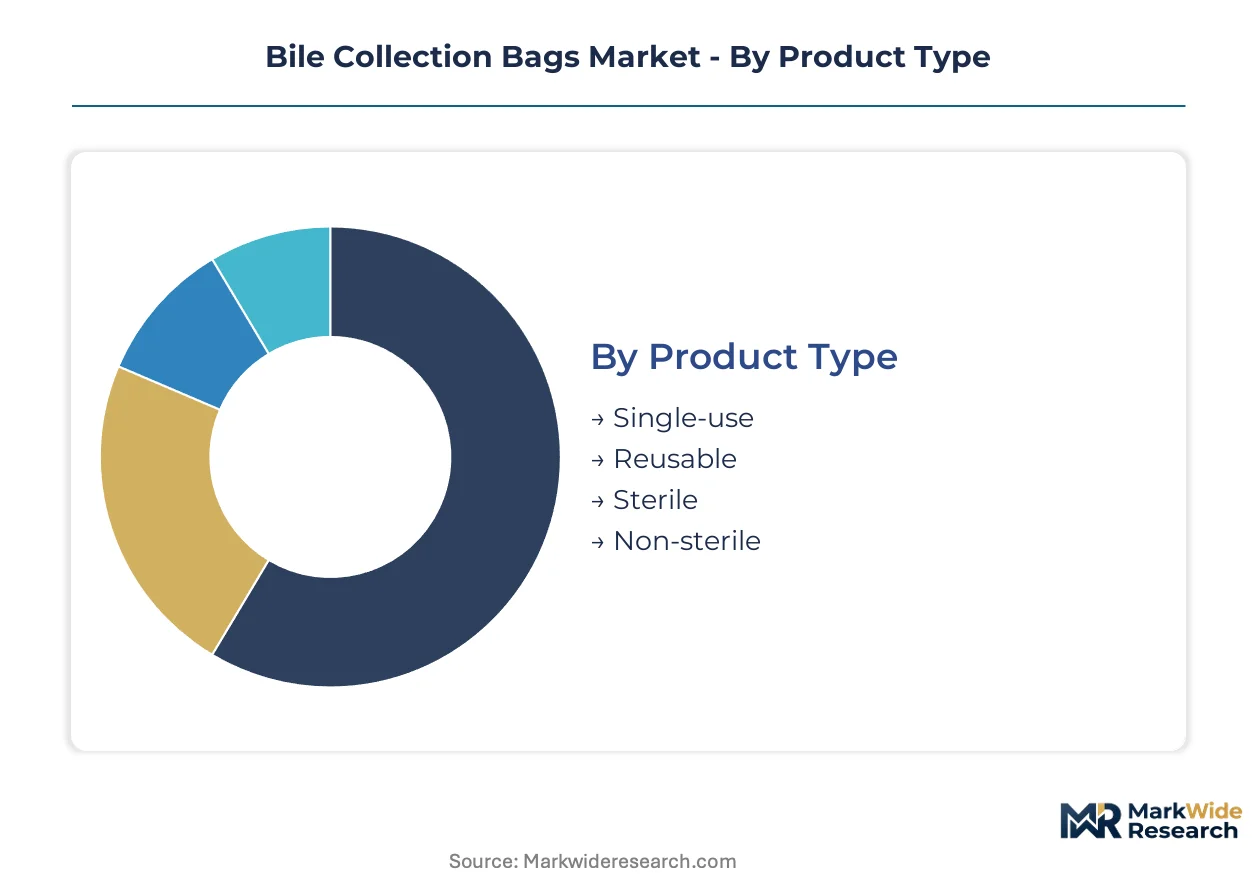
Segmentation in bile collection bags reflects divergent clinical workflows across acute, ambulatory, and home-based settings. Material selection and sterility classification determine reimbursement eligibility and procurement channel access.
Product Type:
Cost tier stratification separates single-patient disposable units from capital-intensive reusable systems with reprocessing infrastructure requirements.
- Single-use:Medical-grade PVC or silicone configurations with integrated anti-reflux valves and graduated volume markings. Demand concentrates in tertiary hospitals across the United States and Germany where cross-contamination protocols mandate disposal after 24-72 hour dwell periods. Medicare bundled payment models accelerate procurement of these closed systems for early discharge protocols.
- Reusable:Rigid canister designs with detachable collection chambers requiring centralized sterilization service contracts. Adoption clusters in German-speaking European markets where captive hospital sterilization departments absorb reprocessing labor costs. REACH authorization burdens for plasticizer compounds are elevating total cost of ownership calculations.
- Sterile:Gamma or ethylene oxide pre-sterilized units with validated barrier packaging for immediate deployment in interventional radiology suites.
- Non-sterile:Bulk-packaged configurations for institutional sterilization workflows in hospital central supply departments.
Single-use holds installed capacity. Reusable is rotating up the share rankings in European cost-containment environments.
Material:
Application severity and indwelling duration dictate polymer selection between commodity feedstocks and biocompatibility-optimized grades.
- Polyethylene:Low-density formulations for short-duration acute drainage with cost-sensitive procurement profiles. Volume demand clusters in high-throughput public hospital systems across India and Brazil where procurement prioritizes unit economics over dwell-time performance.
- PVC:Plasticized medical-grade extrusions with kink-resistant tubing integration. Dominates standard acute-care configurations in the United States despite EPA ethylene oxide sterilization residue compliance pressures. ECHA REACH authorization timelines for phthalate alternatives are compressing formulation stability windows.
- Silicone:Platinum-cured grades enabling 30-90 day indwelling durations in palliative care applications. Premium positioning in Japanese home care channels where METI-funded aging-in-place initiatives extend monitoring responsibility to visiting nurses. ISO 10993 biocompatibility testing timelines delay new formulation launches.
- Rubber:Natural latex and synthetic elastomer configurations for specialized valve diaphragm components requiring compression set resistance.
Silicone captures margin expansion. Polyethylene is climbing the fastest in emerging market procurement tenders.
End User:
Customer type determines packaging configuration, instruction complexity, and technical support bundling requirements.
- Hospitals:Automated supply chain integration with barcode and RFID compatibility for centralized inventory management. Demand concentrates in multi-hospital systems across Texas and Florida where GPO-negotiated vendor panels consolidate procurement.
- Clinics:Lower-volume SKUs with simplified packaging for ambulatory surgery centers performing same-day hepatobiliary procedures.
- Home Care:Patient-managed configurations with pictographic instructions and telehealth-integrated volume monitoring. Expanding most quickly in North American accountable care organizations where early discharge protocols shift monitoring responsibility from inpatient nursing.
- Long-term Care Facilities:Extended-dwell configurations with enhanced securement mechanisms for mobility-impaired residents.
Hospitals anchor procurement volume. Home care is rotating up the share rankings as ambulatory protocols expand.
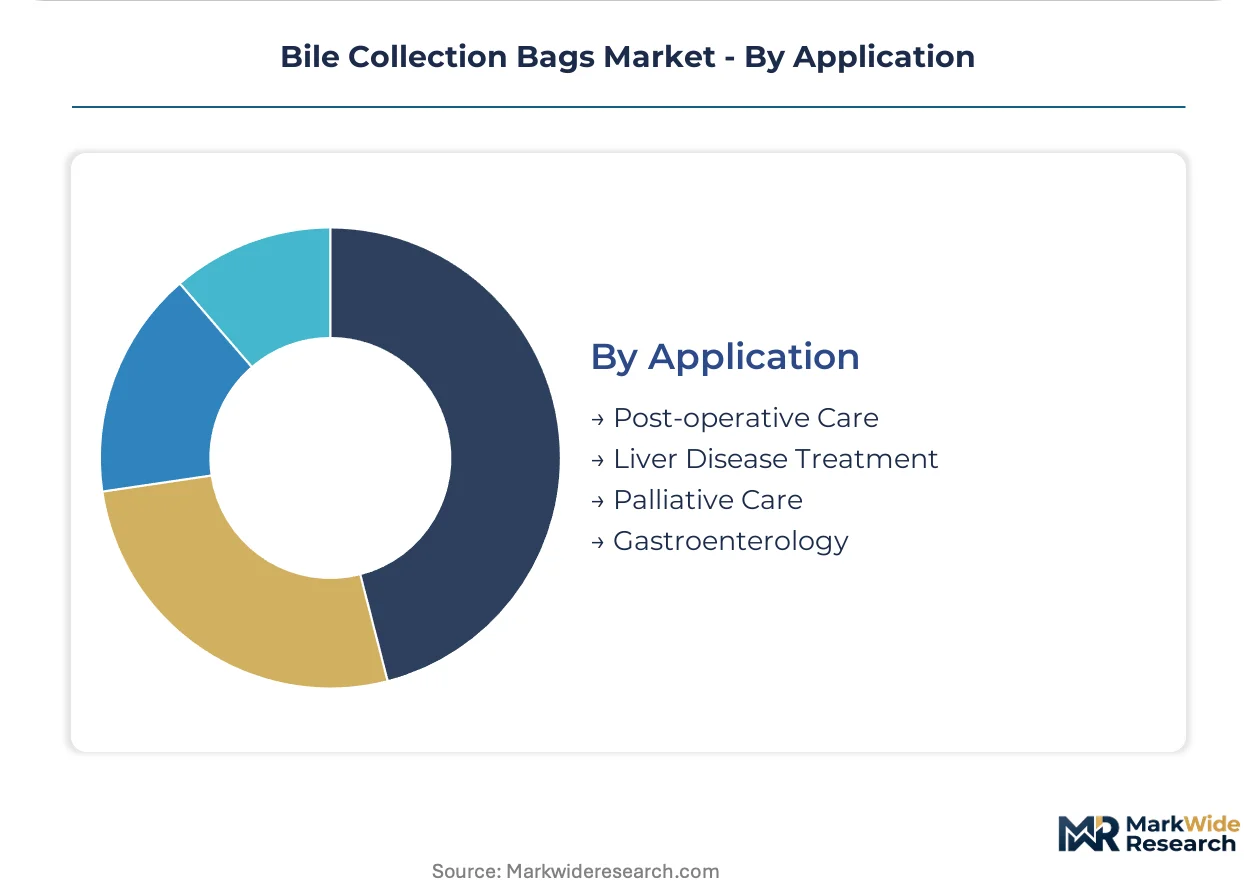
Application:
Clinical indication determines drainage catheter specifications, output monitoring frequency, and interdisciplinary care team composition.
- Post-operative Care:Closed-wound drainage following hepatic resection or biliary reconstruction. Demand concentrates in academic medical centers across the United States and Japan where surgical volumes and established reimbursement pathways sustain replacement cycles.
- Liver Disease Treatment:Ascites and biliary obstruction management in decompensated cirrhosis patients. Percutaneous transhepatic drainage catheter placement in interventional radiology suites drives specialized bag configurations with high-volume capacity.
- Palliative Care:Long-term indwelling applications where biocompatibility tolerance limits determine dwell time and patient comfort prioritization.
- Gastroenterology:Endoscopic retrograde cholangiopancreatography adjunct drainage and therapeutic biliary stenting support.
Post-operative care holds installed capacity. Home care applications are rotating up the share rankings as monitoring shifts to outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare bundled payment models in the United States penalize extended hospital stays and accelerate procurement of closed drainage systems suitable for home nursing oversight. Germany's EMA-coordinated MDR conformity assessments reshape European competitive thresholds through enhanced clinical evidence demands. Japan's METI-funded aging-in-place initiatives extend monitoring responsibility to visiting nurses.
United States
Post-operative ambulatory discharge protocols compress inpatient monitoring windows and force manufacturers to redesign bile collection bags for patient-managed home settings. FDA 510(k) clearance pathways govern market access while EPA ethylene oxide sterilization residue compliance pressures elevate facility upgrade costs. GPO-negotiated vendor panels in Texas and Florida multi-hospital systems consolidate procurement through centralized supply chain control rooms.
Germany
Established reimbursement pathways sustain replacement cycles for aging surgical populations in academic medical centers across Bavaria and North Rhine-Westphalia. ECHA REACH authorization timelines for phthalate alternatives compress formulation stability windows for medical-grade PVC feedstocks. Notified bodies in Germany and the Netherlands demand biocompatibility data packages exceeding legacy MEDDEV guidance.
Japan
PMDA streamlined Class II reviews create entry pathways for closed drainage systems designed for patient self-management in METI-funded aging-in-place initiatives. JIS T 0601 electrical safety and biocompatibility testing standards add certification layers for imported drainage systems. Kanto and Kansai regions concentrate demand from tertiary hospitals with established hepatobiliary surgery volumes.
India
High-throughput public hospital systems prioritize unit economics over dwell-time performance in procurement tenders for short-duration acute drainage. CDSCO medical device rules govern import and manufacture while BIS standards address material specifications. Maharashtra and Gujarat manufacturing hubs unlock supply capacity for standard-grade polyethylene configurations.
Brazil
Cost-sensitive procurement profiles dominate volume demand for low-density polyethylene formulations in public hospital systems. ANVISA medical device regulations establish conformity assessment requirements for imported closed drainage systems. São Paulo and Rio de Janeiro metropolitan areas concentrate surgical volumes driving replacement cycles.
Bile Collection Bags Market Competitive Environment
On the supply side, the industry is structured around three distinct capability tiers anchored by diversified medtech conglomerates, regional polymer specialists, and procedural-focused interventional players. Tier-one participants leverage captive logistics networks and backward integration into medical-grade compounding to defend margin positions. Tier-two competitors concentrate on sterilization service contracts and GPO panel consolidation. Dominant competitive moves include strategic partnerships with third-party sterilization logistics providers and portfolio diversification into telehealth-integrated volume monitoring systems.
Within the diversified medtech conglomerate tier, Fresenius Medical Care AG & Co. and B. Braun Melsungen AG exemplify scale-driven positioning through logistics network extension and captive polymer supply chain control. Cook Medical occupies a procedural specialization niche, anchoring deep catalog penetration in interventional gastroenterology suites. These three entities represent contrasting strategic archetypes: dialysis-centric logistics leverage, German-speaking European market anchoring through in-house extrusion capabilities, and academic medical center specialization respectively.
| Leading Market Players |
|---|
| Medline Industries, Inc. |
| C. R. Bard, Inc. |
| Fresenius Medical Care AG & Co. |
| Redax |
| B. Braun Melsungen AG |
| Hollister Incorporated |
| Cook Medical |
| Teleflex Incorporated |
| ConvaTec Group PLC |
| Others |
Value Chain & Pricing Dynamics
Gamma and ethylene oxide sterilization capacity clusters in Germany and the United States concentrate upstream control over margin pools downstream, forcing manufacturers to absorb logistics premiums or cede pricing power to hospital GPOs consolidating vendor panels. Medical-grade PVC feedstock volatility and REACH authorization burdens for plasticizer compounds compress formulation stability windows and elevate total cost of ownership calculations for standard-grade product lines.
Pricing Analysis
Certification level creates the primary spread between premium silicone configurations and commodity PVC alternatives, with FDA 510(k) clearance and EU MDR Annex I conformity assessments commanding 15-25% markups over basic CE-marked units. Price differentiation hinges on biocompatibility testing depth and sterile barrier validation tiers, while cost compression in polyethylene acute-care configurations intensifies due to high-throughput public hospital procurement in India and Brazil. GPO-negotiated vendor panels in Texas and Florida multi-hospital systems exhibit highest price sensitivity; Japanese home care channels show lowest sensitivity due to METI-funded aging-in-place reimbursement guarantees.
Supply Chain Analysis
Export-control restrictions on medical-grade silicone precursor chemicals limit raw material flows from specialized German and Japanese polymer compounders to downstream extrusion facilities. Manufacturing concentrates in Germany, the United States, and Japan where captive compounding capabilities and in-house extrusion of medical-grade PVC defend margin positions. Raw material dependencies include petrochemical feedstocks, platinum-cured silicone elastomers, and gamma-sterilization isotopes. Single-source vulnerability in third-party sterilization logistics creates geographic bottlenecks for just-in-time hospital replenishment. Distribution runs through GPO-contracted medical-surgical distributors with EDI-integrated inventory visibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through GPO panel consolidation and centralized supply chain control rooms in multi-hospital systems, fragmenting vendor access and forcing pricing transparency. Hospital procurement departments now unbundle after-sales technical support from device pricing and negotiate standalone sterilization service agreements.
For Market Incumbents:Insulate margin positions by deepening backward integration into medical-grade polymer compounding and securing captive sterilization capacity in Germany or the United States. Catheter-based drainage substitution in interventional radiology suites threatens standard bile collection bag volumes; counter through portfolio diversification into telehealth-integrated volume monitoring systems for early discharge protocols. Certification investment in ISO 10993 biocompatibility testing capabilities accelerates new silicone formulation launches against mid-sized competitors outsourcing to Irish and Swiss CROs.
For New Entrants and Emerging Players:Establish a beachhead in Japanese home care channels where METI-funded aging-in-place initiatives and PMDA streamlined Class II reviews create entry pathways for patient self-management configurations. The most penetrable white space sits in Bluetooth-enabled graduated markings paired with remote nursing platforms serving North American accountable care organizations. A telehealth-integrated go-to-market angle bypasses entrenched GPO vendor panels and captures ambulatory discharge protocol demand directly through ACO technology procurement committees.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mid-sized European manufacturers lacking captive clinical affairs teams and outsourcing post-market surveillance to Irish and Swiss CROs. Long-term viability across the analysis window hinges on EU MDR compliance completion and biodegradable polymer convergence capabilities. Acquisition target archetype: regional polymer specialists with extrusion equipment compatible with polylactic acid blends addressing French and Italian single-use plastics reduction mandates. The signal to watch is EPA ethylene oxide sterilization residue standard tightening, which would force capital-intensive facility upgrades and trigger distressed divestitures.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks Medicare bundled payment eligibility for home care configurations in United States hospital networks. |
| EU MDR Annex I Conformity Assessment | Notified bodies in Germany and Netherlands demand enhanced clinical evidence exceeding legacy MEDDEV guidance. |
| Hospital System Partnership | GPO-negotiated vendor panels in Texas and Florida consolidate procurement through centralized control rooms. |
| Software Companion Development | Bluetooth-enabled graduated markings integrate with remote nursing platforms serving early discharge protocols. |
| Reimbursement Strategy | METI-funded aging-in-place initiatives in Japan extend visiting nurse monitoring responsibility to home settings. |
Study Parameters
Operator-level perspectives from hospital purchasing committee members, GPO contracts managers, biomedical engineers, and interventional gastroenterology clinicians anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across the forecast period.
Scenario-bracketing around sterilization capacity constraints, REACH authorization timelines, and ambulatory discharge protocol adoption generated high-low forecast bands. Segmentation dimensions modeled include product type (single-use versus reusable), material grade (silicone, PVC, polyethylene), end-user channel (hospital, home care, long-term care), and application severity (post-operative, palliative, liver disease treatment). CAGRs derived from procedure volume growth, replacement cycle compression, and reimbursement pathway expansion. Industry-specific inputs encompassed hepatobiliary surgery volume projections and percutaneous drainage catheter placement rates.
Stress conditions across ethylene oxide sterilization residue compliance, medical-grade PVC feedstock volatility, and EU MDR clinical evidence demands were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about GPO vendor panel stability and PMDA Class II review streamlining continuity. Material shifts in EPA ambient air standards for sterilization facilities or abrupt REACH authorization withdrawals for phthalate alternatives would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
Surgical Glue Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Endoscope Protective Barrier Covers Market
Medical Supplies
Platelet and Plasma Market
Medical Supplies
Sperm Processing Media Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Medical Clothing Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Ostomy Care and Accessories Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Thermal Printable Wristband Market