
 Urodynamics Equipment and Disposables Market | 2026-2036
Urodynamics Equipment and Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Urodynamics Equipment and Disposables Market Analytics
Specialty clinics is consolidating as the dominant end-use channel for urodynamics systems, displacing traditional hospital-centric procurement models across mature healthcare markets. Laborie leverages its integrated diagnostic platform to sustain leadership in pelvic floor assessment workflows. Boston Scientific Corporation anchors its position through catheter technology specialization, while Verathon, Inc. competes on portable bladder scanner integration with urodynamics suites.
Urodynamics equipment and disposables encompass instrumented systems that measure pressure, flow rate, and electromyographic activity during bladder filling and voiding, typically employing fluid-filled catheters with pressure transducers sampling at 10 Hz and disposable single-use sensors to prevent cross-contamination. These systems serve primarily to objectively diagnose lower urinary tract dysfunction, differentiate between obstructive and neurogenic causes of incontinence, and guide surgical versus conservative treatment decisions. Pressure flow measurement systems occupy the largest installed base but face margin compression as wireless monitoring technology commands premium pricing and replacement cycles accelerate. Disposable sensors represent the fastest-expanding segment as infection control protocols tighten and single-use economics improve manufacturing scale.
The FDA's 510(k) premarket notification framework governs device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for urodynamics systems sold in European markets. Japan's PMDA maintains distinct quality management system audits that extend market access timelines for foreign manufacturers. Stakeholders must monitor reimbursement code consolidation for complex urodynamic procedures and decide whether to prioritize software integration capabilities or hardware miniaturization in next-generation platform development.
Market Dynamics
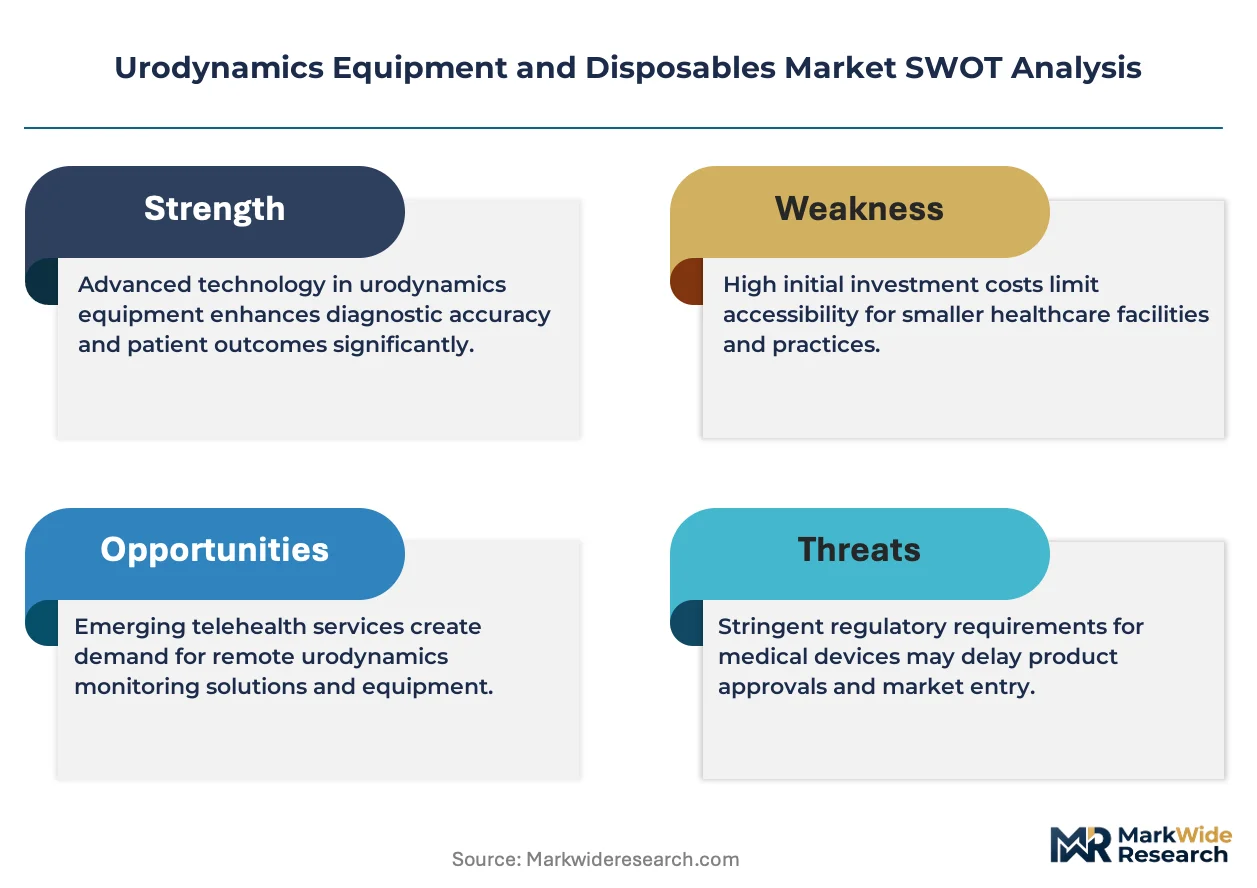
Wireless pressure transducer technology is compressing replacement cycles for fluid-filled catheter systems, forcing incumbent manufacturers to accelerate R&D timelines or cede installed base to modular disposable platforms.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter post-market surveillance requirements for Class IIa urodynamics devices are filtering out marginal competitors and consolidating procurement toward validated platform suppliers in Germany and France.
- Ambulatory surgery center expansion:Freestanding urology clinics in the United States are deploying compact urodynamics suites to capture referral volume outside hospital outpatient departments.
- Single-use sensor manufacturing scale:Automated micro-molding lines for disposable pressure catheters are collapsing per-unit costs and enabling point-of-care inventory models previously uneconomical.
Market Restraints
- Silicone supply concentration:Medical-grade silicone elastomer for catheter tubing concentrates among three German and Japanese chemical suppliers, exposing device margins to petrochemical feedstock volatility.
- FDA 510(k) predicate device dependency:Substantial equivalence requirements for new urodynamics systems create regulatory friction when no cleared predicate matches novel wireless architectures.
- Non-invasive bladder scanning substitution:Portable ultrasound volume measurement is capturing screening cases previously referred for full urodynamic study, compressing addressable procedure volume in primary care settings.
Strategic Opportunities
- India's CDSCO streamlined Class B pathway:Reduced clinical trial requirements for urodynamics catheters are accelerating market access timelines for manufacturers targeting tier-2 city hospital chains.
- Home-based urodynamics monitoring:Telehealth reimbursement expansion in the United States is creating demand for patient-operated bladder pressure logging systems with cloud-connected data transmission.
- AI-integrated pressure-voiding pattern recognition:Machine learning algorithms trained on urodynamic tracings are enabling automated diagnostic suggestions that differentiate neurogenic from obstructive dysfunction.
Industry Challenges
- Cross-functional clinical engineering talent scarcity:Urodynamics system deployment requires technicians trained simultaneously in urologic physiology, pressure transducer calibration, and EMG signal processing, with certification pipelines lagging demand.
- Legacy hospital IT integration complexity:New wireless urodynamics platforms must interface with entrenched electronic health record systems through HL7 or FHIR protocols, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urodynamics Equipment and Disposables Market |
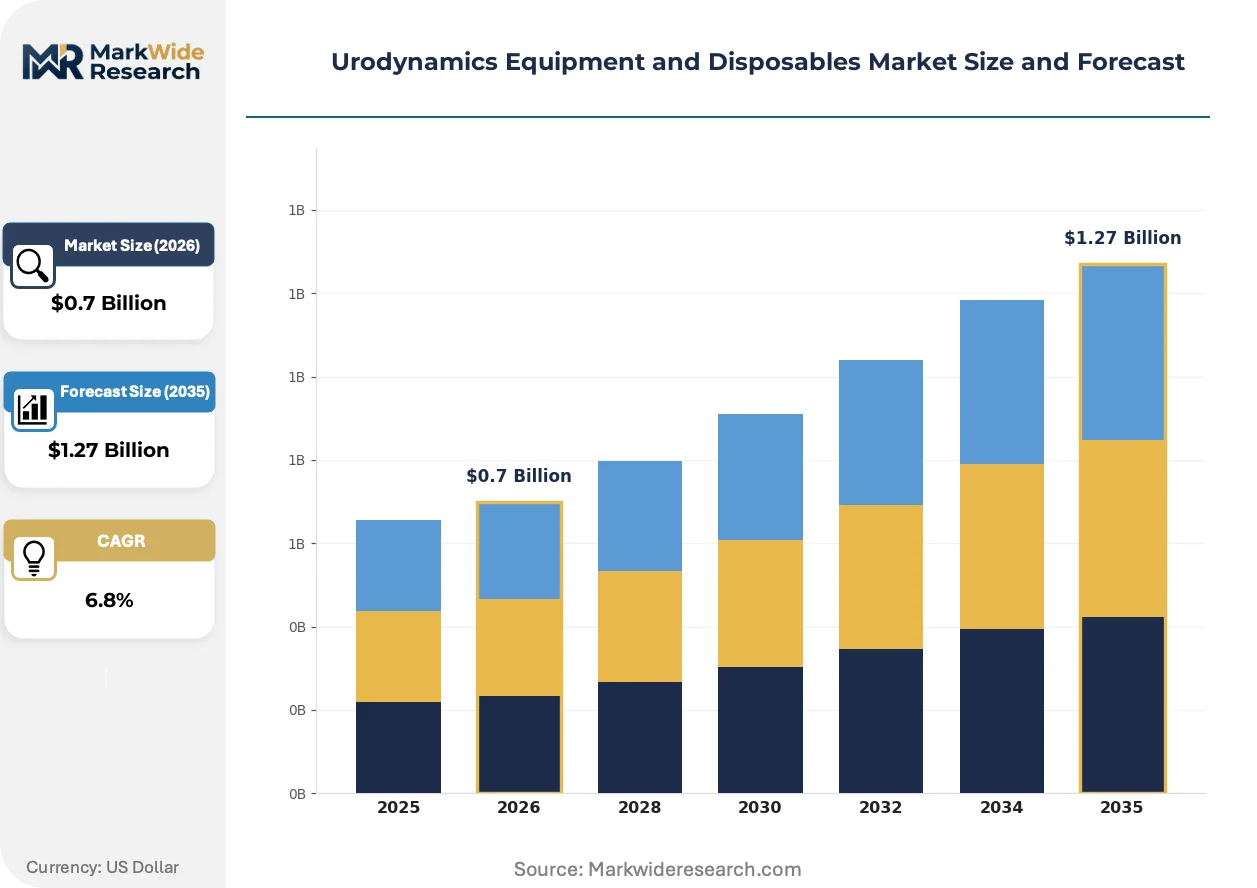
| Market Size in 2026 | $0.7 Billion |
| Market Size in 2035 | $1.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Flow Measurement Systems, Urethral Catheters, Electromyography Units, Disposable Sensors Technology: Wireless Monitoring, Digital Flowmetry, Electromechanical Systems, Software Integration End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Academic Research Institutes Application: Bladder Function Testing, Pelvic Floor Assessment, Neuromuscular Testing, Incontinence Evaluation |
| Companies Covered | Laborie, Boston Scientific Corporation, Verathon, Inc., Albyn Medical, SRS Medical, MEDKONSULT medical technology, The Prometheus Group, CooperSurgical, Digitimer Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urodynamics Equipment and Disposables Market Evolving Landscape
Three interconnected developments are restructuring how urodynamic diagnostic capability deploys: miniaturization of pressure sensing elements, regulatory recalibration of clinical evidence standards, and channel migration toward outpatient settings.
Capacitive micro-machined pressure sensors are electrifying catheter architecture by eliminating fluid-filled lumens and enabling wireless data transmission from intravesical transducers. Ambulatory urology centers in Germany are adopting these solid-state platforms within eighteen-month replacement windows. The technology is electrifying competitive positioning by collapsing the traditional distinction between capital equipment and consumable revenue models.
The EU Medical Device Regulation's post-market clinical follow-up requirements are extending surveillance obligations for urodynamics systems across their entire service life. Manufacturers must now maintain clinical data registries or face notified body audit failures. This regulatory shift most heavily affects pressure-flow study systems, where sponsors are restructuring quality management systems to capture real-world performance evidence.
Specialty clinic procurement committees are consolidating vendor relationships around integrated diagnostic platforms that bundle urodynamics with cystoscopy and ultrasound. Hospital-based urology departments are losing purchasing autonomy as integrated delivery networks centralize capital allocation decisions. This concentration pattern is most visible in the United States, where IDN supply chain offices are negotiating multi-year sole-source agreements for urodynamics suites.
Urodynamics Equipment and Disposables Market Segmentation
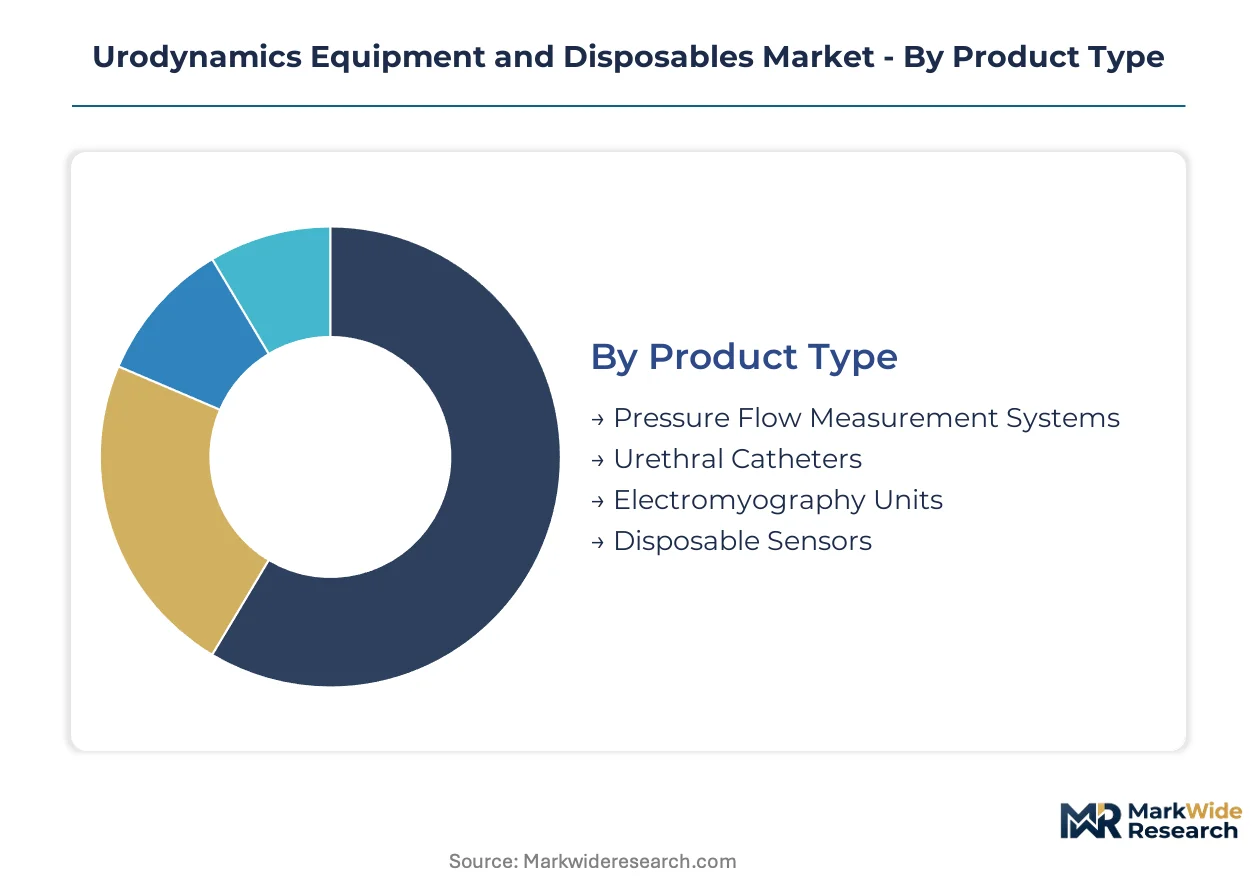
Urodynamics market segmentation reveals distinct procurement patterns across product types and end-use settings. Technology choices and application requirements drive purchasing decisions differently in hospital versus outpatient environments.
Product Type:
Purchasing committees prioritize installed base compatibility and per-procedure economics when selecting urodynamics equipment categories.
- Pressure Flow Measurement Systems:These instrumented platforms employ dual-channel pressure transducers sampling at 10 Hz with automated infusion pumps for controlled bladder filling. German ambulatory urology centers are consolidating procurement around compact integrated suites that combine pressure-flow capability with video urodynamics. Margin pressure intensifies as wireless alternatives command premium positioning.
- Disposable Sensors:Single-use pressure catheters and EMG electrodes manufactured through automated micro-molding eliminate cross-contamination risks. Infection control protocol tightening across United States specialty clinics is collapsing per-unit costs through manufacturing scale expansion. Point-of-care inventory models now support same-day procedure scheduling.
- Urethral Catheters:Fluid-filled lumens in 6-10 French sizes with radiopaque markers enable precise transurethral placement.
- Electromyography Units:Surface and needle electrode configurations capture sphincter muscle activity during voiding phases.
Volume sits with Pressure Flow Measurement Systems; growth tilts toward Disposable Sensors.
Technology:
Replacement cycle acceleration and interoperability requirements shape technology adoption curves across urodynamics platforms.
- Wireless Monitoring:Capacitive micro-machined pressure sensors eliminate fluid-filled catheter lumens and enable Bluetooth data transmission from intravesical transducers. German specialty clinics are adopting solid-state platforms within compressed eighteen-month replacement windows. The technology collapses traditional distinctions between capital equipment and consumable revenue streams.
- Software Integration:Cloud-connected platforms with HL7/FHIR interoperability automate diagnostic reporting and EMG pattern recognition. United States integrated delivery networks are prioritizing vendors with established electronic health record interfaces. Implementation timelines extend where legacy hospital IT architecture requires custom middleware development.
- Digital Flowmetry:Gravimetric and rotating disk flow sensors measure voided volume with ±5% accuracy.
- Electromechanical Systems:Motor-driven infusion pumps with programmable fill rates support standardized urodynamic protocols.
Revenue concentrates in Wireless Monitoring; Software Integration is climbing the fastest.
End User:
Channel migration toward outpatient settings is restructuring vendor relationships and equipment form factor requirements.
- Specialty Clinics:Freestanding urology practices deploy compact diagnostic suites to capture referral volume outside hospital outpatient departments. United States ambulatory surgery center expansion is driving demand for space-efficient platforms with rapid patient throughput capability. Procurement committees favor integrated systems bundling urodynamics with cystoscopy and ultrasound.
- Hospitals:Academic medical centers maintain comprehensive urodynamics laboratories serving complex neurogenic bladder cases. Germany's hospital systems are losing purchasing autonomy as regional procurement consortia centralize capital allocation decisions. Equipment specifications emphasize research-grade signal fidelity and multi-channel expansion capacity.
- Ambulatory Surgical Centers:Same-day discharge protocols require portable systems with streamlined setup workflows.
- Academic Research Institutes:Specialized platforms support investigational protocols and teaching curricula.
Procurement volume favors Specialty Clinics; expansion is steepest in Ambulatory Surgical Centers.
Application:
Clinical indication specificity determines sensor configuration and diagnostic protocol complexity.
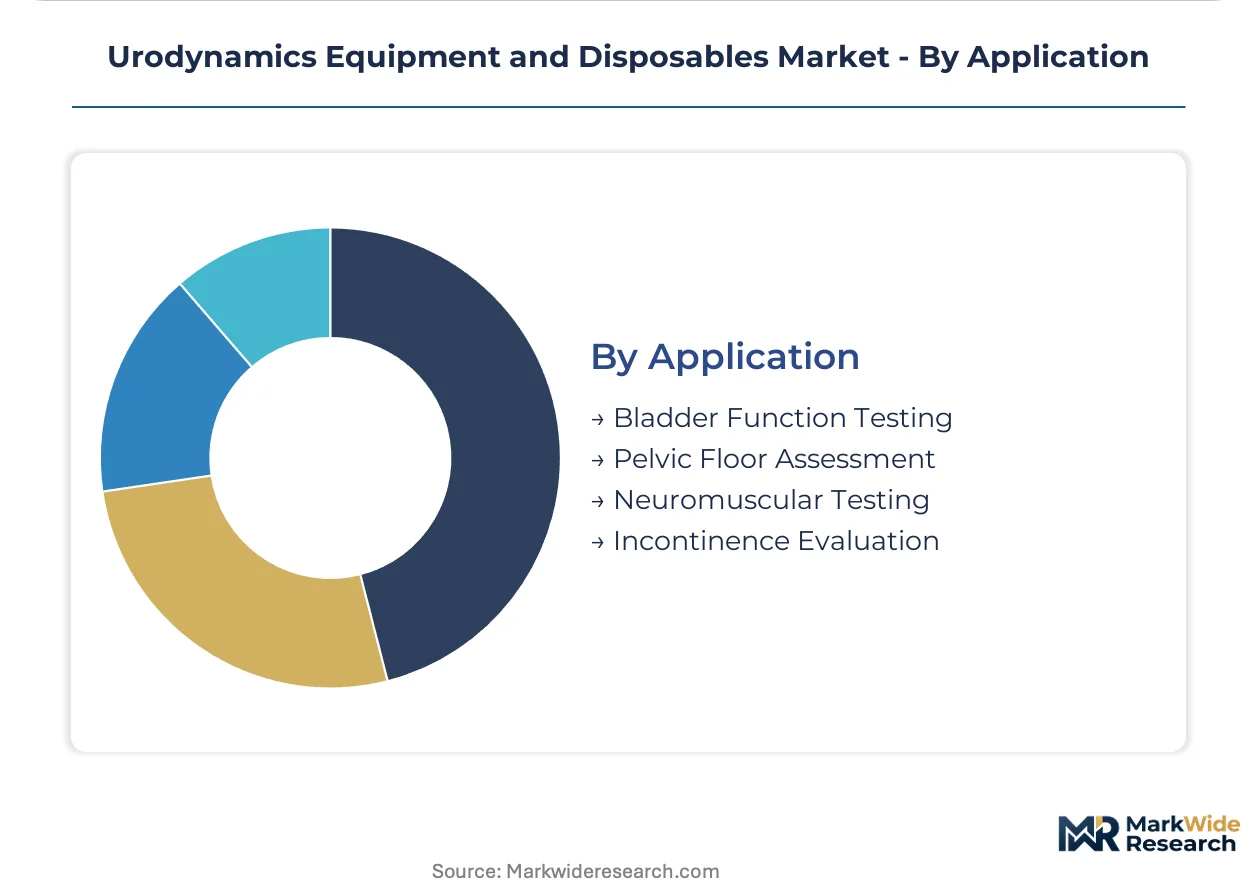
- Bladder Function Testing:Cystometry and pressure-flow studies quantify detrusor contractility and outlet resistance. United States reimbursement code consolidation for complex urodynamic procedures is concentrating procedure volume in validated platform settings. Diagnostic yield requirements favor systems with synchronized video fluoroscopy integration.
- Incontinence Evaluation:Stress leak point pressure measurement and urethral pressure profilometry differentiate intrinsic sphincter deficiency from hypermobility. Germany's expanding ambulatory urology network is deploying streamlined protocols for female stress incontinence assessment. Conservative versus surgical treatment decisions depend on objective pressure-flow documentation.
- Pelvic Floor Assessment:Combined EMG and pressure measurement evaluates coordinated sphincter relaxation during voiding.
- Neuromuscular Testing:Detrusor-sphincter dyssynergia identification requires high-fidelity EMG signal processing.
Procedure volume centers on Bladder Function Testing; Incontinence Evaluation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of urodynamics catheters and pressure sensors concentrates in Germany and Japan, while diagnostic procedure volume tilts toward the United States and Western Europe. This production-consumption asymmetry shapes trade flows and regulatory compliance burdens across the value chain.
United States
Freestanding urology clinics deploy compact urodynamics suites to capture referral volume outside hospital outpatient departments. The FDA's 510(k) premarket notification framework governs device clearance timelines for new entrants. The Southeast region—particularly Florida and Georgia—hosts expanding ambulatory surgery center networks driving equipment procurement.
Germany
Ambulatory urology centers expand diagnostic capacity faster than hospital systems, concentrating demand for wireless monitoring platforms. The EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa urodynamics devices. The Baden-Württemberg industrial corridor houses precision molding operations supplying disposable catheter components across Europe.
Japan
Aging demographics sustain procedure volume for incontinence evaluation and neurogenic bladder assessment. The PMDA maintains distinct quality management system audits that extend market access timelines for foreign manufacturers. The Kanto region around Tokyo anchors specialist urology clinic networks adopting solid-state pressure sensor technology.
India
Tier-2 city hospital chains build urodynamics capability as urology specialization spreads beyond metropolitan centers. The CDSCO streamlined Class B pathway reduces clinical trial requirements for urodynamics catheters. Maharashtra's medical device manufacturing zones supply cost-optimized disposable sensors for domestic and export markets.
United Kingdom
National Health Service procurement consolidation favors validated platform suppliers with established service networks. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with EU MDR standards. London and the Southeast corridor concentrate private urology clinic investment in integrated diagnostic platforms.
Urodynamics Equipment and Disposables Market Competitive Landscape
Top-tier vendors anchor integrated diagnostic platforms, while mid-tier specialists compete on catheter technology or portable device miniaturization. The vendor base stratifies across three functional tiers: full-suite platform providers, disposable component specialists, and regional equipment fabricators. Two strategic archetypes dominate—multinational medical device conglomerates leveraging cross-selling synergies, and focused urology specialists defending niche technical positions. Competitive moves concentrate on wireless sensor R&D partnerships and ambulatory care channel expansion.
Among North American platform providers, Laborie and Boston Scientific Corporation exemplify contrasting strategic positions within the urodynamics value chain. Verathon, Inc. occupies a distinct tier emphasizing portable bladder scanner integration. European specialists including Albyn Medical and SRS Medical represent the catheter technology archetype, while MEDKONSULT medical technology anchors German-speaking regional markets. These named entities illustrate how competitive positioning fragments across technology vectors rather than consolidating around unified platform dominance.
| Leading Market Players |
|---|
| Laborie |
| Boston Scientific Corporation |
| Verathon, Inc. |
| Albyn Medical |
| SRS Medical |
| MEDKONSULT medical technology |
| The Prometheus Group |
| CooperSurgical |
| Digitimer Ltd |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up catheter specialists in Germany and Japan anchor manufacturing consolidation, compressing procurement timelines for disposable pressure sensors while sustaining premium positioning for wireless platforms through captive molding capacity and infection-control certification tiers.
Pricing Analysis
Margin tightening in standard fluid-filled catheter tiers reflects silicone elastomer feedstock volatility and automated micro-molding scale economies collapsing per-unit costs. Three-tier pricing structure across premium wireless, standard electromechanical, and economy gravity-flow systems differentiates by signal fidelity and EMG integration depth. Cost-down pressure on disposable sensors accelerates because United States specialty clinics prioritize same-day inventory turns over capital equipment depreciation. Academic medical centers exhibit lowest price sensitivity, while ambulatory surgery centers in Florida and Georgia drive hardest bargain consolidation.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for medical devices are reshaping sourcing patterns for cost-optimized catheter tubing. Manufacturing gravity centers on Germany's Baden-Württemberg precision molding corridor, Japan's Kanto chemical processing belt, and Maharashtra's emerging device zones. Medical-grade silicone elastomer, capacitive MEMS pressure dies, and radiopaque marker compounds constitute critical input dependencies. Single-source vulnerability concentrates in German and Japanese silicone suppliers exposed to petrochemical volatility. Distribution runs through integrated delivery network supply chain offices negotiating multi-year sole-source agreements in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urodynamics market functions as a vertical-integration race where control over MEMS pressure sensor fabrication and automated micro-molding capacity determines margin capture in disposable segments.
For Market Incumbents: Hedge wireless platform commoditization by deepening backward integration into capacitive pressure sensor wafer production and securing exclusive supply agreements with German silicone compounders. Laborie's integrated diagnostic platform faces substitution threat from portable bladder scanner convergence; defend through cystoscopy-ultrasound bundling contracts with United States integrated delivery networks. For New Entrants and Emerging Players: Capture India's tier-2 city hospital expansion via CDSCO streamlined Class B pathway acceleration, where clinical trial requirements for urodynamics catheters have collapsed. Target home-based urodynamics monitoring white space created by United States telehealth reimbursement expansion, deploying patient-operated bladder pressure logging with cloud-connected HL7/FHIR data transmission as primary go-to-market wedge. For Investors and Strategic Acquirers: FDA 510(k) predicate device dependency disputes for novel wireless architectures are the leading indicator that regulatory friction will consolidate procurement toward validated platform suppliers with established quality management systems. Five-to-ten year viability favors acquiring catheter technology specialists with MEMS sensor partnerships and German notified body relationships, watching EU MDR post-market clinical follow-up compliance costs as margin compression signal.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Sensor R&D Partnership | Capacitive MEMS pressure transducer development collapses fluid-filled catheter replacement cycles in German ambulatory centers. |
| CDSCO Regulatory Fast-Track | Streamlined Class B pathway accelerates market access for disposable catheter manufacturers targeting Maharashtra medical zones. |
| IDN Supply Chain Consolidation | Multi-year sole-source agreements with United States integrated delivery networks lock out fragmented regional competitors. |
| AI Diagnostic Software Integration | Machine learning pattern recognition for pressure-voiding differentiation commands premium positioning in academic medical centers. |
| Silicone Supply Security | Captive agreements with German and Japanese elastomer compounders insulate margins from petrochemical feedstock volatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across urology practice administrators, biomedical engineering directors, hospital purchasing committee members, and GPO contracts managers. FDA 510(k) premarket notification databases, EU MDR notified body audit records, PMDA quality management system filings, and CDSCO device registration logs supplied secondary validation. Bottom-up equipment installation tracking and top-down procedure volume estimates were triangulated against disposable sensor manufacturing throughput data.
Reconciliation of shipment data, procurement contract disclosures, and clinical procedure registries generated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type hierarchy, wireless versus electromechanical technology tiers, specialty clinic versus hospital versus ambulatory surgery center end-use channels, and bladder function versus incontinence versus pelvic floor application categories. CAGRs were derived from installed base replacement cycle analysis and per-procedure disposable consumption rates, with sensitivity testing against EU MDR compliance cost pass-through assumptions and United States telehealth reimbursement expansion scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to wireless sensor commoditization velocity, silicone supply disruption events, and AI diagnostic software regulatory classification shifts. Forecasts reflect documented assumptions regarding reimbursement code stability, infection control protocol tightening trajectories, and ambulatory surgery center licensing expansion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Mortuary Refrigerator Market
Medical Equipment
Global Medical Lifting Slings Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
Centrifuge Market
Medical Equipment
China Radiotherapy Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Medical Computer Carts Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Cryochambers Market
Medical Equipment
Operating Table Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Nuclear Medicine Equipment Market
Medical Equipment
Medical Tubing Market