
 Plasma Expanders Market | 2026-2036
Plasma Expanders Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Expanders Market Outlook
A shift from single-source plasma dependency toward multi-source synthetic formulations is restructuring procurement patterns across hospital systems. Fresenius Kabi AG leverages its integrated manufacturing network to secure supply continuity for gelatin-based solutions across European markets. CSL Limited anchors its position through captive plasma collection infrastructure that sustains fractionation output for albumin and immunoglobulin expanders. Baxter International Inc. competes on perfusion technology leadership, extending its footprint in intraoperative fluid management systems.
Plasma expanders are intravenous solutions designed to restore circulating blood volume in hypovolemic patients, with colloid formulations typically containing macromolecules such as hydroxyethyl starch or gelatin polymers that exert oncotic pressure across capillary membranes. Crystalloid variants rely on electrolyte compositions like lactated Ringer's or normal saline to redistribute across fluid compartments, requiring larger infusion volumes to achieve equivalent hemodynamic effects. Colloid solutions command premium positioning in cardiac surgery and trauma protocols where rapid volume restoration determines patient outcomes, while crystalloids dominate emergency medicine due to lower cost profiles and broader compatibility. The intravenous administration route absorbs the majority of clinical volume, though intraosseous delivery is gaining traction in battlefield and pediatric emergency settings where vascular access proves difficult.
The US FDA enforces Current Good Manufacturing Practice standards for plasma-derived biologics, while the European MDR mandates enhanced clinical evidence for implantable and injectable substances including volume expanders. India's CDSCO aligns with WHO prequalification pathways for essential medicines, accelerating local production of crystalloid solutions under its PLI scheme for pharmaceuticals. Stakeholders must monitor evolving hemostatic safety thresholds for starch-based products, as regulatory agencies recalibrate risk-benefit frameworks that could reshape formulary access and reimbursement categories.
Market Dynamics
The plasma expanders market is restructuring around synthetic polymer chemistry as FDA and EMA pharmacovigilance protocols erode starch-based colloid viability. Manufacturers are redirecting R&D spend toward gelatin and crystalloid formulations that bypass plasma fractionation dependencies.
Growth Catalysts
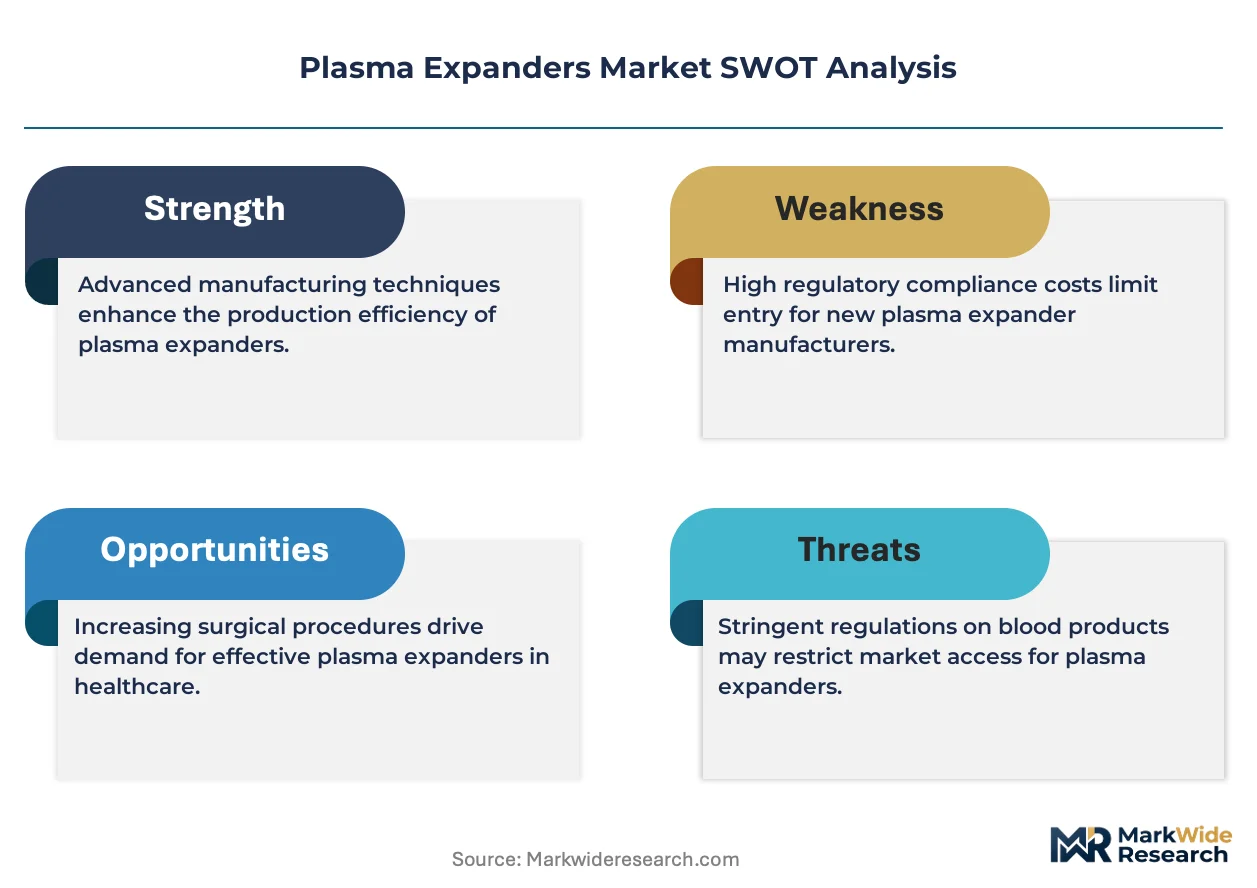
- EU MDR Implementation:The European Medical Device Regulation mandates enhanced clinical evidence for injectable volume expanders, accelerating hospital procurement of well-documented synthetic colloids over legacy starch products.
- Trauma Center Expansion:Emergency departments across the United States are standardizing massive transfusion protocols that embed pre-hospital colloid administration, embedding plasma expanders into critical care workflows.
- Gelatin Polymer Chemistry:Advances in succinylated gelatin formulations have improved molecular stability profiles, enabling extended shelf life and reduced anaphylactic response rates in perioperative settings.
Market Restraints
- Plasma Collection Concentration:Fractionated albumin supply depends on captive collection infrastructure concentrated in the United States and Australia, creating geographic vulnerability for human-derived expanders.
- Hydroxyethyl Starch Restrictions:FDA black box warnings and EMA suspension of high-molecular-weight starch products have eliminated a major colloid category from formulary access.
- Saline Cost Compression:Normal saline and lactated Ringer's solutions command minimal margin, constraining manufacturer investment in crystalloid innovation despite high emergency medicine volume.
Strategic Opportunities
- Intraosseous Delivery Systems:Military and pediatric emergency protocols are adopting bone-infusion expander administration where vascular access fails, opening device-solution bundling opportunities.
- India PLI Scheme:The country's production-linked incentive program for pharmaceuticals is accelerating local crystalloid manufacturing capacity under CDSCO alignment with WHO prequalification pathways.
- Perioperative Goal-Directed Therapy:Hemodynamic monitoring integration with colloid titration protocols is creating demand for algorithm-compatible expander formulations in cardiac surgery suites.
Industry Challenges
- Fractionation Expertise Scarcity:Plasma-derived biologics manufacturing requires specialized protein purification competencies that contract as synthetic alternatives dominate R&D investment.
- Multinational Compliance Divergence:Harmonizing FDA cGMP, EMA MDR, and CDSCO documentation requirements extends product registration timelines and fragments quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Expanders Market |
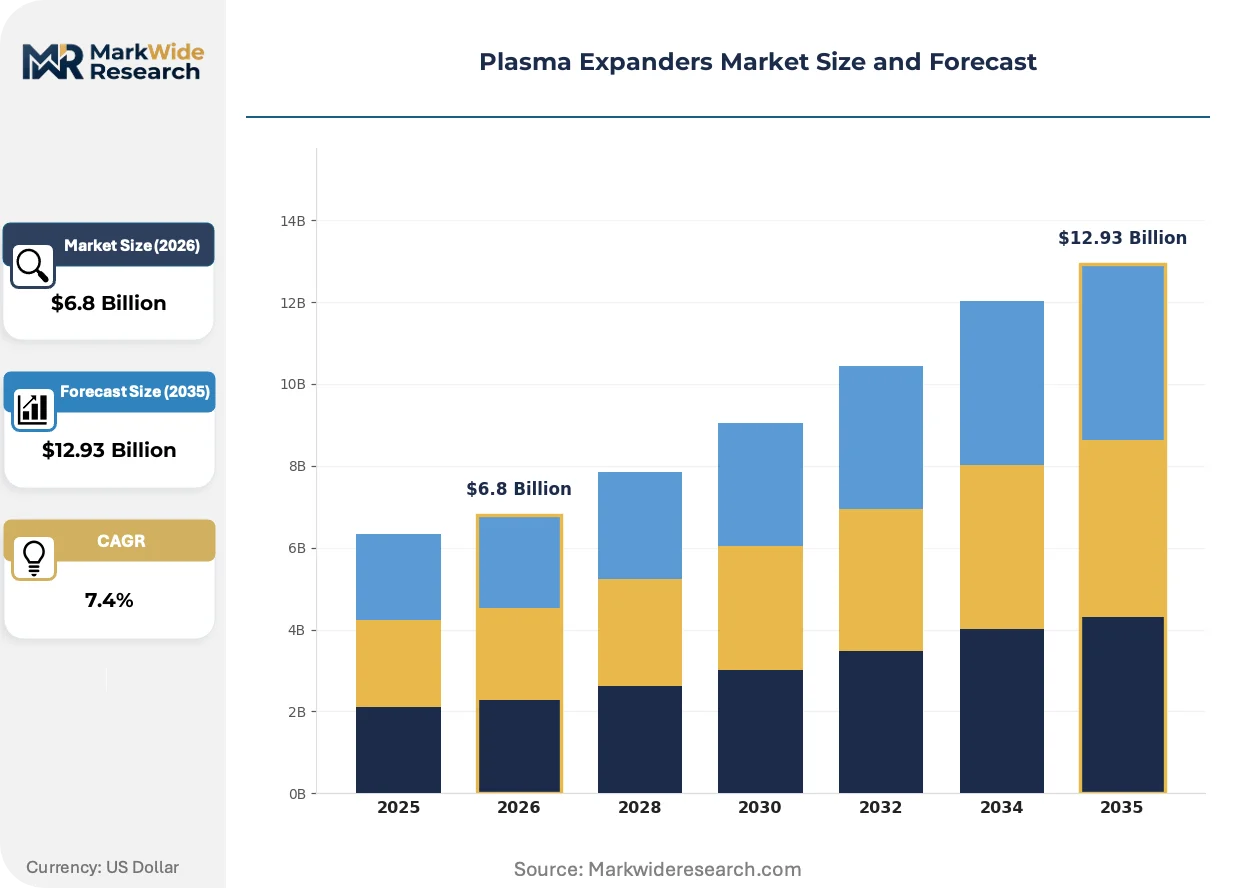
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colloids, Crystalloids, Gelatin-based Solutions, Starch-based Solutions Administration Route: Intravenous, Intraosseous, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Blood Banks, Emergency Medical Services Formulation: Liquid, Powder, Concentrated, Lyophilized |
| Companies Covered | Fresenius Kabi AG, CSL Limited, B. Braun Melsungen AG, Baxter International Inc., Grifols, Pfizer Inc., Abbott, Kedrion Biopharma, Biogen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Expanders Market Strategic Shifts
Synthetic colloid chemistry and point-of-care hemodynamic monitoring are converging to displace empirical fluid resuscitation protocols. Regulatory pressure on starch-based products is accelerating formulation diversification across hospital systems.
Balanced crystalloid solutions are unifying electrolyte compositions that minimize hyperchloremic metabolic acidosis. Academic medical centers in the United States are adopting plasmalyte and lactated Ringer's as default resuscitation fluids. This chemistry shift is compressing normal saline procurement volumes in surgical and intensive care settings.
REACH authorization requirements for polymer-based medical substances are tightening purity thresholds for synthetic colloid excipients. European manufacturers are reformulating gelatin products to eliminate residual aldehyde cross-linkers. The EMA's enhanced scrutiny is redirecting competitive investment toward low-molecular-weight hydroxyethyl starch alternatives with improved renal safety profiles.
Hospital formulary committees are consolidating plasma expander contracts through group purchasing organizations that bundle colloids, crystalloids, and delivery sets. Integrated delivery networks in the United States are displacing standalone product negotiations with multi-year supply agreements. This concentration is most visible in trauma center networks where standardization across facilities reduces clinical variation and procurement overhead.
Plasma Expanders Market Segmentation
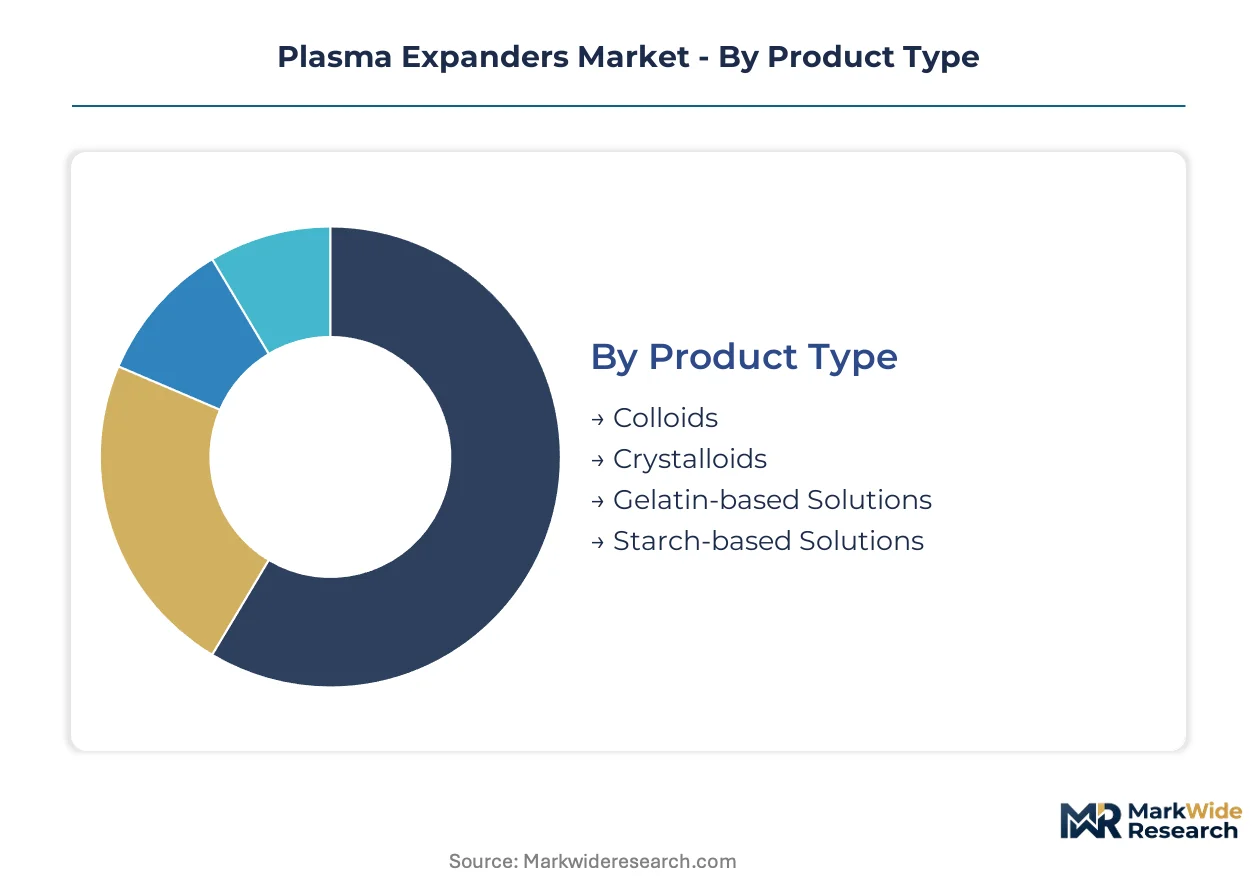
Plasma expander procurement splits sharply between high-cost colloid formulations for surgical precision and commoditized crystalloids for emergency volume loading. Hospital formulary committees weight oncotic efficacy against unit economics when segmenting purchasing across clinical settings.
Product Type:
Volume leadership belongs to crystalloid solutions, while margin concentration sits with synthetic colloid formulations.
- Colloids:Macromolecular solutions including albumin and hydroxyethyl starch exert oncotic pressure across capillary membranes, enabling rapid hemodynamic stabilization with smaller infusion volumes. Cardiac surgery suites in the United States and trauma centers in Germany anchor procurement for these premium formulations.
- Crystalloids:Electrolyte-based solutions redistribute across total body water compartments, requiring larger volumes for equivalent circulatory expansion. Emergency departments standardize normal saline and lactated Ringer's as first-line resuscitation fluids due to cost profiles and broad compatibility.
- Gelatin-based Solutions:Succinylated gelatin polymers from bovine collagen offer intermediate oncotic properties with reduced anaphylactic risk compared to older starch formulations.
- Starch-based Solutions:Hydroxyethyl starch products face EMA suspension and FDA black box warnings, eliminating this category from standard formulary access in most regulated markets.
Mature deployment sits with crystalloid solutions in emergency medicine. Newer deployment is concentrated in gelatin-based colloids for perioperative goal-directed therapy.
Administration Route:
Access reliability determines route selection, with vascular patency dictating primary choice and bone-infusion serving as fallback.
- Intravenous:Peripheral and central venous catheters deliver the overwhelming majority of plasma expander volume, supported by established nursing protocols and infusion pump compatibility across hospital wards and operating theaters.
- Intraosseous:Sternum and proximal tibia access enables rapid fluid administration when vascular collapse prevents peripheral or central line placement. Military combat support hospitals and pediatric emergency departments in the United States are expanding training protocols for this route.
- Subcutaneous:Hypodermoclysis delivers small-volume hydration in palliative care settings where venous access is undesirable or unnecessary.
- Intramuscular:Limited application for specific colloid formulations in pre-hospital settings where vascular access remains pending.
Established infrastructure supports intravenous administration. Intraosseous deployment is climbing the fastest as military and pediatric protocols formalize backup access standards.
End User:
Procurement scale concentrates in integrated hospital networks, with specialized facilities driving formulation specificity.
- Hospitals:Academic medical centers and community hospital systems absorb the majority of plasma expander volume through group purchasing organization contracts that bundle colloids, crystalloids, and delivery sets across surgical, intensive care, and emergency departments.
- Emergency Medical Services:Ground and air ambulance services pre-hospital colloid administration for trauma protocols, embedding plasma expanders into critical care workflows before hospital arrival.
- Clinics:Outpatient surgical centers and infusion suites purchase limited crystalloid volumes for minor procedures and hydration therapy.
- Blood Banks:Fractionation facilities and transfusion services maintain albumin inventories for specific coagulopathy and volume expansion indications.
Contract consolidation favors hospital networks. Emergency Medical Services represent the fastest-growing procurement channel as pre-hospital trauma protocols expand.
Formulation:
Logistics infrastructure and shelf-life requirements segment manufacturing investment across physical states.
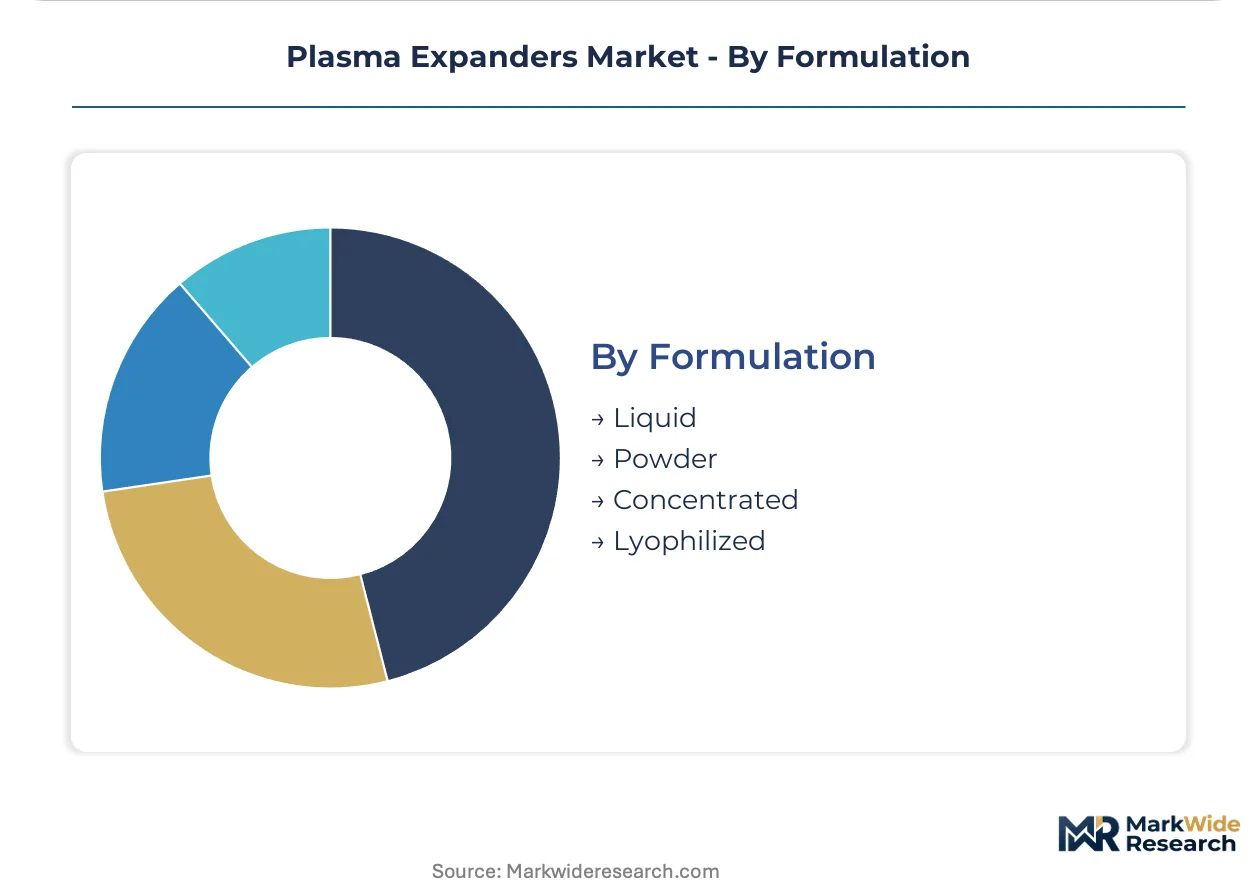
- Liquid:Ready-to-infuse solutions dominate hospital procurement due to immediate availability and elimination of reconstitution steps in time-critical clinical scenarios.
- Lyophilized:Freeze-dried albumin and specialty colloids enable extended stability for strategic stockpiling and military medical logistics where cold chain maintenance proves challenging.
- Powder:Bulk crystalloid concentrates reduce shipping weight and storage footprint, requiring on-site sterile water addition before administration.
- Concentrated:Hyperoncotic albumin formulations permit smaller infusion volumes for specific hepatorenal and burn resuscitation protocols.
Operational simplicity anchors liquid formulation dominance. Lyophilized formats are gaining share fastest in disaster preparedness and expeditionary medical supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement of plasma expanders concentrates in the United States, where aging demographics and high surgical volumes sustain demand for intravenous volume expanders across integrated delivery networks.
United States
Academic medical centers in Massachusetts and California anchor colloid procurement for cardiac surgery protocols. The FDA enforces Current Good Manufacturing Practice standards for plasma-derived biologics, tightening pharmacovigilance requirements that push manufacturers toward synthetic alternatives. Trauma center networks across Texas and Florida standardize massive transfusion protocols embedding pre-hospital colloid administration.
Germany
Emergency departments in Bavaria and North Rhine-Westphalia drive gelatin-based solution adoption for perioperative goal-directed therapy. The EMA mandates enhanced clinical evidence for injectable volume expanders under MDR implementation, accelerating procurement of well-documented synthetic colloids. Fresenius Kabi AG leverages its integrated manufacturing network to secure supply continuity for gelatin-based solutions across European markets.
India
Hospital systems in Maharashtra and Karnataka expand crystalloid procurement as surgical volumes rise in metropolitan centers. The CDSCO aligns with WHO prequalification pathways for essential medicines, accelerating local production under the PLI scheme for pharmaceuticals. Domestic manufacturers in Gujarat and Telangana build sterile saline and lactated Ringer's capacity for regional distribution.
Japan
Metropolitan Tokyo and Osaka medical centers maintain albumin inventories for specific coagulopathy indications. The PMDA enforces stringent quality standards for plasma-derived biologics that sustain premium positioning for human-derived expanders. Regional hospital networks in Chubu and Kyushu consolidate formulary contracts through group purchasing organizations.
Australia
Captive plasma collection infrastructure in Victoria and New South Wales sustains fractionation output for albumin and immunoglobulin expanders. The TGA monitors hemostatic safety thresholds for starch-based products, recalibrating risk-benefit frameworks that reshape formulary access. CSL Limited anchors its regional position through upstream control over collection and fractionation assets.
Plasma Expanders Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers redirect R&D spend toward gelatin and crystalloid formulations that bypass plasma fractionation dependencies. The vendor base splits between integrated plasma fractionators and synthetic polymer specialists, creating tiered competition around supply security versus formulation innovation. Three archetypes define positioning: captive plasma collectors with fractionation expertise, synthetic colloid chemists with polymer manufacturing scale, and diversified infusion therapy providers with distribution breadth. Geographic expansion and portfolio diversification constitute the dominant competitive moves as companies seek regulatory arbitrage across FDA, EMA, and CDSCO jurisdictions.
Among integrated plasma specialists, CSL Limited and Grifols exemplify the captive-collection archetype, anchoring positions through upstream control over raw material supply. Baxter International Inc. and Fresenius Kabi AG occupy positions within the diversified infusion therapy tier, leveraging device-solution bundling and integrated manufacturing networks respectively. B. Braun Melsungen AG represents the European manufacturing specialist archetype, with GmbH-structured operations concentrated in German industrial clusters. These named entities illustrate competitive positioning without exhausting the market's full participant set.
| Leading Market Players |
|---|
| Fresenius Kabi AG |
| CSL Limited |
| B. Braun Melsungen AG |
| Baxter International Inc. |
| Grifols |
| Pfizer Inc. |
| Abbott |
| Kedrion Biopharma |
| Biogen Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive plasma collection infrastructure in the United States and Australia anchors supply security for human-derived expanders while simultaneously constraining pricing flexibility for fractionated albumin. This upstream control dynamic creates divergent margin structures between plasma-dependent biologics and synthetic alternatives that bypass collection dependencies entirely.
Pricing Analysis
Service bundling separates device-solution packages from standalone fluid procurement, with Fresenius Kabi and Baxter embedding infusion pumps and delivery sets into multi-year hospital contracts. Three-tier pricing structure across premium colloids, standard crystalloids, and economy saline segments reflects oncotic efficacy differentiation and regulatory documentation depth. Cost compression in crystalloid tiers stems from group purchasing organization consolidation, while cardiac surgery suites demonstrate lowest price sensitivity due to outcome-critical positioning. Gelatin-based formulations command mid-tier premiums where EMA clinical evidence requirements elevate procurement standards above commodity saline.
Supply Chain Analysis
Plasma fractionation feedstock rests on captive collection infrastructure concentrated in the United States, Australia, and Germany, with CSL and Grifols maintaining upstream control over source material. Bovine collagen for gelatin polymers and synthetic polymer precursors for crystalloid packaging represent secondary input dependencies. Single-source vulnerability in plasma collection creates geographic concentration risk should donor recruitment face disruption. Distribution runs through integrated delivery networks and group purchasing organizations that consolidate formulary contracts across multi-hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic polymer chemistry is displacing starch-based colloids as the dominant fluid resuscitation technology, with gelatin formulations and balanced crystalloids capturing procurement share previously held by hydroxyethyl starch products facing regulatory suspension.
For Market Incumbents: To counter synthetic colloid commoditization, CSL Limited and Grifols must deepen captive plasma collection infrastructure in Australia and the United States to secure fractionation feedstock. Baxter International should expand device-solution bundling in cardiac surgery suites where hemodynamic monitoring integration preserves premium positioning against unbundled competitors.
For New Entrants and Emerging Players: Pediatric emergency departments present the most penetrable buyer archetype as intraosseous delivery protocols formalize across military and civilian trauma networks. Local manufacturers in Maharashtra and Karnataka under India's PLI scheme can capture crystalloid share from multinational incumbents by aligning CDSCO production with WHO prequalification pathways for essential medicines.
For Investors and Strategic Acquirers: Exit pathways concentrate in synthetic polymer specialists with EMA MDR documentation packages that accelerate hospital formulary access. Long-term viability hinges on formulation diversification beyond starch dependencies. The signal to watch is FDA hemostatic safety threshold recalibration for remaining colloid categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Gelatin Polymer Reformulation | EMA REACH compliance for residual aldehyde elimination secures European formulary access. |
| Intraosseous Delivery Partnership | Military medical logistics adoption creates device-fluid bundling opportunities in combat support hospitals. |
| India PLI Manufacturing Scale-Up | CDSCO-aligned crystalloid production captures regional procurement from import-dependent hospital systems. |
| Perioperative Monitoring Integration | Algorithm-compatible colloid titration protocols embed solutions into cardiac surgery workflows. |
| Lyophilized Format Development | Freeze-dried albumin stability enables disaster preparedness stockpiling without cold chain dependency. |
Study Parameters
Independent corroboration across hospital procurement managers, perfusion technology specialists, and plasma fractionation executives underwrites the qualitative findings. Primary interviews with formulary directors at academic medical centers in Massachusetts and California, emergency department chiefs in Texas trauma networks, and regulatory affairs leads at EMA-notified bodies combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, and hospital GPO contract databases. Bottom-up volume modeling across administration routes and top-down market sizing triangulate to consistent outputs.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects in colloid versus crystalloid procurement. Segmentation dimensions modeled include product type, administration route, end-user facility tier, and regional regulatory cluster. CAGRs derive from surgical volume projections, trauma protocol standardization rates, and formulation substitution elasticities where starch restrictions redirect demand toward gelatin alternatives.
Revisions become necessary when FDA hemostatic safety thresholds shift, EMA MDR enforcement intensity changes, or plasma collection economics disrupt fractionation output assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Sterilization Box Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Surgical Tapes Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
Safety Box for Syringe Market
Medical Supplies
Latin America Incontinence Pads Market
Medical Supplies
Intranasal Splints Market
Medical Supplies
Ostomy Care and Accessories Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Global Lancets Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Polymer Exam Gloves Market
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Nasal Splints Market