
 Medical Disposables Market | 2026-2036
Medical Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Disposables Market Intelligence
The growing divide between specialized, high-margin products and high-volume, low-cost consumables is realigning the competitive landscape. BD leverages its technology leadership in complex drug delivery systems. Medline Industries competes on logistical efficiency and broad portfolio management for hospital systems, while 3M differentiates through material science innovation in wound dressings.
Medical disposables are single-use healthcare products designed to prevent cross-contamination and ensure patient safety. They are often manufactured from medical-grade plastics and sterilized using methods like ethylene oxide. Catheters and advanced wound dressings represent high-value product segments. The hospital end-user segment remains the largest volume purchaser, but homecare represents the fastest-growing area for specific product lines like IV sets.
Market access is governed by stringent regulatory frameworks. In the United States, the FDA's 510(k) pathway is critical for device clearance, while the EU's Medical Device Regulation (MDR) imposes stricter clinical evidence requirements. China's NMPA also has its own distinct approval process. Stakeholder success will depend on managing supply chain resilience against geopolitical disruptions and shifting material costs.
Market Dynamics
The decentralization of healthcare delivery from large hospitals to ambulatory and homecare settings is the central force reconfiguring demand patterns. This shift necessitates new product formats, packaging, and logistical capabilities to serve a more distributed patient population effectively.
Growth Catalysts
- Stricter Regulatory Mandates:The European Union's Medical Device Regulation (MDR) elevates clinical evidence and post-market surveillance requirements, pushing manufacturers toward higher-quality, safer products and creating barriers for non-compliant competitors.
- Demographic Shifts in Asia:China's rapidly aging population and expanding public health insurance coverage create sustained volume demand for a wide range of disposables, from basic consumables to more advanced catheters.
- Homecare Segment Expansion:The increasing prevalence of chronic disease management outside of traditional hospital settings accelerates adoption of specific product lines, such as infusion therapy sets and disposable diagnostic test kits for home use.
Market Restraints
- Raw Material Price Volatility:Fluctuation in the cost of petroleum-derived polymers and specialized resins directly impacts the manufacturing cost structure for products like syringes and IV bags, compressing margins for volume-based suppliers.
- Complex Regulatory Pathways:Navigating the FDA's 510(k) premarket notification process in the United States requires significant investment in testing and documentation, creating a substantial barrier to entry for new or smaller device makers.
- Sterilization Process Bottlenecks:Reliance on specific sterilization methods like ethylene oxide (EtO) creates supply chain vulnerabilities, as capacity is limited and subject to increasing environmental scrutiny and regulation from agencies like the EPA.
Strategic Opportunities
- Sustainable Material Development:There is a significant opportunity in developing and commercializing medical-grade bioplastics or recyclable polymers that reduce the environmental footprint of single-use products without compromising patient safety or clinical performance.
- Smart Device Integration:Integrating low-cost sensors into disposables like catheters or wound dressings enables real-time data collection, converging with digital health platforms to improve patient monitoring and clinical outcomes.
- Emerging Market Infrastructure:Building out distribution networks and local manufacturing capabilities in underpenetrated regions, such as Southeast Asia and Latin America, can capture growth as their healthcare systems modernize.
Industry Challenges
- Global Supply Chain Resilience:Manufacturers face the operational challenge of redesigning supply chains to mitigate risks from geopolitical tensions, trade restrictions, and logistical disruptions that can halt the flow of critical components or finished goods.
- Multi-Jurisdictional Compliance:The burden of maintaining concurrent compliance with disparate regulatory frameworks from the FDA, EU MDR, and China's NMPA requires extensive and specialized regulatory affairs teams, increasing overhead costs.
- Aseptic Manufacturing Capacity:Expanding sterile production capacity for injectables and other sensitive disposables is capital-intensive and requires a highly skilled workforce, presenting a significant hurdle to scaling operations quickly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Disposables Market |
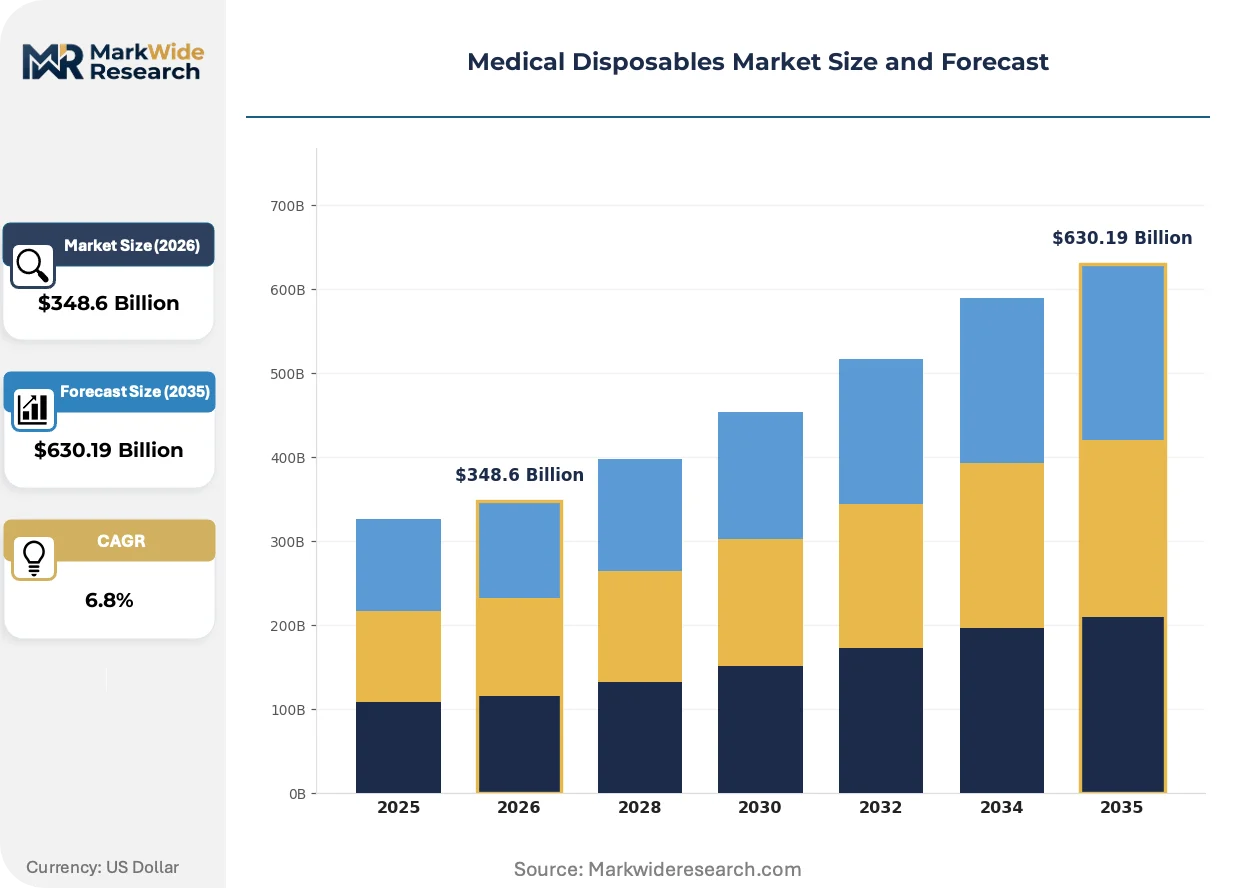
| Market Size in 2026 | $348.6 Billion |
| Market Size in 2035 | $630.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Catheters, IV Sets, Wound Dressings End User: Hospitals, Clinics, Homecare, Laboratories Material: Plastic, Paper, Cotton, Composite Application: Infection Control, Surgical Procedures, Diagnostics, Drug Delivery |
| Companies Covered | Medline Industries, Inc., Cardinal Health, 3M, BD, Smith+Nephew, Owens & Minor, Molnlycke Health Care, B. Braun Melsungen AG, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Disposables Market Strategic Shifts & Innovations
Innovation in the medical disposables market is driven by the twin demands for enhanced clinical functionality and greater environmental sustainability. Material science advancements are at the forefront, enabling products that reduce infection risk while addressing end-of-life disposal concerns.
Advanced polymer composites incorporating antimicrobial agents are being designed for high-contact devices like catheters and wound care products. Hospitals and ambulatory surgery centers are the primary adopters, driven by the need to combat hospital-acquired infections (HAIs). This focus on clinical outcomes means material science innovation is overtaking traditional cost-per-unit metrics as a primary purchasing driver for high-risk applications.
The European Union’s Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence and post-market surveillance. This action increases the time and expense of bringing a product to market, favoring established manufacturers with deep regulatory expertise. High-value segments such as advanced wound dressings and implantable-related disposables are most affected, as their performance claims now require extensive clinical data validation.
A definitive shift toward value-based purchasing is altering how hospital systems assess disposable products. This model expands evaluation beyond unit price to encompass the total cost of care, factoring in benefits like reduced infection rates or shorter patient stays. The trend is most visible within large integrated delivery networks (IDNs) in the United States, where financial reimbursements are increasingly linked to patient outcomes.
Medical Disposables Market Segmentation
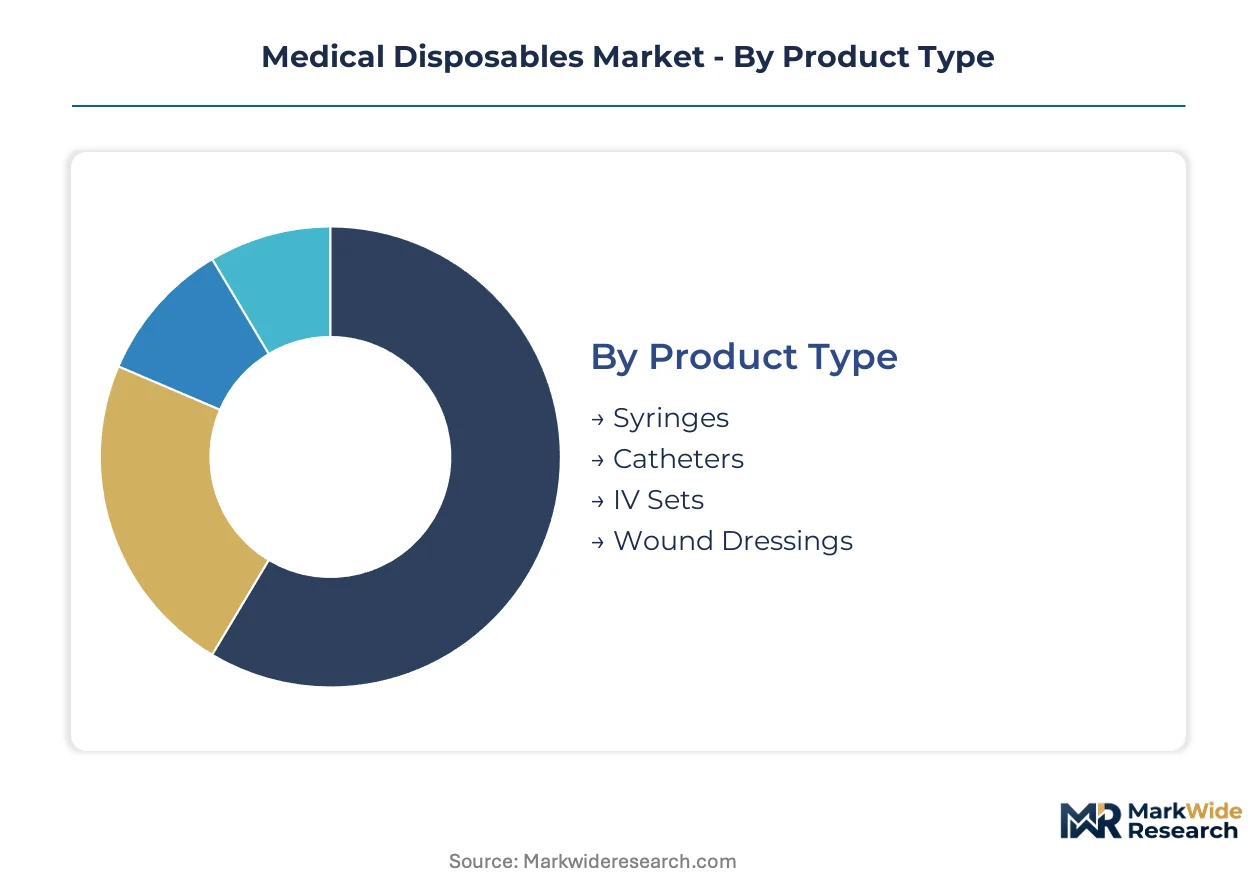
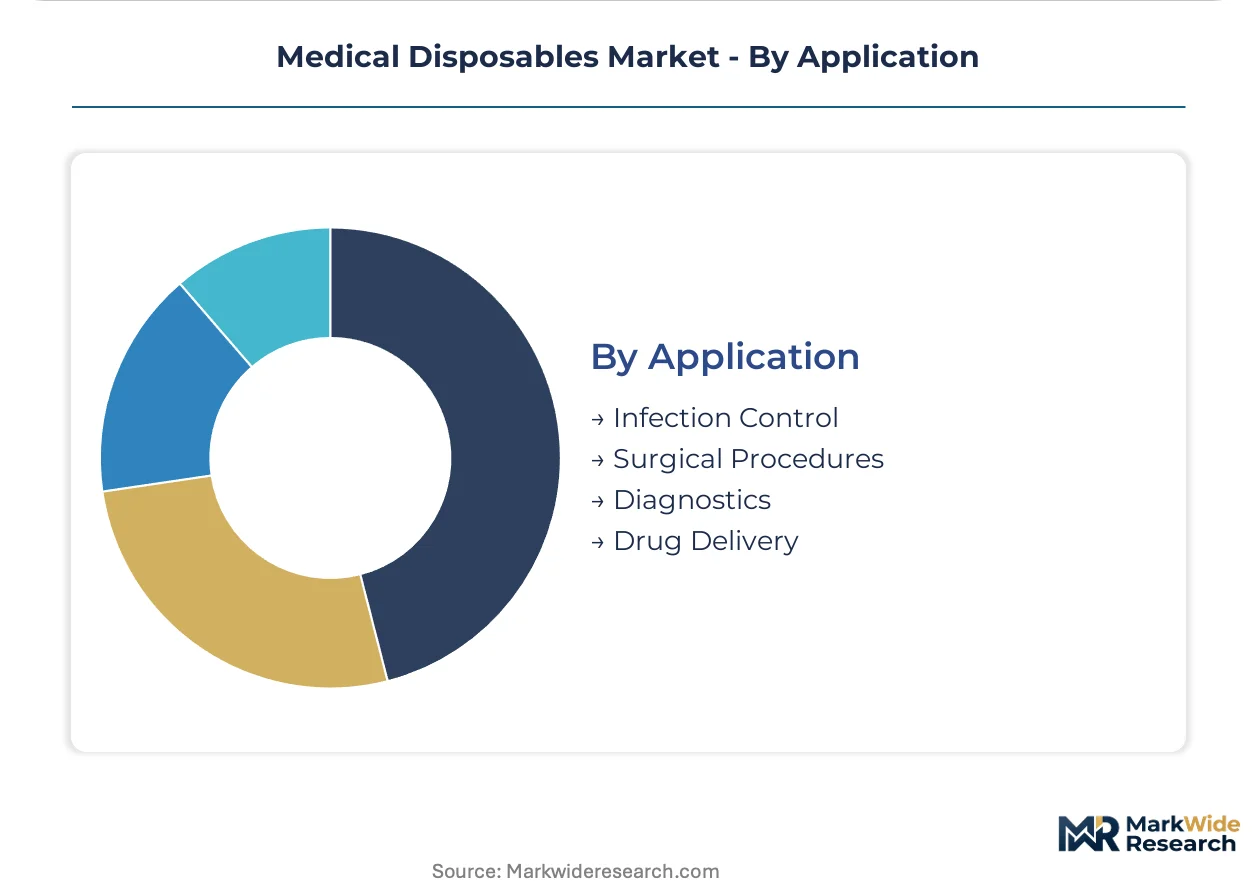
The Medical Disposables Market exhibits diverse demand patterns driven by evolving healthcare delivery models and clinical needs. Understanding these segments enables manufacturers to align product development with specific end-user requirements and regulatory environments.
Product Type:
The product type segmentation highlights the tension between high-volume, low-cost consumables and specialized, premium devices. Volume dictates manufacturing scale, while complexity drives margin potential.
- Syringes:These sterile, single-use devices deliver injections and draw fluids. Standardized designs and high production volumes characterize the global syringe market, with demand concentrated in public health programs across India and Southeast Asia.
- Catheters:These flexible tubes are inserted into body cavities for fluid management or access. Advanced catheter designs incorporate antimicrobial coatings, with demand rising in interventional cardiology procedures in Germany and the United States.
- IV Sets:Intravenous administration sets deliver fluids and medication. Their design prioritizes ease of use and sterility for hospital and expanding homecare settings.
- Wound Dressings:These products protect wounds and promote healing, ranging from basic bandages to advanced hydrocolloids. Innovation in advanced wound dressings for chronic wounds is a key focus for manufacturers serving European clinics.
Today's leader: Catheters. Tomorrow's challenger: Wound Dressings.
End User:
End-user segmentation reveals how different healthcare settings influence product design and logistical requirements. Procurement patterns vary significantly across institutional and decentralized care models.
- Hospitals:Large acute care facilities represent the primary volume purchasers, requiring bulk quantities and diverse product lines. Centralized procurement systems in US hospital networks prioritize cost-efficiency and supply chain reliability.
- Clinics:These outpatient facilities and specialized practices demand disposables tailored for specific procedures, often requiring smaller pack sizes.
- Homecare:This segment encompasses products used in patient homes, driven by chronic disease management and post-acute care. Products for homecare necessitate user-friendly designs and robust remote support, expanding most quickly in Japan and Australia.
- Laboratories:Medical testing laboratories utilize disposables for sample collection, processing, and analysis, including test tubes and pipettes.
The largest volume purchaser remains Hospitals, while Homecare exhibits the steepest expansion trajectory.
Material:
Material composition directly impacts product performance, sterilization methods, and environmental footprint. Innovations in material science increasingly focus on sustainability and enhanced clinical properties.
- Plastic:Petroleum-derived polymers like polypropylene and PVC form the backbone of most medical disposables, offering cost-effectiveness. The challenge for plastic disposables involves managing raw material price volatility and end-of-life waste, particularly in China's rapidly expanding healthcare sector.
- Paper:Used primarily for packaging and drapes, paper disposables offer biodegradability and cost advantages for non-critical applications.
- Cotton:Natural fibers like cotton are essential for absorbent products such as gauze and swabs, valued for their softness and absorbency.
- Composite:These materials combine different substances to achieve superior properties, such as enhanced strength or antimicrobial characteristics. Advanced composites are increasingly used in complex wound dressings and surgical implants, driving product differentiation in European markets.
Plastic material dominates current production, but Composite materials are gaining significant traction for high-value applications.
Application:
Application-based segmentation highlights the specific clinical purpose and functional requirements of medical disposables. Each application demands tailored product features and regulatory compliance.
- Infection Control:This segment includes products designed to prevent pathogen spread, such as gloves, masks, and sterile drapes. Stricter mandates from agencies like the FDA and Europe's EMA drive demand for high-grade infection control products.
- Surgical Procedures:Disposables for surgery encompass instruments, drapes, and sutures, critical for maintaining sterility and efficiency in operating rooms.
- Diagnostics:Diagnostic applications utilize disposables for sample collection, testing, and analysis, including blood collection tubes and rapid test kits. The expansion of point-of-care testing in Canada increases demand.
- Drug Delivery:Products like syringes, IV sets, and specialized infusion devices facilitate medication administration. Innovation focuses on precision dosing and patient comfort for chronic disease management.
Infection Control remains a foundational application, while Drug Delivery applications are climbing the fastest in innovation and adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly specialized engineering and medical workforce underpins innovation and demand for medical disposables in several regions. These concentrations drive localized product development and adoption of advanced healthcare solutions. Regulatory harmonization efforts also influence market access and product evolution.
United States
The United States market sees sustained demand from chronic disease management and complex interventional cardiology procedures. The FDA's 510(k) premarket notification process governs medical device clearance. Boston's medical device cluster consistently drives innovation for advanced catheters and wound dressings.
Germany
Germany's market for medical disposables focuses on sophisticated products for an aging population and advanced wound care. The EU's Medical Device Regulation (MDR) sets stringent requirements for product quality and clinical evidence. Medical technology firms in Bavaria specialize in developing composite materials for surgical implants.
China
China's expanding healthcare infrastructure and rapidly aging population create substantial volume demand for medical disposables. The NMPA's distinct approval process shapes market entry and product localization strategies. Manufacturing hubs in the Yangtze River Delta scale production for basic consumables like syringes and IV sets.
Japan
Japan's rapidly aging population and significant homecare segment expansion drive demand for user-friendly disposables. The PMDA's regulatory framework ensures high standards for medical device safety and efficacy. Research centers in the Kanto region develop smart device integration for patient monitoring.
India
India's growing healthcare access and extensive public health programs generate considerable demand for high-volume consumables. The CDSCO's medical device rules govern manufacturing and import standards. Production facilities in Gujarat and Maharashtra scale output to meet domestic requirements.
Medical Disposables Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the medical disposables market, creating a tiered competitive structure. The landscape features a mix of large diversified conglomerates alongside specialized niche players, contributing to both consolidation in core segments and fragmentation in emerging areas. Strategic archetypes include technology innovators focusing on high-value products, volume manufacturers emphasizing cost-efficiency, and logistics-focused distributors managing broad portfolios. Dominant competitive moves involve strategic partnerships for market access and continuous portfolio diversification to capture new end-user segments.
At the scale-driven end, Medline Industries, Inc. exemplifies a logistics-focused distributor, managing extensive product portfolios for hospital systems. Germany-based B. Braun Melsungen AG represents a diversified technology leader, occupying a position in complex drug delivery systems and surgical disposables. 3M, known for its material science innovation, anchors the advanced wound dressings segment. These entities illustrate the varied strategies employed to secure market share across different product types and end-user segments.
| Leading Market Players |
|---|
| Medline Industries, Inc. |
| Cardinal Health |
| 3M |
| BD |
| Smith+Nephew |
| Owens & Minor |
| Molnlycke Health Care |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap producers like B. Braun Melsungen AG maintain pricing discipline through specialized product portfolios. Their controlled supply chains enable consistent quality and cost management, influencing market stability.
Pricing Analysis
Bundled service contracts for hospital systems often integrate medical disposables, favoring long-term, contract-based pricing models. Price differentiation stems from product quality grades, stringent regulatory certifications like the EU MDR, and volume scale. Pricing softness runs through basic consumables due to intense competition and raw material cost fluctuations. Hospitals prioritize total cost of care for advanced wound dressings, while public health programs in India remain highly price-sensitive for syringes.
Supply Chain Analysis
Stringent certification and qualification processes, particularly for products cleared via the FDA's 510(k) pathway, gate entry into medical disposables supply chains. Production concentrates significantly in China for basic consumables and in Germany for advanced composite materials. The industry relies heavily on petroleum-derived polymers and specialized resins, creating commodity price volatility risk. Distribution runs through large hospital group purchasing organizations and specialized medical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical disposables market operates as a regulatory compounder, where new mandates like the EU's Medical Device Regulation (MDR) drive demand for higher quality, compliant products. This framework accelerates innovation while also creating barriers to entry.
For Market Incumbents: Acquire specialized regulatory expertise and advanced material science firms to counter rising compliance costs and margin pressure from new regulations. Deepen vertical integration into medical-grade polymer production to stabilize input costs and ensure supply chain resilience. Invest in expanding sterile manufacturing capacity in strategic regions like the United States to mitigate geopolitical disruptions.
For New Entrants and Emerging Players: Price-point gaps between premium advanced wound dressings and basic bandages offer white space for innovative mid-tier products. Target the expanding homecare segment in Japan and Australia with user-friendly, disposable diagnostic kits. Focus on sustainable material development for high-volume consumables, leveraging environmental differentiation as a go-to-market strategy.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized manufacturers specializing in high-volume, basic consumables, presenting long-term viability for consolidation plays. Target companies with strong distribution networks in underpenetrated emerging markets like Southeast Asia. Watch for shifts in global sterilization regulations from agencies like the EPA, as this could signal capacity rationalization or technology adoption opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance Biocompatible Material R&D | Develop next-generation polymers for catheters, reducing infection risk in hospital settings. |
| Expand Homecare Logistical Capabilities | Improve direct-to-patient delivery for IV sets, supporting decentralized healthcare models. |
| Invest in Advanced Sterilization Technologies | Diversify beyond ethylene oxide, mitigating regulatory scrutiny from the EPA. |
| Pursue NMPA Approvals in China | Access substantial volume demand from China's expanding healthcare infrastructure. |
| Form GPO Partnerships | Secure long-term contracts with US hospital networks, ensuring stable demand for disposables. |
Research Approach
Bottom-up end-user segment modeling reconciled against top-down manufacturer supply-side tracking forms the analytical core of this study. Primary interviews with clinicians, hospital purchasing committees, and regulatory affairs leads informed qualitative insights. Secondary validation drew from FDA filings, EU MDR guidance documents, and GPO contract databases. This approach ensures robust triangulation of market dynamics and forecast assumptions.
Historical trendline analysis and regression modeling established baseline growth rates across the analysis window. The framework segmented the market by product type, end-user, material, application, and regional regulatory environment. Compound Annual Growth Rates were derived from volume and value projections, incorporating demographic shifts and chronic disease prevalence as key inputs.
Caveats apply where unforeseen geopolitical disruptions or rapid technological advancements in sterilization methods could materially shift the outlook. Forecasts reflect current regulatory landscapes and known pipeline developments. A model refresh is warranted upon material change in global trade policies or significant raw material supply shocks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
US Hospital Gowns Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Hemodialysis Consumables Market
Medical Supplies
Swab Cups Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Single-Use Syringe Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Global Respiratory and Anesthesia Disposables Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Fibrin Sealants Market
Medical Supplies
Abdominal Compression Garments Market
Medical Supplies
Luer Plug Market
Medical Supplies
Cataract Disposable Products Market