
 Saudi Arabia Medical Bandages Market | 2026-2036
Saudi Arabia Medical Bandages Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Medical Bandages Market Insights
Modular dressing kits is pivoting how Saudi hospital procurement teams evaluate bandage suppliers, bundling antimicrobial layers with adjustable compression wraps in single SKUs. Smith & Nephew plc leverages its hydrocolloid technology leadership to anchor premium contracts with Ministry of Health facilities. Medline Industries, Inc. competes through distribution scale, sustaining same-day replenishment across the Kingdom's central hospital zones. Cardinal Health differentiates via private-label elastic bandage lines that occupy mid-tier price positions in clinic channels.
Medical bandages are sterile or non-sterile flexible materials applied to wounds to protect tissue, absorb exudate, and maintain moist healing environments, typically manufactured through needle-punch nonwoven bonding or woven cotton gauze finishing with hypoallergenic adhesive coating. Their primary commercial purpose spans acute wound management, post-operative incision coverage, and chronic ulcer treatment in institutional and home settings. Adhesive bandages lead product type revenue due to high turnover in primary care, while hydrocolloid bandages represent the fastest-expanding category as diabetic foot clinics adopt moisture-retentive protocols. Cotton dominates material volume for cost-sensitive bulk purchasing, though silicone interfaces command margin pools in burn and pediatric applications where trauma-free removal is prioritized.
SFDA mandates biocompatibility testing and ISO 13485 quality system certification for all medical bandage registrations, while Saudi Vision 2030 localization incentives require increasing domestic production share to qualify for government procurement preference. These frameworks shape demand by elevating compliance costs for import-dependent distributors and redirecting capital toward in-country manufacturing partnerships. Stakeholders must monitor how SFDA's alignment with EU MDR technical documentation standards will reshape supplier qualification timelines and local joint-venture requirements.
Market Dynamics
Modular dressing kits are consolidating procurement decisions across Saudi Arabia's hospital networks, bundling previously separate antimicrobial and compression components into single-vendor contracts that reshape supplier relationships.
Growth Catalysts
- SFDA Localization Mandates:Saudi Vision 2030 incentives require domestic production share thresholds for government procurement preference, redirecting capital toward in-country manufacturing partnerships.
- Diabetic Foot Clinic Expansion:Moisture-retentive hydrocolloid protocols are displacing traditional gauze in specialized wound care units, creating demand for advanced dressing categories.
- Riyadh-Jeddah Hospital Cluster Concentration:Tertiary facility procurement volume in these metropolitan zones generates economies of scale that attract premium supplier investment.
Market Restraints
- Silicone Raw Material Volatility:Pediatric and burn applications depend on trauma-free silicone interfaces, where petrochemical feedstock price swings compress margin pools for specialized manufacturers.
- Import Dependency Concentration:European and North American suppliers dominate ISO 13485-certified production, exposing distributors to currency fluctuation and extended lead times.
- SFDA-EU MDR Alignment Friction:Technical documentation standard upgrades are extending registration timelines for new market entrants, creating compliance bottlenecks.
Strategic Opportunities
- Eastern Province Undersupply:Dammam and Khobar medical infrastructure expansion lags Riyadh-Jeddah concentration, creating whitespace for distribution network extension.
- Home Care Channel Emergence:Post-acute wound management is migrating from hospital discharge to retail pharmacy and direct-to-patient channels, unbundling institutional procurement.
- Antimicrobial-Compression Convergence:Silver-impregnated layers integrated with adjustable compression wraps enable premium SKU positioning beyond commodity gauze segments.
Industry Challenges
- Biocompatibility Testing Bottlenecks:SFDA-mandated ISO 10993 cytotoxicity and sensitization protocols require 12-18 month validation cycles that delay product launches.
- Legacy ERP Integration Friction:Hospital procurement systems built on decade-old platforms resist API connectivity with supplier inventory management tools, forcing manual reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Medical Bandages Market |
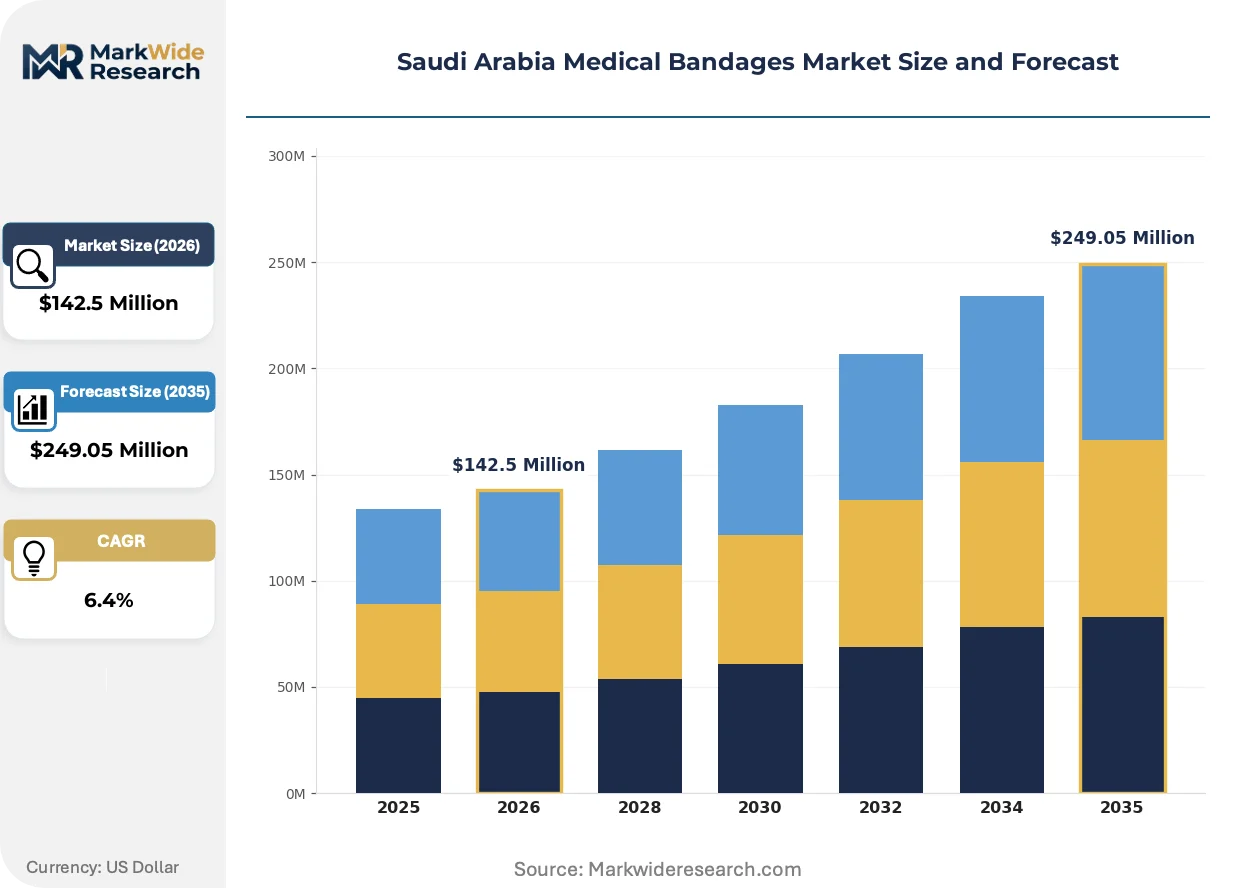
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $249.05 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Bandages, Compression Bandages, Hydrocolloid Bandages, Elastic Bandages Material: Cotton, Non-woven Fabric, Silicone, Foam End User: Hospitals, Clinics, Home Care, Specialty Stores Application: Wound Care, Sports Injury, Surgical Recovery, Burn Treatment |
| Companies Covered | The National Medical Products Co., Ltd. (Damad), Smith & Nephew plc, The 3M Company, Medline Industries, Inc., Medtronic plc, Dukal Corporation, DeRoyal Industries, Inc., Cardinal Health, NICHIBAN Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Medical Bandages Market Trends and Innovations
Active materials and smart packaging are redefining wound care efficacy standards, while regulatory harmonization and procurement centralization compress competitive timelines across the Kingdom.
Antimicrobial silver nanocrystal coatings are decentralizing infection control responsibility from centralized pharmacy oversight to point-of-care nursing staff in Saudi tertiary hospitals. Ward-level dressing selection authority is expanding as these materials demonstrate sustained release profiles against resistant bacterial strains. This capability transfer is compressing formulary committee influence over supplier selection.
SFDA's phased alignment with EU MDR technical documentation standards is elevating clinical evidence requirements for hydrocolloid and alginate dressing registrations. Local joint-venture partners must now maintain quality system documentation equivalent to notified body oversight. Ministry of Health facilities are responding by consolidating supplier panels to entities with established MDR compliance infrastructure.
Consignment inventory arrangements are displacing traditional purchase-order cycles in Jeddah's private hospital networks, transferring working capital burden from buyers to suppliers. Distributors now maintain floor-stock minimums with automated replenishment triggers tied to consumption data. This pattern is most visible in orthopedic and surgical wards where SKU variety complicates demand forecasting.
Saudi Arabia Medical Bandages Market Segmentation
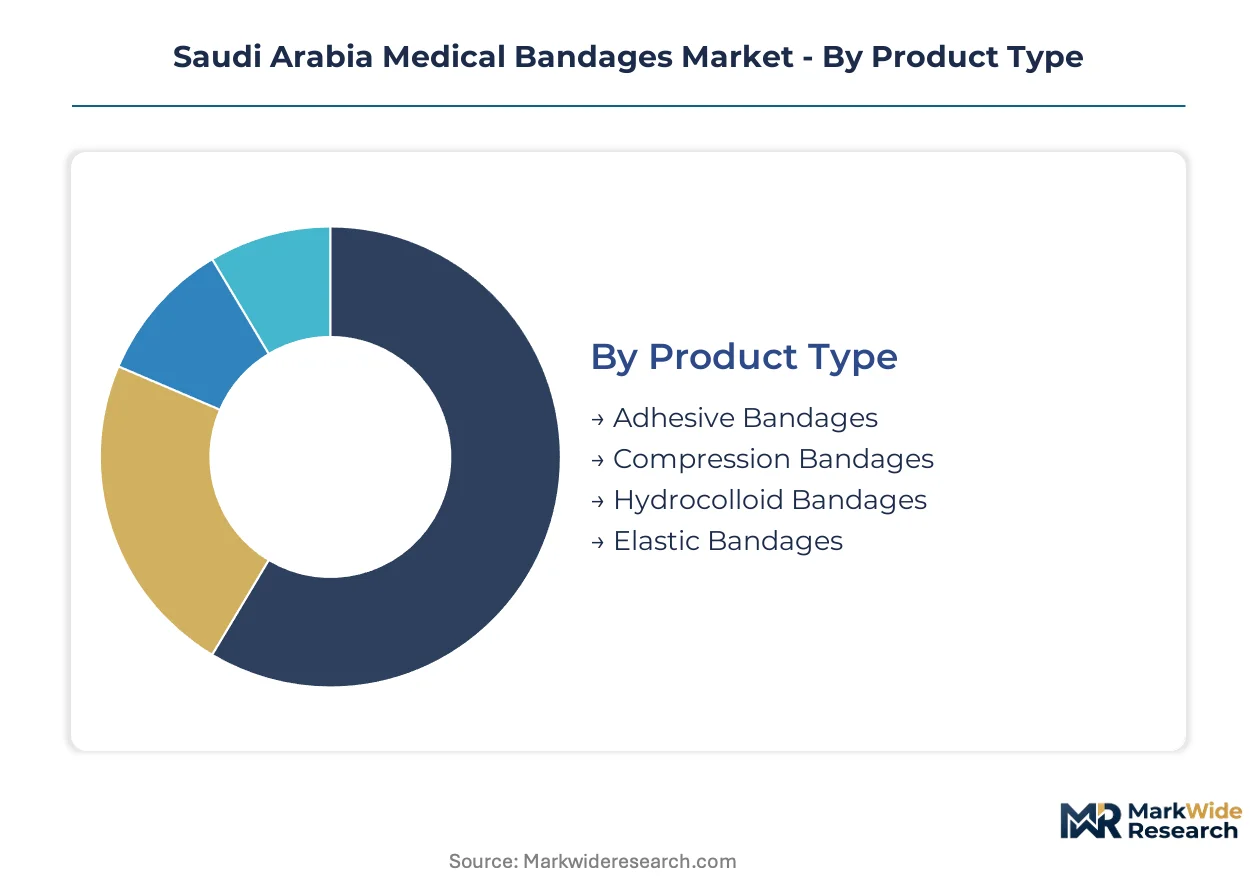
Procurement teams in Saudi Arabia's medical bandage market evaluate suppliers across four intersecting dimensions. Product type determines clinical protocol compatibility, while material selection governs reimbursement eligibility and margin structure.
Product Type:
Hospital procurement committees prioritize turnover velocity and shelf-life stability when selecting bandage categories for formulary inclusion.
- Adhesive Bandages:Hypoallergenic adhesive strips with absorbent nonwoven pads dominate primary care and emergency department consumption. Riyadh's Ministry of Health facilities drive volume through standardized procurement of sterile adhesive strips for outpatient wound closure.
- Hydrocolloid Bandages:Gel-forming polymers maintain moist wound environments that accelerate diabetic ulcer healing. Jeddah's specialized wound care centers are expanding formulary access for moisture-retentive protocols in chronic care units.
- Compression Bandages:Multi-layer elastic systems manage venous insufficiency and lymphedema through graduated pressure application. Demand concentrates in vascular surgery departments at tertiary facilities.
- Elastic Bandages:Woven cotton-spandex blends provide adjustable support for sprains and soft tissue injuries. Retail pharmacy channels stock these for post-discharge patient self-management.
Volume sits with adhesive bandages; growth tilts toward hydrocolloid bandages.
Material:
Raw material selection directly shapes SFDA registration pathways and sterilization validation requirements.
- Cotton:Bleached woven gauze remains the cost baseline for bulk institutional purchasing. Saudi Vision 2030 localization incentives favor domestic cotton processing partnerships.
- Silicone:Soft silicone interfaces enable atraumatic removal for pediatric and burn applications. Petrochemical feedstock volatility compresses margin stability for specialized manufacturers.
- Non-woven Fabric:Needle-punched synthetic webs offer superior fluid absorption and bacterial barrier properties. SFDA biocompatibility testing mandates extend registration timelines for novel nonwoven substrates.
- Foam:Polyurethane foam dressings cushion high-exudate wounds while maintaining thermal insulation. Home care channel expansion is broadening retail distribution for foam-based products.
Cotton absorbs the procurement volume; silicone commands the premium tier expansion.
End User:
Channel structure determines packaging specifications, replenishment frequency, and regulatory documentation depth.
- Hospitals:Tertiary facilities in Riyadh and Jeddah consolidate procurement through centralized supply chains with automated inventory triggers.
- Clinics:Primary care centers prioritize cost-efficient bulk purchasing of standardized adhesive and elastic bandage formats.
- Home Care:Post-acute wound management is migrating from institutional discharge to direct-to-patient delivery models.
- Specialty Stores:Orthopedic and medical supply retailers stock premium compression and silicone products for cash-pay consumers.
Hospitals anchor the volume base; home care is gaining share fastest.
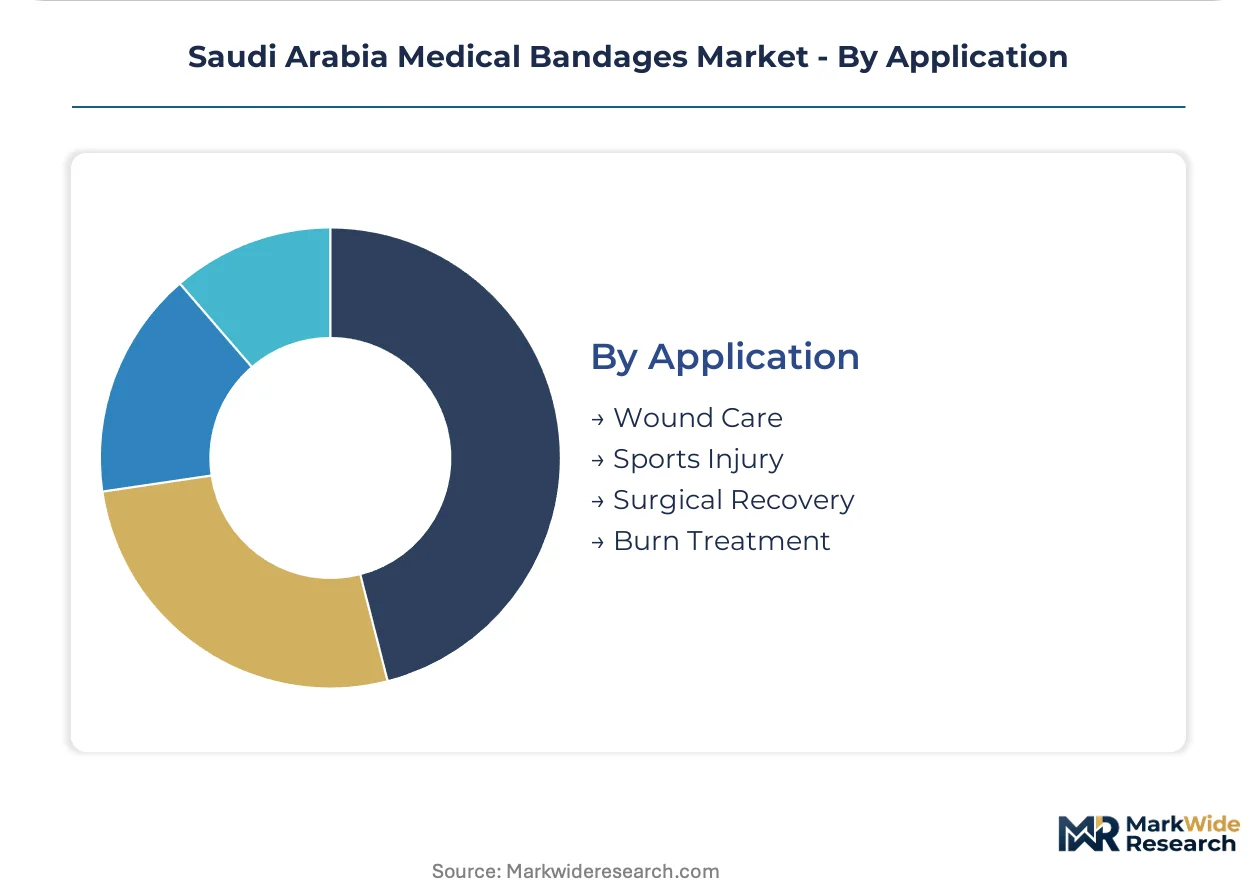
Application:
Clinical indication dictates performance specifications and reimbursement coding alignment.
- Wound Care:Chronic ulcer management protocols specify moisture-retentive dressings with antimicrobial silver integration.
- Sports Injury:Athletic programs and physiotherapy centers demand reusable compression wraps with adjustable tension mechanisms.
- Surgical Recovery:Post-operative incision coverage requires sterile barrier properties and exudate absorption capacity.
- Burn Treatment:Specialized burn centers in Riyadh specify silicone-coated dressings that minimize trauma during dressing changes.
Wound care holds the installed base; burn treatment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City and other special economic zones are concentrating medical device manufacturing incentives, drawing joint-venture partners toward Red Sea coastal infrastructure. Riyadh-Jeddah hospital clusters absorb the majority of advanced wound care procurement volume. SFDA regulatory harmonization with EU MDR standards is reshaping supplier qualification timelines across all zones.
Riyadh
Tertiary hospital networks and specialized burn centers drive demand for silicone-coated and hydrocolloid dressings. Saudi Vision 2030 healthcare privatization mandates are transferring Ministry of Health procurement to independent hospital groups. King Faisal Specialist Hospital anchors premium supplier relationships through centralized formulary committees.
Eastern Province
Dammam and Khobar medical infrastructure expansion lags the central corridor, creating distribution whitespace for elastic bandage and compression product lines. Aramco healthcare facilities and private hospital construction are accelerating procurement volume. The Dammam industrial zone hosts emerging domestic cotton processing partnerships qualifying for localization incentives.
Western Region
Jeddah's private hospital networks pioneer consignment inventory arrangements with automated replenishment triggers. King Abdullah Medical City and private orthopedic centers concentrate demand for post-operative and sports injury applications. The Jeddah Islamic Port facilitates import logistics for European and North American suppliers.
NEOM Northwest
The linear city project incorporates advanced healthcare infrastructure planning with built-in wound care protocol standardization. Regulatory sandbox provisions may accelerate SFDA registration pathways for novel antimicrobial dressing technologies. Remote location challenges are stimulating interest in modular dressing kit formats with extended shelf stability.
Saudi Arabia Medical Bandages Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated structure where scale-driven distributors battle technology-led manufacturers for hospital formulary access. The vendor base separates into three strategic archetypes: multinational device conglomerates with broad wound care portfolios, regional distribution specialists leveraging logistics scale, and domestic joint-venture entities capturing localization preference. M&A activity concentrates on acquiring SFDA registration assets and established hospital relationships. Strategic partnerships between international technology holders and Saudi manufacturing licensees are displacing direct import models.
Within the multinational technology tier, Smith & Nephew plc and 3M Company exemplify premium positioning through hydrocolloid and advanced adhesive platforms. Medline Industries, Inc. occupies the distribution-scale archetype, anchoring same-day replenishment capabilities across central hospital zones. The National Medical Products Co., Ltd. (Damad) represents the domestic joint-venture model, leveraging in-country production to qualify for government procurement preference under Saudi Vision 2030 localization thresholds.
| Leading Market Players |
|---|
| The National Medical Products Co., Ltd. (Damad) |
| Smith & Nephew plc |
| The 3M Company |
| Medline Industries, Inc. |
| Medtronic plc |
| Dukal Corporation |
| DeRoyal Industries, Inc. |
| Cardinal Health |
| NICHIBAN Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
SFDA localization mandates under Saudi Vision 2030 are compressing procurement timelines for advanced wound care dressings, forcing distributors to absorb inventory carrying costs or cede share to domestic joint-venture partners with in-country production capabilities. This demand-side restructuring elevates working capital requirements while narrowing margin pools for import-dependent suppliers.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Jeddah private hospitals demand same-day replenishment for orthopedic and surgical ward SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification tier and antimicrobial technology integration, with hydrocolloid platforms commanding widest spreads. Cost compression in cotton gauze segments is intensifying because Saudi Vision 2030 localization incentives redirect volume toward domestic cotton processing partnerships. Retail pharmacy channels exhibit highest price sensitivity due to patient out-of-pocket exposure, while tertiary burn centers prioritize trauma-free silicone interfaces regardless of unit cost.
Supply Chain Analysis
SFDA domestic-content thresholds are reshaping sourcing patterns, compelling European and North American technology holders to establish Saudi manufacturing licenses rather than direct export models. Raw material flows draw from Egyptian long-staple cotton, German silicone petrochemical feedstocks, and Chinese needle-punched nonwoven substrates. Single-source vulnerability concentrates in ISO 10993 biocompatibility testing capacity, where extended validation cycles create bottlenecks for novel material introductions. Distribution runs through Riyadh-Jeddah hospital cluster hubs with automated consignment inventory triggers, while Eastern Province expansion lags create fulfillment gaps for Dammam and Khobar facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi medical bandage market sits in a technology-transition phase as moisture-retentive hydrocolloid protocols displace traditional gauze in diabetic foot clinics and specialized wound care units.
For Market Incumbents: Cement formulary committee relationships through bundled antimicrobial-compression SKUs that reduce procurement touchpoints for Ministry of Health facilities. Expand backward integration into domestic cotton processing partnerships to capture Saudi Vision 2030 localization preference thresholds. Prioritize MDR compliance infrastructure investment as SFDA-EU alignment elevates clinical evidence requirements for advanced dressing registrations. For New Entrants and Emerging Players: The price-point gap between premium silicone-coated dressings and economy cotton gauze creates whitespace for mid-tier foam-based products with antimicrobial integration. Target Eastern Province distribution network extension where Dammam and Khobar medical infrastructure expansion outpaces established supplier coverage. Pursue direct-to-patient home care channel partnerships as post-acute wound management migrates from hospital discharge to retail pharmacy and e-commerce platforms. For Investors and Strategic Acquirers: Re-rating potential sits with domestic joint-venture entities holding established SFDA registration assets and government procurement relationships given accelerating localization mandate enforcement. Long-term viability across the analysis window favors manufacturers with captive supply of biocompatible materials and quality system documentation equivalent to notified body oversight. Monitor King Abdullah Economic City special economic zone manufacturing incentive announcements as inflection indicators for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Asset Acquisition | Established registration timelines compress competitive entry for hydrocolloid and alginate categories. |
| Domestic Cotton Processing Partnership | Saudi Vision 2030 localization thresholds qualify suppliers for Ministry of Health procurement preference. |
| Consignment Inventory Arrangement | Jeddah private hospital networks transfer working capital burden from buyers to distributors with automated replenishment. |
| Antimicrobial-Compression SKU Bundling | Modular dressing kits reduce procurement committee touchpoints while commanding premium positioning beyond commodity segments. |
| Home Care Channel Direct Distribution | Post-acute wound management migration creates retail pharmacy and e-commerce platform access beyond institutional formulary control. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contracts, and SFDA registration filings underwrites the qualitative findings in this analysis. Primary interviews with hospital purchasing committee members, biomedical engineers, and GPO contracts managers were combined with secondary validation from customs import records, Ministry of Health procurement disclosures, and King Abdullah Economic City investment authority announcements. Bottom-up demand modeling across product type, material, end user, and application segments was cross-checked against top-down market sizing from trade flow analysis.
Rate-of-change decomposition across the modeling period separated volume growth from price-mix effects, with CAGRs derived from regression analysis against healthcare infrastructure investment trajectories and diabetic population prevalence projections. Segmentation dimensions modeled include product type, material substrate, end-user channel structure, and clinical application, with additional granularity for SFDA registration pathway tier and localization compliance status. Forecast inputs incorporated hospital bed expansion pipelines, special economic zone manufacturing incentive schedules, and EU MDR technical documentation alignment timelines.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time inventory turnover metrics at private hospital networks introduce uncertainty bands around demand elasticity assumptions. Forecasts reflect documented assumptions regarding SFDA regulatory harmonization pace and Saudi Vision 2030 localization threshold enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Global Lancet and Pen Needles Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Tongue Depressors Market
Medical Supplies
Disposable Face Mask Market
Medical Supplies
Scintillation Vials Market
Medical Supplies
Europe Syringe Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
Evacuated Drainage Bottles Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Surgical Tapes Market
Medical Supplies
Microcarrier Market
Medical Supplies
Global Dental Sterilization Market