
 Specimen Collection Cards Market | 2026-2036
Specimen Collection Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Specimen Collection Cards Market Analytics
Aftermarket service revenue for sample logistics and cold-chain compliance is reconfiguring how vendors capture lifetime value from disposable card sales. QIAGEN leverages its nucleic acid stabilization chemistry to anchor premium positioning in research-grade cards. Thermo Fisher Scientific sustains broad laboratory channel control through integrated consumables distribution. Danaher Corporation competes on manufacturing scale across its diagnostics platform subsidiaries.
Specimen collection cards are engineered substrates—typically cellulose paper matrices treated with chemical stabilizers or polymer composites—that absorb, preserve, and transport biological samples for downstream analysis. Blood cards dominate clinical volumes due to dried blood spot standardization in neonatal screening and therapeutic drug monitoring. Research applications are expanding fastest as biobanking and longitudinal epidemiological studies drive demand for saliva and urine card formats with ambient-temperature stability. Composite materials are gaining share where multi-analyte preservation requires layered barrier properties beyond untreated cellulose.
FDA oversight of in vitro diagnostic collection devices and CLIA laboratory quality standards shape product validation requirements and market access timelines for new card entrants. ISO 15189 accreditation and CAP guidelines further constrain specifications for diagnostic laboratories in the United States. Stakeholders must monitor evolving home-collection exemptions and state-level laboratory licensing reciprocity to anticipate channel expansion or contraction for direct-to-consumer specimen kits.
Market Dynamics
Decentralized diagnostic testing is compressing traditional laboratory workflows into at-home collection models, forcing card manufacturers to redesign substrates for ambient-temperature stability and unassisted user handling.
Growth Catalysts
- Neonatal screening mandates:State-level newborn screening program expansions across the United States are institutionalizing dried blood spot protocols as default diagnostic infrastructure.
- CLIA-waived test proliferation:FDA exemptions for moderate-complexity laboratory procedures are accelerating point-of-care adoption of specimen cards outside hospital settings.
- Polymer-composite stabilization:Multi-layer barrier substrates now preserve nucleic acids and proteins without cold-chain dependency, unlocking tropical and remote deployment scenarios.
Market Restraints
- Pulp cellulose price volatility:Fluctuating hardwood pulp costs squeeze margin structures for untreated cellulose card producers without chemical stabilization value-add.
- FDA 510(k) pathway congestion:Diagnostic device premarket notification backlogs extend commercialization timelines for novel collection formats by 12-18 months.
- Capillary tube substitutes:Microsampling devices using volumetric absorptive matrices threaten displacement in therapeutic drug monitoring applications.
Strategic Opportunities
- Direct-to-consumer channel penetration:Telehealth platforms in the United States are bundling specimen cards with subscription diagnostic services, bypassing traditional distributor markups.
- Saliva-based oncology screening:Circulating tumor DNA preservation on treated substrates opens longitudinal cancer monitoring without phlebotomy infrastructure.
- ISO 20387 biobanking standards:Quality management mandates for biological resource centers are mandating traceable, temperature-stable collection media with audit-ready chain-of-custody documentation.
Industry Challenges
- Cross-functional talent scarcity:Card manufacturers struggle to recruit chemists with simultaneous expertise in analytical assay validation and large-scale paper manufacturing process engineering.
- Legacy LIS integration friction:Hospital laboratory information systems require custom middleware development to reconcile at-home collection barcoding with centralized specimen tracking protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specimen Collection Cards Market |
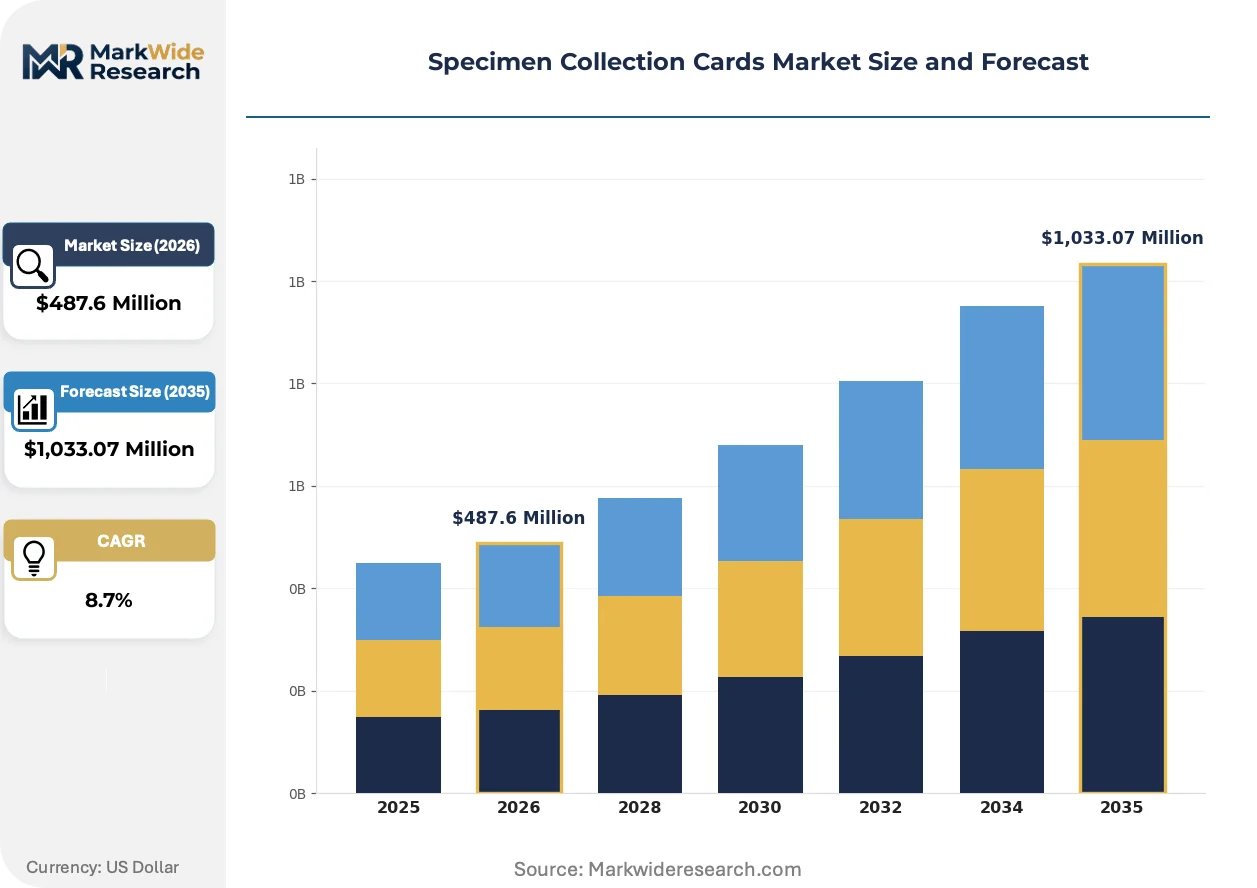
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Cards, Urine Cards, Saliva Cards, Other Fluids Material: Paper, Plastic, Composite, Others Application: Medical Diagnostics, Research Purposes, Forensic Analysis, Epidemiological Studies End User: Hospitals, Diagnostic Laboratories, Research Organizations, Home Healthcare |
| Companies Covered | QIAGEN, PerkinElmer Inc., Danaher Corporation, Thermo Fisher Scientific Inc., Ahlstrom, DBS System SA, Eastern Business Forms, Inc., GenTegra LLC, ARCHIMED Life Science GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specimen Collection Cards Market Evolving Landscape
Substrate engineering and regulatory pathway optimization are converging to redefine competitive advantage around sample integrity duration rather than unit manufacturing cost.
Multi-analyte preservation chemistry is migrating from single-purpose blood spot cards toward universal collection substrates. Biobanking operators in the United States and Nordic countries are piloting these formats for population-scale longitudinal studies. The technology is migrating from research-grade premium positioning into standard clinical procurement catalogs as stabilization performance becomes a baseline specification rather than a differentiator.
FDA's evolving guidance on home-use in vitro diagnostic collection devices is tightening human factors validation requirements. Manufacturers must now demonstrate usability across literacy levels and dexterity impairments before market authorization. Small-format card producers without dedicated regulatory affairs capacity are outsourcing 510(k) preparation to specialized consulting firms, consolidating market access expertise among fewer vendors.
Diagnostic laboratories are unbundling specimen logistics from testing services, creating standalone revenue lines for ambient-stable transport media. Third-party logistics providers in the United States are certifying cold-chain exemption protocols for treated card shipments, displacing traditional refrigerated courier relationships. This reconfiguration is most visible in employer wellness programs and decentralized clinical trials, where sample collection occurs at distributed sites with centralized laboratory analysis.
Specimen Collection Cards Market Segmentation
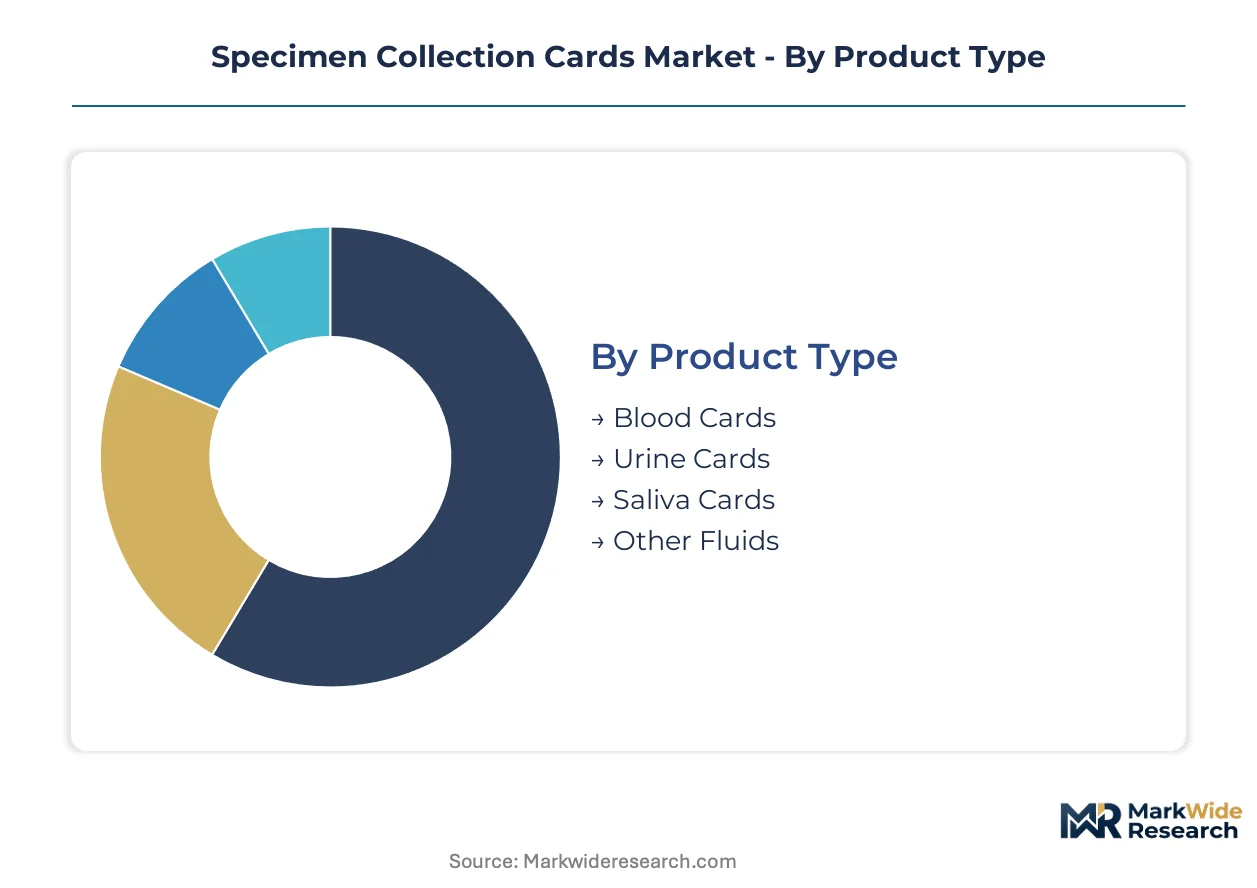
Specimen collection cards fragment across four distinct dimensions—product chemistry, substrate engineering, use-case intensity, and procurement channel. Each axis carries different margin profiles and regulatory exposure, forcing manufacturers to prioritize R&D investment against specific customer workflows rather than pursuing universal formats.
Product Type:
Application intensity and sample stability requirements divide the product landscape into four functional categories, each with distinct ambient-temperature performance specifications.
- Blood Cards:Cellulose matrices treated with chemical stabilizers absorb capillary blood volumes for dried blood spot analysis. Neonatal screening programs in the United States and European national health systems institutionalize this format as default infrastructure, with state-level mandate expansions sustaining procurement volumes.
- Saliva Cards:Treated polymer composites preserve nucleic acids and proteins without refrigeration, enabling at-home collection for genetic testing and infectious disease monitoring. Direct-to-consumer telehealth platforms in the United States are bundling these cards with subscription diagnostic services, bypassing traditional distributor channels.
- Urine Cards:Absorbent substrates with barrier layers prevent leakage during ambient transport. Toxicology screening and employer wellness programs drive steady demand.
- Other Fluids:Specialized formats for cerebrospinal fluid, amniotic fluid, or sweat collection serve niche diagnostic protocols. Rare disease research networks represent the primary customer base.
Blood cards command the established base. The steepest expansion runs through saliva cards.
Material:
Substrate selection determines stabilization chemistry compatibility, manufacturing cost structure, and cold-chain exemption eligibility.
- Paper:Untreated or chemically treated cellulose dominates clinical volumes due to cost efficiency and established assay validation. Pulp price volatility squeezes margin structures for producers without stabilization value-add.
- Composite:Multi-layer barriers combining cellulose with polymer films preserve multiple analyte classes without temperature control. Biobanking operators in Nordic countries and the United States pilot these formats for population-scale longitudinal studies.
- Plastic:Rigid or semi-rigid substrates serve specialized applications requiring dimensional stability during automated handling. High-throughput diagnostic laboratories favor this format for workflow integration.
- Others:Glass fiber, nitrocellulose, and novel nanomaterials address emerging research requirements. Academic consortia drive limited but high-margin procurement.
Paper substrates anchor current procurement volumes. Composite materials are climbing the fastest as multi-analyte preservation becomes baseline specification.
Application:
Use-case maturity and regulatory pathway complexity create four distinct demand environments with divergent validation timelines.
- Medical Diagnostics:CLIA-waived and moderate-complexity laboratory applications dominate commercial volumes. FDA 510(k) pathway congestion extends commercialization timelines for novel formats.
- Research Purposes:Biobanking, drug development, and longitudinal epidemiology drive demand for ambient-stable transport media. ISO 20387 quality management mandates are mandating traceable collection media with audit-ready documentation.
- Forensic Analysis:Chain-of-custody requirements and legal admissibility standards constrain supplier qualification. State crime laboratories in the United States maintain approved vendor lists with limited turnover.
- Epidemiological Studies:Population-scale sampling campaigns require cost-efficient, field-deployable formats. Public health agencies prioritize procurement through centralized tenders.
Medical diagnostics commands the established base. Research purposes are expanding most quickly as biobanking infrastructure scales.
End User:
Procurement sophistication and technical specification authority vary sharply across four customer archetypes, reshaping vendor sales motion requirements.
- Diagnostic Laboratories:Centralized and reference laboratories specify performance-validated substrates with integrated barcoding and LIS compatibility. Legacy LIS integration friction requires custom middleware development for at-home collection reconciliation.
- Home Healthcare:Direct-to-consumer and remote patient monitoring channels demand unassisted usability across literacy and dexterity levels. FDA human factors validation requirements are tightening market access barriers.
- Hospitals:Acute care settings prioritize workflow integration with existing phlebotomy and laboratory infrastructure. Group purchasing organizations consolidate procurement decisions.
- Research Organizations:Academic and contract research organizations prioritize stabilization performance and documentation traceability over unit cost. Grant-funded procurement cycles create demand lumpiness.
Diagnostic laboratories command the established base. Home healthcare is gaining share fastest as decentralized testing models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public health procurement budgets show sharp elasticity variation across geographies, with emerging markets prioritizing cost-efficient untreated cellulose formats while developed systems absorb premium stabilization chemistry at higher price points.
United States
State-level newborn screening mandate expansions and CLIA-waived test proliferation drive dried blood spot standardization. FDA oversight of home-collection devices tightens human factors validation requirements for market authorization. The Research Triangle Park cluster in North Carolina concentrates biobanking infrastructure development for longitudinal epidemiological studies.
Germany
Precision medicine initiatives and population-scale biobanking networks expand demand for ambient-stable transport media. EMA guidance on in vitro diagnostic device performance standards shapes product validation requirements for EU market access. The Munich-Heidelberg corridor anchors pharmaceutical-grade collection card manufacturing and nucleic acid stabilization chemistry R&D.
China
Domestic diagnostic consumables localization policies and expanding neonatal health programs institutionalize dried blood spot protocols. NMPA medical device registration pathways extend commercialization timelines for novel collection formats. The Yangtze River Delta manufacturing belt concentrates cellulose substrate production and polymer-composite barrier film fabrication.
Japan
Aging demographics and remote patient monitoring expansion accelerate at-home specimen collection adoption. PMDA quality management system requirements constrain supplier qualification for diagnostic laboratory procurement. The Kansai region around Osaka maintains specialized manufacturing capacity for high-throughput automated handling formats.
India
National health mission expansions and decentralized diagnostic testing programs drive cost-optimized card procurement at scale. CDSCO medical device rules and state-level laboratory licensing reciprocity shape channel access for direct-to-consumer kits. The Hyderabad-Bengaluru corridor clusters contract research organizations piloting saliva-based oncology screening formats.
Specimen Collection Cards Market Competitive Landscape
Capability concentration sits with chemistry-specialized mid-tier players; scale advantage sits with diversified laboratory consumables distributors. The market structures around three tiers: substrate engineering specialists, integrated diagnostics platforms, and regional paper manufacturing converters. Dominant competitive moves include strategic partnerships with third-party logistics providers certifying cold-chain exemption protocols, and portfolio diversification into multi-analyte preservation formats.
Within the integrated diagnostics platform tier, Danaher Corporation and Thermo Fisher Scientific Inc. exemplify scale-driven channel control through broad laboratory consumables distribution networks. Among chemistry-specialized players, QIAGEN occupies a position representing premium nucleic acid stabilization value-add. These three anchors illustrate divergent strategic positioning: manufacturing scale leverage, integrated channel dominance, and stabilization chemistry specialization respectively.
| Leading Market Players |
|---|
| QIAGEN |
| PerkinElmer Inc. |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| Ahlstrom |
| DBS System SA |
| Eastern Business Forms, Inc. |
| GenTegra LLC |
| ARCHIMED Life Science GmbH |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing belt concentrates cellulose substrate production and polymer-composite barrier fabrication, translating capacity tightness into asymmetric pricing power for treated card producers over untreated commodity suppliers. Pulp price volatility in hardwood markets compresses margins for paper-based card manufacturers lacking chemical stabilization value-add, while multi-layer composite producers capture premium positioning through cold-chain exemption certification.
Pricing Analysis
Aftermarket service revenue for sample logistics and cold-chain compliance drives lifetime value capture beyond unit card sales. Three-tier pricing structure across premium, standard, and economy levels separates nucleic acid stabilization chemistry from basic cellulose absorption and untreated commodity formats. Cost compression in standard-tier untreated cards is intensifying because pulp input volatility squeezes converters without vertical integration into stabilization chemistry. Employer wellness programs and decentralized clinical trials exhibit highest price sensitivity, while biobanking operators prioritize stabilization performance over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with Ahlstrom's integrated pulp-to-card operations and regional Chinese converters serving domestic NMPA-registered producers. Hardwood pulp supply draws from Scandinavian and North American forestry operations, while polymer barrier films source from South Korean and Japanese petrochemical specialists. Single-source vulnerability concentrates in nucleic acid stabilization chemistry, where proprietary formulations create captive supplier relationships. Distribution runs through third-party logistics providers certifying ambient-temperature exemption protocols, displacing traditional refrigerated courier networks for direct-to-consumer and remote patient monitoring channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where FDA 510(k) pathway congestion and CLIA laboratory quality standards create switching costs that protect validated incumbents from rapid displacement.
For Market Incumbents: Pre-empt microsampling device substitution in therapeutic drug monitoring by embedding volumetric absorptive matrices into integrated collection workflows. Accelerate backward integration into nucleic acid stabilization chemistry to defend margin structures against specialty chemical suppliers. Lock in biobanking infrastructure partnerships ahead of ISO 20387 quality management mandate enforcement.
For New Entrants and Emerging Players: Establish a beachhead in saliva-based oncology screening formats where circulating tumor DNA preservation requirements favor new substrate engineering approaches over legacy blood card incumbents. Target direct-to-consumer telehealth platform partnerships in the United States as the most penetrable channel bypassing traditional distributor markups. Lead with ambient-temperature stability certification as the primary go-to-market differentiator against cold-chain-dependent alternatives.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specimen logistics and cold-chain compliance service providers, where subscription diagnostic bundling creates predictable cash flow visibility. Acquisition target archetypes include mid-tier chemistry-specialized card producers with FDA-cleared stabilization formats and underexploited channel relationships. Monitor CLIA-waived test proliferation rates and state-level newborn screening mandate expansions as inflection indicators for demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Home-Collection Device | Human factors validation across literacy levels unlocks direct-to-consumer channel expansion. |
| Hospital System Partnership for LIS Integration | Custom middleware development reconciles at-home barcoding with centralized specimen tracking. |
| CE Marking Pathway for EU Market Access | EMA guidance on in vitro diagnostic performance standards shapes product validation requirements. |
| Biobanking Infrastructure Partnership | ISO 20387 quality management mandates drive traceable, temperature-stable collection media procurement. |
| Third-Party Logistics Certification Program | Cold-chain exemption protocols enable ambient-temperature shipment displacement of refrigerated couriers. |
Research Methodology
Initial hypotheses were tested against primary input from diagnostic laboratory directors, regulatory affairs specialists at card manufacturers, third-party logistics certification officers, and biobanking quality managers, then refined through secondary validation against FDA 510(k) filings, CLIA waiver databases, ISO 15189 accreditation records, and hospital procurement contract disclosures. Bottom-up demand modeling across end-user segments triangulated with top-down supply capacity assessments from cellulose substrate and polymer barrier film producers.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product chemistry, substrate engineering, use-case intensity, and procurement channel. CAGRs were derived from installed base expansion in neonatal screening programs, CLIA-waived test proliferation rates, and direct-to-consumer diagnostic subscription growth. Forecast inputs incorporated pulp price volatility trajectories and regulatory pathway timeline assumptions for novel collection formats.
Sensitivities concentrate around FDA home-collection guidance evolution, CLIA laboratory licensing reciprocity changes, and hardwood pulp cost compression. Forecasts reflect documented assumptions on stabilization chemistry adoption curves and telehealth platform bundling penetration. Quarterly review of 510(k) submission backlogs, state-level newborn screening mandate expansions, and third-party logistics cold-chain exemption certification rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Global Medical Waste Containers Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
Disposable Sanitary Pad Market
Medical Supplies
Medical and Industrial Gloves Market
Medical Supplies
Physiological Saline Market
Medical Supplies
Catheter Tip Syringe Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
US Hospital Consumables Market
Medical Supplies
Global Lancet and Pen Needles Market
Medical Supplies
Ear and Nasal Packing Market
Medical Supplies
Dehydrated Culture Media Market
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
Lumbar Puncture Trays and Needles Market