
 Satellite Imaging Market | 2026-2036
Satellite Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Imaging Market Intelligence
Defense and intelligence agencies are redrawing the buyer landscape for satellite imaging, overtaking traditional civilian government contracts as the primary revenue source. Planet Labs PBC leverages its daily-coverage constellation to dominate agricultural and environmental monitoring contracts. Maxar Technologies anchors high-value defense relationships through its geospatial intelligence platform and classified imagery services. ICEYE competes in synthetic aperture radar with all-weather, day-night imaging capabilities that penetrate cloud cover.
Satellite imaging captures electromagnetic radiation reflected or emitted from Earth's surface using sensors mounted on orbital platforms, with spatial resolution ranging from sub-meter to tens of meters depending on payload design and orbital altitude. The technology serves commercial, defense, and scientific users requiring persistent Earth observation for decision support. Optical imaging leads current revenue generation due to mature sensor economics and broad application familiarity, while hyperspectral imaging represents the fastest-expanding segment as precision agriculture and mineral exploration buyers demand material-composition data beyond visible spectra. Data analytics technology commands expanding margin pools as value shifts from raw pixels to AI-derived insights.
The U.S. National Oceanic and Atmospheric Administration licenses private remote sensing systems under the Land Remote Sensing Policy Act, constraining resolution limits for non-defense operators. The European Union's Space Surveillance and Tracking programme and ISO 19115 metadata standards shape cross-border data interoperability and quality certification. China's MIIT and NMPA impose national security reviews on foreign satellite imagery covering Chinese territory. Stakeholders must monitor evolving export control classifications for AI-enhanced image processing software and dual-use sensor technologies.
Market Dynamics
Defense procurement concentration is restructuring the satellite imaging value chain, with classified imagery contracts now absorbing capacity that previously served commercial agriculture and climate monitoring clients.
Growth Catalysts
- Space Force procurement:The U.S. Space Force sustains multi-year geospatial intelligence contracts that stabilize manufacturer revenue visibility and fund constellation expansion.
- EU Space Surveillance and Tracking:The programme's operational standards for orbital data sharing create interoperability mandates that drive sensor upgrade cycles across European operators.
- Synthetic aperture radar:All-weather, day-night imaging capabilities penetrate cloud cover and darkness, opening persistent monitoring applications for maritime surveillance and disaster response agencies.
Market Restraints
- Launch cost volatility:Falcon Heavy and Ariane 6 pricing fluctuations directly impact constellation deployment economics for capital-constrained operators.
- Resolution licensing:The U.S. Land Remote Sensing Policy Act constrains non-defense operators to sub-meter limits, compressing commercial differentiation against classified systems.
- Optical sensor saturation:Mature optical payload economics face substitution pressure from hyperspectral and SAR alternatives in premium contract bidding.
Strategic Opportunities
- Hyperspectral agriculture:Precision farming buyers in Brazil and Australia demand material-composition data beyond visible spectra for crop stress detection and yield optimization.
- AI analytics bundling:Value migration from raw pixels to machine-interpreted insights creates recurring revenue streams detached from image capture margins.
- Carbon credit verification:MRV (Measurement, Reporting, Verification) mandates under voluntary carbon markets and compliance schemes drive subscription demand for forest and soil monitoring.
Industry Challenges
- Orbital mechanics expertise:Constellation design and station-keeping optimization require scarce aerospace engineering talent competing with launch vehicle manufacturers.
- ITAR classification complexity:Dual-use sensor technologies and AI-enhanced processing software face export control reviews that extend sales cycles to foreign defense clients.
- Ground segment integration:Downlink infrastructure and edge computing deployment at customer sites demand capital commitments that strain balance sheets before revenue materializes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Imaging Market |
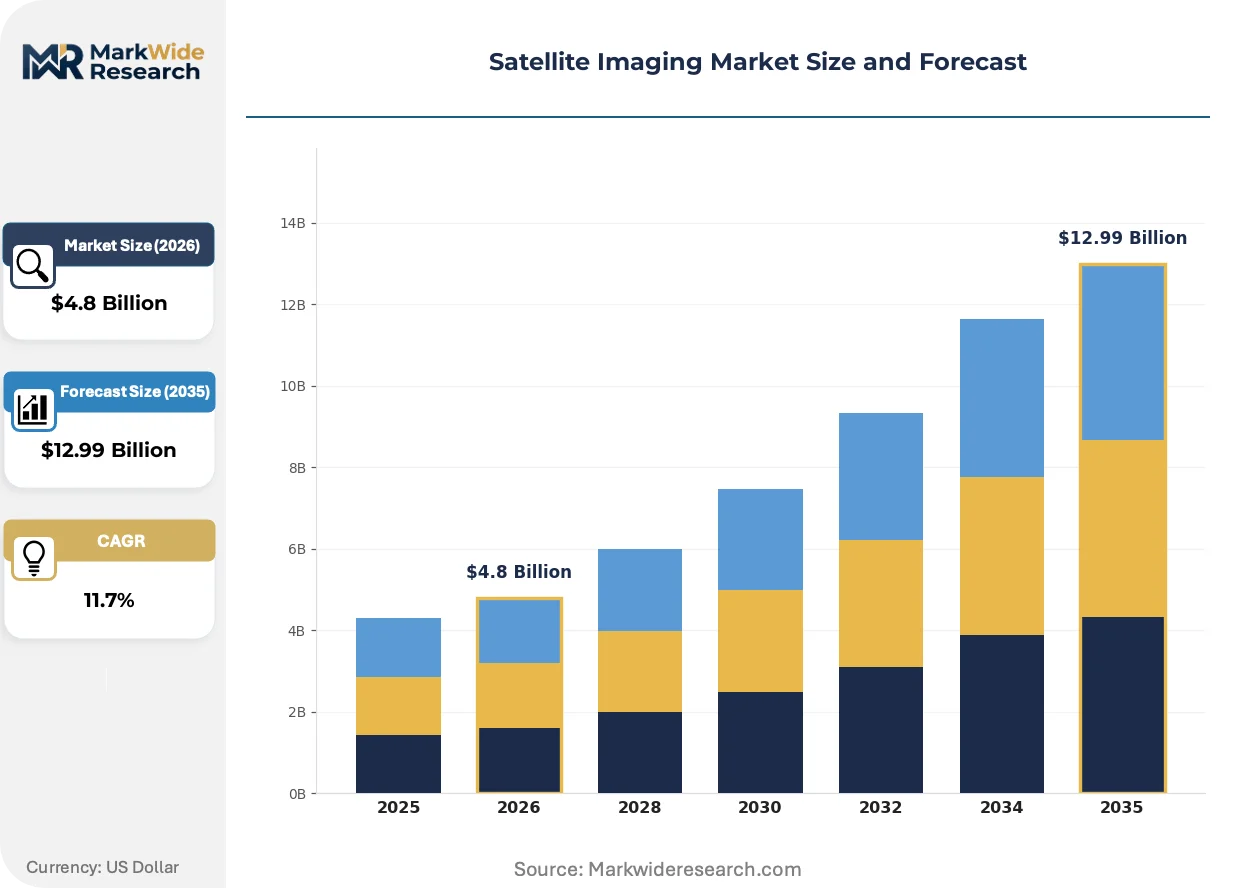
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Imaging, Radar Imaging, Multispectral Imaging, Hyperspectral Imaging End User: Aerospace, Agriculture, Defense, Forestry Application: Environmental Monitoring, Land Use Mapping, Disaster Management, Urban Planning Technology: Satellite Constellations, Ground Stations, Image Processing, Data Analytics |
| Companies Covered | BlackSky Technology Inc., Satellogic, Planet Labs PBC, SI Imaging Services, ICEYE, Airbus Defence & Space, Capella Space, Umbra, Maxar Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Imaging Market Strategic Shifts & Innovations
Sensor diversification and analytics unbundling are fragmenting the traditional imagery value chain, with specialized providers now capturing margin pools that integrated operators once monopolized.
Hyperspectral imaging is bifurcating the Earth observation market between commodity optical providers and premium material-analysis specialists. Mining conglomerates and agricultural biotechnology firms now specify 200-plus spectral bands for mineral composition and crop biochemistry detection. This capability compression is forcing pure-play optical operators into price competition or downstream analytics partnerships.
The EU AI Act's risk classification framework for automated decision systems is reshaping procurement specifications for defense and intelligence imagery analytics. High-risk applications now mandate human-in-the-loop validation and algorithmic transparency documentation. European security agencies are embedding these requirements into tender documents, displacing black-box AI solutions from contested contract rounds.
Subscription-based data access is displacing per-image licensing across commercial agriculture and insurance verticals. Planet Labs and Sentinel Hub pioneered this model; now commodity traders and reinsurance underwriters in the United States and Australia specify API-delivered, time-series data feeds rather than archived scene purchases. This consumption-pattern shift compresses customer acquisition costs while extending lifetime value through platform stickiness.
Satellite Imaging Market Segmentation
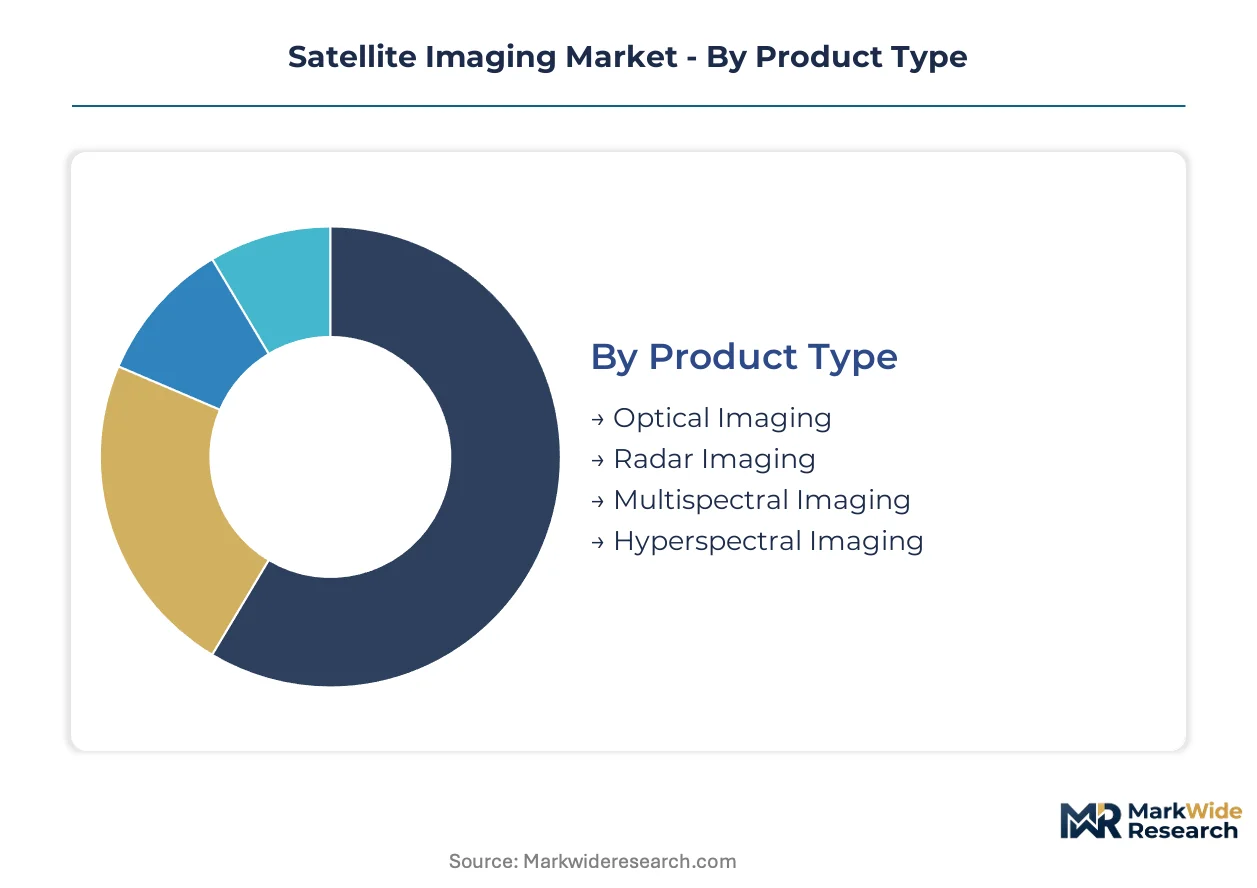
Satellite imaging markets fragment across sensor physics, customer mission requirements, and value-chain position. Each segmentation axis reveals distinct margin pools and competitive entry barriers.
Product Type:
Optical imaging faces intensifying substitution pressure from synthetic aperture radar and hyperspectral alternatives as defense and precision agriculture buyers demand all-weather capability and material-composition data.
- Optical Imaging:Passive sensors capture reflected visible and near-infrared light, with spatial resolution reaching sub-meter precision for reconnaissance applications. U.S. Space Force and NGA contracts sustain capacity absorption for high-resolution optical constellations, though cloud-cover limitations constrain mission assurance in tropical maritime zones.
- Hyperspectral Imaging:Spectrometers disaggregate electromagnetic signatures into 200-plus contiguous bands, enabling mineral composition mapping and crop biochemistry detection. Mining conglomerates in Australia and agricultural biotechnology firms in Brazil specify hyperspectral payloads for yield optimization and exploration targeting, driving the steepest technology upgrade cycles.
- Radar Imaging:Active microwave sensors penetrate cloud cover and darkness for persistent maritime surveillance.
- Multispectral Imaging:Discrete band sensors balance cost and analytical depth for broad-area agriculture monitoring.
Optical imaging retains volume leadership; hyperspectral imaging holds the steepest expansion curve.
End User:
Defense procurement concentration is restructuring revenue concentration, with classified imagery contracts now absorbing capacity that previously served commercial verticals.
- Defense:Military and intelligence agencies specify high-resolution reconnaissance, geospatial intelligence platforms, and classified imagery services. The U.S. Space Force sustains multi-year contracts that stabilize manufacturer revenue visibility, while European security agencies embed EU AI Act algorithmic transparency requirements into tender specifications.
- Agriculture:Precision farming operations demand subscription-based API data feeds for crop stress detection and yield forecasting. Brazilian soybean producers and Australian wheat belt operators specify time-series vegetation indices rather than archived scene purchases, compressing customer acquisition costs while extending platform lifetime value.
- Forestry:Carbon credit verification mandates drive MRV subscription demand for forest biomass monitoring.
- Aerospace:Satellite operators and launch service providers procure imagery for orbital debris tracking and constellation planning.
Defense commands the dominant revenue share; agriculture demonstrates the most rapid consumption-pattern shift toward recurring subscriptions.
Application:
Demand intensity varies sharply by decision-support urgency, with disaster response and security applications commanding premium pricing over planning-oriented use cases.
- Disaster Management:Rapid damage assessment and resource deployment coordination require all-weather, day-night imaging capabilities. SAR constellations penetrate smoke and cloud cover for wildfire progression monitoring in California and flood extent mapping in Southeast Asian river deltas, with response agencies specifying sub-hourly revisit frequencies during active events.
- Environmental Monitoring:Long-term ecosystem health tracking and climate change attribution studies leverage optical and hyperspectral archives. Scientific institutions and NGOs in Norway and Canada subscribe to decades-long time-series for glacier retreat measurement and permafrost degradation analysis.
- Land Use Mapping:Cadastral administration and property taxation authorities require geometrically accurate base layers.
- Urban Planning:Municipal infrastructure departments procure imagery for zoning enforcement and informal settlement detection.
Environmental monitoring retains the deepest archival foundation; disaster management exhibits the most acute willingness-to-pay premiums.
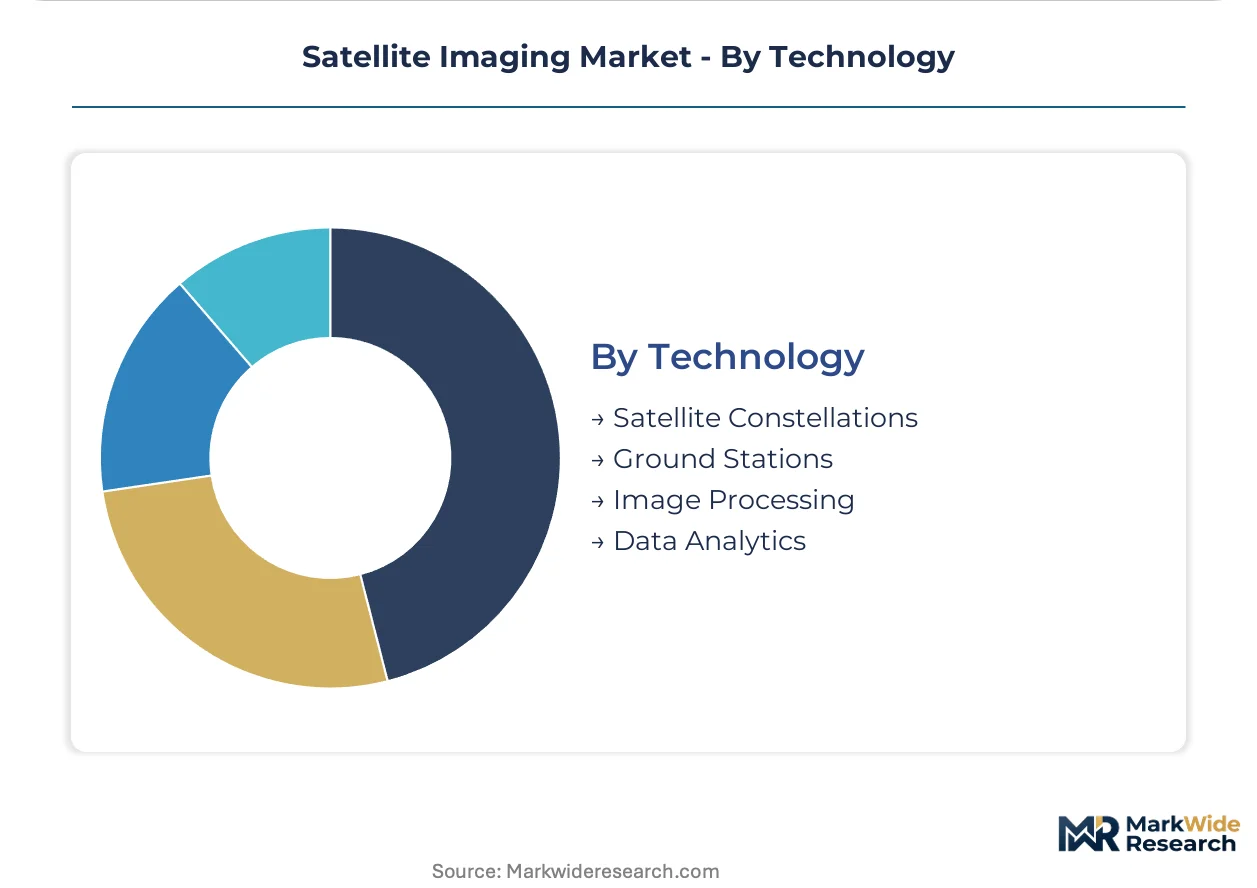
Technology:
Value migration from hardware to software layers is fragmenting the traditional integrated-operator model, with specialized analytics providers capturing margin pools once monopolized by constellation owners.
- Data Analytics:Machine-interpreted insight generation now commands expanding margin pools as buyers prioritize decision-ready outputs over raw pixels. Reinsurance underwriters in London and commodity traders in Chicago specify AI-derived crop yield forecasts and property damage estimates, creating recurring revenue streams detached from image capture economics.
- Satellite Constellations:Orbital platforms with sensor payloads require capital-intensive deployment and station-keeping optimization. Launch cost volatility from Falcon Heavy and Ariane 6 pricing fluctuations directly impacts deployment economics for capital-constrained operators seeking global coverage.
- Image Processing:Radiometric correction and orthorectification pipelines convert raw sensor data into geospatially referenced products.
- Ground Stations:Downlink infrastructure and edge computing deployment demand capital commitments before revenue materialization.
Satellite constellations anchor capital deployment; data analytics exhibits the most rapid margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based operators export geospatial intelligence services to European defense ministries and Asian maritime security agencies, establishing transatlantic and transpacific data corridors that shape procurement patterns.
United States
The U.S. Space Force and National Geospatial-Intelligence Agency sustain multi-year imagery contracts that stabilize manufacturer revenue visibility. NOAA licenses private remote sensing systems under the Land Remote Sensing Policy Act, constraining resolution limits for non-defense operators. Denver and the National Capital Region host constellation operators and geospatial analytics clusters where defense procurement concentration absorbs commercial capacity.
China
MIIT and NMPA impose national security reviews on foreign satellite imagery covering Chinese territory, redirecting domestic procurement toward indigenous operators. The dual carbon goals framework mandates satellite-based environmental monitoring for emissions verification. Beijing and Shanghai anchor state-owned constellation development and downstream analytics integration for Belt and Road infrastructure tracking.
European Union
European security agencies embed EU AI Act algorithmic transparency requirements into tender specifications for defense imagery analytics. The Space Surveillance and Tracking programme tightens operational standards for orbital data sharing across member states. Toulouse and Munich host Airbus Defence & Space operations and specialized SAR payload engineering clusters serving Franco-German defense cooperation.
Australia
Precision agriculture buyers in the wheat belt specify subscription-based API data feeds for crop stress detection and yield forecasting. The Bureau of Meteorology licenses satellite data for drought monitoring and bushfire response coordination. Adelaide and Canberra concentrate earth observation research institutions and defense geospatial integration facilities supporting Indo-Pacific maritime domain awareness.
Japan
METI funds synthetic aperture radar constellation development for disaster response and maritime surveillance applications. The Cabinet Satellite Intelligence Center coordinates imagery acquisition for national security purposes. Tokyo and Tsukuba host optical sensor manufacturers and space agency research facilities advancing hyperspectral payload miniaturization.
Satellite Imaging Market Key Industry Players
Player mix skews toward vertically integrated constellation operators and specialized analytics providers, creating a bifurcated structure where capital-intensive orbital platforms coexist with software-centric insight generators. The vendor base separates into three strategic archetypes: daily-coverage optical specialists, all-weather SAR operators, and AI-driven analytics platforms. Dominant competitive moves include strategic partnerships between sensor operators and defense integrators, plus portfolio diversification into carbon credit verification services.
Within the integrated-operator tier, Planet Labs PBC and Maxar Technologies occupy positions spanning constellation ownership and defense contracting relationships. ICEYE represents the SAR-specialist archetype with all-weather, day-night imaging capabilities. BlackSky Technology Inc. sits within the real-time analytics tier, exemplifying the shift from raw pixel delivery to machine-interpreted intelligence.
| Leading Market Players |
|---|
| BlackSky Technology Inc. |
| Satellogic |
| Planet Labs PBC |
| SI Imaging Services |
| ICEYE |
| Airbus Defence & Space |
| Capella Space |
| Umbra |
| Maxar Technologies |
| Others |
Cost & Logistics Intelligence
ISO 19115 metadata standards gate both supplier qualification and price differentiation simultaneously, forcing constellation operators to invest in certification infrastructure before bidding on European defense contracts while enabling certified providers to command premiums over uncertified competitors in cross-border data interoperability tenders.
Pricing Analysis
Next-generation hyperspectral payloads command three-to-five-fold premiums over mature optical sensors, while legacy synthetic aperture radar systems face downward repricing as ICEYE and Capella Space deploy lighter, higher-revisit alternatives. Subscription-based API access now dominates commercial agriculture and insurance verticals, compressing per-image transactional revenue. Price differentiation rests on spectral band count and AI-analytics bundling, with defense buyers showing lowest sensitivity due to mission-assurance requirements. Cost compression in commodity optical tiers is intensifying because pure-play operators lack downstream analytics capabilities to escape hardware-margin erosion.
Supply Chain Analysis
Port congestion at Long Beach and component backlogs for radiation-hardened electronics have extended sensor payload lead times, forcing constellation operators to pre-position inventory before revenue materialization. Manufacturing concentrates in the United States, Germany, and Japan, with optical sensor fabrication anchored in Colorado and Bavaria. Supply chains draw from indium phosphide semiconductors, precision optics substrates, and launch vehicle capacity. Single-source vulnerability sits with Falcon Heavy and Ariane 6 manifest availability, which dictates constellation deployment cadence. Distribution runs through defense integrators for classified contracts and direct API platforms for commercial subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orbital mechanics expertise scarcity constrains constellation expansion timelines, with aerospace engineering talent competing against launch vehicle manufacturers and deep-space mission programs for the same finite labor pool.
For Market Incumbents: Fortify defense relationships through classified imagery service certifications and in-house production of AI-enhanced analytics to offset raw-pixel commoditization. Maxar Technologies and Planet Labs PBC face emerging SAR-specialist threats from ICEYE and Umbra in maritime surveillance tenders. Capacity addition in low-inclination orbits for tropical coverage represents a priority lever against cloud-cover limitations constraining optical mission assurance. For New Entrants and Emerging Players: Differentiate on carbon credit verification analytics, where MRV subscription demand outstrips specialized provider supply. Precision agriculture in Brazil and Australia offers the most penetrable commercial segment due to subscription-model familiarity and yield-optimization ROI visibility. A go-to-market angle pairing hyperspectral crop stress detection with direct API integration into farm management software platforms bypasses incumbent distribution control. For Investors and Strategic Acquirers: EU AI Act algorithmic transparency requirements reshape the acquisition landscape, displacing black-box AI solutions from contested European defense contract rounds. Long-term viability favors vertically integrated operators owning both constellation assets and downstream analytics capabilities rather than pure-play hardware or software specialists. The signal to watch is Space Force multi-year contract award cadence, which stabilizes revenue visibility for selected manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| AI Analytics Platform Integration | Captures margin migration from raw pixels to machine-interpreted insights for reinsurance underwriters. |
| Hyperspectral Payload Miniaturization | Enables 200-plus spectral band deployment on small-sat platforms for precision agriculture buyers. |
| Defense Certification Investment | Unlocks classified imagery contracts under U.S. Space Force and NGA procurement frameworks. |
| Carbon Credit Verification Service Launch | Addresses MRV mandate demand from voluntary carbon markets and compliance schemes. |
| SAR Constellation Expansion | Penetrates all-weather maritime surveillance segments where optical sensors face cloud-cover constraints. |
Research Approach
Cross-validation between primary interviews with constellation operators and secondary validation from SEC filings and NOAA licensing records anchors the qualitative findings. Interviews covered satellite mission directors, defense procurement officers at the U.S. Space Force, geospatial intelligence platform engineers, agricultural biotechnology firm data scientists, and reinsurance underwriters specifying API-delivered time-series feeds. Secondary sources included EU Space Surveillance and Tracking programme operational standards, ISO 19115 metadata documentation, and customs records for sensor payload component trade flows. Bottom-up unit economics for constellation deployment and top-down addressable market sizing were triangulated against disclosed contract values.
Sensitivity analysis tested launch cost volatility, resolution licensing regime changes, and defense procurement concentration shifts across the projection horizon. The analytical framework modeled sensor physics segmentation, customer mission requirements, and value-chain position dimensions alongside orbital altitude and revisit frequency specifications. CAGRs were derived from disclosed contract durations, subscription renewal rates, and capacity absorption trends. Industry-specific forecast inputs included Space Force budget authorization patterns and EU AI Act implementation timelines for automated decision system risk classifications.
Material uncertainties — launch vehicle manifest delays, export control reclassifications for dual-use sensor technologies, and defense budget reallocation cycles — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued U.S. Space Force procurement concentration and EU operational standards adoption trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
South Korea Satellite Imagery Services Market
Satellite
GEO Satellite Market
Satellite
Asia-Pacific Satellite IoT Market
Satellite
Broadband Satellite System Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
Commercial LEO Satellite Market
Satellite
Fixed Satellite Services (FSS) Market
Satellite
Low-Cost Satellite Market
Satellite
Italy Satellite Communication Market
Satellite
Satellite Manufacturing Market
Satellite
India Satellite Communication Market
Satellite
Europe Small Satellite Market
Satellite
Indonesia Satellite Communications Market
Satellite
Healthcare Satellite Connectivity Market
Satellite
South Korea Satellite Connectivity Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market