
 ASEAN Satellite Imagery Services Market | 2026-2036
ASEAN Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Satellite Imagery Services Market Insights
Platform licensing is rewriting revenue allocation across the ASEAN satellite imagery value chain. Airbus leverages its constellation ownership to sustain direct government contracts across multiple Southeast Asian capitals. Maxar Technologies anchors its position through high-resolution optical archive depth, while L3Harris Corporation competes on radar imaging capabilities for all-weather defense applications.
ASEAN satellite imagery services encompass the capture, processing, and distribution of earth observation data from orbital and aerial platforms, typically resolving ground features between 30 centimeters and 10 meters depending on sensor modality and orbital altitude. These services feed operational workflows spanning maritime boundary enforcement, crop yield prediction, and post-disaster damage quantification. Geospatial analytics commands the dominant margin pool as buyers shift from raw imagery procurement to decision-ready intelligence layers. Disaster management applications exhibit the steepest growth trajectory as ASEAN member states operationalize early warning systems for flood and seismic events. Optical sensors retain volume leadership though radar imaging penetrates equatorial markets where persistent cloud cover degrades passive collection reliability.
Indonesia's National Institute of Aeronautics and Space and the Philippines' Department of Science and Technology shape procurement standards through national space roadmaps and public-private partnership frameworks. TRAI-equivalent spectrum regulators across member states coordinate downlink frequency allocations that determine foreign operator market access. Buyers must evaluate whether to anchor contracts with regional data resellers or establish direct relationships with constellation operators as native ASEAN launch capabilities mature.
Market Dynamics
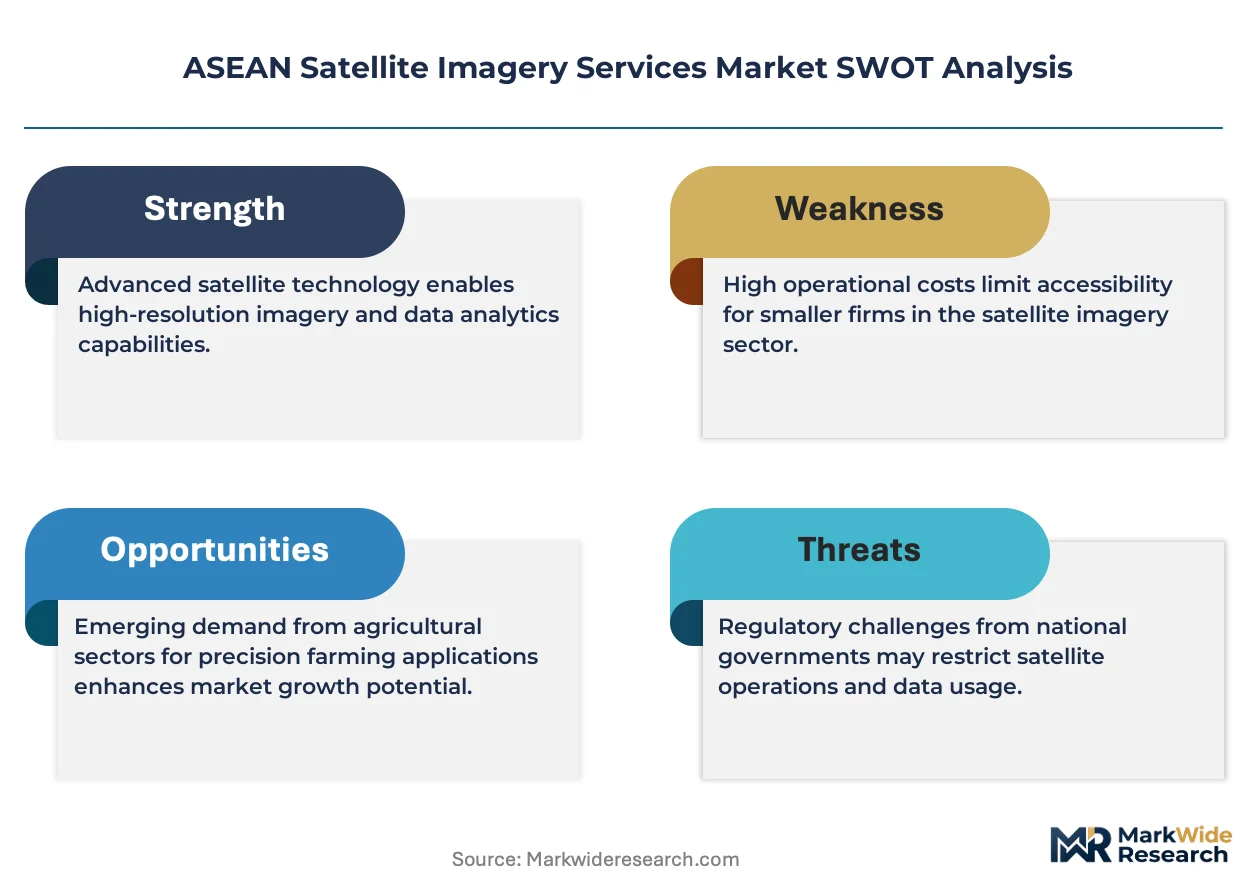
Defense procurement across Southeast Asia is consolidating satellite imagery contracts under national earth observation programs, compressing vendor access windows and privileging operators with direct constellation control over regional resellers.
Growth Catalysts
- Maritime Surveillance Mandates:Indonesia's archipelagic sea lane enforcement directives require persistent geospatial monitoring of territorial waters, expanding subscription volumes for synthetic aperture radar coverage.
- Early Warning System Investments:Thailand's disaster risk reduction framework funds operational flood prediction models integrating satellite-derived precipitation data with ground sensor networks.
- Plantation Certification Requirements:Roundtable on Sustainable Palm Oil traceability standards mandate deforestation-free supply chains, pulling plantation conglomerates toward verified imagery analytics.
Market Restraints
- Launch Capacity Concentration:ASEAN member states lack indigenous heavy-lift capabilities, creating dependency on foreign launch providers for proprietary satellite deployment.
- Cloud Cover Degradation:Passive optical sensors face persistent reliability constraints across equatorial Indonesia and Malaysia, limiting collection windows to seasonal dry periods.
- Frequency Allocation Friction:National spectrum regulators impose divergent downlink licensing requirements that fragment market access for foreign constellation operators.
Strategic Opportunities
- Philippines Maritime Domain Awareness:The archipelago's exclusive economic zone enforcement gaps create demand for persistent radar monitoring of illegal fishing and vessel traffic.
- Carbon Credit Verification:REDD+ forest carbon accounting protocols require measurable, reportable satellite-based biomass assessments across Indonesian and Malaysian concessions.
- Small Satellite Constellation Convergence:CubeSat formation flying combined with edge computing payloads enables real-time disaster response analytics at reduced data latency.
Industry Challenges
- Geospatial Analyst Shortage:National mapping agencies across Vietnam, Myanmar, and Cambodia lack sufficient trained personnel to operationalize raw imagery into decision-ready intelligence layers.
- Legacy System Integration Complexity:Defense ministries maintaining proprietary ground station architectures face substantial reconfiguration costs to ingest commercial satellite data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Satellite Imagery Services Market |
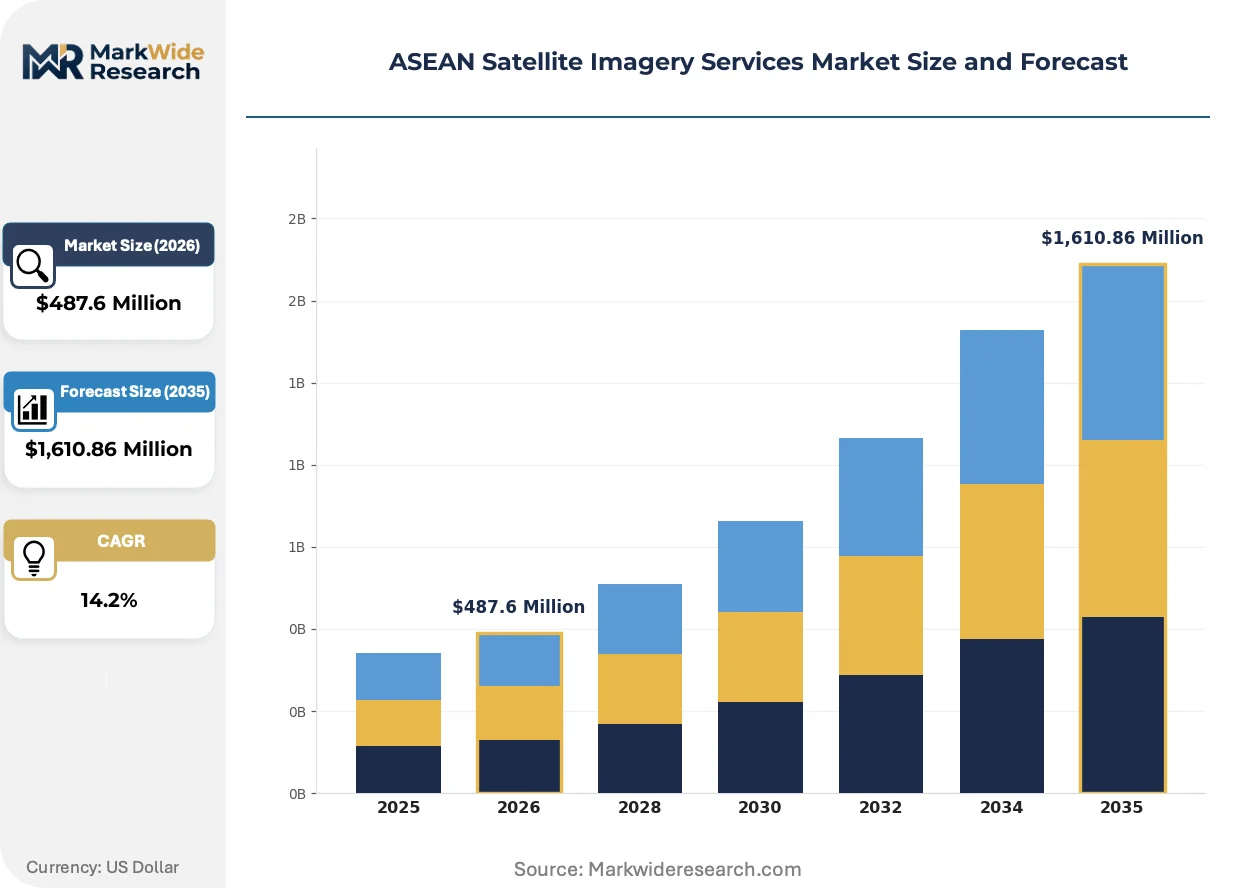
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Geospatial Analytics, Aerial Photography, Remote Sensing, Data Management Application: Agriculture Monitoring, Disaster Management, Urban Planning, Environmental Assessment End User: Government Agencies, Agricultural Sector, Environmental Organizations, Energy Sector Technology: Optical Sensors, Radar Imaging, LiDAR, Multispectral Imagery |
| Companies Covered | Airbus, Maxar Technologies, L3Harris Corporation, Geocircle, Maptogis, Geoinfo Services Sdn Bhd, Ground Data Solutions R&D Sdn Bhd, Pasco Corporation, Sekala, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Satellite Imagery Services Market Trends and Innovations
Sensor miniaturization and on-board processing capabilities are compressing the latency between image capture and actionable intelligence delivery across Southeast Asian operational workflows.
Hyperspectral imaging is collapsing the distinction between raw data procurement and finished agricultural analytics. Plantation operators in Sumatra and Borneo now demand crop health classification delivered within 24 hours of collection. This compression eliminates traditional value chain tiers that previously separated constellation operators from end-use agronomists.
Indonesia's national space roadmap establishes domestic satellite manufacturing and launch capability targets through public-private partnership frameworks. The policy redirects procurement preferences toward operators committing technology transfer and local assembly arrangements. Foreign vendors must now embed Indonesian engineering participation to maintain government contract eligibility.
Subscription-based access models are displacing per-image transaction structures across ASEAN defense and environmental agencies. Buyers in Thailand and Vietnam now prioritize unlimited archive access over spot-tasking flexibility. This behavioral pivot rewards constellation operators with deep historical libraries and penalizes asset-light resellers lacking proprietary orbital capacity.
ASEAN Satellite Imagery Services Market Segmentation
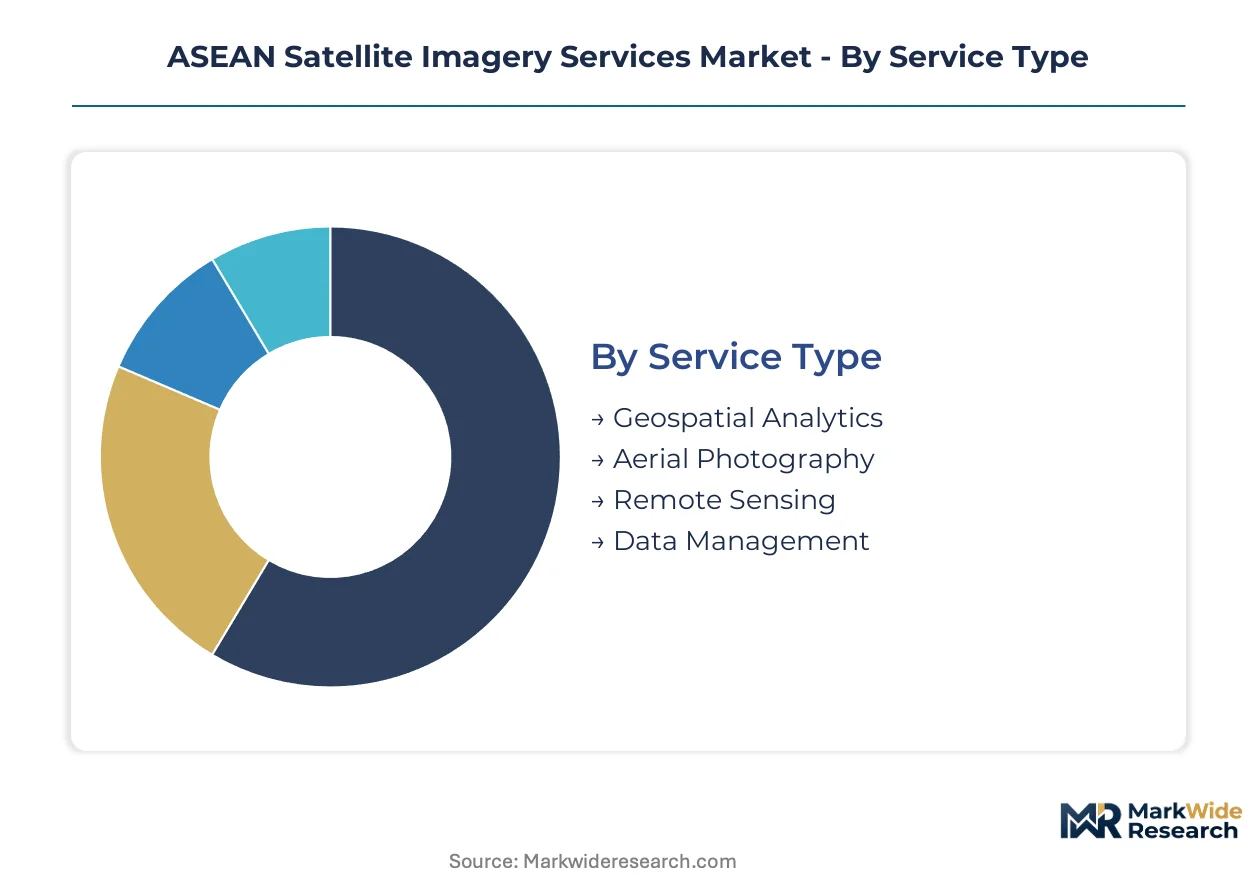
Segmentation in the ASEAN satellite imagery market reveals divergent contract cycles and margin structures across service tiers. Procurement patterns vary sharply between subscription-based analytics and transactional imagery purchases, with technology modality determining renewal frequency and customer lifetime value.
Service Type:
Cycle times compress from multi-year platform licenses down to single-project aerial captures, with analytics layers commanding the longest engagement horizons.
- Geospatial Analytics:Decision-ready intelligence layers integrating satellite-derived data with ground-truth validation and predictive modeling. Indonesian plantation conglomerates and Thai disaster management agencies anchor demand through multi-year subscriptions requiring continuous algorithm refinement.
- Remote Sensing:Systematic earth observation data acquisition from orbital platforms, encompassing both passive optical and active radar collection. Maritime surveillance contracts across the Philippines and Vietnam drive persistent coverage requirements for exclusive economic zone monitoring.
- Aerial Photography:High-resolution capture from manned or unmanned aircraft operating below cloud ceiling. Municipal governments in Malaysia deploy for urban cadastral updates on project-based procurement cycles.
- Data Management:Archive organization, metadata standardization, and distribution infrastructure for institutional imagery libraries. National mapping agencies in Myanmar and Cambodia prioritize this segment to operationalize legacy holdings.
Geospatial Analytics anchors the volume base while Remote Sensing gains share at the steepest rate.
Application:
Margin concentration follows regulatory enforcement intensity, with compliance-driven segments sustaining premium pricing against discretionary planning tools.
- Disaster Management:Early warning system integration combining satellite precipitation data with hydrological modeling. Thailand's disaster risk reduction framework funds operational flood prediction, while Indonesia's seismic monitoring networks require rapid post-event damage quantification.
- Agriculture Monitoring:Crop health classification, yield prediction, and plantation certification verification. Roundtable on Sustainable Palm Oil traceability mandates pull Sumatra and Borneo operators toward verified deforestation-free supply chain analytics.
- Environmental Assessment:Forest carbon accounting, biodiversity mapping, and coastal ecosystem monitoring. REDD+ protocols across Indonesian and Malaysian concessions require measurable, reportable biomass assessments.
- Urban Planning:Land use classification, infrastructure development tracking, and informal settlement mapping. Philippine municipal governments deploy for metropolitan expansion monitoring in Metro Manila and Cebu corridors.
Disaster Management commands the deepest procurement commitments while Agriculture Monitoring expands most quickly under sustainability certification pressure.
End User:
Customer sophistication determines service bundling complexity, with institutional buyers demanding integrated platforms against sector-specific point solutions.
- Government Agencies:National earth observation programs, defense ministries, and disaster management authorities. Indonesia's National Institute of Aeronautics and Space and Thailand's Geo-Informatics and Space Technology Development Agency consolidate procurement under sovereign capability frameworks.
- Agricultural Sector:Plantation conglomerates, agricultural cooperatives, and commodity traders. Malaysian and Indonesian palm oil operators subscribe to deforestation monitoring for European market access compliance.
- Environmental Organizations:Conservation NGOs, carbon credit verifiers, and multilateral climate funds. These buyers prioritize open-data accessibility and methodological transparency over proprietary analytics.
- Energy Sector:Hydrocarbon exploration teams, renewable site assessors, and pipeline operators. Offshore concession monitoring in Vietnamese and Malaysian waters drives radar imaging demand for all-weather coverage.
Government Agencies dominate contract value while the Agricultural Sector climbs fastest under supply chain traceability mandates.
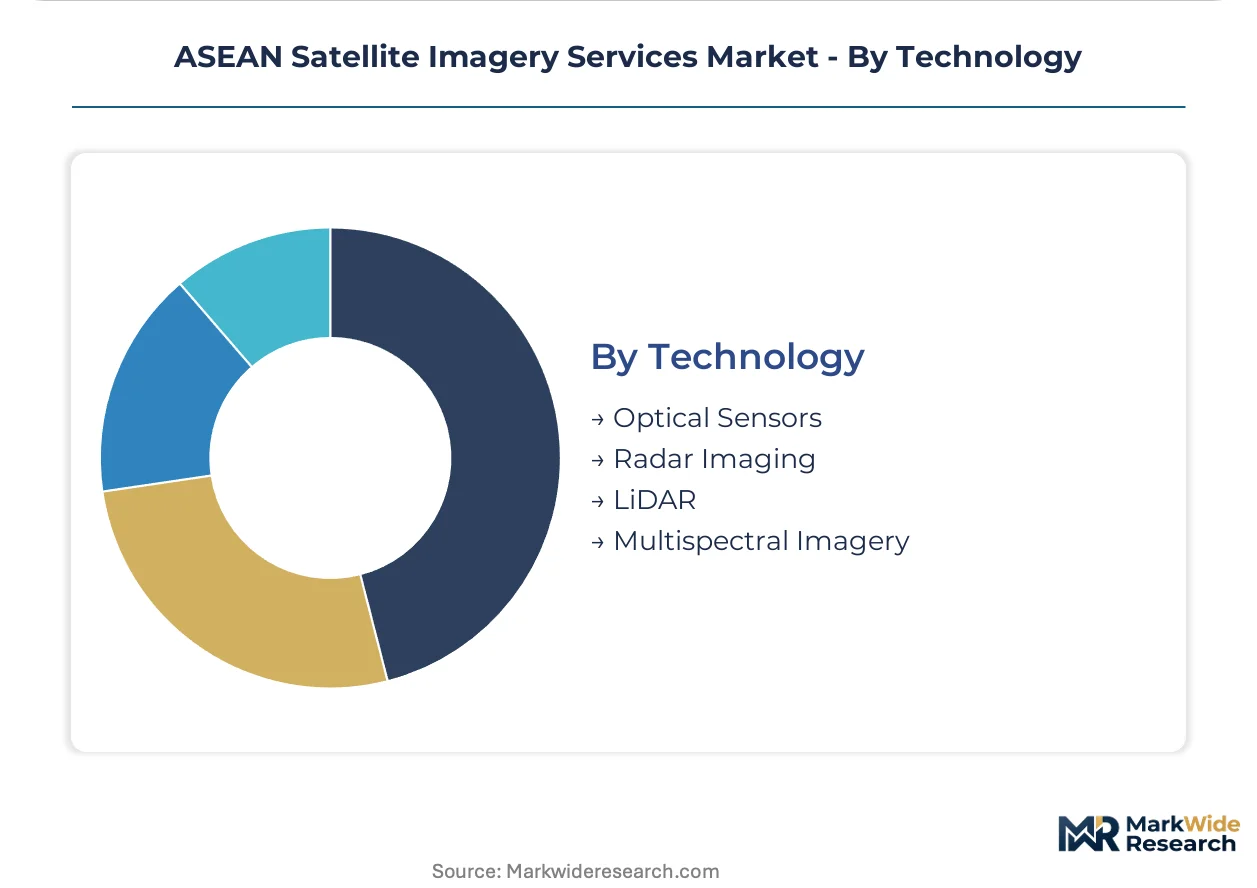
Technology:
Sensor modality determines collection reliability across equatorial climate patterns, with active systems penetrating markets where passive alternatives face persistent degradation.
- Radar Imaging:Synthetic aperture radar enabling all-weather, day-night surface observation regardless of cloud cover. Maritime surveillance applications across Indonesia's archipelagic waters and the Philippines' exclusive economic zone enforcement rely on this technology.
- Optical Sensors:Passive electro-optical imaging spanning panchromatic to multispectral wavelengths. Volume leadership persists in seasonal dry-period agriculture monitoring across Thailand and Vietnam where cloud interference diminishes.
- Multispectral Imagery:Narrow-band spectral capture for vegetation health, mineral identification, and water quality assessment. Plantation operators in Borneo deploy for precision agriculture and disease early detection.
- LiDAR:Light detection and ranging for three-dimensional terrain modeling and canopy structure analysis. Infrastructure planning authorities in Singapore and Kuala Lumpur utilize for dense urban digital elevation models.
Optical Sensors retain the installed base while Radar Imaging captures the steepest expansion trajectory as equatorial defense priorities harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense buyers in Singapore and Malaysia demonstrate the lowest price elasticity, while agricultural subscribers in Vietnam and Myanmar operate under severe budget constraints that compress margins for standard imagery products.
Indonesia
Archipelagic sea lane enforcement and plantation certification mandates drive persistent demand for synthetic aperture radar coverage. The National Institute of Aeronautics and Space coordinates procurement under sovereign capability frameworks requiring technology transfer. Jakarta and Surabaya host the dominant data processing clusters where local engineering partnerships are becoming contract prerequisites.
Thailand
Disaster risk reduction investments and flood prediction system upgrades anchor government subscription volumes. The Geo-Informatics and Space Technology Development Agency consolidates earth observation policy across civilian and defense applications. Bangkok metropolitan authorities deploy high-resolution optical archives for infrastructure corridor monitoring and informal settlement mapping.
Philippines
Exclusive economic zone enforcement gaps and maritime domain awareness programs create demand for persistent vessel tracking capabilities. The Department of Science and Technology shapes technical standards through public-private partnership frameworks. Cebu and Davao emerging as secondary procurement centers for municipal-scale urban planning applications.
Vietnam
Offshore hydrocarbon concession monitoring and coastal ecosystem management pull buyers toward all-weather radar subscriptions. National mapping agencies face analyst shortages that compress operationalization timelines for raw imagery. Ho Chi Minh City anchors the commercial reseller ecosystem serving agricultural cooperatives in the Mekong Delta.
Singapore
Smart nation infrastructure and dense urban digital elevation modeling sustain premium pricing for LiDAR and hyperspectral analytics. The national space office coordinates regional hub ambitions without indigenous launch capacity. One-north and Changi business parks concentrate data science talent serving ASEAN-wide plantation and insurance clients.
ASEAN Satellite Imagery Services Market Competitive Landscape
Constellation owners and regional resellers split the market along the fault line of proprietary orbital capacity versus local relationship networks. Vendor concentration privileges operators with direct satellite control, compressing margins for asset-light intermediaries lacking historical archive depth. Two archetypes dominate: sovereign-embedded multinationals committing technology transfer, and niche specialists offering hyperspectral or radar analytics. Competitive moves center on capacity expansion through small satellite constellation deployment and strategic partnerships with national mapping agencies.
Within the sovereign-embedded tier, Airbus and Maxar Technologies exemplify operators leveraging constellation ownership to sustain direct government contracts across multiple Southeast Asian capitals. L3Harris Corporation occupies a position emphasizing radar imaging capabilities for defense applications where all-weather reliability commands premium positioning. These three anchors represent the divergence between optical archive depth, synthetic aperture radar specialization, and integrated platform licensing approaches reshaping vendor selection criteria.
| Leading Market Players |
|---|
| Airbus |
| Maxar Technologies |
| L3Harris Corporation |
| Geocircle |
| Maptogis |
| Geoinfo Services Sdn Bhd |
| Ground Data Solutions R&D Sdn Bhd |
| Pasco Corporation |
| Sekala |
| Others |
Pricing and Supply Chain Analysis
The Malacca Strait shipping corridor's freight cost volatility compresses margins for optical sensor imports while amplifying price differentiation between radar-equipped platform providers and asset-light resellers lacking constellation control. This logistics chokepoint forces buyers to absorb premium pricing for all-weather imaging capabilities or accept seasonal collection windows degraded by equatorial cloud cover.
Pricing Analysis
Multi-year subscription renewals anchor lifetime value for constellation operators with deep historical archives, while per-image transactional pricing retreats to project-based aerial photography tiers. Three-tier pricing structure across premium radar subscriptions, standard optical archives, and economy aerial captures separates defense ministries from municipal planners from plantation cooperatives. Cost compression in the economy tier intensifies as regional resellers without proprietary orbital capacity compete on relationship networks alone. Agricultural subscribers in Vietnam and Myanmar exhibit the highest price elasticity, while Singaporean defense procurement demonstrates minimal sensitivity to premium positioning.
Supply Chain Analysis
Export control regimes restricting synthetic aperture radar technology limit component flows from US and European suppliers to ASEAN assembly partners, fragmenting vendor access for defense-grade systems. Manufacturing concentration centers on France, the United States, and Japan for high-resolution optical sensors, with South Korea and Taiwan supplying specialized semiconductor components for on-board processing payloads. The supply chain draws from gallium arsenide substrates, precision optics, and radiation-hardened electronics vulnerable to single-source dependencies. Distribution runs through national space agencies and defense procurement offices rather than open commercial channels, privileging sovereign-embedded operators with established government relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where constellation ownership creates switching costs that lock defense ministries into multi-year platform dependencies. Regulatory entrenchment through technology transfer mandates and national space roadmaps further hardens incumbent positions against asset-light challengers.
For Market Incumbents: Pre-empt small satellite constellation deployment in Indonesian and Philippine orbits before domestic launch capabilities mature, securing frequency allocations and ground station partnerships that emerging entrants cannot replicate. Deepen backward integration into edge computing payloads to compress analytics latency below 24-hour thresholds demanded by plantation certification workflows. Counter the threat of regional resellers aggregating CubeSat data by embedding local engineering teams in Jakarta and Bangkok procurement offices.
For New Entrants and Emerging Players: Myanmar's analyst shortage and legacy system integration gaps present the most penetrable entry point for hyperspectral analytics specialists offering decision-ready intelligence layers without requiring constellation ownership. Target Vietnamese agricultural cooperatives in the Mekong Delta through subscription models priced below defense-tier radar contracts but above economy aerial photography. Establish go-to-market partnerships with Ho Chi Minh City commercial resellers already embedded in provincial government relationships.
For Investors and Strategic Acquirers: Indonesia's sovereign capability framework reshapes the acquisition landscape by redirecting procurement preferences toward operators with technology transfer commitments and local assembly arrangements. Position holdings for a 5-10 year window where national space roadmaps mature into indigenous launch capacity, potentially displacing foreign constellation dependency. Target acquisition archetypes: niche radar analytics firms with Philippine maritime domain awareness contracts. Watch for Indonesia's domestic satellite manufacturing milestones as the inflection signal requiring portfolio recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Constellation Capacity Expansion | Additional synthetic aperture radar satellites secure exclusive economic zone monitoring contracts from Indonesia and the Philippines. |
| Technology Transfer Partnership | Local assembly commitments in Jakarta satisfy National Institute of Aeronautics and Space procurement eligibility requirements. |
| Hyperspectral Platform Launch | 24-hour crop health classification collapses value chain tiers separating plantation operators from agronomists in Sumatra. |
| Ground Station Network Buildout | Direct downlink infrastructure in Bangkok and Manila reduces latency for Thai flood prediction system integration. |
| Analytics Talent Acquisition | Vietnamese and Cambodian geospatial analyst hiring addresses operationalization bottlenecks at national mapping agencies. |
Research Methodology
Initial hypotheses were tested against primary input from defense procurement officers at ASEAN ministries, satellite constellation program managers, plantation sustainability directors, and national mapping agency technical leads and refined through secondary validation. Primary fieldwork encompassed structured interviews with earth observation policy coordinators at Thailand's Geo-Informatics and Space Technology Development Agency and Indonesia's National Institute of Aeronautics and Space. Secondary sources included ITU frequency allocation filings, national space roadmap policy documents, Roundtable on Sustainable Palm Oil certification databases, and customs records for satellite component imports. Bottom-up demand modeling from individual subscriber contracts was triangulated against top-down market sizing from constellation operator capacity disclosures.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service type, sensor modality, end-user sophistication, and national regulatory cluster. Modeled categories encompassed geospatial analytics subscriptions, remote sensing archives, aerial photography projects, and data management infrastructure alongside radar versus optical technology splits. CAGRs were derived from subscriber growth rates weighted by contract value escalation and technology substitution patterns. Forecast inputs incorporated Indonesia's sovereign capability timeline, Philippine maritime domain awareness budget allocations, and plantation certification mandate enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed constellation operators or accelerated Indonesian domestic launch programs would shift outcomes. Assumptions reflect observed procurement consolidation under national earth observation programs and sustained technology transfer requirements. Material shifts in ASEAN spectrum harmonization, sovereign launch capability attainment, or defense procurement centralization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Indonesia Satellite Communications Market
Satellite
Europe Satellite Manufacturing Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
Satellite Communication Subsystem Market
Satellite
Spain Satellite-Based Earth Observation Market
Satellite
High-Throughput Satellite Market
Satellite
Global Maritime Satellite Communication Market
Satellite
North America Remote Sensing Satellites Market
Satellite
Satellite Launch Vehicle (SLV) Market
Satellite
LEO Satellite Constellation Market
Satellite
Mexico Satellite Connectivity Market
Satellite
EMEA Satellite Antenna Market
Satellite
Satellite Link Emulator Market
Satellite
Africa Satellite Connectivity Market
Satellite
ASEAN Satellite Communications Market
Satellite
M2M Satellite Communication Market