
 Global Commercial Satellite Broadband Market | 2026-2036
Global Commercial Satellite Broadband Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Satellite Broadband Market Intelligence
United States orbital capacity build-out is reconfiguring supply availability across the commercial satellite broadband landscape. Space Exploration Technologies Corp. leverages reusable launch architecture to compress deployment timelines for constellation expansion. Viasat anchors geostationary service portfolios with high-throughput satellite investments in Ka-band infrastructure. SES S.A. competes through medium Earth orbit positioning that reduces latency for enterprise maritime contracts.
Commercial satellite broadband delivers internet connectivity via relay stations orbiting Earth, utilizing frequency bands including Ka-band, Ku-band, and C-band to transmit data between ground terminals and space-based assets at speeds comparable to terrestrial fiber in remote locations. Low Earth Orbit configurations achieve sub-50 millisecond latency through dense satellite constellations operating at altitudes below 2,000 kilometers, enabling real-time applications previously impossible with geostationary systems. Service offerings cluster around maritime connectivity and enterprise solutions where terrestrial infrastructure proves economically unviable, while consumer internet segments absorb capacity surplus from aviation and government contracts during off-peak demand cycles. Ka-band technology dominates new constellation design due to spectrum efficiency, though Ku-band retains installed-base relevance for broadcast content distribution.
FCC spectrum auctions and ITU coordination frameworks govern orbital slot assignments and interference management, directly constraining launch cadence and constellation density for operators seeking US market access. ESA and national regulators across European Union member states enforce debris mitigation standards through CE-pertinent licensing that shapes satellite design and end-of-life disposal protocols. Stakeholders must monitor spectrum reallocation proceedings and emerging optical inter-satellite link standards that will determine next-generation interoperability and competitive differentiation.
Market Dynamics
Low Earth Orbit constellation density is compressing latency benchmarks and forcing incumbent geostationary operators to reprice maritime and enterprise contracts. This orbital architecture shift is redistributing capacity economics across frequency bands and terminal form factors.
Growth Catalysts
- Maritime fleet modernization:Container shipping lines are mandating real-time hull monitoring and crew connectivity, driving Ka-band terminal installations on vessels transiting Pacific routes.
- FCC Rural Digital Opportunity Fund:The subsidy mechanism is channeling capital toward satellite operators serving census blocks where terrestrial fiber deployment costs exceed viability thresholds.
- Optical inter-satellite links:Laser-based backhaul between orbital nodes is eliminating ground station dependency for polar coverage, expanding addressable markets for scientific and defense applications.
Market Restraints
- Rocket launch capacity scarcity:Reusable first-stage availability constrains constellation deployment cadence, creating queue delays for operators without dedicated launch contracts.
- Spectrum coordination complexity:ITU filing backlogs and national landing rights negotiations extend market entry timelines by 18-36 months for non-incumbent operators.
- Ground terminal cost structure:Phased array antenna economics remain prohibitive for consumer mass adoption, limiting addressable market to enterprise and government segments.
Strategic Opportunities
- Indonesian archipelago connectivity:The national broadband plan identifies satellite as the only viable technology for 17,000+ islands outside submarine cable reach.
- In-flight connectivity unbundling:Airlines are decoupling bandwidth procurement from passenger service provision, creating direct contracting relationships with satellite operators.
- Quantum key distribution integration:Combining LEO constellations with quantum cryptography payloads addresses financial sector demand for tamper-proof transmission infrastructure.
Industry Challenges
- Orbital debris mitigation compliance:ESA-mandated end-of-life disposal protocols require propulsion reserves that consume 15-20% of satellite mass budget, complicating constellation design trade-offs.
- RF engineer scarcity:Specialist talent for Ka-band payload design concentrates in France, Germany, and the United States, creating recruitment bottlenecks for operators in other geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Satellite Broadband Market |
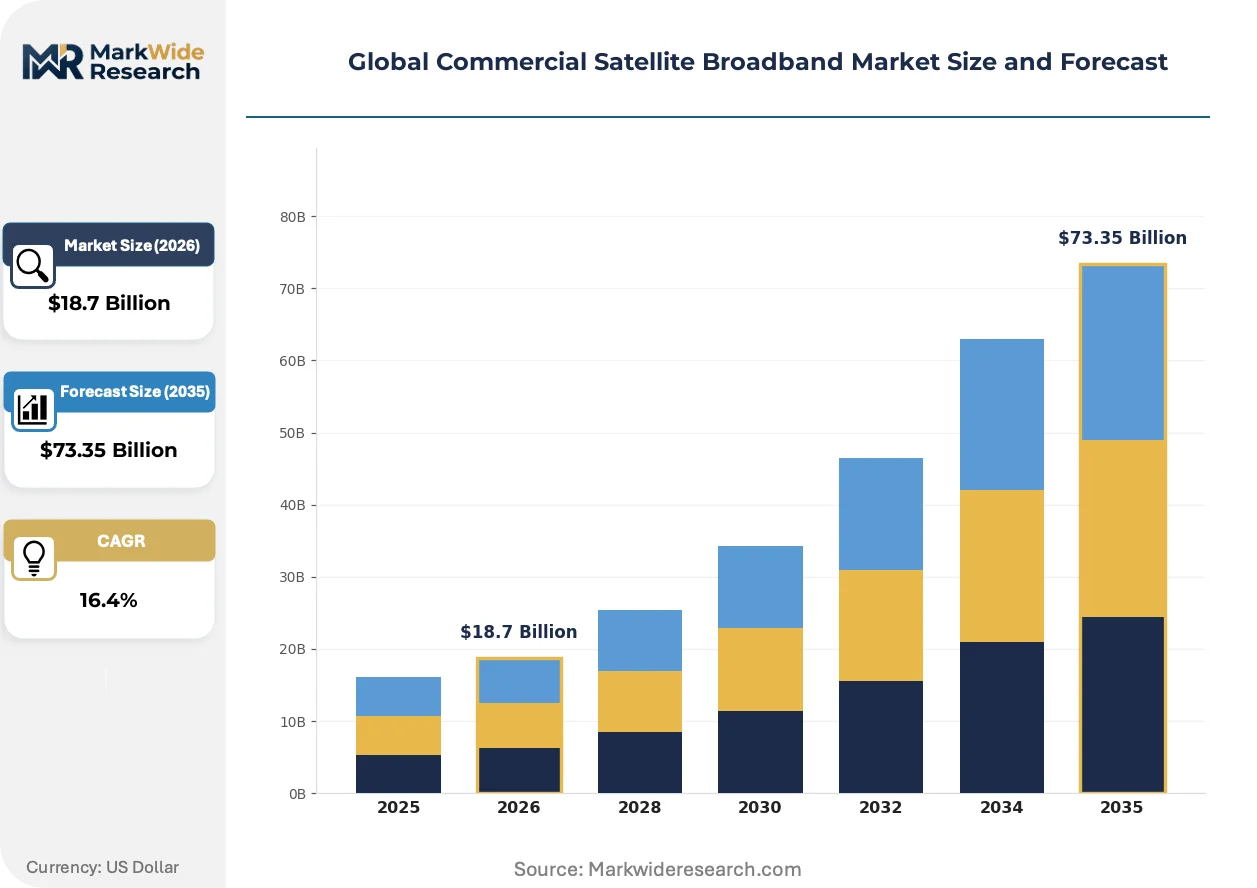
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Satellite Type: Geostationary, Medium Earth Orbit, Low Earth Orbit, Highly Elliptical Orbit Service Offering: Consumer Internet, Maritime Connectivity, Aviation Communication, Enterprise Solutions, Government Services Connectivity Technology: Ka-Band, Ku-Band, C-Band, L-Band, Optical Inter-Satellite Links Customer Segment: Broadband Providers, Network Operators, Content Distributors, Defense Agencies, Scientific Organizations |
| Companies Covered | Space Exploration Technologies Corp., Iridium Communications, Viasat, Gilat Satellite Networks, Telesat Corporation, SES S.A., EchoStar Corporation, Globalstar Inc., Intelsat S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Satellite Broadband Market Strategic Shifts & Innovations
Software-defined payload architectures are decoupling hardware from service provisioning, enabling operators to reconfigure coverage and capacity without replacing orbital assets. This flexibility is compressing product development cycles and blurring traditional segment boundaries.
Electronic beamforming is digitizing antenna control surfaces, replacing mechanical gimbals with solid-state arrays that track multiple satellites simultaneously. Maritime integrators are adopting these terminals for uninterrupted connectivity during vessel maneuvers in congested ports. The technology is digitizing how vessel operators manage bandwidth handoffs between orbital planes.
EU Space Traffic Management guidelines are mandating collision avoidance autonomy for new constellation authorizations, requiring onboard propulsion and decision logic that adds mass and complexity. Operators are redesigning satellite buses to accommodate these systems while maintaining launch cost targets. Medium Earth Orbit providers face the steepest compliance adjustments due to higher orbital velocities and crossing traffic densities.
Enterprise procurement teams are consolidating connectivity contracts under managed service frameworks that bundle terrestrial failover with primary satellite links. Energy sector buyers in remote extraction sites are driving this shift, demanding single-vendor accountability for uptime guarantees. The United States and Brazil exhibit the fastest migration toward these integrated service level agreements.
Global Commercial Satellite Broadband Market Segmentation
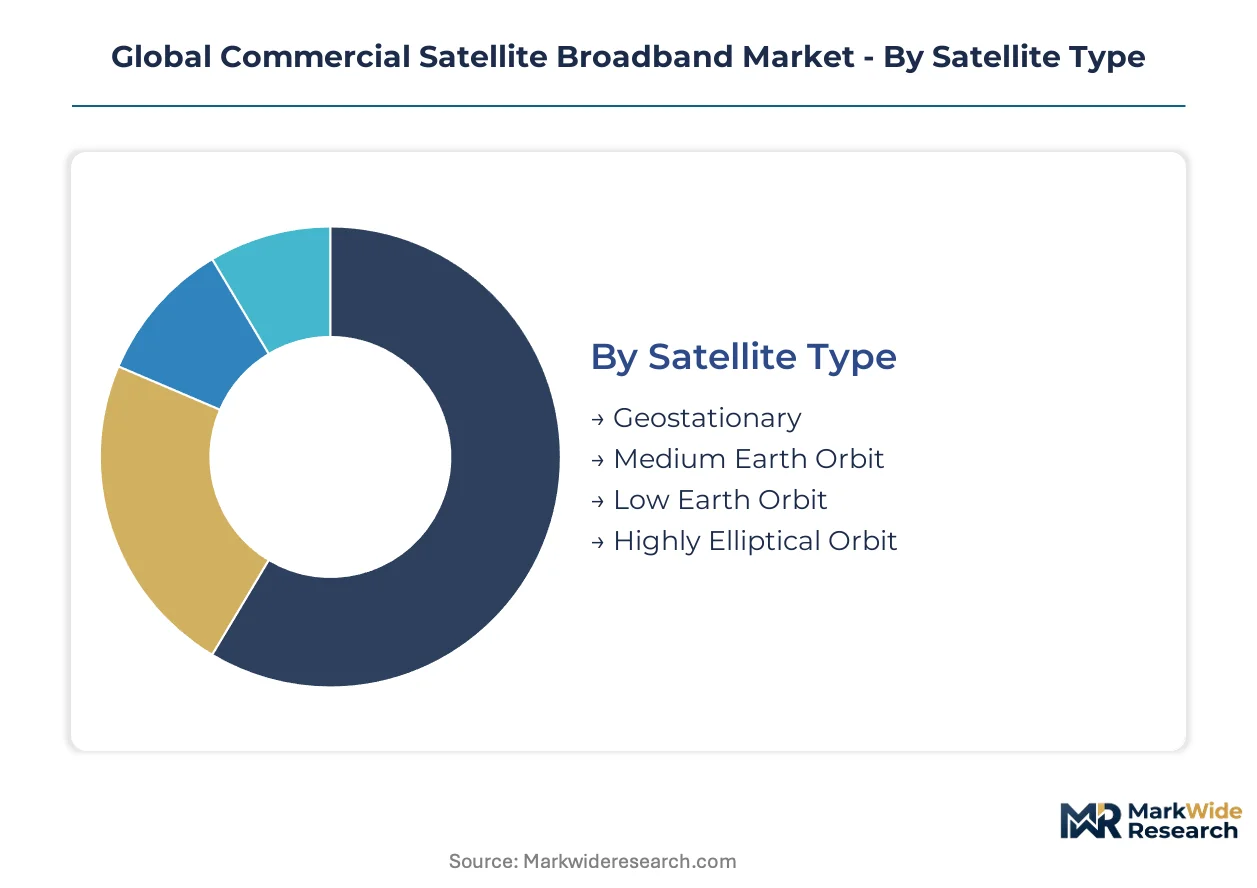
Orbital altitude and frequency allocation determine service economics across the commercial satellite broadband landscape. Operators segment offerings based on latency tolerance, terminal mobility requirements, and regulatory landing rights in target markets.
Satellite Type:
Orbital architecture spans stationary geostationary positions through rapidly moving low-altitude constellations, each delivering distinct latency-bandwidth trade-offs for specific use-case spectra.
- Geostationary:Fixed orbital position at 35,786 kilometers enables continuous coverage of continental landmasses with minimal ground infrastructure. Maritime shipping lines in the Pacific Basin rely on these assets for uninterrupted vessel tracking and crew welfare connectivity during transoceanic routes.
- Low Earth Orbit:Dense constellations below 2,000 kilometers achieve sub-50 millisecond latency through rapid satellite handoffs. United States rural broadband subsidy programs channel demand toward these systems where fiber deployment costs exceed economic viability thresholds.
- Medium Earth Orbit:Intermediate altitude reduces signal path length while maintaining fewer satellites than LEO configurations. European maritime operators favor these assets for reduced latency on North Atlantic shipping corridors.
- Highly Elliptical Orbit:Elongated orbital paths provide extended dwell time over high-latitude regions. Scientific stations in Arctic Norway and northern Canada depend on these satellites for seasonal research data transmission.
Established volume favors Geostationary; emerging adoption favors Low Earth Orbit.
Service Offering:
Revenue concentration shifts with mobility requirements and terrestrial infrastructure gaps across customer environments.
- Maritime Connectivity:Vessel-mounted terminals demand continuous beam tracking through antenna stabilization systems. Container fleets operating Singapore-to-Los Angeles routes mandate real-time hull monitoring and crew internet access.
- Enterprise Solutions:Dedicated bandwidth contracts serve extraction sites and remote logistics hubs. Energy sector procurement teams in Brazil and the United States consolidate connectivity under managed service frameworks with terrestrial failover guarantees.
- Aviation Communication:Air-to-ground links support passenger internet and cockpit data services. Airlines in the United States are decoupling bandwidth procurement from passenger service provision.
- Government Services:Sovereign capacity requirements drive dedicated military and civilian agency contracts. Defense agencies specify encrypted payloads and autonomous ground station operation.
- Consumer Internet:Mass-market residential terminals compete with terrestrial alternatives on price and reliability. Rural Digital Opportunity Fund subsidies in the United States expand addressable household penetration.
Defense and enterprise contracts anchor current revenue; aviation and consumer segments are climbing the fastest as terminal economics improve.
Connectivity Technology:
Frequency band selection governs spectrum efficiency, atmospheric resilience, and regulatory coordination complexity.
- Ka-Band:High-frequency spectrum above 26 GHz enables concentrated spot beams with aggressive frequency reuse. New constellation designs prioritize this band for capacity density in United States and European markets.
- Ku-Band:Established 12-18 GHz infrastructure supports broadcast content distribution and legacy maritime terminals. Installed-base relevance persists where Ka-band ground equipment replacement costs deter migration.
- C-Band:Lower frequency below 8 GHz penetrates heavy precipitation with minimal signal degradation. Tropical maritime routes and equatorial landmasses maintain demand for weather-resilient links.
- L-Band:Narrow spectrum allocation supports mobile voice and low-data messaging. Scientific organizations deploy these terminals for remote telemetry where bandwidth requirements remain minimal.
- Optical Inter-Satellite Links:Laser-based backhaul eliminates ground station dependency for polar and oceanic coverage. Financial sector interest is accelerating for quantum cryptography integration.
Ku-Band retains installed-base dominance; Optical Inter-Satellite Links are gaining share fastest as constellation density increases.
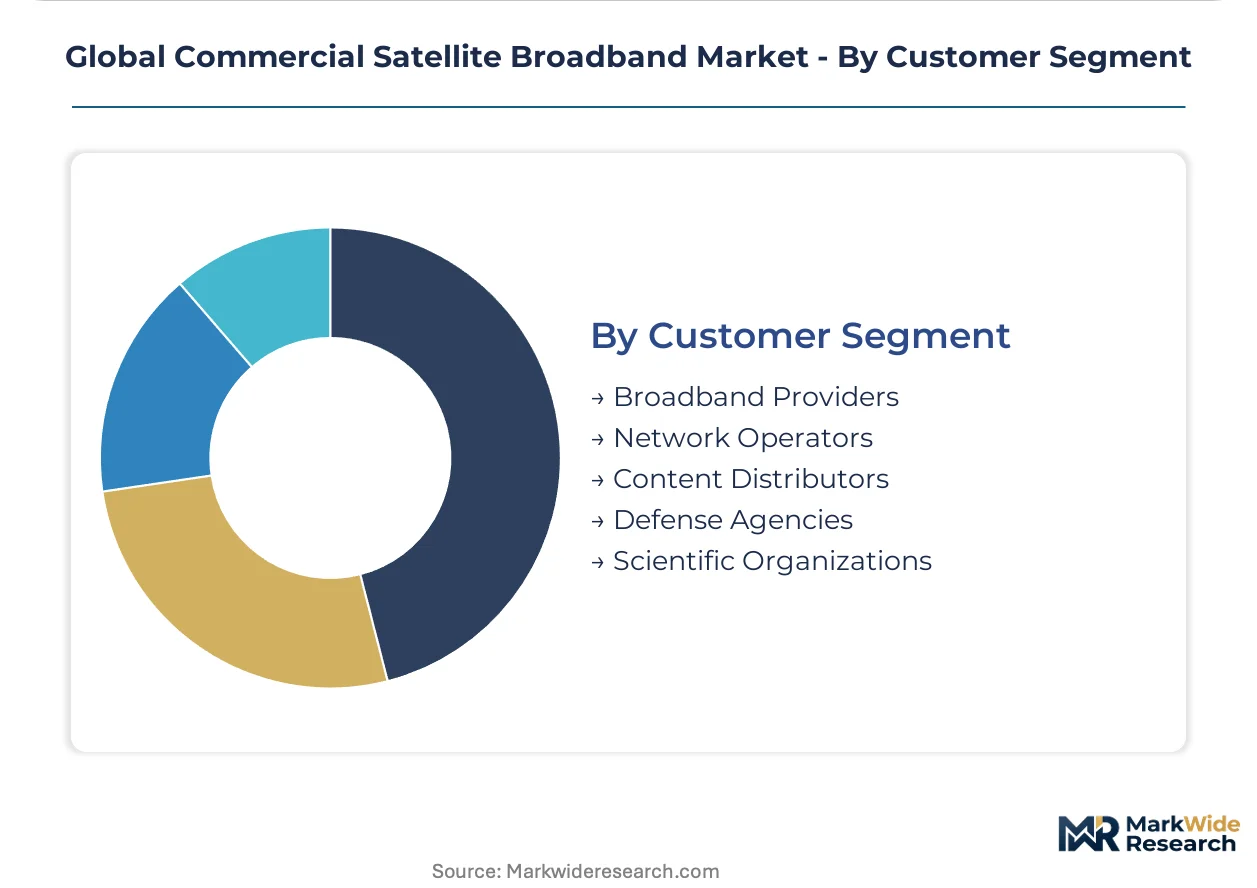
Customer Segment:
Procurement authority and technical integration requirements differentiate buyer categories across the value chain.
- Network Operators:Wholesale capacity purchasers integrate satellite links into hybrid terrestrial-satellite service portfolios. Indonesian archipelago connectivity planning identifies satellite as the sole viable technology for 17,000+ islands.
- Defense Agencies:Classified requirements drive hardened terminal specifications and dedicated orbital capacity. NATO member states and allied governments procure through consolidated framework agreements.
- Broadband Providers:Retail internet service providers resell satellite capacity under consumer-facing brands. United States rural markets concentrate demand where FCC subsidy mechanisms reduce subscriber acquisition costs.
- Content Distributors:Broadcast and streaming platforms require reliable multicast distribution to edge caches. Maritime and aviation integrators bundle entertainment content with core connectivity services.
- Scientific Organizations:Research institutions demand guaranteed availability for polar and oceanic data collection. Antarctic programs and oceanographic surveys specify autonomous operation without continuous ground station visibility.
Network operators command established procurement volume; defense agencies represent the steepest expansion trajectory as sovereign capacity requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Launch infrastructure concentrates in the United States and China, while maritime demand clusters along Pacific shipping lanes and European North Atlantic corridors. Regulatory frameworks diverge between FCC spectrum auctions and ITU coordination protocols. Terminal manufacturing distributes across Germany, South Korea, and the United States.
United States
FCC Rural Digital Opportunity Fund subsidies channel capital toward census blocks where fiber deployment costs exceed viability thresholds. SpaceX leverages reusable launch architecture from Cape Canaveral and Vandenberg to compress constellation deployment timelines. Seattle and Hawthorne host terminal engineering clusters advancing phased array antenna economics.
China
MIIT spectrum allocations and national broadband mandates accelerate LEO constellation authorization for remote western provinces. The national satellite internet plan prioritizes coverage of Qinghai and Xinjiang regions where terrestrial infrastructure remains sparse. Shanghai and Beijing concentrate payload manufacturing and ground system integration capabilities.
Germany
ESA debris mitigation standards through CE-pertinent licensing shape satellite design and end-of-life disposal protocols for European operators. Munich and Ottobrunn host RF engineering talent pools specializing in Ka-band payload architecture. German maritime operators favor MEO configurations for reduced latency on North Atlantic shipping corridors.
Brazil
ANATEL spectrum frameworks govern orbital slot assignments for operators seeking Latin American market access. Energy sector procurement teams in remote extraction sites consolidate connectivity under managed service frameworks with terrestrial failover guarantees. São Paulo anchors enterprise demand for hybrid satellite-terrestrial networks.
Indonesia
The national broadband plan identifies satellite as the sole viable technology for 17,000+ islands outside submarine cable reach. Ministry of Communication and Informatics regulations prioritize universal service obligations for archipelago connectivity. Jakarta concentrates network operator procurement authority for wholesale capacity contracts.
Global Commercial Satellite Broadband Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in antenna and payload supply chains. The vendor base organizes around three strategic archetypes: constellation operators with vertical launch integration, geostationary incumbents defending maritime enterprise contracts, and ground equipment manufacturers capturing terminal economics. Consolidation pressure intensifies as LEO density forces repricing of legacy service portfolios. Dominant competitive moves include spectrum portfolio accumulation through ITU filings and optical inter-satellite link deployment for polar coverage expansion.
Within the constellation operator tier, Space Exploration Technologies Corp. and Telesat Corporation occupy positions reflecting divergent orbital architectures and launch strategies. Viasat anchors the geostationary incumbent category with Ka-band infrastructure investments. SES S.A. represents the medium Earth orbit specialization targeting enterprise maritime latency requirements. These three entities exemplify how competitive positioning fragments across altitude bands and frequency allocations rather than consolidating around unified technical standards.
| Leading Market Players |
|---|
| Space Exploration Technologies Corp. |
| Iridium Communications |
| Viasat |
| Gilat Satellite Networks |
| Telesat Corporation |
| SES S.A. |
| EchoStar Corporation |
| Globalstar Inc. |
| Intelsat S.A. |
| Others |
Cost & Logistics Intelligence
Launch pad undercapacity at Cape Canaveral and Vandenberg is compressing deployment cadence for constellation operators, forcing price premiums for priority queue slots while squeezing terminal manufacturers into extended payment terms to preserve working capital.
Pricing Analysis
FCC Rural Digital Opportunity Fund subsidies dictate the pricing tier structure for consumer-facing satellite broadband in the United States. Three-tier pricing structure across premium maritime enterprise, standard rural residential, and economy government bulk contracts separates buyer segments by latency tolerance and service-level guarantees. Price differentiation hinges on Ka-band terminal certification grade and dedicated bandwidth allocation. Cost compression in the consumer tier is intensifying because SpaceX reusable launch economics are resetting cost baselines. Government defense agencies exhibit lowest price sensitivity due to sovereign capacity requirements; Indonesian network operators show highest sensitivity due to universal service obligation constraints.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for phased array antenna procurement, with supply-chain finance facilities emerging to bridge working capital gaps for terminal manufacturers. Manufacturing gravity centers on the United States for payload engineering, South Korea for semiconductor components, and Germany for RF subsystem integration. Raw material dependencies include gallium nitride for power amplifiers, specialized aluminum-lithium alloys for satellite buses, and rare earth elements for magnet manufacturing. Single-source vulnerability concentrates in solid-state power amplifier suppliers. Distribution runs through direct operator-to-enterprise contracting for maritime and energy sectors, with broadband providers intermediating consumer retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized Ka-band RF engineering talent pools in France, Germany, and the United States are constraining constellation design velocity, creating acquisition premiums for teams with flight-proven payload experience.
For Market Incumbents: Entrench maritime enterprise relationships through managed service frameworks bundling terrestrial failover with primary satellite links. Defend against LEO latency displacement by accelerating MEO constellation refresh cycles. Prioritize ITU spectrum portfolio accumulation to block non-incumbent orbital filings. For New Entrants and Emerging Players: Indonesian archipelago connectivity represents the most penetrable entry point, with 17,000+ islands outside submarine cable reach creating wholesale capacity demand. Arctic scientific stations and polar shipping routes offer second-mover white space. Pursue direct airline contracting relationships as in-flight connectivity unbundling accelerates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across optical inter-satellite link payload manufacturing as laser component costs decline. Long-term viability favors operators with demonstrated launch cadence execution and ITU filing precedence. Acquisition targets should show vertical integration into terminal manufacturing or captive launch capacity. Monitor FCC Rural Digital Opportunity Fund disbursement velocity as inflection indicator for consumer segment addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Inter-Satellite Link Deployment | Laser-based backhaul eliminates polar ground station dependency for scientific and defense applications. |
| Reusable Launch Architecture Expansion | SpaceX Falcon 9 cadence compression resets constellation deployment cost baselines industry-wide. |
| Managed Service Framework Consolidation | Energy sector buyers in Brazil and the United States demand single-vendor uptime accountability. |
| Spectrum Portfolio Accumulation | ITU filing precedence determines orbital slot access and interference protection for next-generation constellations. |
| Phased Array Terminal Cost Reduction | Solid-state antenna economics improvement unlocks consumer mass-market penetration beyond enterprise segments. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with constellation program directors, maritime fleet technology officers, RF payload engineers, and FCC regulatory counsel; and secondary validation through ITU satellite network filings, FCC Rural Digital Opportunity Fund disbursement records, ESA debris mitigation compliance databases, and operator launch manifests. Bottom-up capacity modeling triangulated against top-down subsidy allocation analysis.
Forecast inputs include orbital altitude segment growth, frequency band adoption curves, and service offering revenue mix shifts across the projection horizon. Segmentation dimensions modeled encompass satellite type, connectivity technology, and customer procurement authority. CAGRs were derived from launch cadence projections, terminal deployment economics, and subsidy program budget trajectories. Industry-specific inputs incorporate ITU coordination timeline backlogs and reusable first-stage availability constraints.
Macroeconomic conditions sit as an overlay; deviation in launch insurance premiums, rare earth element pricing, or FCC appropriation continuity would shift the trajectory. Forecasts reflect documented assumptions on spectrum allocation timelines and debris mitigation compliance costs. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Commercial Satellite Imaging Market
Satellite
Sudan Satellite Transponder Market
Satellite
Commercial Satellite Launch Service Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
India Satellite-Based Earth Observation Market
Satellite
Fixed Satellite Services (FSS) Market
Satellite
Russia Satellite Communications Market
Satellite
Satellite Manufacturing Market
Satellite
Electric Propulsion Satellite Market
Satellite
Satellite Antenna Market
Satellite
Vehicle Mounted Satellite Communication Station Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
US Satellite Connectivity Market
Satellite
Asia-Pacific Satellite Connectivity Market
Satellite
UAE Satellite Imagery Services Market
Satellite
Global LEO Satellite Market