
 Iran Defense Market | 2026-2036
Iran Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Defense Market Foresight
Procurement from Iran's armed forces is consolidating around state-controlled conglomerates, reducing vendor fragmentation. Defense Industries Organization sustains vertically integrated manufacturing of armored vehicles and artillery systems. Iran Electronics Industries specializes in domestic radar and electronic warfare components. Aerospace Industries Organization anchors ballistic missile production and unmanned aerial vehicle development.
Iran defense encompasses military equipment, platforms, and systems designed for national security operations, incorporating composite armor, solid-fuel propulsion, and frequency-hopping communications. The sector serves territorial defense, asymmetric warfare deterrence, and regional power projection. Land Systems and Munitions represent mature segments with established production lines and state-funded replenishment cycles. Air Defense Systems and Missile Technology attract concentrated R&D investment due to strategic priority and export potential. Surveillance Systems within the technology dimension show expanding integration with indigenous satellite and signals-intelligence infrastructure.
Iran's defense sector operates under oversight from the Ministry of Defense and Armed Forces Logistics, with procurement shaped by sanctions-evasion protocols and domestic substitution mandates. The country's national standards body enforces military-grade specifications for electronics and metallurgy, restricting foreign component reliance. Stakeholders must monitor how procurement centralization affects subcontractor access and whether technology transfer limitations redirect investment toward captive supply chains.
Market Dynamics
Procurement consolidation around the Islamic Revolutionary Guard Corps is compressing vendor access and redirecting supply chains toward state-controlled manufacturing conglomerates. This centralization is eliminating traditional subcontractor tiers and mandating backward integration into metallurgy and electronics production.
Growth Catalysts
- Domestic Substitution Mandates:Iran's Ministry of Defense and Armed Forces Logistics enforces component localization protocols that redirect funding toward captive foundries and semiconductor packaging facilities.
- Solid-Fuel Propulsion Advances:Indigenous composite motor casing production is reducing reliance on foreign precursor chemicals for ballistic and cruise missile programs.
- Tehran Defense Industrial Corridor:Geographic concentration of aerospace and electronics manufacturing in the capital region is enabling just-in-time assembly integration and reducing logistics friction.
Market Restraints
- Sanctions-Evasion Input Costs:Dual-use component sourcing through third-country intermediaries adds 40-60% procurement overhead for precision guidance electronics.
- Foreign Metallurgy Dependence:High-grade aluminum-lithium alloys and titanium billets remain concentrated in non-aligned supplier networks with irregular shipment reliability.
- Technical Limitation in Turbofan Engines:Domestic propulsion systems for manned aircraft plateau at subsonic performance thresholds, constraining fighter modernization cycles.
Strategic Opportunities
- Unmanned Aerial Vehicle Export Markets:Shahed-series loitering munitions and reconnaissance platforms are penetrating African and Central Asian defense procurement channels.
- Signals Intelligence Integration:Convergence of indigenous satellite infrastructure with ground-based electronic warfare systems is opening integrated surveillance-as-capability offerings.
- Khorasan Industrial Zone Expansion:Eastern Iran's underdeveloped manufacturing belt offers tax-advantaged production sites for ammunition and propellant facilities.
Industry Challenges
- Aerospace Systems Engineering Talent Gap:Domestic universities produce insufficient flight-control software and aerodynamics specialists for next-generation platform development.
- Legacy Platform Integration Complexity:Retrofitting 1970s-era airframes with modern avionics requires reverse-engineering foreign bus architectures with incomplete documentation.
- ITAR-Analogue Compliance Timeline:Iran's national standards body certification cycles for military-grade electronics extend 18-24 months, delaying product qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Defense Market |
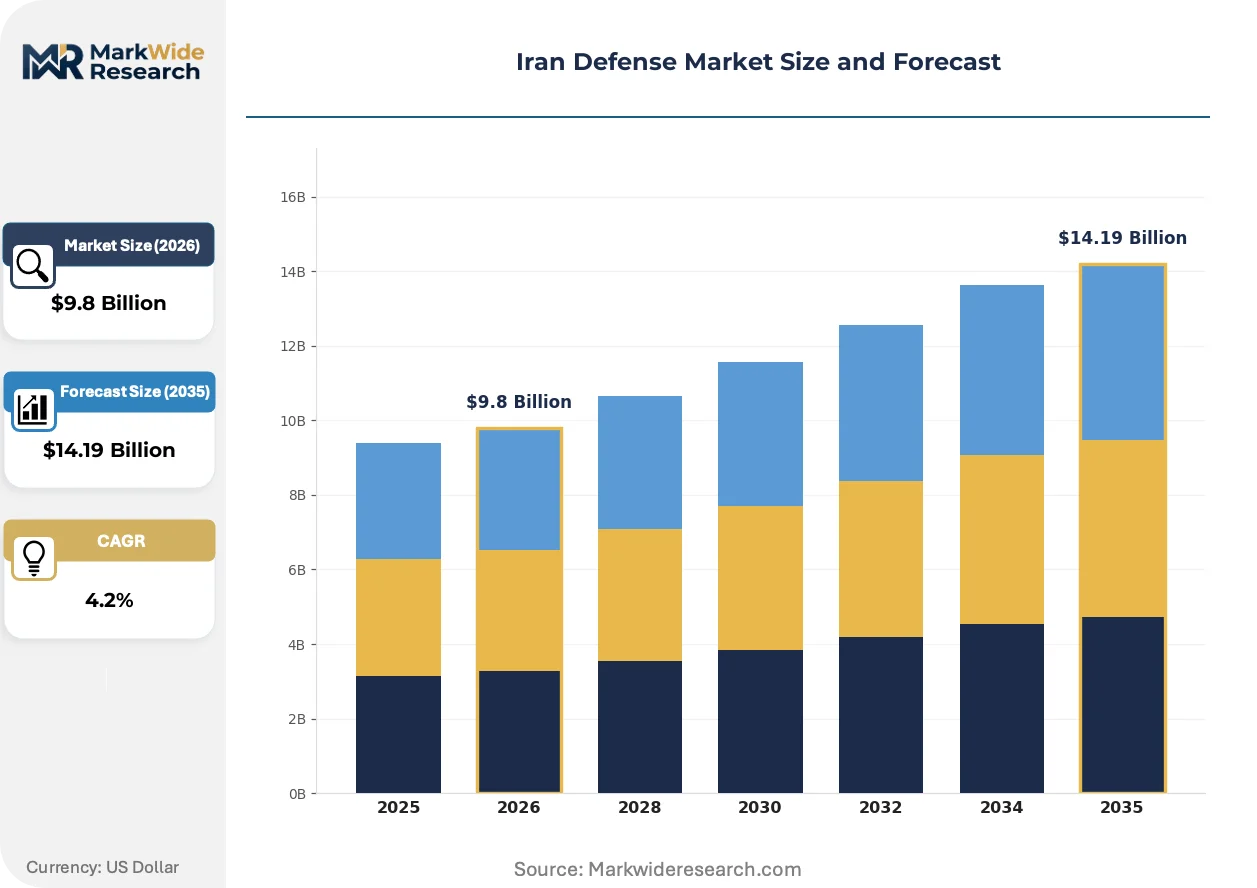
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.19 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Land Systems, Naval Vessels, Air Defense Systems, Munitions Technology: Missile Technology, Cybersecurity Solutions, Surveillance Systems, Radar Systems Application: National Security, Counterterrorism, Border Security, Intelligence Gathering End User: Armed Forces, Paramilitary Groups, Government Agencies, Defense Contractors |
| Companies Covered | Iran Electronics Industries, Defense Industries Organization, Aerospace Industries Organization, Aviation Industries Organization, Marine Industries Organization, General Dynamics, Lockheed Martin, Northrop Grumman, Raytheon Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Defense Market Shifts & Advancements
Frequency-hopping communications and solid-state radar architectures are displacing analog systems across Iran's defense electronics sector. These shifts are compressing development cycles and enabling platform miniaturization.
GaN-based active electronically scanned array technology is electrifying domestic radar and electronic warfare programs. The Aerospace Industries Organization has accelerated adoption for air defense and maritime surveillance applications. This transition is enabling simultaneous multi-target tracking capabilities that previously required foreign subsystem imports.
Iran's national standards body has tightened military-grade electronics specifications to mirror ISO 9001 and MIL-STD traceability requirements. Industrial consequence includes mandatory lot-tracking for semiconductor components and metallurgical batches. Air Defense Systems manufacturers face the steepest compliance burden, with qualification timelines extending to capture supply chain provenance documentation.
Buyer concentration within the Islamic Revolutionary Guard Corps is compressing traditional competitive bidding cycles into sole-source negotiations with state conglomerates. Defense Industries Organization and Iran Electronics Industries now capture direct development contracts that previously filtered through multiple subcontractor tiers. This pattern is most visible in Tehran's defense industrial corridor, where procurement officers prioritize supply security over unit cost minimization.
Iran Defense Market Segmentation
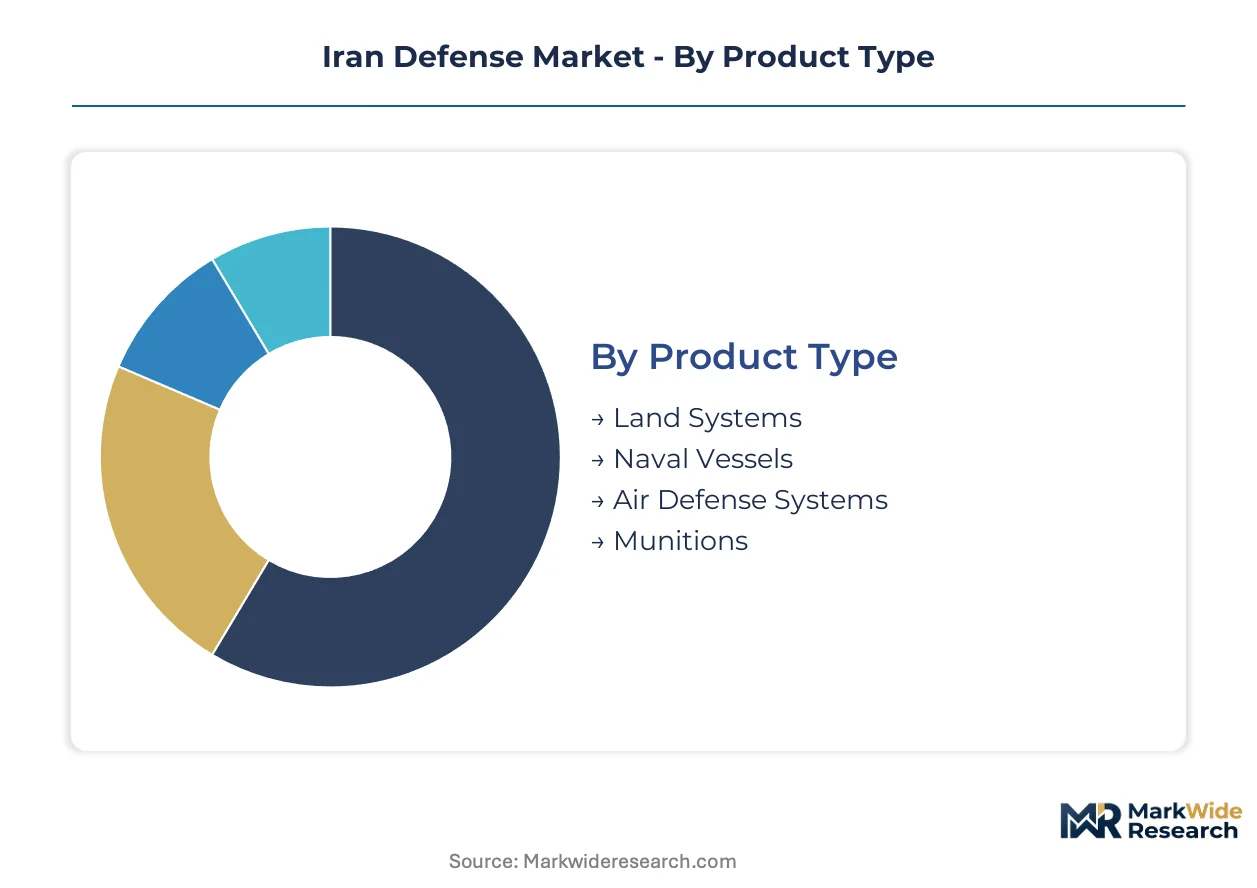
Segmentation reveals how procurement centralization under the Islamic Revolutionary Guard Corps redirects demand toward specific product categories and technologies. Understanding these divisions clarifies where state conglomerates concentrate manufacturing investment versus where sanctions-evasion sourcing persists.
Product Type:
Standardization dominates land and naval platforms with mature production lines, while air defense and munitions retain customization flexibility for mission-specific requirements.
- Land Systems:Armored vehicles and artillery platforms incorporate composite armor and domestic steel alloys. Demand concentrates within the Defense Industries Organization's Tehran corridor facilities, driven by ground force modernization cycles and state-funded replenishment mandates.
- Air Defense Systems:Indigenous GaN-based radar and solid-state architectures enable simultaneous multi-target tracking. Procurement centralizes around Aerospace Industries Organization development contracts, propelled by strategic priority for territorial defense and regional deterrence capabilities.
- Naval Vessels:Coastal patrol craft and submarine production at Bandar Abbas facilities.
- Munitions:Small-caliber ammunition and propellant manufacturing across state-controlled foundries.
Leading the category by volume: Land Systems. Growing fastest: Air Defense Systems.
Technology:
Cost tier stratification separates mature radar exports from capital-intensive missile R&D requiring captive semiconductor production.
- Missile Technology:Solid-fuel propulsion systems with composite motor casings reduce foreign precursor dependence. Development concentrates at Aerospace Industries Organization facilities in Tehran, shaped by ballistic and cruise program expansion and Shahed-series export demand.
- Surveillance Systems:Integration of indigenous satellite infrastructure with ground-based signals-intelligence platforms. Investment clusters within Iran Electronics Industries, driven by convergence of electronic warfare and space-based reconnaissance capabilities.
- Cybersecurity Solutions:Military-grade encryption and frequency-hopping communications for command networks.
- Radar Systems:Active electronically scanned array production for air defense and maritime applications.
Highest margin capture: Missile Technology. Steepest expansion trajectory: Surveillance Systems.
Application:
Customer-type concentration distinguishes routine territorial operations from intelligence activities requiring specialized vendor clearances.
- National Security:Territorial defense and strategic deterrence encompassing ballistic missile deployment and air defense networks. Procurement flows through Ministry of Defense and Armed Forces Logistics channels with sole-source contracting protocols.
- Intelligence Gathering:Signals-intelligence and satellite reconnaissance integration for regional monitoring. Demand localizes within Islamic Revolutionary Guard Corps technical divisions, propelled by indigenous space program advancement and cross-border surveillance requirements.
- Counterterrorism:Rapid-response units and internal security operations.
- Border Security:Perimeter surveillance and coastal monitoring installations.
Dominant budget allocation: National Security. Gaining share fastest: Intelligence Gathering.
End User:
Supply concentration intensifies from fragmented contractor tiers toward armed forces and paramilitary direct contracting with state conglomerates.
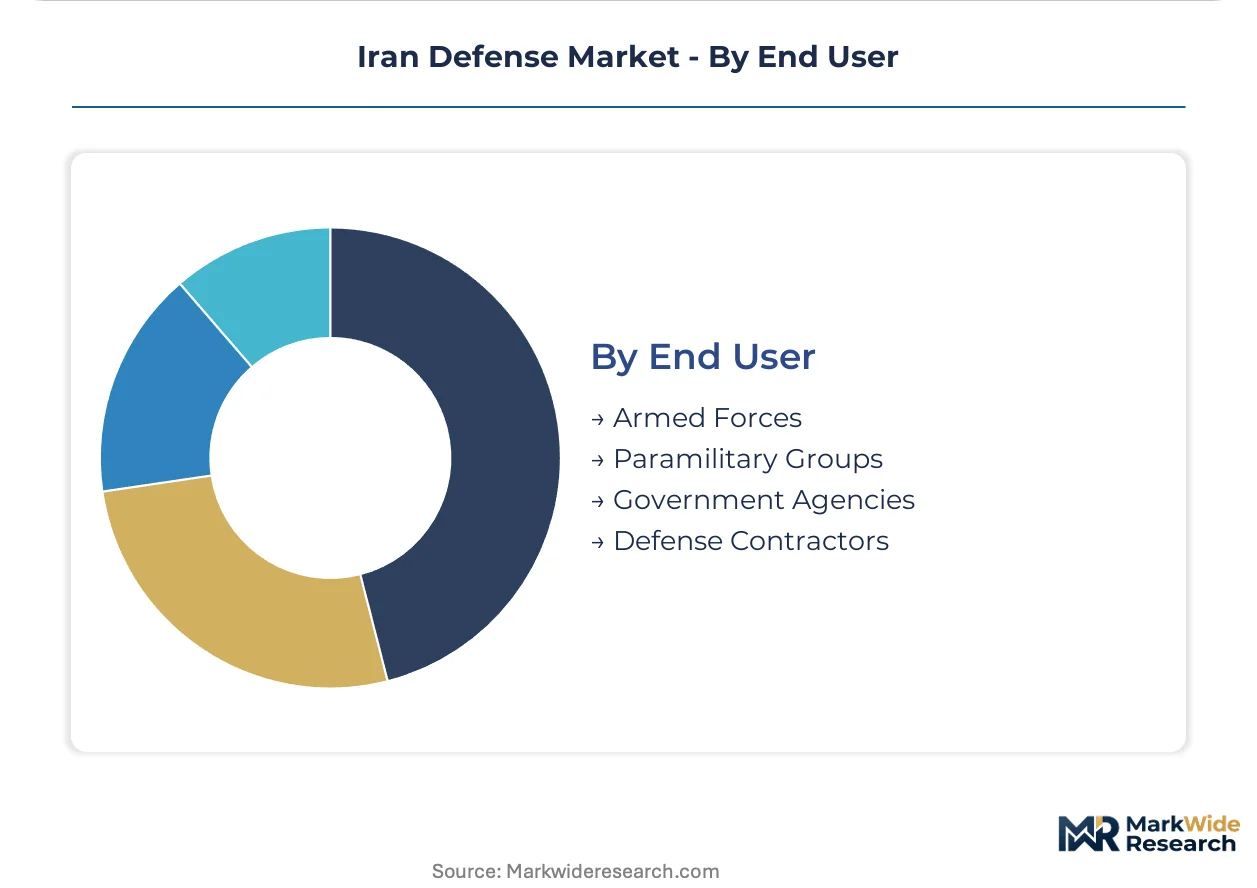
- Armed Forces:Artillery, armor, and conventional air defense procurement through formal military acquisition channels. Volume concentrates in land systems replacement cycles, shaped by Artesh ground force restructuring and equipment standardization mandates.
- Paramilitary Groups:Islamic Revolutionary Guard Corps asymmetric warfare capabilities including unmanned aerial vehicles and missile systems. Procurement centralizes through direct development contracts with Aerospace Industries Organization, driven by expeditionary force requirements and technology export programs.
- Government Agencies:Ministry of Intelligence and national police technical equipment.
- Defense Contractors:Subsystem suppliers and component fabricators under state conglomerate oversight.
Largest procurement volume: Armed Forces. Fastest contract growth: Paramilitary Groups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration within Tehran's defense industrial corridor is redirecting demand patterns across Iran's domestic geography. State-controlled conglomerates are consolidating manufacturing investment in the capital region while peripheral zones capture satellite production mandates.
Tehran Province
Ballistic missile development and GaN-based radar manufacturing dominate procurement flows. The Ministry of Defense and Armed Forces Logistics enforces sole-source contracting protocols for strategic programs. The Parchin and Shahid Hemmat industrial complexes anchor solid-fuel propulsion and aerospace assembly integration.
Isfahan Province
Uranium conversion and metallurgical processing facilities support nuclear and defense material supply chains. Iran's national standards body mandates military-grade certification for specialty alloys produced here. The Esfahan Nuclear Technology Center corridor concentrates precision machining and component fabrication.
Semnan Province
Solid-fuel motor testing and space launch infrastructure drive capital allocation. The Imam Khomeini Space Port and adjacent military ranges enable integrated missile and satellite program development. Domestic substitution mandates prioritize captive propellant chemistry production in this eastern corridor.
Hormozgan Province
Naval vessel construction and coastal defense systems procurement concentrate at Bandar Abbas shipyards. The Marine Industries Organization operates submarine and fast-attack craft assembly lines. Maritime surveillance radar integration with indigenous satellite infrastructure is expanding regional electronic warfare capabilities.
Khorasan Razavi Province
Ammunition and small-caliber munitions manufacturing attracts tax-advantaged investment under eastern development incentives. The Khorasan Industrial Zone offers subsidized land and energy for propellant and explosives facilities. State conglomerates are relocating volatile chemical processing away from Tehran's population center.
Iran Defense Market Competitive Landscape
Tehran-based state conglomerates anchor one tier; peripheral industrial zone operators hold subcontractor and component supply positions. The vendor structure is consolidating rapidly as the Islamic Revolutionary Guard Corps compresses procurement channels into direct development contracts. Three archetypes dominate: vertically integrated prime contractors, captive metallurgy and electronics foundries, and sanctions-evasion sourcing intermediaries. Competitive moves center on backward integration into semiconductor packaging and alloy production, plus geographic diversification of volatile chemical processing.
Among state-controlled defense conglomerates, Iran Electronics Industries, Defense Industries Organization, and Aerospace Industries Organization exemplify the prime contractor archetype. These entities occupy positions as sole-source recipients for major platform development, representing the consolidation endpoint that eliminates traditional competitive bidding. Their structure as ministry-affiliated organizations enables direct access to state-funded replenishment cycles and strategic priority programs.
| Leading Market Players |
|---|
| Iran Electronics Industries |
| Defense Industries Organization |
| Aerospace Industries Organization |
| Aviation Industries Organization |
| Marine Industries Organization |
| General Dynamics |
| Lockheed Martin |
| Northrop Grumman |
| Raytheon Corporation |
| Others |
Supply & Pricing Matrix
Islamic Revolutionary Guard Corps procurement centralization enforces sole-source contracting that eliminates competitive bidding premiums. State conglomerates capture development contracts through ministry-affiliated channels, compressing price discovery into security-weighted negotiations rather than cost-minimization frameworks.
Pricing Analysis
Volume procurement of land systems and munitions trades at thin margins against state replenishment mandates, while missile technology and GaN-based radar systems command development premiums. Price differentiation hinges on strategic priority tiering and captive foundry certification status under Iran's national standards body protocols. Cost compression in precision guidance electronics intensifies because sanctions-evasion sourcing through third-country intermediaries layers procurement overhead. Ground force modernization programs exhibit highest price sensitivity due to standardized equipment cycles, whereas air defense networks tolerate premium positioning for territorial deterrence capabilities.
Supply Chain Analysis
Freight routing through Dubai and Istanbul intermediaries dominates dual-use component ingress, with logistics costs amplified by documentation fragmentation and transshipment complexity. Supply concentration centers on China for semiconductor packaging equipment, Russia for titanium billet feedstock, and domestic Tehran corridor facilities for solid-fuel propulsion assembly. Raw material dependencies encompass high-grade aluminum-lithium alloys, frequency-hopping communications chipsets, and composite motor casing precursors. Single-source vulnerability pervades turbofan engine component streams. Distribution runs through Ministry of Defense and Armed Forces Logistics procurement officers directly to state conglomerate manufacturing complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iran's defense market functions as a vertical-integration race where captive control over metallurgy and semiconductor packaging determines contract access. Players securing backward integration into alloy production and propellant chemistry capture procurement preference from consolidated buyers.
For Market Incumbents: Deploy certification acceleration as a competitive moat. State conglomerates should compress Iran's national standards body qualification timelines for military-grade electronics to 12-15 months through pre-submission documentation protocols, defending against emerging foundry entrants in Khorasan Industrial Zone. Captive supply of GaN-based active electronically scanned array substrates reinforces Aerospace Industries Organization positioning against Electronics Industries radar division encroachment. For New Entrants and Emerging Players: Capture ammunition and propellant manufacturing relocation opportunities in Khorasan Razavi Province. Tax-advantaged eastern development incentives and subsidized energy access create penetrable white space for volatile chemical processing facilities displaced from Tehran's population center. Direct contracting with Defense Industries Organization for small-caliber foundry output bypasses traditional subcontractor tier exclusion. For Investors and Strategic Acquirers: The window for entry favors semiconductor packaging equipment specialists with sanctions-evasion logistics expertise. Long-term viability hinges on dual-use technology transfer capabilities that survive trade restriction volatility. Acquisition targets should exhibit captive alloy certification and Ministry of Defense sole-source contract history. Watch for signals of indigenous satellite infrastructure convergence with ground-based electronic warfare as inflection indicator for surveillance systems investment priority.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallurgy | Captive aluminum-lithium alloy production reduces Aerospace Industries Organization foreign billet dependence. |
| Semiconductor Packaging Facility Expansion | Domestic GaN substrate fabrication enables Iran Electronics Industries radar qualification acceleration. |
| Khorasan Industrial Zone Relocation | Tax-advantaged propellant chemistry processing attracts Defense Industries Organization ammunition investment. |
| Signals Intelligence Platform Integration | Satellite-ground electronic warfare convergence opens Islamic Revolutionary Guard Corps procurement channels. |
| Solid-Fuel Propulsion Certification | Composite motor casing standardization secures Aerospace Industries Organization ballistic program dominance. |
Research Methodology
Independent corroboration across Ministry of Defense procurement officers, state conglomerate technical directors, and sanctions-evasion logistics intermediaries underwrites the qualitative findings. Primary interviews with ballistic program engineers, radar systems architects, and metallurgical certification specialists combined with secondary validation from customs trade data, UN arms registry filings, and industrial facility satellite imagery analysis. Bottom-up segment sizing triangulates against top-down defense budget allocation assessments across the analysis window.
Rate-of-change decomposition separates volume effects from mix-shift and pricing dynamics throughout the forecast period. The analytical framework models product type segmentation across land systems, air defense, naval vessels, and munitions; technology segmentation across missile systems, surveillance, cybersecurity, and radar; application segmentation across national security, intelligence gathering, counterterrorism, and border security; and end-user segmentation across armed forces, paramilitary groups, government agencies, and defense contractors. CAGRs derive from procurement cycle timing, state funding authorization trajectories, and substitution mandate enforcement intensity.
The model holds under sustained sanctions architecture and domestic substitution policy continuity; deviation in trade restriction relaxation or regional conflict escalation would shift demand composition and investment priority. Forecasts reflect documented assumptions regarding procurement centralization persistence and state conglomerate manufacturing capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Military Tank Container Market
Military Vehicles
Southeast Asia Defense Market
Military Vehicles
Indonesia Defense Market
Military Vehicles
Military Trucks Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Military Ground Vehicle Actuators Market
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Military Amphibious Vehicle Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Japan Defense Market
Military Vehicles
Main Battle Tank Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Russia Defense Market