
 Commercial Aircraft Air Management System Market | 2026-2036
Commercial Aircraft Air Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Air Management System Market Outlook
The EU Green Deal's aviation emissions targets is rebalancing OEM sourcing criteria toward lighter, more efficient thermal architectures. Honeywell International Inc. leverages its integrated environmental control portfolio to sustain long-term contracts with major airframers. Parker Hannifin Corporation anchors the high-pressure pneumatic valve segment through captive manufacturing of precision components. Safran SA differentiates via electric air management architectures that reduce engine bleed dependency.
Commercial Aircraft Air Management Systems encompass the integrated pneumatic, thermal, and pressure-regulating subsystems that condition engine bleed air and recirculated cabin air to maintain safe temperature, pressure, and air quality throughout all flight phases. These systems typically operate across pressure differentials up to 8.6 psi at cruise altitude while managing airflow rates exceeding 500 cubic feet per minute per cabin zone. Environmental Control Systems dominate installed value due to their central role in integrating heating, cooling, and filtration functions across the airframe. Electric technology architectures represent the fastest-expanding segment as airframers pursue more-electric aircraft designs that replace pneumatic ducts with distributed motor-driven compressors and fans.
FAA airworthiness standards under Part 25 dictate cabin altitude limits and smoke penetration resistance that shape system redundancy requirements and certification testing protocols. EASA CS-25 harmonization with FAA rules creates a unified regulatory baseline for suppliers seeking dual-jurisdiction approval, while REACH chemical restrictions influence sealant and lubricant selections in European-sourced components. Stakeholders must monitor the pace of electric architecture certification timelines and position supply chains for the transition from centralized pneumatic manifolds to distributed electromechanical actuation.
Market Dynamics
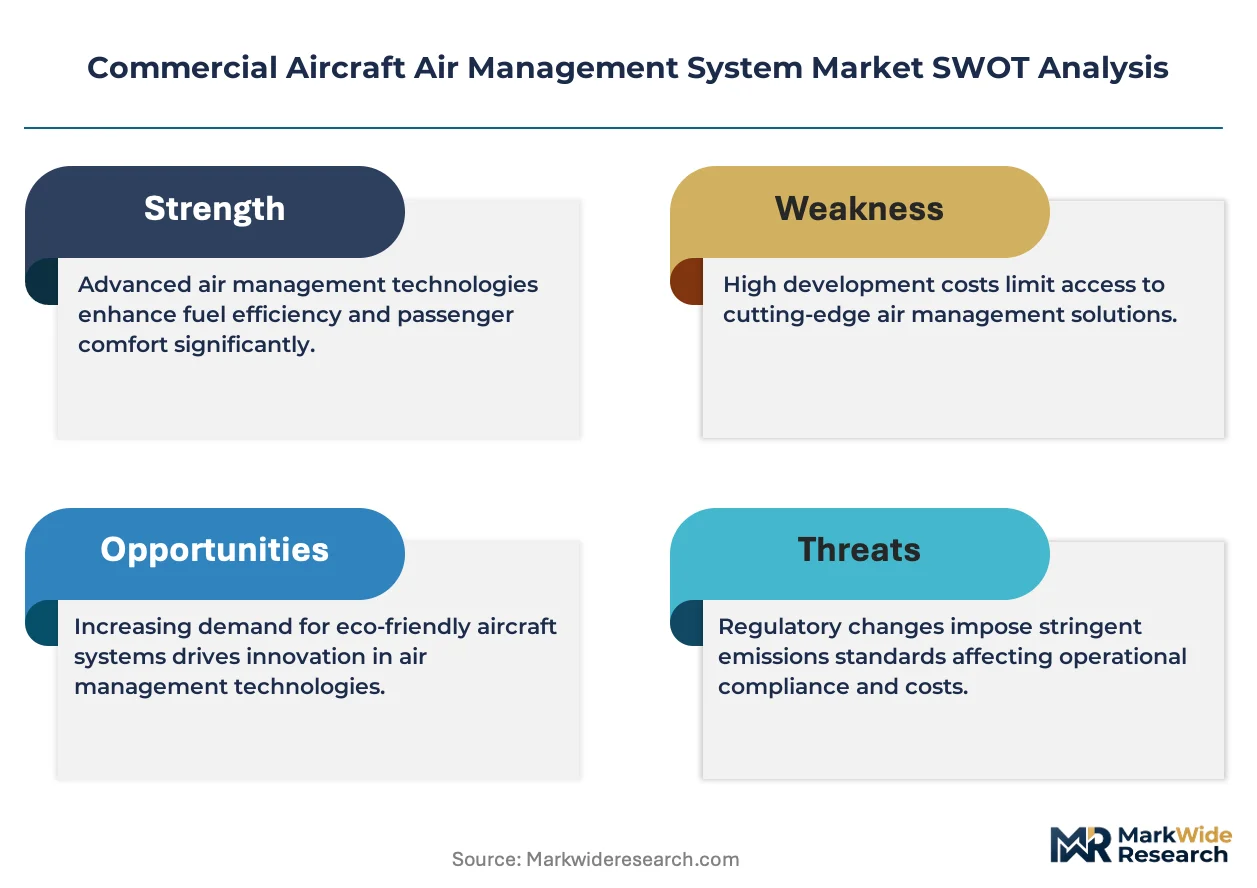
The transition from centralized pneumatic manifolds to distributed electromechanical architectures is forcing suppliers to retool engineering capabilities and certification pathways simultaneously. This technology displacement is redrawing competitive boundaries between incumbent pneumatic specialists and emerging electric systems integrators.
Growth Catalysts
- Narrowbody Fleet Renewal:Airlines in the United States and Southeast Asia are accelerating replacement schedules for aging single-aisle aircraft, driving procurement of integrated air management platforms that reduce weight and maintenance burden.
- FAA Part 25 Certification Harmonization:Unified airworthiness standards with EASA CS-25 are compressing dual-approval timelines, enabling faster market entry for suppliers seeking transatlantic contracts.
- More-Electric Aircraft Mandates:Airframers are specifying motor-driven compressor architectures that eliminate engine bleed dependency, creating fresh demand for power electronics and thermal management integration.
Market Restraints
- Titanium and Nickel Alloy Cost Volatility:Precision pneumatic valves and heat exchanger cores depend on aerospace-grade alloys whose price swings compress component margins unpredictably.
- Supplier Concentration in Precision Machining:High-pressure valve manufacturing clusters in Germany and Switzerland create geographic vulnerability to trade disruption or capacity constraints.
- REACH Chemical Restrictions:ECHA regulations on sealants and lubricants are eliminating qualified European material suppliers faster than alternatives achieve aviation certification.
Strategic Opportunities
- India Defense and Civil Aviation Expansion:IndiGo and Air India's fleet growth, combined with HAL's regional aircraft programs, are creating captive demand for localized air management system production.
- Urban Air Mobility Thermal Architectures:eVTOL developers require miniaturized environmental control systems that adapt commercial aircraft technology to battery-constrained platforms.
- EU Green Deal Aviation Emissions Targets:The European Commission's binding carbon intensity reductions are redirecting OEM sourcing criteria toward lighter, more efficient thermal management solutions.
Industry Challenges
- Power Electronics and Electromechanical Systems Talent Scarcity:The shift from pneumatic to electric architectures has outpaced university engineering pipelines and incumbent workforce retraining programs.
- FAA Electric Architecture Certification Timeline Uncertainty:Novel motor-driven compressor designs lack established validation protocols, extending approval cycles and freezing procurement decisions.
- Legacy Pneumatic System Integration Complexity:Hybrid architectures combining electric and pneumatic subsystems introduce failure-mode interactions that exceed existing system safety assessment frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Air Management System Market |
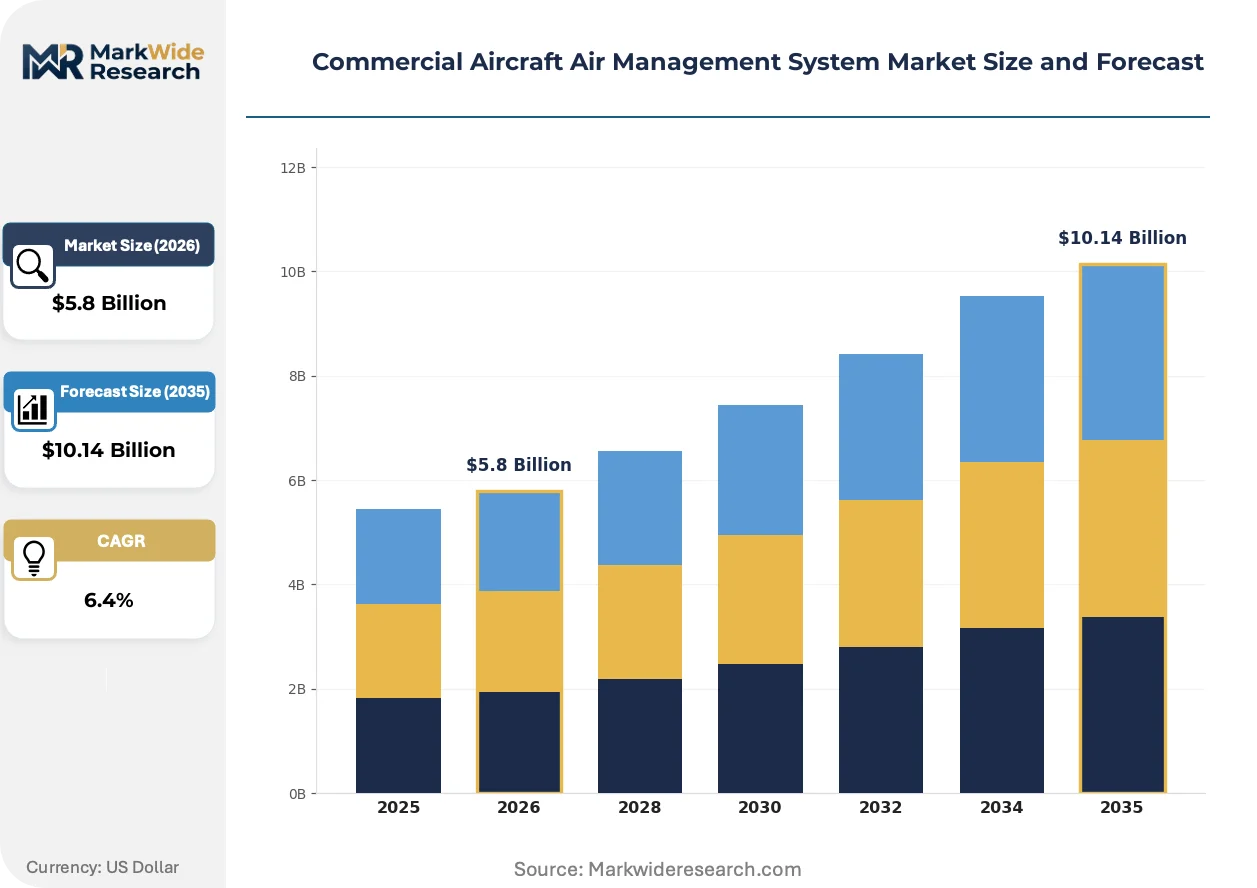
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Environmental Control System, Thermal Management System, Cabin Pressure Control System, Auxiliary Power Unit Technology: Electric, Pneumatic, Hybrid, Mechanical End User: Commercial Airlines, Aircraft Manufacturers, Maintenance Organizations, Private Operators Component: Compressor, Valve, Ducting, Sensor |
| Companies Covered | Thales Group, Parker Hannifin Corporation, Honeywell International Inc., Meggitt PLC, Diehl Stiftung & Co. KG, Raytheon Technologies Corporation, Liebherr-International AG, AMETEK Inc., Safran SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Air Management System Market Strategic Shifts
Electrification of thermal management is compressing the traditional division between airframe and propulsion system engineering. This convergence is eliminating legacy pneumatic infrastructure while demanding new competencies in power distribution and motor control.
Distributed electromechanical compressor architectures are integrating motor-driven fans and variable-speed compressors to replace centralized engine bleed systems. Regional jet and single-aisle programs at airframers in Brazil and Canada are specifying these platforms for entry-into-service after 2030. The technology is integrating thermal, pneumatic, and electrical subsystems into unified control domains that reduce wiring weight and simplify maintenance access.
REACH chemical restrictions and the EU F-Gas Regulation are eliminating hydrofluorocarbon refrigerants from European-sourced environmental control systems. This regulatory pressure is accelerating qualification of hydrofluoroolefin alternatives and transcritical CO2 cycles for cabin cooling. Heat exchanger manufacturers in France and Germany are retooling production lines to accommodate higher-pressure refrigerant circuits and corrosion-resistant alloys.
Airline technical procurement teams are consolidating vendor relationships around full-system integrators capable of delivering environmental control, cabin pressure, and air distribution as unified platforms. This concentration is displacing component-level sourcing for valves, sensors, and heat exchangers. The shift is most visible at low-cost carriers in the United States and Ireland, where fleet standardization and reduced spare inventory drive preference for single-source air management contracts.
Commercial Aircraft Air Management System Market Segmentation
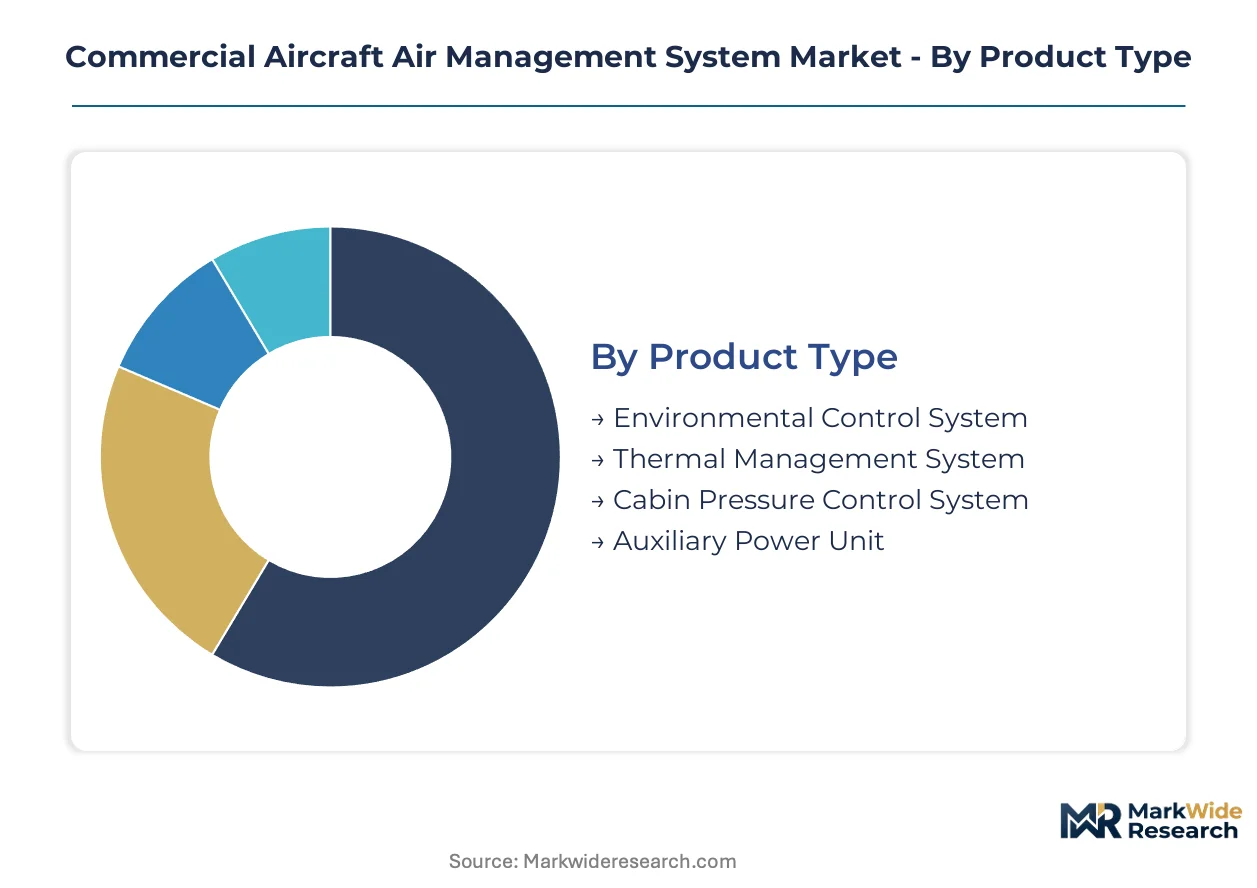
Fleet renewal cycles and certification mandates are fragmenting demand across product architectures. Suppliers must align portfolios with divergent technology roadmaps while managing legacy pneumatic commitments alongside electric system qualification timelines.
Product Type:
Upgrade cycles for narrowbody platforms are redistributing installed value across integrated air management platforms as airlines prioritize weight reduction and maintenance interval extension.
- Environmental Control System:Centralized thermal, filtration, and humidity regulation subsystems integrating heat exchangers, air cycle machines, and ozone converters. Demand concentrates at Boeing and Airbus single-aisle programs where 8.6 psi pressure differential specifications and 500+ CFM zone airflow requirements drive specification complexity. FAA Part 25 cabin altitude limits and smoke penetration standards dictate redundant architecture mandates that elevate certification costs.
- Thermal Management System:Distributed heat rejection and temperature regulation subsystems managing avionics cooling, cargo compartment conditioning, and galley thermal loads. Procurement is accelerating at regional jet manufacturers in Brazil and Canada specifying more-electric architectures that replace bleed-air dependencies with motor-driven compressor networks.
- Cabin Pressure Control System:Outflow valves, pressure sensors, and controller units maintaining altitude-equivalent cabin environments across climb, cruise, and descent phases.
- Auxiliary Power Unit:Self-contained turbine systems providing pneumatic and electrical power for ground operations and emergency backup.
Volume placements concentrate in Environmental Control Systems; the faster expansion belongs to Thermal Management Systems as electric architectures gain specification share.
Technology:
Cost tier differentiation separates established pneumatic installations from emerging electric platforms commanding premium pricing for weight and efficiency advantages.
- Electric:Motor-driven compressor architectures eliminating engine bleed air dependency through distributed electromechanical actuation and variable-speed fan control. Demand is concentrating at airframers pursuing more-electric aircraft mandates where power electronics integration and thermal management convergence create new engineering competency requirements. EASA CS-25 harmonization with FAA rules is compressing dual-approval timelines for novel validation protocols.
- Pneumatic:Traditional bleed-air systems utilizing engine compressor stages, precoolers, and pneumatic manifolds for cabin conditioning and pressurization. Procurement persists at legacy widebody programs and cargo conversions where certification grandfathering and maintenance infrastructure delay technology transition.
- Hybrid:Combined pneumatic-electric architectures enabling incremental electrification without full system replacement.
- Mechanical:Direct-coupled compressor and fan systems without electronic control interfaces.
Customer procurement stratifies across cost tiers: electric platforms claim premium positioning for new programs; pneumatic systems defend installed base through aftermarket service contracts.
End User:
Application-specific requirements fragment specifications between production-line integration and aftermarket replacement demand.
- Commercial Airlines:Fleet operators specifying integrated platforms for narrowbody renewal programs and standardizing configurations across mixed fleets. Procurement concentrates at low-cost carriers in the United States and Ireland consolidating vendor relationships around full-system integrators capable of unified environmental control, cabin pressure, and air distribution contracts.
- Aircraft Manufacturers:OEMs integrating air management architectures at initial assembly, specifying electric technology for entry-into-service after 2030. Boeing production rate adjustments and aftermarket expansion shape supplier order books.
- Maintenance Organizations:Third-party and airline-affiliated MRO providers managing component overhaul and replacement.
- Private Operators:Business jet and fractional ownership fleets with customized cabin environment specifications.
Volume leadership sits with Commercial Airlines; Aircraft Manufacturers are climbing the fastest as electric architecture penetration accelerates at greenfield programs.
Component:
Supply concentration in precision machining creates margin pressure for high-pressure valve and compressor manufacturers dependent on titanium and nickel alloy sourcing.
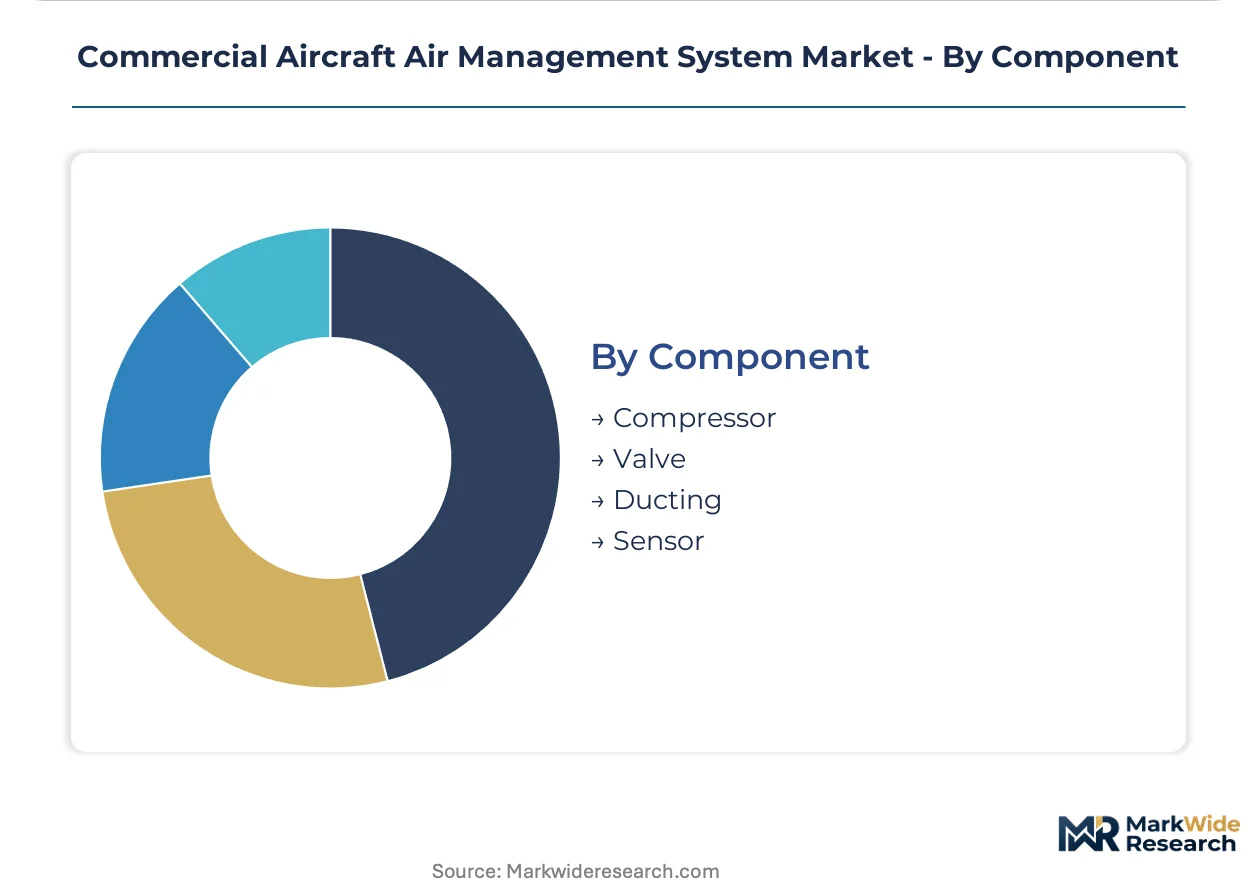
- Valve:High-pressure pneumatic regulators, shutoff valves, and modulating controls managing bleed-air distribution and pressure regulation. Manufacturing clusters in Germany and Switzerland create geographic vulnerability to trade disruption; REACH chemical restrictions eliminate qualified European sealant suppliers faster than alternatives achieve aviation certification.
- Compressor:Air cycle machines, motor-driven compressors, and bootstrap units generating conditioned airflow. Demand is bifurcating between legacy pneumatic designs and electric motor-driven architectures requiring power electronics integration.
- Ducting:Pneumatic distribution manifolds, flexible joints, and isolation systems routing conditioned air across cabin zones.
- Sensor:Pressure transducers, temperature probes, and flow measurement devices providing feedback for closed-loop control.
Component procurement concentrates in Valve and Compressor categories; Sensor demand is expanding most quickly as distributed electromechanical architectures multiply measurement points across unified control domains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita, Kansas anchors North American aerospace manufacturing, with Boeing's supplier network and Spirit AeroSystems' fabrication facilities driving precision component demand for air management systems.
United States
FAA Part 25 certification harmonization with EASA standards compresses dual-approval timelines for electric architecture suppliers. Boeing's production rate adjustments in Everett and Charleston reshape supplier order books across environmental control and thermal management platforms. The IRA clean energy provisions accelerate electrification investments at aerospace clusters in Washington State and South Carolina.
France
EU Green Deal aviation emissions targets redirect OEM sourcing toward lighter thermal architectures at Airbus facilities in Toulouse and Hamburg-coordinated programs. EASA CS-25 harmonization with FAA rules creates unified regulatory baselines for suppliers seeking transatlantic contracts. Safran SA's electric air management development in Paris-Saclay exemplifies the shift from engine bleed dependency.
Germany
REACH chemical restrictions eliminate qualified sealant suppliers faster than alternatives achieve aviation certification, pressuring valve manufacturers in Baden-Württemberg. Diehl Stiftung & Co. KG's precision machining operations in Nuremberg anchor high-pressure pneumatic component supply. The country's automotive power electronics talent pools support electromechanical system transitions at aerospace engineering centers in Munich and Hamburg.
India
IndiGo and Air India's fleet expansion creates captive demand for localized air management production under the PLI scheme for aerospace components. HAL's regional aircraft programs in Bangalore and Hyderabad specify integrated environmental control platforms. DGFT import substitution policies accelerate domestic manufacturing of valves and sensors at emerging clusters in Maharashtra and Tamil Nadu.
United Kingdom
Meggitt PLC's thermal management engineering in Coventry and Leicester supplies compressor and heat exchanger technologies to Airbus and Boeing programs. The UK's Jet Zero Council mandates carbon-neutral aviation by 2050, redirecting R&D funding toward electric architectures. Precision machining clusters in the Midlands face margin pressure from titanium and nickel alloy cost volatility.
Commercial Aircraft Air Management System Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification complexity and system integration depth. The vendor base organizes around three tiers: full-system integrators commanding sole-source contracts, subsystem specialists capturing platform-specific niches, and component fabricators competing on machining precision and alloy sourcing. Consolidation pressures favor integrators with captive environmental control, cabin pressure, and air distribution capabilities. Competitive moves center on strategic partnerships for electric architecture development and backward integration into precision valve manufacturing.
Among diversified aerospace conglomerates, Honeywell International Inc., Parker Hannifin Corporation, and Safran SA occupy positions spanning pneumatic heritage and electric transition pathways. Honeywell exemplifies the integrated environmental control portfolio archetype, sustaining long-term contracts through unified thermal, pressure, and filtration platforms. Parker Hannifin represents precision pneumatic valve specialization, with captive manufacturing capabilities concentrated in high-pressure regulator segments. Safran anchors the electric architecture vector, reducing engine bleed dependency through motor-driven compressor development. These three players collectively illustrate the competitive tension between defending legacy pneumatic installed bases and capturing premium positioning in more-electric aircraft mandates.
| Leading Market Players |
|---|
| Thales Group |
| Parker Hannifin Corporation |
| Honeywell International Inc. |
| Meggitt PLC |
| Diehl Stiftung & Co. KG |
| Raytheon Technologies Corporation |
| Liebherr-International AG |
| AMETEK Inc. |
| Safran SA |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal's aviation emissions targets gate both qualified supply and premium-tier pricing access, as REACH chemical restrictions eliminate legacy sealant suppliers faster than alternatives achieve FAA and EASA certification. Buyers seeking electric air management architectures face extended lead times and elevated qualification costs that compress margin flexibility across component tiers.
Pricing Analysis
Certification-grade pricing anchors value capture, with dual FAA-EASA approval tiers commanding substantial premiums over single-jurisdiction alternatives. Three-tier pricing structure across premium, standard, and economy levels separates electric motor-driven compressor platforms from hybrid pneumatic-electric systems and legacy bleed-air configurations. Cost compression in standard-tier pneumatic valves is intensifying because titanium and nickel alloy sourcing volatility feeds directly into component pricing. Low-cost carriers in the United States and Ireland exhibit highest price sensitivity through consolidated vendor negotiations, while aircraft manufacturers pursuing more-electric mandates show lowest sensitivity due to weight-reduction imperatives.
Supply Chain Analysis
Regional distribution centers in Wichita, Toulouse, and Hamburg coordinate hub-and-spoke patterns for precision-machined valve assemblies and heat exchanger cores. Manufacturing concentrates in Germany, Switzerland, and the United States for high-pressure pneumatic regulators; motor-driven compressor production is expanding in France and India under PLI scheme incentives. Raw material dependencies draw from aerospace-grade titanium alloys, nickel-based superalloys, and specialized refrigerants transitioning from hydrofluorocarbons to hydrofluoroolefins. Single-source vulnerability in German and Swiss precision machining clusters creates geographic concentration risk. Distribution runs through OEM direct contracts and airline-affiliated MRO networks, with full-system integrators displacing component-level procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with backward integration into precision valve manufacturing and captive power electronics assembly emerging as decisive competitive levers.
For Market Incumbents: Anchor defense through certification grandfathering at legacy widebody programs while accelerating electric architecture qualification timelines. Pursue captive manufacturing of high-pressure pneumatic regulators to offset titanium alloy cost volatility. Consolidate aftermarket service contracts at narrowbody operators in the United States to create switching costs against emerging electric systems integrators.
For New Entrants and Emerging Players: The price-point gap between premium electric platforms and economy-tier pneumatic retrofits creates white-space opportunity at regional jet manufacturers in Brazil and Canada. Target hybrid architecture specifications enabling incremental electrification without full system replacement. Pursue power electronics talent acquisition from automotive clusters in Germany as the primary go-to-market enabler.
For Investors and Strategic Acquirers: FAA electric architecture certification timeline clarity is the leading indicator that procurement decisions will unlock across deferred new programs. Frame long-term viability around five-to-ten year positioning for more-electric aircraft mandates. Acquire precision machining specialists with existing EASA CS-25 valve approvals and available capacity for motor-driven compressor housings.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Architecture Certification Investment | Dual FAA-EASA approval compresses procurement cycles at Boeing and Airbus single-aisle programs. |
| Backward Integration into Precision Machining | Captive valve manufacturing insulates margins from titanium and nickel alloy price volatility. |
| Power Electronics Talent Acquisition | Automotive engineering pipelines in Munich and Stuttgart address capability scarcity in motor control. |
| Regional Manufacturing Localization | PLI scheme facilities in Maharashtra capture IndiGo and Air India fleet expansion demand. |
| Full-System Integration Capability Buildout | Unified environmental control, cabin pressure, and air distribution contracts displace component sourcing. |
Study Parameters
Multi-period observation of fleet renewal cycles, certification timeline progressions, and alloy price movements anchored the trend analysis, supplemented by interviews with environmental control system engineering directors, airline technical procurement managers, MRO operations heads, and power electronics specialists at tier-one suppliers. Secondary validation drew from FAA Part 25 airworthiness directives, EASA CS-25 harmonization updates, EU ECHA REACH restriction amendments, and customs data on aerospace-grade titanium and nickel alloy trade flows. Bottom-up triangulation across component-level production estimates and top-down reconciliation against OEM platform delivery schedules ensured methodological consistency.
The input-output matrix framed demand modeling across product type, technology architecture, end-user procurement tier, and geographic production cluster dimensions. CAGRs were derived from segment-level volume trajectories weighted by installed value per platform. Forecast inputs incorporated Boeing and Airbus production rate adjustments, electric architecture entry-into-service timelines, and REACH chemical restriction implementation schedules across the projection horizon.
Inputs from regulatory filings, OEM procurement disclosures, and alloy commodity exchanges were available through the study window; gaps in real-time electric architecture certification progress introduce uncertainty bands around technology transition timing. Forecasts reflect documented assumptions regarding fleet renewal acceleration and emissions mandate enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Environment Control
Ice Protection Systems Market
Aircraft Environment Control
HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market
Aircraft Environment Control
Aerospace Flight Control System Market
Aircraft Environment Control
Aircraft Waste Tank Market
Aircraft Environment Control
Gas Turbine Air Filtration Market
Aircraft Environment Control
Aircraft Air Conditioning Unit Market
Aircraft Environment Control
Turbine Air Filtration Market
Aircraft Environment Control
Airborne Molecular Contamination Control Services Market