
 Satellite Services Market | 2026-2036
Satellite Services Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Services Market Outlook
Government and military end users is redrawing procurement priorities across the satellite services landscape. SES anchors its position through extensive geostationary fleet coverage over Europe and the Americas. SpaceX competes aggressively with its Starlink low Earth orbit constellation, leveraging vertical launch integration to compress deployment cycles. Intelsat sustains legacy broadcast and media distribution contracts while navigating spectrum reallocation mandates.
Satellite services encompass the provision of space-based capabilities including signal relay, remote sensing data transmission, and precision positioning, typically operating across frequency bands from L-band to Ka-band and relying on orbital altitudes ranging from 600 km to 35,786 km above Earth. These systems enable continuous connectivity, Earth monitoring, and navigation support for industries where terrestrial infrastructure proves inadequate or economically unviable. Communication services dominate current revenue pools due to entrenched enterprise and consumer broadband contracts, while Earth observation segments are attracting accelerated investment from climate analytics and agricultural yield optimization platforms. Low Earth orbit technology is displacing traditional geostationary architectures in latency-sensitive applications, though medium Earth orbit systems retain advantages for specialized navigation and aeronautical use cases.
The FCC governs spectrum licensing and orbital debris mitigation standards for U.S.-based operators, directly conditioning market access and constellation deployment schedules. Eutelsat Communications navigates ESA and national regulatory frameworks across EU member states, where the EU Space Programme and emerging IRIS² constellation plans are reshaping procurement rules. Operators must monitor evolving ITU coordination procedures and national security review mechanisms as sovereign capacity requirements intensify across NATO-aligned governments.
Market Dynamics
Low Earth orbit constellation deployment is compressing latency benchmarks and forcing geostationary operators to restructure service architectures around hybrid orbital strategies.
Growth Catalysts
- Defense procurement frameworks:NATO-aligned governments are mandating sovereign satellite capacity for secure tactical communications, creating dedicated procurement channels for encrypted relay services.
- Ka-band spectrum liberalization:The FCC's streamlined licensing for non-geostationary systems is accelerating constellation deployment timelines and reducing regulatory friction for new market entrants.
- Climate analytics platforms:Agricultural yield optimization and carbon monitoring applications are driving demand for high-revisit Earth observation data streams.
Market Restraints
- Launch cost volatility:Propellant price fluctuations and launch vehicle availability constraints are compressing margin structures for constellation operators dependent on third-party lift services.
- Spectrum coordination complexity:ITU filing backlogs and cross-border interference disputes are extending deployment schedules for multi-orbital systems.
- Optical ground station substitution:Laser-based terrestrial alternatives for specific backhaul applications are eroding addressable market for radio-frequency satellite links in select enterprise segments.
Strategic Opportunities
- Sub-Saharan connectivity gaps:Terrestrial fiber deficits across Nigeria, Kenya, and Ethiopia present white-space demand for direct-to-consumer broadband satellite services.
- In-orbit servicing convergence:Robotics and refueling technology maturation is enabling life-extension services for aging geostationary assets.
- EU IRIS² constellation mandate:The European Union's sovereign infrastructure program is creating dedicated procurement pools for secure government and defense applications.
Industry Challenges
- RF engineer scarcity:Specialized talent pools for phased-array antenna design and spectrum engineering are concentrated among legacy aerospace employers, constraining hiring velocity for emerging constellation operators.
- Type certification timelines:User terminal approvals under FCC Part 25 and ETSI standards are extending customer acquisition cycles for consumer broadband rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Services Market |
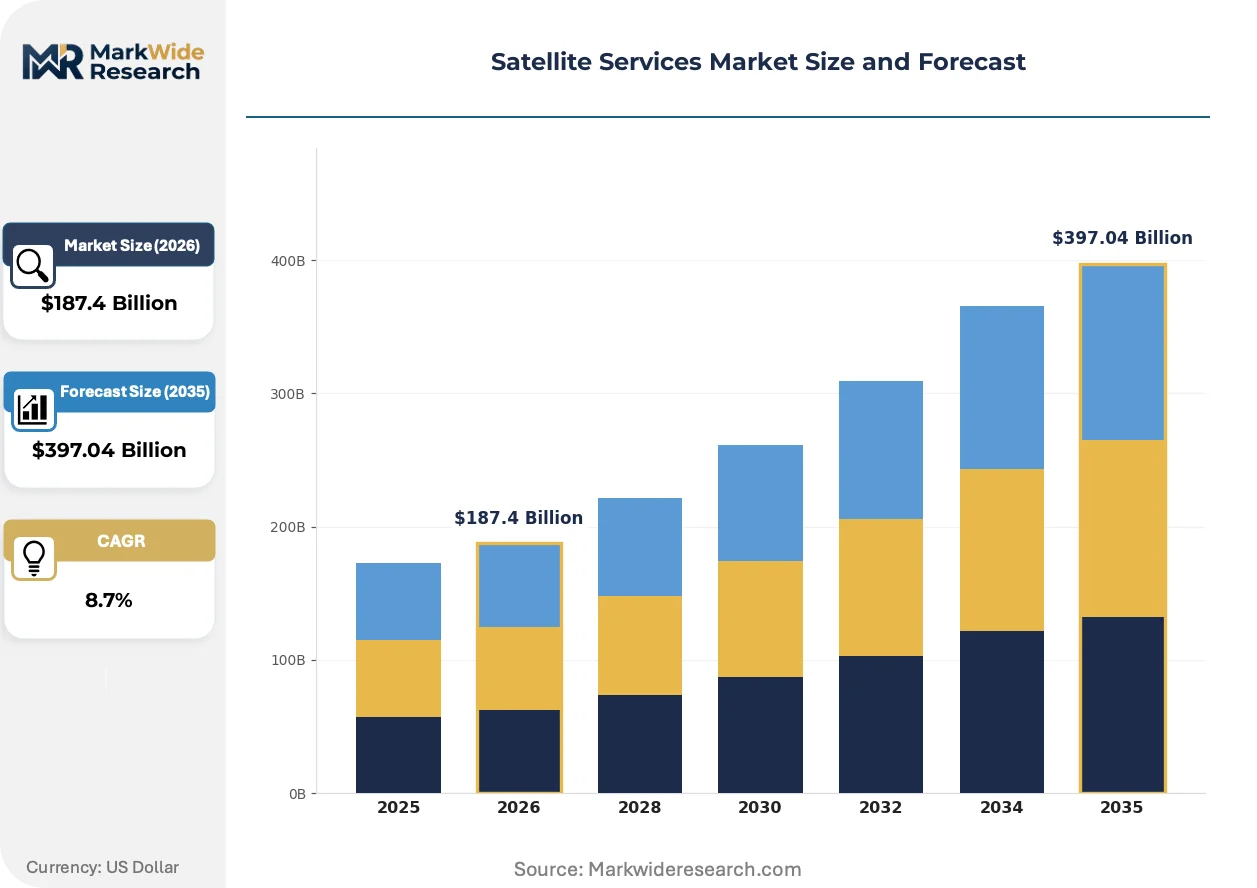
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Communication, Broadcasting, Earth Observation, Navigation Application: Aerospace, Maritime, Telecommunications, Agriculture Technology: Geostationary, Low Earth Orbit, Medium Earth Orbit, CubeSat End User: Government, Commercial, Military, Non-Profit |
| Companies Covered | SES, Intelsat, Viasat, EchoStar Corporation, Eutelsat Communications, SpaceX, Inmarsat, Iridium Communications, Globalstar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Services Market Strategic Shifts
Orbital architecture diversification is fragmenting traditional service models as latency requirements harden across autonomous systems and financial trading networks.
Electronically steered flat-panel antennas are bifurcating maritime and aeronautical connectivity markets from legacy parabolic hardware. Cruise operators and commercial airlines are adopting these terminals for seamless beam-switching across multi-orbital constellations. This technology is bifurcating procurement decisions between integrated service bundles and terminal-agnostic subscription models.
REACH chemical restrictions on satellite manufacturing materials are forcing European operators to reformulate thermal control coatings and propulsion system components. Industrial consequence includes extended qualification timelines for new spacecraft bus designs. The Earth observation segment is most affected, with operators accelerating supplier audits to preempt compliance disruptions.
Enterprise buyers are consolidating satellite service contracts under multi-orbit managed service agreements rather than single-constellation subscriptions. Systems integrators and value-added resellers are displacing direct operator relationships in the energy and mining verticals. This pattern is most visible across Australian and Canadian remote resource extraction sites where terrestrial redundancy requirements mandate hybrid connectivity sourcing.
Satellite Services Market Segmentation
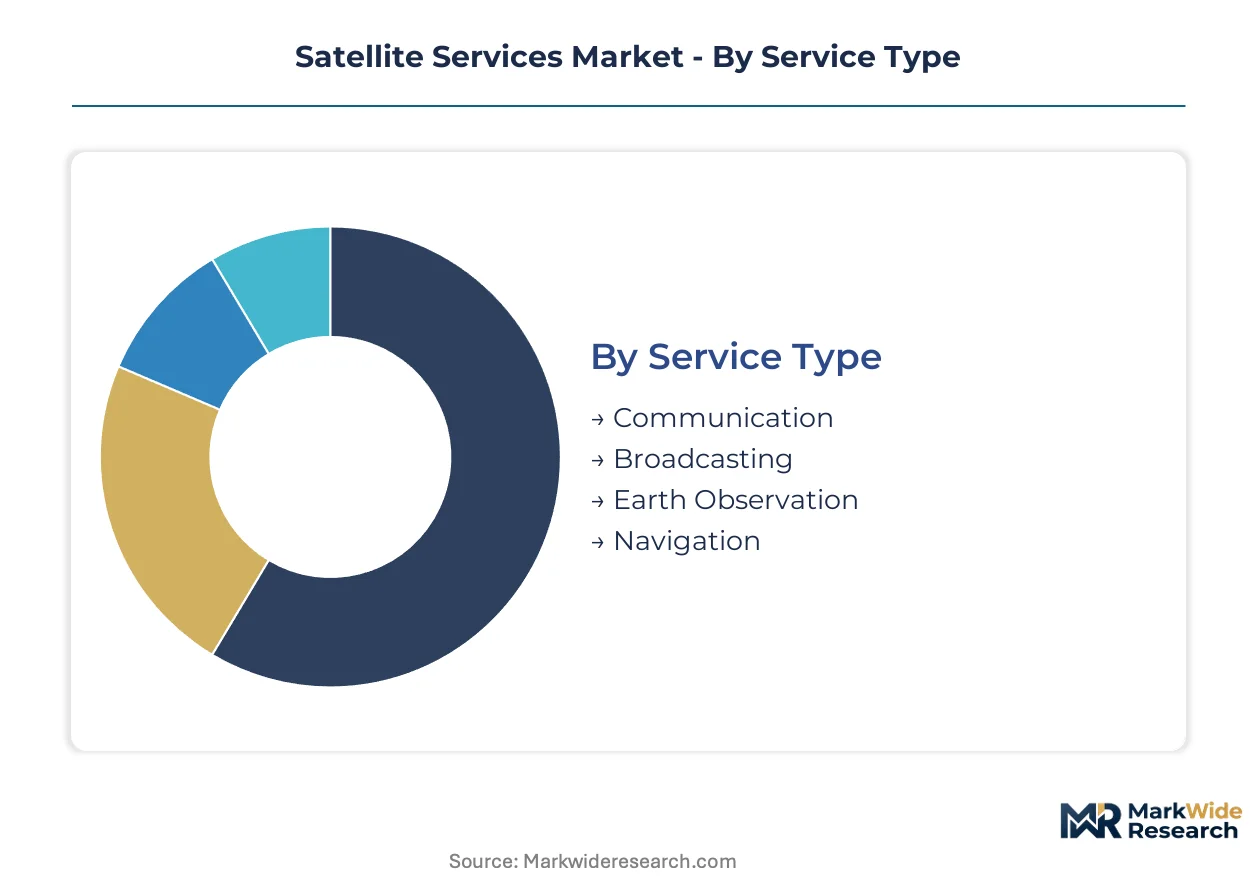
Satellite services fragment across orbital architectures, service modalities, and procurement channels that dictate entirely different margin structures and competitive dynamics. Understanding these divides reveals where operators concentrate capital deployment versus where they merely defend legacy revenue streams.
Service Type:
Margins pool thickest where long-term enterprise contracts lock in predictable capacity utilization against high fixed orbital costs.
- Communication:Signal relay and broadband transmission across L-band through Ka-band frequencies anchor current revenue concentration. Enterprise maritime contracts and government secure links in the United States generate the steadiest cash flows, though Starlink's consumer push is compressing retail pricing power.
- Broadcasting:Direct-to-home television and radio distribution leverage geostationary orbital slots for continuous regional coverage. Legacy media contracts across European and Latin American markets sustain this segment, though cord-cutting is eroding subscriber bases faster than operators can reprice.
- Earth Observation:Remote sensing data streams support climate analytics and agricultural yield platforms. Demand concentrates where revisit frequency requirements exceed 24-hour cycles, pushing investment toward synthetic aperture radar and hyperspectral imaging constellations.
- Navigation:Precision positioning and timing services enable aviation, autonomous vehicles, and financial timestamping. Military authentication requirements and aviation safety certification create steep barriers that protect incumbent system operators.
The dominant share belongs to Communication, while Earth Observation is closing the gap fastest.
Application:
Cost tiers separate mission-critical government procurement from price-sensitive commercial deployments.
- Aerospace:In-flight connectivity and crew communications for commercial aviation and private aircraft demand low-latency links that geostationary systems struggle to deliver. Airlines are consolidating procurement under multi-orbit managed service agreements rather than single-constellation subscriptions.
- Maritime:Merchant shipping, cruise lines, and offshore energy platforms require continuous coverage across oceanic corridors where terrestrial infrastructure is absent. Electronically steered flat-panel antennas are displacing legacy parabolic hardware in this segment, bifurcing procurement between integrated bundles and terminal-agnostic models.
- Telecommunications:Backhaul extension for mobile network operators and direct-to-consumer broadband in fiber-deficit regions. Sub-Saharan markets across Nigeria, Kenya, and Ethiopia present white-space demand that constellation operators are targeting with consumer-priced terminals.
- Agriculture:Precision farming applications leverage Earth observation data for yield optimization and irrigation management. Climate analytics platforms are driving subscription growth, though farmer price sensitivity limits margin expansion.
Aerospace commands premium pricing, but Maritime is expanding most quickly as cruise and shipping fleets refresh connectivity hardware.
Technology:
Supply concentration sits with launch-integrated operators who control deployment velocity and orbital slot access.
- Geostationary:Fixed orbital position at 35,786 kilometers enables continuous regional coverage with minimal ground infrastructure. Legacy broadcast and enterprise contracts sustain these assets, though latency limitations are pushing latency-sensitive applications toward lower orbits.
- Low Earth Orbit:Constellations at 600-1,200 kilometers compress latency to sub-50 milliseconds for autonomous systems and financial trading networks. SpaceX's vertical launch integration has compressed deployment cycles, forcing incumbent operators into hybrid orbital strategies.
- Medium Earth Orbit:Intermediate altitude systems balance coverage footprint with latency performance for specialized navigation and aeronautical applications. GPS and Galileo deployments demonstrate this architecture's durability where continuous global availability matters more than bandwidth density.
- CubeSat:Standardized small satellite form factors enable rapid technology demonstration and niche sensing missions. University and research institution procurement dominates, though some commercial operators are exploring constellations for targeted Earth observation services.
Geostationary retains the largest installed base, while Low Earth Orbit is climbing the fastest as constellation operators scale manufacturing and launch cadence.
End User:
Customer type determines contract structure, payment security, and regulatory scrutiny intensity.
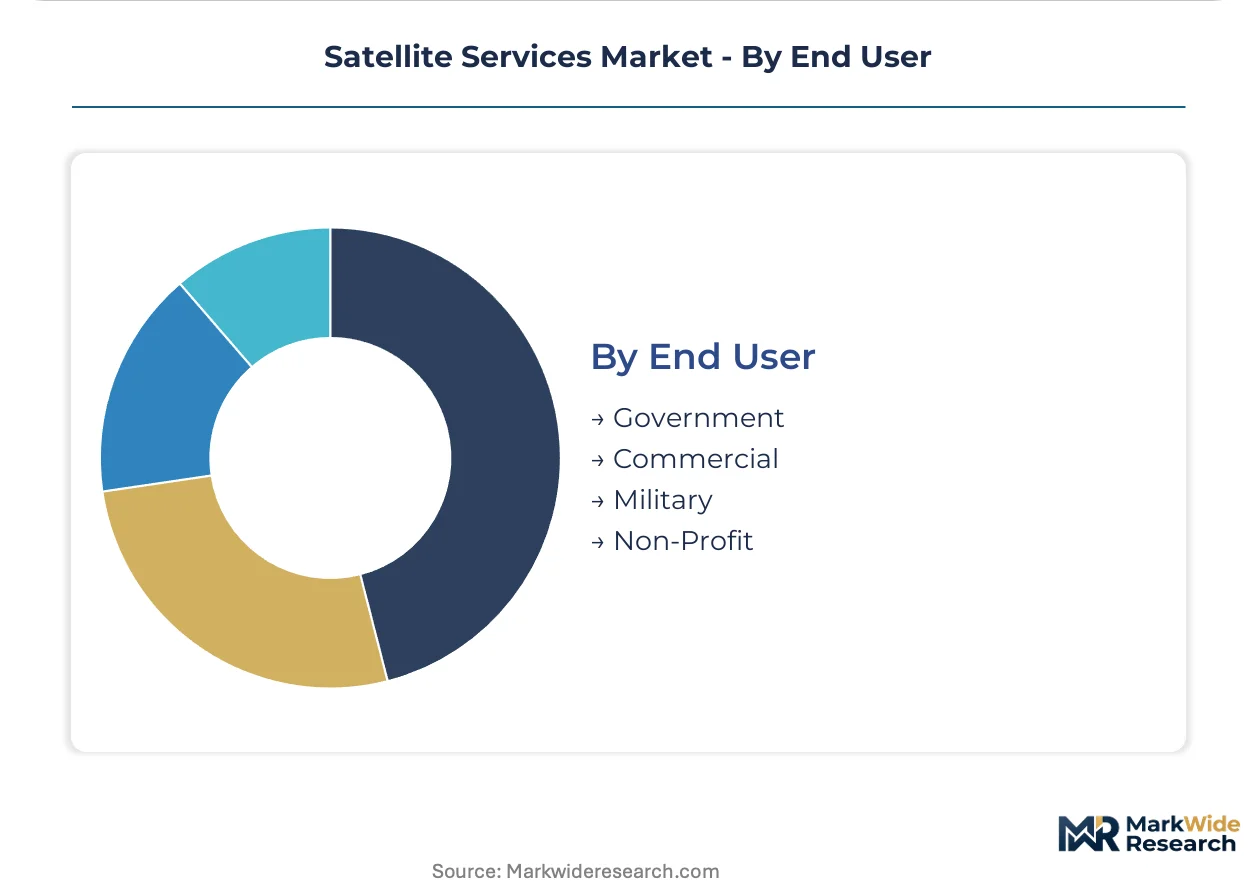
- Government:Civilian agency procurement for weather monitoring, disaster response, and scientific research. The FCC's spectrum licensing frameworks and ITU coordination procedures condition access for U.S.-based operators serving federal contracts.
- Commercial:Enterprise connectivity, media distribution, and agricultural analytics across energy, mining, and logistics verticals. Australian and Canadian remote resource extraction sites are consolidating contracts under systems integrators rather than direct operator relationships.
- Military:Secure tactical communications, intelligence surveillance, and navigation warfare capabilities. NATO-aligned governments are mandating sovereign satellite capacity, creating dedicated procurement channels for encrypted relay services.
- Non-Profit:Humanitarian connectivity, environmental monitoring, and educational broadband in underserved regions. Development finance institution subsidies often support these deployments, constraining pricing flexibility for operators.
Military and Government combined represent the most defensible revenue pool, while Commercial is gaining share fastest as enterprise managed service agreements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Satellite service exports from the United States flow predominantly toward NATO defense procurement channels and commercial maritime operators across European and Asia-Pacific buyer geographies. Federal space contracts anchor domestic demand while launch infrastructure concentration accelerates constellation deployment velocity.
United States
Federal defense procurement and commercial launch infrastructure anchor domestic demand concentration. The FCC's streamlined spectrum licensing for non-geostationary orbit systems compresses deployment timelines for constellation operators. California's aerospace corridor hosts vertically integrated launch facilities that manufacture and deploy spacecraft buses in compressed cycles.
France
EU sovereign infrastructure mandates and Ariane launch heritage sustain institutional demand for secure government communications. ESA coordination frameworks and national space programs condition procurement rules for encrypted relay services. Toulouse's aerospace cluster concentrates satellite manufacturing and ground segment engineering capabilities for institutional clients.
Germany
Automotive connectivity requirements and industrial IoT backhaul drive enterprise subscription growth for low-latency links. REACH chemical restrictions on manufacturing materials force reformulation of thermal control coatings and propulsion components. Munich's engineering corridor hosts systems integrators consolidating multi-orbit managed service agreements for remote resource extraction clients.
United Kingdom
Maritime connectivity refresh cycles and in-flight broadband procurement from commercial aviation operators concentrate service demand. The national space regulator coordinates ITU filing procedures for constellation operators seeking orbital slot access. Harwell's space cluster anchors Earth observation data analytics platforms serving agricultural yield optimization contracts.
Japan
Precision positioning requirements for autonomous vehicle testing and financial timestamping sustain navigation service demand. METI industrial policy frameworks support domestic constellation deployment for sovereign communications capacity. Tokyo's satellite manufacturing corridor specializes in compact spacecraft buses for rapid technology demonstration missions.
Satellite Services Market Competitive Environment
Listed leaders compete with private specialists across capital access and deployment velocity dimensions. The market structure concentrates around launch-integrated operators who control orbital slot access and manufacturing scale, while legacy geostationary incumbents defend entrenched enterprise contracts. Three archetypes dominate: vertically integrated constellation deployers, legacy orbital slot holders with hybrid transition strategies, and regional specialists serving sovereign procurement channels. Competitive moves center on spectrum portfolio accumulation and strategic partnerships with systems integrators displacing direct operator relationships.
Among Luxembourg and US-based operators, SES and Intelsat exemplify legacy geostationary incumbents navigating hybrid orbital transitions, while SpaceX represents vertically integrated constellation deployers compressing launch-to-service cycles through captive manufacturing and lift capacity. These anchors occupy positions across the spectrum from entrenched broadcast distribution to consumer broadband disruption, reflecting divergent strategic postures toward latency-sensitive application migration.
| Leading Market Players |
|---|
| SES |
| Intelsat |
| Viasat |
| EchoStar Corporation |
| Eutelsat Communications |
| SpaceX |
| Inmarsat |
| Iridium Communications |
| Globalstar |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month spacecraft bus lead times from prime contractors concentrate pricing power among vertically integrated operators while compressing margin structures for constellation deployers dependent on external manufacturing. This supply bottleneck feeds directly into subscription pricing tiers, where captive launch and production capacity enables aggressive consumer broadband positioning against legacy geostationary incumbents.
Pricing Analysis
Geostationary-to-low-Earth-orbit pricing gaps separate three distinct service tiers: legacy broadcast distribution at premium enterprise rates, hybrid multi-orbit managed services at mid-market positioning, and direct-to-consumer broadband at economy scale. Three-tier pricing structure across premium, standard, and economy levels reflects orbital altitude, latency performance, and terminal sophistication rather than brand differentiation alone. Cost compression in consumer broadband intensifies because SpaceX's captive manufacturing erodes hardware subsidy recovery timelines for competing constellation operators. Government and military procurement shows least price sensitivity due to sovereign capacity mandates, while agricultural yield optimization platforms face acute farmer budget constraints.
Supply Chain Analysis
Inbound logistics costs for propulsion system components face chronic volatility across Pacific trade lanes serving California's aerospace corridor and European launch sites. Manufacturing concentration sits with the United States, France, and Germany, where Toulouse's satellite bus production, Munich's systems integration capabilities, and California's vertical launch facilities anchor upstream supply. Raw material dependencies center on gallium arsenide for phased-array substrates, xenon propellant for electric thrusters, and specialized aluminum-lithium alloys for spacecraft structures. Single-source vulnerability persists for radiation-hardened semiconductors sourced from domestic foundries with ITAR restrictions. Distribution runs through direct operator relationships in government verticals and systems integrator channels for enterprise energy and mining contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orbital architecture fragmentation creates multiple white-space entry points as latency requirements harden across autonomous systems and sovereign capacity mandates proliferate among NATO-aligned governments.
For Market Incumbents: Shield geostationary enterprise contracts through hybrid orbital service bundles that integrate low-Earth-orbit capacity for latency-sensitive applications. Accelerate in-orbit servicing investments to extend aging asset life against replacement capital requirements. Defensive consolidation around spectrum portfolio accumulation counters emerging constellation entrants with streamlined FCC licensing advantages. For New Entrants and Emerging Players: Anchor in sub-Saharan connectivity gaps across Nigeria, Kenya, and Ethiopia where terrestrial fiber deficits exceed satellite service penetration. Target maritime connectivity refresh cycles with electronically steered flat-panel terminal offerings that displace legacy parabolic hardware. Direct-to-consumer go-to-market approaches through mobile network operator partnerships bypass established distribution channels. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy geostationary operators with stranded orbital slots and entrenched broadcast contracts facing cord-cutting erosion. Long-term viability over the coming decade hinges on successful hybrid orbital transition execution rather than legacy asset defense. Watch ITU coordination backlogs as inflection indicators for deployment timeline compression or extension.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Service Integration | Combines geostationary coverage continuity with low-Earth-orbit latency performance for enterprise maritime contracts. |
| Spectrum Portfolio Accumulation | FCC streamlined licensing for Ka-band non-geostationary systems accelerates constellation deployment timelines against regulatory friction. |
| In-Orbit Servicing Capability Buildout | Robotics and refueling technology maturation extends aging geostationary asset life beyond original design specifications. |
| Electronically Steered Terminal Manufacturing Scale-Up | Flat-panel antenna production ramp enables maritime and aeronautical procurement shifts from legacy parabolic hardware. |
| EU IRIS² Constellation Partnership | European sovereign infrastructure mandate creates dedicated procurement pools for secure government and defense applications. |
Study Parameters
Operator-level perspectives from constellation program directors, ground segment engineering leads, spectrum regulatory counsel, and defense procurement officers anchored the qualitative base. Primary interview data combined with secondary validation drawn from FCC licensing databases, ESA procurement disclosures, ITU satellite network filings, and operator financial statements. Bottom-up capacity deployment modeling triangulated against top-down addressable market sizing across orbital architectures and service modalities.
Sensitivity analysis tested forecast robustness against launch cadence variability, propellant cost volatility, and regulatory timeline compression scenarios. Segmentation dimensions modeled include orbital altitude tier, service type, end-user category, and regional procurement framework across the projection horizon. CAGRs derived from unit economics of constellation deployment costs per satellite and service revenue per subscriber, incorporating launch vehicle availability constraints and ground infrastructure buildout schedules as industry-specific inputs.
Material uncertainties — spectrum coordination disputes, sovereign capacity mandate shifts, and launch vehicle supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding ITU filing queue resolution and REACH chemical compliance timeline adherence. Practitioners should keep alternative scenarios live as NATO defense procurement priorities and FCC orbital debris mitigation standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Remote Sensing Satellite Market
Satellite
Asia-Pacific Satellite Connectivity Market
Satellite
Optical Satellite Communication Market
Satellite
South Korea Satellite Communication Market
Satellite
Electric Propulsion Satellite Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
Latin America Satellite Connectivity Market
Satellite
Russia Satellite Communications Market
Satellite
South Korea Satellite Connectivity Market
Satellite
Europe Satellite IoT Market
Satellite
ASEAN Satellite Imagery Services Market
Satellite
Europe Satellite Bus Market
Satellite
Satellite Backhaul Market
Satellite
Japan Satellite Communication Market
Satellite
Canada Satellite Connectivity Market
Satellite
North America Satellite Bus Market