
 Global Maritime Satellite Communication Market | 2026-2036
Global Maritime Satellite Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Global Maritime Satellite Communication Market Foresight
European satellite operators is restructuring maritime bandwidth provisioning as Nordic maritime clusters push for higher throughput. Inmarsat Group Limited leverages its geostationary constellation to anchor global safety-of-life services. Viasat Inc. competes through high-capacity Ka-band networks targeting cruise and offshore segments. Iridium Communications Inc. specializes in L-band resilience for polar-route shipping.
Maritime satellite communication encompasses ship-to-shore and ship-to-ship data, voice, and distress signaling via geostationary, medium-earth-orbit, and low-earth-orbit satellite constellations operating across L-band, Ku-band, and Ka-band frequencies with terminal antennas stabilized to within 0.2 degrees in heavy seas. The technology enables real-time navigation updates, engine telemetry, crew welfare connectivity, and regulatory compliance for vessels operating beyond terrestrial network range. VSAT Terminals command the largest installed base among product types, though Iridium Systems gains ground in fishing and expedition fleets requiring compact form factors. Fleet Management services generate recurring revenue streams as oilfield services and freight forwarders mandate continuous asset tracking. Merchant Shipping remains the dominant application by vessel count, while Offshore Exploration commands premium pricing per-bandwidth due to operational criticality.
The International Maritime Organization's updated Global Maritime Distress and Safety System framework, alongside the EU's Radio Equipment Directive and the US FCC's Part 25 licensing for earth stations on vessels, mandate certified terminal interoperability and emergency priority signaling. These frameworks elevate barriers for uncertified equipment vendors while accelerating fleet refresh cycles. Stakeholders must weigh spectrum auction outcomes against next-generation constellation deployment timelines when committing to multi-year service contracts.
Market Dynamics
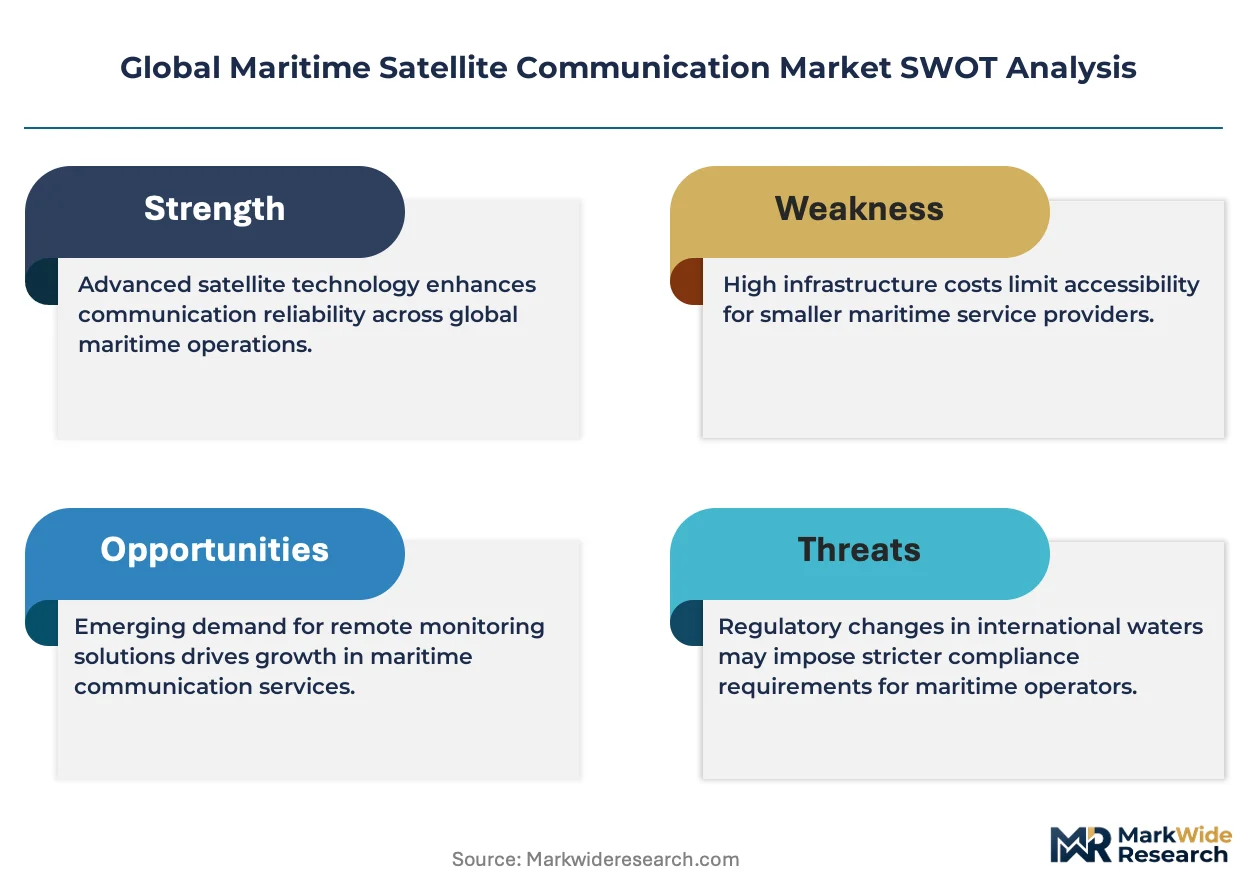
The International Maritime Organization's GMDSS modernization mandate is forcing commercial fleets to replace legacy L-band terminals with multi-orbit capable systems, compressing equipment refresh cycles and redistributing service provider market power.
Growth Catalysts
- IMO GMDSS Modernization:The updated Global Maritime Distress and Safety System framework mandates satellite terminal interoperability for vessels over 300 gross tonnage, compelling fleet-wide hardware upgrades.
- Ku/Ka-band Capacity Expansion:High-throughput satellite deployments enable streaming video, cloud-based navigation, and real-time engine diagnostics for container ships and cruise operators.
- Singapore Maritime Cluster:The port authority's digitalization incentives and vessel registration density create concentrated demand for integrated fleet management platforms.
Market Restraints
- Geostationary Orbit Congestion:Slot scarcity above high-traffic shipping lanes limits new operator entry and concentrates pricing power among incumbent spectrum holders.
- L-band Spectrum Reallocation:Military and aviation priority claims in the 1-2 GHz range threaten maritime service continuity and force costly terminal retuning.
- Terminal Hardware Costs:Stabilized VSAT antennas with sub-0.2-degree tracking precision require precision gyroscopic components, inflating upfront capital outlays for smaller fleet operators.
Strategic Opportunities
- Arctic Route Expansion:Polar shipping lanes opening via ice-class vessels require Iridium's LEO constellation coverage where geostationary signals fail, creating a captive addressable market.
- EU Green Deal Alignment:Emissions monitoring mandates under the Carbon Border Adjustment Mechanism incentivize real-time fuel consumption telemetry via satellite backhaul.
- Crew Welfare Monetization:Seafarer connectivity packages for social media and telemedicine represent untapped recurring revenue streams distinct from operational data services.
Industry Challenges
- Multi-orbit Integration Complexity:Fleet operators struggle to harmonize geostationary, medium-earth-orbit, and low-earth-orbit service handoffs without specialized network engineering talent.
- Type Approval Bottlenecks:National regulators in Norway, Greece, and Singapore maintain divergent terminal certification timelines, delaying vessel deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Maritime Satellite Communication Market |
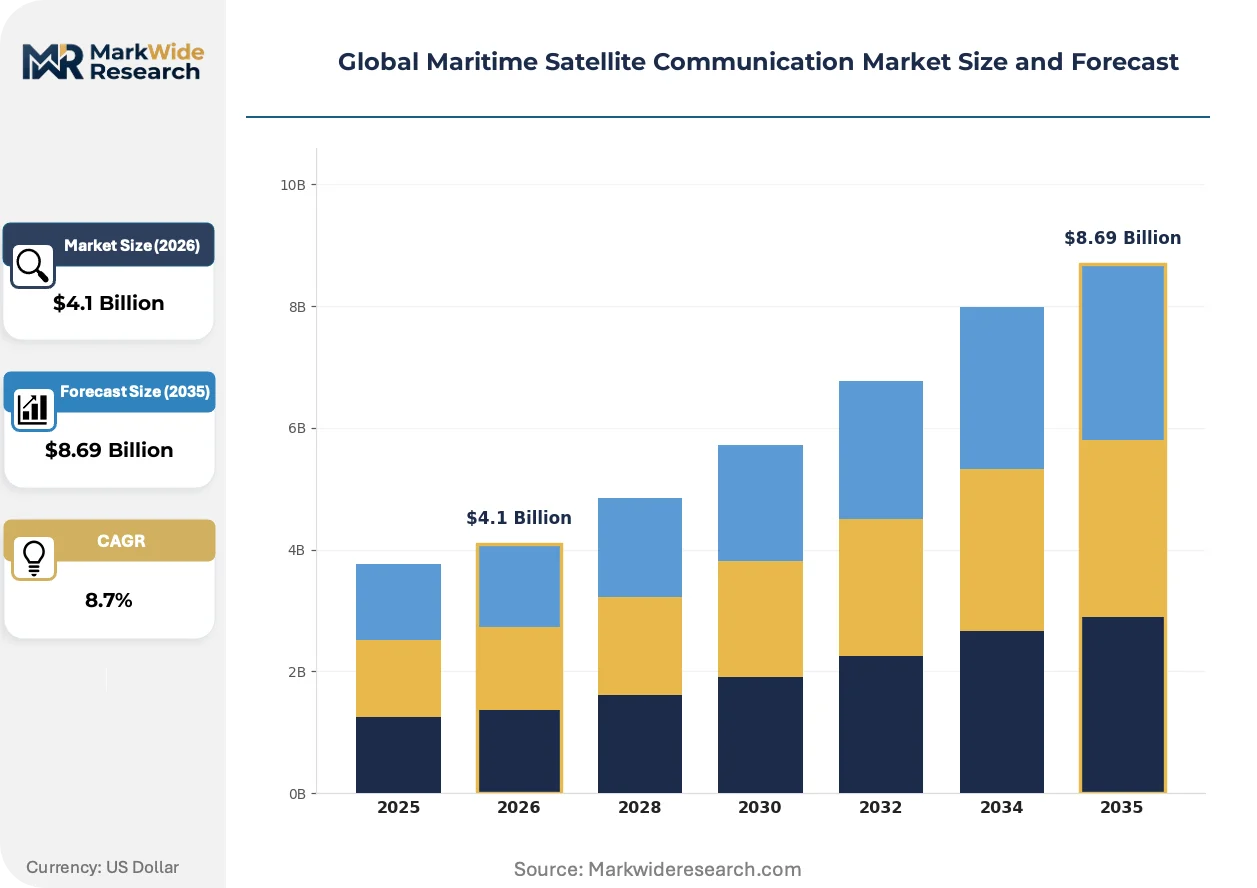
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VSAT Terminals, Inmarsat GSPS, Iridium Systems, FleetBroadband, L-Band Terminals Service Type: Data Connectivity, Voice Communication, Fleet Management, Weather Services, Emergency Alerts Application: Merchant Shipping, Offshore Exploration, Cruise Ships, Fishing Vessels, Naval Vessels End User: Cruise Operators, Fisheries, Oilfield Services, Defense Agencies, Freight Forwarders |
| Companies Covered | Inmarsat Group Limited, Viasat Inc., Iridium Communications Inc., Marlink SAS, KVH Industries Inc., Speedcast International, SES Satellite, Thuraya Telecommunications Company, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Maritime Satellite Communication Market Shifts & Advancements
Maritime connectivity architecture is pivoting from single-band dependency toward hybrid orbit configurations, with terminal manufacturers and service providers racing to bundle seamless handoff capabilities.
Software-defined radio terminals are consolidating multiple frequency bands and orbital regimes into unified hardware platforms. Container lines and offshore drillers are adopting these systems to reduce deck footprint and simplify sparing strategies. The technology is consolidating vendor relationships as fleet operators favor single-source managed service contracts over multi-provider arrangements.
The EU Radio Equipment Directive now mandates cybersecurity certification for satellite terminals operating in European waters, imposing hardware design constraints that preclude uncertified equipment from EU-flagged vessels. Shipowners are responding by embedding compliance verification into procurement specifications, favoring vendors with established EU notified body relationships.
Charterers are unbundling connectivity services from vessel hire agreements, directly contracting satellite providers to ensure data sovereignty over cargo monitoring and engine performance. This disintermediation concentrates buying power with commodity traders and oil majors while reducing shipowner service selection autonomy, with the pattern most pronounced in Singapore and Rotterdam spot charter markets.
Global Maritime Satellite Communication Market Segmentation
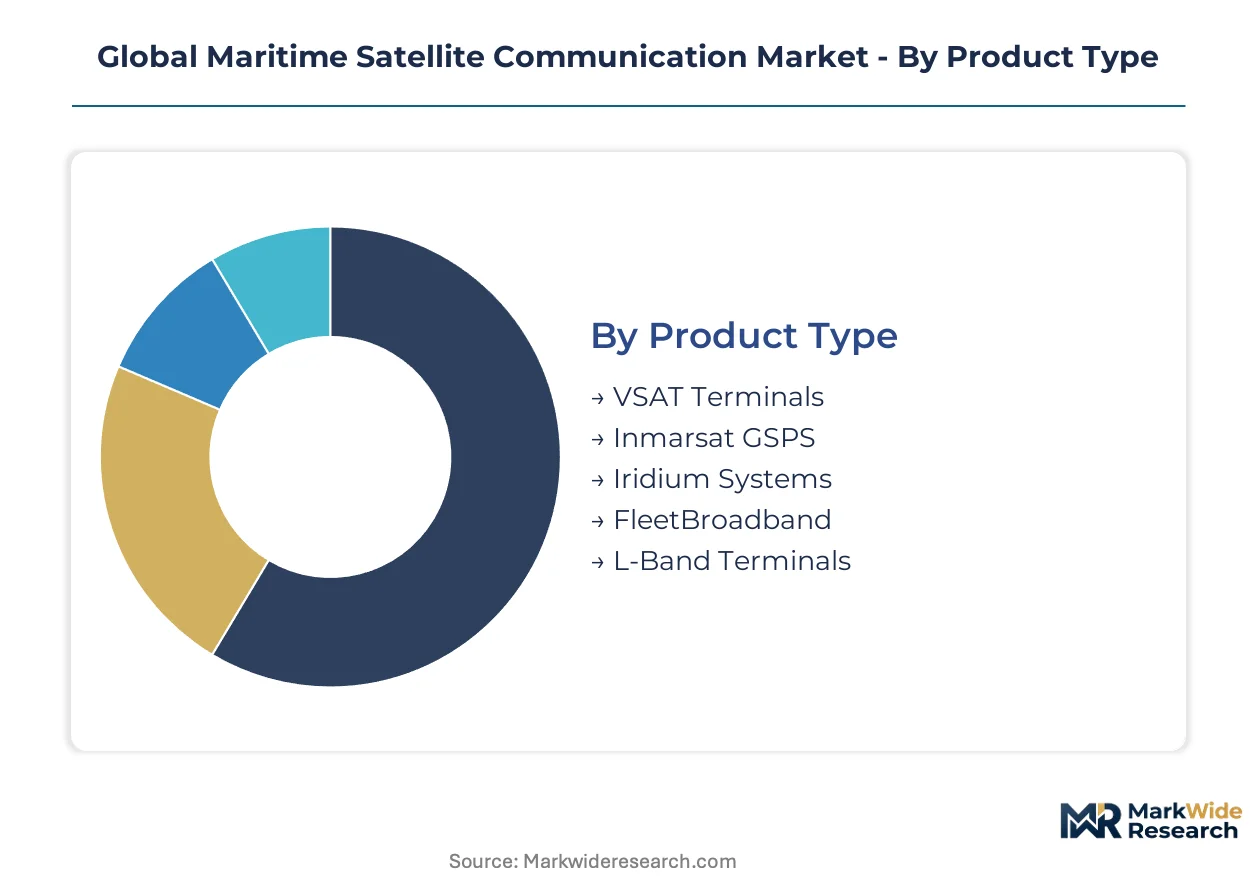
Maritime satellite communication segments reflect divergent technical architectures and integration depths. Terminal hardware, service bundles, vessel applications, and operator types each demand distinct procurement criteria and lifecycle management approaches.
Product Type:
Standalone terminal systems dominate deck-mounted installations, while embedded modules integrate directly into bridge electronics suites.
- VSAT Terminals:Stabilized Ku/Ka-band antenna systems with gyroscopic tracking precision below 0.2 degrees. Container lines operating Singapore-Rotterdam routes deploy these for high-throughput engine telemetry and crew welfare streaming.
- Iridium Systems:Compact L-band transceivers leveraging low-earth-orbit constellation coverage. Polar-route ice-class vessels operating Norway's Northern Sea Route depend on these where geostationary signals fail.
- Inmarsat GSPS:Geostationary handheld voice terminals for basic ship-to-shore communication.
- FleetBroadband:Integrated IP-based maritime broadband terminals supporting simultaneous voice and data.
- L-Band Terminals:Legacy safety-of-life equipment facing IMO-mandated replacement cycles.
Volume placements concentrate in VSAT Terminals; the faster expansion belongs to Iridium Systems.
Service Type:
Operational services command premium pricing per megabyte, while crew-facing connectivity competes on flat-rate subscription models.
- Fleet Management:Continuous vessel tracking, fuel consumption monitoring, and route optimization via satellite backhaul. Oilfield services contractors in the North Sea mandate these services for chartered asset visibility.
- Data Connectivity:High-bandwidth IP services enabling cloud navigation updates and real-time engine diagnostics.
- Voice Communication:Ship-to-shore telephony for crew welfare and operational coordination.
- Weather Services:Gridded meteorological data broadcasts for route planning.
- Emergency Alerts:Distress signaling integrated with GMDSS compliance frameworks.
Fleet Management claims the steepest expansion trajectory as charterers disintermediate shipowners to secure data sovereignty.
Application:
Commercial vessel categories separate by regulatory compliance burden and bandwidth intensity per vessel.
- Merchant Shipping:Container, bulk, and tanker fleets representing the largest installed terminal base by vessel count. Greek and Singapore-flagged fleets drive replacement demand under IMO GMDSS modernization deadlines.
- Offshore Exploration:Drillships and production platforms requiring mission-critical redundancy. Norwegian North Sea operators pay premium per-bandwidth pricing for guaranteed uptime SLAs.
- Cruise Ships:Passenger vessels demanding symmetric bandwidth for guest connectivity.
- Fishing Vessels:Smaller craft prioritizing compact terminal form factors and L-band resilience.
- Naval Vessels:Military applications with hardened security and frequency-hopping requirements.
Merchant Shipping anchors absolute terminal shipments; Offshore Exploration generates the highest service revenue per vessel.
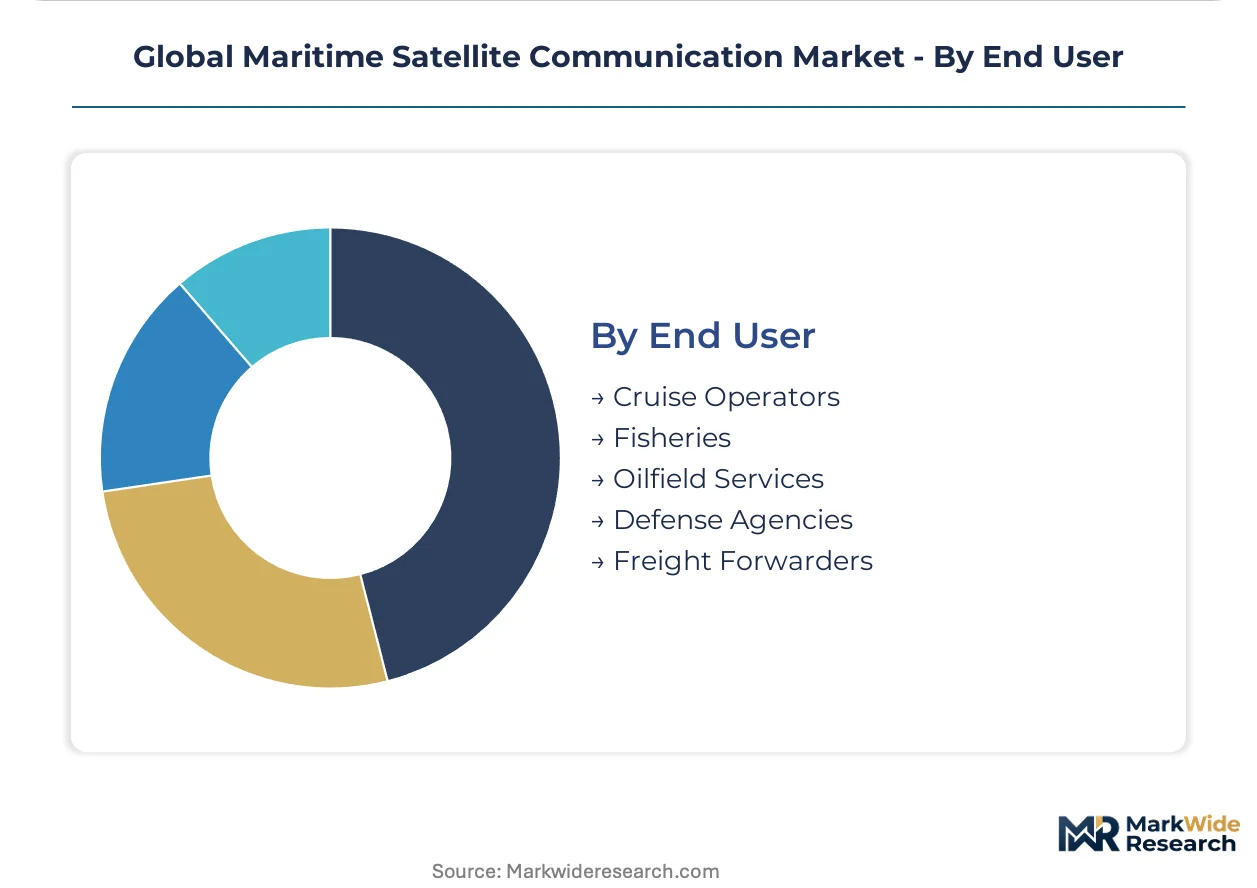
End User:
Direct satellite contracting patterns separate asset owners from charterers seeking data control.
- Oilfield Services:Schlumberger, Halliburton, and Transocean equivalents chartering specialized vessels. These operators increasingly bypass shipowners to contract connectivity directly, concentrating procurement power in Houston and Aberdeen.
- Freight Forwarders:Commodity traders and logistics platforms requiring cargo visibility independent of carrier systems.
- Cruise Operators:Carnival, Royal Caribbean, and Norwegian Cruise Line managing guest experience as core revenue.
- Fisheries:Industrial trawler fleets and coastal cooperatives with cost-sensitive terminal selections.
- Defense Agencies:National navies with classified communication requirements and dedicated spectrum allocations.
Oilfield Services and Freight Forwarders are gaining share fastest through charter market disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's bunkering infrastructure and vessel registration density anchor Asia-Pacific maritime connectivity demand. Norwegian North Sea oilfield clusters and Greek shipping ownership networks concentrate terminal procurement decisions in European waters.
Singapore
Container transshipment volumes and flag-state registration density drive VSAT terminal deployments across the Strait of Malacca. The Maritime and Port Authority's digitalization incentives subsidize fleet management platform adoption. Jurong Port and Tuas Mega Port terminals host concentrated service provider technical support operations.
Norway
Offshore exploration rig counts and ice-class vessel construction sustain premium bandwidth pricing in the North Sea. The Norwegian Maritime Authority enforces strict terminal type-approval timelines under EU Radio Equipment Directive alignment. Stavanger and Bergen maritime clusters coordinate polar-route connectivity specifications for Northern Sea Route operations.
Greece
Shipowner control of global tanker and bulk carrier fleets concentrates L-band replacement demand ahead of IMO GMDSS deadlines. The Hellenic Ministry of Maritime Affairs coordinates with classification societies on cybersecurity certification requirements. Piraeus port authority and Athens-based fleet management centers drive procurement aggregation for international vessel registries.
United States
Gulf of Mexico offshore drilling activity and Jones Act vessel compliance sustain specialized terminal demand. The FCC's Part 25 licensing framework for earth stations on vessels creates regulatory entry barriers for uncertified equipment. Houston oilfield services contractors and Louisiana offshore supply bases concentrate direct satellite contracting power away from shipowners.
United Kingdom
London marine insurance markets and Aberdeen offshore engineering clusters influence connectivity specification standards. The UK Space Agency coordinates satellite operator licensing with Maritime and Coastguard Agency safety requirements. Southampton and Liverpool port digitalization programs mandate real-time cargo telemetry for container terminal efficiency.
Global Maritime Satellite Communication Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue low-earth-orbit specialization and software-defined terminal architectures. The vendor base stratifies across geostationary incumbents with spectrum depth, regional service integrators with port-level technical presence, and constellation operators with polar coverage advantages. Three archetypes dominate: spectrum holders anchoring safety-of-life services, bandwidth wholesalers targeting cruise and offshore segments, and niche specialists in fishing vessel compact terminals. Competitive moves concentrate on multi-orbit service bundling and cybersecurity certification pre-positioning for EU market access.
Within the geostationary tier, Inmarsat Group Limited and Viasat Inc. occupy positions defined by orbital slot control and high-throughput capacity deployment respectively. Iridium Communications Inc. exemplifies the low-earth-orbit specialization archetype, anchoring polar-route service capabilities where geostationary signals fail. These three entities represent distinct technical positioning strategies—L-band resilience, Ka-band throughput, and LEO coverage—rather than direct substitutability in fleet procurement decisions.
| Leading Market Players |
|---|
| Inmarsat Group Limited |
| Viasat Inc. |
| Iridium Communications Inc. |
| Marlink SAS |
| KVH Industries Inc. |
| Speedcast International |
| SES Satellite |
| Thuraya Telecommunications Company |
| Leonardo S.p.A. |
| Others |
Supply & Pricing Matrix
Gyroscopic stabilization engineers concentrated in Stuttgart and Tokyo drive labor-cost differentials that widen pricing-tier spreads between precision VSAT terminals and compact L-band alternatives. Terminal manufacturers pass specialized workforce premiums through to offshore exploration operators while fishing fleets absorb economy-tier hardware with reduced tracking precision.
Pricing Analysis
Warranty and lifecycle service bundling separate premium contracts from hardware-only transactions in maritime satellite procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EU Radio Equipment Directive and IMO GMDSS frameworks versus uncertified alternatives. Pricing pressure stems from charterer disintermediation as oilfield services contractors negotiate direct satellite contracts, compressing shipowner margins. Freight forwarders exhibit highest price sensitivity due to cargo-visibility commoditization, while offshore drillers accept premium pricing for guaranteed uptime SLAs.
Supply Chain Analysis
Gallium nitride power amplifier supply rests on Japanese and US specialty semiconductor foundries, with precision gyroscopic components drawing from German and Swiss precision engineering clusters. Raw material dependencies span rare earth magnets for antenna stabilization motors, high-purity aluminum for reflector dishes, and radiation-hardened chipsets for orbital radiation tolerance. Single-source vulnerability concentrates in geostationary transponder manufacturing, where slot scarcity limits alternative supplier qualification. Distribution runs through port-level technical service hubs in Singapore, Rotterdam, and Houston rather than direct manufacturer-to-fleet relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Maritime Satellite Communication Market operates as a cost-of-compliance arena where IMO GMDSS modernization mandates erect terminal certification barriers that protect incumbent spectrum holders from unqualified competitors.
For Market Incumbents: Lock in multi-orbit service bundling capabilities before LEO constellation operators achieve seamless handoff engineering. Defend against charterer disintermediation by embedding fleet management platforms with proprietary data analytics that reduce customer switching elasticity. Prioritize cybersecurity certification investment under EU Radio Equipment Directive to exclude uncertified hardware from EU-flagged vessel procurement. For New Entrants and Emerging Players: Begin with polar-route specialization where Iridium's LEO coverage holds geographic monopoly and geostationary incumbents cannot replicate service. Target fishing vessel and expedition fleet segments underserved by VSAT form factor constraints, offering compact L-band terminals with simplified installation protocols. Pursue software-defined radio architectures that consolidate multiple frequency bands into unified hardware platforms, reducing deck footprint and sparing complexity. For Investors and Strategic Acquirers: Re-rating potential sits with regional service integrators possessing port-level technical presence given charter market disintermediation concentrating procurement power in commodity trading hubs. Long-term viability favors entities with established EU notified body relationships and multi-orbit handoff capabilities rather than single-band dependency. Monitor Arctic route shipping volume as inflection indicator for polar-capable LEO constellation valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Service Bundling | Enables seamless GEO-MEO-LEO handoffs for fleet operators lacking specialized network engineering talent. |
| Cybersecurity Certification Investment | Secures EU Radio Equipment Directive compliance that precludes uncertified equipment from European waters. |
| Polar Route Capability Development | Captures Northern Sea Route traffic where geostationary signals fail and ice-class vessels require LEO coverage. |
| Direct Charterer Contracting | Bypasses shipowner intermediation to secure data sovereignty for oilfield services and commodity traders. |
| Software-Defined Terminal Architecture | Consolidates multiple frequency bands into unified hardware platforms with reduced deck footprint. |
Research Methodology
IMO regulatory filings, satellite operator spectrum auction records, and vessel registration databases formed the secondary backbone for market sizing and compliance timeline mapping. Primary interviews with fleet management directors, satellite service procurement officers, maritime regulatory affairs leads, and terminal engineering heads validated equipment refresh cycle assumptions and charter market disintermediation patterns. Bottom-up terminal shipment estimates by vessel type and flag state triangulated against top-down service revenue projections from operator disclosures.
Bottom-up modeling anchored on VSAT terminal installations, Iridium system placements, and service contract values across merchant shipping, offshore exploration, and cruise applications. Segmentation dimensions spanned product type, service bundle, vessel category, and end-user contracting pattern throughout the forecast period. CAGRs derived from equipment replacement cycles under GMDSS modernization deadlines, Ku/Ka-band capacity expansion timelines, and polar route traffic growth assumptions.
Spectrum reallocation decisions, constellation deployment delays, and charter market contracting pattern shifts are the dominant revision risks to installed base forecasts. Regulatory approval timelines for terminal type certification in Norway, Greece, and Singapore introduce deployment schedule uncertainty. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Communications Service Market
Satellite
Saudi Arabia Satellite Imagery Services Market
Satellite
Indonesia Satellite Communications Market
Satellite
Satellite Communication (SATCOM) Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
Satellite Services Market
Satellite
Global Satellite Modem Market
Satellite
All-Electric Satellites Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
Commercial LEO Satellite Market
Satellite
UAE Satellite Imagery Services Market
Satellite
Sudan Satellite Transponder Market
Satellite
Europe Satellite Bus Market
Satellite
Satellite Gateway Market
Satellite
China Satellite Communication Market