
 Russia Non-Contact Infrared Thermometer Market | 2026-2036
Russia Non-Contact Infrared Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Non-Contact Infrared Thermometer Market Insights
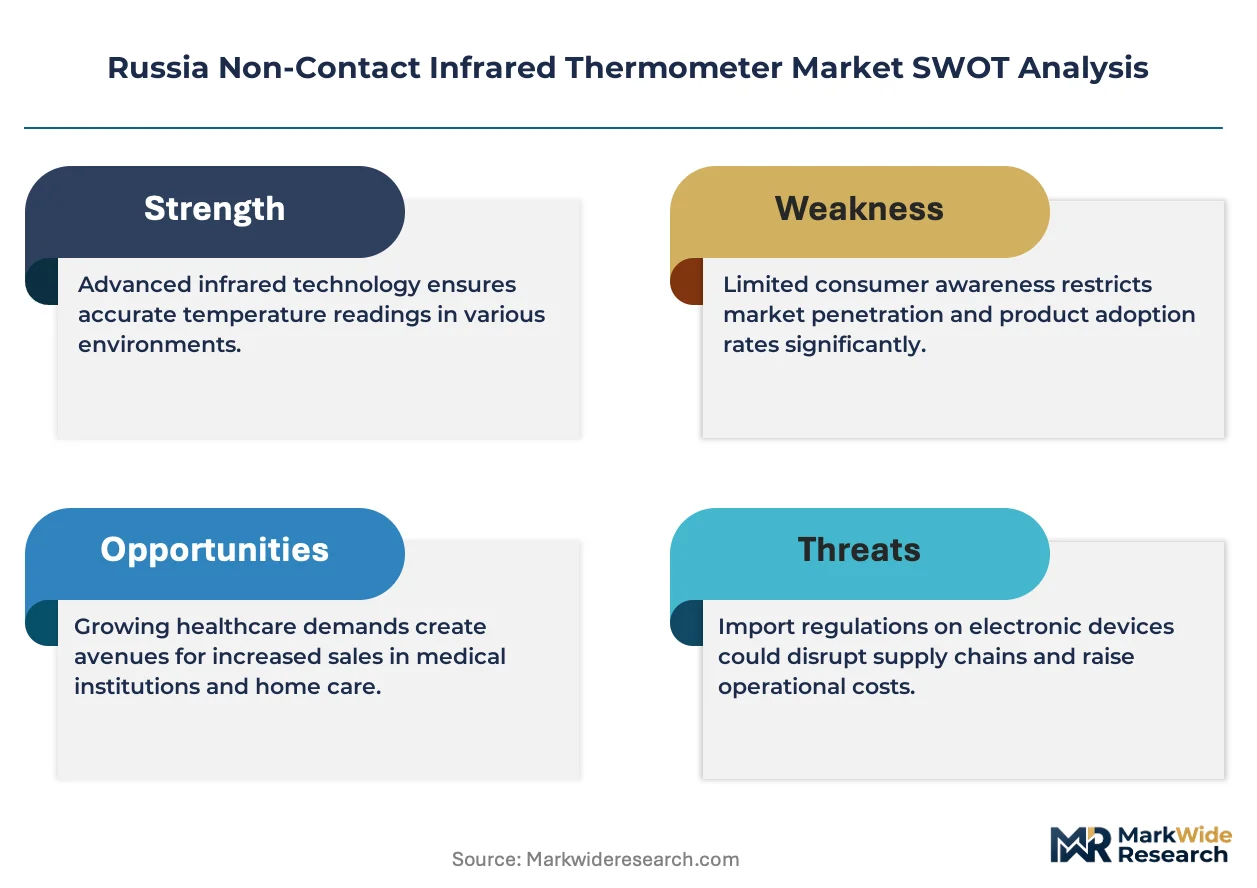
Healthcare procurement is realigning toward non-contact screening protocols across Russia's federal hospital networks. Fluke Corporation leverages its industrial metrology heritage to compete in high-precision segments. Testo SE & Co. KGaA anchors its position through specialized HVAC and food safety applications. PCE Instruments differentiates via calibrated laboratory-grade devices for research institutes.
A non-contact infrared thermometer measures surface temperature by detecting infrared radiation emitted by an object, typically operating within spectral ranges of 8-14 micrometers for medical applications and achieving accuracy within ±0.2°C at close distances. Its primary purpose spans fever screening in clinical settings, process monitoring in manufacturing, and HACCP compliance in food handling. Healthcare applications dominate unit volume across Russian state tenders, while industrial segments command higher per-unit pricing due to extended temperature ranges and certification requirements. Digital technology integration is accelerating as manufacturers embed Bluetooth connectivity and cloud logging for regulatory traceability.
Rosstandart's GOST R certification and Russia's Ministry of Health registration requirements shape product entry pathways for foreign manufacturers. The Eurasian Economic Union's technical regulations on medical devices, aligned with harmonized standards, create compliance complexity for importers from Europe and Asia. Stakeholders must monitor evolving localization mandates and the Central Bank's import-substitution financing mechanisms as procurement rules tighten domestic preference clauses.
Market Dynamics
Rosstandart's tightening GOST R certification requirements for medical-grade infrared devices is compressing product approval timelines and forcing foreign manufacturers toward localization partnerships with Russian distributors.
Growth Catalysts
- Hospital Network Expansion:Federal hospital networks in Moscow and Saint Petersburg are mandating non-contact temperature screening protocols across emergency departments and outpatient clinics.
- GOST R Certification Alignment:Harmonization with Eurasian Economic Union technical regulations is streamlining cross-border device registration for compliant manufacturers.
- Industrial Process Monitoring:Manufacturing corridors in the Central Federal District are deploying infrared thermometers for predictive maintenance and quality control automation.
Market Restraints
- Import Substitution Financing:Central Bank mechanisms favoring domestic procurement create capital access asymmetry for foreign device manufacturers.
- Sensor Supply Concentration:Infrared detector module production concentrates in Asian manufacturing hubs, exposing Russian assemblers to transit and customs volatility.
- Accuracy Standard Escalation:Medical-grade ±0.2°C tolerance requirements demand calibrated reference sources that extend production cycles.
Strategic Opportunities
- Bluetooth-Enabled Fleet Management:Cloud logging functionality is creating attach-rate potential for software subscriptions in hospital network tenders.
- HACCP Compliance Mandates:Food safety regulators are expanding infrared thermometer requirements across cold chain logistics and processing facilities.
- Research Institute Calibration Services:Laboratory-grade device segments offer recurring revenue through annual recertification contracts.
Industry Challenges
- Metrology Technician Scarcity:Certified calibration specialists for infrared reference standards are concentrated in Moscow and Saint Petersburg, constraining regional service coverage.
- Legacy System Integration:Hospital information systems require custom API development to ingest temperature screening data streams from new device deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Non-Contact Infrared Thermometer Market |
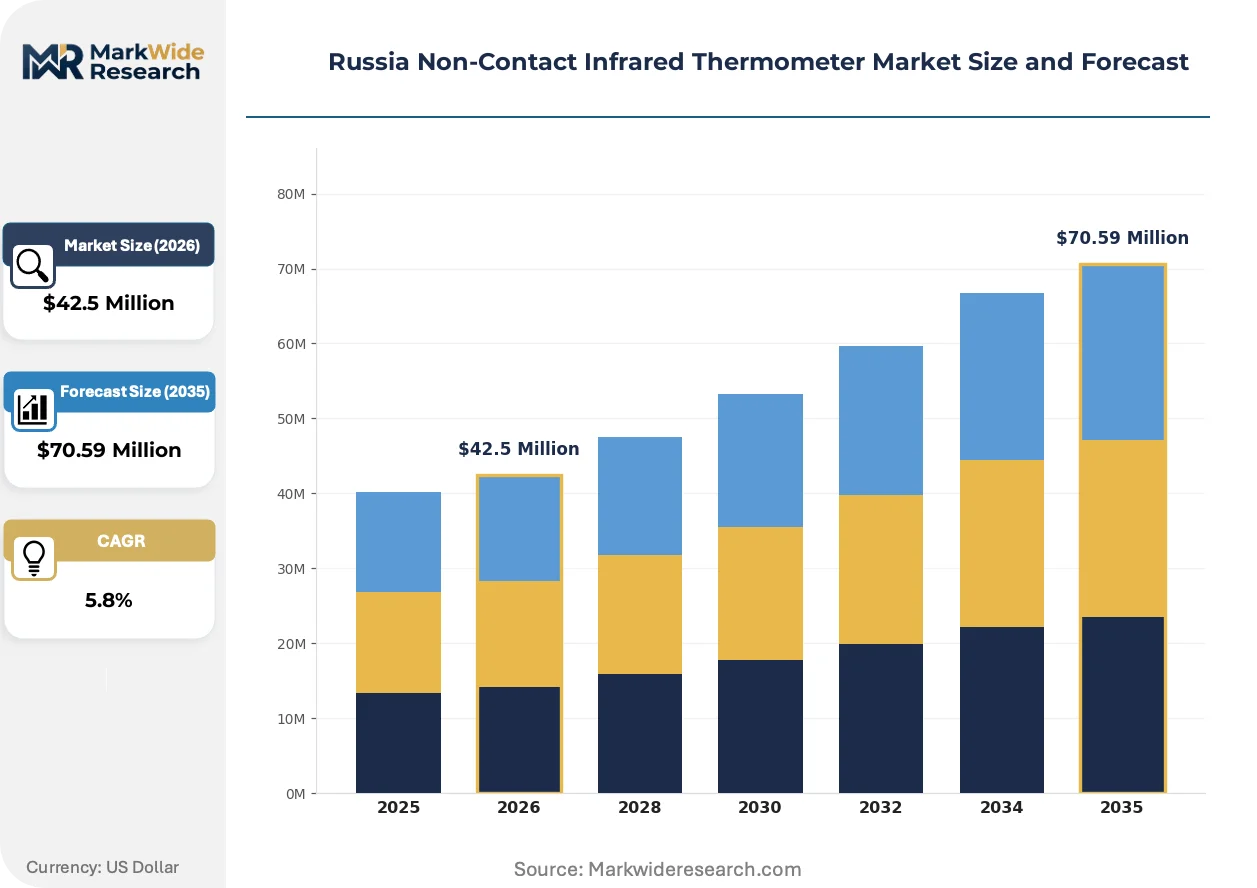
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $70.59 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Healthcare, Industrial, Food Safety, Automotive Technology: Infrared, Laser, Thermocouple, Digital End User: Hospitals, Laboratories, Manufacturing Plants, Restaurants Sales Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | OMRON Healthcare Inc., Fluke Corporation, Testo SE & Co. KGaA, PCE Instruments, Microlife Corporation, Omega Engineering, AMETEK Land, Welch Allyn, Contec Medical Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Non-Contact Infrared Thermometer Market Trends and Innovations
Digital connectivity architectures are reconfiguring how temperature data flows from point-of-measurement to enterprise systems, creating new value capture layers beyond hardware sales.
Multi-sensor fusion is integrating infrared temperature detection with facial recognition and access control systems in high-throughput screening installations. Corporate campuses and transportation hubs in Moscow are deploying these integrated checkpoints at scale. The convergence is integrating thermal screening into broader security infrastructure, compressing standalone device margins while expanding system-level contract values.
Rosstandart's updated GOST R 8.736-2022 standard for non-contact thermometry is mandating traceable calibration certificates for all medical-grade devices sold in Russia. Importers must now maintain accredited in-country calibration facilities or partner with certified Russian metrology laboratories. The regulation is forcing European and Asian manufacturers to establish local service partnerships, reshaping distribution economics.
State tender specifications are prioritizing devices with embedded data logging and exportable screening records. Hospital procurement committees in the Central Federal District are rejecting analog-only models from approved vendor lists. This specification creep is accelerating replacement cycles for installed base units that lack digital connectivity, concentrating demand refresh in federal district hospital networks.
Russia Non-Contact Infrared Thermometer Market Segmentation
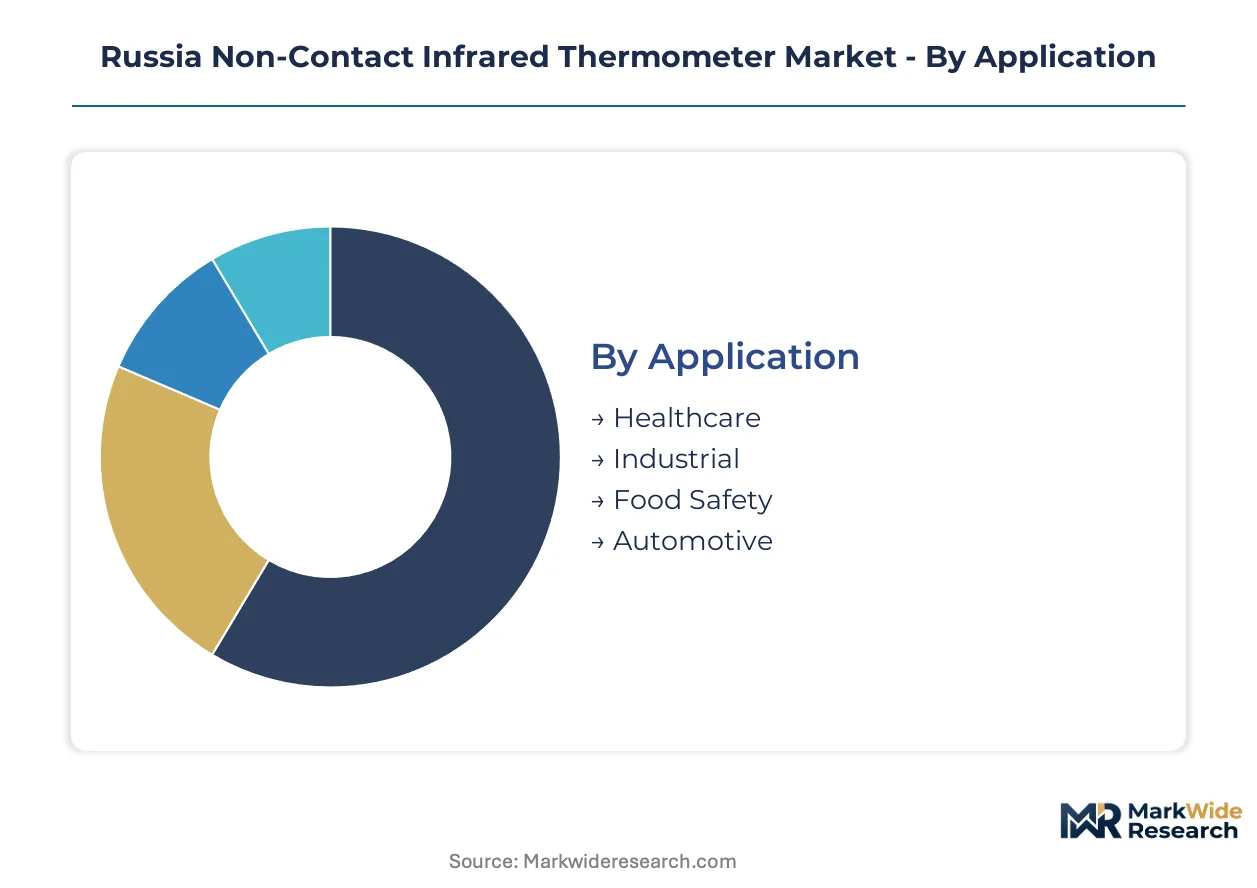
Infrared thermometry in Russia fragments across distinct performance tiers and compliance regimes. Each segment carries unique GOST R certification pathways and procurement channels that determine vendor access to federal tenders.
Application:
Technical specifications diverge sharply between medical-grade precision requirements and industrial range tolerance.
- Healthcare:Devices operate within 8-14 micrometer spectral range achieving ±0.2°C accuracy for fever screening compliance. Moscow and Saint Petersburg hospital networks mandate embedded data logging for state procurement eligibility.
- Industrial:Extended temperature ranges from -50°C to 1000°C serve predictive maintenance in Central Federal District manufacturing corridors. Per-unit pricing exceeds medical segments due to ruggedized housing and calibration certification.
- Food Safety:HACCP-compliant units with IP65 ratings dominate cold chain logistics and processing facility audits.
- Automotive:Portable diagnostics tools integrate with OBD systems for engine and HVAC troubleshooting in service centers.
Healthcare leads on scale; Industrial leads on momentum.
Technology:
Sensor architecture determines calibration complexity and regulatory approval timelines under Rosstandart oversight.
- Infrared:Pyroelectric and thermopile detectors form the dominant architecture, with medical variants requiring traceable reference sources for GOST R 8.736-2022 compliance.
- Laser:Sight-enabled targeting systems reduce measurement error in high-temperature industrial environments. Demand concentrates in metallurgy and power generation facilities.
- Thermocouple:Contact-verification hybrids serve laboratory calibration workflows where infrared accuracy requires periodic validation.
- Digital:Bluetooth-enabled models with cloud logging functionality are gaining share fastest in hospital fleet management tenders.
Infrared dominates installed base; Digital climbs the fastest on connectivity attach rates.
End User:
Procurement authority and technical specification complexity vary dramatically across buyer categories.
- Hospitals:Federal district networks enforce standardized tender specifications requiring Ministry of Health registration and annual recalibration contracts.
- Laboratories:Research institutes in Moscow and Saint Petersburg demand laboratory-grade devices with ISO/IEC 17025 traceable certificates for publication-grade measurements.
- Manufacturing Plants:Central Federal District automotive and aerospace clusters deploy infrared thermometers for quality control automation and thermal process monitoring.
- Restaurants:HACCP audit requirements drive replacement cycles in Moscow's food service sector, with procurement concentrated through wholesale distributors.
Hospitals anchor volume; Laboratories command premium pricing on certification services.
Sales Channel:
Channel selection determines margin structure and compliance documentation access for foreign manufacturers.
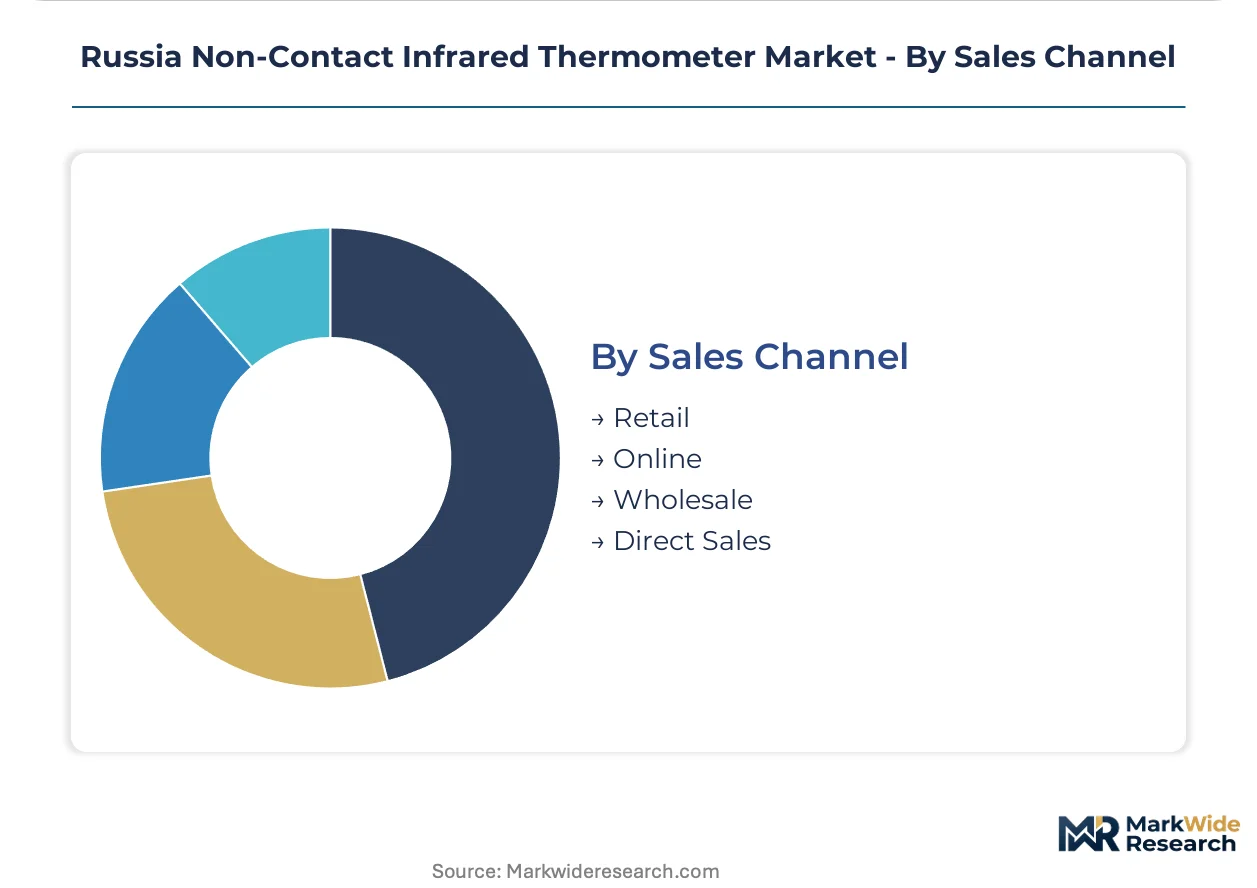
- Retail:Pharmacy chains and medical supply stores serve individual practitioners and small clinics with lower-complexity devices.
- Online:E-commerce platforms face intensifying Rosstandart enforcement on counterfeit medical-grade listings, pushing authorized distributors toward verified seller programs.
- Wholesale:Regional distributors consolidate demand from provincial hospital networks and industrial clusters outside Moscow and Saint Petersburg.
- Direct Sales:Foreign manufacturers establish local offices to navigate GOST R certification and tender participation in federal procurement.
Wholesale captures regional volume; Direct Sales expands most quickly on localization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing manufacturing capacity toward jurisdictions with streamlined metrology certification pathways. Russia's tightening GOST R requirements are accelerating localization partnerships as foreign manufacturers seek cost-of-compliance parity with domestic assemblers.
Central Federal District
Moscow's federal hospital networks and Saint Petersburg's research institutes drive procurement volume for medical-grade devices with embedded data logging. Rosstandart's GOST R 8.736-2022 standard mandates traceable calibration certificates, compressing approval timelines for localized production. The district's manufacturing corridors deploy industrial infrared thermometers for predictive maintenance automation.
Volga Federal District
Automotive clusters in Tatarstan and Samara Oblast generate demand for portable diagnostic tools integrating with OBD systems. The region's machine-building plants require extended temperature range devices for thermal process monitoring. Procurement concentrates through wholesale distributors serving provincial industrial facilities outside capital markets.
Siberian Federal District
Metallurgy and power generation facilities in Novosibirsk and Kemerovo deploy laser-sight enabled thermometers for high-temperature environments. Cold chain logistics operators across the region adopt HACCP-compliant units with IP65 ratings for audit compliance. Distribution runs through regional distributors consolidating demand from remote industrial sites.
Northwestern Federal District
Saint Petersburg's research institutes demand laboratory-grade devices with ISO/IEC 17025 traceable certificates for publication-grade measurements. The city's food processing sector drives replacement cycles through HACCP audit requirements. Hospital procurement committees reject analog-only models, accelerating digital connectivity adoption.
Ural Federal District
Heavy industry concentration in Chelyabinsk and Yekaterinburg creates demand for ruggedized industrial thermometers with calibration certification. The district's manufacturing plants deploy infrared thermometry for quality control automation in aerospace and defense supply chains. Service coverage constraints from metrology technician scarcity extend equipment downtime risks.
Russia Non-Contact Infrared Thermometer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with medical-grade procurement favoring established certification holders while industrial applications tolerate OEM sourcing. The vendor base concentrates around three strategic archetypes: multinational metrology houses leveraging industrial heritage, specialized HVAC and food safety equipment providers, and calibrated laboratory-grade device fabricators serving research markets. Competitive moves center on localization partnerships for GOST R compliance and Bluetooth-enabled fleet management software attach rates.
Among multinational participants, Fluke Corporation anchors the high-precision industrial segment through its metrology heritage, while Testo SE & Co. KGaA occupies a position within specialized environmental and food safety applications. PCE Instruments exemplifies the laboratory-grade calibration tier serving research institutes with traceable certification requirements. These three represent distinct competitive vectors—industrial precision, environmental specialization, and research calibration—each demanding different regulatory navigation strategies under Rosstandart oversight.
| Leading Market Players |
|---|
| OMRON Healthcare Inc. |
| Fluke Corporation |
| Testo SE & Co. KGaA |
| PCE Instruments |
| Microlife Corporation |
| Omega Engineering |
| AMETEK Land |
| Welch Allyn |
| Contec Medical Systems |
| Others |
Pricing and Supply Chain Analysis
Rosstandart's GOST R 8.736-2022 calibration mandate is forcing foreign manufacturers toward localized service partnerships, compressing distributor margins and elevating landed costs for devices without in-country metrology infrastructure.
Pricing Analysis
Distributor markups in federal hospital tenders absorb compliance documentation burdens and calibration certification costs. Three-tier pricing structure across laboratory-grade, medical-grade, and industrial-grade certification levels separates premium segments anchored by ISO/IEC 17025 traceability from economy tiers facing price erosion. Cost compression in standard medical-grade units intensifies because wholesale channels consolidate demand from provincial networks. Hospital procurement committees in Moscow exhibit lowest price sensitivity due to budgetary autonomy, while regional clinics face capital constraints.
Supply Chain Analysis
Rosstandart's tightening domestic-content preferences are reshaping sourcing toward Eurasian Economic Union assembly partners and licensed Russian distributors. Infrared detector module production concentrates in China, Taiwan, and South Korea, exposing Russian assemblers to transit volatility and customs processing delays. Pyroelectric sensor arrays, thermopile detectors, and reference calibration sources constitute critical input dependencies. Single-source vulnerability concentrates in precision optics supply. Distribution runs through wholesale regional distributors consolidating provincial hospital and industrial demand outside capital markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Federal tender specifications now reject analog-only devices, redirecting procurement toward Bluetooth-enabled units with embedded data logging.
For Market Incumbents: Anticipate margin compression in standard medical-grade tiers as import-substitution financing advantages domestic assemblers. Defensive positioning demands deepening calibration service capabilities through accredited Moscow metrology partnerships. Channel control via exclusive distributor agreements protects tender participation access against emerging OEM competitors from Asia. For New Entrants and Emerging Players: E-commerce verification programs offer a digital-channel route to bypass wholesale margin stacking and reach provincial clinic procurement officers directly. White-space targets concentrate in Siberian and Ural Federal District industrial corridors underserved by metrology technician networks. Cold chain logistics operators present the most penetrable segment given HACCP audit expansion. A calibration-service bundling go-to-market angle differentiates against hardware-only incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with laboratory-grade device fabricators holding ISO/IEC 17025 accredited facilities and recurring recertification contract books. Long-term viability hinges on software attach rates from fleet management platforms rather than hardware replacement cycles. Acquisition targets should display established Rosstandart certification pathways and hospital GPO relationships. The signal to watch is Ministry of Health tender specification shifts toward mandatory cloud connectivity.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Localization | Accredited Moscow metrology partnerships satisfy GOST R 8.736-2022 and compress approval timelines. |
| Bluetooth Fleet Management Platform | Cloud logging functionality captures software subscription revenue from hospital network tenders. |
| Wholesale Distribution Consolidation | Regional distributor partnerships extend coverage into Volga and Siberian Federal District corridors. |
| HACCP Compliance Specialization | IP65-rated device portfolios capture food safety audit mandates across cold chain logistics. |
| Research Institute Service Contracts | Annual recertification agreements with Saint Petersburg laboratories generate recurring revenue streams. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged hospital procurement committees, biomedical engineers, GPO contracts managers, and Rosstandart certification specialists across Moscow and Saint Petersburg. Secondary validation drew from Eurasian Economic Union medical device registration databases, federal tender documentation, customs import records, and hospital equipment procurement disclosures. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across application segments.
Historical reference periods anchored the projection horizon to pre-pandemic baseline demand and post-surge normalization trajectories. Segmentation dimensions spanned application tier, technology architecture, end-user category, and sales channel structure. CAGRs derived from regression analysis of tender award volumes, import shipment values, and replacement cycle assumptions. Forecast inputs incorporated GOST R certification timeline data and Ministry of Health procurement budget allocations.
The model assumes a particular technology adoption path; alternative pathways for multi-sensor fusion screening systems would alter the outlook if integrated checkpoint deployments accelerate beyond standalone device replacement. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and Eurasian Economic Union harmonization progress. Sensor supply concentration and metrology technician scarcity constitute primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia-Pacific Touch Sensor Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Digital Temperature Gauge Market
Sensors and Controls
Cryogenic Temperature Controller Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
US Distributed Acoustic Sensing Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
Global Level Sensors Market
Sensors and Controls
Pressure Monitoring Market