
 Infrared Detector Market | 2026-2036
Infrared Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Detector Market Intelligence
The shift towards performance-based contracting in defense procurement is reshaping competitive positioning among infrared detector manufacturers. Teledyne Technologies leverages its extensive portfolio of imaging technologies to secure large-scale government contracts. Raytheon Technologies dominates the high-end military segment with its advanced missile tracking solutions. FLIR Systems specializes in thermal imaging systems for both commercial and defense applications, extending its market reach.
An infrared detector is a semiconductor device that converts radiant energy in the infrared spectrum into an electrical signal. These devices often utilize materials like Mercury Cadmium Telluride (MCT) to achieve high sensitivity and rapid response times for thermal imaging and sensing. While MCT technology leads in high-performance military applications, uncooled microbolometers command the larger volume market for consumer electronics and industrial uses. Defense contractors represent the highest-value end-user segment, while consumer electronics firms offer significant volume growth potential.
Export controls, particularly the US International Traffic in Arms Regulations (ITAR), strictly govern the sale and transfer of high-performance detectors. In parallel, standards from bodies like the ISO and requirements such as CE marking in Europe dictate quality and safety benchmarks for commercial-grade products. Navigating this dual-use regulatory environment is the central strategic challenge for manufacturers seeking to serve both military and commercial clients.
Market Dynamics
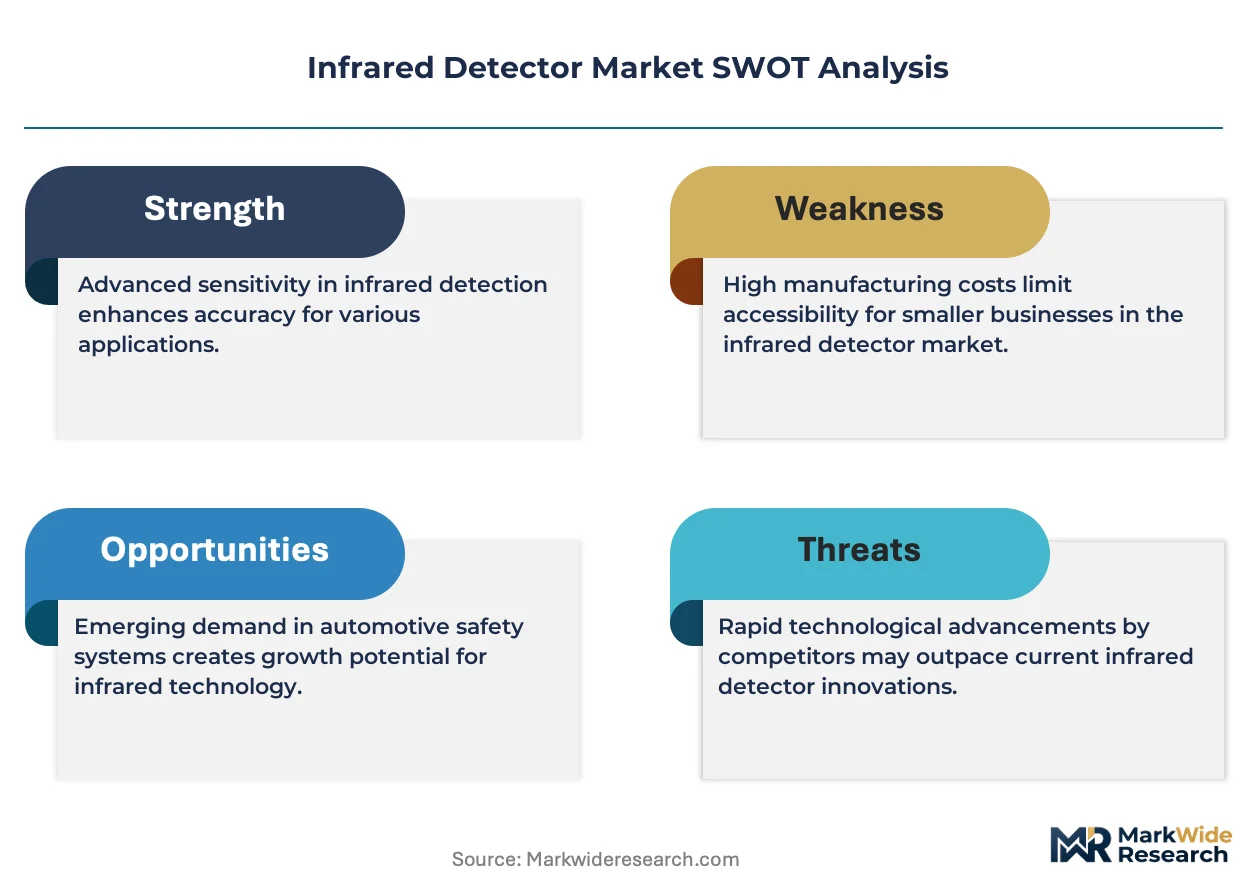
The central dynamic in the infrared detector market is the structural tension between the low-volume, high-performance requirements of the defense sector and the high-volume, cost-sensitive demands of commercial and industrial applications, governed by a complex dual-use regulatory framework.
Growth Catalysts
- Defense Modernization:National security initiatives in the United States, India, and South Korea are accelerating procurement of next-generation missile defense and surveillance systems, directly increasing orders for high-sensitivity cooled detectors.
- Industrial Automation:The adoption of predictive maintenance and quality control systems in manufacturing facilities drives demand for uncooled thermal cameras to monitor machinery and processes, preventing costly downtime.
- MCT Technology Maturation:Continuous improvements in Mercury Cadmium Telluride (MCT) fabrication are enhancing detector sensitivity and operational temperature ranges, expanding capabilities for military reconnaissance and scientific research applications.
Market Restraints
- Export Controls:The US International Traffic in Arms Regulations (ITAR) severely restricts the export of high-performance infrared detectors and related technology, limiting market access for manufacturers and raising compliance costs.
- Raw Material Constraints:Production of MCT detectors depends on a concentrated supply chain for high-purity tellurium, creating price volatility and supply risks for manufacturers reliant on this critical material.
- High Cooled Detector Costs:The manufacturing complexity and cryogenic cooling requirements for high-performance cooled detectors make them prohibitively expensive for most commercial applications, constraining their market to defense and high-end scientific use.
Strategic Opportunities
- Autonomous Mobility:Integration of long-wave infrared (LWIR) sensors into advanced driver-assistance systems (ADAS) and autonomous vehicles offers a significant growth vector for improving all-weather perception and pedestrian detection.
- Medical Thermography:Non-contact temperature screening and diagnostic imaging represent an expanding application for infrared detectors, particularly in public health surveillance and early-stage disease detection.
- Smart Buildings:The use of infrared sensors for occupancy detection, HVAC optimization, and security monitoring in commercial and residential buildings presents a large-volume opportunity for low-cost microbolometer arrays.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of semiconductor physicists and engineers with expertise in III-V and II-VI compound materials like MCT and InSb hinders research, development, and production scaling.
- Dual-Use Compliance Burden:Manufacturers serving both defense and commercial markets face significant administrative and legal overhead in managing separate supply chains and compliance protocols to adhere to ITAR and commercial standards.
- System Integration Complexity:Integrating sensitive infrared detectors into multi-sensor platforms for applications like autonomous vehicles requires overcoming significant challenges related to signal processing, data fusion, and environmental interference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Detector Market |
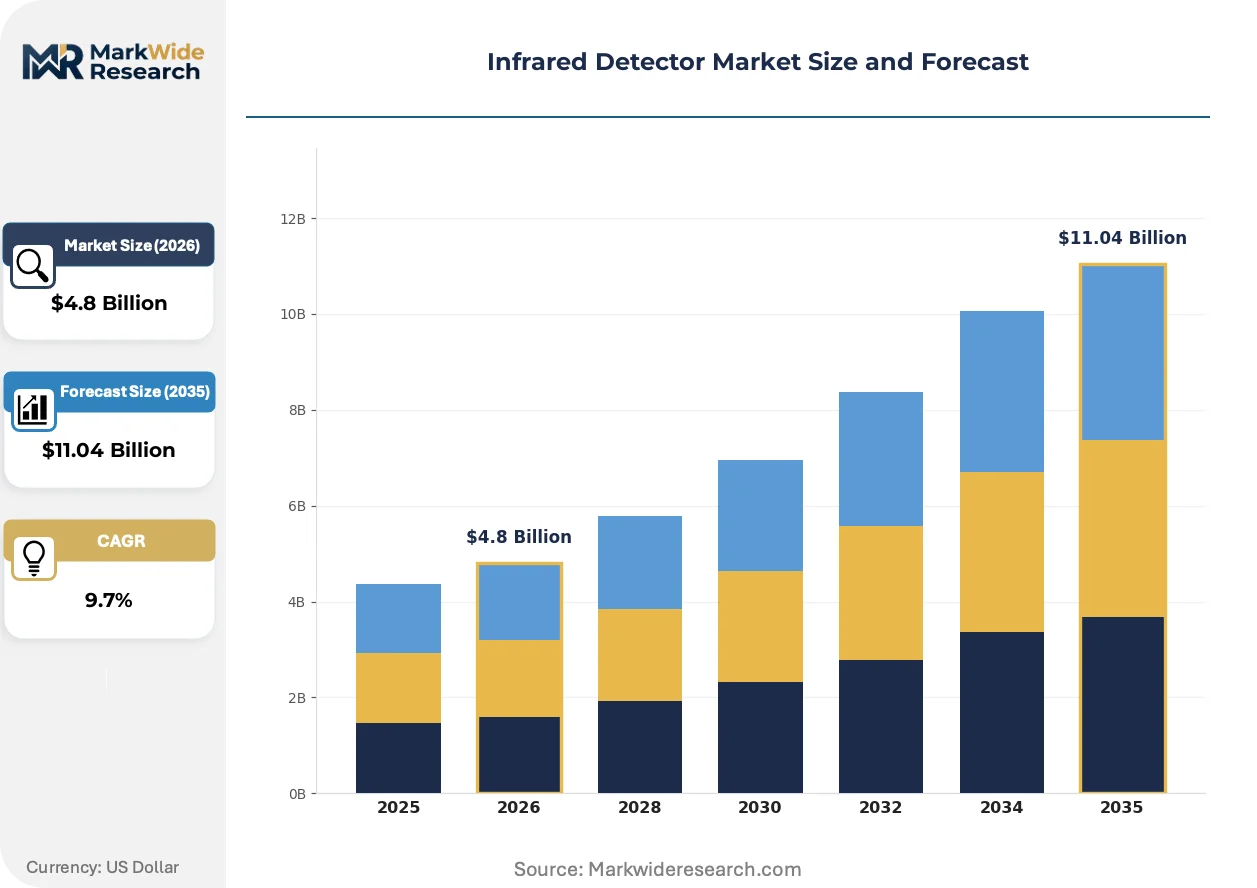
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photoconductive Detectors, Photovoltaic Detectors, Thermal Detectors, Quantum Detectors Technology: Indium Gallium Arsenide, Mercury Cadmium Telluride, Lead Sulfide, Pyroelectric, Microbolometer Application: Fire Detection, Gas Analysis, Night Vision, Missile Tracking, Environmental Monitoring End User: Defense Contractors, Consumer Electronics Firms, Scientific Research Institutes, Aerospace Developers |
| Companies Covered | Murata Manufacturing, FLIR Systems, Teledyne Technologies, Raytheon Technologies, Hamamatsu Photonics, Texas Instruments, Lynred, Honeywell, Excelitas Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Detector Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards democratizing thermal imaging, moving it from a specialized military tool to a mainstream sensing modality through advancements in uncooled technologies and integrated system design.
Wafer-Level Packaging
Wafer-level packaging (WLP) for microbolometers is a key manufacturing trend. This technique allows for the vacuum sealing of thousands of detectors simultaneously at the wafer level before they are diced into individual units. The process significantly reduces manufacturing costs and device size, enabling the production of more compact and affordable thermal cameras for consumer and industrial markets.
Regulatory Harmonization Efforts
While stringent controls like ITAR remain, efforts toward international standards are simplifying commercial trade. The adoption of ISO 17671 for non-destructive testing using thermography provides a common framework for industrial applications. This harmonization helps manufacturers design products that meet benchmarks accepted across multiple jurisdictions, such as CE marking requirements in Europe, reducing compliance fragmentation for non-military products.
Shift to Integrated Imaging Cores
System integrators and OEMs are increasingly purchasing complete thermal imaging cores rather than discrete detector components. This model provides a pre-calibrated module containing the detector, lens, and processing electronics, which simplifies product development. The trend is most pronounced in the security, drone, and test equipment segments, where rapid time-to-market is a critical competitive factor.
Infrared Detector Market Segmentation
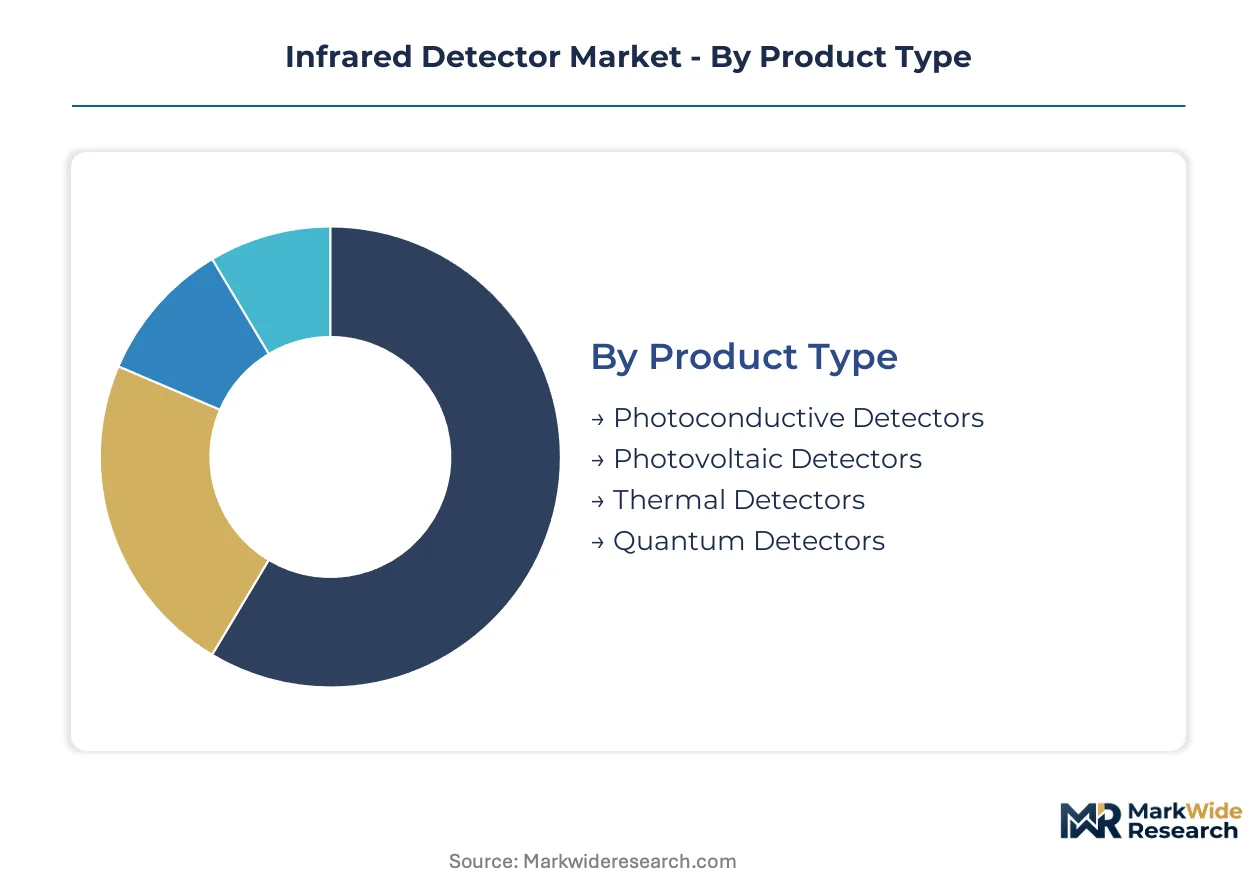
The infrared detector market exhibits distinct segmentation, driven by diverse technical requirements and end-user applications. Understanding these segments is crucial for manufacturers to align product development with specific demand profiles and regulatory frameworks across various industries.
Product Type:
Product types in infrared detectors differentiate based on their operational principles, influencing their response times and sensitivity to radiant energy. Segments with longer development cycles often involve more specialized materials and fabrication processes.
- Thermal Detectors:These devices measure changes in temperature caused by absorbed infrared radiation, converting it into an electrical signal. Demand for these detectors concentrates in industrial automation and consumer electronics, driven by the need for cost-effective thermal imaging solutions.
- Photovoltaic Detectors:Photovoltaic detectors generate a voltage when exposed to infrared radiation, offering high sensitivity and rapid response times. Military applications for missile tracking and advanced night vision systems heavily rely on these high-performance devices.
- Photoconductive Detectors:These detectors change their electrical conductivity in response to absorbed infrared photons. Environmental monitoring systems and gas analysis equipment frequently utilize photoconductive detectors for their spectral response characteristics.
- Quantum Detectors:Quantum detectors operate by directly detecting individual infrared photons, enabling extremely high sensitivity. Scientific research institutes and specialized aerospace missions employ quantum detectors for their precision in low-light conditions.
Thermal Detectors anchors the volume base while Photovoltaic Detectors gains share at the steepest rate.
Technology:
Infrared detector technologies are distinguished by the semiconductor materials used, which dictate performance characteristics like spectral range and operating temperature. Cost-efficiency considerations heavily influence technology selection for high-volume applications.
- Mercury Cadmium Telluride:MCT technology provides high detectivity and fast response across a broad infrared spectrum, often requiring cryogenic cooling for optimal performance. Defense contractors in the United States prioritize MCT for advanced missile warning systems.
- Microbolometer:Uncooled microbolometers measure temperature changes in a resistive element, offering a cost-effective solution for thermal imaging without cryogenic cooling. Consumer electronics firms and smart building developers represent significant volume opportunities for microbolometer arrays.
- Indium Gallium Arsenide:InGaAs detectors offer high sensitivity in the short-wave infrared (SWIR) region, suitable for telecommunications and industrial inspection. Industrial quality control systems benefit from InGaAs for defect detection in manufacturing processes.
- Lead Sulfide:PbS detectors are sensitive to the short to mid-wave infrared spectrum and operate at room temperature. Flame detection and gas sensing applications often incorporate Lead Sulfide detectors due to their cost-effectiveness.
- Pyroelectric:Pyroelectric detectors respond to changes in temperature, generating an electrical charge without the need for cooling. Motion sensors and basic thermal alarms frequently employ pyroelectric technology.
Mercury Cadmium Telluride technology leads in high-performance military applications, while Microbolometer technology sees the most rapid expansion in commercial markets.
Application:
Infrared detector applications span various sectors, each demanding specific performance parameters and integration capabilities. High-value applications often involve stringent regulatory compliance and specialized certifications.
- Missile Tracking:High-performance cooled infrared detectors provide critical target acquisition and guidance for defense systems. National security initiatives in the United States and South Korea drive significant procurement for missile tracking solutions.
- Night Vision:Infrared night vision systems enable visibility in low-light or complete darkness for military and security personnel. Defense modernization efforts across India and other nations accelerate demand for advanced night vision capabilities.
- Fire Detection:Infrared sensors detect the heat signatures of fires, providing early warning in industrial facilities and commercial buildings. Industrial safety regulations mandate fire detection systems, creating consistent demand for these detectors.
- Environmental Monitoring:Infrared detectors measure gas concentrations and thermal anomalies for climate science and pollution control. Scientific research institutes utilize these detectors for atmospheric analysis and ecological studies.
- Gas Analysis:Specialized infrared detectors identify and quantify specific gases based on their unique absorption spectra. Industrial process control and medical diagnostics employ gas analysis for safety and quality assurance.
Missile Tracking applications command the highest average revenue per unit, with Night Vision expanding most quickly across defense and security sectors.
End User:
End-user segments define the primary purchasers and integrators of infrared detector technologies, influencing market volume, value, and distribution channels. The regulatory environment significantly impacts market access for different end-user types.
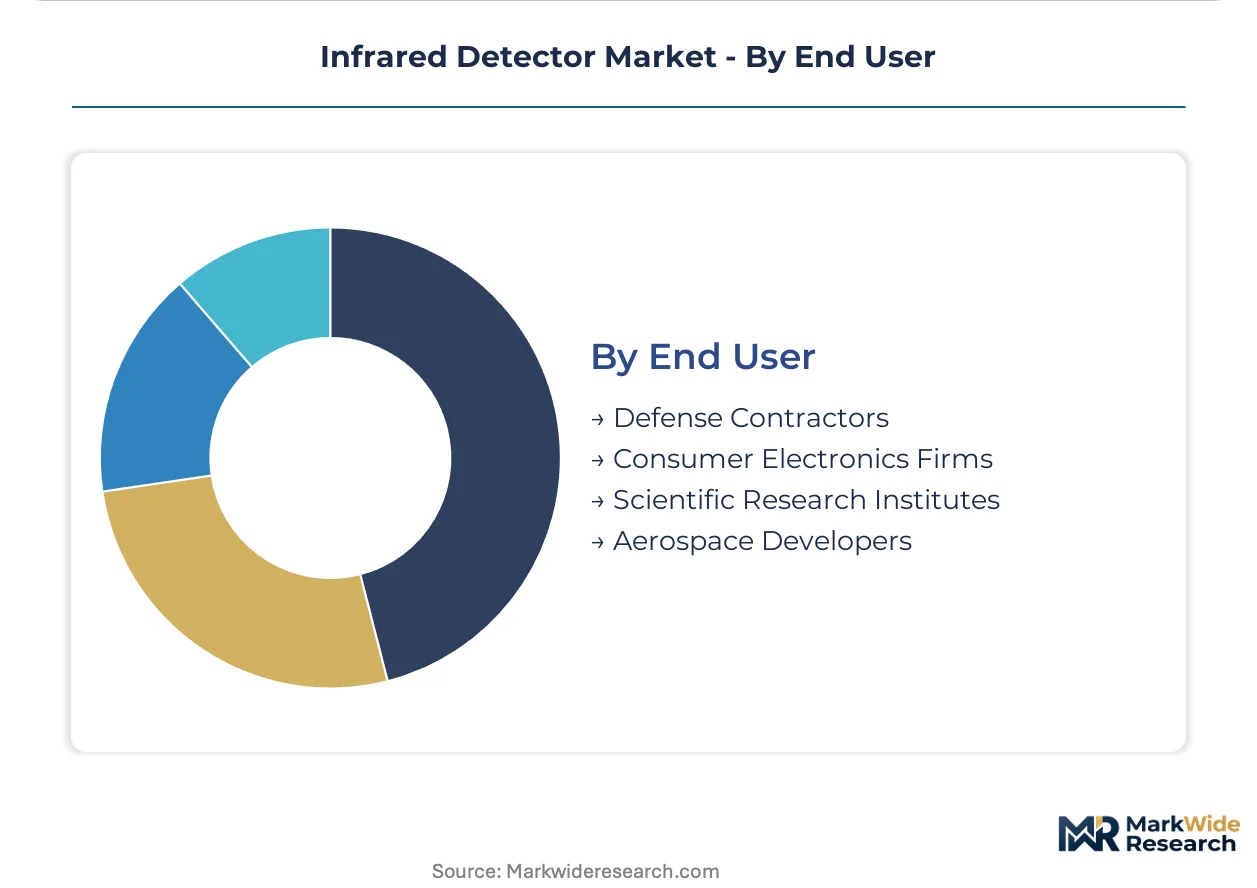
- Defense Contractors:These entities procure high-performance infrared detectors for military platforms, including missile systems, surveillance, and targeting. Teledyne Technologies and Raytheon Technologies secure large government contracts within this segment.
- Consumer Electronics Firms:Manufacturers of smart devices and automotive systems integrate compact, cost-effective infrared detectors for various functionalities. Autonomous mobility and smart building initiatives represent significant growth vectors for consumer electronics firms.
- Scientific Research Institutes:Academic and government research organizations utilize highly sensitive infrared detectors for fundamental scientific discovery and experimental applications. These institutes often drive advancements in detector sensitivity and spectral range.
- Aerospace Developers:Companies designing and manufacturing aircraft, satellites, and spacecraft require specialized infrared detectors for navigation, Earth observation, and space-based astronomy. Export controls, like US ITAR, impact the global supply of these advanced components.
Defense Contractors represent the highest-value end-user segment, while Consumer Electronics Firms offer significant volume growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global infrared detector market navigates a complex export-import balance. Demand for advanced military-grade detectors, often subject to strict controls, contrasts with the high-volume commercial sector. This duality shapes regional manufacturing capabilities and market access strategies.
United States
United States demand for infrared detectors centers on missile tracking and advanced night vision systems for defense. US International Traffic in Arms Regulations (ITAR) severely restricts export of high-performance detectors, influencing domestic production. Defense contractors in states like California and Arizona concentrate on developing next-generation imaging solutions for military platforms.
South Korea
South Korea drives demand through national security initiatives and integration into consumer electronics. The Ministry of National Defense procurement policies prioritize advanced surveillance systems for border security. Manufacturers in the Gyeonggi Province actively develop compact thermal imaging modules for automotive and smart home applications.
Germany
Germany's industrial automation sector and automotive ADAS integration significantly propel infrared detector demand. CE marking requirements ensure product conformity for commercial applications across the European Union. Research institutions in the Dresden region focus on material science advancements for uncooled microbolometers and quantum detectors.
India
India's defense modernization efforts and industrial safety regulations create substantial demand for infrared detectors. The PLI scheme incentivizes local production of electronic components, fostering domestic supply chains. Bengaluru's aerospace and defense cluster integrates advanced thermal imaging for surveillance and missile guidance systems.
Infrared Detector Market Key Industry Players
On the supply side, the industry is characterized by a dual-tier structure, serving both highly specialized defense applications and volume-driven commercial markets. High-performance military specialists focus on advanced cooled detectors, while diversified imaging solution providers target broader industrial and consumer segments. Competitive moves often involve technology licensing to expand market reach and strategic partnerships for system integration. Portfolio diversification across application areas remains a key strategy for many firms.
On the high-end military and aerospace vector, Teledyne Technologies exemplifies a diversified imaging technologies provider, leveraging its extensive portfolio for government contracts. This firm represents companies with deep expertise in specialized sensor fabrication and system integration. Raytheon Technologies anchors the advanced missile tracking segment, known for its high-performance military solutions and critical defense applications. Its positioning reflects a focus on high-value, low-volume components. FLIR Systems, a global provider, occupies a significant position in thermal imaging systems for both defense and commercial applications, extending its market reach across multiple sectors. This company represents the broader thermal imaging solution providers catering to dual-use markets.
| Leading Market Players |
|---|
| Murata Manufacturing |
| FLIR Systems |
| Teledyne Technologies |
| Raytheon Technologies |
| Hamamatsu Photonics |
| Texas Instruments |
| Lynred |
| Honeywell |
| Excelitas Technologies |
| Others |
Cost & Logistics Intelligence
Manufacturers in California and Arizona concentrate on high-performance infrared detector production, directly influencing the pricing power for advanced military-grade components. This regional capacity dictates availability and cost structures for critical defense applications, particularly missile tracking systems.
Pricing Analysis
Industrial OEM buyers anchor per-unit transactional pricing for many commercial infrared detector components. Price differentiation stems from performance specifications, such as detectivity and response time, and the volume scale of procurement. Cost compression in commercial microbolometer segments is intensifying due to advancements in wafer-level packaging. Consumer electronics firms exhibit the highest price sensitivity, while defense contractors prioritize performance over cost for critical systems.
Supply Chain Analysis
Contract manufacturing concentration in regions like the United States, South Korea, and Germany supports the global infrared detector supply chain. Production of Mercury Cadmium Telluride detectors relies on high-purity tellurium, indium, and cadmium. Raw material constraints for tellurium present a structural supply chain risk, creating price volatility. Distribution for defense applications often occurs through direct sales channels, while commercial products reach markets via specialized distributors and system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The infrared detector market presents fragmentation opportunities as autonomous mobility drives demand for specialized long-wave infrared sensors, creating new niches.
For Market Incumbents:
Pre-empt emerging uncooled technologies by accelerating research into advanced Mercury Cadmium Telluride fabrication techniques. Diversify into high-volume microbolometer production to capture commercial market share. Strategic partnerships for system integration can mitigate the threat from new entrants offering simplified solutions. Invest in commercial certifications like CE marking to expand market access beyond military contracts.
For New Entrants and Emerging Players:
Cost-effective microbolometer arrays for occupancy detection in smart buildings represent a penetrable entry point. Medical thermography for non-contact temperature screening offers another significant white-space target. Focus on integrated imaging cores with simplified application programming interfaces to accelerate OEM adoption. This go-to-market angle reduces system integration complexity for new clients.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors vertically integrated specialists with strong intellectual property in uncooled microbolometer fabrication or short-wave infrared technologies. The market offers sustained growth over the next decade due to defense modernization and commercial volume expansion. Increased regulatory harmonization for dual-use products, indicating reduced compliance burdens, serves as a key inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Wafer-Level Packaging Capacity | Reduces microbolometer manufacturing costs, enabling wider adoption in consumer electronics firms. |
| Diversify Tellurium Sourcing | Mitigates raw material constraints for Mercury Cadmium Telluride detector production, stabilizing supply. |
| Develop AI-Powered Data Fusion Algorithms | Improves system integration complexity for multi-sensor platforms in autonomous mobility applications. |
| Pursue CE Marking for Commercial Products | Streamlines market access for thermal detectors across European Union industrial automation sectors. |
| Invest in III-V Compound Material Research | Addresses specialized talent scarcity, advancing quantum detector sensitivity for scientific research institutes. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews, complemented by extensive secondary validation. Stakeholders included defense procurement officers, consumer electronics R&D leads, industrial automation engineers, and academic researchers. Secondary data sources encompassed US International Traffic in Arms Regulations guidelines, ISO standards, CE marking documentation, and national defense budgets. This combined approach supported bottom-up and top-down triangulation.
The analytical framework was calibrated against historical market performance over the projection horizon, modeling key segmentation dimensions. These included product type, technology, application, end-user, and regional regulatory environment. Compound annual growth rates were derived from historical trends and future demand projections. Key industry-specific forecast inputs included defense spending allocations and industrial automation investment trends.
Macroeconomic conditions sit as an overlay; deviation in geopolitical stability or raw material supply would shift the trajectory of the infrared detector market. Forecasts reflect documented assumptions regarding technological advancements and regulatory developments. Quarterly review of defense procurement cycles and commercial technology adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Superconducting Detector Market
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Smart Water Leak Detector Market
Detection and Regulation Devices
Global Counterfeit Money Detection Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Hydrogen Leak Detector Market
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Chemical Detection Armband Market
Detection and Regulation Devices
Digital Attenuators Market
Detection and Regulation Devices
Portable Metal Detectors Market
Detection and Regulation Devices
Indeflator Devices Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Global Noise Detection and Monitoring Market
Detection and Regulation Devices
Radiometric Detectors Market