
 Pressure Monitoring Market | 2026-2036
Pressure Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Monitoring Market Outlook
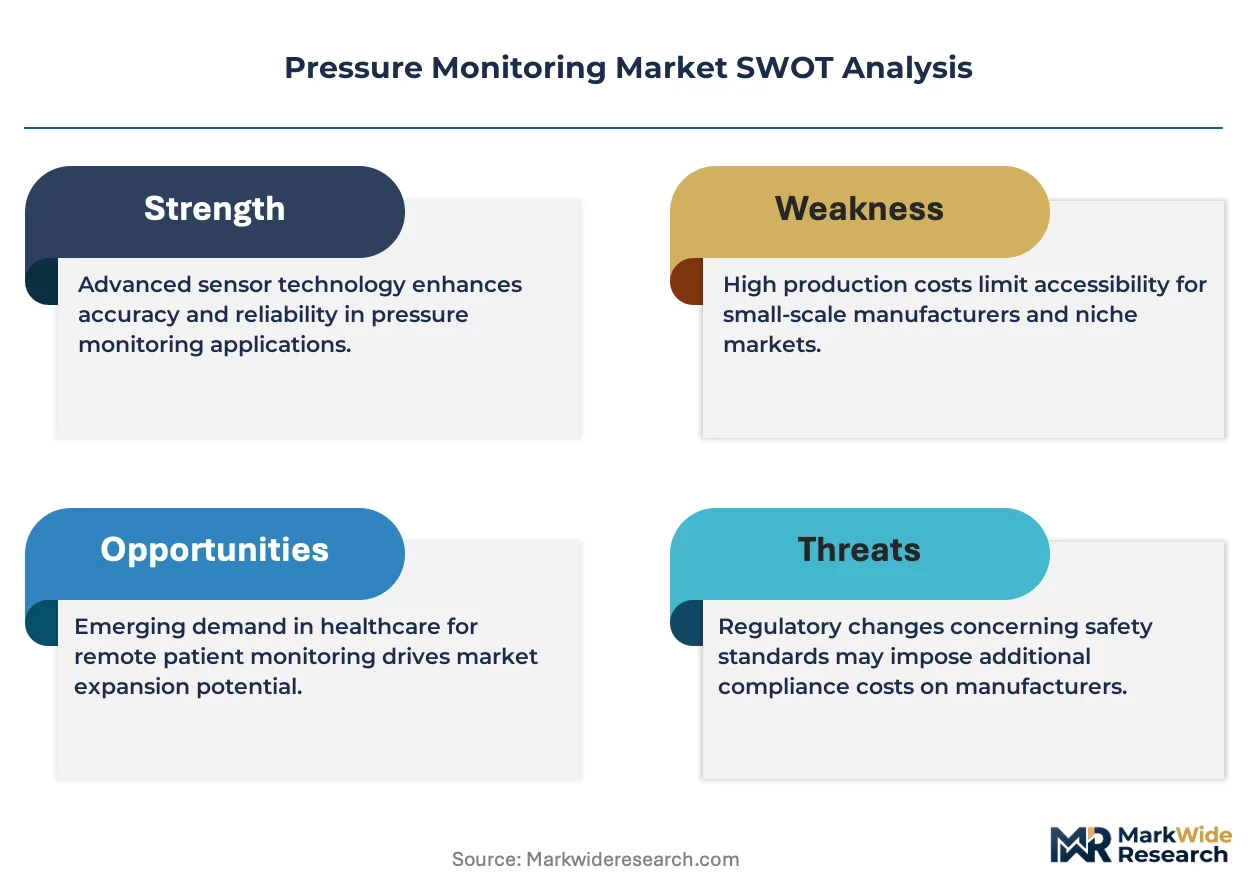
ISO 13485 certification for medical device quality management is collapsing the supplier pool as smaller manufacturers struggle to sustain compliance costs. Medtronic leverages its vertically integrated manufacturing footprint across cardiovascular and respiratory monitoring lines. GE Healthcare anchors its position through deep installed bases in hospital critical care units. Drägerwerk AG & Co. KGaA specializes in anesthesia-specific pressure monitoring configurations that dominate European operating theaters.
Pressure monitoring encompasses instruments that measure fluid or gas pressure through piezoelectric, capacitive, or strain-gauge sensing elements, typically calibrated in millimeters of mercury or pascals for clinical and industrial precision. These systems enable continuous hemodynamic assessment, respiratory mechanics tracking, and process control safety interlocks across healthcare and manufacturing environments. Pressure transducers capture the fastest-growing share as catheter-based minimally invasive procedures expand cardiology and critical care applications. Wireless monitoring technology shifts margin pools toward software-integrated platforms that reduce cabling infrastructure and enable remote patient surveillance. Embedded systems retain dominance in industrial facilities where hardwired reliability outranks connectivity flexibility.
FDA 510(k) clearance pathways and ISO 81060-2 validation standards govern clinical pressure monitoring accuracy claims in the United States, while the EU Medical Device Regulation imposes stricter post-market surveillance obligations on manufacturers selling into European hospitals. These frameworks elevate R&D barriers and compress timelines for product iterations. Stakeholders must weigh certification investments against the accelerating shift toward cloud-integrated platforms that demand concurrent cybersecurity compliance.
Market Dynamics
Wireless telemetry is collapsing the installed base of hardwired pressure monitoring systems in hospital critical care units, forcing manufacturers to restructure R&D spend toward software-integrated platforms and cloud connectivity stacks.
Growth Catalysts
- Minimally invasive catheterization:Cardiac catheter laboratories in the United States are replacing traditional invasive monitoring with disposable pressure transducers that reduce bloodstream infection risk. The FDA's streamlined 510(k) clearance for substantially equivalent devices accelerates product cycles for catheter-based sensors.
- EU Medical Device Regulation post-market surveillance:European hospitals now demand extended device traceability, creating pull-through for integrated pressure monitoring platforms with embedded data-logging capabilities. Germany's Klinikum networks are consolidating procurement around suppliers offering MDR-compliant lifecycle documentation.
- Piezoelectric MEMS fabrication:Semiconductor foundries in Taiwan and South Korea are scaling wafer-level production of silicon pressure sensors, collapsing unit costs for disposable medical-grade transducers. This process shift enables single-use economics in previously reusable-dominated applications.
Market Restraints
- ISO 13485 compliance cost concentration:Smaller contract manufacturers in Italy and Spain are exiting the supplier pool as quality management system audits and documentation burdens consume disproportionate administrative bandwidth relative to revenue scale.
- Platinum-based strain gauge dependency:Pressure transducer accuracy relies on thin-film platinum deposition, and spot market volatility for platinum group metals creates input cost instability that compresses gross margins unpredictably.
- Hardwired system stranded asset risk:Industrial process control facilities in Germany's chemical corridor face accelerated depreciation of embedded pressure monitoring infrastructure as wireless retrofit kits gain certification, creating disincentive for incremental capital investment in legacy architectures.
Strategic Opportunities
- Home-based respiratory monitoring:Sleep apnea and COPD patient populations in Japan are shifting from polysomnography labs to home-based continuous positive airway pressure systems with integrated pressure feedback loops. METI's reimbursement code expansion for remote patient monitoring creates a regulatory tailwind.
- AI-enabled predictive maintenance:Industrial pressure monitoring in Saudi Arabia's desalination plants is converging with machine learning analytics to predict membrane fouling before pressure differentials trigger safety interlocks. This application remains underpenetrated relative to predictive maintenance adoption in rotating equipment.
- Direct-to-hospital distribution:Group purchasing organization consolidation in the United States is creating white space for manufacturers to bypass distributor markups through direct contracting with integrated delivery networks, capturing margin previously allocated to intermediaries.
Industry Challenges
- Cybersecurity engineering talent scarcity:Cloud-integrated pressure monitoring platforms require embedded systems engineers with both FDA software validation and IEC 62443 industrial cybersecurity expertise, a skill intersection concentrated at a handful of medical device hubs.
- Legacy DCS integration friction:Honeywell and Yokogawa distributed control systems in petrochemical facilities use proprietary pressure signal protocols, forcing sensor manufacturers to maintain multiple analog output variants and complicating product line rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Monitoring Market |
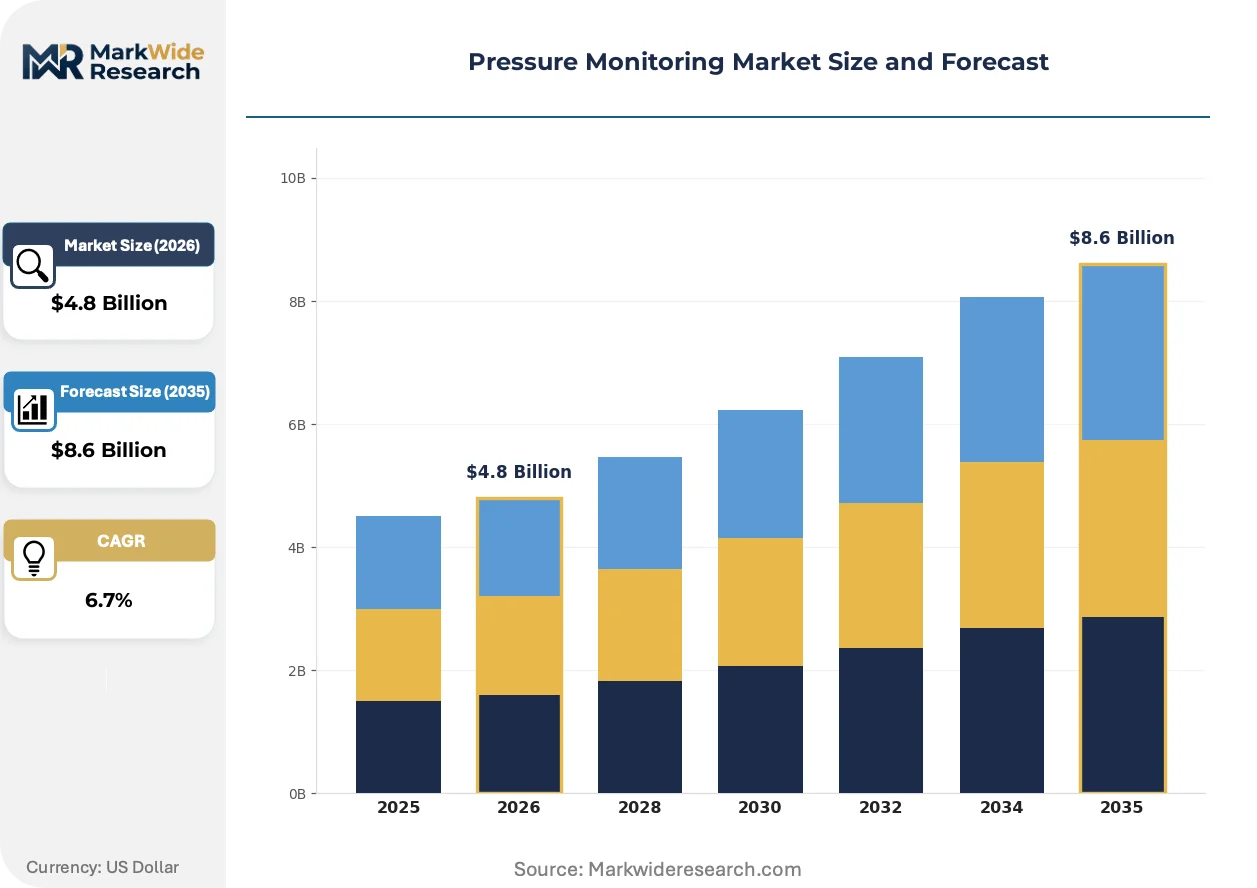
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Manometers, Analog Manometers, Pressure Transducers, Pressure Sensors End User: Hospitals, Clinics, Home Healthcare, Industrial Facilities Technology: Wireless Monitoring, Wired Monitoring, Embedded Systems, Cloud-based Solutions Application: Cardiology, Anesthesia, Critical Care, Research Laboratories |
| Companies Covered | Koninklijke Philips N.V., Medtronic, GE Healthcare, Drägerwerk AG & Co. KGaA, Omron Corporation, A&D Company, Nihon Kohden Corporation, Hill-Rom Holdings, Inc., Masimo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Monitoring Market Strategic Shifts
Digital pressure sensing architectures are fragmenting the competitive landscape between semiconductor-native suppliers and traditional electromechanical incumbents, with implications for value capture across hardware, firmware, and analytics layers.
Capacitive MEMS pressure sensors are bifurcating the market between high-precision laboratory calibration instruments and mass-produced disposable medical devices. Cardiac catheterization labs in Cleveland Clinic and Mayo Clinic networks are adopting wafer-scale capacitive elements for hemodynamic monitoring, collapsing the cost curve for single-use pressure transducers while compressing margins for reusable strain-gauge systems that dominated the prior decade.
REACH restrictions on perfluorinated compounds are forcing pressure sensor manufacturers to reformulate gel fill materials in invasive blood pressure transducers. The European Chemicals Agency's 2023 substance of very high concern designation for certain fluoropolymers is accelerating migration to silicone-based alternatives, with German and French hospital procurement offices now requiring material disclosure documentation that was previously optional.
Hospital supply chain directors are unbundling pressure monitoring hardware from long-term service contracts that bundled calibration, replacement, and software updates. This pattern is most visible in United States academic medical centers, where Vanderbilt University Medical Center and University of California Health systems have moved to spot purchasing of pressure transducers paired with third-party ISO 17025 calibration services, stripping OEMs of captive aftermarket revenue streams.
Pressure Monitoring Market Segmentation
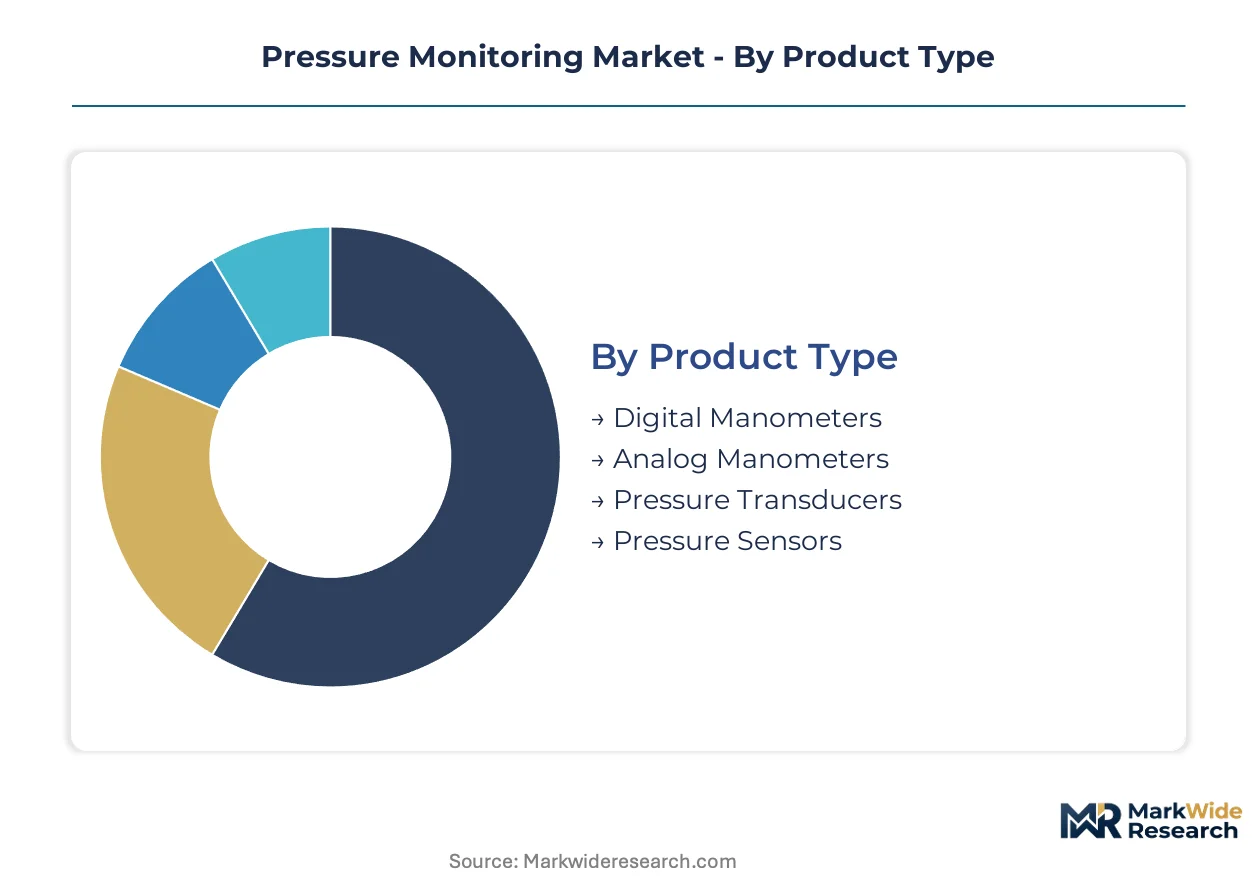
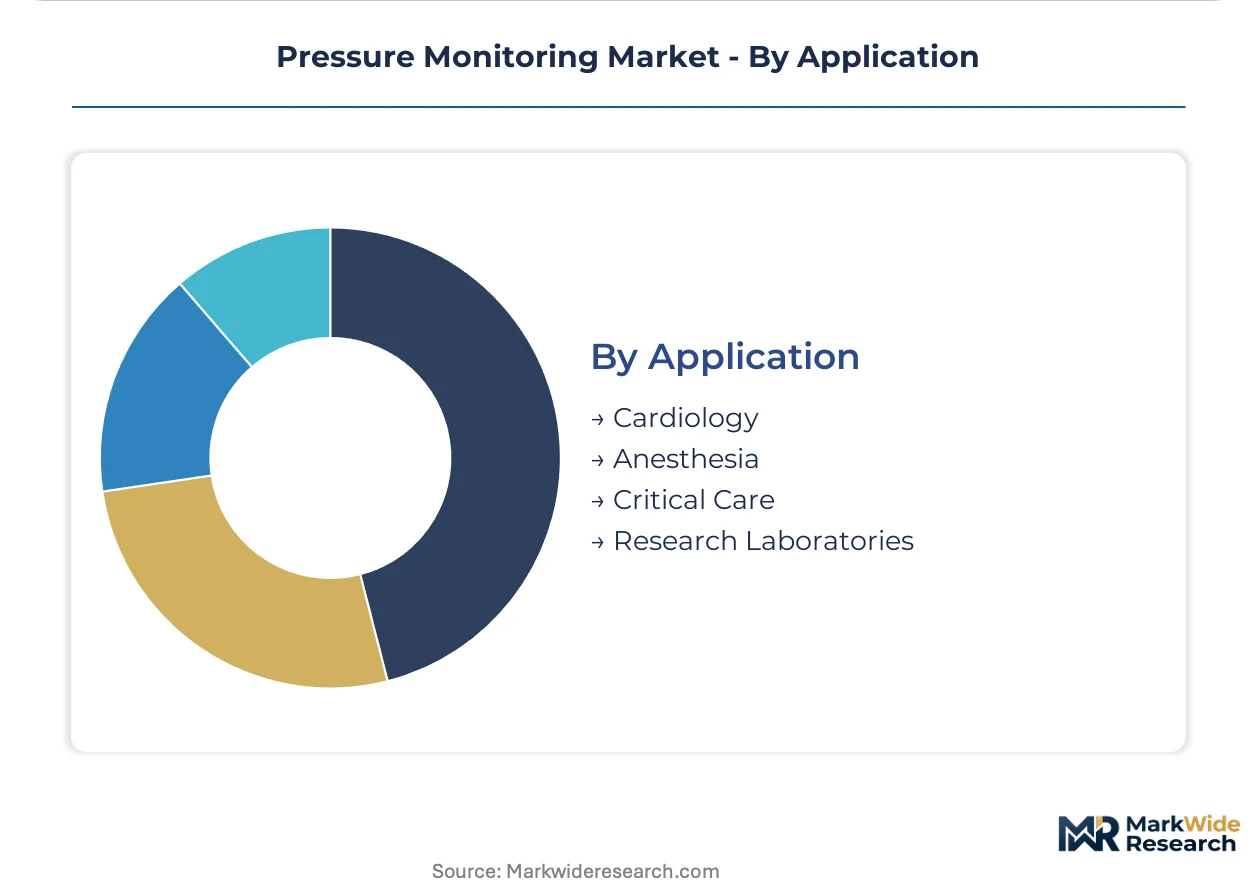
Pressure monitoring markets fragment across hardware configurations, care settings, connectivity architectures, and clinical workflows. Each segmentation axis carries distinct regulatory burdens, margin structures, and competitive dynamics that determine supplier positioning.
Product Type:
FDA 510(k) clearance requirements and ISO 81060-2 validation standards create sharp regulatory differentiation across product categories, with invasive blood pressure devices facing stricter accuracy thresholds than industrial gauges.
- Pressure Transducers:Piezoelectric and capacitive sensing elements convert fluid pressure into electrical signals with millimeter-of-mercury precision. Cardiac catheterization labs in Cleveland Clinic and Mayo Clinic networks are adopting disposable transducers for hemodynamic monitoring during percutaneous coronary interventions, driven by infection control protocols and single-use economics.
- Digital Manometers:Solid-state pressure measurement instruments with LCD readouts and data-logging capabilities serve both clinical calibration and industrial process control. United States academic medical centers including Vanderbilt University Medical Center are unbundling these devices from long-term service contracts, shifting procurement toward spot purchasing paired with third-party ISO 17025 calibration services.
- Analog Manometers:Bourdon tube or diaphragm-based mechanical gauges retain dominance in resource-constrained settings where battery dependency creates operational risk.
- Pressure Sensors:MEMS-fabricated silicon elements enable miniaturization for wearable and implantable applications, with Taiwan and South Korean foundries scaling wafer-level production.
Pressure transducers handle the majority of throughput in clinical settings; pressure sensors are expanding most quickly as semiconductor fabrication costs collapse.
End User:
Customer concentration patterns vary sharply by procurement sophistication, with consolidated health systems demanding integrated platforms while fragmented industrial buyers prioritize unit economics.
- Hospitals:Integrated delivery networks in the United States leverage bulk procurement power to extract pricing concessions on wireless monitoring infrastructure. Germany's Klinikum networks are consolidating supplier relationships around vendors offering MDR-compliant lifecycle documentation and embedded data-logging capabilities.
- Home Healthcare:Sleep apnea and COPD patient populations in Japan are migrating from polysomnography labs to continuous positive airway pressure systems with integrated pressure feedback loops, supported by METI reimbursement code expansion for remote patient monitoring.
- Clinics:Outpatient cardiology and respiratory practices favor portable digital manometers for point-of-care diagnostics where capital budgets constrain acquisition of hospital-grade systems.
- Industrial Facilities:Petrochemical plants in Germany's chemical corridor face stranded asset risk on hardwired pressure monitoring infrastructure as wireless retrofit kits gain IEC 62443 cybersecurity certification.
Hospitals command the largest revenue pool; home healthcare is climbing the fastest as reimbursement shifts toward ambulatory settings.
Technology:
Connectivity architecture determines cybersecurity compliance burden and recurring revenue potential, with cloud-integrated platforms requiring concurrent FDA software validation and IEC 62443 expertise.
- Wireless Monitoring:Bluetooth Low Energy and proprietary radio protocols eliminate cabling infrastructure while enabling remote patient surveillance. Cardiology departments are replacing hardwired systems with telemetry platforms that stream hemodynamic data to centralized monitoring stations, restructuring manufacturer R&D spend toward software-integrated stacks.
- Cloud-based Solutions:Data aggregation platforms with predictive analytics capabilities serve industrial predictive maintenance applications, including membrane fouling prediction in Saudi Arabian desalination plants.
- Wired Monitoring:Hardwired architectures retain preference in anesthesia and critical care where latency tolerance is minimal and electromagnetic interference resilience is paramount.
- Embedded Systems:Standalone processing units with local data storage dominate industrial process control where network connectivity introduces unacceptable safety system dependencies.
Wireless monitoring captures the steepest expansion trajectory; embedded systems retain the largest installed base in industrial applications.
Application:
Clinical workflow integration requirements and reimbursement coding determine technology adoption patterns across specialty departments.
- Cardiology:Hemodynamic monitoring during catheter-based procedures drives demand for high-fidelity pressure transducers with disposable economics. The FDA's streamlined 510(k) pathway for substantially equivalent devices accelerates product cycles for sensor manufacturers targeting cardiac catheterization labs.
- Anesthesia:Airway pressure monitoring and invasive blood pressure tracking require synchronized multi-parameter integration, with Drägerwerk configurations dominating European operating theaters through deep anesthesia workstation compatibility.
- Critical Care:Continuous multi-site pressure surveillance in intensive care units is shifting from bedside monitors to centralized telemetry architectures with distributed sensor networks.
- Research Laboratories:High-precision calibration requirements for experimental protocols sustain demand for laboratory-grade capacitive sensors with NIST-traceable certification.
Cardiology generates the dominant revenue concentration; anesthesia maintains the most stable replacement cycle demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification reforms and EU Medical Device Regulation post-market surveillance obligations are redrawing procurement patterns across hospital systems and industrial facilities. Reimbursement code expansions in Japan and health system consolidation in the United States concentrate demand around certified suppliers with integrated data-logging capabilities.
United States
Integrated delivery networks in Nashville and Cleveland leverage bulk procurement power to extract pricing concessions on wireless monitoring infrastructure. FDA 510(k) clearance pathways accelerate product cycles for catheter-based pressure transducers targeting cardiac catheterization labs. Academic medical centers in California and Tennessee are unbundling hardware from long-term service contracts, shifting toward spot purchasing paired with third-party ISO 17025 calibration services.
Germany
Klinikum networks consolidate supplier relationships around vendors offering MDR-compliant lifecycle documentation and embedded data-logging capabilities. The EU Medical Device Regulation imposes stricter post-market surveillance obligations, elevating documentation burdens for manufacturers. Industrial process control facilities in North Rhine-Westphalia's chemical corridor face stranded asset risk on hardwired pressure monitoring infrastructure as wireless retrofit kits gain IEC 62443 cybersecurity certification.
Japan
Sleep apnea and COPD patient populations are migrating from polysomnography labs to home-based continuous positive airway pressure systems with integrated pressure feedback loops. METI's reimbursement code expansion for remote patient monitoring creates regulatory tailwind for cloud-integrated platforms. Semiconductor foundries in Kyushu and Kansai regions are scaling wafer-level production of silicon pressure sensors, collapsing unit costs for disposable medical-grade transducers.
Saudi Arabia
Desalination plants in the Eastern Province are converging pressure monitoring with machine learning analytics to predict membrane fouling before pressure differentials trigger safety interlocks. The country's national water regulator is tightening process control safety requirements for critical infrastructure. Industrial facilities in Riyadh are retrofitting embedded pressure monitoring systems with wireless telemetry to reduce cabling infrastructure and enable centralized surveillance.
Taiwan
Semiconductor foundries in Hsinchu Science Park are scaling wafer-level production of piezoelectric MEMS pressure sensors, collapsing unit costs for disposable medical-grade transducers. The country's industrial development authority is channeling capital toward precision sensor fabrication to capture medical device supply chain migration from mainland China. Manufacturing clusters in Taichung and Tainan are specializing in capacitive MEMS elements for cardiac catheterization applications.
Pressure Monitoring Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with vertically integrated manufacturing footprints across cardiovascular and respiratory monitoring lines. Market structure concentrates around three to five global suppliers with deep installed bases in hospital critical care units and anesthesia workstations. Strategic archetypes include semiconductor-native sensor fabricators exploiting wafer-scale cost curves, diversified health technology conglomerates leveraging cross-selling into integrated delivery networks, and regional specialists dominating anesthesia-specific configurations in European operating theaters. Dominant competitive moves center on backward integration into MEMS fabrication capacity and direct-to-hospital distribution contracts that bypass group purchasing organization markups.
Among diversified health technology conglomerates, Koninklijke Philips N.V., Medtronic, and GE Healthcare occupy positions anchored by deep installed bases in hospital critical care units. Philips represents the integrated platform archetype with telemetry infrastructure spanning cardiology and critical care workflows. Medtronic exemplifies vertical control over cardiovascular and respiratory monitoring supply chains. GE Healthcare sits within the imaging-to-monitoring convergence tier, leveraging diagnostic equipment relationships for pressure monitoring placement. Drägerwerk AG & Co. KGaA and Omron Corporation represent specialization vectors—Drägerwerk in anesthesia workstation integration and Omron in consumer-facing blood pressure monitoring with clinical-grade sensor technology.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Medtronic |
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Omron Corporation |
| A&D Company |
| Nihon Kohden Corporation |
| Hill-Rom Holdings, Inc. |
| Masimo Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Taiwanese MEMS foundries and medical device OEMs lock in wafer capacity and price visibility for disposable pressure transducers, insulating buyers from platinum group metal spot volatility while exposing non-contracted purchasers to margin compression.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-compliant systems and uncertified industrial gauges. Three-tier pricing structure across FDA-cleared, CE-marked, and non-medical grades separates hospital procurement budgets from factory-floor instrumentation. Cost compression in the mid-tier is intensifying because semiconductor foundries are collapsing unit economics for capacitive MEMS elements. Academic medical centers exhibit the sharpest price sensitivity, while anesthesia workstation integrators retain the least due to compatibility lock-in.
Supply Chain Analysis
Platinum thin-film deposition capacity in Germany and Japan underwrites transducer accuracy specifications for hemodynamic monitoring. Taiwan and South Korea feed wafer-scale MEMS fabrication, while the United States anchors strain-gauge assembly for critical care applications. Supply chains draw from platinum group metals, silicon wafers, and biocompatible gel fill materials. Single-source vulnerability concentrates in Taiwanese foundry capacity for disposable catheter sensors. Distribution runs through group purchasing organizations in the United States and direct hospital contracts in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intersection of FDA software validation and IEC 62443 cybersecurity expertise has become the binding constraint for cloud-integrated platform development, with fewer than a dozen medical device hubs globally producing engineers fluent in both domains.
For Market Incumbents: Consolidate backward integration into MEMS fabrication capacity in Taiwan or South Korea to capture collapsing unit costs for disposable transducers. Deepen anesthesia workstation compatibility layers to defend against semiconductor-native entrants. Certification investment in MDR-compliant lifecycle documentation secures position within Germany's consolidating Klinikum networks. For New Entrants and Emerging Players: Anchor in home-based respiratory monitoring for Japan's sleep apnea and COPD populations, where METI reimbursement expansion outpaces supply from established hospital-focused vendors. Direct-to-hospital distribution contracts with United States integrated delivery networks bypass GPO markups. White space concentrates in AI-enabled predictive maintenance for industrial desalination and chemical process applications. For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor-native sensor fabricators with existing FDA 510(k) clearances and wafer-scale cost curves, positioned for catheter-based procedure expansion. Long-term viability hinges on software-integrated platform revenue recurring beyond hardware replacement cycles. Watch for FDA premarket notification reforms accelerating product cycles as an inflection signal for M&A timing.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Backward Integration | Taiwanese foundry partnerships secure wafer capacity for disposable transducer economics. |
| MDR-Compliant Lifecycle Documentation | German hospital networks now mandate embedded data-logging for supplier qualification. |
| Cloud-Integrated Platform Development | FDA software validation and IEC 62443 expertise convergence enables remote patient surveillance. |
| Direct-to-Hospital Distribution Contracts | United States integrated delivery networks bypass GPO markups through direct manufacturer agreements. |
| AI-Enabled Predictive Maintenance Software | Saudi desalination plants adopt membrane fouling prediction before pressure differential triggers. |
Study Parameters
A standing panel of cardiac catheterization lab directors, hospital biomedical engineers, GPO contracts managers, and semiconductor foundry operations executives provided ongoing calibration across primary interviews and secondary validation. Sources included FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and Taiwan's Industrial Development Bureau trade statistics. Bottom-up unit economics for pressure transducer fabrication were triangulated against top-down hospital capital expenditure tracking.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions spanned product type, end user, connectivity architecture, and clinical workflow integration. CAGRs were derived from modeled adoption curves for wireless telemetry platforms and semiconductor cost-down trajectories. Industry-specific inputs included catheter-based procedure volumes, MDR compliance cost burdens, and platinum group metal price series.
Material uncertainties — FDA premarket notification reforms, REACH substance restrictions on fluoropolymers, and Taiwan semiconductor capacity allocation — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement code stability and health system consolidation velocity. Practitioners should keep alternative scenarios live as regulatory frameworks for cybersecurity validation and post-market surveillance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
Middle East and Africa Lidar Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
Europe MEMS and Sensors Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
MEMS Energy Harvesting Devices Market
Sensors and Controls
Temperature Controller Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Weather Radar Market