
 Global Level Sensors Market | 2026-2036
Global Level Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Level Sensors Market Outlook
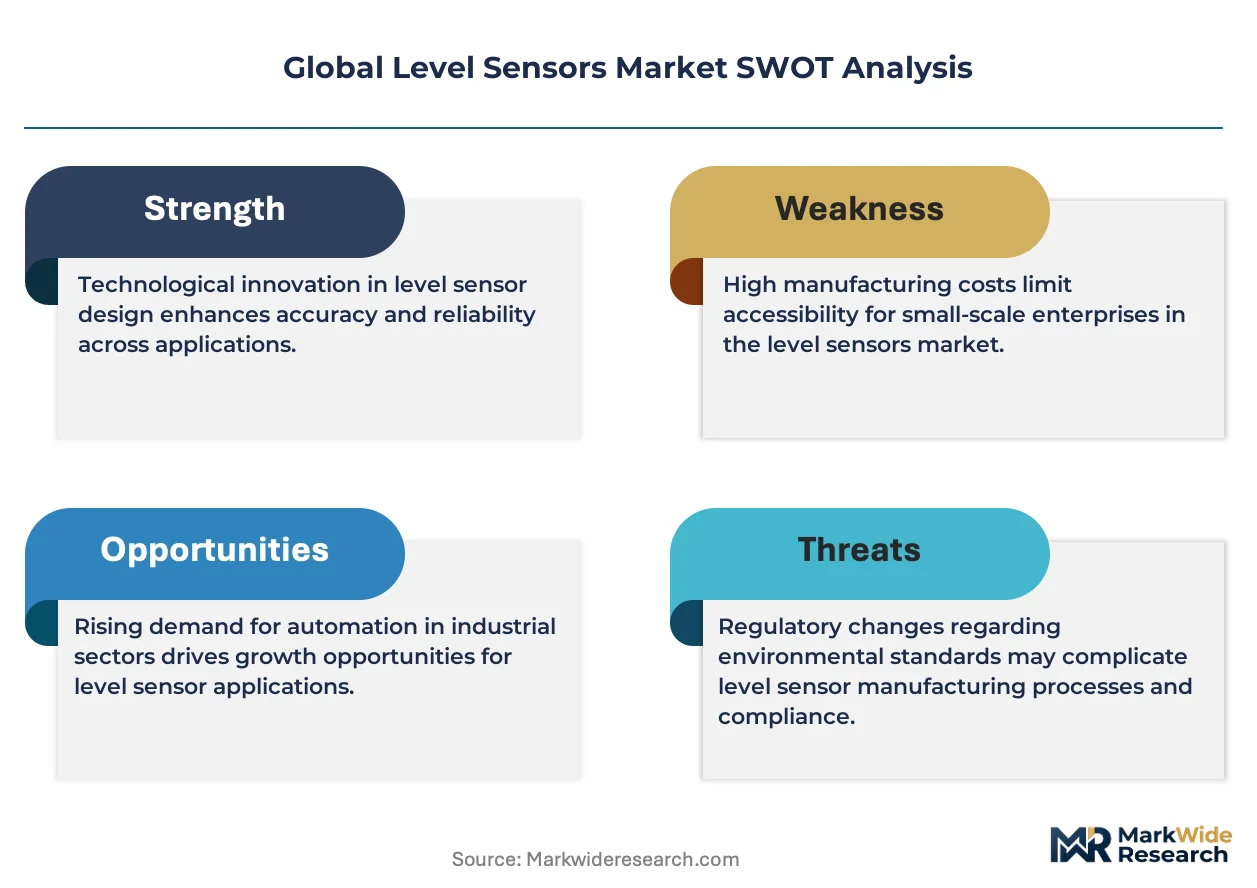
Polymer composites are repositioning housing economics for submersible level sensors, cutting unit weight and corrosion susceptibility against traditional stainless-steel enclosures. Emerson Electric Co. leverages captive polymer molding operations to defend margin pools in offshore oil platforms. Endress+Hauser AG anchors European market presence through calibration laboratories in Switzerland and Germany. Vega GmbH specializes in radar-level instrumentation for bulk solids applications in cement and mining.
Level sensors detect material height or volume within vessels, tanks, and silos using electromagnetic, acoustic, or mechanical principles, typically operating at pressure ratings from vacuum to 400 bar and temperature spans between minus 40°C and 450°C depending on process fluid compatibility. Their primary purpose is enabling automated inventory management, overflow prevention, and pump control across continuous and batch manufacturing. Radar sensors command premium positioning in hydrocarbon storage where foam, vapor, and condensation degrade ultrasonic accuracy. Smart sensors with IO-Link and HART protocols represent the fastest-expanding technology segment as facilities pursue predictive maintenance integration. Analog sensors retain substantial installed-base presence in legacy water treatment infrastructure where digital retrofit capital remains constrained.
The EPA enforces Spill Prevention, Control, and Countermeasure rules that mandate redundant level monitoring aboveground storage tanks exceeding threshold volumes, directly stimulating replacement demand for mechanical float systems. EMA and EU F-Gas Regulation classifications restrict certain sealed sensor technologies in refrigeration and chemical processing, redirecting procurement toward hermetically welded alternatives. OSHA process safety management standards for highly hazardous chemicals further tighten inspection intervals and calibration documentation requirements. Stakeholders must evaluate sensor architecture choices against evolving cybersecurity frameworks for operational technology networks as IT-OT convergence accelerates attack surface exposure.
Market Dynamics
Smart sensor protocols are compressing replacement cycles across process industries as facilities prioritize predictive maintenance integration over legacy analog installations.
Growth Catalysts
- EPA SPCC mandates:Redundant level monitoring requirements for aboveground storage tanks above threshold volumes are forcing mechanical float replacements across US chemical terminals and petroleum distribution facilities.
- EU F-Gas Regulation:Restrictions on sealed sensor technologies in refrigeration and chemical processing are redirecting procurement toward hermetically welded ultrasonic and radar alternatives.
- Radar sensor penetration:Hydrocarbon storage operators facing foam, vapor, and condensation challenges are accelerating adoption of frequency-modulated continuous wave technology for custody transfer accuracy.
Market Restraints
- Stainless steel input volatility:Nickel and molybdenum price swings directly compress margin pools for sensor housing manufacturers dependent on 316L enclosures.
- Calibration infrastructure concentration:Endress+Hauser and Vega maintain captive laboratory networks in Switzerland and Germany, creating regional service access disparities.
- Ultrasonic accuracy ceilings:Temperature gradients and vapor density variations in high-pressure vessels limit acoustic technology penetration above 100 bar operating conditions.
Strategic Opportunities
- India refinery modernization:State-owned oil marketing companies are tendering tank farm automation contracts requiring IO-Link compatible level instrumentation for centralized SCADA integration.
- Polymer composite substitution:Offshore platform operators are specifying glass-reinforced nylon housings to reduce topside weight and saltwater corrosion exposure.
- CSRD disclosure alignment:EU-based process manufacturers must install continuous level monitoring to support Scope 3 emissions tracking and automated inventory reconciliation.
Industry Challenges
- OT cybersecurity skill scarcity:IT-OT convergence exposes level sensor networks to ransomware targeting Modbus and HART protocol vulnerabilities, yet facilities lack embedded security engineering capacity.
- Legacy analog retrofit complexity:Water treatment infrastructure with 4-20mA installations faces capital constraints blocking digital migration despite predictive maintenance incentives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Level Sensors Market |
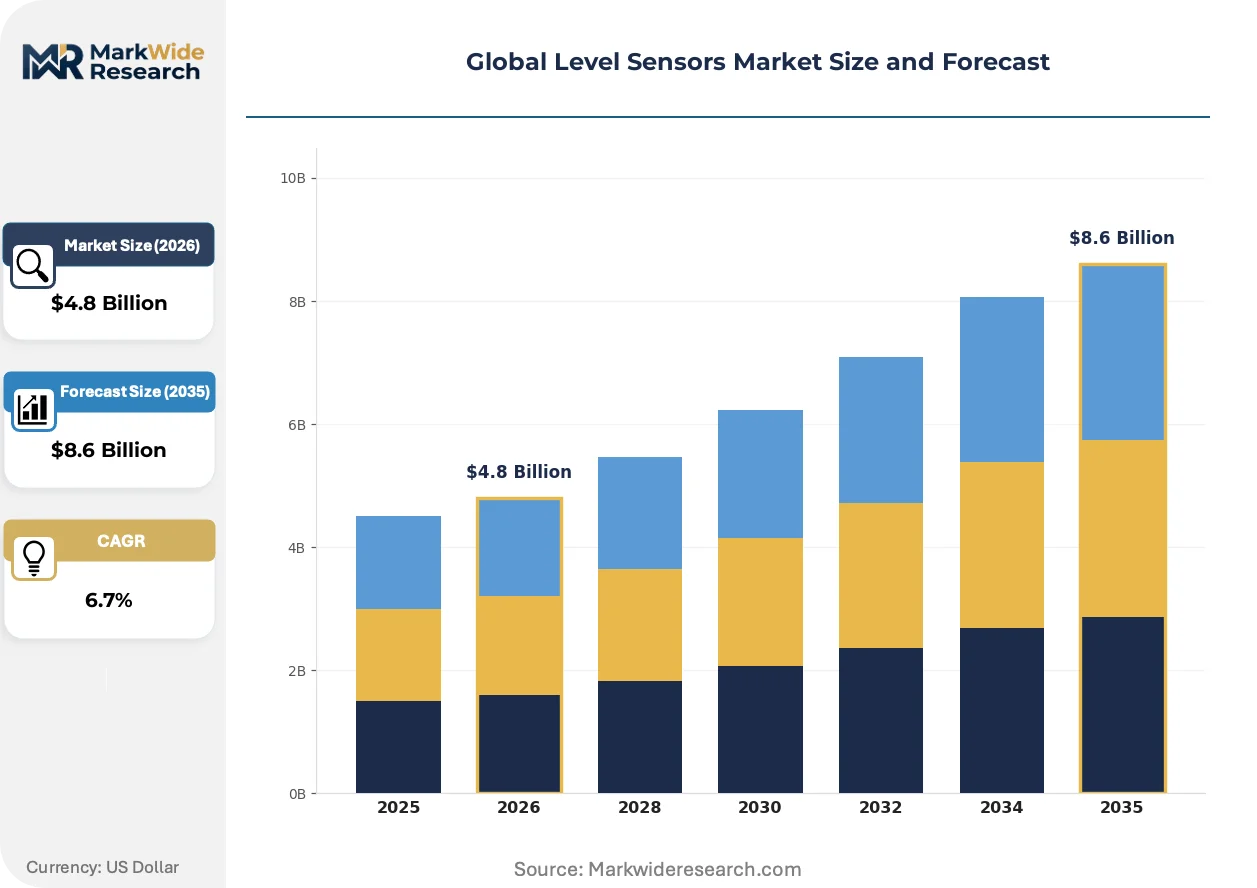
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive Sensors, Ultrasonic Sensors, Magnetic Float Sensors, Radar Sensors Technology: Digital Level Sensors, Analog Level Sensors, Smart Sensors, Non-contact Level Sensors End User: Oil & Gas, Water & Wastewater, Chemicals, Food & Beverage Installation: Surface Mount, Submersible, Remote, Integrated |
| Companies Covered | Emerson Electric Co., ABB Ltd., Siemens AG, AMETEK Inc., Honeywell International Inc., Endress+Hauser AG, Pepperl+Fuchs GmbH, Vega GmbH, Magnetrol International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Level Sensors Market Strategic Shifts
Sensor intelligence is migrating toward edge computing architectures, compressing latency for real-time process control while complicating vendor software maintenance obligations.
Silicon carbide MEMS pressure elements are expanding into submersible level transmitters for geothermal and heavy oil extraction. Baker Hughes and Schlumberger procurement specifications now prioritize ceramic sensing diaphragms for hydrogen sulfide resistance. This material transition is expanding into standard industrial applications as unit costs fall below traditional piezoresistive assemblies.
EMA and EU F-Gas Regulation classifications are tightening refrigerant leak detection mandates across cold chain logistics. Sensor manufacturers must certify hermetic sealing to IEC 60079-11 intrinsic safety standards for ammonia and CO2 systems. German chemical processors are accelerating procurement of welded titanium diaphragm sensors to preempt 2025 inspection interval compressions.
Aftermarket service unbundling is fragmenting traditional vendor relationships. End-users in Texas and Alberta petrochemical corridors are sourcing calibration and repair from third-party metrology laboratories rather than manufacturer service networks. This procurement pattern shift is most visible among mid-size independent refiners seeking to reduce OEM dependency.
Global Level Sensors Market Segmentation
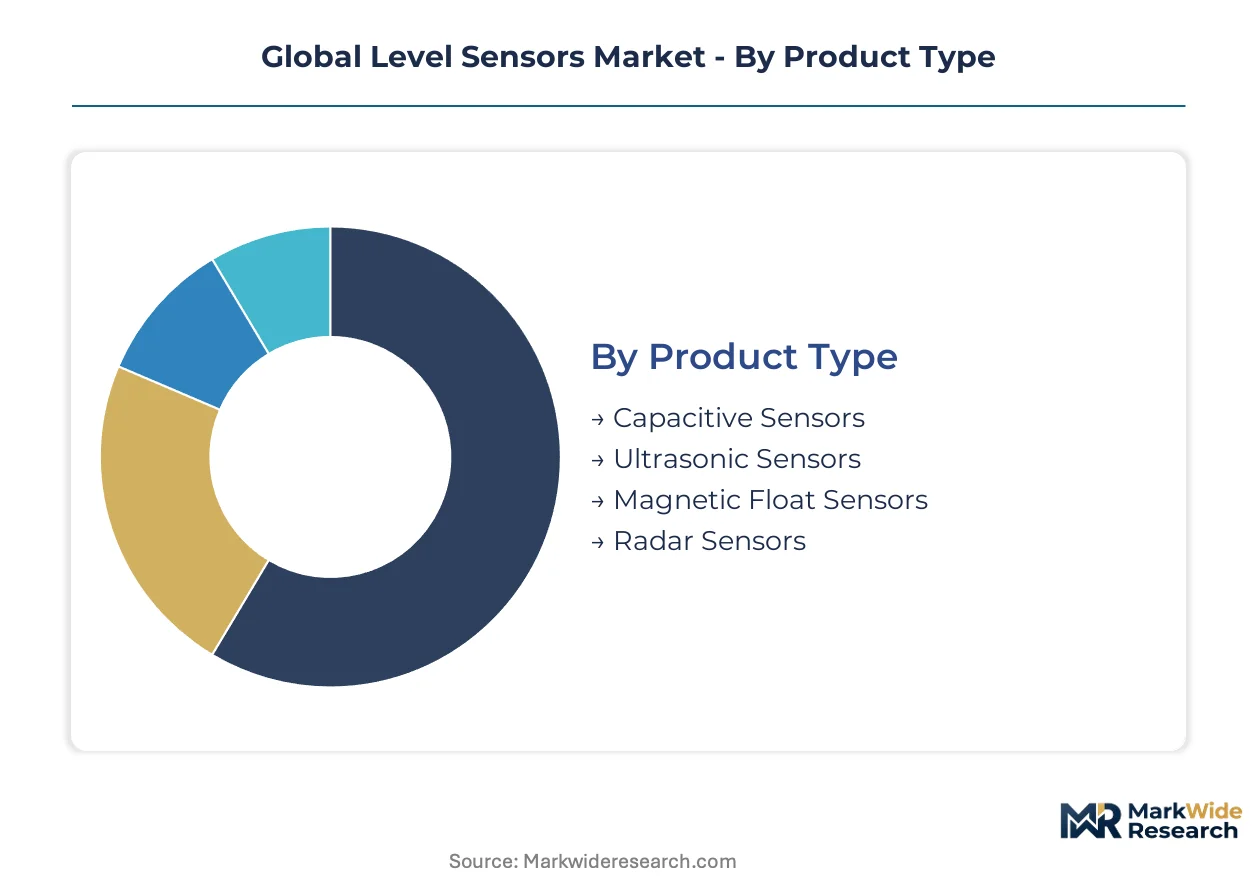
Level sensor procurement patterns diverge sharply across process industries, with upgrade cycles compressing fastest where predictive maintenance ROI is demonstrable. Technology choices cluster around existing control architecture rather than greenfield specification, creating path-dependent demand concentration.
Product Type:
Replacement cycles for mechanical float systems are accelerating under EPA SPCC mandates, while radar and ultrasonic alternatives capture premium positioning in hazardous vapor environments.
- Capacitive Sensors:These devices measure liquid level through dielectric constant variations between probe and vessel wall, suited for aggressive chemicals and slurries. German chemical processors specify capacitive probes with PTFE coatings for sulfuric acid storage under EU F-Gas hermetic sealing requirements.
- Ultrasonic Sensors:Acoustic time-of-flight measurement operates without media contact, reducing corrosion exposure in wastewater sumps. Texas petrochemical terminals deploy redundant ultrasonic arrays for aboveground tank leak prevention under tightened inspection intervals.
- Magnetic Float Sensors:Reed switch actuation via internal magnet provides simple ON/OFF control for pump stations.
- Radar Sensors:Frequency-modulated continuous wave technology penetrates foam and vapor for custody transfer accuracy in hydrocarbon storage.
Radar sensors sit at the top of the volume ranking, with ultrasonic alternatives climbing the fastest.
Technology:
Digital migration trajectories separate facilities with SCADA integration budgets from those maintaining 4-20mA infrastructure.
- Digital Level Sensors:Binary output interfaces enable direct PLC integration without analog conversion cards. Indian state-owned refineries specify digital sensors with Modbus RTU for centralized tank farm monitoring during modernization tenders.
- Smart Sensors:Onboard diagnostics and IO-Link protocols support predictive maintenance algorithms. Food & beverage processors in Switzerland deploy smart level transmitters to automate CIP cycle verification and reduce unplanned downtime.
- Analog Level Sensors:4-20mA output dominates legacy water treatment infrastructure.
- Non-contact Level Sensors:Radar and laser alternatives eliminate mechanical wear in abrasive bulk solids.
Analog installations retain the largest installed base, though smart sensors are gaining share fastest among greenfield chemical projects.
End User:
Regulatory exposure intensity determines specification tier, with hydrocarbon storage and chemical processing facing the most stringent redundant monitoring mandates.
- Oil & Gas:Custody transfer accuracy requirements drive radar specification for crude and refined product tanks. Offshore platforms in the North Sea specify polymer-housed submersible sensors to reduce topside weight against traditional stainless-steel enclosures.
- Chemicals:Aggressive media compatibility and hermetic sealing dominate procurement criteria. Process Safety Management standards from OSHA mandate calibration documentation that smart sensors automate.
- Water & Wastewater:Municipal budget constraints preserve analog float switch dominance.
- Food & Beverage:Hygienic design and CIP compatibility prioritize 3-A sanitary standards.
Oil & Gas commands the highest average selling prices, with Chemicals expanding most quickly on regulatory replacement demand.
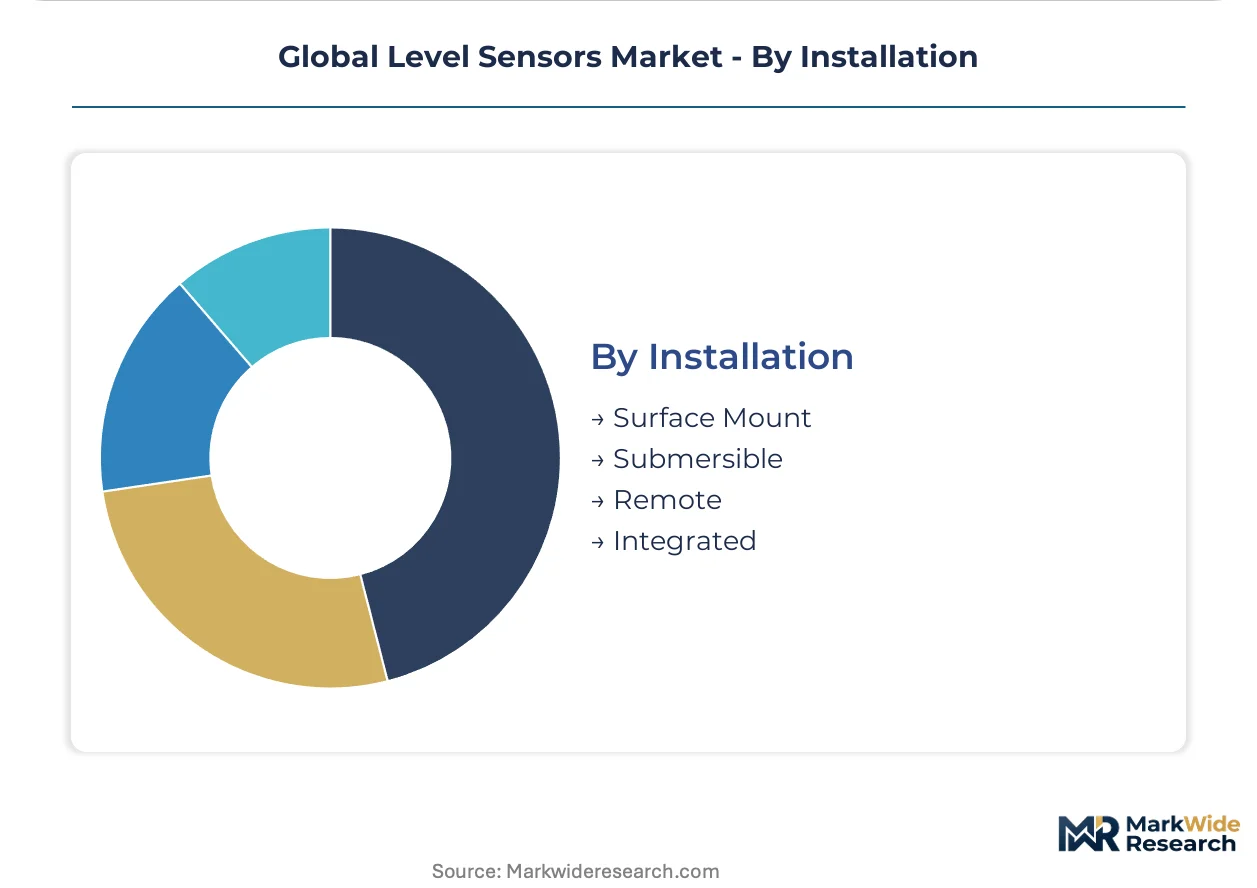
Installation:
Mounting geometry constrains technology selection, with submersible configurations dominating sump and well applications where vessel access is impractical.
- Submersible:IP68-rated transmitters with vented cable assemblies measure hydrostatic pressure in deep wells and boreholes. Geothermal extraction operators in California specify silicon carbide sensing elements for hydrogen sulfide resistance.
- Surface Mount:External attachment via flange or thread avoids process fluid contact. Cement silos in India deploy surface-mounted radar through plastic vessel tops for bulk solids inventory management.
- Remote:Wireless transmission bridges physical gaps between sensor location and control room.
- Integrated:Pump-motor combinations with built-in level control reduce field wiring complexity.
Submersible configurations lead in unit shipments, with surface-mounted radar climbing fastest on solids measurement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical processors anchor sensor demand through hermetic sealing upgrades under EU F-Gas Regulation mandates. Procurement concentrates in industrial clusters where tank farm automation and predictive maintenance integration drive replacement cycles.
United States
Texas petrochemical terminals deploy redundant ultrasonic arrays for aboveground tank leak prevention under tightened EPA SPCC inspection intervals. OSHA Process Safety Management standards mandate calibration documentation that smart sensors automate. Houston and Corpus Christi refineries tender tank farm modernization contracts requiring IO-Link compatible instrumentation.
Germany
BASF and Bayer facilities specify welded titanium diaphragm sensors to preempt 2025 inspection interval compressions under EU F-Gas Regulation. EMA classifications restrict sealed sensor technologies in refrigeration, redirecting procurement toward hermetically welded alternatives. Ludwigshafen and Leverkusen chemical clusters concentrate demand for capacitive probes with PTFE coatings.
China
State-owned refineries in Shandong and Jiangsu provinces modernize tank farm monitoring infrastructure with centralized SCADA integration requirements. MEE environmental enforcement tightens emissions tracking mandates, stimulating continuous level monitoring installations. Sinopec procurement specifications prioritize Modbus RTU digital sensors for custody transfer accuracy.
India
Indian Oil and Bharat Petroleum tender tank farm automation contracts requiring IO-Link compatible level instrumentation. BIS certification requirements and PLI scheme incentives accelerate domestic sensor assembly capacity. Gujarat and Maharashtra refinery corridors concentrate demand growth as state-owned oil marketing companies replace mechanical float systems.
Switzerland
Food and beverage processors in the Swiss Mittelland deploy smart level transmitters to automate CIP cycle verification and reduce unplanned downtime. Swissmedic-aligned quality standards elevate specification tiers for hygienic design instrumentation. Basel pharmaceutical clusters specify 3-A sanitary standard sensors for bioprocess tank monitoring.
Global Level Sensors Market Competitive Environment
Global majors compete with regional champions across calibration infrastructure and polymer composite manufacturing capabilities. The vendor base stratifies into three tiers: diversified industrial conglomerates with captive sensor divisions, specialized level instrumentation pure-plays, and regional system integrators with local service networks. Dominant competitive moves include M&A to acquire IO-Link protocol expertise and backward integration into polymer molding operations to defend margin pools.
Within the diversified industrial tier, Emerson Electric Co. and Siemens AG represent scale-driven positioning through captive manufacturing and global distribution networks. Among specialized instrumentation providers, Endress+Hauser AG and Vega GmbH exemplify the calibration-laboratory archetype with regional service density in European industrial corridors. These named entities anchor competitive dynamics without constraining the full competitive set.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| ABB Ltd. |
| Siemens AG |
| AMETEK Inc. |
| Honeywell International Inc. |
| Endress+Hauser AG |
| Pepperl+Fuchs GmbH |
| Vega GmbH |
| Magnetrol International Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Germany and Switzerland anchor premium pricing through captive calibration laboratories, while private-equity-rolled-up service networks in North America compress regional price spreads through aftermarket unbundling. This ownership bifurcation concentrates pricing power among European instrumentation pure-plays while fragmenting procurement leverage for buyers in Texas and Alberta petrochemical corridors.
Pricing Analysis
Input-cost pass-through from nickel and molybdenum volatility directly compresses margin pools for manufacturers dependent on 316L stainless-steel enclosures. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in economy-tier analog sensors is intensifying because municipal water treatment buyers face capital constraints blocking digital migration. Independent refiners exhibit highest price sensitivity, while offshore platform operators in the North Sea accept premium positioning for polymer-composite weight reduction.
Supply Chain Analysis
India's PLI scheme incentives and BIS certification requirements are reshaping sourcing patterns, accelerating domestic sensor assembly capacity in Gujarat and Maharashtra. Supply concentration centers on Germany, Switzerland, and China for precision sensing elements and polymer molding operations. The chain draws from nickel alloy foundries in China, ceramic diaphragm suppliers in Japan, and glass-reinforced nylon compounders in Germany. Single-source vulnerability in silicon carbide MEMS substrates creates chokepoint exposure for geothermal and heavy oil extraction specifications. Distribution runs through authorized distributor networks for process industries and direct OEM procurement for large refinery modernization tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with specification tiers compressing toward smart instrumentation as Indian and Chinese state-owned refineries mandate IO-Link compatibility for predictive maintenance ROI.
For Market Incumbents: Deploy backward integration into polymer molding operations to defend margin pools against nickel price volatility and emerging composite housing specialists. Expand captive calibration laboratory networks in India and China to preempt regional service access disparities that third-party metrology laboratories in Texas and Alberta are exploiting. Prioritize cybersecurity engineering capacity building as IT-OT convergence exposes level sensor networks to ransomware targeting Modbus and HART protocol vulnerabilities. For New Entrants and Emerging Players: Begin with municipal water treatment infrastructure in North America, where legacy 4-20mA analog installations face capital constraints blocking digital migration despite predictive maintenance incentives. Target mid-size independent refiners seeking to reduce OEM dependency through aftermarket service unbundling. Pursue direct sales partnerships with third-party metrology laboratories to bypass established distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional system integrators with local service networks in Indian and Chinese refinery corridors. Long-term viability hinges on protocol expertise acquisition as facilities prioritize predictive maintenance integration. The signal to watch is tender specifications from Indian Oil and Bharat Petroleum requiring IO-Link compatible instrumentation, which would accelerate consolidation among pure-play sensor manufacturers lacking digital protocol capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Molding | Emerson Electric Co. leverages captive operations to defend offshore platform margins against stainless-steel input volatility. |
| Calibration Laboratory Network Expansion | Endress+Hauser AG and Vega GmbH maintain regional service density that third-party metrologists in Texas are fragmenting. |
| IO-Link Protocol Expertise Acquisition | Smart sensor procurement from Indian and Chinese state refineries accelerates M&A targets with digital instrumentation capabilities. |
| Hermetic Sealing Certification Investment | Welded titanium diaphragm sensors preempt 2025 EU F-Gas Regulation inspection interval compressions for German chemical processors. |
| Cybersecurity Engineering Capacity Buildout | Operational technology networks face ransomware exposure as IT-OT convergence accelerates attack surface vulnerability. |
Study Parameters
Direct dialogue with plant engineers, maintenance directors at downstream OEMs, aftermarket service heads, and procurement leads at state-owned refineries grounded qualitative findings in operational reality. Secondary validation drew from customs and trade data, SEC 10-K filings, EPA SPCC enforcement records, and EU F-Gas Regulation compliance databases. Bottom-up and top-down triangulation cross-checked sensor shipment volumes against refinery modernization tender specifications and tank farm automation project announcements.
Segmentation outputs across product type, technology tier, end-use industry, and installation configuration structured the analytical framework over the projection horizon. CAGRs were derived from regression analysis of historical replacement cycle compression and regulatory mandate timing. Forecast inputs incorporated nickel and molybdenum price trajectory assumptions, polymer composite substitution elasticity, and smart sensor adoption curves in chemical processing and hydrocarbon storage.
Several conditions sit outside the modeled scope, including black-swan commodity price spikes, accelerated cybersecurity regulatory frameworks for operational technology, and sovereign trade policy shifts affecting sensor component tariffs. Forecasts reflect documented assumptions about replacement cycle timing and technology migration rates. A small set of named triggers warrants ongoing watch: EPA enforcement intensity for aboveground storage tank monitoring, EU F-Gas Regulation hermetic sealing deadline compliance, and Indian PLI scheme capacity buildout acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Eye Tracking Systems Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
Thermal Scanners Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Taiwan Sensors Market