
 Oxygen Gas Sensors Market | 2026-2036
Oxygen Gas Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Gas Sensors Market Analytics
A shift from single-source to multi-source procurement for electrochemical sensing elements is hardening across Tier-1 automotive suppliers. Robert Bosch GmbH leverages captive semiconductor fabrication to secure zirconia cell supply for exhaust gas monitoring. Honeywell International Corporation anchors its position through backward integration into ceramic substrate manufacturing for industrial safety applications. Sensirion AG differentiates by specializing in miniaturized optical sensing modules for medical-grade oxygen measurement.
An oxygen gas sensor detects partial pressure or concentration of molecular oxygen through electrochemical reaction, optical fluorescence quenching, or catalytic oxidation, typically operating within 0-100% volume ranges with response times under 15 seconds for critical care use. Electrochemical types dominate industrial safety deployments due to established calibration protocols and lower unit cost, while optical variants capture expanding margin pools in medical devices and environmental monitoring where drift-free stability and extended calibration intervals command premium positioning. Wired connectivity still leads manufacturing and oil & gas installations, though Bluetooth-enabled portable units are gaining share in research laboratories requiring flexible deployment.
The FDA enforces 510(k) premarket notification for oxygen sensors integrated into ventilators and anesthesia workstations, while the EU MDR requires notified body oversight for active implantable and respiratory device accessories. OSHA permissible exposure limits for oxygen-deficient atmospheres mandate continuous monitoring in confined industrial spaces, sustaining replacement demand across manufacturing and energy infrastructure. Stakeholders must monitor evolving IEC 60601-1-8 alarm signal standards for medical electrical equipment, as harmonization gaps between FDA and EU MDR testing protocols could fragment product development roadmaps and certification timelines.
Market Dynamics
Medical device procurement is hardening around optical sensing architectures as EU MDR performance verification timelines compress development cycles and OEMs demand drift-free stability for ventilator integrations.
Growth Catalysts
- EU Medical Device Regulation:Tightened performance verification requirements for respiratory care accessories are forcing upgrades to optical oxygen sensors across German and Swiss precision device exporters.
- Automotive zirconia cell demand:Exhaust gas monitoring mandates under Euro 7 and EPA Tier 3 standards are sustaining electrochemical sensor volumes for catalytic converter feedback loops.
- Confined space monitoring:OSHA permissible exposure limits for oxygen-deficient atmospheres mandate continuous replacement cycles across US manufacturing and energy infrastructure.
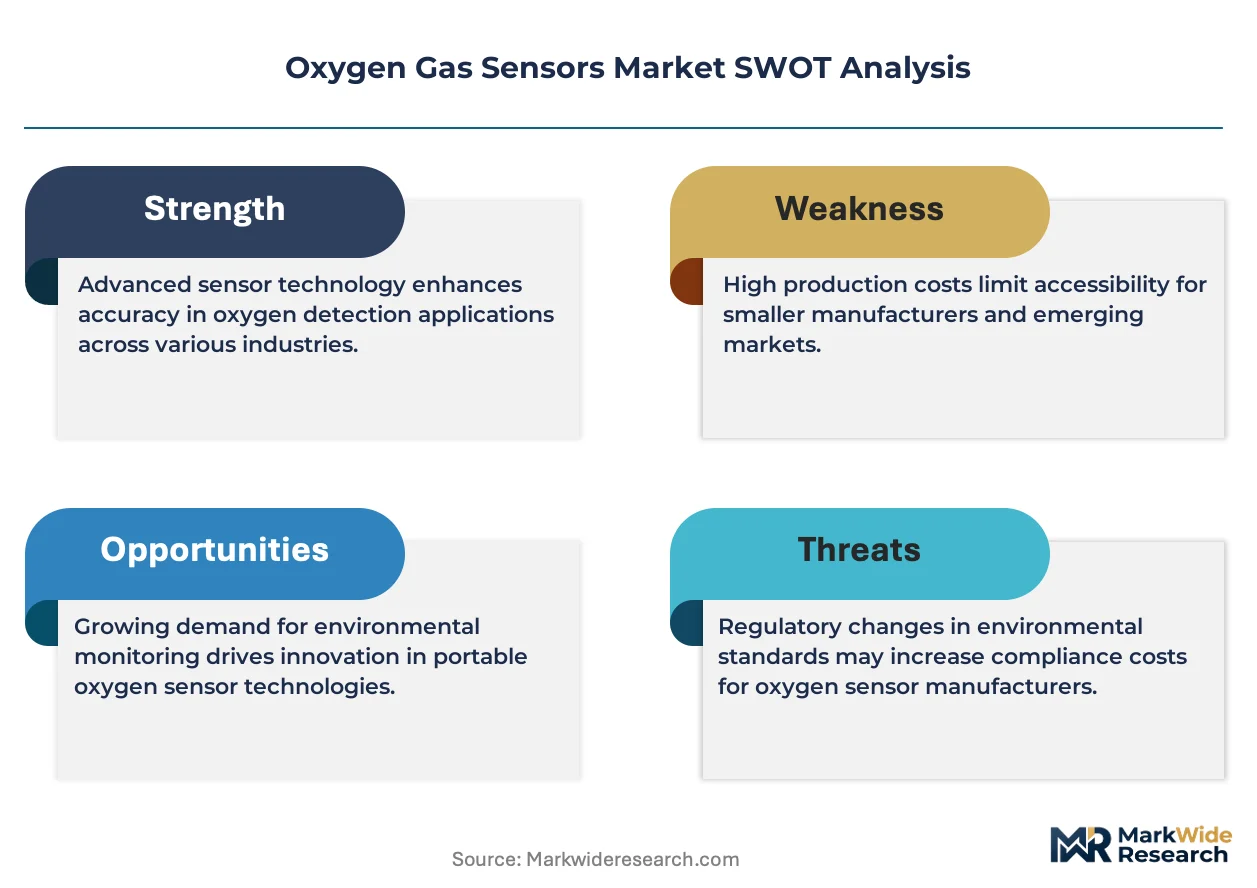
Market Restraints
- Palladium electrode cost volatility:Electrochemical cell manufacturers face margin compression from precious metal input swings in catalytic electrode formulations.
- Zirconia substrate concentration:Ceramic supply for automotive exhaust sensors clusters among Japanese and German specialty powder producers, creating single-source vulnerability.
- Optical sensor thermal limitation:Fluorescence quenching architectures degrade above 60°C, excluding them from high-temperature industrial process control applications.
Strategic Opportunities
- Home respiratory monitoring:Post-acute care discharge protocols in the US and Germany are expanding addressable demand for portable pulse oximetry and oxygen concentrator feedback systems.
- Wearable integration:Miniaturized optical modules are converging with flexible electronics for continuous SpO2 tracking in consumer health devices and athletic performance optimization.
- Green hydrogen production:Electrolyzer safety systems require dissolved oxygen monitoring in high-purity water loops, opening industrial process control applications beyond traditional combustion monitoring.
Industry Challenges
- IEC 60601-1-8 alarm harmonization:Divergent FDA and EU MDR testing protocols for medical electrical equipment alarm signals are fragmenting product development roadmaps and extending certification timelines.
- Cleanroom assembly capex:Medical-grade optical sensor production requires ISO 14644 Class 7 environments, constraining capacity expansion for mid-tier suppliers.
- Legacy system integration:Wired 4-20mA output formats dominate installed manufacturing bases, complicating Bluetooth-enabled portable unit adoption without signal converter middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Gas Sensors Market |
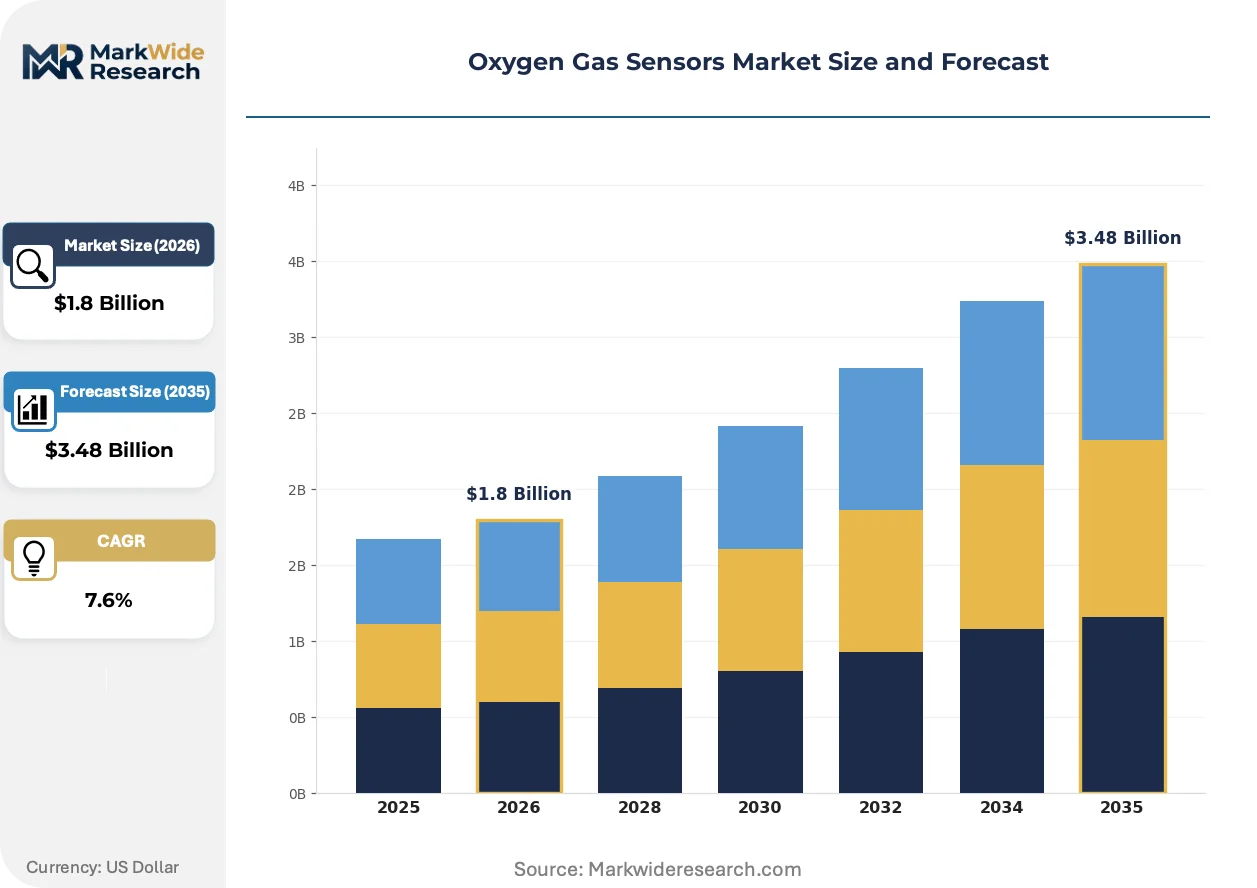
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Catalytic, Electrochemical, Optical, Metal Oxide Application: Environmental Monitoring, Industrial Safety, Medical Devices, Automotive Technology: Wi-Fi, Bluetooth, Zigbee, Wired End User: Manufacturing, Healthcare, Oil & Gas, Research Laboratories |
| Companies Covered | Robert Bosch GmbH, Honeywell International Corporation, ABB Limited, Yokogawa Electric Corporation, Sensirion AG, Eaton Corporation, General Electric Company, Figaro Engineering Inc., City Technology Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Gas Sensors Market Evolving Landscape
Optical fluorescence quenching architectures are displacing electrochemical cells in premium medical segments while regulatory pressure on calibration intervals accelerates technology substitution timelines.
Photonic integrated circuits are integrating silicon photonics with polymer optical waveguides to shrink oxygen sensor footprints below 5mm³ for catheter-based and implantable applications. Cardiovascular device manufacturers in Switzerland and Massachusetts are piloting these modules for intravascular monitoring. The technology is integrating sensing and signal processing on single substrates, collapsing bill-of-materials costs and enabling disposable single-use configurations.
REACH authorization requirements for lead-containing electrochemical sensors are forcing formulation shifts toward bismuth and tin oxide electrode materials across European industrial safety suppliers. The regulation's sunset dates for Annex XIV substances are compressing R&D timelines for alternative chemistries. German and French gas detection OEMs are accelerating optical sensor partnerships to bypass material substitution complexity entirely.
Multi-year service contracts with bundled calibration and replacement sensor provisioning are displacing transactional component sales in oil and gas and pharmaceutical manufacturing verticals. Channel intermediaries in the US Gulf Coast and Rotterdam port complexes are repositioning as managed service providers. This shift is most visible among Dutch and Belgian industrial gas distributors consolidating maintenance spend under single-vendor agreements.
Oxygen Gas Sensors Market Segmentation
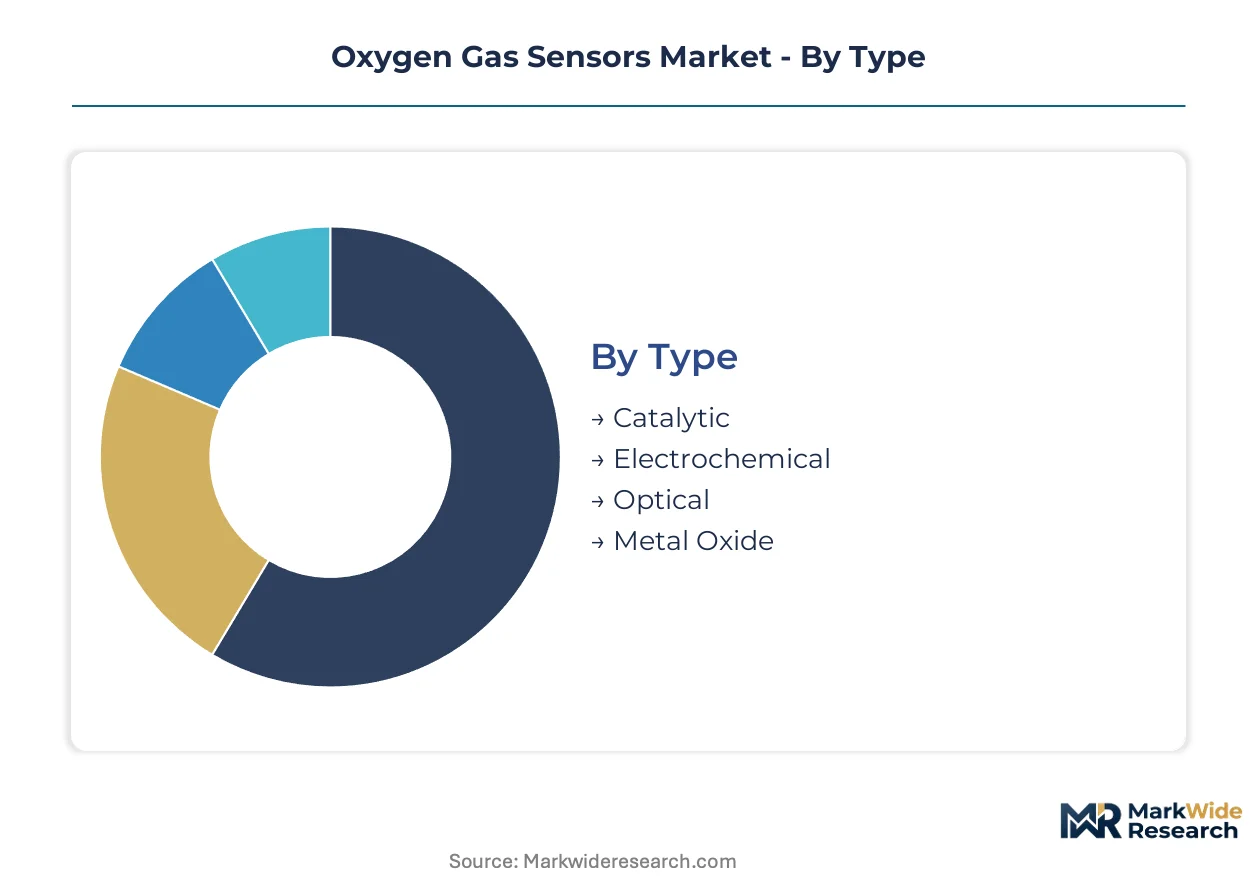
Oxygen gas sensor procurement splits sharply between cost-sensitive industrial buyers and premium-seeking medical device OEMs. Technology choices cascade through connectivity requirements, calibration protocols, and regulatory compliance burdens that reshape vendor selection criteria across verticals.
Type:
Buyers in this category differentiate primarily by total cost of ownership versus performance stability trade-offs.
- Electrochemical:Catalytic oxidation reactions between oxygen and precious metal electrodes generate measurable current signals. Industrial safety deployments across German chemical manufacturing clusters favor these units for established calibration protocols and sub-dollar per-day operating costs.
- Optical:Fluorescence quenching of ruthenium complexes measures partial pressure without electrode degradation. Swiss and Massachusetts cardiovascular device manufacturers are concentrating procurement for ventilator and catheter-based monitoring where drift-free stability commands premium positioning.
- Catalytic:Platinum-catalyzed combustion detection serves explosive atmosphere applications with rapid response characteristics.
- Metal Oxide:Semiconductor resistance changes at elevated temperatures enable compact form factors for consumer electronics integration.
Volume sits with electrochemical cells; growth tilts toward optical architectures as EU MDR verification timelines compress substitution decisions.
Application:
Regulatory intensity and replacement cycle frequency separate high-margin medical segments from commodity industrial monitoring.
- Medical Devices:Pulse oximetry, anesthesia workstations, and ventilator feedback loops demand ISO 13485-certified manufacturing with traceable calibration histories. German precision sensor OEMs are expanding cleanroom capacity to serve ventilator manufacturers facing FDA 510(k) and EU MDR dual certification requirements.
- Automotive:Zirconia-based exhaust gas monitoring for catalytic converter feedback operates at 300-600°C with sub-second response times. Bosch's captive semiconductor fabrication in Reutlingen anchors European supply for Euro 7 compliance deadlines.
- Industrial Safety:Confined space monitoring for OSHA permissible exposure limits sustains replacement demand across US Gulf Coast petrochemical infrastructure.
- Environmental Monitoring:Atmospheric and dissolved oxygen tracking for watershed management employs lower-specification optical units with extended deployment intervals.
Revenue concentrates in medical devices; expansion accelerates fastest in automotive as emissions standards tighten across multiple geographies.
Technology:
Installation legacy and mobility requirements drive divergent connectivity procurement patterns between fixed infrastructure and portable deployments.
- Wired:4-20mA analog outputs and Modbus digital protocols dominate manufacturing plant floors where electromagnetic interference resistance outweighs flexibility needs. Rotterdam port complex oil & gas terminals specify hardwired loops for intrinsic safety compliance in hazardous area classifications.
- Bluetooth:Low-energy protocols enable smartphone-tethered portable units for research laboratory flexibility. Dutch and Belgian industrial gas distributors are bundling Bluetooth-enabled replacement sensors into multi-year service contracts with predictive maintenance analytics.
- Wi-Fi:TCP/IP connectivity supports centralized monitoring dashboards across distributed pharmaceutical manufacturing campuses.
- Zigbee:Mesh networking protocols serve battery-constrained environmental monitoring arrays in remote watershed installations.
Installed base favors wired connectivity; Bluetooth modules are climbing fastest as service contract models displace transactional component sales.
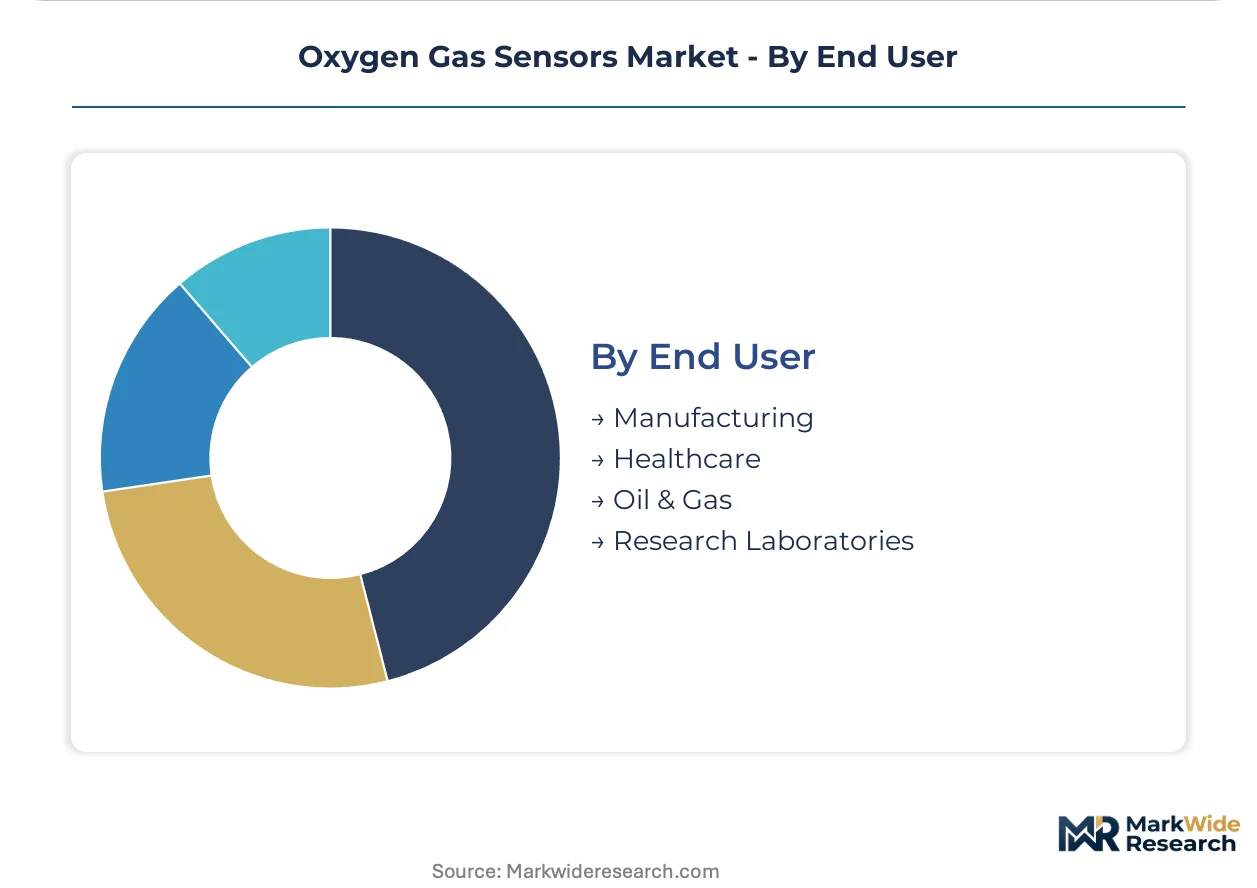
End User:
Volume scale and technical sophistication create distinct customer archetypes with diverging vendor relationship expectations.
- Healthcare:Hospital systems and home respiratory device manufacturers demand ISO 14644 Class 7 cleanroom assembly with lot traceability. US post-acute care discharge protocols are expanding addressable demand for portable oxygen concentrator feedback systems in Germany and Switzerland.
- Manufacturing:Automotive and electronics production lines specify electrochemical cells for oxygen-deficient atmosphere monitoring under OSHA enforcement. Replacement cycles align with annual safety audit schedules.
- Oil & Gas:Offshore platforms and refinery maintenance operations require ATEX-certified units with multi-year calibration intervals. Managed service providers in the US Gulf Coast are consolidating maintenance spend under single-vendor agreements.
- Research Laboratories:Academic and pharmaceutical R&D facilities prioritize Bluetooth-enabled flexibility for experimental reconfiguration without infrastructure modification.
Procurement volume clusters in healthcare; manufacturing safety mandates sustain the steepest replacement cycle predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zirconia ceramic substrate production concentrates in German and Japanese specialty powder facilities, anchoring automotive sensor supply chains for Euro 7 and EPA Tier 3 compliance deadlines.
United States
OSHA permissible exposure limits for oxygen-deficient atmospheres drive replacement cycles across Gulf Coast petrochemical infrastructure. FDA 510(k) premarket notification requirements govern ventilator sensor integrations. Houston and Corpus Christi industrial clusters sustain electrochemical cell demand for confined space monitoring.
Germany
EU MDR performance verification timelines compress development cycles for precision device exporters. REACH authorization requirements for lead-containing sensors accelerate optical architecture adoption. Stuttgart and Reutlingen semiconductor fabrication centers anchor Bosch's captive zirconia cell supply for exhaust monitoring.
Switzerland
Swissmedic oversight of active implantable devices elevates cleanroom assembly standards for cardiovascular monitoring applications. Post-acute care discharge protocols expand home respiratory device demand. Basel and Zurich precision sensor OEMs specialize in miniaturized optical modules for catheter-based systems.
China
GB standards for industrial safety equipment sustain electrochemical sensor volumes in manufacturing zones. Dual carbon goals tighten emissions monitoring requirements across heavy industry. Yangtze River Delta electronics clusters integrate metal oxide sensors for consumer device applications.
Japan
METI industrial safety mandates sustain replacement demand across chemical and steel production facilities. PMDA quality management system requirements govern medical-grade sensor imports. Nagoya automotive manufacturing corridors anchor zirconia-based exhaust monitoring deployment.
Oxygen Gas Sensors Market Competitive Landscape
Global majors compete with regional champions across technology architecture and regulatory certification depth. The vendor base organizes around three tiers: diversified industrial conglomerates with captive semiconductor fabrication, specialized sensor OEMs with medical-grade cleanroom capacity, and regional safety equipment suppliers serving price-sensitive industrial verticals. Dominant competitive moves include backward integration into ceramic substrate manufacturing and multi-year service contract bundling to displace transactional component sales.
Among diversified industrial conglomerates, Robert Bosch GmbH exemplifies the captive supply archetype through in-house zirconia cell production. Honeywell International Corporation occupies a position spanning industrial safety and aerospace applications with backward integration into ceramic manufacturing. Sensirion AG represents the specialized medical-grade tier, anchoring Swiss precision capabilities in miniaturized optical architectures. These three entities illustrate the competitive spectrum from scale-driven vertical integration to technology-specialized differentiation.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Honeywell International Corporation |
| ABB Limited |
| Yokogawa Electric Corporation |
| Sensirion AG |
| Eaton Corporation |
| General Electric Company |
| Figaro Engineering Inc. |
| City Technology Limited |
| Others |
Value Network & Pricing Analysis
Optical fluorescence quenching architectures are compressing electrochemical cost premiums as Swiss and German OEMs scale cleanroom capacity for medical-grade production. This technology transition simultaneously elevates fixed cost barriers for mid-tier suppliers and concentrates pricing power among integrated precision sensor manufacturers.
Pricing Analysis
Multi-year calibration-inclusive service contracts now dominate oil and gas procurement, displacing per-unit transactional sales for unbundled electrochemical cells. Pricing stratifies across medical-grade optical modules with ISO 13485 certification, industrial electrochemical cells with standard warranty terms, and commodity metal oxide sensors for consumer integration. Cost compression in electrochemical tiers is intensifying because REACH authorization deadlines for lead-containing electrodes force rapid material substitution R&D. Hospital systems and ventilator OEMs exhibit lowest price sensitivity; confined space safety managers at Gulf Coast petrochemical facilities remain most price-constrained.
Supply Chain Analysis
Direct-to-OEM channels handle Tier-1 automotive and medical device demand, while industrial gas distributors in Rotterdam and Houston intermediate fragmented safety equipment procurement. Zirconia ceramic substrate production concentrates in Germany and Japan, with ruthenium complex dyes for optical sensors sourcing primarily from Swiss specialty chemical producers. Palladium electrode formulations for electrochemical cells draw from South African and Russian mining output, exposing margins to precious metal commodity volatility. Distribution runs through ATEX-certified equipment distributors for hazardous area applications and GPO contracts for hospital system sensor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EU MDR compliance costs and cleanroom assembly capex requirements force sub-scale electrochemical suppliers toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through captive zirconia substrate production and multi-year service contract bundling that locks replacement cycles. Bosch's Reutlingen semiconductor fabrication exemplifies upstream control over critical ceramic supply. Invest in ISO 14644 Class 7 cleanroom expansion ahead of Swiss and German ventilator OEM demand surges, as FDA 510(k) dual-certification timelines compress supplier qualification windows. For New Entrants and Emerging Players: Launch via Bluetooth-enabled portable unit partnerships with Dutch and Belgian industrial gas distributors repositioning as managed service providers. Home respiratory monitoring post-acute care protocols in Germany and Switzerland offer the most penetrable white-space, with portable oxygen concentrator feedback systems escaping incumbent electrochemical lock-in. Target green hydrogen electrolyzer safety applications where dissolved oxygen monitoring specifications remain unsettled. For Investors and Strategic Acquirers: Re-rating potential sits with specialized optical sensor OEMs possessing medical-grade cleanroom capacity given EU MDR verification timeline compression. Five-to-ten year viability favors Swiss and German precision manufacturers with established cardiovascular device partnerships over undifferentiated industrial safety suppliers. Monitor IEC 60601-1-8 alarm signal harmonization progress between FDA and EU MDR protocols as inflection indicator for certification timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Manufacturing | Bosch's Reutlingen captive supply secures zirconia cell volumes for Euro 7 compliance deadlines. |
| Multi-Year Service Contract Bundling | Dutch industrial gas distributors consolidate maintenance spend under predictive maintenance analytics agreements. |
| ISO 14644 Class 7 Cleanroom Capacity Expansion | German precision OEMs meet ventilator manufacturer FDA 510(k) and EU MDR dual certification requirements. |
| Photonic Integrated Circuit Development | Swiss and Massachusetts cardiovascular device manufacturers pilot sub-5mm³ modules for intravascular monitoring. |
| REACH-Compliant Electrode Material Substitution | German and French gas detection OEMs accelerate optical partnerships to bypass bismuth and tin oxide formulation complexity. |
Research Methodology
Independent corroboration across primary interviews with biomedical engineers, hospital GPO contracts managers, Tier-1 automotive procurement leads, and industrial safety distributors underwrites the qualitative findings. Secondary validation draws from FDA 510(k) premarket notification databases, EU MDR notified body oversight records, OSHA permissible exposure limit enforcement data, and SEC filings of diversified industrial conglomerates. Bottom-up sensor unit demand modeling triangulates against top-down medical device and automotive production forecasts.
Comparable historical reference periods anchor volume and value projections across the analysis window. The analytical framework segments by sensing technology architecture, application vertical regulatory intensity, connectivity protocol installation legacy, and end-user replacement cycle predictability. CAGRs derive from technology substitution elasticity estimates calibrated to EU MDR and EPA Tier 3 compliance deadline impacts. Forecast inputs incorporate REACH authorization sunset timelines for lead-containing electrochemical sensors and photonic integrated circuit yield improvement curves.
The model assumes a particular technology adoption path; alternative pathways for optical fluorescence quenching thermal limitation breakthroughs would alter the outlook. Forecasts reflect assumptions around regulatory harmonization progress and precious metal electrode cost volatility. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
Global Capacitive Sensor Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
Global E-Compass Market
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Ultrasonic Air in Line Sensor Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Wireless Pressure Sensors Market
Sensors and Controls
Dew Point Thermometer Market
Sensors and Controls
Latin America Wearable Sensors Market