
 Magnetometer Sensor Market | 2026-2036
Magnetometer Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetometer Sensor Market Foresight
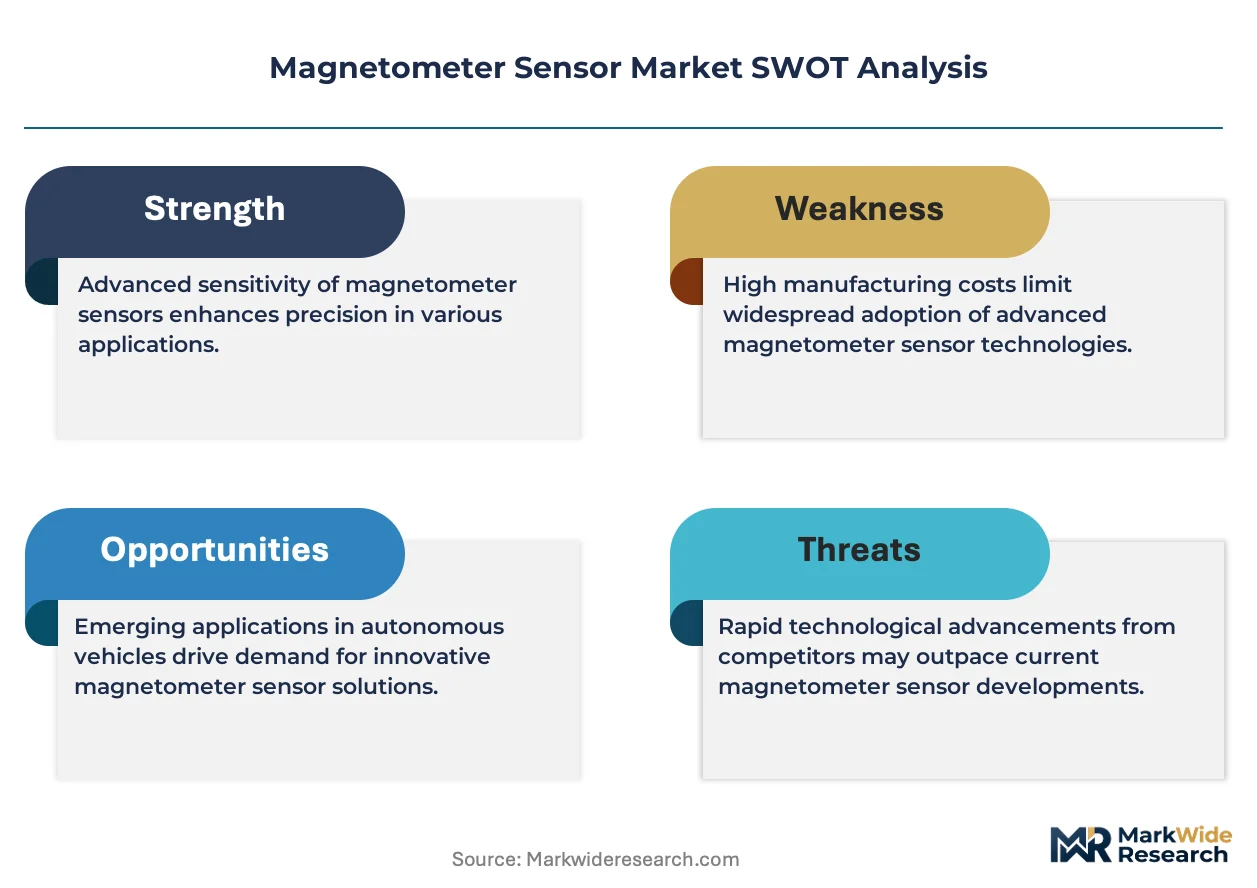
Multi-source procurement among tier-one automotive suppliers is realigning how magnetometer vendors secure long-term contracts. Honeywell International leverages its aerospace heritage to dominate high-precision fluxgate segments for defense and geophysical applications. NXP Semiconductors anchors its position through integrated magnetic sensor solutions bundled with automotive microcontroller platforms. STMicroelectronics competes by sustaining R&D intensity in low-power Hall effect designs for consumer electronics and industrial automation.
A magnetometer sensor measures magnetic field strength and direction, typically detecting fields from 10 nT to 100 mT depending on technology type, with fluxgate variants achieving sub-nanotesla resolution through saturable core switching. These devices serve navigation, current sensing, geophysical mapping, and proximity detection across industrial and commercial systems. Hall effect technology occupies the highest volume tier due to silicon integration and cost-down trajectories in automotive motor control. SQUID sensors command premium positioning in medical imaging and scientific instrumentation where extreme sensitivity outweighs cryogenic cooling requirements. Consumer electronics applications represent the fastest-expanding demand pool as smartphones and wearables embed compass and motion-fusion functions.
The EU Green Deal and F-Gas Regulation shape automotive sensor requirements by mandating electrified powertrains that depend on accurate magnetic feedback for motor commutation. EPA tailpipe standards and NHTSA safety mandates in the United States drive similar magnetometer integration into EV platforms and advanced driver-assistance systems. ISO 26262 functional safety certification increasingly gates market access for automotive-grade magnetic sensors. Stakeholders must monitor how dual carbon goals in China and evolving EU AI Act requirements for autonomous systems redirect R&D investment toward fault-tolerant, multi-axis sensor architectures.
Market Dynamics
Automotive electrification is compressing sensor procurement timelines as EV platforms demand fault-tolerant magnetic feedback systems for motor commutation and battery management. Tier-one suppliers now bundle multi-axis magnetometer arrays with functional safety certification to meet ISO 26262 gates.
Growth Catalysts
- EU Green Deal mandates:Electrified powertrain requirements under the F-Gas Regulation are forcing automakers to integrate precision magnetic sensors for torque vectoring and regenerative braking control.
- Consumer electronics volume:Smartphone compass fusion and wearable motion tracking are pulling low-power Hall effect designs into billion-unit annual production scales.
- China's dual carbon goals:Domestic EV makers are captive-sourcing fluxgate and AMR sensors from local foundries to reduce import dependency for magnetic sensing subsystems.
Market Restraints
- Rare earth magnet price volatility:Neodymium and dysprosium cost swings destabilize fluxgate core material budgets and force long-term supply agreements with Chinese refiners.
- Cryogenic infrastructure limits:SQUID sensor deployment remains constrained by liquid helium cooling requirements that restrict medical imaging applications to specialized research hospitals.
- ISO 26262 certification friction:Functional safety documentation timelines extend automotive qualification cycles, delaying revenue recognition for new magnetic sensor entrants.
Strategic Opportunities
- India PLI scheme leverage:Electronics manufacturing incentives are attracting magnetometer packaging and test operations to serve domestic automotive and industrial automation demand.
- AMR-TMR convergence:Anisotropic magnetoresistive and tunnel magnetoresistive technology fusion is opening sub-millitesla precision tiers for current sensing in grid-scale inverters.
- EU AI Act compliance:Autonomous vehicle sensor redundancy requirements are creating specification windows for triple-redundant magnetic heading reference systems.
Industry Challenges
- Magnetic calibration expertise scarcity:Foundry engineers with saturable core design experience command premium compensation, constraining fluxgate production scaling.
- Multi-axis fusion complexity:Integrating magnetometer, accelerometer, and gyroscope data streams for dead-reckoning navigation demands specialized sensor fusion firmware talent.
- Legacy automotive platform retrofit friction:Internal combustion vehicle architectures lack the electrical bandwidth and processing headroom for advanced magnetic field monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetometer Sensor Market |
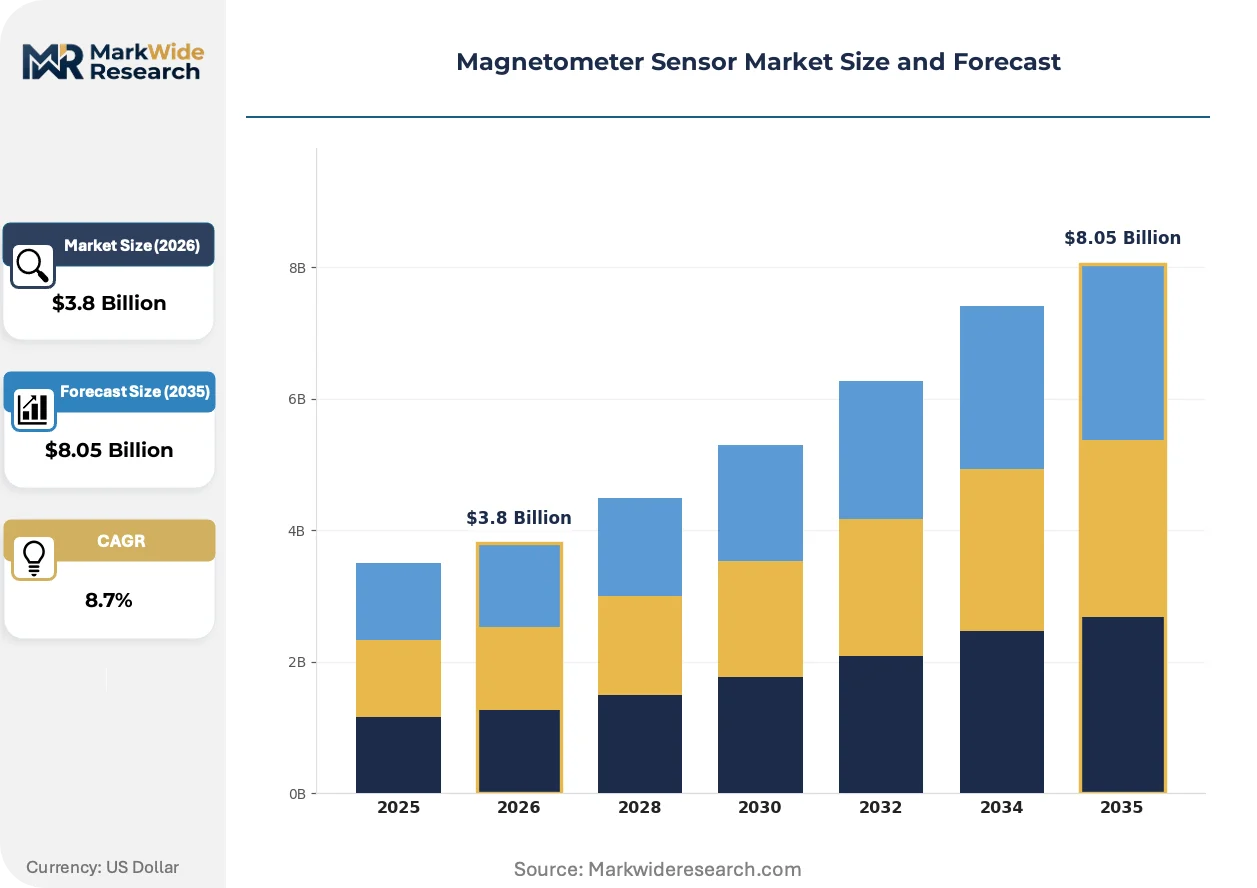
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fluxgate, Hall Effect, Magneto-optical, SQUID Application: Automotive Navigation, Industrial Automation, Geophysical Surveys, Consumer Electronics End User: Aerospace, Automotive, Healthcare, Defense Form Factor: Handheld, Integrated, Portable, Fixed |
| Companies Covered | Honeywell International, NXP Semiconductors, Allegro MicroSystems, Asahi Kasei, Infineon Technologies, TDK Corporation, STMicroelectronics, Robert Bosch, NVE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetometer Sensor Market Shifts & Advancements
Magnetometer technology trajectories are diverging between extreme miniaturization for consumer wearables and hardened precision for electrified transport. Three distinct vectors now command R&D investment priority.
TMR (tunnel magnetoresistive) sensing is electrifying current measurement architectures in EV powertrains and charging infrastructure. Tier-one automotive suppliers are adopting TMR-based shunt replacements for non-invasive busbar monitoring. This transition is compressing Hall effect dominance in high-current applications where thermal drift tolerance matters.
REACH substance restrictions and RoHS recast directives are forcing magnetic sensor packagers to eliminate leaded solders and specific epoxy formulations. European industrial automation OEMs now specify halogen-free substrate materials in magnetometer module procurement tenders. German machine builders are accelerating qualification of green-compliant fluxgate designs for factory robotics.
Multi-source qualification mandates from automotive Tier-1s are fragmenting historical single-vendor relationships. Bosch and Continental now require dual-qualified magnetometer sources for each platform generation. This behavioral shift is most visible in Germany and Japan, where keiretsu-style supply structures are yielding to audit-driven vendor pools.
Magnetometer Sensor Market Segmentation
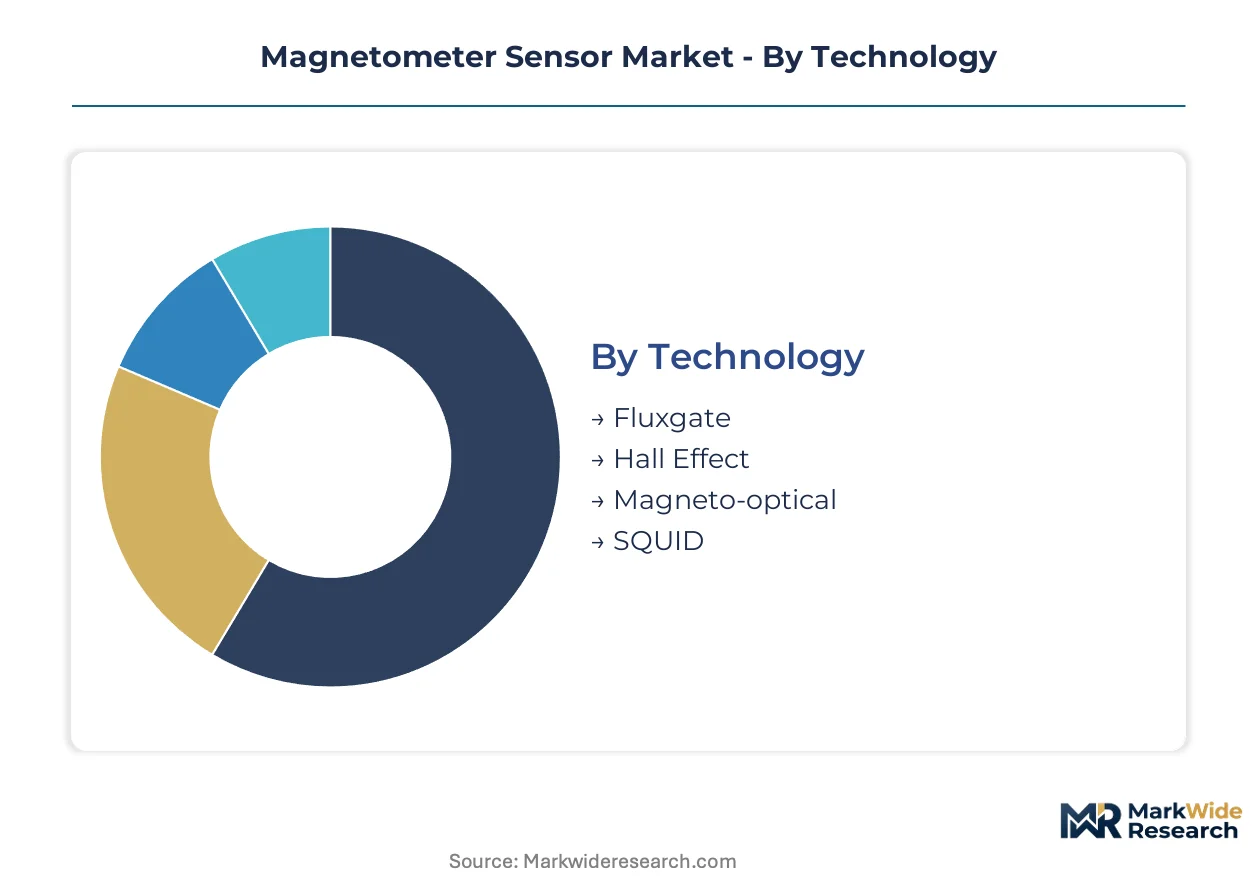
Magnetometer architectures diverge sharply between discrete precision instruments and silicon-integrated sensing elements. Understanding where each technology sits on this integration spectrum shapes procurement strategies across defense, automotive, and consumer verticals.
Technology:
Standalone fluxgate systems serve calibration laboratories and geophysical observatories, while Hall effect and emerging solid-state variants embed directly into motor control ASICs and smartphone compass modules.
- Fluxgate:Saturable core designs achieve sub-nanotesla resolution through periodic magnetic switching. Defense agencies in Germany and Japan specify fluxgate magnetometers for submarine navigation and aeromagnetic mapping where magnetic cleanliness is mandatory.
- Hall Effect:Silicon-integrated variants dominate automotive motor commutation and battery current sensing. NXP Semiconductors and Infineon Technologies anchor supply to EV platforms in China and the United States, where ISO 26262 functional safety certification gates market access.
- Magneto-optical:Fiber-coupled sensors exploit Faraday rotation for non-invasive high-voltage current measurement in grid infrastructure. Deployment concentrates in utility-scale inverter monitoring where galvanic isolation is non-negotiable.
- SQUID:Superconducting quantum interference devices require liquid helium cooling and command premium positioning in magnetoencephalography and low-field MRI. Research hospitals in Switzerland and the United States represent the primary installed base.
Volume placements concentrate in Hall effect; the faster expansion belongs to fluxgate as defense budgets modernize magnetic surveillance capabilities.
Application:
Cost tiers separate mission-critical navigation systems from mass-market orientation sensing, with industrial automation occupying the mid-tier precision band.
- Automotive Navigation:Dead-reckoning systems fuse magnetometer, accelerometer, and gyroscope data for tunnel and urban canyon positioning. Tier-one suppliers in Germany bundle triple-redundant magnetic heading references to satisfy EU AI Act autonomous vehicle requirements.
- Industrial Automation:Factory robotics demand medium-precision field sensing for end-effector positioning and magnetic encoder feedback. Japanese machine builders specify AMR-based proximity detection for collaborative robot safety zones.
- Geophysical Surveys:Aeromagnetic and marine exploration contracts drive demand for vector magnetometer arrays. Survey operators in Canada and Australia deploy airborne fluxgate systems for mineral exploration targeting rare earth deposits.
- Consumer Electronics:Smartphone compass fusion and wearable motion tracking pull low-power Hall effect designs into billion-unit annual scales. Design wins concentrate with Apple and Samsung flagship devices.
Revenue margins peak in geophysical surveys; consumer electronics delivers volume scale that amortizes R&D across massive unit shipments.
End User:
Customer procurement sophistication ranges from defense specification rigor to healthcare's clinical validation requirements.
- Aerospace:Satellite attitude control and unmanned aerial vehicle navigation demand radiation-hardened magnetometer modules. NASA and ESA qualification protocols extend development timelines but lock in decade-long supply agreements.
- Automotive:EV powertrain integration requires fault-tolerant magnetic feedback for motor commutation and battery management. China's dual carbon goals are accelerating captive sourcing from domestic foundries to reduce import dependency.
- Healthcare:Magnetocardiography and fetal magnetoencephalography applications depend on SQUID sensor sensitivity where cryogenic infrastructure is available. Tertiary medical centers in Germany and the United States host the primary installed systems.
- Defense:Magnetic anomaly detection for submarine surveillance and unexploded ordnance location commands the highest precision tiers. Procurement flows through national security channels in the United States, United Kingdom, and Japan with ITAR and comparable export controls.
Defense contracts anchor the premium price band; automotive electrification is climbing the fastest as EV platform volumes compound.
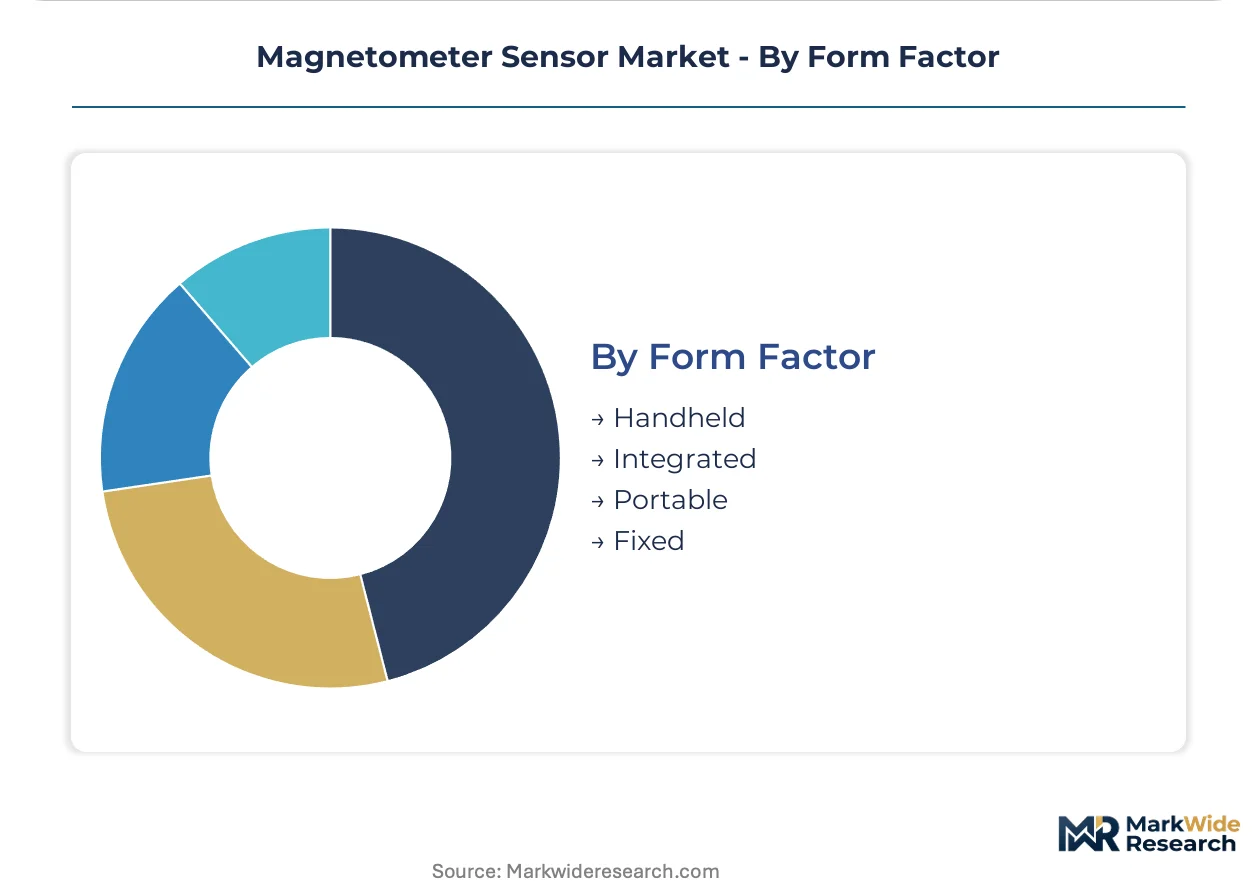
Form Factor:
Physical integration constraints dictate whether magnetometers ship as standalone instruments or embedded subcomponents.
- Handheld:Battery-powered units serve field geologists and utility technicians requiring portable magnetic field mapping. Archaeological survey teams in Italy and Greece deploy handheld fluxgate systems for subsurface feature detection.
- Integrated:Die-level or package-level magnetometers embed within larger sensor hubs or microcontroller platforms. STMicroelectronics and Bosch Sensortec dominate smartphone and wearable design wins through 6-axis and 9-axis fusion modules.
- Portable:Ruggedized enclosures protect precision sensors for mobile laboratory and temporary monitoring deployments. Environmental agencies in France utilize portable magneto-optical systems for power line corona discharge assessment.
- Fixed:Permanent installations support geomagnetic observatories, space weather monitoring stations, and industrial process control. INTERMAGNET network standards govern interoperability for scientific installations across 40+ countries.
Fixed installations dominate scientific infrastructure spending; integrated form factors are gaining share fastest as IoT edge devices proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium and dysprosium refining capacity in China's Inner Mongolia and Jiangxi provinces anchors raw material availability for fluxgate core production. This geographic concentration shapes magnetometer supply security calculations across automotive and defense procurement offices worldwide.
China
Domestic EV makers BYD and NIO are captive-sourcing AMR and fluxgate sensors from local foundries to reduce import dependency for magnetic sensing subsystems. MIIT's dual carbon goals are tightening performance standards for electrified powertrain components. Yangtze River Delta clusters in Suzhou and Wuxi host scaling production lines serving both local automotive demand and export markets.
Germany
Bosch and Continental are bundling triple-redundant magnetic heading references to satisfy EU AI Act autonomous vehicle requirements. KBA safety mandates are accelerating ISO 26262 functional safety certification timelines for automotive-grade sensors. Baden-Württemberg's Stuttgart region concentrates R&D intensity for low-power Hall effect designs in industrial automation.
United States
NASA and Department of Defense procurement channels are extending development timelines for radiation-hardened magnetometer modules but locking in decade-long supply agreements. NHTSA safety mandates are driving magnetometer integration into EV platforms and advanced driver-assistance systems. Greater Boston hosts SQUID sensor research hospitals where cryogenic infrastructure supports medical imaging applications.
Japan
METI's industrial automation incentives are pulling AMR-based proximity detection into collaborative robot safety zones. Keiretsu-style supply structures are yielding to audit-driven vendor pools with multi-source qualification mandates. Kansai's Osaka-Kyoto corridor concentrates machine builder demand for medium-precision field sensing in factory robotics.
India
PLI scheme electronics manufacturing incentives are attracting magnetometer packaging and test operations to serve domestic automotive and industrial automation demand. CEA grid modernization programs are specifying magneto-optical sensors for utility-scale inverter monitoring. Tamil Nadu's Sriperumbudur electronics cluster is emerging as a preferred location for Hall effect sensor module assembly.
Magnetometer Sensor Market Competitive Landscape
Global majors compete with regional champions across technology integration and certification depth. The vendor base separates into three tiers: aerospace-defense heritage suppliers commanding premium fluxgate segments, automotive-integrated semiconductor houses bundling magnetic sensors with microcontroller platforms, and Asian component specialists scaling cost-optimized Hall effect production. Consolidation pressure is intensifying around functional safety certification capabilities and multi-axis sensor fusion firmware expertise. Dominant competitive moves include strategic partnerships for ISO 26262 qualification acceleration and geographic expansion into India's PLI-subsidized manufacturing zones.
Within the aerospace-defense heritage tier, Honeywell International exemplifies precision fluxgate positioning for submarine navigation and geophysical mapping applications. Among European automotive-integrated suppliers, NXP Semiconductors and STMicroelectronics occupy positions where magnetic sensor solutions bundle with broader microcontroller and sensor hub portfolios. These three companies represent distinct archetypes: heritage precision instrumentation, automotive silicon integration, and consumer-industrial convergence.
| Leading Market Players |
|---|
| Honeywell International |
| NXP Semiconductors |
| Allegro MicroSystems |
| Asahi Kasei |
| Infineon Technologies |
| TDK Corporation |
| STMicroelectronics |
| Robert Bosch |
| NVE Corporation |
| Others |
Supply & Pricing Matrix
Neodymium and dysprosium refining costs cascade through fluxgate magnetometer production tiers, with Yangtze River Delta foundries passing rare earth volatility to automotive Tier-1s through long-term offtake contracts indexed to Chinese spot markets. This input-cost architecture stratifies final pricing across ISO 26262-certified automotive grades, industrial automation mid-tiers, and consumer electronics economy segments.
Pricing Analysis
Warranty and calibration service bundling separate premium fluxgate vendors from unbundled Hall effect commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with ISO 26262 ASIL-D ratings commanding substantial premiums over uncertified industrial grades. Cost compression in consumer electronics Hall effect modules is intensifying because smartphone OEMs are consolidating design wins toward single-source sensor hub integrators. Automotive OEMs exhibit lowest price sensitivity due to functional safety liability exposure, while wearable device makers operate at highest cost elasticity.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for magnetometer packaging and test operations previously concentrated in China. Raw material dependencies center on rare earth refining in Inner Mongolia and Jiangxi provinces, silicon wafer supply from Taiwan and South Korea, and specialized epoxy substrates from Japan. Single-source vulnerability in Chinese rare earth processing creates structural risk for fluxgate core availability. Distribution runs through direct OEM contracts for automotive volumes and authorized distributors for industrial replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around functional safety certification capabilities, with ISO 26262 qualification timelines forcing sub-scale competitors toward exit or acquisition.
For Market Incumbents: Extend certification depth into triple-redundant magnetic heading architectures demanded by EU AI Act autonomous vehicle requirements. Deepen backward integration into rare earth alloy sourcing through offtake agreements with Chinese refiners to defend margin position against AMR-TMR technology substitution threats.
For New Entrants and Emerging Players: The premium-economy price-point gap in industrial automation magnetometers offers white-space entry below Honeywell fluxgate positioning and above commodity Hall effect tiers. Target India's PLI-subsidized electronics manufacturing clusters where packaging and test capabilities are scaling fastest. Pursue design-win partnerships with domestic Indian automotive Tier-2s supplying Mahindra and Tata Motors EV platforms.
For Investors and Strategic Acquirers: Accelerated multi-source qualification mandates from Bosch and Continental are the leading indicator that ISO 26262-certified magnetic sensor firmware assets will command scarcity premiums. Position acquisition screening toward mid-cap specialists with existing automotive safety certification and trapped engineering talent in sensor fusion algorithms. Watch for Tier-1 supplier consolidation announcements as the inflection signal for rollup timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 Certification Acceleration | Unlocks automotive Tier-1 design wins under KBA and NHTSA safety mandates. |
| Rare Earth Supply Agreement | Secures fluxgate core material allocation from Jiangxi and Inner Mongolia refiners. |
| AMR-TMR Technology Fusion | Opens grid-scale inverter current sensing specifications from CEA and European utilities. |
| India PLI Manufacturing Footprint | Captures cost advantages for Hall effect module assembly serving domestic automotive demand. |
| Triple-Redundant Sensor Architecture | Meets EU AI Act autonomous vehicle redundancy requirements for magnetic heading systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with automotive Tier-1 procurement officers, fluxgate design engineers, semiconductor foundry operations managers, and industrial automation OEM technical directors. Bottom-up sensor shipment estimates triangulated against top-down EV platform production forecasts from vehicle registration databases and MIIT production disclosures.
Data-stream reconciliation across technology type, application vertical, end-user sector, and form factor dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by average selling price evolution, incorporating rare earth cost pass-through assumptions and certification premium persistence for automotive safety tiers.
Inputs from Chinese customs records and German KBA type-approval databases were available through the study window; gaps in SQUID sensor hospital procurement data introduce uncertainty bands around medical imaging segment sizing. Forecasts reflect documented assumptions regarding EV platform ramp schedules and dual carbon policy implementation intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
RTD Temperature Sensors Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Air Particle Monitor System Market
Sensors and Controls
Condition Monitoring System Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Photodiode Sensors Market
Sensors and Controls
Flow Sensor Market
Sensors and Controls
Capacitive Pressure Sensor Market
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
Wireless Ph Monitoring Systems Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Asia Pacific Safety I/O Modules Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market