
 Global Nanosensors Market | 2026-2036
Global Nanosensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nanosensors Market Outlook
The EU Green Deal is hardening demand for emissions-monitoring nanosensors across European industrial facilities. Honeywell International Inc. leverages its sensing portfolio to anchor positions in environmental compliance systems. Agilent Technologies Inc. specializes in laboratory-grade optical nanosensors for pharmaceutical quality control. IBM Corporation navigates quantum-dot architectures for next-generation diagnostic platforms.
Nanosensors are devices engineered at the nanoscale, typically 1-100 nanometers, that detect physical, chemical, or biological stimuli with signal-to-noise ratios unattainable by conventional sensors; carbon nanotube and graphene substrates enable electrochemical detection limits in the parts-per-trillion range for industrial safety and clinical diagnostics. Optical sensors dominate current revenue pools due to mature semiconductor fabrication compatibility, while biological sensors represent the fastest-expanding segment as CRISPR-integrated nanoprobes enter clinical validation. Quantum dot technology commands premium positioning in medical diagnostics where photostability requirements exceed organic fluorophore capabilities.
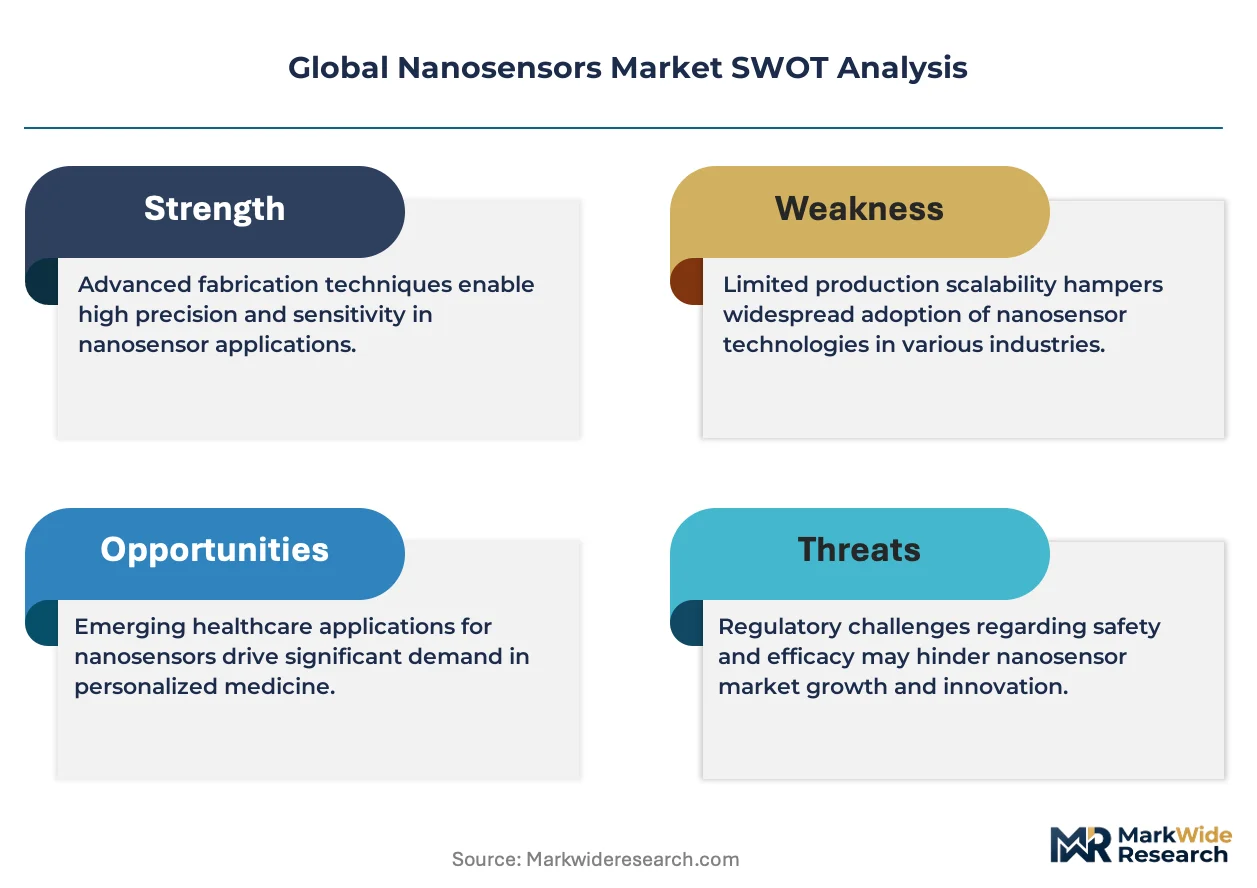
FDA clearance pathways for in-vivo nanosensor implants are tightening biocompatibility documentation requirements in the United States, while REACH compliance in Europe restricts certain nanomaterial formulations in consumer-facing applications. China's NMPA has issued draft guidelines on nanomaterial characterization for medical devices, creating dual-track regulatory complexity for multinational suppliers. Stakeholders must monitor convergence between EPA air-quality standards and ISO 10993 biocompatibility protocols as cross-industry certification demands intensify.
Market Dynamics
Point-of-care diagnostic networks are hardening demand for electrochemical nanosensor substrates, while REACH compliance in Europe and FDA biocompatibility pathways in the United States are compressing formulation choices for multinational suppliers.
Growth Catalysts
- EU Green Deal emissions mandates:Industrial facilities across Germany, France, and the Netherlands are retrofitting stacks with chemical nanosensors to meet binding carbon-monitoring requirements.
- CRISPR-integrated nanoprobes:Clinical validation pipelines in oncology and infectious disease are accelerating biological sensor segment expansion.
- Germany's industrial automation corridor:Concentrated demand from automotive and precision manufacturing clusters is anchoring carbon nanotube sensor deployment.
Market Restraints
- High-purity graphene supply concentration:Synthesis capacity clusters in China and South Korea, creating input cost volatility for electrochemical sensor manufacturers.
- ISO 10993 biocompatibility documentation:Extended validation timelines for in-vivo implants are stretching FDA clearance pathways beyond thirty-six months.
- Organic fluorophore substitution threat:Lower-cost alternatives constrain quantum dot pricing power in non-photostability applications.
Strategic Opportunities
- India's pharmaceutical quality control expansion:CDSCO tightening of active ingredient purity standards is opening laboratory-grade optical nanosensor demand.
- Quantum-dot and AI convergence:Machine learning-enhanced signal processing is enabling real-time diagnostic interpretation at point-of-care.
- Japan's METI carbon-neutrality incentives:Subsidies for industrial sensor retrofits are accelerating chemical nanosensor adoption in steel and chemical processing.
Industry Challenges
- Cross-functional nanofabrication talent scarcity:Simultaneous mastery of semiconductor lithography and biological functionalization commands premium compensation.
- Dual-track regulatory complexity:China's NMPA draft nanomaterial guidelines force parallel documentation streams distinct from FDA and EMA requirements.
- Legacy system integration friction:Hospital IT infrastructure in the United States and Europe requires custom middleware for nanosensor data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nanosensors Market |
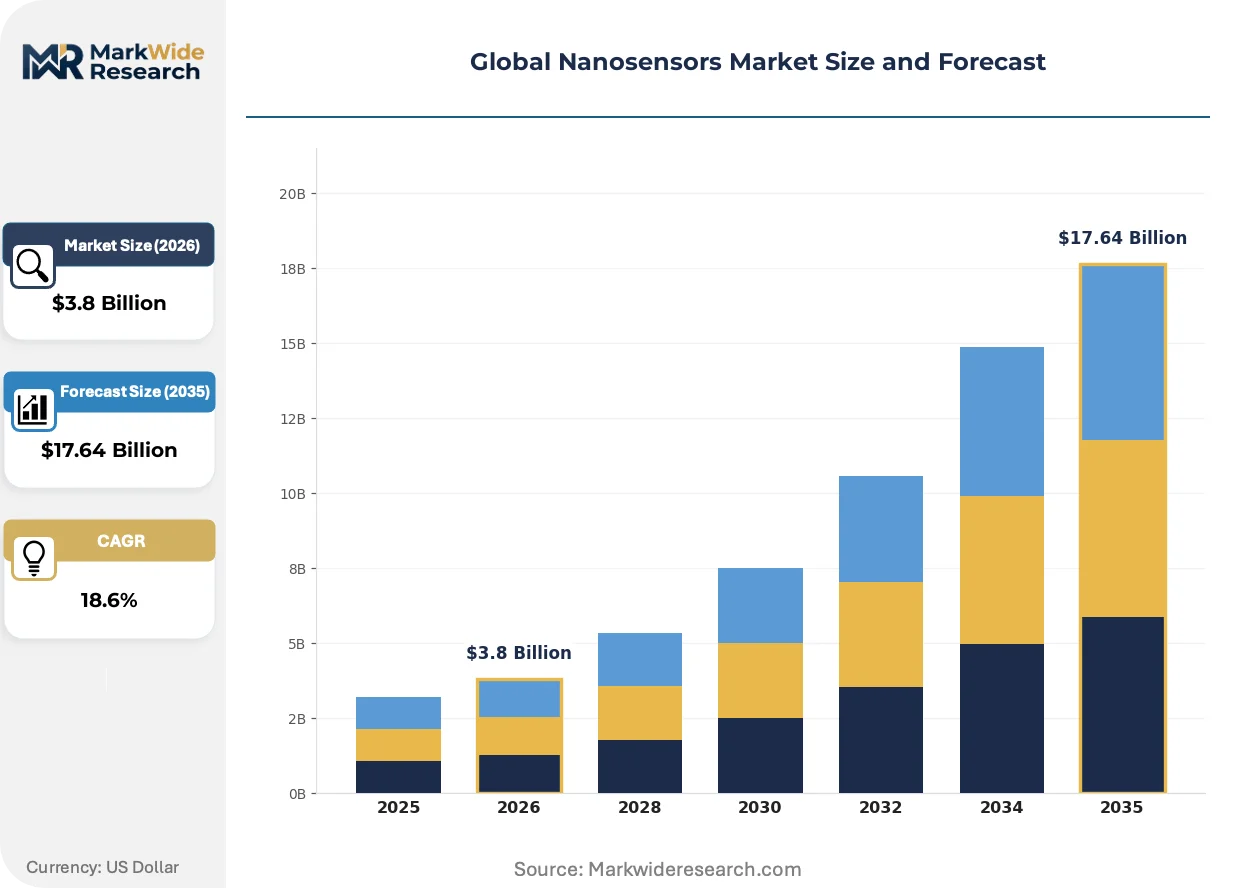
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Sensors, Optical Sensors, Biological Sensors, Mechanical Sensors Technology: Carbon Nanotubes, Quantum Dots, Graphene, Nanowires Application: Environmental Monitoring, Medical Diagnostics, Food Safety, Industrial Automation End User: Healthcare, Manufacturing, Agriculture, Defense |
| Companies Covered | Honeywell International Inc., Agilent Technologies Inc., Analog Devices Inc., OMRON Corporation, Texas Instruments Incorporated, Bruker Corporation, Samsung Electronics, Lockheed Martin Corporation, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nanosensors Market Strategic Shifts
Photostability requirements in medical diagnostics are compressing organic fluorophore viability, while regulatory convergence between environmental and biocompatibility standards is reshaping certification strategies.
Graphene-based electrochemical substrates are absorbing detection limit requirements previously served by carbon nanotubes. Pharmaceutical manufacturers in Switzerland and the United States are adopting these substrates for parts-per-trillion contaminant screening. The shift is absorbing market share from legacy optical methods in quality control applications.
REACH restrictions on certain nanomaterial formulations are forcing reformulation of consumer-facing sensor products in Europe. Industrial suppliers are redirecting affected chemistries toward medical device applications where exposure pathways differ. Germany's chemical processing sector is responding fastest, with facilities completing compliance audits ahead of enforcement deadlines.
Hospital procurement committees are consolidating vendor relationships around integrated diagnostic platforms rather than standalone sensor components. Point-of-care networks in the United States are replacing fragmented purchasing with multi-year service agreements bundling hardware, calibration, and data analytics. The concentration is most visible in cardiology and oncology verticals where downtime costs exceed equipment price differentials.
Global Nanosensors Market Segmentation
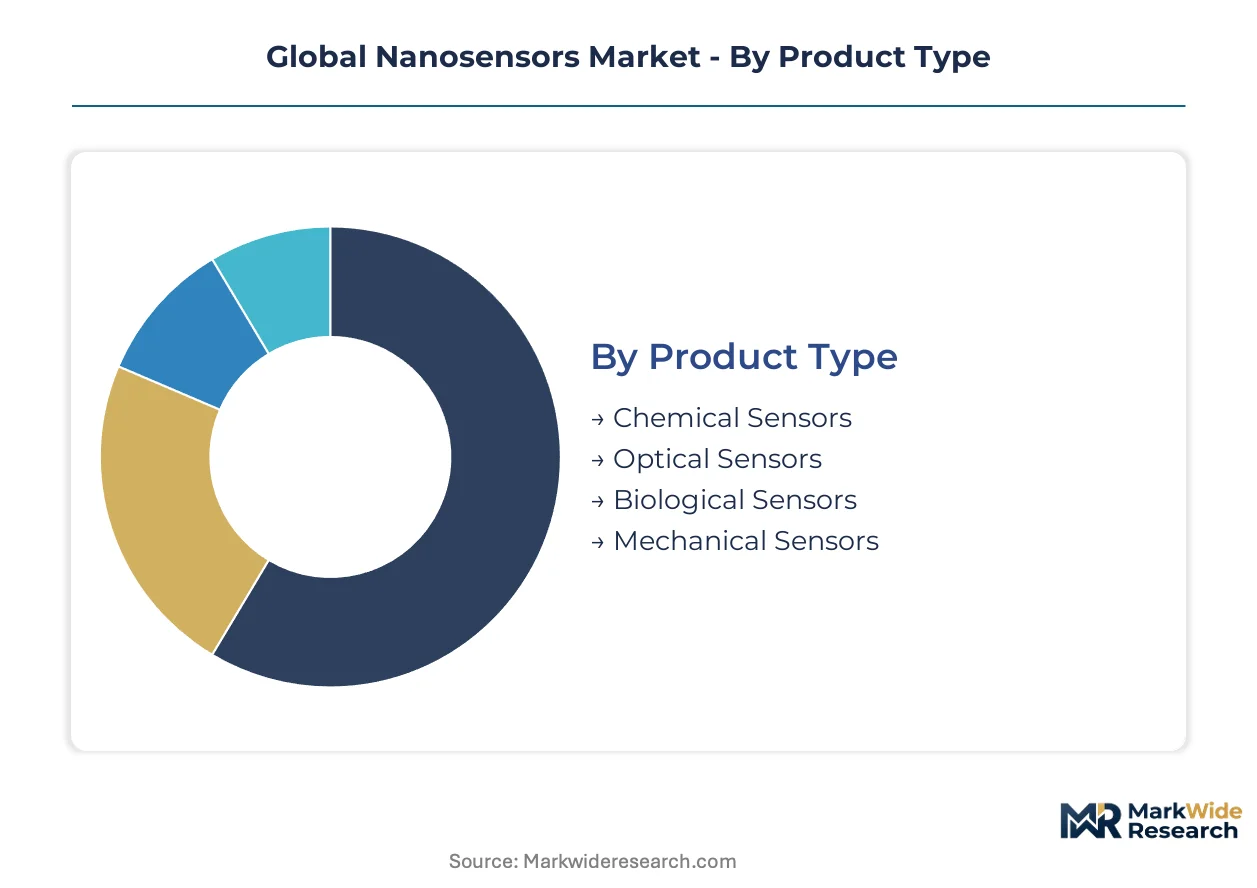
Nanosensor procurement patterns diverge sharply across end-use contexts. Buyers prioritize detection limits in pharmaceutical quality control, response speed in point-of-care networks, and cost resilience in emissions monitoring installations.
Product Type:
End-users select substrates based on signal-to-noise requirements and biocompatibility constraints rather than unit economics alone.
- Chemical Sensors:Electrochemical architectures detect gas-phase contaminants at parts-per-trillion thresholds. Germany's industrial automation corridor anchors concentrated demand as EU Green Deal mandates harden emissions documentation requirements.
- Optical Sensors:Semiconductor fabrication compatibility drives mature supply chains and volume pricing. Hospital procurement committees in the United States bundle these into multi-year diagnostic platform agreements spanning cardiology and oncology verticals.
- Biological Sensors:CRISPR-integrated nanoprobes entering clinical validation pipelines.
- Mechanical Sensors:Strain-sensitive nanostructures deployed in precision manufacturing feedback loops.
Optical sensors lead volumes today; biological sensors are gaining share fastest.
Technology:
Material selection locks manufacturers into specific fabrication equipment and regulatory documentation pathways.
- Carbon Nanotubes:Established electrochemical detection substrates with proven REACH compliance pathways. Japan's METI carbon-neutrality incentives accelerate retrofit demand in steel and chemical processing facilities.
- Quantum Dots:Photostable fluorophores commanding premium positioning where organic alternatives fail. FDA clearance pathways for in-vivo diagnostic platforms require extended biocompatibility validation timelines.
- Graphene:Absorbing detection limit requirements from legacy carbon nanotube applications in pharmaceutical screening.
- Nanowires:Field-effect transistor configurations for ultra-low power wearable diagnostics.
Carbon nanotubes dominate current procurement volumes; quantum dots show the steepest expansion trajectory in medical diagnostics.
Application:
Regulatory enforcement intensity varies dramatically across monitoring contexts, shaping buyer urgency and budget allocation.
- Environmental Monitoring:Stack-mounted chemical sensors retrofitted under binding carbon-monitoring requirements. Facilities across France and the Netherlands complete compliance audits ahead of enforcement deadlines.
- Medical Diagnostics:Point-of-care networks consolidating around integrated platforms rather than standalone components. India's CDSCO tightening of active ingredient purity standards opens laboratory-grade optical nanosensor demand.
- Food Safety:Pathogen detection at processing plant intake points.
- Industrial Automation:Real-time process control in automotive precision manufacturing clusters.
Environmental monitoring absorbs the largest capital deployment; medical diagnostics is climbing the fastest.
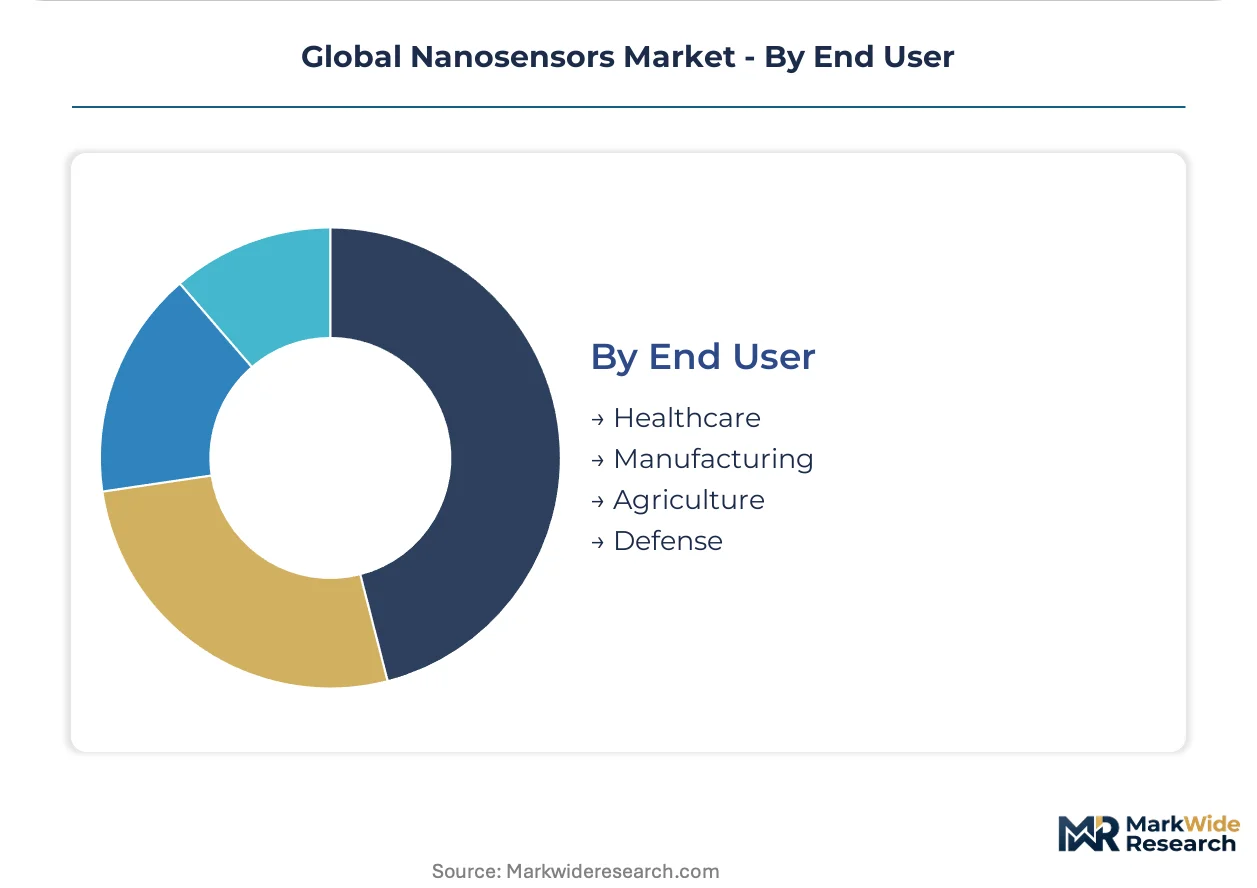
End User:
Budget cycles and procurement authority structures determine sales cycle length and contract configuration.
- Healthcare:Hospital IT infrastructure requires custom middleware integration. Procurement committees favor bundled hardware-calibration-analytics agreements over component sourcing.
- Manufacturing:Automotive and precision engineering clusters in Germany's industrial corridor drive carbon nanotube sensor deployment for quality assurance.
- Agriculture:Soil and livestock monitoring applications with emerging biosensor demand.
- Defense:Chemical and biological threat detection with specialized durability specifications.
Manufacturing leads current end-user spending; healthcare is expanding most quickly as point-of-care networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nanosensor technology first achieved commercial scale in United States semiconductor fabrication facilities during the 1990s, with subsequent expansion into German automotive quality control and Japanese precision manufacturing. The current geographic distribution reflects this legacy: mature optical sensor supply chains cluster in North American and European industrial corridors, while electrochemical substrate production concentrates in East Asian materials science hubs.
United States
FDA clearance pathways for in-vivo nanosensor implants are tightening biocompatibility documentation requirements, stretching validation timelines beyond thirty-six months. Hospital procurement committees in cardiology and oncology verticals are consolidating around bundled hardware-calibration-analytics agreements rather than standalone component sourcing. Greater Boston and the Pacific Northwest anchor concentrated demand from point-of-care diagnostic network expansion.
Germany
The EU Green Deal's binding carbon-monitoring mandates are accelerating chemical nanosensor deployment across industrial facilities in the automotive and precision manufacturing sectors. REACH compliance restrictions on certain nanomaterial formulations are forcing reformulation of consumer-facing sensor products, with affected chemistries redirecting toward medical device applications. The industrial automation corridor spanning Bavaria and Baden-Württemberg anchors concentrated carbon nanotube sensor demand from quality assurance retrofit programs.
China
NMPA draft guidelines on nanomaterial characterization for medical devices are creating dual-track regulatory complexity for multinational suppliers operating parallel documentation streams. High-purity graphene synthesis capacity clusters domestically, supplying electrochemical sensor manufacturers with substrate materials capable of parts-per-trillion detection limits. The Yangtze River Delta and Pearl River Delta regions concentrate both production capacity and domestic demand from environmental monitoring infrastructure investment.
Japan
METI carbon-neutrality incentives are subsidizing industrial sensor retrofits across steel and chemical processing facilities, accelerating chemical nanosensor adoption in emissions monitoring applications. Field-effect transistor configurations using nanowire architectures are gaining traction in ultra-low power wearable diagnostic development. The Chubu region around Nagoya and the Kansai industrial belt anchor precision manufacturing demand for strain-sensitive nanostructures in real-time process control.
India
CDSCO tightening of active ingredient purity standards is opening laboratory-grade optical nanosensor demand from pharmaceutical quality control expansion. Domestic manufacturing incentives are attracting component assembly operations serving both domestic diagnostic network growth and export markets. Maharashtra and Gujarat anchor concentrated demand from contract research organizations and active pharmaceutical ingredient manufacturers upgrading contaminant screening capabilities.
Global Nanosensors Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology sophistication and regulatory certification depth. The vendor base stratifies into three tiers: diversified industrial conglomerates with sensing portfolios, specialized instrumentation houses with laboratory-grade optical platforms, and materials-science-driven substrate specialists. Consolidation pressure is intensifying as hospital procurement committees demand integrated diagnostic platforms rather than fragmented component sourcing. Dominant competitive moves include strategic partnerships bridging semiconductor fabrication with biological functionalization capabilities, and geographic expansion into India's pharmaceutical quality control market.
Within the diversified industrial tier, Honeywell International Inc. and Lockheed Martin Corporation exemplify archetypes spanning environmental compliance systems and specialized durability specifications respectively. Agilent Technologies Inc. occupies a position among laboratory-grade instrumentation specialists, while IBM Corporation sits within the quantum-architecture frontier. Samsung Electronics represents the scale-driven electronics integration archetype. These anchors collectively illustrate the competitive tension between breadth of sensing portfolio and depth of substrate-level materials science mastery.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Agilent Technologies Inc. |
| Analog Devices Inc. |
| OMRON Corporation |
| Texas Instruments Incorporated |
| Bruker Corporation |
| Samsung Electronics |
| Lockheed Martin Corporation |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committee consolidation around bundled diagnostic platforms is compressing component-level pricing power and forcing substrate suppliers toward multi-year service contract structures that embed calibration and analytics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates photostable quantum dot substrates from carbon nanotube electrochemical sensors and commodity graphene formulations. Certification grade under FDA clearance pathways and ISO 10993 biocompatibility documentation tiers drive spreads between medical and industrial applications. Cost compression in standard-tier optical sensors is intensifying because organic fluorophore substitution threats constrain quantum dot pricing power outside photostability-critical diagnostics. Emissions monitoring installations in Germany's industrial corridor show least price sensitivity due to binding EU Green Deal compliance deadlines, while point-of-care networks in India face acute budget constraints.
Supply Chain Analysis
Freight cost volatility from East Asian materials hubs to European and North American fabrication facilities is amplifying landed cost differentials for high-purity graphene and carbon nanotube substrates. Synthesis capacity clusters in China and South Korea, with secondary nodes in Japan and the United States, anchor electrochemical sensor feedstock supply. Raw material dependencies span high-purity graphite precursors, rare-earth quantum dot precursors, and semiconductor-grade silicon substrates. Single-source vulnerability concentrates in Chinese graphene production for parts-per-trillion detection applications. Distribution runs through specialized chemical distributors serving pharmaceutical quality control labs and direct OEM supply agreements for industrial automation integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Nanosensors Market functions as a stable compounder anchored by regulatory enforcement intensity that mandates sensor deployment regardless of macroeconomic cycles.
For Market Incumbents: Lock in long-term supply agreements with Chinese and South Korean graphene synthesis facilities before capacity constraints tighten. Deepen backward integration into carbon nanotube purification to defend margin position against emerging substrate specialists. Prioritize ISO 10993 documentation investment to extend FDA clearance moats beyond thirty-six-month validation timelines that entrench incumbent advantages. For New Entrants and Emerging Players: Begin with India's pharmaceutical quality control expansion where CDSCO tightening of active ingredient purity standards opens laboratory-grade optical nanosensor demand underserved by established instrumentation houses. Target agricultural soil and livestock monitoring applications where biosensor requirements remain nascent and specification standards are fluid. Deploy software-enhanced signal processing as the primary go-to-market angle to differentiate commodity hardware. For Investors and Strategic Acquirers: Asymmetric upside sits with materials-science-driven substrate specialists possessing simultaneous semiconductor lithography and biological functionalization capabilities. Five-to-ten-year viability hinges on regulatory certification depth rather than volume scale alone. Watch for convergence between EPA air-quality standards and ISO 10993 biocompatibility protocols as the inflection signal that rewards cross-industry certification investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphene Synthesis | Captures margin from Chinese supply concentration and stabilizes input costs for electrochemical sensor production. |
| Hospital System Partnership | Secures multi-year bundled agreements in United States cardiology and oncology verticals ahead of procurement committee consolidation. |
| CE Marking Pathway Investment | Accelerates EU Green Deal compliance product positioning for German industrial automation corridor demand. |
| Software Companion Development | Enables machine learning-enhanced diagnostic interpretation that differentiates quantum dot platforms from organic fluorophore alternatives. |
| Joint Venture with Indian CROs | Captures CDSCO-driven pharmaceutical quality control expansion in Maharashtra and Gujarat contract research clusters. |
Study Parameters
Multiple input streams — primary interviews with biomedical engineers and hospital GPO contracts managers, secondary validation through FDA 510(k) filings and EMA medical device registrations, and customs trade data on nanomaterial imports — were reconciled through bottom-up and top-down triangulation. Conversations with semiconductor fabrication specialists, pharmaceutical quality control directors, and industrial automation procurement leads informed substrate demand assumptions. Secondary sources included ISO certification databases, REACH compliance filings, and NMPA draft guideline releases.
Data-stream reconciliation across product type, technology material, application context, and end-user procurement authority produced volume and value outputs across the projection horizon. Segmentation dimensions modeled encompassed detection limit tier, biocompatibility certification status, regional regulatory cluster, and vertical integration depth. CAGRs were derived from installed base expansion rates and replacement cycle analysis specific to emissions monitoring retrofit timelines and point-of-care network buildouts. Industry-specific forecast inputs incorporated EU Green Deal enforcement phase-ins and METI carbon-neutrality subsidy disbursement patterns.
Several conditions sit outside the modeled scope, including unforeseen nanomaterial toxicity findings that could trigger REACH restrictions, breakthrough organic fluorophore photostability improvements that displace quantum dot demand, and geopolitical disruptions to Chinese graphene export flows. Forecasts reflect documented assumptions about regulatory timeline adherence and hospital procurement consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
China Sensors Market
Sensors and Controls
RTD Temperature Sensors Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
Distributed Fiber Optic Sensing Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Smart Hydrophone Market
Sensors and Controls
Level Measuring Equipment Market
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Gesture Control Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
Aeroderivative Sensor Market