
 Global Wireless Sensors Market | 2026-2036
Global Wireless Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Sensors Market Foresight
East Asian semiconductor foundry capacity is realigning toward wireless sensor silicon production. Honeywell International Inc. leverages its aerospace heritage to dominate high-reliability pressure sensing for aviation applications. Bosch Sensortec GmbH anchors consumer-grade inertial measurement units with MEMS fabrication scale that competitors struggle to match. Texas Instruments Incorporated sustains RF front-end integration leadership through proprietary low-power transceiver architectures.
Wireless sensors are self-contained measurement nodes that combine a sensing element, signal conditioning circuitry, microprocessor, and radio transceiver to transmit data without physical cabling, typically operating on sub-1 GHz or 2.4 GHz ISM bands with battery lives extending 5–10 years through duty-cycled sleep protocols. Their primary purpose is enabling distributed monitoring in locations where wired infrastructure proves impractical, costly, or hazardous to install. Temperature and pressure sensor types command the largest installed base due to universal applicability across process industries, while LoRaWAN and NB-IoT technology segments are expanding fastest where cellular coverage or unlicensed spectrum supports long-range, low-bitrate telemetry at minimal infrastructure cost. Smart manufacturing applications concentrate margin pools through high-volume enterprise contracts, whereas precision agriculture remains fragmented across regional equipment dealers.
The FCC in the United States governs spectrum allocation for unlicensed sensor transmissions under Part 15 rules, while the EU AI Act and CE marking requirements under the MDR framework shape product compliance pathways for European deployments. China's MIIT enforces GB standards for short-range radio devices that manufacturers must satisfy for market access. Stakeholders must monitor evolving spectrum harmonization negotiations between regulators, as divergent national frequency assignments threaten interoperability and scale economies for multinational sensor networks.
Market Dynamics
Industrial IoT deployments are compressing sensor procurement cycles as smart manufacturing mandates from the EU Green Deal and China's dual carbon goals force simultaneous digitization across multiple sectors.
Growth Catalysts
- EU Green Deal mandates:Digitalization requirements for industrial decarbonization are mandating sensor networks for energy monitoring across German, French, and Italian process industries.
- LoRaWAN spectrum allocation:Unlicensed sub-1 GHz deployments in agricultural and utility telemetry are slashing infrastructure costs for distributed monitoring in remote locations.
- China's eastern manufacturing corridor:Factory automation investments in Jiangsu and Zhejiang provinces are generating concentrated demand for predictive maintenance sensor arrays.
Market Restraints
- MEMS foundry concentration:Taiwan and South Korea dominate silicon wafer processing for inertial measurement units, creating single-source vulnerability for consumer-grade sensor supply.
- Battery chemistry volatility:Lithium-ion cell prices fluctuate with Chilean and Australian mining output, directly impacting 5-10 year maintenance-free sensor cost targets.
- GB standards compliance:China's MIIT certification requirements for short-range radio devices impose 6-12 month market entry delays for foreign manufacturers.
Strategic Opportunities
- India's PLI scheme:Electronics manufacturing incentives are attracting sensor packaging and testing investments to Gujarat and Tamil Nadu industrial zones.
- Energy harvesting convergence:Photovoltaic and thermoelectric power scavenging integrated with ultra-low-power transceivers is eliminating battery dependence in building automation.
- Precision agriculture telemetry:Soil moisture and microclimate monitoring in Brazil's Cerrado and US Midwest grain belts remains underpenetrated by industrial-grade sensor networks.
Industry Challenges
- RF engineering talent scarcity:Sub-1 GHz antenna design and protocol stack optimization skills concentrate in semiconductor hubs, constraining product development velocity outside Shenzhen, Dresden, and Austin.
- CE marking under MDR:Medical device sensor classifications require notified body involvement that extends European commercialization timelines by 8-14 months.
- Legacy SCADA integration:Brownfield industrial sites in North American oil patch and European chemical corridors require protocol translation gateways that add cost and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Sensors Market |
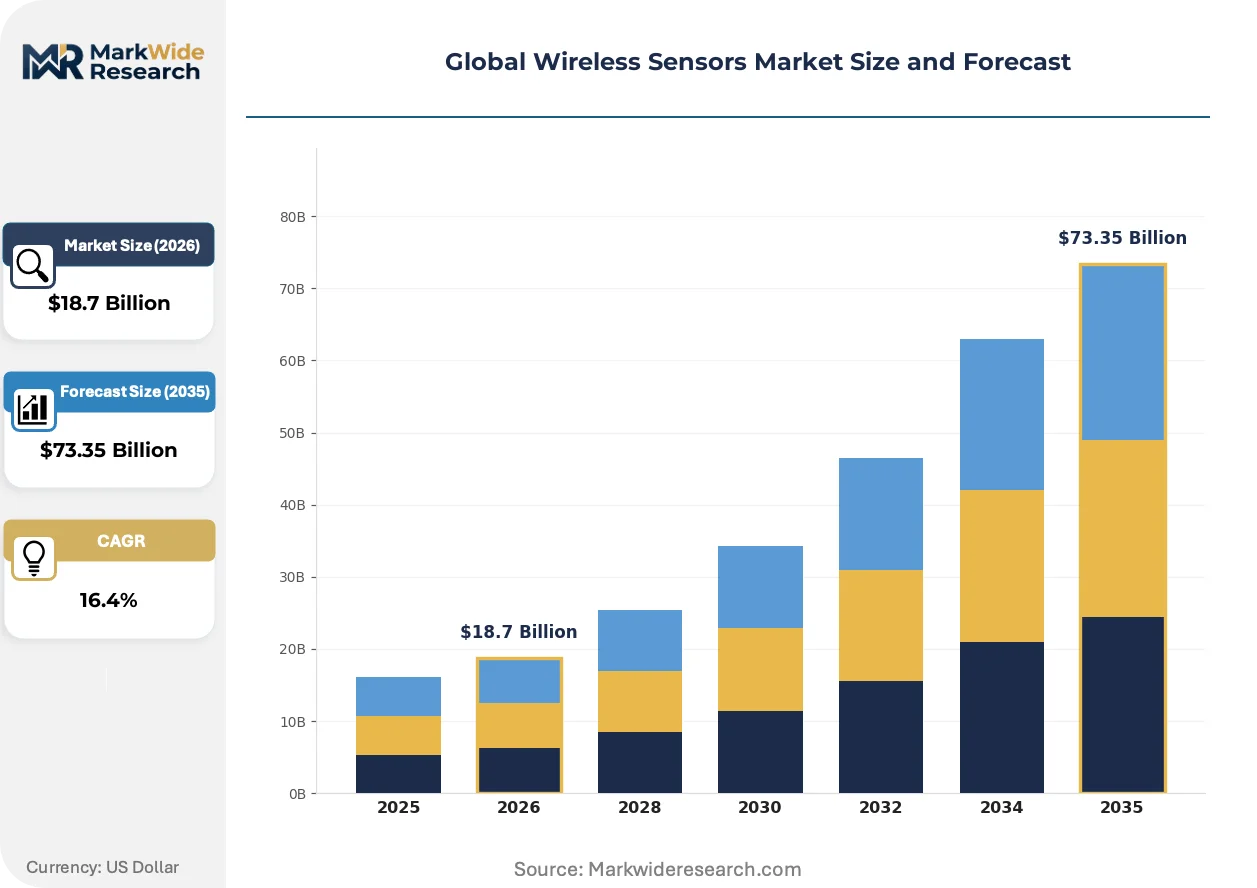
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
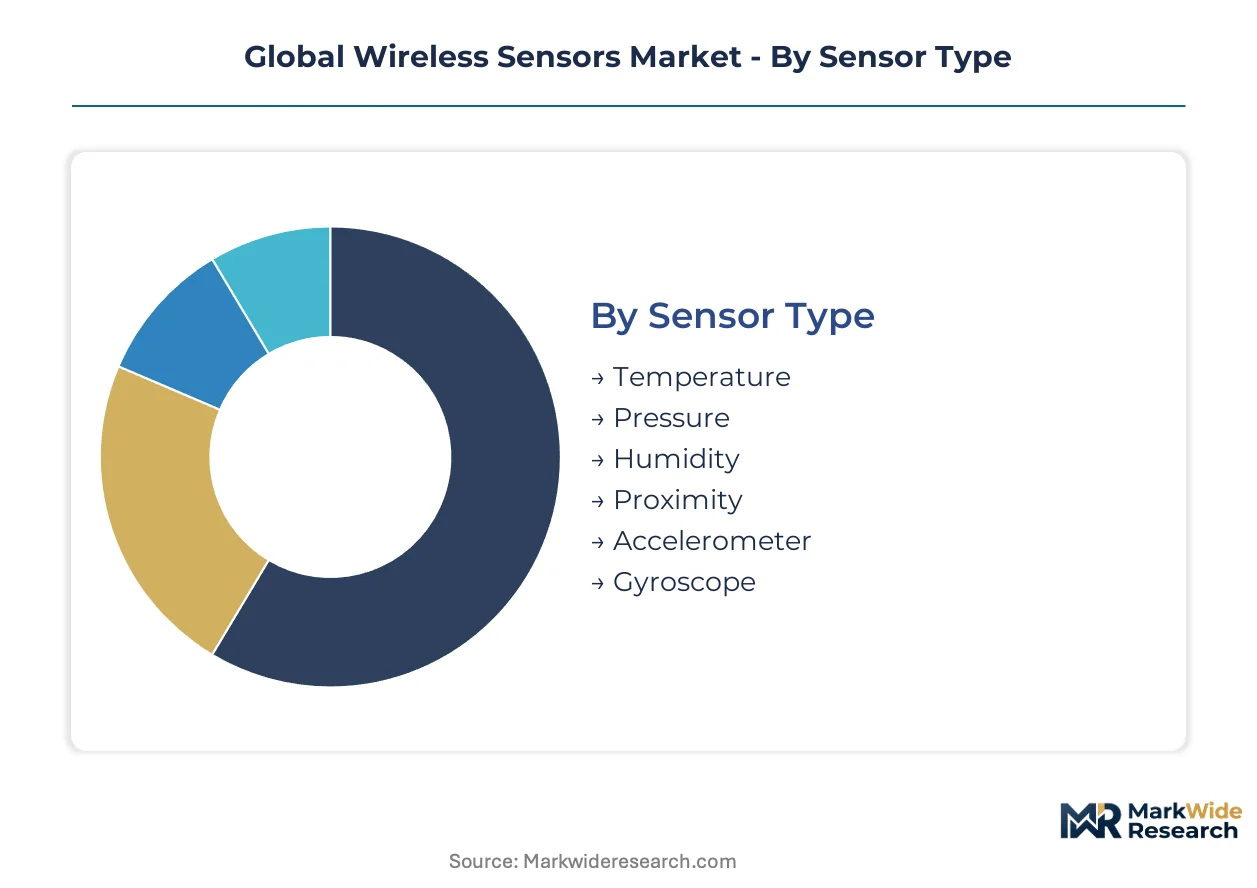
| Segmentation | Sensor Type: Temperature, Pressure, Humidity, Proximity, Accelerometer, Gyroscope Technology: Radio Frequency Identification, Zigbee, Bluetooth, Wi-Fi, LoRaWAN, NB-IoT Application: Smart Manufacturing, Structural Health Monitoring, Precision Agriculture, Energy Management, Traffic Monitoring, Environmental Surveillance End User: Building Automation Firms, Utility Providers, Agricultural Services, Transportation Management Companies, Aerospace Engineering, Food Processing Plants |
| Companies Covered | Emerson Electric Co., ABB, Honeywell International Inc., Analog Devices, Inc., Bosch Sensortec GmbH, Schneider Electric SE, Texas Instruments Incorporated, NXP Semiconductors, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Sensors Market Shifts & Advancements
Edge intelligence migration and energy autonomy are restructuring how sensor networks are architected, shifting computational load from cloud to node while eliminating maintenance cycles.
Multi-protocol radio silicon is modularizing hardware platforms to serve both licensed cellular and unlicensed ISM deployments from common circuit designs. Automotive Tier 1 suppliers and smart building integrators are consolidating vendor lists around these flexible chipsets. This convergence is compressing SKU proliferation and enabling volume pricing leverage for mid-scale manufacturers.
The EU AI Act's risk classification framework is mandating audit trails for sensor data used in automated decision systems across healthcare and critical infrastructure. Industrial OEMs must now implement cryptographic signing at the sensor node to satisfy conformity assessment requirements. German and French medical device manufacturers are prioritizing secure element integration to preempt regulatory rejection.
Buyers in process industries are unbundling sensor hardware from multi-year service contracts, demanding per-node pricing transparency and competitive replacement sourcing. This disintermediation pressures incumbent suppliers who historically captured margin through captive maintenance agreements. The shift is most pronounced in Texas and Alberta oilfield services, where operator procurement teams now specify open protocol requirements in RFPs.
Global Wireless Sensors Market Segmentation
Wireless sensor architectures vary dramatically across sensing modalities, radio protocols, and deployment environments. Procurement teams must match technical specifications to operational constraints—range requirements, power budgets, and data throughput—rather than defaulting to lowest-cost options.
Sensor Type:
Temperature and pressure transducers anchor industrial deployments through universal process applicability, while motion-sensing MEMS devices scale through consumer electronics spillover.
- Temperature:Thermocouple and RTD-based wireless nodes dominate HVAC and cold chain logistics. German chemical processors and Texas oilfield operators specify these for hazardous area compliance where wired infrastructure risks ignition.
- Pressure:Piezoresistive and capacitive sensing elements measure fluid dynamics in pipelines and pneumatic systems. Demand concentrates in Alberta oil sands and North Sea offshore platforms where remote wellhead monitoring eliminates cabling costs.
- Humidity:Capacitive polymer sensors track moisture in pharmaceutical cleanrooms and grain storage silos.
- Proximity:Inductive and ultrasonic variants detect object presence for automated guided vehicles and security perimeters.
- Accelerometer:MEMS devices capture vibration signatures for predictive maintenance on rotating machinery.
- Gyroscope:Angular rate sensors stabilize drones and enable dead-reckoning navigation where GPS fails.
Temperature leads on scale; accelerometer leads on momentum.
Technology:
Radio protocol selection determines infrastructure cost, range, and power autonomy—trade-offs that reshape total cost of ownership across deployment scenarios.
- Radio Frequency Identification:Passive UHF tags harvest interrogator energy for asset tracking without batteries. Retail and logistics operators in the US Midwest deploy these for pallet-level inventory visibility.
- Zigbee:Mesh networking at 2.4 GHz enables self-healing building automation networks. Korean smart apartment developers specify Zigbee 3.0 for lighting and climate control integration.
- Bluetooth:Low Energy 5.x protocols support short-range wearable and beacon applications. Nordic semiconductor ecosystems dominate this segment through protocol stack maturity.
- Wi-Fi:HaLow and traditional 802.11 variants suit high-bandwidth video and audio streaming in surveillance and industrial vision systems.
- LoRaWAN:Sub-1 GHz unlicensed spectrum carries telemetry across 10+ kilometer ranges in agricultural and utility deployments. French water utilities and Brazilian soybean operators standardize on this for irrigation and smart metering.
- NB-IoT:Licensed cellular narrowband serves deep indoor penetration for smart gas meters and structural monitors. Chinese tower infrastructure supports the densest NB-IoT sensor concentrations globally.
LoRaWAN climbs the fastest in rural and remote telemetry; NB-IoT gains share fastest in dense urban cellular coverage.
Application:
End-use verticals impose distinct reliability, latency, and regulatory requirements that filter compatible sensor architectures.
- Smart Manufacturing:Predictive maintenance arrays on CNC machines and conveyor systems demand sub-millisecond vibration sampling. Jiangsu and Zhejiang province factories deploy these at scale under China's dual carbon digitization mandates.
- Structural Health Monitoring:Strain gauges and accelerometers embedded in bridges and dams detect fatigue cracking. Japanese civil engineering consortia lead deployment on seismic-prone infrastructure.
- Precision Agriculture:Soil moisture and microclimate sensors enable variable-rate irrigation. Brazil's Cerrado region and California Central Valley operators are expanding deployments where water scarcity drives efficiency investments.
- Energy Management:Sub-metering sensors disaggregate consumption by circuit and machine. EU Green Deal compliance requirements are accelerating German and Italian industrial facility deployments.
- Traffic Monitoring:Inductive loops and radar sensors feed adaptive signal control in Singapore and Dubai smart city programs.
- Environmental Surveillance:Air quality and water quality sensors support regulatory compliance and public health alerts.
Smart manufacturing dominates revenue concentration; precision agriculture shows steepest expansion trajectory.
End User:
Buyer sophistication and procurement scale fragment the vendor landscape across customer categories.
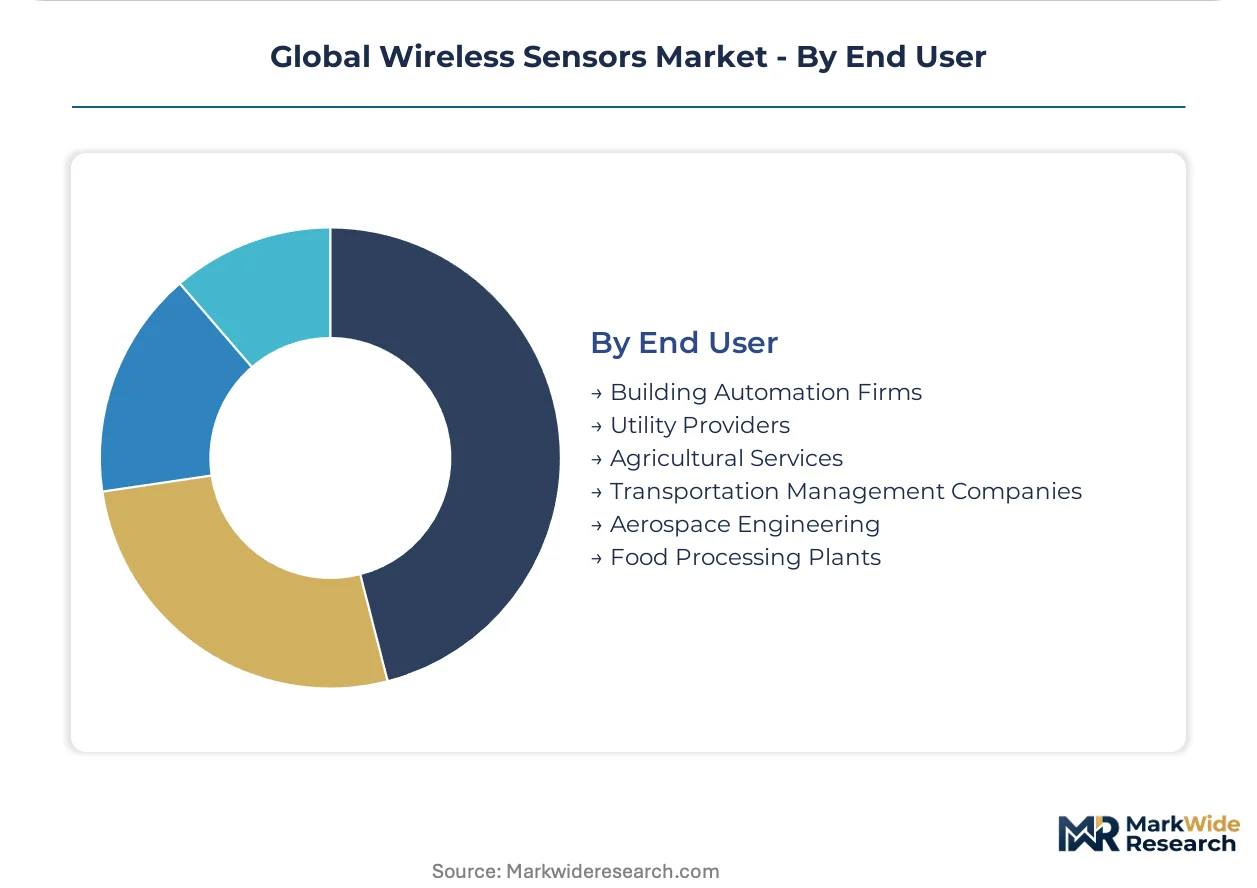
- Building Automation Firms:System integrators specify multi-protocol gateways and unified dashboards. Honeywell and Siemens Building Technologies dominate specification in North American and European commercial real estate.
- Utility Providers:Electric, gas, and water utilities mandate decade-long battery life and IP68 ingress protection. Enel and E.ON European smart grid programs drive volume standardization.
- Agricultural Services:Equipment dealers and co-ops distribute soil and weather sensors to fragmented farming operations.
- Transportation Management Companies:Fleet operators track vehicle health and cargo conditions across distributed logistics networks.
- Aerospace Engineering:FAA and EASA certification requirements impose rigorous environmental testing on avionics sensors.
- Food Processing Plants:HACCP compliance drives cold chain and processing line temperature monitoring with audit trail documentation.
Utility providers anchor volume procurement; building automation firms lead technology integration sophistication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing wireless sensor production maps as manufacturers migrate toward jurisdictions with streamlined certification pathways and concentrated demand clusters. Cost-of-compliance gaps between major economies are accelerating facility relocation decisions.
United States
Industrial IoT deployments in Texas and California oilfields drive demand for hazardous-area certified pressure transmitters. FCC Part 15 spectrum rules govern unlicensed sub-1 GHz and 2.4 GHz transmissions, creating predictable regulatory terrain for sensor vendors. Houston's energy corridor hosts dense concentrations of predictive maintenance sensor arrays on offshore platforms and pipeline networks.
Germany
Smart manufacturing mandates under the EU Green Deal force simultaneous sensor network rollouts across chemical and automotive plants. CE marking under the MDR framework imposes conformity assessment requirements for medical-grade wireless monitors. Baden-Württemberg's industrial belt anchors Europe's densest predictive maintenance sensor deployments on CNC machinery and robotic assembly lines.
China
Factory automation investments in Jiangsu and Zhejiang provinces generate concentrated demand for vibration and temperature monitoring arrays. MIIT enforces GB standards for short-range radio devices that foreign manufacturers must satisfy for market access. The Yangtze River Delta manufacturing corridor hosts the world's largest concentration of industrial wireless sensor procurement contracts.
India
Electronics manufacturing incentives under the PLI scheme attract sensor packaging and testing investments to Gujarat and Tamil Nadu industrial zones. BIS certification requirements shape product compliance pathways for domestic market entry. The Delhi-Mumbai Industrial Corridor is emerging as a hub for building automation sensor integration in commercial real estate developments.
Japan
Structural health monitoring deployments on seismic-prone infrastructure drive demand for accelerometer and strain gauge networks. METI industrial policy supports sensor technology development through targeted R&D programs. The Chubu region around Nagoya anchors automotive Tier 1 supplier sensor specifications for vehicle health monitoring systems.
Global Wireless Sensors Market Competitive Landscape
United States and European producers anchor one tier with established industrial automation channels; East Asian specialists hold manufacturing scale advantages in MEMS fabrication and radio silicon integration. The vendor landscape fragments across three tiers: diversified industrial conglomerates with captive distribution, semiconductor-focused component suppliers, and emerging energy-harvesting specialists. Consolidation pressure concentrates in the mid-market as enterprise buyers demand multi-protocol platforms. Strategic moves center on backward integration into MEMS foundry capacity and protocol stack licensing to secure margin pools.
Within the diversified industrial tier, Emerson Electric Co. and ABB exemplify full-stack automation vendors with captive sensor-to-control-system integration. Honeywell International Inc. occupies a position bridging aerospace heritage and industrial reliability requirements. Texas Instruments Incorporated and Analog Devices, Inc. anchor the semiconductor-centric archetype with RF front-end and signal conditioning silicon dominance. Bosch Sensortec GmbH represents the consumer-to-industrial crossover model leveraging MEMS fabrication scale. These groupings illustrate how competitive positioning depends on whether vendors control silicon, system integration, or end-user relationships.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| ABB |
| Honeywell International Inc. |
| Analog Devices, Inc. |
| Bosch Sensortec GmbH |
| Schneider Electric SE |
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Siemens AG |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap sensor specialists in Germany and Japan anchor premium-tier pricing through captive MEMS fabrication, while private-equity-rolled-up distributors compress margins in volume segments by consolidating procurement leverage across North American industrial accounts.
Pricing Analysis
Distributor margin layers in industrial wireless sensors typically capture 15-25 points between factory gate and end-user invoice, with direct-to-OEM contracts bypassing this markup entirely. Three-tier pricing structure across aviation-certified, industrial-grade, and consumer-spillover tiers separates Honeywell's aerospace pressure transducers from Bosch's commodity MEMS accelerometers. Cost compression in standard-grade temperature nodes is intensifying because Chinese Jiangsu province manufacturers are scaling 802.15.4 radio silicon integration. Food processing plants exhibit the highest price sensitivity due to HACCP compliance documentation requirements, whereas aerospace engineering buyers prioritize FAA certification over unit cost.
Supply Chain Analysis
Ocean freight cost volatility between East Asian semiconductor hubs and European industrial corridors directly impacts landed pricing for MEMS inertial measurement units and RF front-end modules. Taiwan and South Korea dominate silicon wafer processing for sensor die fabrication, while China anchors final assembly and radio calibration testing. Raw material dependencies include Chilean lithium carbonate for battery cells, German specialty gases for MEMS etching, and Japanese ceramic substrates for high-temperature transducers. Single-source vulnerability concentrates in Taiwan foundry capacity for consumer-grade accelerometers. Distribution runs through authorized industrial automation distributors in Texas and Baden-Württemberg, with direct OEM relationships commanding volume in Chinese state-owned enterprise procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in wireless sensors hinges on energy-harvesting module cost-down curves and the premium-tier shift toward cryptographic-secure nodes under EU AI Act mandates.
For Market Incumbents: Extend protocol stack licensing revenue by embedding multi-radio silicon in building automation gateways, countering Nordic Semiconductor's Bluetooth ecosystem dominance. Deepen backward integration into Taiwanese MEMS foundry partnerships to offset single-source supply risk for inertial measurement units. Prioritize secure element integration for German medical device OEMs facing MDR conformity assessment delays. For New Entrants and Emerging Players: E-commerce direct channels bypass established distributor networks in precision agriculture, where Brazilian Cerrado equipment co-ops remain fragmented and price-sensitive. Target soil moisture telemetry in California Central Valley water districts with LoRaWAN hardware bundled with irrigation management software. Pursue white-label manufacturing relationships with Indian PLI scheme beneficiaries in Gujarat packaging facilities. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking MEMS fabrication scale and RF engineering talent concentrated in Dresden and Austin. Five-to-ten year viability favors vendors controlling both silicon design and protocol certification pathways. Watch for GB standards harmonization signals between China's MIIT and European CE marking frameworks as inflection indicators for cross-border scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Radio Silicon Integration | Modular hardware platforms serve both LoRaWAN and NB-IoT deployments from common circuit designs, compressing SKU proliferation. |
| Secure Element Node Embedding | Cryptographic signing at the sensor satisfies EU AI Act audit trail requirements for German medical device manufacturers. |
| Energy Harvesting Convergence | Photovoltaic and thermoelectric power scavenging eliminates battery dependence in Korean smart building automation networks. |
| Backward Integration into MEMS Foundry | Captive silicon wafer processing insulates against Taiwan single-source vulnerability for consumer-grade inertial measurement units. |
| Open Protocol RFP Specification | Texas and Alberta oilfield operators now mandate unbundled per-node pricing, disintermediating captive maintenance agreements. |
Research Methodology
Multiple input streams — semiconductor foundry utilization data, industrial OEM procurement contract analysis, and regulatory filing documentation — were reconciled across primary interviews with MEMS fabrication engineers, building automation system integrators, and FCC certification consultants. Secondary validation drew from MIIT GB standards publications, EU MDR notified body assessment records, and EIA industrial energy consumption surveys. Bottom-up sensor shipment estimates by radio protocol and top-down automation spending allocation models were triangulated to constrain variance.
Data-stream reconciliation anchored volume projections across the analysis window, with segmentation modeled by sensing modality, radio technology, and end-use vertical plus regional regulatory cluster as an industry-specific dimension. CAGRs were derived from installed base replacement cycles and net new deployment trajectories in Chinese manufacturing corridors and German process industries. Forecast inputs incorporated LoRaWAN spectrum allocation timelines and NB-IoT tower infrastructure buildout disclosures from Chinese tower operators.
The model assumes a particular technology adoption path; alternative pathways for energy-harvesting power architectures would alter the outlook for battery chemistry demand and maintenance-free deployment economics. Forecasts reflect assumptions about EU Green Deal implementation pacing and China's dual carbon digitization enforcement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Flow Sensor Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Middle-East and Africa Nanosensors Market
Sensors and Controls
Silicon Photomultiplier (Sipm) Market
Sensors and Controls
Reed Sensor Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Condition Monitoring System Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Corrosion Monitoring Market
Sensors and Controls
Europe Gas Sensors Market