
 US Digital Thermometer Market | 2026-2036
US Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
US Digital Thermometer Market Insights
Multi-pack bundling with probe covers and hygiene accessories is broadening buyer choice beyond standalone units. Exergen Corporation leverages its temporal artery patent portfolio to sustain premium positioning in non-contact segments. Welch Allyn anchors hospital procurement through integrated diagnostic station contracts. Omron Healthcare differentiates via pharmacy retail channel control and consumer brand recognition.
A digital thermometer is an electronic temperature measurement instrument employing thermistors or infrared sensors to quantify body heat with precision typically within ±0.1°C, converting resistance or thermal radiation into digital display readings for clinical or household diagnostic screening. Forehead infrared models lead volume due to non-contact hygiene protocols, though ear thermometers retain higher average selling prices in pediatric and hospital segments. Homecare demand is accelerating fastest as post-acute monitoring protocols extend beyond clinical walls.
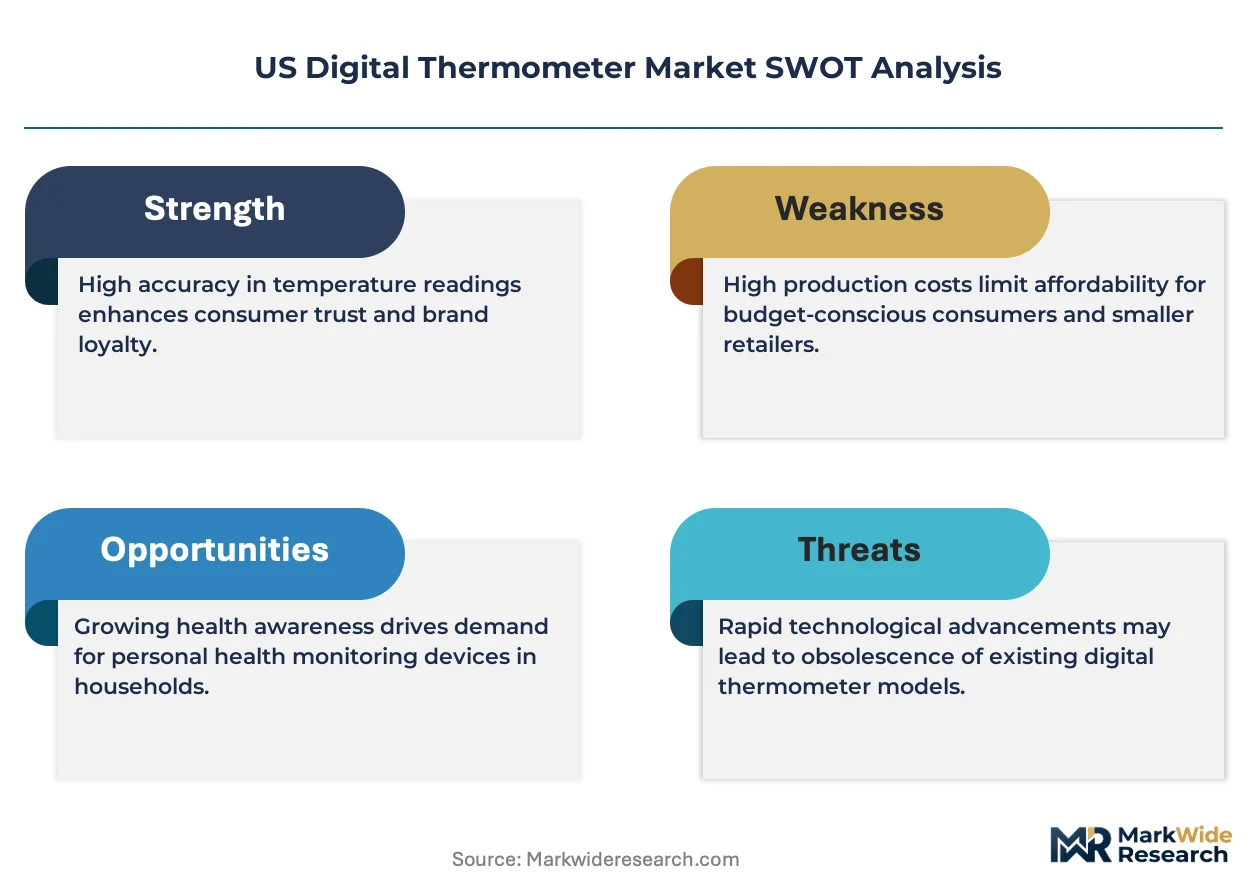
FDA 510(k) premarket notification requirements and ASTM E1965 infrared thermometer standards govern product safety and performance claims, while HIPAA privacy rules shape connected device data architectures. The Federal Trade Commission monitors advertising claims for fever-detection accuracy, creating compliance cost layers for new entrants. Stakeholders must weigh connected-health data integration against evolving cybersecurity guidance from the FDA's software-as-medical-device framework.
Market Dynamics
Homecare self-monitoring protocols are redirecting procurement volume from hospital supply chains toward direct-to-consumer channels, compressing traditional distributor margins while elevating brand recognition as the primary purchase determinant.
Growth Catalysts
- FDA 510(k) pathway clarity:Streamlined premarket notification timelines for infrared thermometers accelerate commercialization cycles for manufacturers targeting clinical-grade positioning.
- Post-acute monitoring expansion:Hospital discharge protocols now mandate temperature tracking, creating sustained pull through retail pharmacy networks and connected health platforms.
- Aging demographic clusters:Texas, California, and Florida house concentrated Medicare populations generating recurring replacement demand for home diagnostic devices.
Market Restraints
- Semiconductor input volatility:Thermistor and infrared sensor chip supply concentrates in East Asian foundries, exposing US manufacturers to tariff and logistics cost swings.
- Accuracy ceiling limitations:Non-contact infrared models face ±0.2°C precision constraints versus contact thermistors, restricting penetration in NICU and oncology infusion settings.
- FTC advertising scrutiny:Fever-detection accuracy claims trigger compliance review cycles that delay campaign launches and inflate legal overhead for new entrants.
Strategic Opportunities
- HIPAA-compliant data architecture:Connected thermometer platforms integrating with telehealth reimbursement codes capture recurring subscription revenue from accountable care organizations.
- Multi-pack bundling formats:Probe cover and hygiene accessory combinations differentiate commodity hardware while lifting average transaction values in mass retail.
- Pediatric segment specialization:Ear thermometer form factors with fever-alert algorithms address parental anxiety points, commanding sustained price premiums over forehead alternatives.
Industry Challenges
- FDA software-as-medical-device cybersecurity guidance:Connected product architectures require ongoing vulnerability patching and documentation, extending engineering overhead timelines.
- ASTM E1965 calibration certification:Infrared thermometer accuracy validation demands specialized thermal reference equipment, creating capital barriers for contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Digital Thermometer Market |
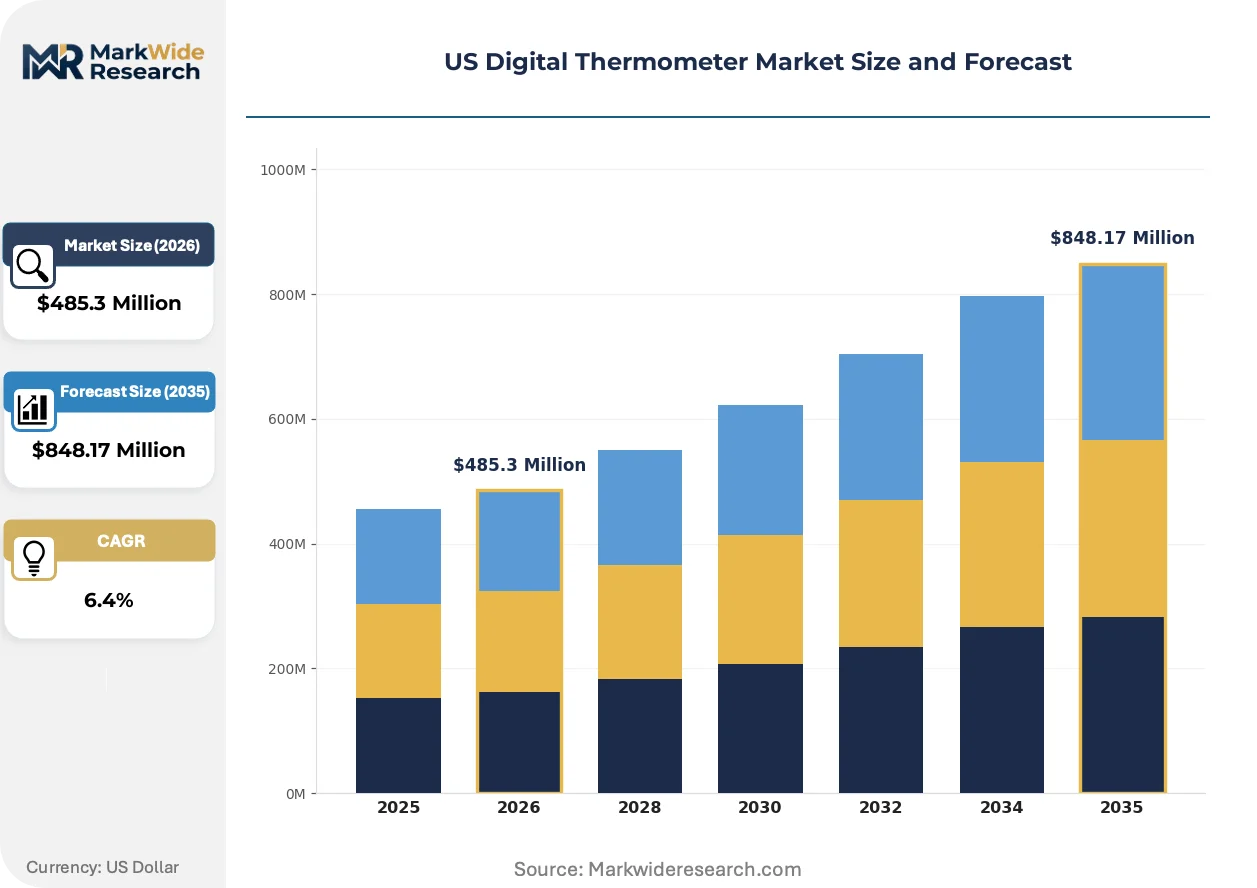
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $848.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forehead, Oral, Ear, Rectal Technology: Infrared, Digital, Flexible, Glass End User: Homecare, Hospitals, Clinics, Laboratories Distribution Channel: Online, Retail, Wholesale, Direct |
| Companies Covered | Medline Industries, RG Medical Diagnostics, Omron Healthcare, Microlife Corporation, A&D Medical, Exergen Corporation, American Diagnostic Corporation, Terumo Corporation, Welch Allyn, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Digital Thermometer Market Trends and Innovations
Non-contact measurement modalities and connected data infrastructure are restructuring competitive advantage around hygiene protocols and longitudinal health tracking rather than standalone hardware precision.
Temporal artery infrared scanning is overtaking tympanic membrane measurement in pediatric practices. Primary care networks across the Midwest and Southeast are standardizing forehead-based workflows to eliminate probe cover consumption and cross-contamination protocols. This shift compresses average selling prices for ear thermometer SKUs while elevating software-integrated forehead models with fever-history logging.
ASTM E1965-98 standard revisions are tightening infrared thermometer accuracy tolerances for clinical claims. Manufacturers must now submit expanded thermal stability testing under expanded ambient temperature ranges, extending 510(k) preparation cycles by four to six months. Hospital procurement committees are prioritizing ASTM-certified units over uncertified imports, reshaping supplier qualification criteria.
Retail pharmacy chains are unbundling thermometer sales from diagnostic service bundles. CVS Health and Walgreens are positioning connected thermometers as standalone wellness category anchors rather than seasonal flu-shot attachments. This channel autonomy elevates consumer brand recognition over clinical endorsement as the primary purchase driver, particularly in suburban markets with limited primary care access.
US Digital Thermometer Market Segmentation
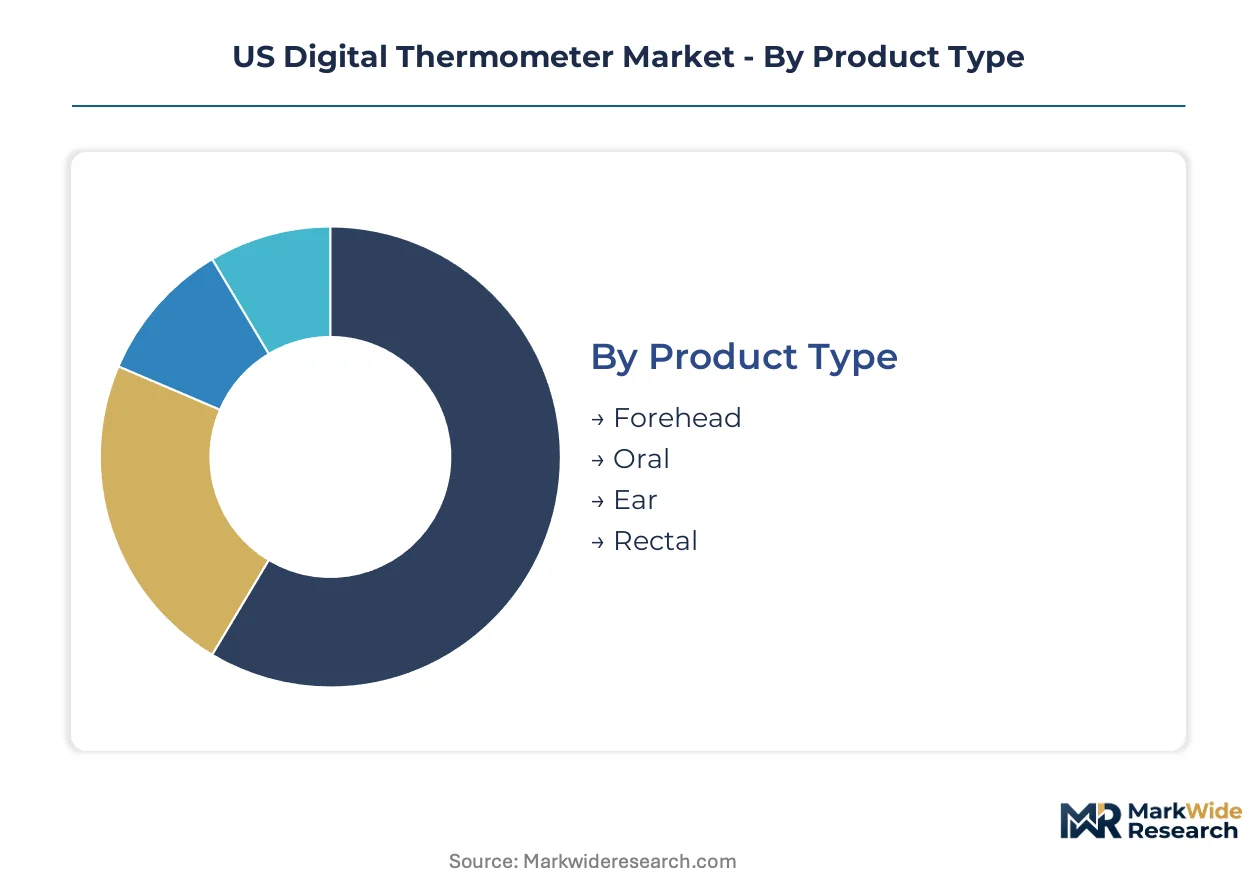
Digital thermometer segmentation reveals divergent buyer priorities across clinical precision requirements, hygiene protocols, and procurement channel preferences. Understanding these fault lines enables manufacturers to align R&D investment and distribution strategy with the highest-margin demand pockets.
Product Type:
Buyer differentiation hinges on contact versus non-contact hygiene tolerance and the precision demands of specific patient populations.
- Forehead:Temporal artery infrared sensors capture thermal radiation from superficial blood vessels without skin contact. Texas, California, and Florida pediatric practices are standardizing these workflows to eliminate probe cover consumption and cross-contamination protocols.
- Oral:Thermistor-based contact measurement employs precision resistive elements positioned sublingually for core temperature approximation. Homecare settings in suburban markets with limited primary care access favor these units for post-acute monitoring protocols due to lower price points and intuitive operation.
- Ear:Tympanic membrane infrared detection targets the hypothalamus-proximal blood supply for rapid core temperature estimation. NICU and oncology infusion settings retain demand despite higher unit costs.
- Rectal:Direct core temperature measurement via flexible probe insertion delivers highest precision for neonatal and immuno-compromised patients. Hospital procurement committees specify these for critical care applications where ±0.1°C accuracy is mandatory.
Forehead leads volumes today; rectal is gaining share fastest in critical care specialization.
Technology:
Cost tier stratification separates clinical-grade certification investments from commodity household positioning.
- Infrared:Non-contact thermal radiation sensors convert emitted heat into electrical signals through pyroelectric or thermopile detectors. FDA 510(k) premarket notification requirements and ASTM E1965 standards govern accuracy claims for clinical-grade units.
- Digital:Thermistor-based resistive temperature detection employs precision-calibrated semiconductor elements for contact measurement. Retail pharmacy chains position these as standalone wellness category anchors rather than seasonal flu-shot attachments.
- Flexible:Elongated probe configurations with articulated tips adapt to anatomical variation in pediatric and geriatric applications. Homecare demand concentrates in Medicare population clusters generating recurring replacement cycles.
- Glass:Mercury-free gallium-indium-tin alloy alternatives replicate traditional thermometer haptics for institutional buyers with legacy protocol requirements. Limited volume persists in long-term care facilities with established documentation workflows.
Infrared dominates revenue contribution; flexible is climbing the fastest as homecare protocols extend monitoring duration.
End User:
Volume concentration versus margin capture splits procurement behavior across institutional and direct-to-consumer channels.
- Homecare:Direct-to-consumer acquisition for post-acute temperature tracking and chronic condition self-management. CVS Health and Walgreens channel autonomy elevates consumer brand recognition over clinical endorsement as the primary purchase driver.
- Hospitals:Integrated diagnostic station contracts and enterprise procurement frameworks prioritize ASTM E1965-certified units with cybersecurity documentation under FDA software-as-medical-device guidance.
- Clinics:Ambulatory care networks standardizing forehead-based workflows to reduce consumable overhead and infection control liability.
- Laboratories:Specimen handling and environmental monitoring applications requiring calibrated thermal reference compliance for research protocol integrity.
Homecare leads volumes today; hospitals are expanding share fastest through connected-health platform integration.
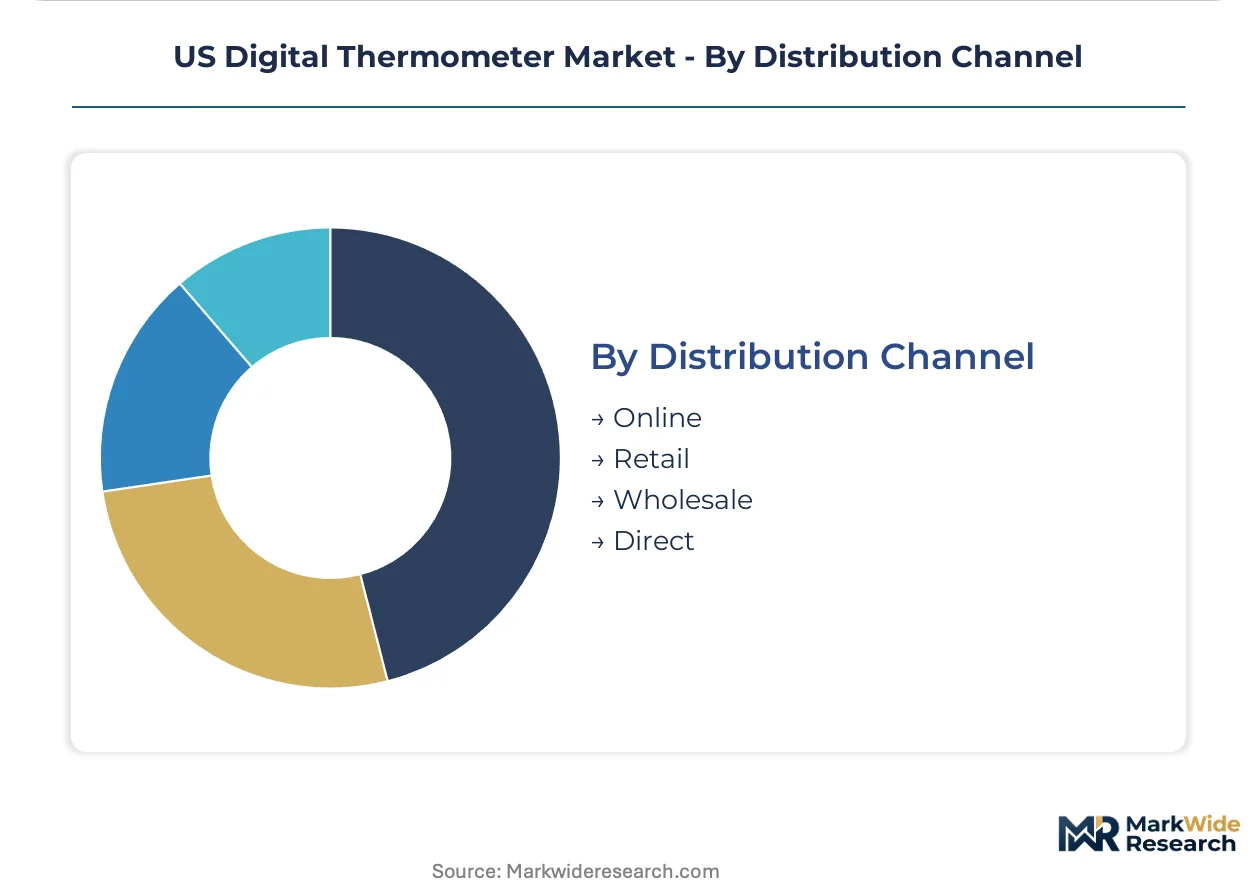
Distribution Channel:
Customer type and purchase urgency dictate channel selection between immediate availability and price optimization.
- Online:E-commerce platforms enable specification comparison and subscription replenishment for probe covers and hygiene accessories. Direct-to-consumer channels compress traditional distributor margins while elevating brand recognition.
- Retail:Pharmacy and mass merchandiser physical presence captures impulse demand during seasonal illness peaks. Multi-pack bundling with probe covers differentiates commodity hardware while lifting average transaction values.
- Wholesale:Medical supply distributors serve institutional procurement with volume pricing and consolidated logistics for hospital network contracts.
- Direct:Manufacturer-to-institution relationships support integrated diagnostic station deployments and customized calibration certification requirements.
Retail leads volumes today; online is gaining share fastest through connected device subscription attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US digital thermometer industry traces its clinical-grade manufacturing lineage to Massachusetts and Minnesota, where early medical device clusters established FDA-compliant production protocols during the 1980s semiconductor integration wave. These northeastern and midwestern hubs seeded the quality infrastructure that now supports nationwide distribution networks.
Texas
Houston and Dallas-Fort Worth medical center networks generate concentrated hospital procurement volume for ASTM E1965-certified infrared units. Texas Medicaid expansion and Medicare Advantage penetration create recurring replacement cycles among aging suburban populations. The Texas Medical Center complex anchors enterprise diagnostic station contracts requiring cybersecurity documentation under FDA software-as-medical-device guidance.
California
Los Angeles and San Francisco Bay Area health systems prioritize connected thermometer platforms integrating with telehealth reimbursement codes. California Consumer Privacy Act compliance costs shape data architecture investments for homecare device manufacturers targeting direct-to-consumer channels. San Diego's biotech corridor drives pediatric specialization demand with fever-alert algorithm specifications.
Florida
Miami and Tampa retirement communities sustain high replacement velocity for homecare oral and forehead thermometers. Florida's hospital network density concentrates procurement pull through integrated diagnostic station contracts. The state's post-acute monitoring protocol adoption accelerates retail pharmacy channel volume through CVS Health and Walgreens storefront penetration.
New York Metro
New York-Presbyterian and Mount Sinai health systems mandate ASTM-certified units with expanded thermal stability testing for NICU applications. New York State's connected health initiative subsidizes thermometer-telehealth integration for accountable care organizations. Brooklyn and Queens manufacturing zones retain legacy thermistor calibration expertise serving institutional buyers.
Illinois
Chicago's hospital procurement committees prioritize FDA 510(k)-cleared units with documented cybersecurity patching protocols. Illinois Medicaid managed care expansion drives homecare thermometer volume through pharmacy retail networks. Rockford and Peoria manufacturing clusters supply flexible probe configurations for pediatric and geriatric applications.
US Digital Thermometer Market Competitive Landscape
The competitive structure tilts toward diversified medical device conglomerates with established hospital procurement relationships. Three to five manufacturers capture the majority of institutional contract value, while mid-tier specialists compete on pediatric form factors and retail pharmacy placement. Archetypes include patent-protected non-contact innovators, integrated diagnostic station suppliers, and consumer brand-anchored pharmacy channel controllers. Dominant competitive moves center on multi-pack bundling with hygiene accessories and HIPAA-compliant data platform integration.
Among diversified medical device conglomerates, Medline Industries and Welch Allyn occupy positions anchored by enterprise procurement frameworks and integrated diagnostic station deployments. Exergen Corporation exemplifies the patent-protected innovation archetype, while Omron Healthcare represents consumer brand-anchored pharmacy channel control. These three companies illustrate the strategic segmentation between institutional contract depth and direct-to-consumer recognition.
| Leading Market Players |
|---|
| Medline Industries |
| RG Medical Diagnostics |
| Omron Healthcare |
| Microlife Corporation |
| A&D Medical |
| Exergen Corporation |
| American Diagnostic Corporation |
| Terumo Corporation |
| Welch Allyn |
| Others |
Pricing and Supply Chain Analysis
FDA software-as-medical-device cybersecurity documentation gates qualified supply access and premium-tier pricing for connected thermometer architectures, compressing margins for uncertified imports while elevating ASTM E1965-validated units.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared infrared units with cybersecurity documentation from uncertified imports and basic thermistor models. Price differentiation hinges on ASTM E1965 certification grade and hospital procurement contract scale. Cost compression in the economy tier intensifies as East Asian contract manufacturers absorb tariff exposure. Homecare consumers exhibit highest price sensitivity; hospital GPOs prioritize total cost of ownership over unit price.
Supply Chain Analysis
Workforce availability constraints in Massachusetts and Minnesota legacy medical device clusters limit domestic thermistor calibration capacity expansion. Thermopile infrared sensors draw from Taiwan and South Korea foundries; flexible probe assemblies source from Mexico maquiladoras. Single-source vulnerability concentrates in pyroelectric detector supply. Distribution runs through medical supply distributors serving hospital networks and pharmacy retail chains capturing direct-to-consumer volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US digital thermometer market compounds steadily as post-acute monitoring protocols institutionalize temperature tracking beyond clinical walls.
For Market Incumbents: Anchor hospital procurement relationships through integrated diagnostic station contracts requiring ASTM E1965 certification and documented cybersecurity patching protocols. Deepen backward integration into thermistor calibration equipment to defend against East Asian contract manufacturer price aggression. Prioritize HIPAA-compliant data platform development to capture recurring subscription revenue from accountable care organizations integrating thermometer-telehealth bundles. For New Entrants and Emerging Players: Pediatric fever-alert algorithm specialization offers a technology-first wedge into underserved parental anxiety segments commanding sustained price premiums. Target suburban markets with limited primary care access where retail pharmacy channel autonomy elevates consumer brand recognition over clinical endorsement. Pursue direct-to-consumer online positioning with subscription replenishment for probe covers and hygiene accessories. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier contract manufacturers lacking ASTM E1965 certification infrastructure but possessing flexible probe assembly capabilities. Long-term viability favors targets with software-as-medical-device documentation experience and established pharmacy retail placement. Watch FDA software guidance expansion as the inflection signal for connected-platform acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Premarket notification clearance accelerates commercialization timelines for clinical-grade infrared positioning. |
| Hospital System Partnership | Enterprise diagnostic station contracts with Texas Medical Center networks anchor recurring procurement volume. |
| Software Companion Development | HIPAA-compliant fever-history logging platforms capture telehealth reimbursement code integration revenue. |
| Reimbursement Strategy | Medicare Advantage and Medicaid managed care alignment drives homecare thermometer replacement cycles. |
| CE Marking Pathway | European regulatory preparation enables diversification beyond FTC advertising scrutiny exposure. |
Research Methodology
Coverage spans Texas, California, Florida, New York Metro, and Illinois, with primary inputs from each regional cluster. The analysis combines interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and pharmacy category buyers with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ASTM standard revision documentation. Bottom-up unit demand modeling triangulates against top-down market sizing.
Rate-of-change decomposition across the projection horizon segments volume by product type, technology tier, end-user setting, and distribution channel. CAGRs derive from regression analysis against aging demographic trajectories, post-acute protocol adoption curves, and semiconductor input cost indices. Forecast inputs include Medicare Advantage penetration rates by state and retail pharmacy storefront density metrics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software-as-medical-device guidance evolution and East Asian foundry capacity allocation. Material deviation in semiconductor tariff policy or ASTM E1965 standard revision timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Wireless Sensors Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Europe Gas Sensors Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
Europe Emission Monitoring System Market
Sensors and Controls
Japan Sensor Market
Sensors and Controls
RET Controller Market
Sensors and Controls
Earth and Space Mining Sensors Market
Sensors and Controls
Level Measuring Equipment Market