
 Wind Vane Sensor Market | 2026-2036
Wind Vane Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Vane Sensor Market Analytics
Sensor-as-a-service subscription models is decoupling hardware sales from long-term revenue streams in the wind vane sensor sector. Gill Instruments leverages its coastal UK manufacturing base to sustain dominance in marine-grade installations. Vaisala competes through optical technology leadership that differentiates its aviation-certified product line. Campbell Scientific anchors its position in agricultural meteorology networks across the North American plains.
A wind vane sensor measures wind direction through mechanical rotation of a fin-aligned arrow, typically achieving accuracy within ±3 degrees via magnetic or optical encoding transducers; its primary commercial purpose is to feed real-time directional data into weather stations, turbine control systems, and flight safety infrastructure. Digital wind vanes now command the technology margin pool as utilities demand RS-485 and SDI-12 outputs for SCADA integration, while smart wind vanes with embedded edge processing represent the fastest-growing product category for offshore wind farms requiring local gust detection without telemetry latency. Magnetic technology still occupies the largest installation base due to cost parity, though ultrasonic units are displacing mechanical alternatives in salt-laden environments where bearing corrosion degrades precision.
IEC 61400-12-1 wind measurement standards, FAA technical specifications for airport weather systems, and EU Marine Strategy Framework Directive monitoring protocols collectively shape product certification requirements and market access conditions across target geographies. Offshore installation classifications now trigger mandatory redundant sensor configurations under German maritime authority rules, compressing margins for single-unit suppliers while expanding addressable revenue per platform. Stakeholders must weigh the capital intensity of ultrasonic R&D against the service-recurring potential of predictive maintenance subscriptions as turbine operators renegotiate supplier contracts.
Market Dynamics
Offshore wind farm operators are forcing redundant sensor architectures as German maritime authority rules mandate dual-measurement systems, compressing supplier margins on single-unit sales while expanding per-platform revenue capture.
Growth Catalysts
- IEC 61400-12-1 measurement standards:Tightened accuracy requirements for turbine power performance testing are compelling utilities to upgrade legacy mechanical vanes with digital encoders across North Sea installations.
- Edge computing integration:Smart wind vanes with embedded gust detection algorithms eliminate telemetry latency for floating offshore platforms where real-time yaw control prevents structural fatigue.
- China's dual carbon goals:Provincial grid operators in Jiangsu and Guangdong are accelerating coastal wind farm construction, creating concentrated demand clusters for marine-grade directional sensors.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing dominance in Inner Mongolia creates input cost volatility for magnetic encoder manufacturers dependent on Chinese magnet supply chains.
- Salt-laden corrosion degradation:Mechanical bearing systems suffer precision loss in marine atmospheres, forcing premature replacement cycles that erode total cost-of-ownership advantages against ultrasonic alternatives.
- FAA technical specification compliance:Aviation certification timelines for airport weather systems extend 18-24 months, gating market access for sensor suppliers lacking prior airfield installation records.
Strategic Opportunities
- Predictive maintenance subscriptions:Sensor-as-a-service models decouple hardware revenue from recurring diagnostic streams, allowing suppliers to capture lifetime value from turbine operator contracts.
- EU Marine Strategy Framework Directive monitoring:Expanded water quality and meteorological observation mandates are opening coastal environmental monitoring networks as a new installation channel beyond energy applications.
- Ultrasonic-optical hybrid convergence:Combining time-of-flight wind speed measurement with optical direction encoding addresses the accuracy-robustness tradeoff that has fragmented technology selection.
Industry Challenges
- SCADA protocol integration complexity:RS-485 and SDI-12 output standardization gaps between turbine OEMs force sensor suppliers to maintain multiple firmware branches, fragmenting R&D resources.
- Marine-grade IP67 certification timelines:Extended salt-spray and vibration testing protocols delay product launches by 8-12 months, compressing competitive windows for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Vane Sensor Market |
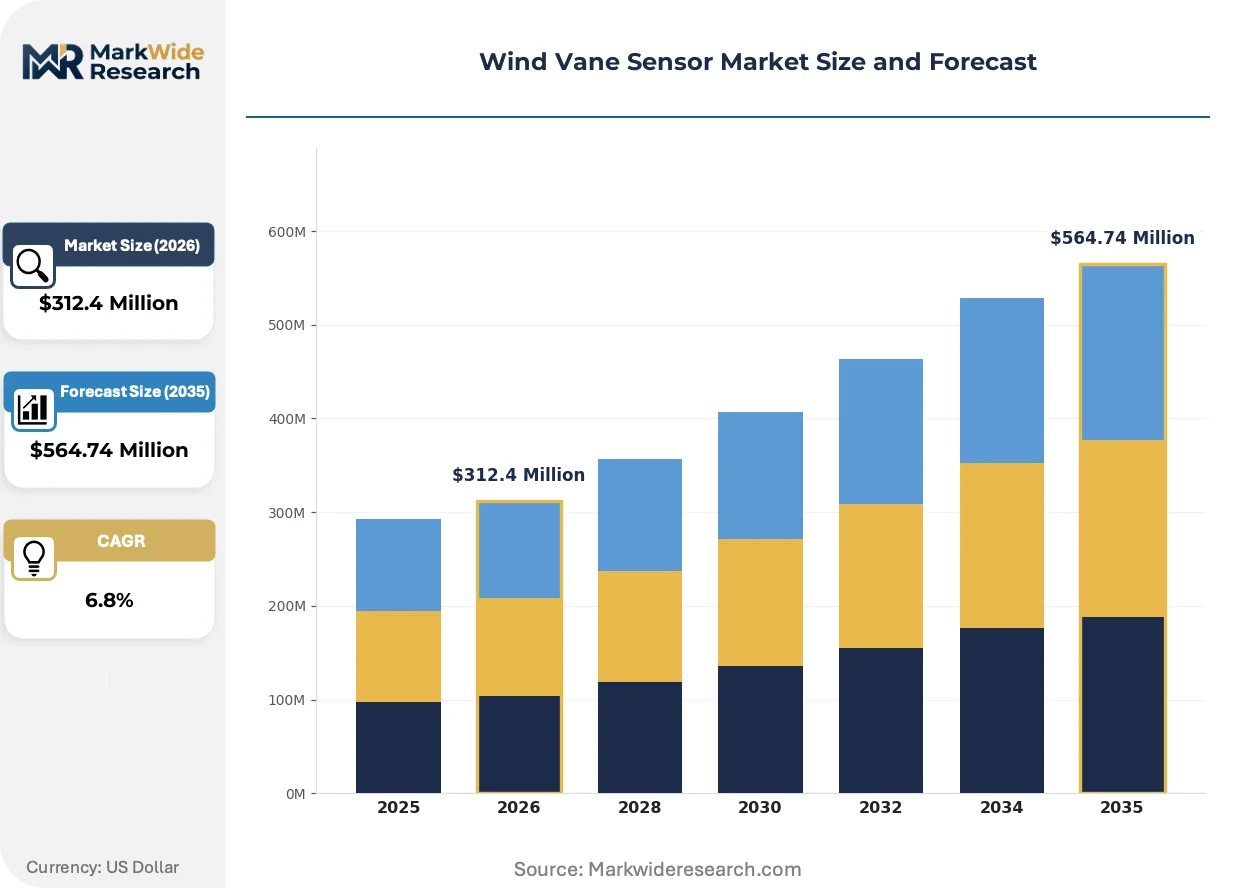
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Wind Vanes, Digital Wind Vanes, Smart Wind Vanes, Wireless Wind Vanes End User: Aerospace, Meteorology, Renewable Energy, Agriculture Technology: Magnetic, Capacitive, Optical, Ultrasonic Installation: Onshore, Offshore, Mobile, Fixed |
| Companies Covered | CJ Capteurs, Skyview Systems, Gill Instruments, Instromet Weather Systems, Cassens & Plath GmbH, Veinland GmbH, Vaisala, Campbell Scientific, Met One Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Vane Sensor Market Evolving Landscape
Digital encoding architectures are displacing mechanical potentiometer systems across utility-scale installations, while edge-processing capabilities and subscription-based service models are restructuring how sensor value is captured and delivered.
Optical encoder technology is automating wind direction measurement through contactless position sensing that eliminates mechanical wear. Offshore wind developers in the North Sea are adopting these systems at accelerated pace to satisfy IEC redundancy requirements. The technology is automating calibration routines that previously required manual technician intervention, reducing offshore maintenance vessel dispatches.
REACH substance restrictions on heavy metals in electronics are compelling sensor manufacturers to reformulate solder compositions and bearing lubricants. Industrial consequence includes accelerated validation cycles for alternative material sets in marine housings. Aviation-certified product lines face the most complex compliance burden as dual FAA-EASA jurisdiction creates overlapping substance documentation requirements.
Buyer consolidation among European offshore wind farm operators is compressing supplier negotiation leverage and extending payment terms. Traditional component distributors are losing ground to direct procurement frameworks where turbine OEMs specify approved vendor lists. This pattern is most visible in Germany, where RWE and Ørsted's consolidated purchasing power has shifted contract structures toward multi-year framework agreements with penalty clauses for accuracy drift.
Wind Vane Sensor Market Segmentation
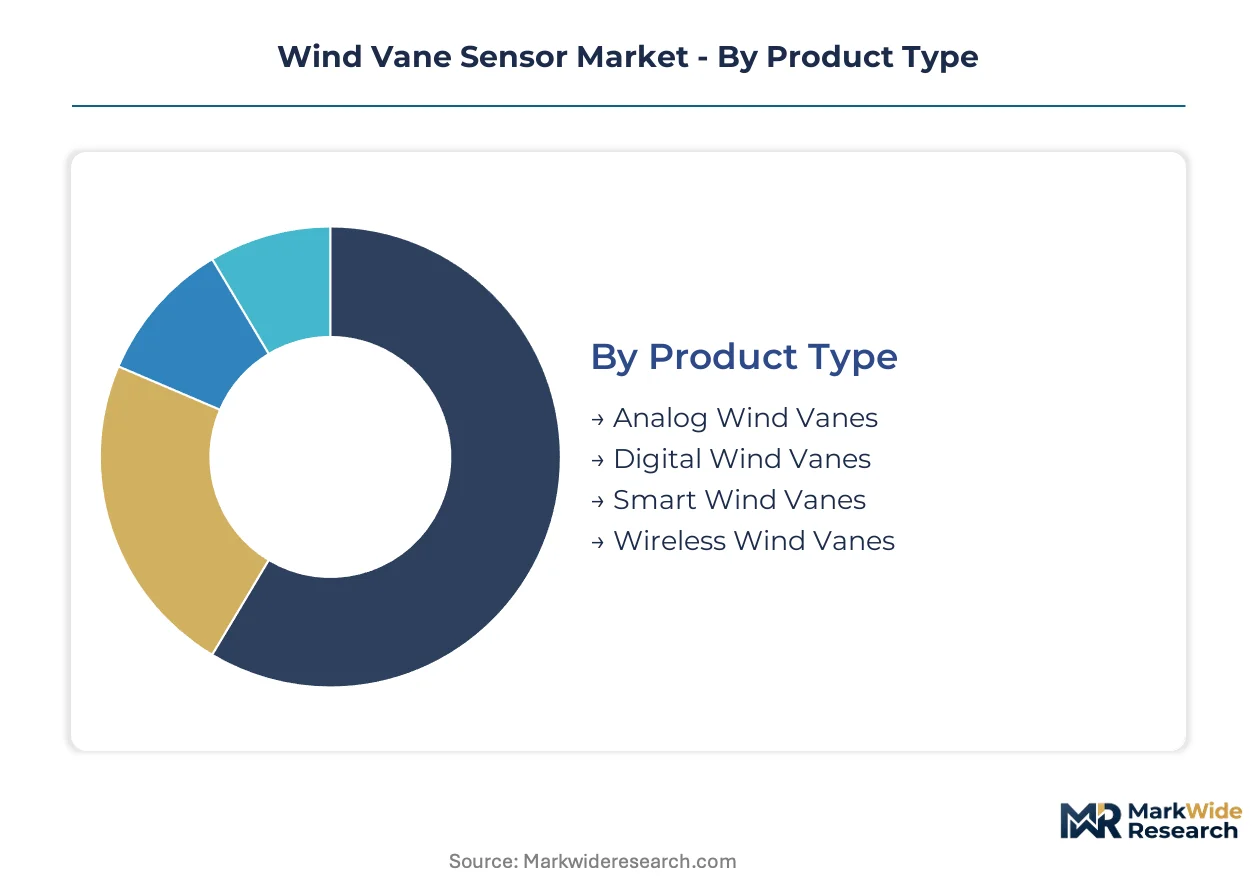
Wind vane sensor segmentation reveals how technology choices cascade through certification requirements, installation economics, and service model potential. Product architecture decisions made at procurement lock in maintenance burdens and data integration pathways for operational lifespans exceeding fifteen years.
Product Type:
Volume concentrates in established analog and digital formats, while premium capture shifts toward connected architectures that enable recurring revenue streams.
- Analog Wind Vanes:Potentiometer-based direction sensing with voltage output signals dominates legacy installed base across agricultural meteorology networks. Demand persists in India and Brazil where cost sensitivity overrides digital integration requirements, though replacement cycles accelerate as SCADA modernization mandates propagate.
- Digital Wind Vanes:RS-485 and SDI-12 output protocols command the technology margin pool as North Sea offshore operators standardize on IEC 61400-12-1 compliant encoders. German maritime authority certification requirements compress supplier margins while expanding per-platform sensor counts through redundant configurations.
- Smart Wind Vanes:Embedded edge processing with local gust detection algorithms eliminates telemetry latency for floating offshore platforms. These units are gaining share fastest in Jiangsu and Guangdong coastal wind zones where real-time yaw control prevents structural fatigue.
- Wireless Wind Vanes:LoRaWAN and cellular telemetry integration reduces cabling costs for temporary meteorological deployments and remote agricultural stations.
Today's leader: Digital Wind Vanes. Tomorrow's challenger: Smart Wind Vanes.
End User:
Application-driven segmentation exposes divergent accuracy requirements and procurement authority structures across buyer categories.
- Aerospace:FAA and EASA certification timelines extending 18-24 months gate market access for suppliers lacking prior airfield installation records. Optical encoding technology dominates this segment due to contactless position sensing that eliminates mechanical wear in safety-critical flight systems.
- Meteorology:National weather services and research institutions drive demand for WMO-compliant measurement chains with traceable calibration protocols. Campbell Scientific anchors its position in agricultural meteorology networks across the North American plains through integrated station architectures.
- Renewable Energy:Offshore wind farm operators in the North Sea are forcing redundant sensor architectures as German maritime authority rules mandate dual-measurement systems.
- Agriculture:Irrigation automation and frost protection systems utilize lower-accuracy mechanical vanes with wireless telemetry integration.
Renewable Energy commands current procurement volume. Aerospace maintains the steepest expansion trajectory through aviation infrastructure modernization.
Technology:
Encoding methodology determines corrosion resistance, calibration stability, and total cost of ownership in salt-laden marine atmospheres.
- Magnetic:Hall-effect and magnetoresistive encoders occupy the largest installation base due to cost parity with potentiometer alternatives. Rare earth processing concentration in Inner Mongolia creates input cost volatility for manufacturers dependent on Chinese neodymium magnet supply chains.
- Optical:LED-photodetector position sensing eliminates mechanical contact and enables automated calibration routines that reduce offshore maintenance vessel dispatches. Vaisala competes through optical technology leadership that differentiates its aviation-certified product line.
- Capacitive:Dielectric sensing architectures provide humidity-resistant operation in tropical meteorological deployments.
- Ultrasonic:Time-of-flight wind speed measurement with optical direction encoding addresses the accuracy-robustness tradeoff, displacing mechanical alternatives in salt-laden environments where bearing corrosion degrades precision.
Magnetic technology anchors present installed base. Ultrasonic-optical hybrid convergence defines the replacement cycle.
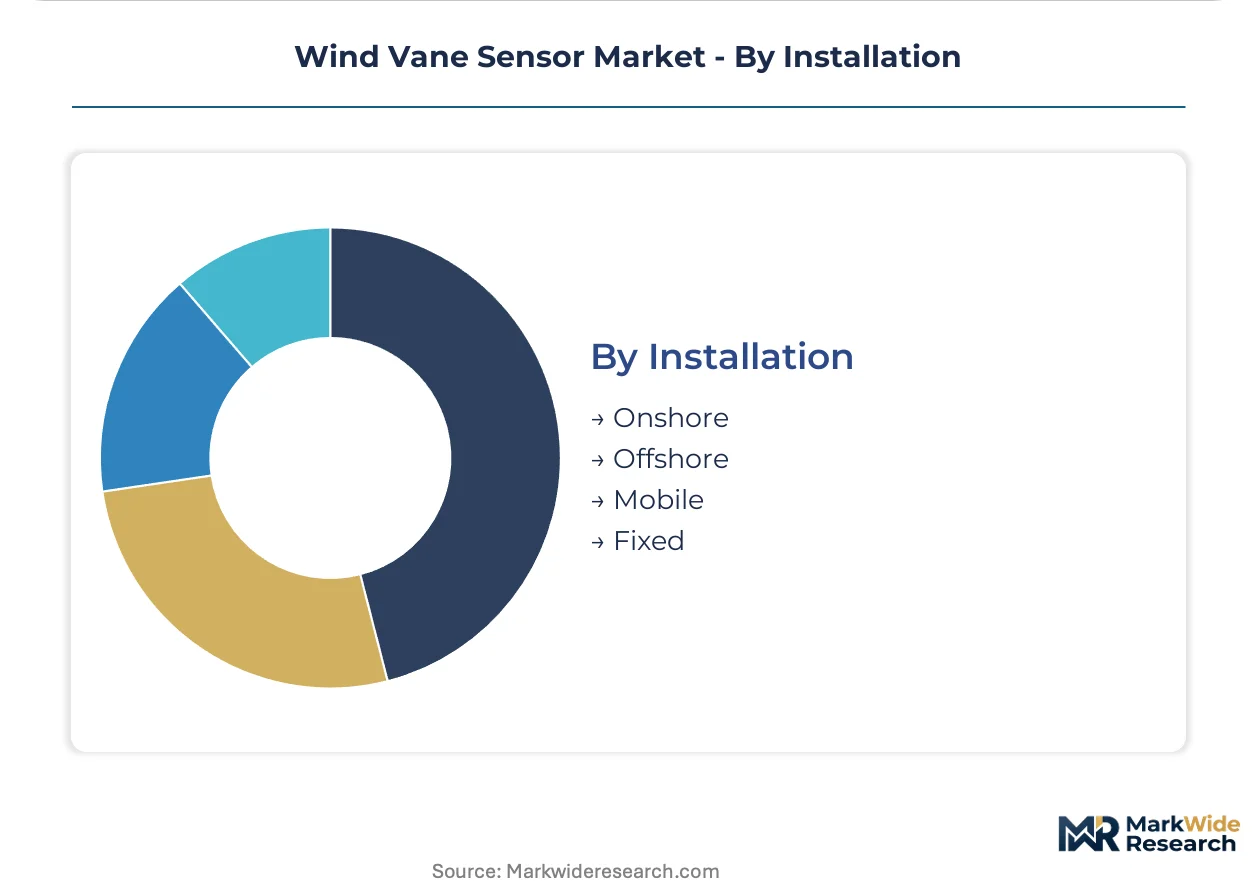
Installation:
Deployment environment dictates housing specifications, maintenance accessibility, and regulatory compliance burdens.
- Onshore:Land-based wind farms and meteorological towers utilize standard IP65-rated housings with technician-accessible calibration ports. China's dual carbon goals are accelerating coastal onshore construction in Jiangsu and Guangdong provinces.
- Offshore:Floating and fixed-bottom platforms require IP67 marine-grade certification with extended salt-spray and vibration testing protocols that delay product launches by 8-12 months. Gill Instruments leverages its coastal UK manufacturing base to sustain dominance in marine-grade installations.
- Mobile:Vehicle-mounted and portable meteorological systems demand ruggedized housings with rapid-deployment mounting interfaces.
- Fixed:Permanent aviation and research installations prioritize long-term stability over service accessibility.
Offshore installations concentrate premium value capture. Mobile deployments represent the most fragmented procurement pattern.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as suppliers migrate production toward jurisdictions with streamlined marine certification protocols and proximity to offshore wind clusters.
Germany
North Sea offshore installations dominate procurement volume as the Federal Maritime and Hydrographic Agency mandates redundant sensor configurations for all floating platforms. The country's implementation of IEC 61400-12-1 standards exceeds baseline requirements, compressing supplier margins while expanding per-turbine sensor counts. Hamburg anchors the European marine certification ecosystem, with testing laboratories processing IP67 validation for Baltic and North Sea deployments.
China
Jiangsu and Guangdong provincial grid operators are accelerating coastal wind farm construction under national dual carbon targets, creating concentrated demand clusters for marine-grade directional sensors. The Ministry of Ecology and Environment tightened offshore environmental monitoring protocols, requiring real-time meteorological data transmission from all installations. Yangtze River Delta manufacturing bases are scaling ultrasonic sensor output to serve domestic renewable energy developers.
United States
FAA technical specifications for airport weather systems extend 18-24 month certification timelines, gating market access for sensor suppliers lacking prior airfield installation records. The Federal Aviation Administration maintains strict optical encoder requirements for flight safety infrastructure. Greater Boston hosts aviation meteorology research institutions driving precision instrument demand for next-generation terminal weather systems.
United Kingdom
Coastal manufacturing bases leverage proximity to North Sea offshore zones where Gill Instruments sustains dominance in marine-grade installations. The Maritime and Coastguard Agency aligns with German redundancy standards for floating platform deployments. Scottish waters are emerging as a secondary offshore wind frontier with distinct regulatory pathways through Marine Scotland licensing frameworks.
India
Central Electricity Authority grid integration standards are compelling wind farm operators to upgrade legacy mechanical vanes with digital encoders across Gujarat and Tamil Nadu wind corridors. The Bureau of Indian Standards is developing indigenous certification protocols for coastal meteorological monitoring equipment. Maharashtra's renewable energy parks are piloting smart vane installations with embedded edge processing for gust detection.
Wind Vane Sensor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium aviation and offshore applications consolidating around certified incumbents while agricultural meteorology remains fragmented. The vendor base organizes into three strategic archetypes: marine-grade specialists with coastal manufacturing proximity, aviation-certified precision instrument houses, and diversified environmental monitoring platforms. Dominant competitive moves include geographic expansion toward Chinese offshore wind zones and technology licensing partnerships for ultrasonic-optical hybrid architectures.
Among UK-based fabricators, Gill Instruments occupies a position exemplifying marine-grade specialization, while Vaisala represents the aviation-certified precision tier with optical technology leadership. Campbell Scientific anchors the agricultural meteorology archetype across North American plains networks. Instromet Weather Systems and Met One Instruments sit within the diversified environmental monitoring segment, serving multiple end-use verticals through modular product architectures. Cassens & Plath GmbH and Veinland GmbH exemplify German engineering-intensive positioning with maritime regulatory expertise.
| Leading Market Players |
|---|
| CJ Capteurs |
| Skyview Systems |
| Gill Instruments |
| Instromet Weather Systems |
| Cassens & Plath GmbH |
| Veinland GmbH |
| Vaisala |
| Campbell Scientific |
| Met One Instruments |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between IEC 61400-12-1 compliant marine units and legacy analog agricultural sensors manifests in both pricing stratification and supply chain configuration. Premium optical encoder manufacturers command three-tier pricing structure across aviation-certified, offshore-redundant, and standard meteorology tiers, while commodity potentiometer suppliers face margin compression from consolidated European wind farm procurement.
Pricing Analysis
Distributor margins of 15-25 percent on marine-grade installations are compressing as RWE and Ørsted negotiate direct-to-OEM framework agreements with penalty clauses for accuracy drift. Price differentiation hinges on IP67 certification tier and redundant sensor bundling, with single-unit suppliers losing leverage against ultrasonic-optical hybrid providers. Pricing pressure stems from buyer consolidation in German North Sea zones, where payment terms have extended to 120 days. Agricultural meteorology networks in India and Brazil remain most price-sensitive, while aviation-certified optical systems show least elasticity due to FAA-EASA dual jurisdiction barriers.
Supply Chain Analysis
Refurbishment flows for salt-corroded mechanical bearing systems are expanding as offshore operators seek to defer full replacement costs in Jiangsu and Guangdong coastal zones. Manufacturing concentrates in the United Kingdom, Germany, and coastal China, with Yangtze River Delta facilities scaling ultrasonic output for domestic renewable developers. Neodymium magnet supply draws from Inner Mongolia rare earth processing, creating input volatility for Hall-effect encoder producers. Single-source vulnerability in Chinese magnet supply chains threatens margin stability. Distribution runs through turbine OEM approved-vendor lists and direct procurement frameworks, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by the shift toward IEC 61400-12-1 redundant architectures that disqualify single-unit mechanical suppliers from German maritime authority contracts.
For Market Incumbents: Extend optical encoder R&D into ultrasonic-optical hybrid architectures to defend against displacement in salt-laden marine environments where bearing corrosion degrades precision. Deepen backward integration into neodymium magnet supply through offtake agreements with Yangtze River Delta processors to offset Inner Mongolia concentration risk. Lock in multi-year framework agreements with consolidated European offshore operators before FAA-EASA certification timelines gate aviation market access for emerging competitors. For New Entrants and Emerging Players: EU Marine Strategy Framework Directive monitoring protocols in coastal European waters open a window for environmental observation networks beyond energy applications. Target agricultural meteorology in India and Brazil where cost sensitivity preserves analog potentiometer demand during SCADA modernization transitions. Pursue sensor-as-a-service subscription models to decouple hardware revenue from recurring diagnostic streams, capturing lifetime value without front-loaded capital requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where FAA-EASA dual jurisdiction creates overlapping documentation burdens that favor incumbents with prior airfield installation records. Long-term viability favors aviation-certified precision instrument houses and marine-grade specialists with coastal manufacturing proximity over diversified environmental monitoring platforms. Acquisition target archetype: ultrasonic R&D specialists with IP67 validation capabilities but limited commercial scale. Monitor German maritime authority rule expansions to Baltic floating platforms as inflection indicator for redundant sensor demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic-Optical Hybrid Development | Combines time-of-flight measurement with optical encoding to address accuracy-robustness tradeoffs in North Sea installations. |
| Sensor-as-a-Service Subscription Launch | Decouples hardware revenue from predictive maintenance diagnostics, aligning with turbine operator contract renegotiation cycles. |
| IP67 Marine Certification Acceleration | Compresses 8-12 month salt-spray validation timelines to capture German Federal Maritime and Hydrographic Agency contract windows. |
| Neodymium Magnet Supply Integration | Secures captive input from Yangtze River Delta processors to stabilize Hall-effect encoder cost structures against Inner Mongolia volatility. |
| Aviation Certification Pathway Investment | Navigates 18-24 month FAA-EASA timelines to access flight safety infrastructure modernization budgets. |
Research Methodology
Direct dialogue with turbine control engineers, offshore platform maintenance directors, meteorological station procurement leads, and aviation weather system integrators grounded qualitative findings in operational constraints. Secondary validation drew from IEC 61400-12-1 standard documentation, FAA technical specification filings, German Federal Maritime and Hydrographic Agency regulatory notices, and EU Marine Strategy Framework Directive implementation guidelines. Bottom-up sensor shipment estimates by technology tier and installation environment were triangulated against top-down renewable energy capex allocations across the analysis window.
Bottom-up volume modeling segmented by encoding technology, installation classification, and end-use vertical was cross-checked against top-down offshore wind farm development pipeline data. CAGRs were derived from regression analysis across the projection horizon incorporating technology substitution curves for ultrasonic displacement of mechanical alternatives. Industry-specific forecast inputs included Jiangsu and Guangdong provincial grid operator procurement schedules, German redundancy mandate compliance timelines, and REACH substance restriction validation cycles for marine housing materials.
Revisions become necessary when neodymium export restrictions from Inner Mongolia materialize, when FAA-EASA certification timelines extend beyond current baselines, or when consolidated European offshore operators shift from framework agreements to spot procurement. Practitioners should monitor German maritime authority rule expansions, Chinese dual carbon goal provincial implementation intensity, and aviation infrastructure modernization appropriations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Control Knobs for Panel Potentiometer Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Door Control Modules Market
Sensors and Controls
Taiwan Sensors Market
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
Nanopositioning Piezo Actuator Market
Sensors and Controls
Microseismic Monitoring Technology Market
Sensors and Controls
Mass Flow Controller Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
US Pressure Sensors Market