
 Infrared Thermometers Market | 2026-2036
Infrared Thermometers Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Thermometers Market Analysis
Chinese sensor module production is realigning toward higher-precision infrared detector arrays for medical and industrial use. Fluke Corporation leverages its calibration laboratory network to sustain premium positioning in North American industrial channels. Testo SE & Co. KGaA anchors European food safety compliance through handheld units certified to HACCP protocols. FLIR Systems competes on thermal imaging heritage, extending its brand into mainstream thermometer categories through distribution partnerships.
Infrared thermometers measure surface temperature by detecting infrared radiation emitted by objects, typically operating across spectral ranges from 8 to 14 micrometres for non-contact medical applications or narrower bands for industrial furnaces and molten metals. Their primary purpose spans fever screening in clinical settings, process control in manufacturing, and food safety verification in commercial kitchens. Handheld devices dominate unit volume across healthcare and food service channels, while fixed-mount systems command stronger margins in continuous industrial monitoring. Bluetooth-enabled models are gaining traction in laboratory and quality-assurance workflows where data logging integrates with enterprise systems.
FDA 510(k) clearance requirements shape clinical product development cycles in the United States, while ISO 80601-2-56 governs medical electrical equipment accuracy standards internationally. REACH and RoHS compliance in Europe restricts certain substances in sensor housings and electronic components, affecting supply chain sourcing. China's NMPA registration rules for medical devices create a separate approval pathway for clinical-grade units sold domestically. Stakeholders must monitor evolving accuracy thresholds and wireless connectivity certifications as healthcare systems and industrial facilities converge on interoperable thermal monitoring platforms.
Market Dynamics
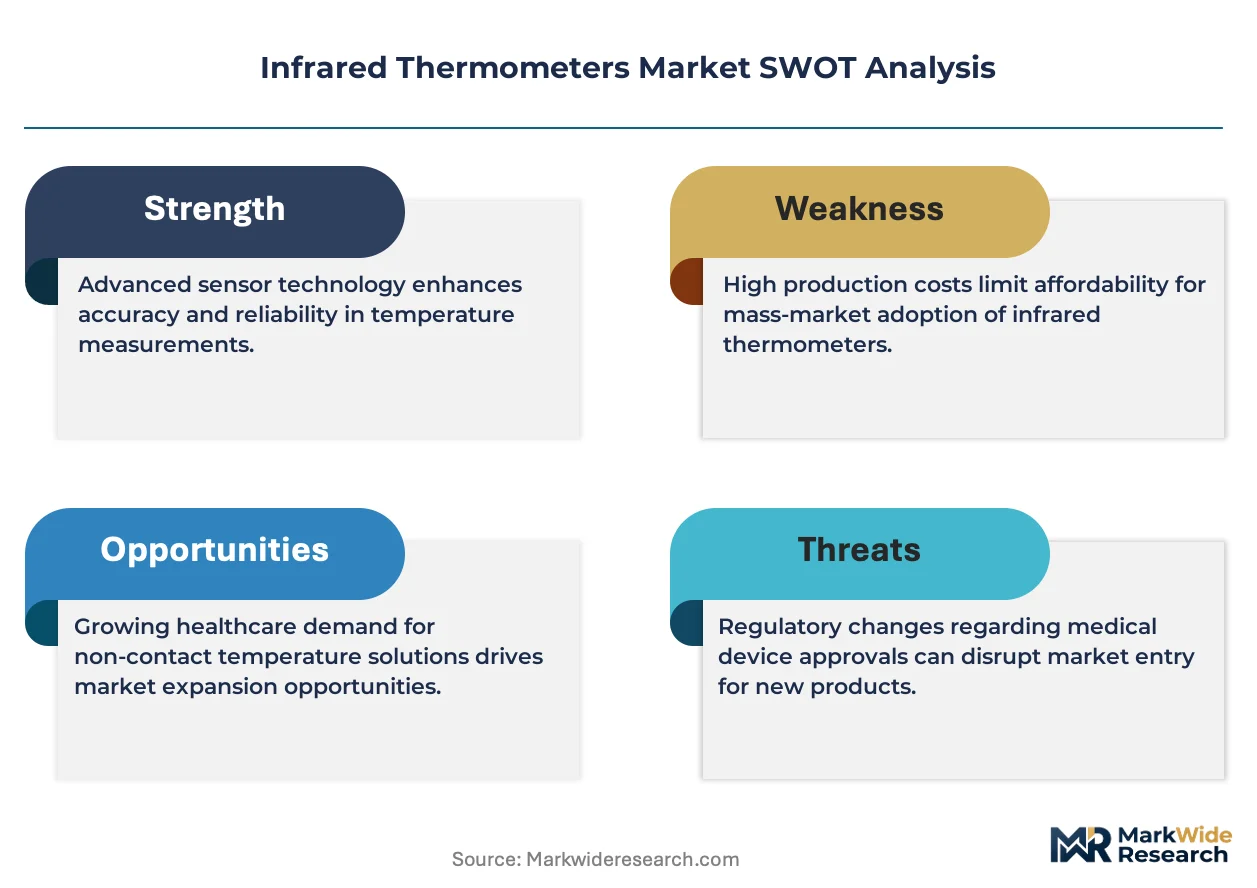
The infrared thermometers market is experiencing structural pressure from FDA tightening 510(k) clearance requirements for clinical-grade accuracy, forcing manufacturers to redesign sensor calibration protocols and extend development timelines by 12-18 months for new medical device submissions.
Growth Catalysts
- Non-contact screening mandates:Healthcare facilities across Germany and the United States are institutionalizing fever detection protocols at entry points, creating installed-base expansion for handheld clinical units.
- ISO 80601-2-56 harmonization:International alignment on medical electrical equipment accuracy standards is reducing regulatory fragmentation and enabling single-SKU strategies for cross-border sales.
- Industrial furnace monitoring:Steel and glass manufacturers in China are retrofitting fixed-mount systems for continuous temperature tracking, displacing thermocouple arrays in high-throughput environments.
Market Restraints
- Indium gallium arsenide detector costs:Precision infrared sensor substrates face price volatility due to concentrated refining capacity, compressing margins on mid-tier clinical devices.
- REACH substance restrictions:ECHA limitations on lead and cadmium in electronic housings force reformulation of sensor encapsulants, extending supplier qualification cycles.
- Contact thermometer substitution:Tympanic and oral thermometers retain preference in pediatric settings where surface emissivity variability undermines infrared reliability.
Strategic Opportunities
- Bluetooth-enabled laboratory workflows:Quality-assurance departments in pharmaceutical manufacturing are adopting data-logging models that integrate directly with enterprise LIMS platforms.
- Food safety compliance in India:FSSAI enforcement of HACCP documentation requirements is opening demand for certified handheld units in cold-chain logistics and hospitality.
- Emissivity-adjustable industrial units:Multi-spectral sensors that auto-calibrate for polished metals versus oxidized surfaces are penetrating aerospace MRO facilities.
Industry Challenges
- FDA 510(k) timeline compression:Clinical-grade submissions face reviewer backlogs and predicate device disputes, delaying revenue recognition for 18-24 months.
- Optical coating supply reconfiguration:German and Japanese specialty coating houses are prioritizing defense and semiconductor customers, extending lead times for medical-grade germanium windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Thermometers Market |
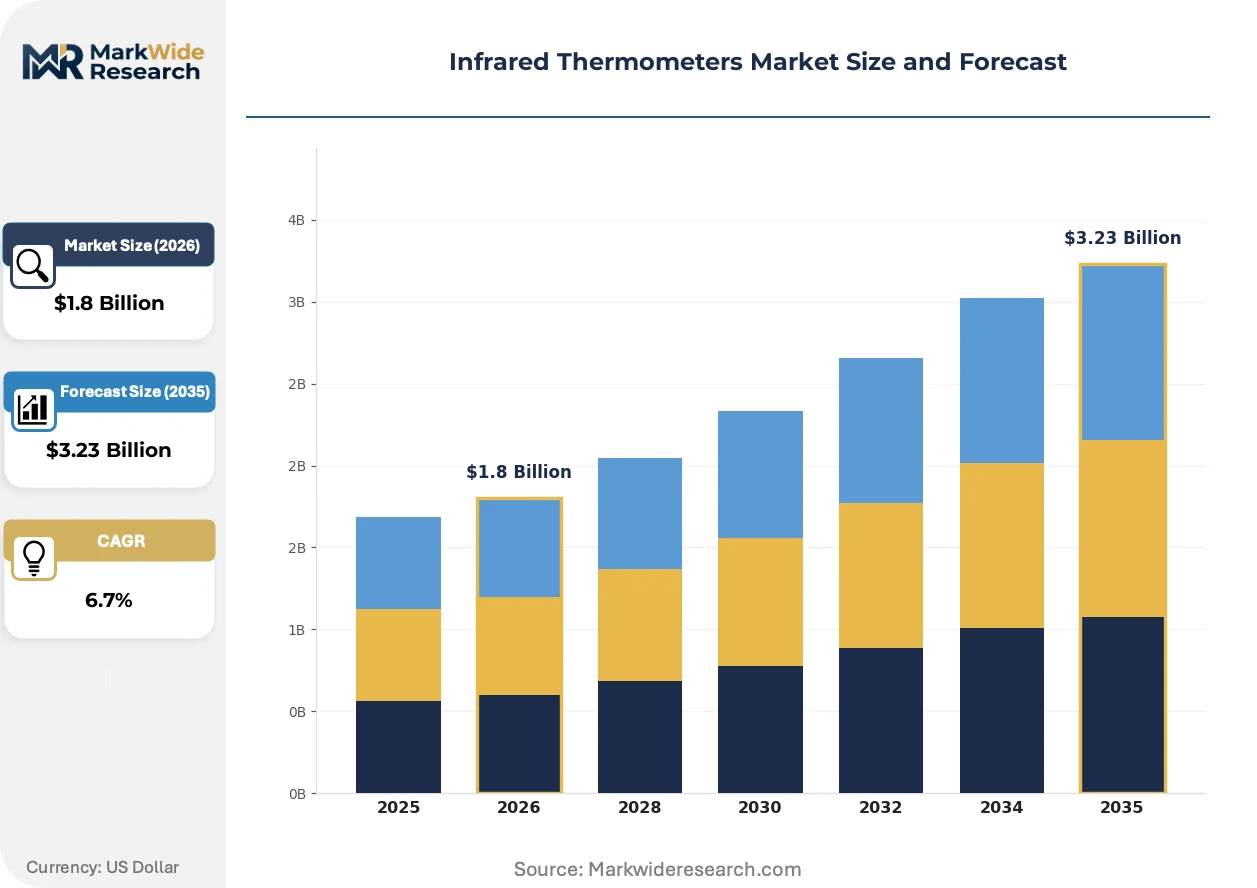
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Handheld, Bluetooth-enabled, Pocket-sized Application: Healthcare, Food Safety, Industrial Monitoring, HVAC End User: Hospitals, Restaurants, Manufacturing Plants, Laboratories Technology: Laser-based, Non-contact, Infrared Sensors, Wi-Fi-enabled |
| Companies Covered | Fluke Corporation, FLIR Systems, Testo SE & Co. KGaA, Optris GmbH, Omega Engineering, AMETEK Land, Omron Healthcare, Microlife Corporation, Chino Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Thermometers Market Emerging Trajectories
Sensor architecture is fragmenting into application-specific configurations as medical and industrial use cases diverge on precision, connectivity, and environmental tolerance requirements. Manufacturers are responding with platform strategies that share core detector technology while customizing signal processing and housing designs.
Multi-pixel infrared detector arrays are modularizing into standardized sub-assemblies that separate optical front-ends from digital back-ends. Medical OEMs in the United States are adopting these modules to accelerate FDA submission timelines by outsourcing detector validation to specialized suppliers. This architecture is compressing the traditional vertically integrated model and enabling faster iteration on ergonomic and software features.
China's NMPA is tightening registration requirements for medical device software, mandating cybersecurity documentation and clinical validation for algorithm-driven temperature compensation. Domestic manufacturers are restructuring quality management systems to accommodate pre-market review expansion. Clinical-grade units sold in China now require separate approval pathways from industrial instruments, bifurcating product portfolios.
Hospital procurement departments are consolidating thermometer purchasing through group purchasing organizations and standardizing on single-vendor platforms to reduce training and maintenance overhead. This concentration is displacing fragmented departmental purchasing in United States health systems. The shift is most visible in integrated delivery networks where standardization mandates now cover both inpatient and ambulatory temperature monitoring protocols.
Infrared Thermometers Market Segmentation
Infrared thermometers serve divergent precision, connectivity, and environmental tolerance requirements across medical, industrial, and commercial domains. Product architecture fragments into application-specific configurations as manufacturers balance standardization economies against customization premiums.
Product Type:
Standardization dominates high-volume handheld production, while fixed-mount and connected variants demand bespoke calibration and housing engineering.
- Fixed:Permanently mounted units integrate into continuous process monitoring systems for steel furnaces and glass manufacturing lines. Steel producers in China are retrofitting fixed-mount arrays to displace thermocouple infrastructure in high-throughput environments.
- Handheld:Battery-powered pistol-grip devices dominate unit volume across clinical screening and food service inspection. German healthcare facilities are institutionalizing handheld units at facility entry points under standardized fever detection protocols.
- Bluetooth-enabled:Wireless data-logging models integrate with enterprise LIMS platforms in pharmaceutical quality assurance. FDA 510(k) clearance requirements extend development timelines for clinical-grade connected devices.
- Pocket-sized:Compact pen-format instruments target consumer and light commercial use with reduced optical resolution. REACH substance restrictions on sensor encapsulants compress margins in this price-sensitive tier.
Most installed capacity flows through Handheld. Expansion is steepest in Bluetooth-enabled.
Application:
Regulatory intensity varies sharply across use cases, with healthcare demanding clinical-grade certification and industrial segments prioritizing environmental tolerance.
- Healthcare:Clinical fever screening requires FDA 510(k) or NMPA registration with ±0.2°C accuracy thresholds. ISO 80601-2-56 harmonization is enabling single-SKU strategies for cross-border hospital procurement.
- Food Safety:HACCP-compliant handheld units verify cold-chain integrity in commercial kitchens and logistics. FSSAI enforcement in India is opening demand for certified devices in hospitality and retail.
- Industrial Monitoring:High-temperature furnace and molten metal applications drive demand for narrow-spectral-range detectors. Emissivity-adjustable multi-spectral sensors are penetrating aerospace MRO facilities.
- HVAC:Building systems diagnostics favor mid-range accuracy with robust environmental sealing. Contact thermometer substitution limits infrared penetration in residential service technician toolkits.
Healthcare commands the highest certification premiums. Food Safety is climbing the fastest as regulatory documentation requirements expand.
End User:
Procurement concentration differs radically between consolidated hospital systems and fragmented restaurant and laboratory purchasing.
- Hospitals:Integrated delivery networks in the United States are consolidating thermometer purchasing through group purchasing organizations. Standardization mandates now cover both inpatient and ambulatory temperature monitoring protocols.
- Restaurants:Fragmented owner-operated establishments drive price competition in food safety segments. HACCP documentation requirements are shifting procurement toward certified units with calibration certificates.
- Manufacturing Plants:Continuous process industries favor fixed-mount systems with 4-20mA output integration. Chinese steel and glass manufacturers are retrofitting thermal monitoring infrastructure.
- Laboratories:Pharmaceutical quality-assurance departments prioritize Bluetooth-enabled models with direct LIMS connectivity. NMPA software registration requirements are bifurcating clinical from industrial product portfolios in China.
Manufacturing Plants represent the largest fixed-mount installed base. Laboratories are expanding most quickly for connected data-logging models.
Technology:
Sensor architecture separates optical front-end precision from digital back-end connectivity as modular sub-assemblies reshape competitive boundaries.
- Laser-based:Visible targeting beams assist operator alignment in industrial and HVAC applications. Optical coating supply reconfiguration from German and Japanese specialty houses is extending lead times for medical-grade components.
- Non-contact:Core infrared detection principle across all product categories, with spectral filtering tailored to target emissivity. Indium gallium arsenide detector substrate costs face volatility from concentrated refining capacity.
- Infrared Sensors:Thermopile and microbolometer detector arrays constitute the foundational measurement element. Chinese sensor module production is realigning toward higher-precision detector arrays for medical and industrial use.
- Wi-Fi-enabled:Enterprise network integration supports centralized monitoring in multi-facility healthcare systems. China's NMPA is tightening cybersecurity documentation requirements for medical device software.
Infrared Sensors anchor all product architectures. Wi-Fi-enabled is gaining share fastest as hospital procurement standardizes on interoperable platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate sensor module assembly to jurisdictions with streamlined medical device approval pathways and concentrated raw material refining capacity.
United States
Hospital procurement consolidation through group purchasing organizations is standardizing thermometer platforms across integrated delivery networks. FDA 510(k) clearance requirements for clinical-grade accuracy are extending development timelines for new medical device submissions. The Boston-Cambridge corridor anchors precision optical coating suppliers serving defense and medical instrument manufacturers.
Germany
Healthcare facilities are institutionalizing fever detection protocols at facility entry points under standardized screening mandates. REACH substance restrictions on lead and cadmium in electronic housings are forcing reformulation of sensor encapsulants and extending supplier qualification cycles. The Stuttgart region concentrates specialty coating houses prioritizing industrial and semiconductor customers.
China
Steel and glass manufacturers are retrofitting fixed-mount thermal monitoring systems to displace thermocouple infrastructure in high-throughput furnace environments. NMPA registration rules for medical device software are mandating cybersecurity documentation and clinical validation for algorithm-driven temperature compensation. The Yangtze River Delta hosts sensor module producers realigning toward higher-precision infrared detector arrays.
Japan
Precision infrared detector substrate production faces price volatility due to concentrated indium gallium arsenide refining capacity. METI industrial standards are harmonizing with ISO 80601-2-56 medical electrical equipment accuracy benchmarks. The Chubu region around Nagoya maintains specialty optical component fabrication for thermal imaging instruments.
India
FSSAI enforcement of HACCP documentation requirements is opening demand for certified handheld units in cold-chain logistics and hospitality operations. CDSCO medical device regulations are creating parallel approval pathways for clinical-grade versus industrial thermal instruments. The Maharashtra-Gujarat industrial corridor is emerging as a distribution hub for food safety compliance equipment.
Infrared Thermometers Market Vendor Landscape
German and Japanese producers anchor one tier of precision optical component supply; Chinese manufacturers hold volume-scale detector array production. The vendor base separates into three strata: vertically integrated instrument builders, modular detector specialists, and calibration service providers. Two dominant competitive moves are reshaping positioning: strategic partnerships between sensor module suppliers and ergonomic design houses, and geographic expansion of calibration laboratory networks to reduce service response times.
Within the precision-tier segment, Fluke Corporation and FLIR Systems exemplify North American positioning anchored in thermal imaging heritage and calibration infrastructure. Testo SE & Co. KGaA occupies a position representing European regulatory compliance specialization. These three entities illustrate how competitive differentiation concentrates in certification depth, service network density, and detector technology access rather than unit manufacturing scale alone.
| Leading Market Players |
|---|
| Fluke Corporation |
| FLIR Systems |
| Testo SE & Co. KGaA |
| Optris GmbH |
| Omega Engineering |
| AMETEK Land |
| Omron Healthcare |
| Microlife Corporation |
| Chino Corporation |
| Others |
Supply Flow & Price Mechanics
Precision optical coating specialists concentrated in Germany and Japan command wage premiums that widen spreads between clinical-grade and industrial thermometer tiers. Labor-cost differentials between European coating houses and Chinese module assemblers translate directly into three distinct price bands across the market.
Pricing Analysis
Distributor margins on clinical-grade handheld units absorb certification documentation costs before hospital procurement committees see landed prices. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared devices from ISO-compliant industrial units and uncertified consumer models. Price differentiation hinges on calibration traceability and wireless connectivity modules. Margins are tightening in the mid-tier clinical segment as Chinese manufacturers achieve NMPA registration parity. Pediatric clinics and small restaurant operators exhibit highest price sensitivity, while integrated hospital systems prioritize standardization over unit cost.
Supply Chain Analysis
Freight costs for germanium optical windows and indium gallium arsenide substrates fluctuate with defense-sector demand spikes from German and Japanese specialty houses. Manufacturing concentrates in China for detector module assembly, Germany for precision coating, and Japan for substrate refining. Raw material dependencies include rare earth elements for sensor encapsulants, germanium for infrared-transparent windows, and specialized polymers for medical-grade housings. Single-source vulnerability in indium refining creates supply continuity exposure. Distribution runs through medical device distributors in North America, industrial instrumentation channels in Europe, and direct OEM relationships in Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between China's streamlined NMPA software registration pathway and the United States' extended FDA 510(k) timelines, with development cost differentials exceeding two-to-one for connected clinical devices.
For Market Incumbents: Lock in calibration laboratory network density to defend service revenue against modular detector suppliers eroding hardware margins. Deepen backward integration into infrared sensor substrate sourcing to offset indium price volatility. Prioritize GPO contract renewals before hospital procurement consolidation peaks.
For New Entrants and Emerging Players: Capture FSSAI enforcement tailwinds in Indian food safety compliance where certified handheld demand outruns established supply. Focus initial penetration on cold-chain logistics operators lacking HACCP documentation infrastructure. Pursue private-label partnerships with European industrial distributors seeking Asian manufacturing alternatives.
For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking thermal monitoring capabilities for smart factory portfolios. Long-term viability rests on software-defined temperature compensation algorithms rather than hardware scale. Monitor NMPA cybersecurity documentation requirements as inflection signal for clinical-grade software valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | Fluke Corporation leverages service density to sustain premium positioning against modular competitors. |
| NMPA Software Registration Investment | Domestic Chinese manufacturers restructure quality systems to capture clinical-grade market share. |
| Bluetooth-Enabled LIMS Integration | Pharmaceutical QA departments adopt data-logging models for enterprise workflow connectivity. |
| Emissivity-Adjustable Sensor Development | Multi-spectral units penetrate aerospace MRO facilities with auto-calibration for surface variability. |
| GPO Consolidation Response | Hospital procurement standardization mandates displace fragmented departmental purchasing across United States health systems. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with biomedical engineers, hospital GPO contracts managers, industrial maintenance directors, and food safety compliance officers. Secondary validation draws from FDA 510(k) filings, NMPA registration databases, ECHA REACH substance restriction updates, and customs trade records for infrared detector module flows. Bottom-up unit shipment estimates triangulate against top-down value projections across product tiers.
Granularity extends to handheld versus fixed-mount form factors, clinical versus industrial certification grades, and wired versus wireless connectivity configurations across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macro healthcare infrastructure spending and industrial automation capex patterns. Forecast inputs incorporate steel furnace retrofit cycles in China, hospital procurement consolidation timelines in the United States, and FSSAI enforcement intensity in India.
Regulatory timeline delays, raw material price spikes, and contact thermometer substitution in pediatric settings are the dominant revision risks to modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Spectrum Analyzer Market
Analytical Instruments
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market
Analytical Instruments
Contact Angle Measuring Instrument Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Spatial Mass Spectrometry Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Thermoluminescent Dosimeter (TLD) System Market
Analytical Instruments
Global Particle Counters Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Electron Probe Microanalyzers (EPMA) Market
Analytical Instruments
Global Gel Documentation Systems Market
Analytical Instruments
Global Spectroscopy Market
Analytical Instruments
High-Vacuum Gauge Market