
 Asia-Pacific Touch Sensor Market | 2026-2036
Asia-Pacific Touch Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Touch Sensor Market Outlook
Project finance for semiconductor foundries is reshaping competitive entry in the Asia-Pacific touch sensor sector. Shenzhen Goodix Technology leverages captive wafer supply partnerships to dominate capacitive controller shipments for smartphones. STMicroelectronics anchors European-Asian hybrid manufacturing footprints, sustaining dual-source resilience for automotive tier-1 customers. Broadcom competes through proprietary signal-processing IP that extends touch latency performance below two milliseconds for premium tablet applications.
Asia-Pacific touch sensors are electro-mechanical transducers that detect physical contact through changes in capacitance, resistance, or optical interruption, typically operating at layer thicknesses below 0.3 millimeters for capacitive variants. These components translate human input into digital signals for display interfaces across consumer and industrial systems. Capacitive technology leads volume shipments due to its multi-touch capability and optical clarity, while pressure sensing represents the fastest-expanding segment as automotive haptic interfaces require force-quantified inputs. Gesture recognition occupies a narrower but higher-margin niche in healthcare sterilization environments where contactless control reduces contamination risk.
China's SAMR enforces GB standards for electromagnetic compatibility in touch-enabled devices, directly shaping product certification timelines for domestic and imported controllers. Japan's METI and South Korea's MFDS coordinate divergent approaches to medical device touch interfaces, creating compliance complexity for vendors serving hospital equipment markets across Northeast Asia. India's BIS mandatory certification for electronic components, expanded under revised consumer protection rules, now covers resistive touch modules used in point-of-sale terminals. Stakeholders must monitor how divergent national standards for durability testing and environmental operating ranges fragment what suppliers can ship across borders without redesign.
Market Dynamics
Foldable display procurement by smartphone manufacturers across China and South Korea is compressing touch sensor form-factor requirements below 0.1 millimeter thickness, forcing controller suppliers to redesign signal-to-noise architectures for crease-zone durability.
Growth Catalysts
- Automotive haptic interfaces:Force-quantified input requirements from tier-1 automotive suppliers in Japan are expanding pressure-sensing module volumes for center-console applications.
- METI energy-efficiency mandates:Japan's tightening standby-power regulations for consumer electronics are accelerating low-power capacitive controller adoption across white-goods manufacturers.
- Guangdong cluster concentration:Display panel foundries in Shenzhen and Dongguan are localizing touch sensor lamination within 50-kilometer radii, reducing logistics friction for smartphone OEMs.
Market Restraints
- Indium tin oxide price volatility:Capacitive electrode material costs fluctuate with rare-earth export quotas from Chinese suppliers, squeezing margin structures for mid-tier controller vendors.
- Single-source photomask dependency:Advanced touch-ASIC lithography relies on two Japanese equipment suppliers, creating concentration risk for 28-nanometer node production.
- Optical fingerprint substitution:Under-display ultrasonic sensors are displacing capacitive home-button modules in premium smartphones, eroding legacy controller demand.
Strategic Opportunities
- India BIS certification expansion:Mandatory electronic component testing for point-of-sale terminals creates first-mover advantage for resistive touch vendors establishing local calibration labs.
- Healthcare sterilization environments:Gesture recognition modules for contactless surgical equipment control command 40-60% gross margins in South Korean hospital procurement.
- Automotive-grade multi-stack integration:Convergence of touch, force, and haptic feedback layers into single lamination stacks reduces BOM complexity for EV dashboard suppliers.
Industry Challenges
- Signal-processing firmware talent scarcity:Capacitive noise-cancellation algorithm development requires mixed-signal engineering expertise concentrated in Hsinchu and Seoul, constraining vendor scaling.
- Dual-certification timeline compression:Parallel METI and MFDS medical-device touch interface approvals for hospital equipment extend product launch cycles by 8-14 months.
- Legacy automotive system integration:CAN bus protocol translation for retrofitted touch interfaces in existing vehicle platforms demands custom gateway hardware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Touch Sensor Market |
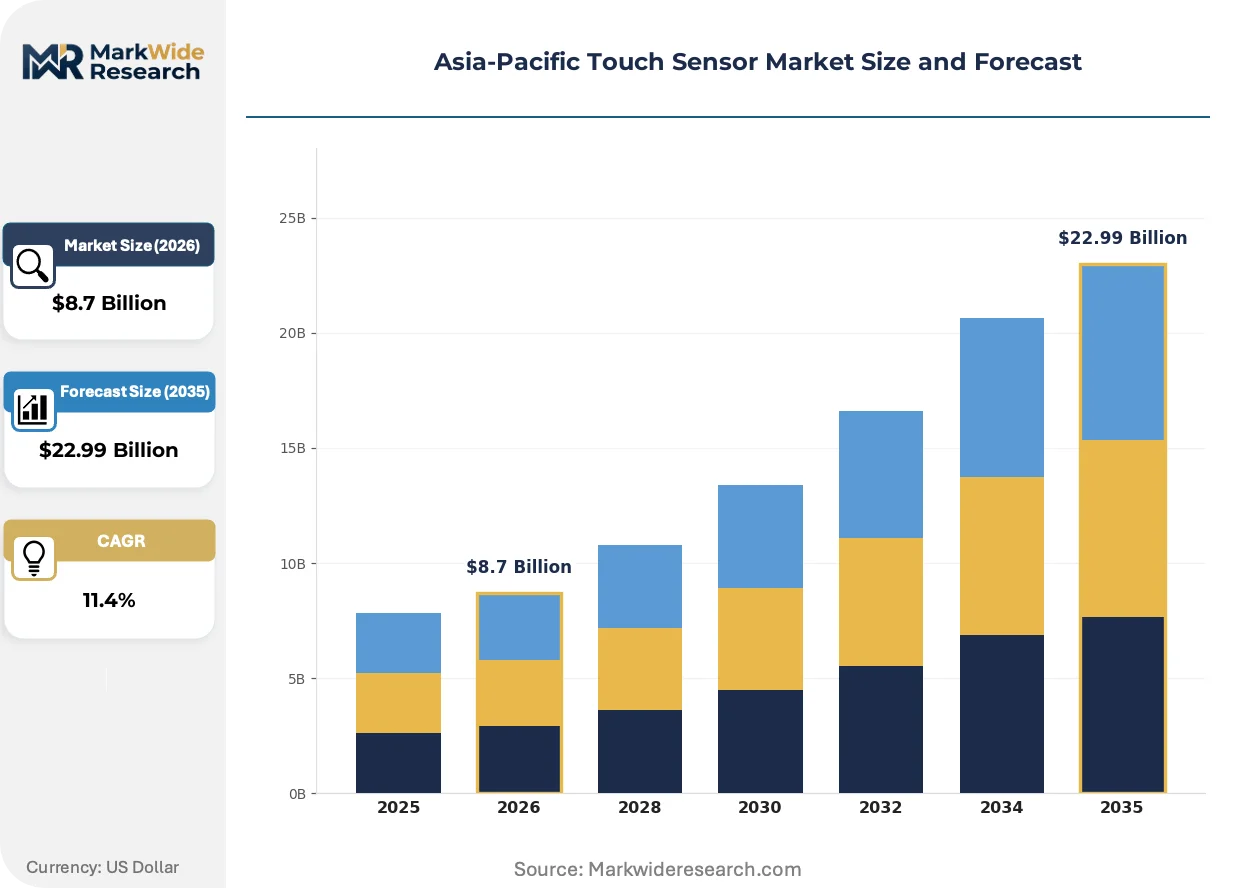
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Resistive, Infrared, Optical End User: Consumer Electronics, Automotive, Healthcare, Industrial Technology: Multi-Touch, Single-Touch, Gesture Recognition, Pressure Sensing Application: Smartphones, Tablets, Automotive Displays, Point-of-Sale Terminals |
| Companies Covered | Synaptics Incorporated, Broadcom, STMicroelectronics, Texas Instruments, Shenzhen Goodix Technology, Microchip Technology, Elan Microelectronics, FocalTech Systems, NXP Semiconductors, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Touch Sensor Market Strategic Shifts
Signal-processing architectures are migrating from discrete analog front-ends to software-defined detection pipelines, compressing hardware BOMs while expanding multi-touch resolution capabilities for foldable form factors.
Self-capacitance-to-mutual-capacitance hybrid detection is virtualizing electrode routing patterns, enabling single-layer sensor films to achieve two-layer performance. Chinese display integrators in Guangdong province are adopting this architecture for mid-tier smartphone lines, collapsing traditional ITO patterning steps and reducing lamination thickness by 30-40 microns. The technology is virtualizing supply chain tiering between premium and standard controller segments.
China's SAMR GB electromagnetic compatibility standards for touch-enabled devices are tightening conducted-emission limits above 30 MHz, forcing controller vendors to redesign power-supply filtering stages. Domestic certification timelines have extended by 6-10 weeks for imported ASICs, pushing multinational suppliers toward joint-venture local testing facilities. Medical-grade touch controllers face the steepest compliance burden under revised hospital-equipment interference protocols.
Component sourcing is consolidating through direct foundry partnerships rather than merchant distributor channels, with smartphone OEMs in South Korea negotiating wafer-start commitments 12-18 months forward. This procurement compression is displacing spot-market purchasing for capacitive controller die, concentrating volume commitments among three dominant foundry relationships. The shift is most visible in Seoul-based procurement offices managing foldable display ramp schedules.
Asia-Pacific Touch Sensor Market Segmentation
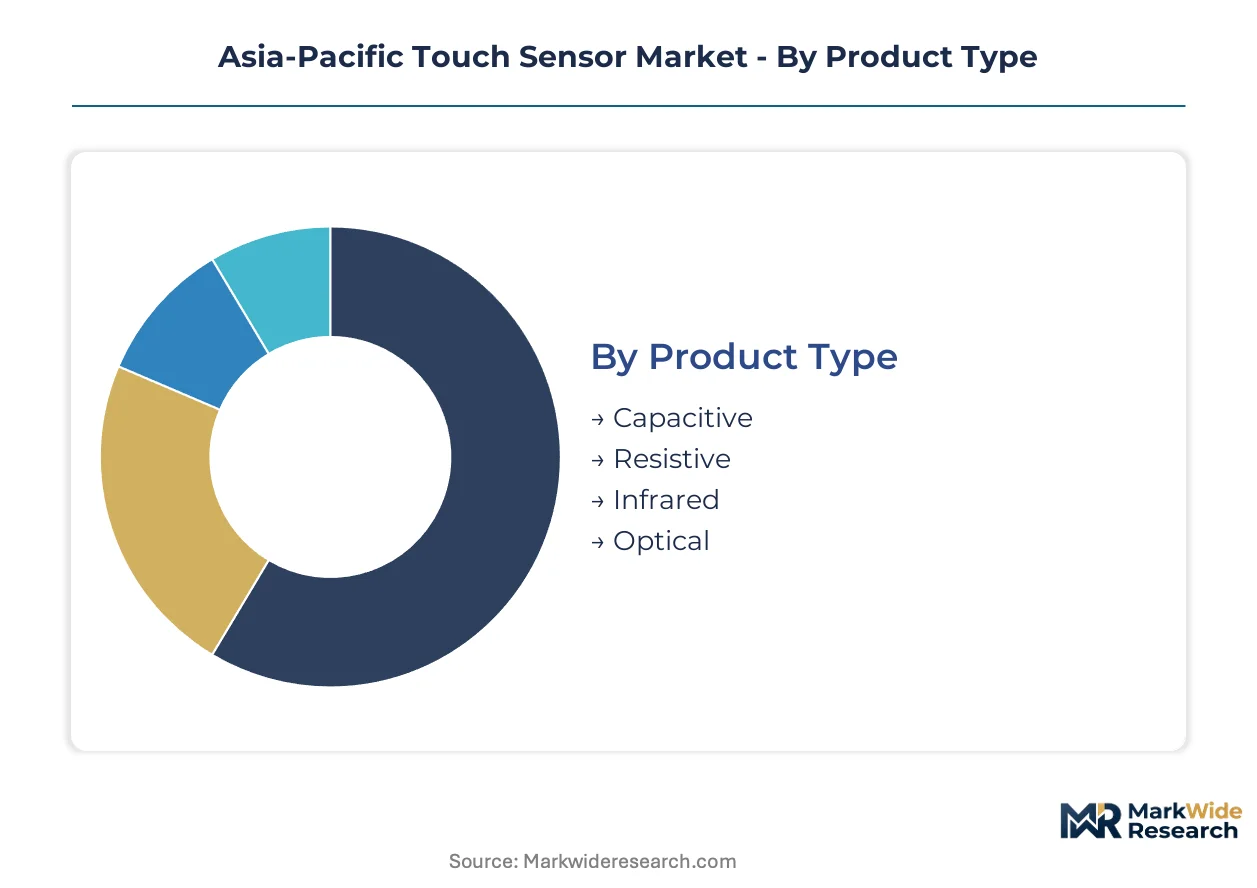
Touch sensor segmentation in the Asia-Pacific region reflects divergent procurement cycles across consumer, automotive, and industrial verticals. Controller vendors must align product roadmaps with smartphone OEMs' 12-month refresh cadences while simultaneously supporting automotive tier-1s' 36-48 month platform commitments.
Product Type:
Capacitive and resistive variants dominate replacement schedules measured in months, whereas infrared and optical technologies lock into multi-year infrastructure deployments.
- Capacitive:Electrode arrays detect touch through mutual-capacitance field disruption, achieving sub-0.3 millimeter stack heights. Smartphone manufacturers across South Korea and China source these for foldable displays where crease-zone durability demands signal-to-noise architecture redesigns.
- Resistive:Pressure-activated membrane sandwiches translate mechanical force into resistance changes, tolerating stylus and gloved input. India's BIS certification expansion for point-of-sale terminals is accelerating procurement from Guangdong lamination clusters.
- Infrared:LED-phototransistor grids frame display perimeters for touch detection without surface overlay. Large-format digital signage deployments in Japanese rail stations specify these for vandal-resistant public interfaces.
- Optical:Camera-based or waveguide systems interpret touch through light interruption patterns. Under-display fingerprint modules in premium Chinese smartphones are displacing legacy capacitive home-button implementations.
Capacitive variants anchor the volume base while optical technologies gain share at the steepest rate.
End User:
Cost tier stratification separates high-volume consumer shipments from automotive and healthcare segments where certification premiums justify controller ASP multiples.
- Consumer Electronics:Smartphones, tablets, and wearables drive the highest absolute shipment volumes with compressed 9-12 month product lifecycles. South Korean OEM procurement offices in Seoul negotiate wafer-start commitments 12-18 months forward for foldable display ramp schedules.
- Automotive:Center-console and dashboard interfaces require AEC-Q100 qualified controllers with extended temperature ranges. Japanese tier-1 suppliers specify force-quantified pressure sensing for haptic feedback integration in EV platforms.
- Healthcare:Sterilization-compatible touch surfaces and contactless gesture modules command substantial gross margin premiums. South Korean hospital procurement under MFDS medical device regulations favors gesture recognition for surgical equipment contamination control.
- Industrial:HMI panels and factory automation terminals prioritize environmental sealing and electromagnetic immunity. China's SAMR GB electromagnetic compatibility standards tighten conducted-emission limits for industrial controller certification.
Consumer electronics anchors the volume base while healthcare applications expand most quickly on margin-driven procurement.
Technology:
Volume concentration clusters around mature multi-touch and single-touch implementations, with pressure sensing and gesture recognition capturing emerging application niches.
- Multi-Touch:Parallel capacitance scanning enables simultaneous finger tracking for pinch, zoom, and rotate gestures. Chinese display integrators in Shenzhen and Dongguan deploy hybrid self-mutual capacitance architectures to collapse ITO patterning steps.
- Single-Touch:Simplified detection circuitry serves cost-optimized resistive applications in legacy industrial panels and budget consumer devices. Indian point-of-sale terminal manufacturers specify these for BIS-certified resistive module integration.
- Gesture Recognition:Time-of-flight and radar-based sensing enables contactless control for sterile environments. South Korean hospital equipment vendors deploy these modules where surgical scrub protocols prohibit surface contact.
- Pressure Sensing:Force-sensitive resistor or strain-gauge layers quantify input pressure for haptic feedback loops. Japanese automotive tier-1s are expanding procurement for center-console applications requiring force-quantified inputs.
Multi-touch anchors the volume base while pressure sensing climbs the fastest on automotive haptic interface adoption.
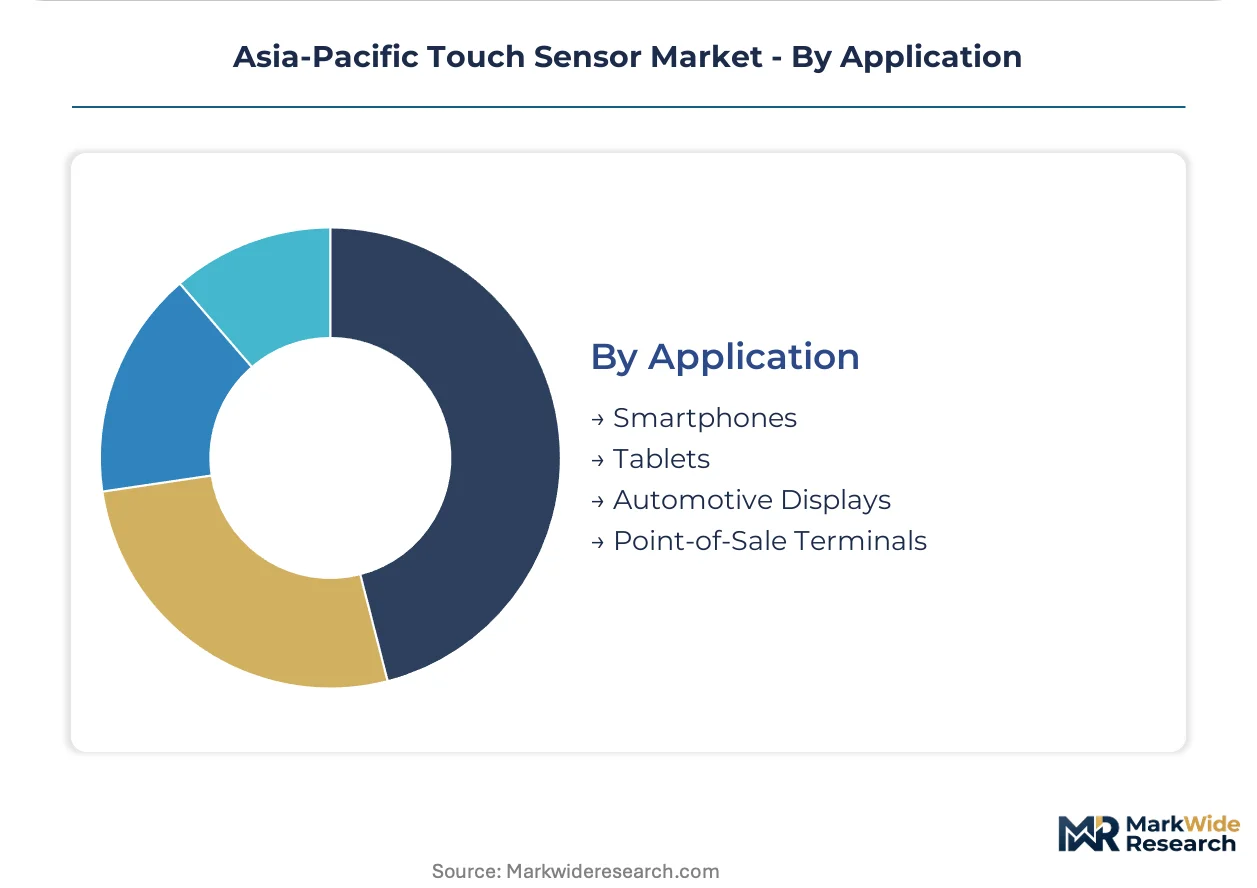
Application:
Geographic procurement patterns concentrate smartphone and tablet demand in Northeast Asian manufacturing clusters, while automotive and POS terminals distribute across broader national markets.
- Smartphones:Foldable form factors below 0.1 millimeter thickness are compressing controller signal-to-noise requirements. Chinese OEMs in Guangdong province localize touch sensor lamination within 50-kilometer radii of display panel foundries.
- Tablets:Premium stylus-compatible interfaces demand sub-two-millisecond latency for handwriting capture. Broadcom's proprietary signal-processing IP targets this specification tier for South Korean and Chinese tablet OEMs.
- Automotive Displays:Curved and free-form dashboard surfaces require conformable sensor films with automotive-grade reliability validation. Japanese METI energy-efficiency mandates for standby power are accelerating low-power capacitive controller adoption.
- Point-of-Sale Terminals:Resistive touch durability suits high-frequency retail environments with gloved or stylus operation. India's BIS mandatory certification expansion creates first-mover positioning for vendors establishing local calibration infrastructure.
Smartphone applications anchor the volume base while automotive displays gain share on EV platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed semiconductor incentives across Northeast Asia are accelerating touch sensor localization. National industrial policies in China, South Korea, and Japan prioritize captive controller supply chains for display manufacturing.
China
Smartphone OEM procurement for foldable displays drives controller demand in Guangdong province. SAMR enforces GB electromagnetic compatibility standards that extend certification timelines for imported ASICs by 6-10 weeks. Shenzhen and Dongguan display panel clusters now localize touch sensor lamination within 50-kilometer radii.
South Korea
Seoul-based procurement offices negotiate wafer-start commitments 12-18 months forward for foldable display ramp schedules. MFDS medical device regulations govern hospital equipment touch interfaces, creating compliance complexity alongside Japanese METI standards. Busan-Ulsan manufacturing corridors anchor automotive haptic interface production for EV platforms.
Japan
METI energy-efficiency mandates for standby power accelerate low-power capacitive controller adoption across white-goods manufacturers. PMDA and METI coordinate divergent approval timelines for medical device touch interfaces, extending product launch cycles. Nagoya automotive tier-1s specify force-quantified pressure sensing for center-console applications.
India
BIS mandatory certification expansion under revised consumer protection rules now covers resistive touch modules for point-of-sale terminals. Domestic calibration infrastructure remains underdeveloped, creating first-mover positioning for vendors establishing local testing labs. Maharashtra and Karnataka electronics manufacturing zones concentrate terminal assembly operations.
Vietnam
Smartphone assembly relocation from China drives secondary touch sensor module demand in Bac Ninh and Bac Giang provinces. General functional oversight from national electronics regulators shapes import compliance for controller components. Ho Chi Minh City logistics hubs coordinate Southeast Asian distribution for Guangdong-sourced sensor films.
Asia-Pacific Touch Sensor Market Competitive Environment
On the supply side, the industry is consolidating around captive foundry partnerships and proprietary signal-processing IP. Controller vendors fragment across three tiers: integrated display-panel suppliers with in-house ASIC design, fabless specialists leveraging merchant foundry capacity, and diversified semiconductor conglomerates serving automotive qualification requirements. Competitive positioning depends on backward integration into wafer supply, technology licensing for noise-cancellation algorithms, and geographic diversification of test-and-assembly operations.
Within the fabless specialist tier, Shenzhen Goodix Technology exemplifies the China-based controller archetype that dominates capacitive shipments through captive wafer partnerships. STMicroelectronics anchors the European-Asian hybrid manufacturing footprint, sustaining dual-source resilience for automotive customers. Broadcom occupies a position in premium tablet applications where proprietary signal-processing IP extends touch latency performance below two milliseconds.
| Leading Market Players |
|---|
| Synaptics Incorporated |
| Broadcom |
| STMicroelectronics |
| Texas Instruments |
| Shenzhen Goodix Technology |
| Microchip Technology |
| Elan Microelectronics |
| FocalTech Systems |
| NXP Semiconductors |
| Others |
Value Chain & Pricing Dynamics
Indium tin oxide refining capacity concentrated in Chinese rare-earth processing zones anchors margin distribution across capacitive electrode supply tiers. Controller vendors absorb commodity volatility through long-term offtake structures or pass-through clauses in automotive tier-1 contracts.
Pricing Analysis
Certification level creates the primary spread between automotive AEC-Q100 qualified controllers and consumer-grade alternatives. Pricing stratifies across premium, standard, and economy tiers where medical-grade MFDS compliance commands substantial premiums over industrial variants. Cost compression in mid-tier smartphone controllers is intensifying because Guangdong display integrators consolidate procurement through captive foundry partnerships. Automotive OEMs exhibit lowest price sensitivity due to 36-48 month platform lock-ins, while Indian POS terminal manufacturers face acute pressure from BIS certification overhead.
Supply Chain Analysis
Japanese photolithography equipment export controls constrain 28-nanometer touch-ASIC fabrication flows to Chinese foundries. Manufacturing concentrates in Taiwan, South Korea, and Japan where advanced node capacity feeds controller die production. Raw material dependencies include indium tin oxide for electrodes, photomasks from Japanese suppliers, and specialty glass substrates. Single-source photomask vulnerability represents the dominant structural risk for advanced controller ramp schedules. Distribution runs through direct OEM procurement offices in Seoul and Shenzhen rather than merchant distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific touch sensor demand sits in early-cycle expansion as foldable display adoption accelerates across Chinese and South Korean smartphone OEMs. Penetration headroom remains substantial in automotive haptic interfaces and healthcare gesture recognition.
For Market Incumbents: Build captive wafer supply moats through 12-18 month forward commitments at dominant foundry relationships. Deepen backward integration into ITO patterning capabilities to offset rare-earth price volatility. Defend against ultrasonic fingerprint substitution by accelerating under-display capacitive controller development. Prioritize dual-source resilience for photomask supply to mitigate Japanese equipment concentration risk. For New Entrants and Emerging Players: India's BIS-certified resistive touch modules for point-of-sale terminals represent the most penetrable entry point given underdeveloped domestic calibration infrastructure. South Korean hospital procurement for MFDS-compliant gesture recognition offers 40-60% gross margin capture in surgical equipment sterilization environments. Establish local testing labs in Maharashtra electronics manufacturing zones as the primary go-to-market anchor. For Investors and Strategic Acquirers: Secondary-cycle assets sit with fabless controller specialists holding proprietary noise-cancellation algorithm IP. Long-term viability across the projection horizon hinges on automotive qualification breadth and foldable display design-win pipelines. Watch for inflection signals in Seoul-based procurement office wafer-start commitment volumes as forward demand indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Consolidation | Captive wafer supply agreements with TSMC or Samsung Foundry secure controller die allocation for foldable display ramps. |
| Automotive AEC-Q100 Certification | Extended temperature range qualification unlocks tier-1 procurement from Nagoya-based EV dashboard suppliers. |
| Hybrid Capacitance Architecture Deployment | Self-mutual capacitance virtualization collapses ITO patterning steps for 30-40 micron thickness reduction in mid-tier smartphones. |
| India BIS Calibration Infrastructure | Local testing lab establishment captures first-mover positioning in point-of-sale terminal certification expansion. |
| Medical Device Dual Certification | Parallel METI and MFDS approval capabilities compress 8-14 month launch cycle extensions for hospital equipment vendors. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SAMR regulatory filings, GB standard certification databases, and automotive tier-1 procurement disclosures. Touch controller engineering directors, display panel procurement managers in Guangdong, and hospital biomedical engineers in South Korea provided operational validation. Secondary sources include SEC semiconductor filings, IHS Markit vehicle production data, and BIS certification registries. Bottom-up shipment estimates triangulate against top-down display panel production forecasts.
Forecast inputs incorporate technology migration curves for foldable form factors, automotive EV platform proliferation rates, and medical device regulatory approval timelines. Segmentation dimensions span product type, end-user vertical, technology implementation, and application category across the analysis window. CAGRs derive from installed base replacement cycles, penetration rate assumptions, and content-per-unit trajectories. Industry-specific inputs include indium tin oxide price elasticity coefficients and foundry capacity utilization thresholds.
Practitioners should monitor rare-earth export quota announcements, photolithography equipment export control adjustments, and foldable display yield rate improvements for early signals. Forecasts reflect assumptions regarding continued smartphone OEM procurement consolidation and automotive haptic interface standardization. Material shifts in Japanese semiconductor equipment trade policy or Chinese display panel capacity expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
APAC Temperature Sensors Market
Sensors and Controls
Absolute Pressure Sensor Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Hydrogen Monitor Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Volatile Organic Compound Gas Sensor Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Piezoelectric Materials Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Mexico Digital Thermometer Market