
 Digital Temperature Gauge Market | 2026-2036
Digital Temperature Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Temperature Gauge Market Outlook
Germany is fragmenting digital temperature gauge manufacturing capacity as precision instrument makers respond to industrial automation pull. WIKA Alexander Wiegand SE & Co. KG anchors high-accuracy gauge production for process industries across Europe. Fluke Corporation leverages its calibration heritage to dominate portable diagnostic segments. Testo SE & Co. KGaA specializes in food safety applications where regulatory compliance dictates instrument selection.
A digital temperature gauge converts thermal energy into quantified electrical signals through thermocouple, resistance temperature detector, or infrared sensor architectures, displaying processed readings on liquid-crystal or LED interfaces with typical accuracies between 0.1°C and 2.2°C depending on sensor class. These instruments serve critical process control, quality assurance, and safety monitoring functions across manufacturing and commercial environments. Infrared product types capture expanding share in non-contact measurement scenarios where product contamination risks prohibit probe insertion. Laboratory applications sustain premium pricing through calibration traceability requirements that exclude lower-tier suppliers. Wired technology segments retain dominance in heavy industrial settings where electromagnetic interference compromises wireless reliability.
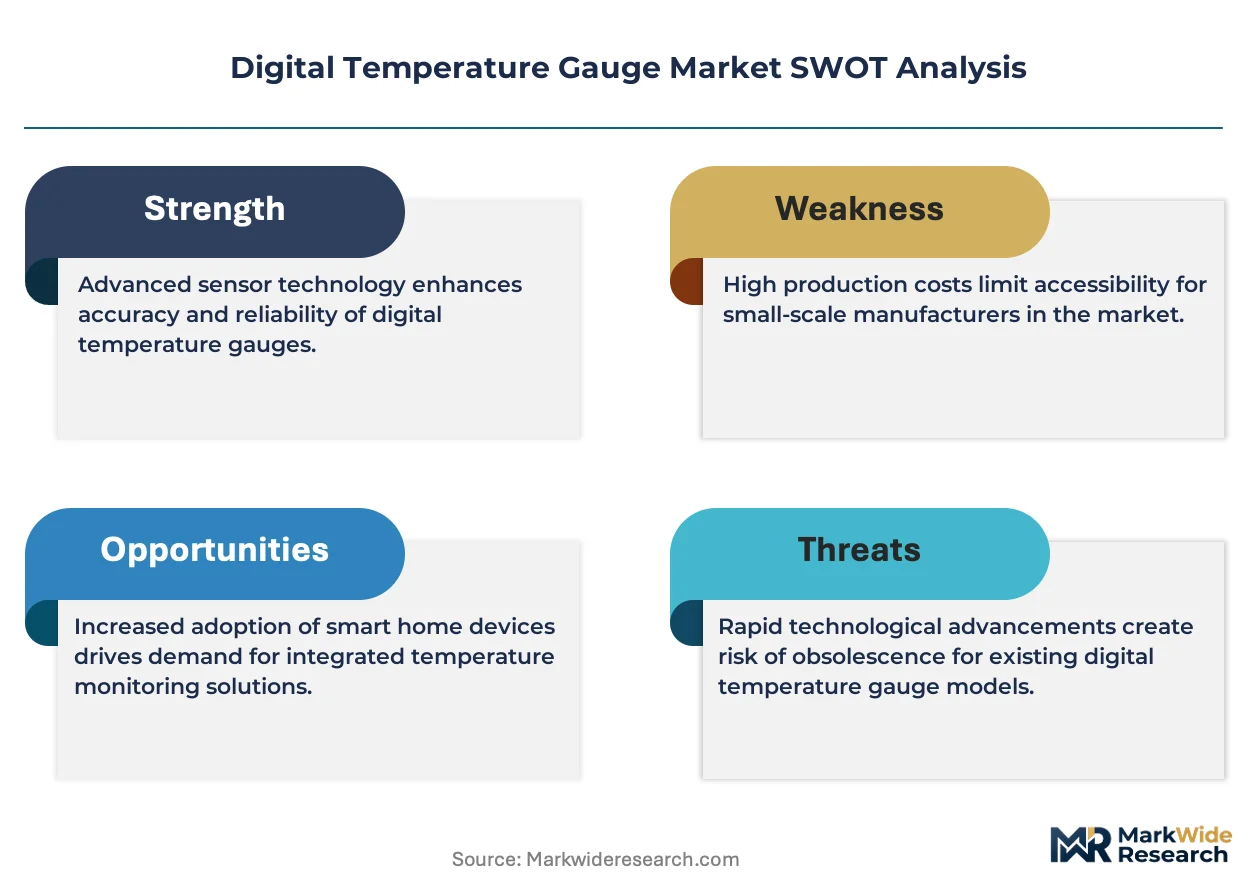
FDA food safety regulations and HACCP enforcement in the United States compel continuous temperature documentation, directly expanding digital gauge deployment in processing plants. EU MDR and CE marking requirements for medical-grade instruments elevate compliance costs for manufacturers serving European healthcare end users. Stakeholders must monitor evolving cybersecurity standards for wireless-connected gauges as industrial IoT adoption accelerates in critical infrastructure settings.
Market Dynamics
Wireless sensor architectures and industrial IoT protocols are compressing replacement cycles for wired instrumentation, forcing incumbents to reengineer product portfolios around connectivity stacks rather than measurement accuracy alone.
Growth Catalysts
- HACCP Enforcement:FDA food safety mandates in the United States require continuous temperature documentation across processing lines, compelling facility upgrades to digital logging systems.
- Industrial Automation:Germany's manufacturing base sustains elevated investment in precision process control, pulling high-accuracy gauge demand from automotive and chemical sectors.
- Infrared Non-Contact Sensing:Pharmaceutical aseptic filling operations adopt IR architectures to eliminate probe contamination risks in sterile environments.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea dominate ASIC fabrication for signal conditioning circuits, exposing gauge makers to single-source fragility.
- Calibration Infrastructure Costs:ISO 17025-accredited laboratories require six-figure capital commitments for traceable reference standards, elevating barrier to tier-one supplier status.
- Wireless Reliability Limits:Electromagnetic interference in heavy industrial settings constrains 2.4 GHz protocol adoption, preserving wired architecture dominance in steel and cement plants.
Strategic Opportunities
- India Food Processing Expansion:FSSAI enforcement tightens across cold chain logistics, creating first-time digital gauge demand in dairy and seafood distribution networks.
- EU MDR Medical-Grade Certification:CE marking requirements for patient-contact temperature monitoring exclude uncertified competitors, concentrating margin in compliant suppliers.
- Edge AI Integration:Convergence of on-device inference with temperature sensing enables predictive maintenance alerts without cloud dependency, opening premium positioning in critical infrastructure.
Industry Challenges
- Embedded Firmware Talent Scarcity:Gauge manufacturers compete with automotive and consumer electronics for engineers skilled in low-power wireless stack development.
- Legacy System Integration:4-20 mA analog outputs persist in decades-old distributed control systems, forcing dual-protocol engineering that extends development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Temperature Gauge Market |
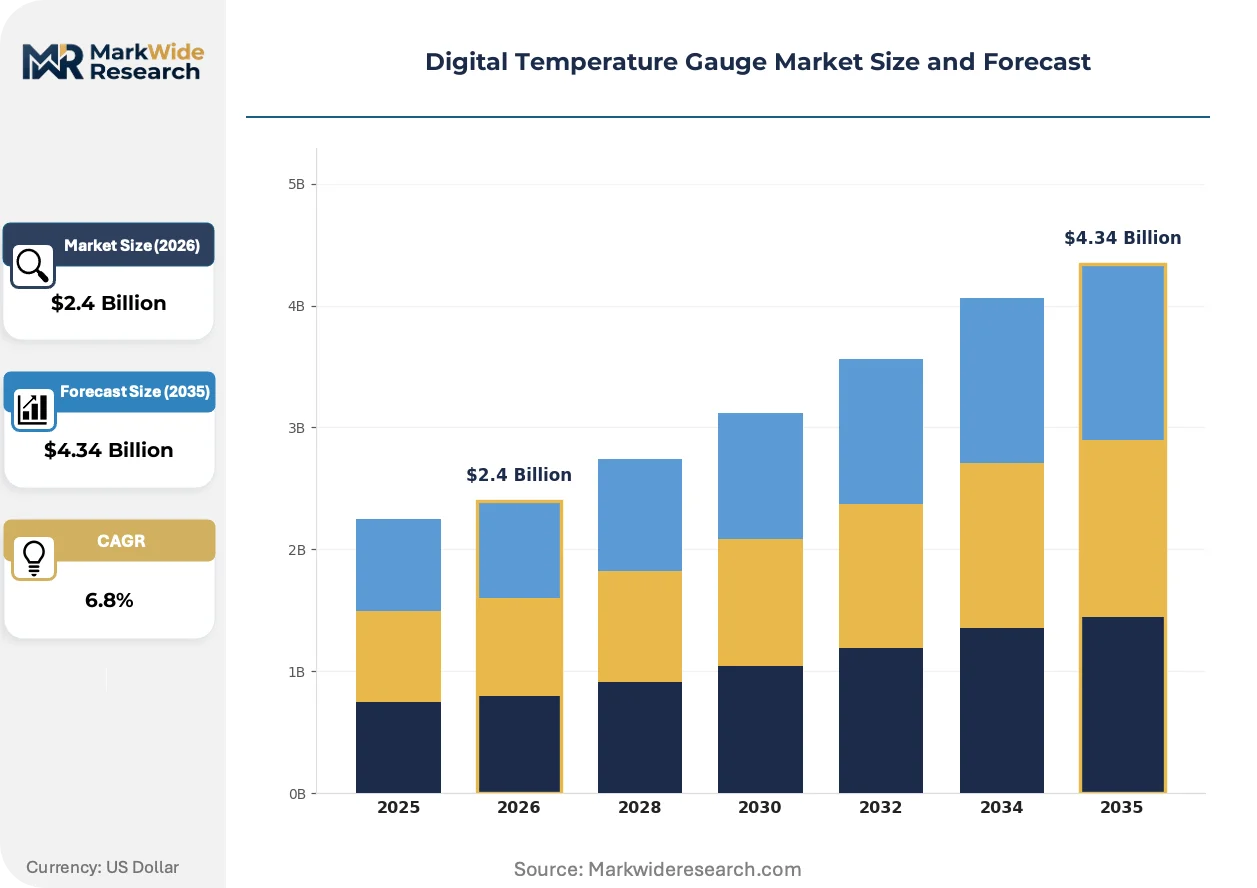
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared, Thermocouple, Bimetallic, Resistance Application: Food Processing, Industrial, HVAC, Laboratory End User: Manufacturing, Healthcare, Automotive, Retail Technology: Wireless, Wired, Analog, Digital |
| Companies Covered | Fluke Corporation, Testo SE & Co. KGaA, Omega Engineering, WIKA Alexander Wiegand SE & Co. KG, Endress+Hauser Group Services AG, Extech Instruments, Hart Scientific, Ashcroft (Nagano Keiki), Kimo Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Temperature Gauge Market Strategic Shifts
Measurement architectures are bifurcating between ultra-precise laboratory-grade instrumentation and ruggedized edge devices, with connectivity and on-device intelligence becoming the primary differentiation vectors.
MEMS-based temperature sensors with integrated digital output are rendering obsolete discrete thermocouple assemblies requiring cold-junction compensation circuits. Pharmaceutical packaging lines in Switzerland and Germany adopt these monolithic solutions for rapid sterilization validation. The elimination of signal conditioning boards compresses bill-of-material costs and shrinks calibration drift windows.
EU F-Gas Regulation phase-down schedules are accelerating infrared sensor adoption as non-contact alternatives to probe-based measurement in refrigeration system monitoring. Industrial cold storage operators in France and the Netherlands retrofit existing infrastructure with IR gauges to maintain compliance without refrigerant venting. The regulatory friction is shifting specification priority from accuracy to measurement range and response speed.
Equipment-as-a-service contracting is displacing capital purchase models for high-volume food processing chains. Temperature monitoring hardware bundles into per-unit processing fees, transferring obsolescence risk from plant operators to instrumentation vendors. This restructuring concentrates most visibly in Nordic dairy cooperatives and German meat processing conglomerates seeking to offload asset management overhead.
Digital Temperature Gauge Market Segmentation
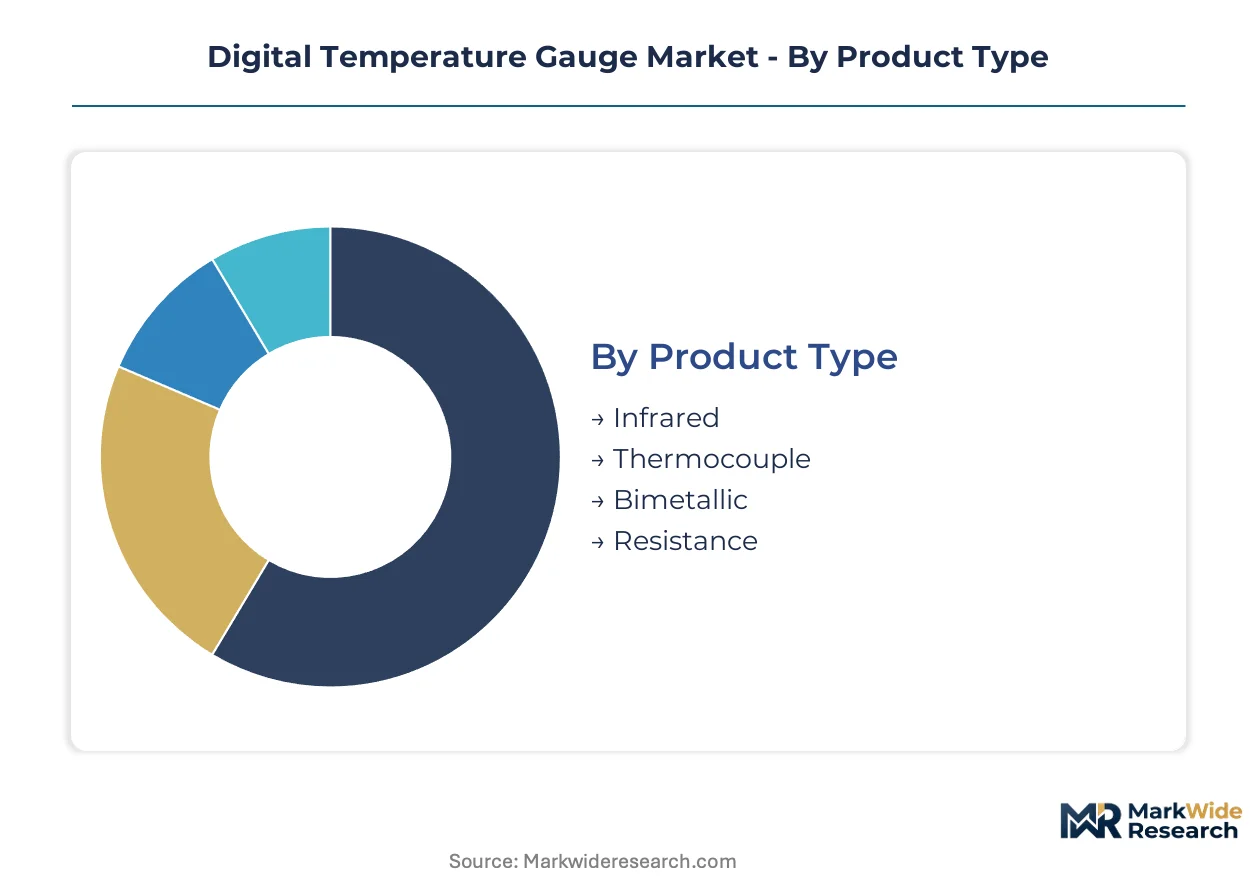
Digital temperature gauge procurement varies sharply by installation environment, with calibration intervals and connectivity requirements driving total cost of ownership calculations across industrial and commercial settings.
Product Type:
After-sales service intensity diverges dramatically across sensor architectures, with contact-based systems demanding periodic calibration recertification while non-contact alternatives require lens maintenance and emissivity adjustment protocols.
- Infrared:Non-contact measurement via thermal radiation detection enables sterile pharmaceutical filling lines and hazardous zone monitoring without probe contamination. Demand clusters in Swiss and German pharmaceutical packaging facilities where EU GMP Annex 1 sterility requirements prohibit physical intrusion. F-Gas Regulation compliance in French and Dutch cold storage operations accelerates retrofit demand for refrigerant system monitoring.
- Thermocouple:Junction of dissimilar metals generates voltage proportional to temperature differential, supporting extreme range measurement from cryogenic to furnace applications. German automotive foundries and steel producers specify Type K and Type S configurations for molten metal process control where 0.75% accuracy tolerances suffice.
- Bimetallic:Differential expansion of bonded metal strips drives mechanical indication without electrical power, sustaining niche demand in explosion-proof environments and remote field installations.
- Resistance:Platinum RTD elements deliver 0.1°C precision for laboratory calibration chains and custody transfer measurement in petrochemical loading terminals.
Infrared holds the largest share; momentum sits with thermocouple architectures in heavy industrial retrofit cycles.
Application:
Cost tier stratification separates premium laboratory instrumentation from volume industrial deployments, with certification grade and connectivity protocol determining pricing bands.
- Food Processing:HACCP-mandated continuous logging drives digital gauge density across US poultry and dairy processing lines, with FDA enforcement expanding documentation requirements to cold chain distribution nodes.
- Industrial:Process control instrumentation in German chemical and automotive sectors sustains demand for SIL-rated devices with 4-20 mA and HART protocol compatibility.
- HVAC:Building automation integration favors wireless BACnet and Modbus implementations, with EU Energy Performance of Buildings Directive driving sensor deployment in commercial retrofits.
- Laboratory:ISO 17025 traceability requirements confine procurement to accredited suppliers, with calibration certificate validity determining instrument lifecycle economics.
Food processing commands volume leadership; HVAC applications are expanding most quickly through smart building mandates.
End User:
Customer type determines procurement channel and specification authority, with centralized engineering teams in manufacturing contrasting decentralized facility management in retail.
- Manufacturing:Process industries specify gauges through instrument engineering departments with integrated distributed control system architectures, favoring established suppliers with global service networks.
- Healthcare:EU MDR and FDA 510(k) requirements for patient-contact temperature monitoring elevate compliance costs, concentrating supply among certified medical device manufacturers.
- Automotive:EV battery cell formation and thermal runaway testing protocols create demand for multi-channel data acquisition systems with millisecond sampling rates.
- Retail:Cold chain monitoring for grocery and pharmacy segments prioritizes wireless cloud-connected loggers over precision accuracy, with FSSAI enforcement tightening in Indian urban distribution networks.
Manufacturing retains the largest installed base; healthcare delivers the steepest expansion trajectory through regulatory-driven replacement cycles.
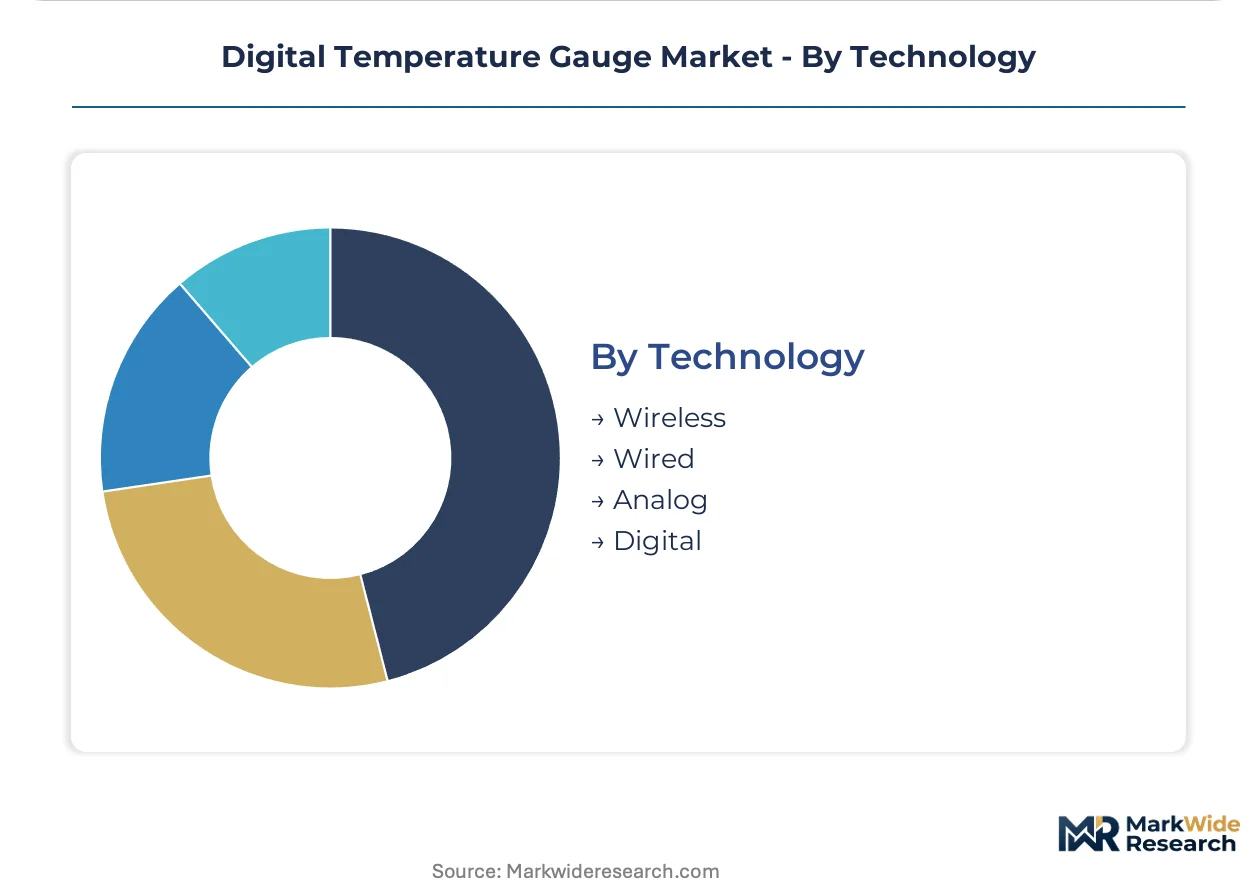
Technology:
Supply concentration in semiconductor fabrication for signal conditioning ASICs constrains architecture migration timelines, with wireless stack development competing for embedded firmware talent across industrial sectors.
- Wireless:Battery-powered LoRaWAN and Bluetooth Low Energy implementations enable retrofit deployment without conduit installation, though electromagnetic interference in steel and cement plants limits reliable adoption.
- Wired:4-20 mA current loop and fieldbus protocols retain dominance in safety-critical process control, with legacy DCS integration requirements extending replacement cycles.
- Analog:Direct millivolt or resistance output persists in simple indicator applications and cost-constrained commercial installations.
- Digital:Integrated microprocessor architectures with on-device linearization and diagnostic capabilities command premium positioning in calibration-critical applications.
Wired technology maintains volume leadership; wireless configurations are gaining share fastest through industrial IoT adoption in food and pharmaceutical sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of HACCP documentation requirements anchors United States demand, while Germany's industrial automation investments and India's FSSAI tightening create complementary growth poles across three continents.
United States
Food processing facilities drive gauge density through poultry and dairy line upgrades. FDA mandates continuous temperature logging across cold chain distribution nodes. Chicago and Minneapolis processing clusters deploy digital logging systems for compliance documentation.
Germany
Automotive foundries and chemical producers specify SIL-rated process control instrumentation. EU MDR elevates compliance costs for medical-grade temperature monitoring devices. Stuttgart and Ludwigshafen industrial corridors sustain elevated precision instrument procurement.
India
FSSAI enforcement tightens across dairy and seafood cold chain logistics. PLI scheme incentives support domestic manufacturing scale-up for food safety equipment. Maharashtra and Gujarat distribution networks generate first-time digital gauge demand.
China
EV battery cell formation protocols require multi-channel temperature acquisition systems. GB standards and dual carbon goals accelerate industrial sensor deployment. Yangtze River Delta manufacturing bases integrate precision measurement into battery thermal runaway testing.
Switzerland
Pharmaceutical packaging lines adopt MEMS-based sensors for sterilization validation. Swissmedic and EU GMP Annex 1 requirements prohibit probe intrusion in aseptic filling operations. Basel pharmaceutical cluster leads non-contact infrared gauge retrofit cycles.
Digital Temperature Gauge Market Competitive Environment
Capability concentration sits with precision instrument specialists; scale advantage sits with diversified industrial conglomerates. The vendor base stratifies across three tiers: laboratory-grade calibration houses, process control integrators, and volume commercial suppliers. Strategic archetypes include heritage calibration laboratories, industrial automation platforms, and food safety specialists. Competitive moves center on wireless stack acquisitions and service contracting model expansion.
Within the precision instrumentation tier, WIKA Alexander Wiegand SE & Co. KG and Fluke Corporation exemplify divergent positioning strategies. Testo SE & Co. KGaA occupies a specialist position in regulatory-compliant food safety applications. These three entities represent the spectrum from industrial process control to portable diagnostic and compliance-driven segments.
| Leading Market Players |
|---|
| Fluke Corporation |
| Testo SE & Co. KGaA |
| Omega Engineering |
| WIKA Alexander Wiegand SE & Co. KG |
| Endress+Hauser Group Services AG |
| Extech Instruments |
| Hart Scientific |
| Ashcroft (Nagano Keiki) |
| Kimo Instruments |
| Others |
Value Chain & Pricing Dynamics
Taiwan's semiconductor foundry cluster governs signal conditioning ASIC availability, translating wafer allocation tightness directly into tier-one gauge pricing power and extended lead times for precision instrumentation.
Pricing Analysis
German laboratory-grade gauges command 40-60% premiums over comparable Asian-manufactured units, with ISO 17025 calibration certificates and SIL safety ratings driving price stratification across premium, standard, and economy tiers. Pricing pressure stems from MEMS sensor commoditization in food safety applications, compressing margins for mid-tier suppliers without medical-grade certification. Retail cold chain buyers exhibit highest price sensitivity, while pharmaceutical aseptic filling operations prioritize measurement reliability over unit cost.
Supply Chain Analysis
Export controls on advanced node semiconductors constrain ASIC sourcing flexibility, forcing gauge manufacturers to navigate restricted-technology licensing for wireless stack components. Taiwan and South Korea anchor signal conditioning chip fabrication, with platinum RTD elements and thermocouple alloys drawing from South African and Russian raw material streams. Single-source vulnerability concentrates in 4-20 mA transmitter ASICs. Distribution runs through authorized industrial instrumentation distributors with calibration service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded firmware engineering talent for low-power wireless stacks sits in acute shortage, constraining product development velocity across the vendor base and amplifying acquisition premiums for capable development teams.
For Market Incumbents: Harden calibration infrastructure moats by securing ISO 17025 accreditation expansion into Indian and Southeast Asian markets before regional competitors consolidate. Acquire wireless stack specialists to offset firmware talent scarcity. Defend against MEMS-based sensor displacement by emphasizing traceability chains that disposable silicon cannot replicate.
For New Entrants and Emerging Players: Build out FSSAI-compliant food safety gauge offerings targeting Indian dairy and seafood cold chain networks where first-time digital instrumentation demand outpaces established service coverage. Penetrate through equipment-as-a-service contracting models that transfer obsolescence risk from capital-constrained processors.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because HACCP, EU MDR, and F-Gas enforcement trajectories favor incumbent-compliant suppliers over price competitors. Target acquisition profiles center on precision instrument specialists with existing notified body relationships and calibration laboratory networks. Watch FDA enforcement intensity around cold chain distribution documentation as the demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Stack Acquisition | Secures embedded firmware capability for LoRaWAN and Bluetooth Low Energy gauge architectures ahead of talent scarcity. |
| Calibration Laboratory Expansion | Establishes ISO 17025-accredited facilities in India to capture FSSAI-driven food safety gauge recertification demand. |
| Equipment-as-a-Service Contracting | Transfers capital expenditure burden from Nordic dairy cooperatives to instrumentation vendors with recurring revenue streams. |
| MEMS Sensor Integration | Eliminates discrete thermocouple assemblies for Swiss pharmaceutical sterilization validation applications. |
| EU MDR Certification Investment | Excludes uncertified competitors from patient-contact temperature monitoring through notified body approval pathways. |
Study Parameters
A standing panel of plant engineers, calibration laboratory managers, food safety compliance officers, and industrial instrumentation distributors provided ongoing calibration against secondary data streams including FDA warning letter databases, EU MDR notified body filings, and German mechanical engineering association order statistics. Primary fieldwork combined structured interviews with process control specification authorities and aftermarket service heads. Secondary validation drew from customs trade records, SEC filings of listed precision instrument manufacturers, and industry association shipment data. Bottom-up gauge deployment estimates triangulated against top-down process industry capital expenditure projections.
Scenario bracketing anchored volume and value outputs across conservative, baseline, and expansion cases throughout the forecast period. Segmentation modeling incorporated sensor architecture, connectivity protocol, end-use industry vertical, certification grade tier, and regional regulatory cluster dimensions. CAGRs derived from historical shipment trajectories adjusted for technology substitution elasticities and regulatory enforcement intensity curves. Forecast inputs included semiconductor foundry capacity utilization rates and food processing facility inspection citation trends.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified industrial conglomerates or sudden liberalization of ASIC export controls would shift outcomes. Material shifts in FDA HACCP enforcement scope, EU MDR implementation timelines, or Taiwan semiconductor supply continuity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Electric Vehicle (EV) Sensor Market
Sensors and Controls
Water and Wastewater Sensors Market
Sensors and Controls
Mass Flow Controller Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Quantum Dot Sensor Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
Non-Contact Sensor Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Specialty Control Plasma Market
Sensors and Controls
Doppler Lidar Market