
 Non-Contact Infrared Thermometer Market | 2026-2036
Non-Contact Infrared Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Contact Infrared Thermometer Market Intelligence
Capital-intensity divergence between players is rotating competitive advantage toward firms with captive sensor fabrication and calibration infrastructure. Fluke Corporation leverages its industrial instrumentation heritage to dominate process-control deployments in manufacturing units. Omron Healthcare sustains clinical credibility through hospital channel control and regulatory dossier depth. Testo SE & Co. KGaA anchors European industrial demand with precision thermal measurement protocols.
A non-contact infrared thermometer measures surface or body temperature by detecting infrared radiation emitted by an object, typically operating across spectral ranges of 8-14 micrometers with response times under 500 milliseconds. Its primary purpose spans fever screening in medical settings, preventive equipment monitoring in industrial plants, and HACCP compliance in food processing chains. Handheld units occupy the highest volume tier due to low procurement friction across hospitals and households, while fixed installations capture margin pools in automated manufacturing lines where continuous thermal monitoring replaces periodic manual checks. Medical application demand leads absolute value generation, though industrial deployment is expanding fastest as predictive maintenance programs adopt infrared diagnostics.
FDA 510(k) clearance requirements and IEC 60601-1-11 standards govern clinical device accuracy and electromagnetic compatibility, constraining market entry for uncertified manufacturers. EMA recognition of infrared thermometry for pharmaceutical cold-chain validation extends addressable demand into European distribution networks. Stakeholders must monitor evolving accuracy thresholds from ISO 80601-2-56 revisions and decide whether to absorb compliance costs or cede clinical segments to established regulatory dossier holders.
Market Dynamics
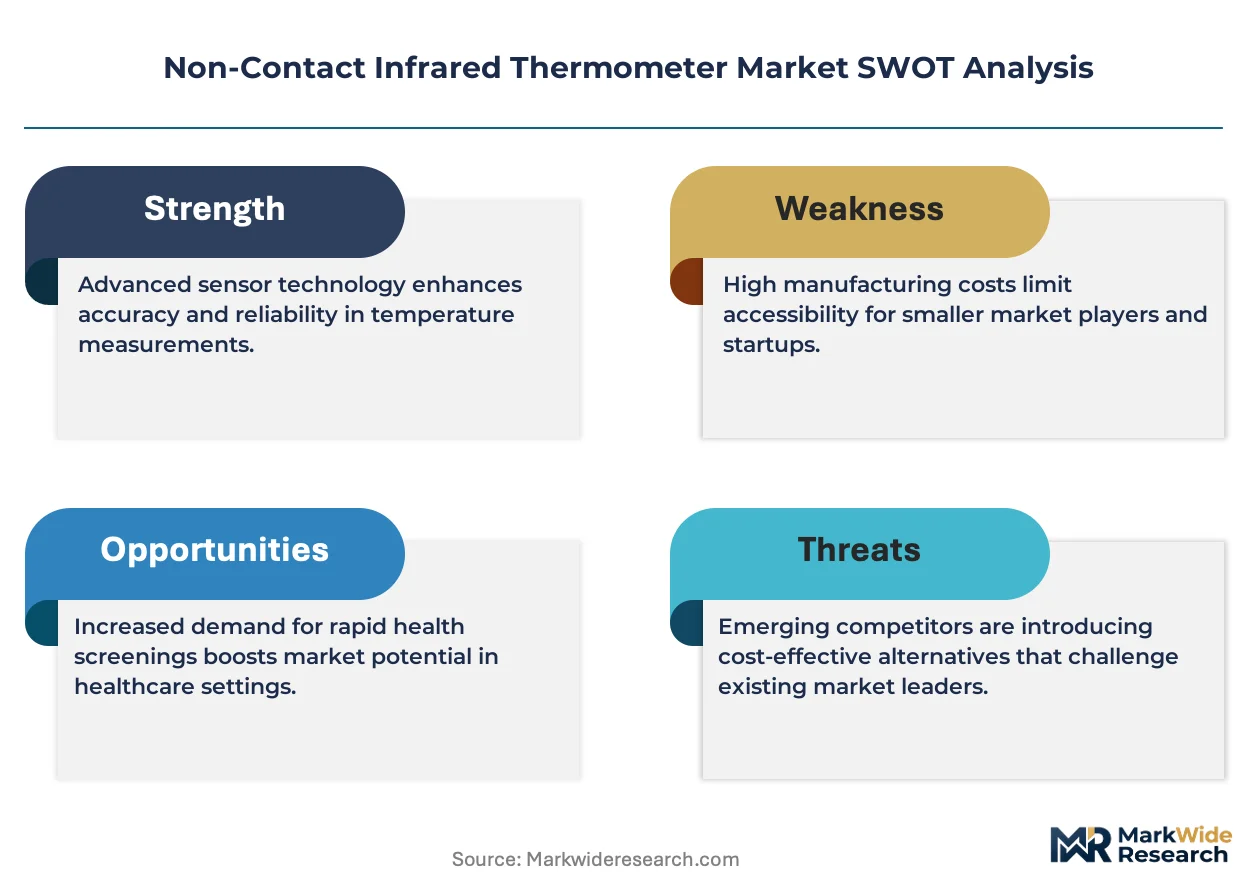
Calibration infrastructure ownership is becoming the decisive competitive moat as FDA tightens clinical-grade accuracy thresholds and industrial buyers demand traceable thermal measurement chains.
Growth Catalysts
- Hospital infection control protocols:Post-pandemic screening mandates in US acute-care facilities sustain bulk procurement of forehead thermometers for triage stations.
- GB 9706.1-2020 implementation:China's updated medical electrical equipment standard accelerates replacement cycles for non-compliant legacy devices in domestic hospitals.
- Predictive maintenance adoption:Manufacturing plants deploy fixed-mount infrared sensors to monitor motor bearing temperatures, reducing unplanned downtime in continuous-process industries.
Market Restraints
- MEMS sensor supply concentration:Thermal detector fabrication relies on a narrow base of Asian foundries, exposing procurement to geopolitical disruption.
- Ambient temperature interference:Clinical accuracy degrades in uncontrolled environments below 15°C, limiting outdoor deployment reliability.
- Contact thermometer substitution:Tympanic and oral probes retain preference in pediatric settings where infrared measurement uncertainty exceeds clinical tolerance.
Strategic Opportunities
- Indian pharmaceutical cold chain:CDSCO recognition of infrared validation for vaccine storage opens distribution network monitoring contracts.
- Edge AI convergence:On-device neural processing enables fever classification without cloud connectivity, appealing to data-sensitive European healthcare providers.
- Direct-to-facility ecommerce:Hospital procurement teams bypass distributor markups through manufacturer portals, compressing channel costs.
Industry Challenges
- Calibration technician scarcity:ISO 17025-accredited thermal metrology expertise concentrates in Germany and Japan, constraining service network expansion.
- 510(k) documentation burden:FDA clinical equivalence studies require 12-18 month timelines, delaying product launches for emerging sensor architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Contact Infrared Thermometer Market |
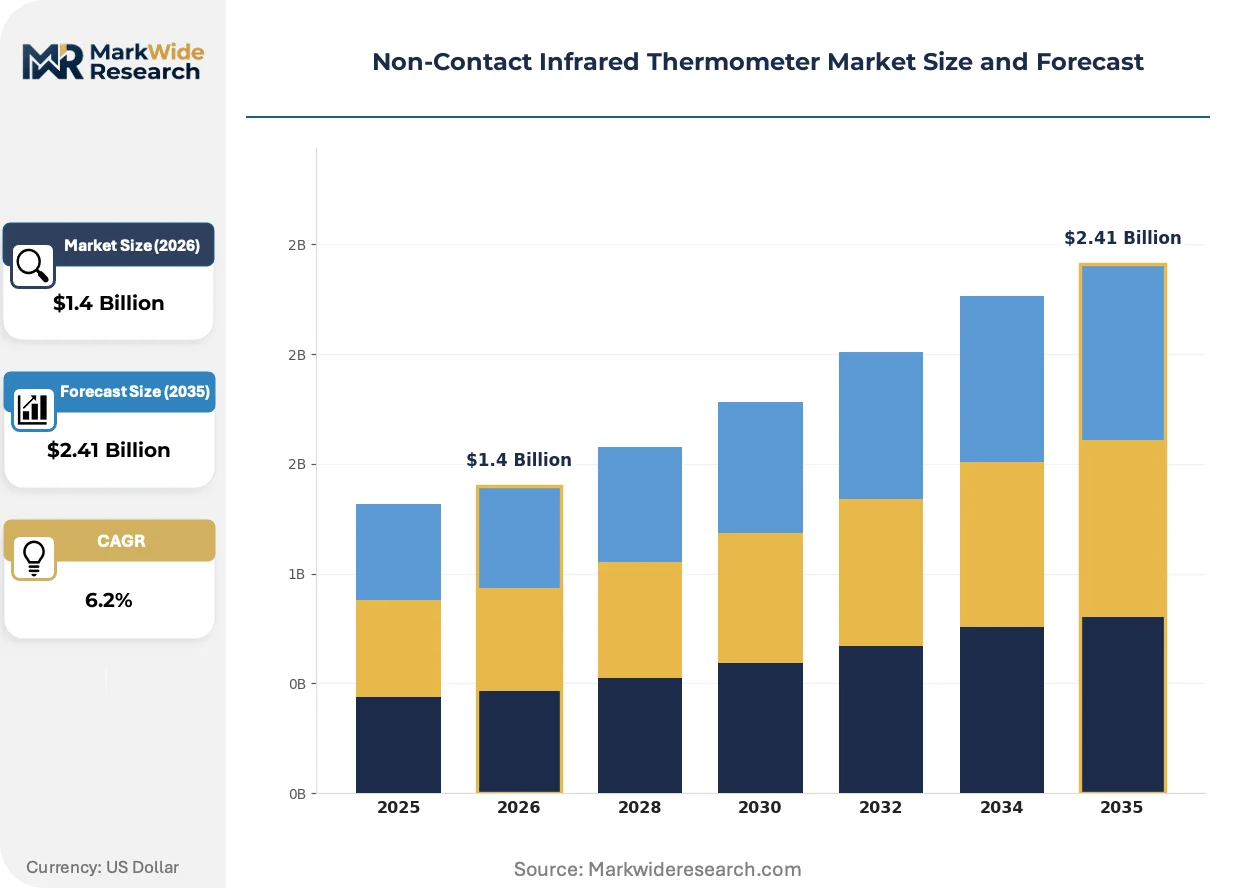
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fixed, Desktop, Portable Technology: Infrared Sensor, Laser, Digital, Thermal Application: Medical, Industrial, Food Safety, Personal Use End User: Hospitals, Manufacturing Units, Households, Laboratories |
| Companies Covered | Fluke Corporation, Omron Healthcare, Braun Healthcare, Exergen Corporation, Testo SE & Co. KGaA, Paul Hartmann, Contec Medical Systems, Microlife Corporation, Hanna Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Contact Infrared Thermometer Market Strategic Shifts & Innovations
Multi-spectral sensing architectures are compressing the gap between industrial process control and clinical diagnostic precision, forcing component suppliers to serve divergent accuracy requirements simultaneously.
Thermopile array sensors with integrated ASIC signal conditioning are fragmenting the historical divide between single-point spot measurements and thermal imaging systems. Food processing HACCP auditors now deploy handheld units with 32x24 pixel resolution, compressing the addressable market for entry-level thermal cameras. Component vendors face portfolio complexity as medical-grade and industrial-grade variants diverge in calibration protocols.
FDA updated guidance on clinical infrared thermometry in 2023 tightened equivalence study requirements for new 510(k) submissions. Manufacturers must now demonstrate correlation against pulmonary artery catheter reference methods rather than oral thermometry. This elevates clinical trial costs and extends time-to-market for sensor startups lacking regulatory dossier depth.
Hospital procurement departments are consolidating thermometer purchases through group purchasing organizations, compressing vendor margins and privileging suppliers with multi-year calibration service contracts. This behavior shift concentrates volume with firms offering integrated hardware-software-service bundles. The pattern is most pronounced in US integrated delivery networks managing 50+ facility footprints.
Non-Contact Infrared Thermometer Market Segmentation
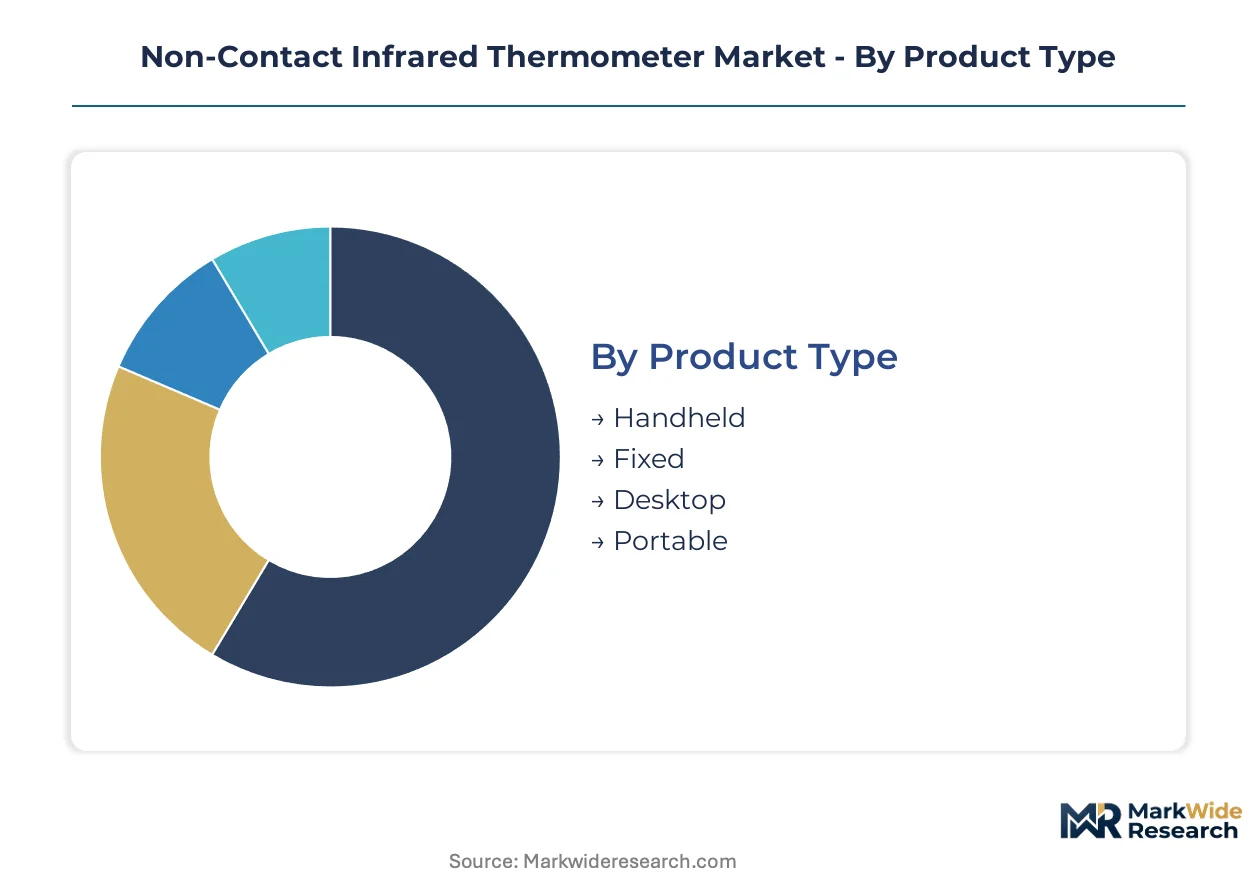
Segmentation in the non-contact infrared thermometer market determines channel strategy, margin structure, and regulatory compliance burden. Product form factor dictates whether procurement flows through medical distributors, industrial supply houses, or consumer retail channels.
Product Type:
Channel economics vary sharply by product type, with handheld units moving through high-velocity retail and medical supply networks while fixed installations require direct manufacturer sales engineering.
- Handheld:Battery-powered pistol-grip units with single-point laser targeting dominate hospital triage stations and food processing audit workflows. US acute-care facilities sustain bulk replenishment cycles through group purchasing organizations, while household demand concentrates through pharmacy retail chains.
- Fixed:Permanently mounted sensors with continuous data logging integrate into manufacturing line control systems. Predictive maintenance programs in continuous-process industries drive replacement of periodic manual spot-checking with automated thermal monitoring.
- Desktop:Stationary units with integrated display screens serve laboratory calibration stations and reception-area screening checkpoints.
- Portable:Compact wand-style devices with foldable probes target field service technicians and mobile health screening units.
Handheld dominates installed base. Fixed is where expansion concentrates.
Technology:
Technology selection determines accuracy tier, calibration protocol, and end-market addressability.
- Infrared Sensor:Thermopile detectors operating across 8-14 micrometer spectral range constitute the core sensing architecture. Medical-grade variants require FDA 510(k) clearance with demonstrated correlation to pulmonary artery catheter reference methods.
- Laser:Visible targeting beams improve measurement repeatability in industrial environments with complex surface geometries. Manufacturing maintenance teams prioritize laser-equipped units for motor bearing and electrical connection inspection.
- Digital:ASIC-integrated signal processing enables faster response times under 500 milliseconds and on-device temperature compensation.
- Thermal:Multi-pixel array sensors deliver 32x24 resolution for area temperature mapping, compressing the functional gap with entry-level thermal imaging systems.
Infrared Sensor anchors clinical revenue. Thermal is gaining share fastest in food safety and industrial crossover applications.
Application:
Application focus determines regulatory jurisdiction, accuracy specification, and service contract structure.
- Medical:Fever screening in hospitals, clinics, and public health checkpoints requires IEC 60601-1-11 electromagnetic compatibility and clinical-grade calibration traceability. China's GB 9706.1-2020 implementation accelerates domestic hospital replacement cycles.
- Industrial:Equipment condition monitoring and electrical inspection drive demand for ruggedized units with wide temperature ranges and intrinsically safe certifications.
- Food Safety:HACCP compliance mandates surface temperature verification in processing, storage, and distribution. EMA recognition of infrared validation for pharmaceutical cold chains extends addressable demand into European distribution networks.
- Personal Use:Consumer-grade forehead thermometers for household fever monitoring compete on price and ease of use rather than clinical accuracy certification.
Medical commands premium pricing. Industrial shows steepest expansion trajectory as predictive maintenance programs scale.
End User:
End user category shapes procurement authority, volume concentration, and aftermarket service requirements.
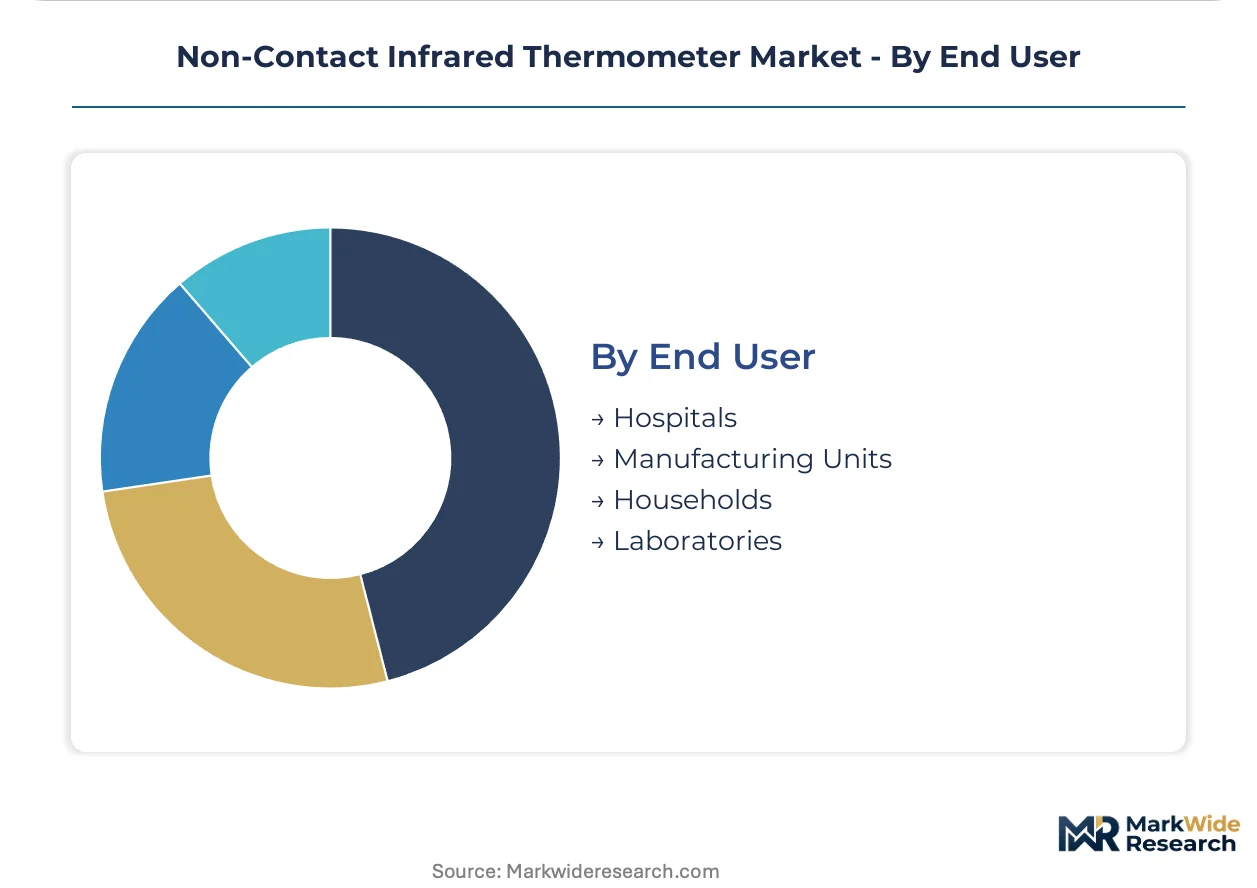
- Hospitals:Integrated delivery networks managing multi-facility footprints consolidate thermometer purchases through group purchasing organizations, privileging vendors with multi-year calibration service contracts.
- Manufacturing Units:Process industries deploy fixed-mount sensors for continuous motor and bearing temperature monitoring, reducing unplanned downtime in petrochemical and paper production lines.
- Households:Post-pandemic residual demand sustains pharmacy and e-commerce channel volume for consumer-grade forehead thermometers.
- Laboratories:Metrology and research facilities require ISO 17025-traceable calibration chains and expanded uncertainty documentation for thermal measurement validation.
Hospitals concentrate contract value. Manufacturing Units drive volume growth in fixed-installation segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with US hospital procurement teams absorbing premium pricing for calibration-certain units while Indian pharmaceutical distributors prioritize cost efficiency in cold-chain validation deployments.
United States
Acute-care facilities sustain bulk replenishment cycles through group purchasing organizations, privileging vendors with multi-year service contracts. FDA 510(k) clearance requirements govern clinical-grade accuracy thresholds, constraining uncertified manufacturer entry. Texas Medical Center in Houston anchors hospital procurement concentration, with integrated delivery networks managing 50-plus facility footprints consolidating thermometer purchases.
Germany
Industrial process-control deployments drive fixed-mount sensor demand across petrochemical and automotive manufacturing lines. EMA recognition of infrared validation for pharmaceutical cold chains extends addressable demand into European distribution networks. Munich and Stuttgart industrial clusters concentrate precision thermal measurement protocol adoption, with calibration infrastructure ownership becoming decisive competitive moat.
China
Hospital procurement networks and industrial safety mandates scale infrared thermometer deployment across medical and manufacturing settings simultaneously. GB 9706.1-2020 implementation accelerates domestic hospital replacement cycles for non-compliant legacy devices. Yangtze River Delta manufacturing hubs anchor industrial sensor demand, while Beijing-Tianjin-Hebei hospital networks drive clinical-grade volume.
India
Pharmaceutical cold-chain expansion creates distribution network monitoring contract opportunities as vaccine storage validation requirements tighten. CDSCO recognition of infrared thermometry for temperature-sensitive biologics opens regulatory pathway for clinical adoption. Maharashtra and Gujarat pharmaceutical manufacturing clusters concentrate deployment, with Mumbai-based logistics providers piloting automated thermal screening protocols.
Japan
Precision manufacturing quality control sustains demand for thermopile array sensors with integrated ASIC signal conditioning. METI industrial standards govern measurement traceability requirements in automotive and electronics production environments. Nagoya industrial corridor and Osaka manufacturing belt concentrate fixed-installation sensor deployment, with predictive maintenance programs reducing unplanned downtime.
Non-Contact Infrared Thermometer Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive structure. The market fragments across three strategic clusters: industrial instrumentation heritage firms with captive calibration infrastructure, clinical device specialists with regulatory dossier depth, and component suppliers serving divergent accuracy requirements. Dominant competitive moves center on M&A for sensor fabrication capacity and strategic partnerships for distribution network access.
Within the industrial instrumentation tier, Fluke Corporation and Testo SE & Co. KGaA exemplify players leveraging metrology heritage for process-control dominance. Omron Healthcare occupies a position representing clinical credibility through hospital channel control. These three anchors demonstrate how calibration infrastructure ownership and regulatory dossier depth concentrate competitive advantage as accuracy thresholds tighten across both medical and industrial segments.
| Leading Market Players |
|---|
| Fluke Corporation |
| Omron Healthcare |
| Braun Healthcare |
| Exergen Corporation |
| Testo SE & Co. KGaA |
| Paul Hartmann |
| Contec Medical Systems |
| Microlife Corporation |
| Hanna Instruments |
| Others |
Cost & Logistics Intelligence
Multi-year calibration service contracts lock in both supply access and price visibility for hospital procurement teams navigating FDA 510(k) clearance requirements and tightening IEC 60601-1-11 accuracy thresholds. These arrangements concentrate purchasing power with vendors offering bundled hardware-software-service packages across integrated delivery networks.
Pricing Analysis
After-sales revenue from ISO 17025-accredited calibration services drives lifetime value, with three-tier pricing structure across premium, standard, and economy levels separating clinical-grade units with FDA clearance from industrial variants and consumer forehead thermometers. Price differentiation hinges on certification tier and volume scale, with hospital group purchasing organizations extracting steepest discounts through consolidated procurement. Cost compression in the consumer segment intensifies as pharmacy retail chains prioritize low unit costs over accuracy traceability, while medical-grade pricing holds firm due to regulatory compliance burdens.
Supply Chain Analysis
China and Taiwan anchor thermopile detector fabrication, with Japan and Germany concentrating precision ASIC signal conditioning and calibration infrastructure. The supply chain draws from germanium lens substrates, MEMS thermal detectors, and medical-grade plastic housings. Single-source vulnerability in Asian foundry capacity exposes procurement to geopolitical disruption. Distribution runs through medical supply distributors for handheld clinical units, direct manufacturer sales engineering for fixed industrial installations, and pharmacy retail chains for consumer-grade devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025-accredited thermal metrology expertise concentrates in Germany and Japan, leaving hospital service network expansion constrained and creating acquisition premiums for calibration-capable firms.
For Market Incumbents: Secure captive sensor fabrication capacity through backward integration into thermopile detector production or binding offtake agreements with Taiwanese foundries. Deepen hospital channel control by embedding multi-year calibration contracts within group purchasing organization frameworks, defending against emerging sensor startups lacking regulatory dossier depth. For New Entrants and Emerging Players: Anchor in Indian pharmaceutical cold-chain validation contracts where CDSCO recognition creates first-mover positioning before clinical-grade competition intensifies. Target field service technician segments with portable wand-style devices, leveraging direct-to-facility ecommerce channels to bypass established distributor markups and compress customer acquisition costs. For Investors and Strategic Acquirers: Component suppliers with dual medical-industrial calibration protocols represent the most defensible acquisition archetype as multi-spectral sensing architectures fragment accuracy requirements. Watch FDA 510(k) submission backlogs as an inflection indicator; extended review timelines signal regulatory moat widening that favors incumbent regulatory dossier holders over capital-constrained entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Acquisition | Captures ISO 17025-accredited thermal metrology capacity concentrated in Germany and Japan. |
| Hospital GPO Partnership Expansion | Locks in multi-year service contracts with integrated delivery networks managing 50-plus facilities. |
| Edge AI Firmware Development | Enables on-device fever classification appealing to data-sensitive European healthcare providers. |
| Indian CDSCO Regulatory Pathway | Opens pharmaceutical cold-chain monitoring contracts as vaccine storage validation tightens. |
| Direct-to-Facility Ecommerce Platform | Compresses channel costs by bypassing distributor markups for hospital procurement teams. |
Research Approach
A standing panel of hospital procurement managers, biomedical engineers, GPO contracts specialists, and industrial maintenance directors provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with FDA regulatory consultants and thermopile sensor manufacturing executives. Secondary sources encompassed FDA 510(k) clearance databases, IEC 60601 standard revision records, hospital procurement contract filings, and trade data from customs authorities. Bottom-up unit economics triangulated against top-down market sizing across product type, application, and end-user dimensions.
Consistency checks validated volume and value outputs against external benchmarks including regulatory filing trajectories and foundry capacity disclosures. The analytical framework modeled handheld, fixed, desktop, and portable form factors; medical, industrial, food safety, and personal use applications; and hospitals, manufacturing units, households, and laboratories as end-user categories across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro healthcare expenditure and industrial automation investment patterns, incorporating predictive maintenance adoption curves and hospital infection control protocol evolution as industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of stable FDA review timelines and continued MEMS foundry capacity availability; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in regulatory accuracy thresholds and geopolitical disruption to Asian semiconductor supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Europe Temperature Sensors Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Electric Pipette Controllers Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Latin America Proximity Sensors Market
Sensors and Controls
Phototransistor Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
PM2.5 Sensors Market