
 Cryogenic Temperature Controller Market | 2026-2036
Cryogenic Temperature Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Temperature Controller Market Outlook
Sub-10-milliKelvin precision tier is rotating toward dominance as quantum computing and topological qubit research displace legacy 4-Kelvin standards. Lake Shore Cryotronics leverages its sensor-calibration infrastructure to anchor North American laboratory supply chains. Oxford Instruments plc sustains European market presence through deep cryostat integration. Janis Research Company LLC competes on custom probe-station configurations for materials characterization.
Cryogenic temperature controllers are precision instruments that regulate thermal environments below 123 Kelvin through closed-loop feedback between resistance temperature detectors, superconducting sensors, and cryogenic refrigeration stages, enabling stable operation of superconducting circuits and quantum devices. The cryostat segment leads installed base value due to capital-intensive vacuum-jacketed dewar assemblies, while closed-loop technology captures the fastest expansion as autonomous PID tuning replaces manual operator intervention in unattended quantum computing facilities. Semiconductor manufacturing end-users concentrate procurement around high-throughput wafer-probe systems, whereas particle physics applications sustain long-cycle demand through CERN, DESY, and Fermilab upgrade timelines.
FDA 21 CFR Part 820 quality system requirements govern medical cryopreservation controller validation, while ISO 17025 calibration standards dictate metrological traceability for research laboratory procurement. The EU AI Act and GDPR indirectly shape controller architecture by mandating audit trails and data sovereignty in automated quantum computing testbeds. Stakeholders must monitor helium supply chain constraints and alternative cryogen roadmap decisions by national research funding agencies.
Market Dynamics
Helium-3 supply constraints and the EU F-Gas Regulation phase-down are forcing manufacturers to abandon hydrofluorocarbon-dependent architectures and reengineer cooling systems around dilution refrigerator and adiabatic demagnetization technologies.
Growth Catalysts
- Quantum computing infrastructure buildout:National laboratories in Germany, the United States, and Japan are commissioning milli-Kelvin precision systems for topological qubit research. Procurement specifications now mandate sub-10-milliKelvin stability thresholds.
- EU F-Gas Regulation compliance deadlines:The phasedown of hydrofluorocarbon refrigerants creates mandatory replacement cycles for legacy cryogenic systems across European research facilities. Manufacturers redesigning around helium-3 and dry dilution technologies capture upgrade demand.
- Superconducting circuit commercialization:Foundries in South Korea and Taiwan are integrating cryogenic probe stations into high-throughput wafer testing workflows. This extends precision temperature control from laboratory environments into semiconductor manufacturing.
Market Restraints
- Helium supply chain concentration:The United States, Qatar, and Algeria control over 80% of global helium extraction. Geopolitical disruptions or export restrictions immediately constrain dilution refrigerator production and maintenance operations.
- Capital intensity of cryostat assemblies:Vacuum-jacketed dewar systems require specialized stainless steel fabrication and superinsulation materials. Input cost volatility for niobium-titanium superconducting wire compresses margins on custom configurations.
- Technical limitation in unattended operation:Current PID autotuning algorithms struggle with thermal load transients in pulse-tube cryocoolers. Manual operator intervention remains necessary for stable base temperature maintenance in many installations.
Strategic Opportunities
- India's National Quantum Mission procurement:The country's dedicated quantum technology funding creates demand for imported cryogenic infrastructure. Local assembly partnerships with IISc Bangalore and TIFR Mumbai offer market entry pathways.
- Medical cryopreservation regulatory tailwind:FDA 21 CFR Part 820 quality system requirements and evolving tissue banking standards in the European Union mandate validated temperature logging. This extends controller applications beyond research into clinical biobanking.
- Integration of machine learning with cryogenic control:Predictive thermal modeling algorithms converging with hardware-in-the-loop systems enable autonomous fault detection. Quantum computing testbeds in the Netherlands and Canada are piloting these architectures.
Industry Challenges
- Specialized cryogenic engineering talent scarcity:The intersection of low-temperature physics, control systems, and vacuum technology requires rare expertise. Universities in Germany and Switzerland produce limited graduates relative to industry demand.
- ISO 17025 calibration timeline compression:Metrological traceability requirements for research laboratory procurement extend validation cycles. Accreditation bottlenecks at national measurement institutes delay controller deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Temperature Controller Market |
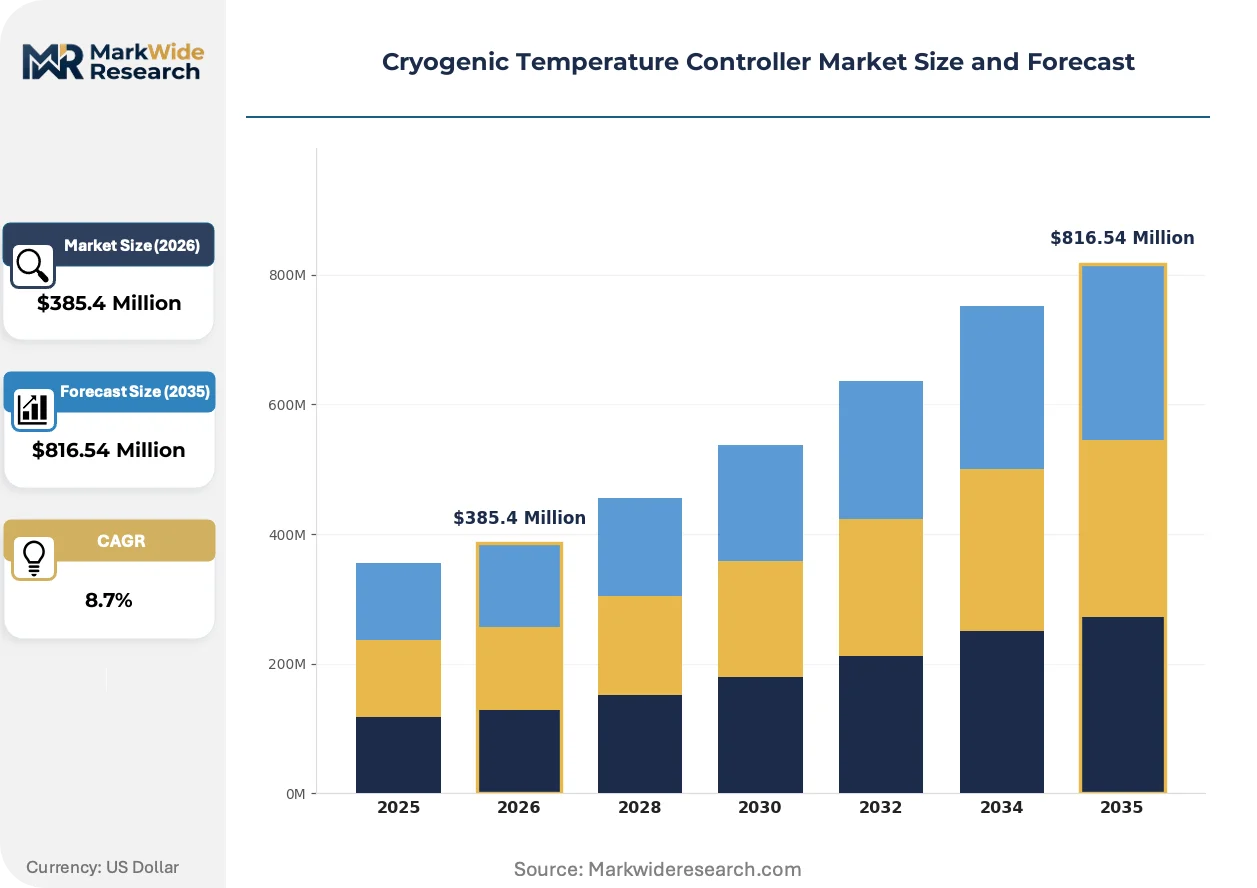
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Nitrogen, Cryostat, Refrigeration System, Temperature Sensors End User: Aerospace, Semiconductor Manufacturing, Research Laboratories, Medical Applications Technology: Closed Loop, Open Loop, Resistive Heating, Stirling Cycle Application: Superconductivity, Material Testing, Vacuum Systems, Particle Physics |
| Companies Covered | Lake Shore Cryotronics, Inc, Oxford Instruments plc, Janis Research Company LLC, Cryomech, Inc, Cryogenic Control Systems, Inc, LOT-QuantumDesign GmbH, American Magnetics Inc, Advanced Research Systems, Inc, Montana Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Temperature Controller Market Strategic Shifts
Closed-loop autonomous control architectures are supplanting manual operator intervention, while regulatory pressure on fluorinated gases and shifting procurement models in quantum computing facilities are restructuring competitive requirements.
Adiabatic demagnetization refrigeration is supplanting helium-3 based dilution systems in sub-100-milliKelvin applications. Quantum computing laboratories at Max Planck institutes and Canadian national facilities are adopting these solid-state alternatives to reduce cryogen dependency. This technology is supplanting wet cryostat architectures and enabling longer unattended operation cycles in remote computing facilities.
The EU F-Gas Regulation mandates an 80% phase-down of hydrofluorocarbon refrigerants by 2030. Cryogenic equipment manufacturers must redesign cooling circuits around natural refrigerants or closed-cycle helium systems. European quantum technology clusters in Munich and Stuttgart are accelerating procurement of compliant architectures ahead of enforcement deadlines.
Facility managers at quantum computing testbeds are unbundling after-sales service contracts from hardware procurement. Independent calibration and maintenance providers are capturing recurring revenue streams previously retained by original equipment manufacturers. This behavioral shift is most visible in United States national laboratory procurement, where multi-vendor service agreements now dominate large installations.
Cryogenic Temperature Controller Market Segmentation
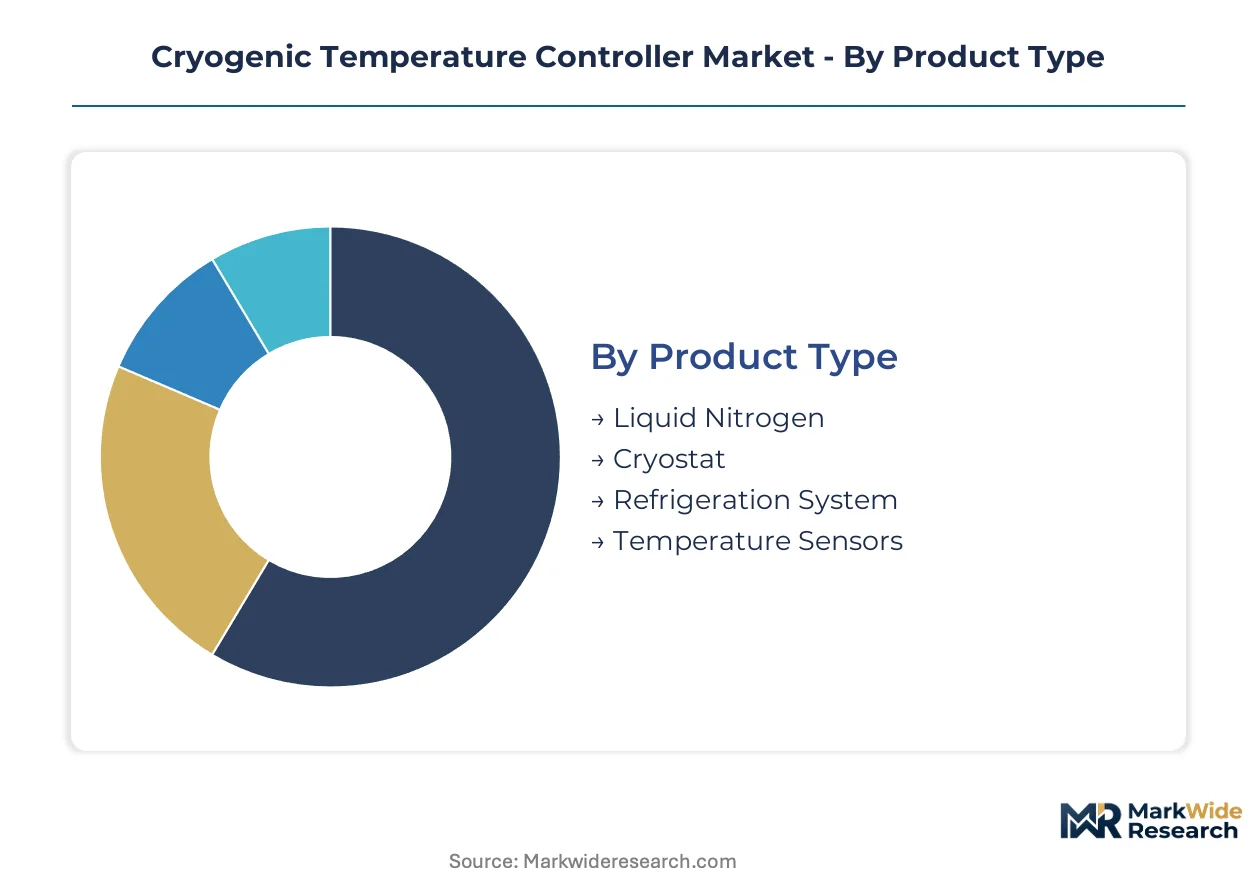
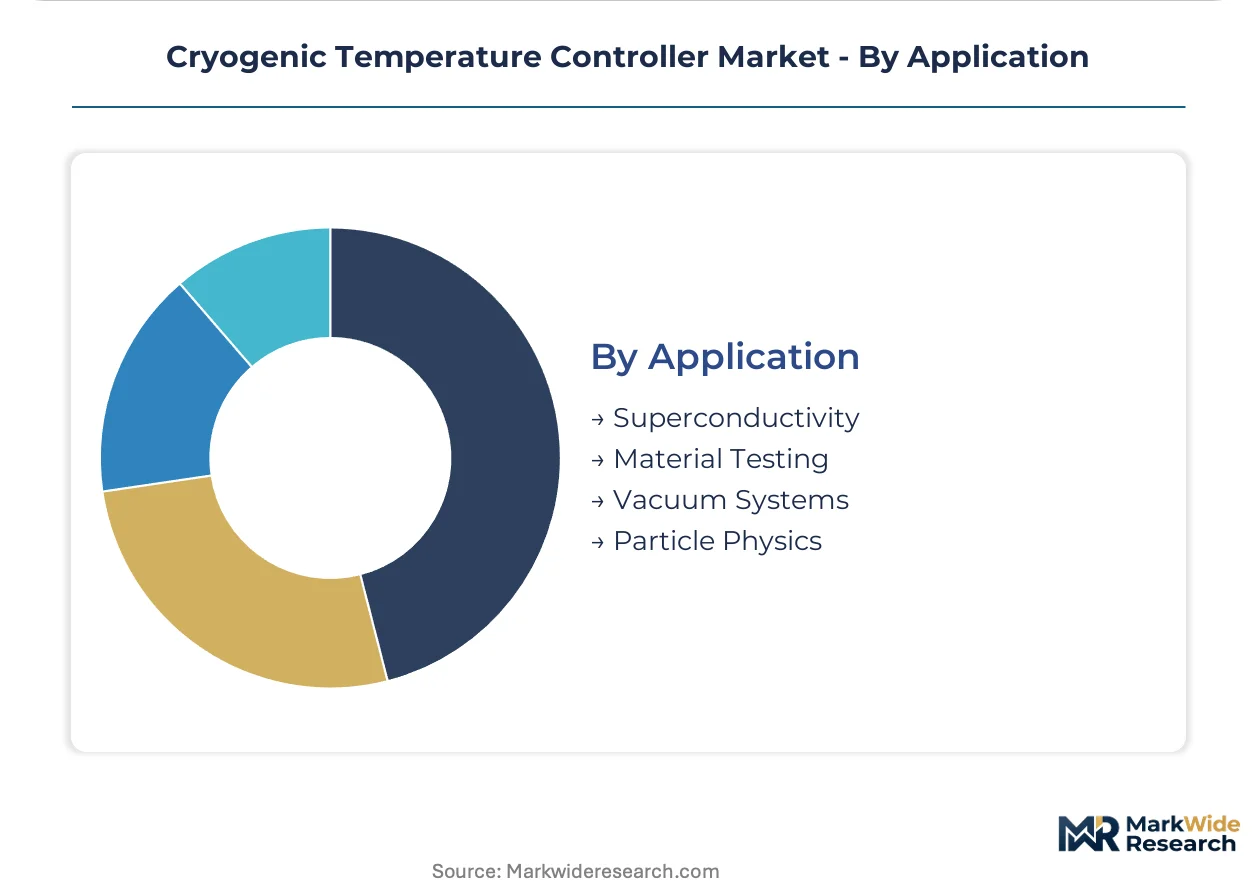
Cryogenic temperature controller procurement splits across four dimensions that determine specification requirements and vendor selection criteria. Product type governs capital intensity and maintenance protocols. End-user verticals impose distinct regulatory and operational constraints. Technology choice balances precision against unattended operation capability. Application context dictates temperature range and stability thresholds.
Product Type:
FDA 21 CFR Part 820 quality system requirements and ISO 17025 calibration standards create divergent compliance burdens across hardware categories, with medical and research procurement following separate validation protocols.
- Cryostat:Vacuum-jacketed dewar assemblies integrate superinsulation materials and niobium-titanium superconducting wire to maintain milli-Kelvin environments. Demand concentrates at CERN, DESY, and Fermilab where upgrade timelines sustain long-cycle procurement. Capital intensity compresses margins on custom configurations.
- Temperature Sensors:Resistance temperature detectors and superconducting sensors provide closed-loop feedback for PID control architectures. Quantum computing laboratories in Germany and the United States drive specifications for sub-10-milliKelvin precision tiers. Sensor-calibration infrastructure anchors laboratory supply chain decisions.
- Liquid Nitrogen:Open-cycle cooling systems serve materials characterization workflows requiring 77-Kelvin baselines without dilution refrigerator complexity.
- Refrigeration System:Pulse-tube and Gifford-McMahon cryocoolers enable closed-cycle operation for unattended quantum computing facilities.
Established volume favors cryostat assemblies; emerging adoption favors temperature sensors.
End User:
Customer procurement authority varies from centralized national laboratory budgets to distributed semiconductor foundry capital expenditure committees.
- Research Laboratories:Max Planck institutes, Fraunhofer facilities, and national quantum testbeds specify sub-10-milliKelvin stability thresholds for topological qubit research. EU F-Gas Regulation compliance deadlines accelerate replacement cycles for legacy hydrofluorocarbon-dependent systems. Metrological traceability requirements extend validation timelines.
- Semiconductor Manufacturing:Foundries in South Korea and Taiwan integrate cryogenic probe stations into high-throughput wafer testing workflows. Procurement concentrates around automated probe-station configurations with closed-loop thermal control. Superconducting circuit commercialization extends precision requirements from laboratory into production environments.
- Aerospace:Satellite payload testing and space qualification protocols demand compact, vibration-isolated cooling architectures.
- Medical Applications:Tissue banking and cryopreservation services mandate validated temperature logging under FDA 21 CFR Part 820 and evolving European Union biobanking standards.
Procurement scale favors semiconductor manufacturing; specification complexity favors research laboratories.
Technology:
Control architecture maturity determines operator intervention requirements and facility staffing models.
- Closed Loop:Autonomous PID tuning architectures replace manual operator intervention through hardware-in-the-loop feedback between sensors and cryogenic refrigeration stages. Quantum computing testbeds in the Netherlands and Canada pilot machine learning integration for predictive thermal modeling. This segment is climbing the fastest as unattended operation becomes mandatory for remote computing facilities.
- Resistive Heating:Precision heater elements enable fine temperature control above base cryogenic temperatures for materials characterization workflows. Demand concentrates in custom probe-station configurations where thermal cycling protocols require rapid setpoint changes.
- Open Loop:Manual setpoint adjustment persists in legacy installations and teaching laboratory environments with continuous operator presence.
- Stirling Cycle:Compact mechanical refrigeration suits portable and field-deployable cooling requirements without liquid cryogen logistics.
Operational automation favors closed loop; cost sensitivity favors open loop.
Application:
Physics domain determines temperature floor, stability tolerance, and electromagnetic interference shielding requirements.
- Superconductivity:Quantum device operation and superconducting circuit testing demand sub-100-milliKelvin environments with micro-Kelvin stability over hour-scale measurements. Adiabatic demagnetization refrigeration is displacing helium-3 dilution systems at Canadian national facilities and German Max Planck institutes to reduce cryogen dependency.
- Particle Physics:Detector cooling for CERN, DESY, and Fermilab experiments sustains demand for large-capacity cryostat systems with radiation-hard sensor configurations. Long-cycle upgrade timelines buffer procurement against short-term funding fluctuations.
- Material Testing:Low-temperature mechanical and electrical property characterization spans 4-Kelvin to 300-Kelvin ranges with moderate stability requirements.
- Vacuum Systems:Cryopumping and ultra-high vacuum maintenance leverage cryogenic surfaces for gas capture without mechanical pumps.
Technical complexity favors superconductivity; procurement predictability favors particle physics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium extraction concentrates in the United States, Qatar, and Algeria, creating supply chain dependencies that shape regional procurement strategies for dilution refrigerator systems and milli-Kelvin precision infrastructure.
United States
National quantum testbeds at Fermilab and Argonne National Laboratory drive specifications for sub-10-milliKelvin stability systems. FDA 21 CFR Part 820 governs medical cryopreservation controller validation for tissue banking applications. Greater Boston and the Midwest corridor host dense clusters of superconducting circuit research facilities expanding procurement.
Germany
Fraunhofer institutes and Max Planck facilities around Munich and Stuttgart anchor European demand for next-generation controller specifications. The EU F-Gas Regulation mandates 80% hydrofluorocarbon phase-down by 2030, forcing cooling architecture redesigns. The Bavarian quantum technology cluster accelerates procurement of helium-3 and dilution refrigerator systems ahead of compliance deadlines.
Japan
METI-funded quantum computing initiatives at RIKEN and national university laboratories sustain demand for precision cryogenic infrastructure. National research funding agency roadmaps prioritize alternative cryogen development to reduce helium import dependency. The Tsukuba science city concentration drives specifications for unattended autonomous control systems.
China
Domestic superconducting circuit foundries and national laboratory networks expand procurement of closed-loop cryogenic control systems. MIIT standards and national dual carbon goals shape refrigeration technology selection toward lower-emission architectures. The Yangtze River Delta concentration of semiconductor research facilities drives high-throughput wafer-probe system demand.
Canada
National quantum computing testbeds pilot machine learning integration with cryogenic control architectures for predictive thermal modeling. Health Canada regulations govern medical cryopreservation applications alongside research laboratory procurement. The Waterloo-Toronto corridor anchors quantum device commercialization efforts requiring stable milli-Kelvin environments.
Cryogenic Temperature Controller Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the cryogenic temperature controller market. The vendor base clusters around three strategic positions: precision sensor-calibration specialists, integrated cryostat manufacturers, and custom probe-station configurators. Consolidation pressure concentrates among cryostat assemblies where vacuum-jacketed dewar fabrication requires specialized superinsulation expertise. Dominant competitive moves include strategic partnerships with national laboratory procurement programs and technology licensing for autonomous PID control algorithms.
Within the precision instrumentation tier, Lake Shore Cryotronics, Inc. and Oxford Instruments plc represent established anchors for laboratory supply chain decisions. Janis Research Company LLC exemplifies the custom configuration specialist archetype. These three entities occupy positions that span North American and European procurement channels, with corporate structures reflecting long-cycle research equipment manufacturing traditions. Their geographic distribution across the United States and United Kingdom mirrors the regional concentration of quantum computing and superconducting circuit research funding.
| Leading Market Players |
|---|
| Lake Shore Cryotronics, Inc |
| Oxford Instruments plc |
| Janis Research Company LLC |
| Cryomech, Inc |
| Cryogenic Control Systems, Inc |
| LOT-QuantumDesign GmbH |
| American Magnetics Inc |
| Advanced Research Systems, Inc |
| Montana Instruments |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between national laboratories and helium extraction facilities lock in cryogen supply access while anchoring price visibility for dilution refrigerator manufacturers facing volatile feedstock costs.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European procurement channels. Three-tier pricing separates ISO 17025-certified precision systems from standard laboratory configurations and economy-grade teaching equipment. Price differentiation rests on metrological traceability grade and after-sales service bundling. Cost compression in mid-tier configurations is intensifying because niobium-titanium superconducting wire input volatility compresses margins on custom cryostat assemblies. Semiconductor foundries exhibit lowest price sensitivity due to throughput-critical requirements; academic laboratories face highest budget constraint pressure.
Supply Chain Analysis
Helium-3 isotope separation capacity chokepoints in the United States and Russia tether production schedules for sub-100-milliKelvin systems to geopolitically exposed feedstock channels. Geographic supply concentrates in the United States, Qatar, and Algeria for raw helium extraction, with niobium-titanium superconducting wire drawing primarily from Japanese and German metallurgical facilities. Supply chain risk centers on single-source vulnerability for helium-3 enrichment infrastructure. Distribution runs through direct national laboratory procurement channels and specialized scientific equipment distributors serving semiconductor foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around FDA 21 CFR Part 820 and ISO 17025 certification timelines creates structural barriers against rapid competitive displacement.
For Market Incumbents: Fortify sensor-calibration infrastructure through captive supply of resistance temperature detector reference standards to lock in laboratory procurement decisions. Deepen backward integration into niobium-titanium superconducting wire fabrication to defend margin position against raw material volatility. The emerging threat of adiabatic demagnetization refrigeration substitution demands accelerated R&D in solid-state cooling integration.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for medical cryopreservation controllers offer regulatory entry velocity into clinical biobanking applications. Target India's National Quantum Mission procurement as the most penetrable geography, where local assembly partnerships with IISc Bangalore circumvent established vendor relationships. Lead with autonomous PID tuning software as a service-layer wedge to bypass capital-intensive cryostat manufacturing.
For Investors and Strategic Acquirers: Precision sensor-calibration specialists with embedded national laboratory relationships represent the priority acquisition archetype for platform consolidation. Long-term viability over the coming decade hinges on helium supply chain decoupling capabilities. The signal to monitor is alternative cryogen roadmap commitments by METI and the EU Quantum Flagship program.
| Strategic Initiative | Industry Significance |
|---|---|
| Helium-3 Supply Diversification Partnership | Qatari and Algerian extraction expansion reduces concentration risk for dilution refrigerator manufacturers. |
| Adiabatic Demagnetization Refrigeration Licensing | Max Planck institute technology transfer enables cryogen-independent sub-100-milliKelvin product lines. |
| Autonomous PID Control Algorithm Acquisition | Machine learning integration from Netherlands quantum testbeds accelerates unattended operation capabilities. |
| ISO 17025 Accreditation Expansion | Calibration infrastructure in India and Japan captures procurement from national quantum missions. |
| Medical Cryopreservation Regulatory Submission | FDA 21 CFR Part 820 validation opens clinical biobanking revenue streams beyond research laboratories. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary research phases. Cryogenic engineering directors at national laboratories, semiconductor foundry procurement leads, and medical device regulatory affairs specialists provided operational validation. Secondary sources included FDA 510(k) filings, EU F-Gas Regulation implementation reports, helium trade data from customs authorities, and ISO 17025 accreditation databases. Bottom-up unit economics for cryostat assemblies were triangulated against top-down national research funding allocations.
Across the analysis window, forecasts were constructed through segmented modeling of product type, end-user vertical, control technology architecture, and application physics domain. CAGRs were derived from installed base replacement cycles, quantum computing infrastructure buildout timelines, and regulatory compliance deadline clustering. Industry-specific inputs incorporated helium supply constraint scenarios and adiabatic demagnetization refrigeration adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained national quantum funding commitments or helium supply disruption scenarios would require recalibration. Forecasts reflect documented assumptions around technology substitution rates and regulatory enforcement timing. Practitioners should keep alternative scenarios live as EU F-Gas Regulation phase-down milestones and alternative cryogen development roadmaps evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Safety Laser Scanner Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
NB-IoT Smart Meter Market
Sensors and Controls
Aton Management and Monitoring System Market
Sensors and Controls
Torque Transducer Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Ultrasound Sensors Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Tactile Indicators Market