
 Thin Film Sensor Market | 2026-2036
Thin Film Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Film Sensor Market Outlook
A shortage of MEMS process engineers is unwinding capacity expansion timelines across Asian foundry networks. Sensata Technologies leverages its automotive heritage to dominate temperature sensor supply chains for powertrain electrification. Texas Instruments sustains R&D intensity in resistive thin film architectures for industrial automation endpoints. First Sensor AG specializes in optical thin film stacks for aerospace environmental monitoring, anchoring its position in German defense and satellite programs.
Thin film sensors are transducers fabricated through physical or chemical vapor deposition of functional materials onto ceramic, silicon, or polymer substrates, typically achieving active layers between ten nanometers and several micrometers in thickness; this deposition precision enables high sensitivity, fast response times, and minimal thermal mass for applications ranging from jet engine blade monitoring to continuous glucose tracking. Temperature sensors occupy the largest revenue pool due to universal deployment across automotive thermal management and HVAC systems, while gas sensors represent the fastest-expanding category as industrial safety mandates and smart building automation multiply detection node density. Piezoelectric technology leads in structural health monitoring for civil infrastructure and wind turbine blades, whereas electrochemical platforms dominate wearable medical applications where biocompatibility and power efficiency constrain design choices.
The EPA enforces emissions monitoring standards that mandate thin film gas sensor integration in stationary industrial sources across the United States, while REACH and RoHS in Europe restrict hazardous substances in sensor substrates and packaging materials, forcing reformulation of lead-containing piezoelectric compounds. China's GB standards and MIIT directives on smart manufacturing are accelerating domestic thin film sensor certification for industrial IoT networks. Stakeholders must monitor how divergent substance regulations between the EU, United States, and China fragment material qualification pathways and reshape supplier geographic footprints.
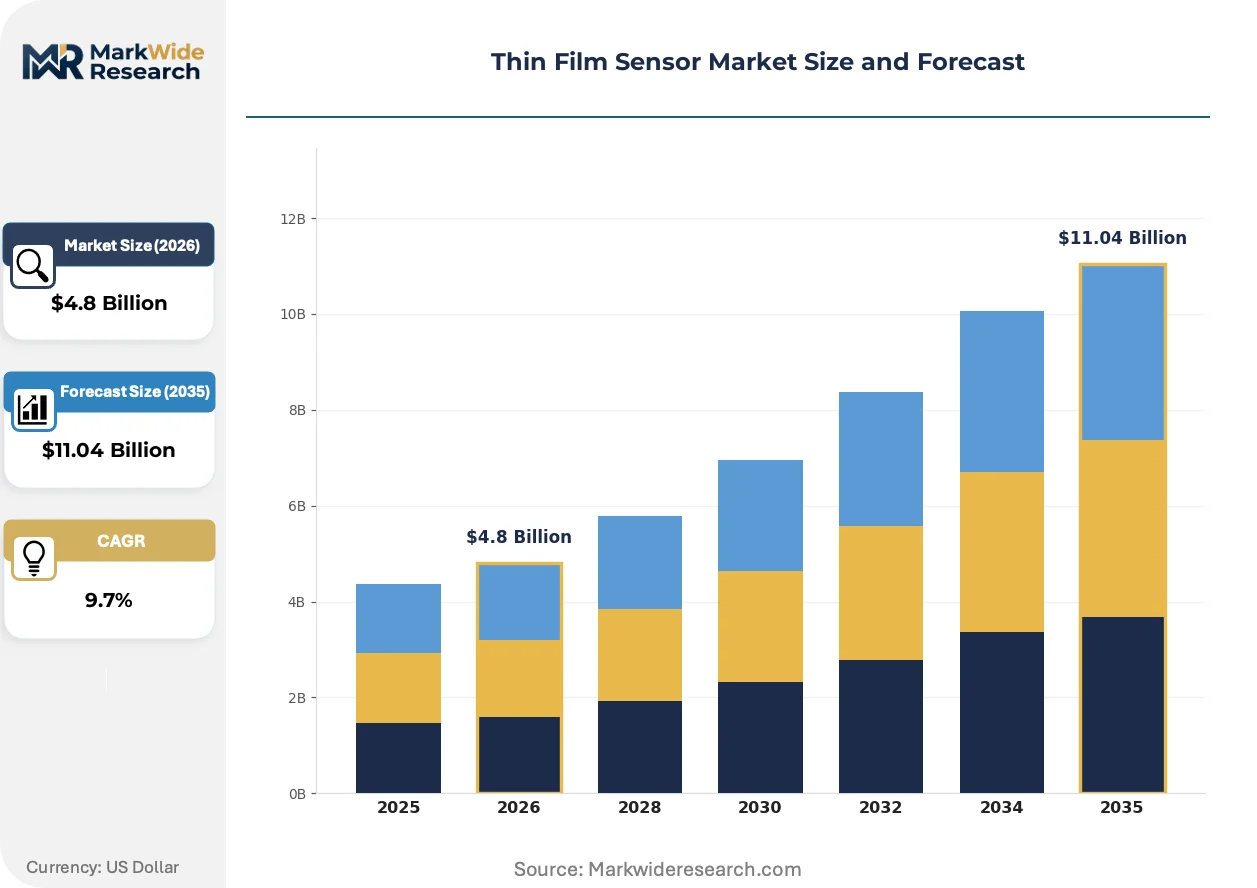
Market Dynamics
Automotive electrification programs in Germany and Japan are compressing OEM qualification timelines for thin film temperature and pressure modules, while MEMS fabrication expertise shortages across Southeast Asian foundries are forcing capacity investments toward South Korea and Taiwan.
Growth Catalysts
- Automotive Electrification:Powertrain thermal management systems in German and Japanese vehicle platforms are mandating thin film temperature sensors for battery pack monitoring. OEM procurement volumes are accelerating as EV production scales.
- EU Green Deal:REACH substance restrictions are compelling material substitutions in European sensor manufacturing, opening demand for compliant piezoelectric formulations and lead-free substrates.
- Industrial IoT Mandates:China's GB standards and MIIT directives on smart manufacturing are accelerating domestic thin film sensor certification for factory automation networks.
Market Restraints
- Palladium Price Volatility:Electrochemical gas sensors rely on palladium catalyst layers, and metal commodity swings compress margin structures for mid-tier manufacturers.
- MEMS Engineer Scarcity:Southeast Asian foundries face acute shortages of process engineers with deep expertise in multi-layer thin film deposition, unwinding legacy capacity expansion assumptions.
- Optical Sensor Substitution:Fiber optic sensing systems are displacing resistive thin film architectures in high-temperature aerospace turbine applications above 800°C.
Strategic Opportunities
- Wind Turbine Structural Health:Piezoelectric thin film arrays for blade monitoring represent underpenetrated demand in offshore installations across the North Sea and Baltic coastlines.
- Continuous Glucose Tracking:Wearable medical applications are driving biocompatible electrochemical sensor development, with Japanese and South Korean device makers expanding pilot programs.
- Dual Carbon Alignment:China's dual carbon goals are creating procurement preference for domestically certified thin film sensors in state-backed industrial IoT deployments.
Industry Challenges
- Multi-Site Qualification Burden:Tier-1 automotive suppliers demand identical sensor performance across German, Japanese, and South Korean manufacturing locations, stretching validation resources.
- Legacy System Integration:Industrial automation endpoints in mature manufacturing bases require analog-to-digital interface adaptation for new thin film outputs, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Film Sensor Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Humidity Sensors, Gas Sensors Technology: Electrochemical, Optical, Piezoelectric, Resistive End User: Automotive, Aerospace, Healthcare, Industrial Application: Wearable Devices, Smart Packaging, Environmental Monitoring, Structural Health |
| Companies Covered | Sensata Technologies, Texas Instruments, Panasonic Corporation, Analog Devices Inc., TE Connectivity, Honeywell International Inc., STMicroelectronics, NXP Semiconductors, First Sensor AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Film Sensor Market Strategic Shifts
Physical vapor deposition techniques are fragmenting across multiple substrate-material combinations, while regulatory substance restrictions and procurement model compression are simultaneously reshaping competitive positioning.
Atomic layer deposition for aluminum oxide passivation layers is fragmenting process equipment vendor landscapes. Automotive battery manufacturers are adopting these films for thermal runaway detection at sub-micron precision. The technology is fragmenting previously consolidated supply relationships as OEMs qualify multiple deposition tool suppliers.
REACH substance restrictions on lead-containing piezoelectric compounds are forcing reformulation of ceramic sensor substrates across European manufacturing. ECHA enforcement timelines are compressing material qualification windows to eighteen months. German and French sensor houses are accelerating partnerships with Japanese ceramic suppliers for compliant compositions.
Sensor-as-a-service contracting is displacing traditional component procurement in smart building automation. Facility management platforms are bundling thin film gas detection nodes with predictive maintenance software. This shift concentrates most visibly in Dutch and Danish commercial real estate portfolios seeking LEED certification compliance.
Thin Film Sensor Market Segmentation
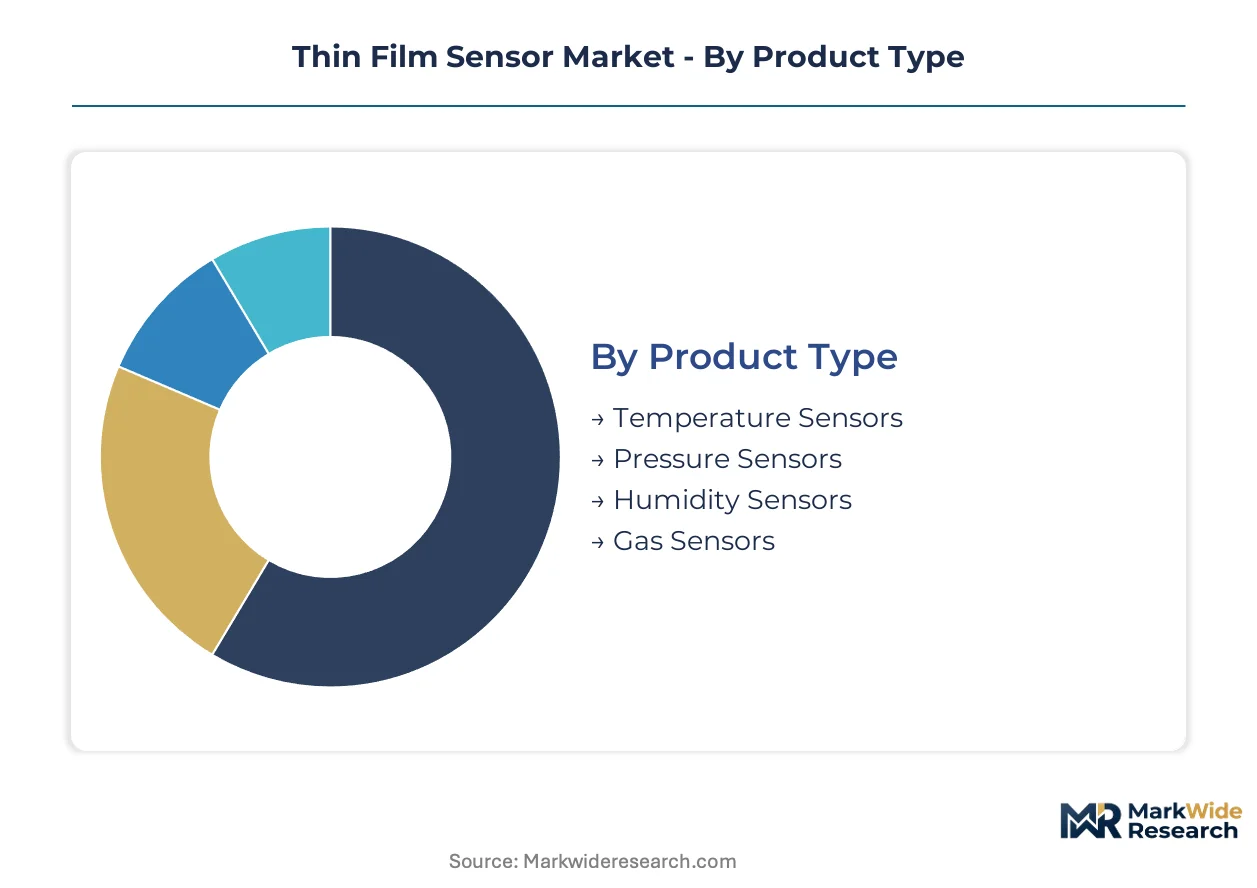
Thin film sensor architectures fragment across deposition methods, substrate materials, and functional layers, creating distinct competitive arenas where technical specifications and regulatory compliance intersect. Procurement patterns diverge sharply between automotive OEMs demanding multi-site qualification and industrial integrators prioritizing analog compatibility.
Product Type:
Temperature sensors dominate domestic procurement across German and Japanese automotive supply chains, while gas sensors drive export-led demand from Chinese and South Korean manufacturing bases.
- Temperature Sensors:Resistive platinum or nickel thin film elements deposited on ceramic substrates achieve millisecond response times for battery thermal management. German OEMs mandate these modules across powertrain platforms, compressing qualification timelines to eighteen months under EU Green Deal procurement rules.
- Gas Sensors:Electrochemical cells with palladium catalyst layers detect carbon monoxide and volatile organic compounds at parts-per-million sensitivity. Industrial safety mandates from the EPA and China's MEE are multiplying detection node density in stationary sources and smart building networks.
- Pressure Sensors:Piezoelectric thin film diaphragms on silicon substrates measure manifold absolute pressure in combustion and electric powertrains.
- Humidity Sensors:Capacitive polymer thin films absorb moisture to alter dielectric properties, serving HVAC and pharmaceutical storage applications.
Temperature sensors hold the largest share; momentum sits with gas sensors as industrial emissions monitoring expands.
Technology:
Cost tiers separate mature resistive architectures from premium optical stacks, with piezoelectric formulations occupying a mid-tier position constrained by material substitution timelines.
- Resistive:Metal thin films on ceramic or polymer substrates provide stable ohmic response across wide temperature ranges. Texas Instruments sustains R&D intensity for industrial automation endpoints where analog signal compatibility reduces integration costs.
- Optical:Interferometric thin film stacks measure environmental parameters through refractive index shifts. First Sensor AG anchors German defense and satellite programs with aluminum oxide passivation layers deposited via atomic layer deposition.
- Piezoelectric:Lead zirconate titanate thin films generate charge under mechanical stress for structural health monitoring. REACH restrictions on lead content are forcing Japanese ceramic supplier partnerships for compliant reformulations.
- Electrochemical:Three-electrode cells with catalytic working electrodes dominate wearable glucose tracking and industrial gas detection.
Resistive technology commands volume leadership; optical platforms are climbing the fastest as aerospace qualification cycles complete.
End User:
Application maturity varies sharply, with automotive and industrial segments requiring multi-year validation while healthcare and aerospace move through accelerated certification pathways.
- Automotive:Battery pack monitoring and thermal runaway detection mandate thin film temperature and pressure modules. Japanese and German OEM procurement volumes are scaling with EV platform launches.
- Industrial:Factory automation networks under China's MIIT directives and GB standards are accelerating domestic thin film sensor certification for predictive maintenance systems.
- Healthcare:Continuous glucose monitors and wearable vitals trackers demand biocompatible electrochemical sensors. South Korean and Japanese device makers are expanding pilot programs for regulatory submission.
- Aerospace:Turbine blade monitoring and environmental control systems utilize optical thin film stacks above 800°C where fiber optic alternatives compete.
Automotive end-use holds the largest share; healthcare is gaining share fastest as wearable form factors mature.
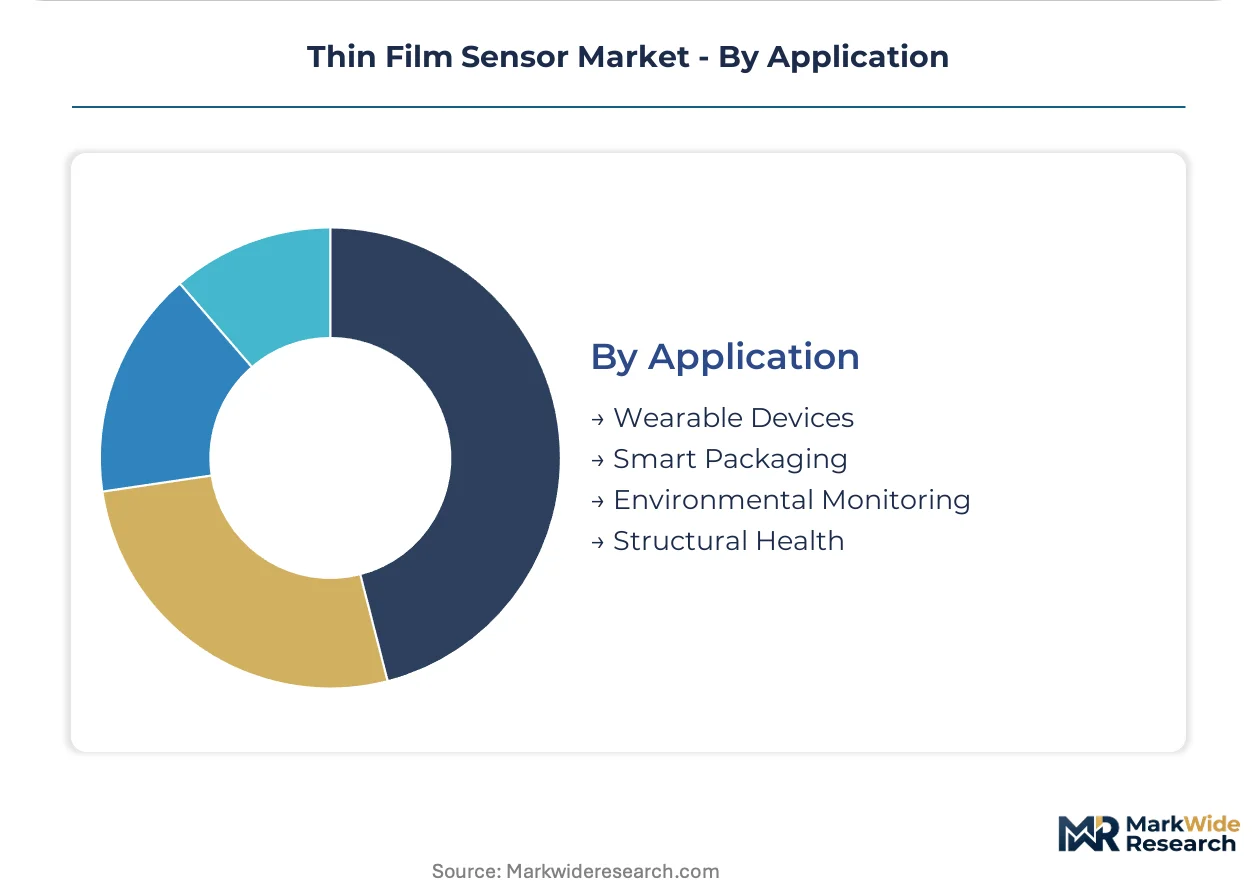
Application:
Customer type fragmentation separates high-volume consumer electronics integrators from specialized infrastructure contractors with divergent technical support requirements.
- Environmental Monitoring:Stationary industrial sources across the United States integrate thin film gas sensors under EPA emissions standards. Dutch and Danish commercial real estate portfolios bundle detection nodes with predictive maintenance software for LEED certification.
- Structural Health:Piezoelectric thin film arrays embedded in wind turbine blades detect crack propagation and ice accumulation. Offshore installations across the North Sea and Baltic coastlines represent underpenetrated demand.
- Wearable Devices:Skin-conformal electrochemical sensors track glucose and lactate in continuous monitoring applications.
- Smart Packaging:Printed humidity and gas sensors monitor pharmaceutical and food supply chain integrity.
Environmental monitoring holds the largest share; structural health is expanding most quickly as offshore wind capacity builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions monitoring standards mandate thin film gas sensor integration across United States industrial installations, while divergent substance regulations between the EU, United States, and China fragment material qualification pathways and reshape supplier geographic footprints.
United States
Stationary industrial sources deploy thin film gas sensors under EPA emissions standards for carbon monoxide and volatile organic compound detection. The EPA enforces parts-per-million sensitivity requirements that compress procurement timelines for electrochemical cell manufacturers. Houston and Gulf Coast petrochemical clusters anchor domestic demand for high-temperature pressure monitoring modules.
Germany
Automotive OEMs mandate thin film temperature sensors across battery thermal management and powertrain electrification platforms. REACH substance restrictions and the EU Green Deal compel lead-free piezoelectric formulations and material substitutions in sensor substrates. Bavarian sensor houses accelerate partnerships with Japanese ceramic suppliers for compliant compositions under ECHA enforcement timelines.
Japan
METI-directed automotive electrification programs expand OEM procurement of thin film temperature and pressure modules for EV platform launches. JIS standards govern sensor performance specifications for industrial automation and factory IoT networks. Nagoya and Osaka manufacturing corridors concentrate MEMS fabrication expertise for multi-layer deposition processes.
China
MIIT directives and GB standards on smart manufacturing accelerate domestic thin film sensor certification for predictive maintenance systems in factory automation networks. Dual carbon goals create procurement preference for state-certified sensors in industrial IoT deployments. Yangtze River Delta fabrication clusters redirect capacity investments as Southeast Asian foundries face MEMS engineer scarcity.
South Korea
Device makers expand pilot programs for biocompatible electrochemical sensors in continuous glucose tracking and wearable vitals applications. MFDS regulatory pathways compress submission timelines for medical-grade thin film architectures. Seoul Capital Area and Busan-Ulsan corridors concentrate R&D intensity in resistive and optical sensor stacks.
Thin Film Sensor Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with automotive heritage and MEMS fabrication capabilities determining competitive position. The vendor base separates into three archetypes: diversified semiconductor conglomerates with captive sensor divisions, pure-play sensor specialists with deep vertical application expertise, and industrial automation incumbents leveraging distribution scale. Dominant competitive moves include strategic partnerships for compliant material sourcing under REACH timelines and geographic expansion toward South Korean and Taiwanese foundry capacity.
Within the automotive-electrification tier, Sensata Technologies and Texas Instruments exemplify divergent strategic positions. Sensata occupies a heritage-anchored role in temperature sensor supply chains for powertrain thermal management, while Texas Instruments represents R&D-intensive investment in resistive architectures for industrial automation endpoints. First Sensor AG sits within the aerospace-specialist vector, its German GmbH structure signaling optical thin film expertise for defense and satellite environmental monitoring programs.
| Leading Market Players |
|---|
| Sensata Technologies |
| Texas Instruments |
| Panasonic Corporation |
| Analog Devices Inc. |
| TE Connectivity |
| Honeywell International Inc. |
| STMicroelectronics |
| NXP Semiconductors |
| First Sensor AG |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month qualification timelines for automotive thin film temperature modules concentrate pricing power with German and Japanese OEMs, compressing margin structures for mid-tier electrochemical sensor manufacturers dependent on palladium catalyst layers. This lead-time rigidity reinforces contract-based procurement dominance while fragmenting spot-market liquidity for specialty ceramic substrates.
Pricing Analysis
Geographic price spreads between South Korean foundry output and European in-house production run 15-25 percent for comparable resistive temperature sensors. Three-tier pricing structure across automotive-certified, industrial-grade, and unqualified economy levels separates Sensata's heritage-anchored premiums from emerging Chinese suppliers. Pricing pressure stems from MEMS engineer scarcity in Southeast Asian foundries forcing capacity premiums in Taiwan and South Korea. Automotive OEMs exhibit lowest price sensitivity due to thermal runaway liability exposure, while smart building integrators demand per-node cost compression for LEED certification compliance.
Supply Chain Analysis
Port congestion on the Shanghai-Rotterdam lane elevates inbound logistics costs for Japanese ceramic substrate suppliers serving Bavarian sensor houses. Manufacturing concentrates in Taiwan, South Korea, and Germany, with Yangtze River Delta clusters redirecting investments amid Southeast Asian MEMS expertise shortages. Palladium catalyst layers, aluminum oxide passivation films, and lead-free piezoelectric ceramics constitute critical input dependencies. Single-source vulnerability sits with Japanese ceramic suppliers for REACH-compliant formulations. Distribution runs through Tier 1 automotive supplier networks and industrial automation system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin film sensor market fragmentation creates specialist acquisition opportunities as automotive electrification, industrial IoT mandates, and wearable medical applications multiply distinct performance requirements. Demand-side bifurcation between millisecond-response automotive modules and biocompatible electrochemical trackers opens niche dominance pathways.
For Market Incumbents: Secure captive supply of REACH-compliant ceramic substrates through backward integration or long-term offtake with Japanese suppliers before ECHA enforcement compresses qualification windows. Anchor automotive qualification pipelines with multi-site validation investments in South Korea and Taiwan to preempt MEMS engineer scarcity disruptions. Defend margin position by locking eighteen-month OEM thermal management contracts before Chinese domestic suppliers achieve GB standard certification parity. For New Entrants and Emerging Players: Lead with continuous glucose monitoring electrochemical architectures for South Korean and Japanese wearable device makers, where MFDS regulatory pathways favor nimble submission timelines over heritage scale. Target underpenetrated offshore wind structural health monitoring across North Sea installations with piezoelectric blade arrays. Establish sensor-as-a-service contracting models for Dutch and Danish commercial real estate LEED compliance, bundling predictive maintenance software with gas detection node deployment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified semiconductor conglomerates with underperforming captive sensor divisions lacking automotive heritage or MEMS fabrication depth. Aerospace-specialist optical thin film houses with atomic layer deposition capabilities and defense program anchors offer durable five-to-ten year viability. Watch for inflection when Chinese state-backed industrial IoT procurement shifts from import preference to domestic certification parity under dual carbon alignment.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Partnership | ECHA enforcement timelines compress supplier qualification to eighteen months for European manufacturing. |
| Multi-Site Automotive Validation | German OEMs mandate identical performance across German, Japanese, and South Korean production locations. |
| Sensor-as-a-Service Contracting | Dutch and Danish commercial real estate bundles detection nodes with predictive maintenance for LEED certification. |
| MEMS Foundry Capacity Expansion | Taiwan and South Korea attract redirected investments as Southeast Asian engineer shortages unwind legacy assumptions. |
| Biocompatible Electrochemical R&D | South Korean and Japanese device makers expand pilot programs for continuous glucose tracking regulatory submission. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA enforcement records, ECHA substance restriction databases, MIIT directive filings, and customs trade data for palladium and ceramic substrate flows. Interviews with MEMS process engineering directors, Tier 1 automotive supplier procurement leads, industrial automation system integrators, and wearable device regulatory affairs managers inform demand-side validation. Bottom-up unit economics for temperature, pressure, gas, and humidity sensor modules triangulate against top-down OEM procurement volume disclosures and foundry capacity announcements.
Segmentation dimensions modeled span product type, deposition technology, end-use industry, and application across the analysis window. Resistive, optical, piezoelectric, and electrochemical technology tiers incorporate distinct material cost structures and qualification timeline assumptions. Automotive, industrial, healthcare, and aerospace end-use segments apply divergent price elasticity and regulatory compliance burdens. CAGRs derive from installed base growth in battery thermal management, emissions monitoring node density, and wearable form factor adoption curves.
Forecasts assume regulatory continuity in EPA emissions standards, REACH substance restrictions, and MIIT smart manufacturing directives; material policy shifts would require re-modeling. Palladium commodity volatility, MEMS engineer supply elasticity, and fiber optic substitution thresholds in aerospace applications constitute specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
North America Turbomachinery Control Systems Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Global Battery Free RFID Sensor Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
Submarine Sensor Market
Sensors and Controls
Position Sensor Market
Sensors and Controls
Air Particle Monitor System Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Middle East and Africa Lidar Market
Sensors and Controls
Distributed Temperature Sensing Market
Sensors and Controls
Sound Sensor Market