
 Wearable Thermometers Market | 2026-2036
Wearable Thermometers Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Thermometers Market Analytics
Multi-source sensor procurement is consolidating around semiconductor foundries with dedicated medical-grade fabrication lines. Texas Instruments Inc. anchors North American supply through its precision analog-to-digital converter portfolio for skin-contact thermometry. STMicroelectronics NV competes on MEMS integration density, embedding temperature sensing within broader inertial measurement units. Masimo leverages its pulse-oximetry hospital installed base to cross-sell wearable thermal monitoring into perioperative workflows.
Wearable thermometers are continuous or intermittent temperature-sensing devices affixed to skin, ear canal, or clothing, typically employing thermistors or infrared detectors with accuracy thresholds of ±0.1°C for clinical-grade units. Their primary purpose spans fever surveillance, ovulation tracking, athletic heat-stress prevention, and post-surgical recovery monitoring. Smart patches command premium positioning in hospital-at-home programs where adhesive-integrated Bluetooth transmission replaces wired spot checks. Infrared ear thermometers retain consumer-channel dominance due to instant-read familiarity, though Bluetooth-enabled units are displacing standalone models in pediatric telehealth kits. Thermal imaging wearables occupy a nascent niche in industrial athlete management where coaches demand non-contact core-temperature estimation.
FDA 510(k) premarket notification governs clinical claims for U.S. wearable thermometers, while the EU Medical Device Regulation (MDR) imposes post-market surveillance and unique device identification obligations for European market access. Japan's PMDA requires thermal-sensor biocompatibility testing under JIS T 10993 standards, adding certification cost for foreign entrants. Stakeholders must weigh regulatory capital intensity against channel-specific margin structures before committing to geographic expansion or product-line extensions.
Market Dynamics
FDA's tightened 510(k) data-validation requirements for wireless sensors are forcing manufacturers to rebuild clinical evidence packages, compressing margins for mid-tier entrants while advantaging incumbents with hospital installed bases.
Growth Catalysts
- Class II medical device clearance pathways:FDA's evolving digital health guidance creates competitive moats for firms that pre-invest in biocompatibility testing and electromagnetic compatibility documentation.
- Pediatric home monitoring:Parents in the United States, Germany, and Japan are adopting continuous temperature tracking for fever management, driving replacement cycles from spot-check thermometers to adhesive-integrated Bluetooth patches.
- Sports-medicine infrastructure:Athletic heat-stress prevention programs at collegiate and professional levels are procuring thermal monitoring wearables as standard equipment, embedding sensors into training protocols.
Market Restraints
- Semiconductor foundry concentration:Dedicated medical-grade fabrication lines at Texas Instruments and STMicroelectronics create single-source vulnerability for precision analog-to-digital converters and MEMS-integrated temperature sensors.
- Biocompatibility certification costs:Japan's PMDA requires thermal-sensor testing under JIS T 10993 standards, adding fixed compliance burdens that deter smaller foreign entrants from PMDA registration.
- Infrared ear thermometer substitution:Instant-read familiarity and lower price points of non-connected infrared units continue to dominate consumer pharmacy channels, slowing Bluetooth-enabled displacement.
Strategic Opportunities
- Hospital-at-home program expansion:CMS reimbursement shifts in the United States are creating procurement slots for adhesive-integrated smart patches that replace wired spot checks in post-surgical recovery monitoring.
- EU Medical Device Regulation tailwinds:MDR's unique device identification and post-market surveillance obligations favor suppliers with established quality management systems, compressing competitive field for European market access.
- MEMS-inertial convergence:Embedding temperature sensing within broader inertial measurement units enables multi-parameter athlete monitoring, opening industrial sports-medicine contracts beyond standalone thermometry.
Industry Challenges
- Clinical validation timelines:FDA's heightened scrutiny of wireless sensor accuracy claims extends 510(k) review cycles, delaying revenue recognition and straining R&D capitalization.
- Legacy health system integration:Perioperative workflows at hospitals require API compatibility with existing electronic health record architectures, forcing wearable thermometer vendors to maintain multiple software integration teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Thermometers Market |
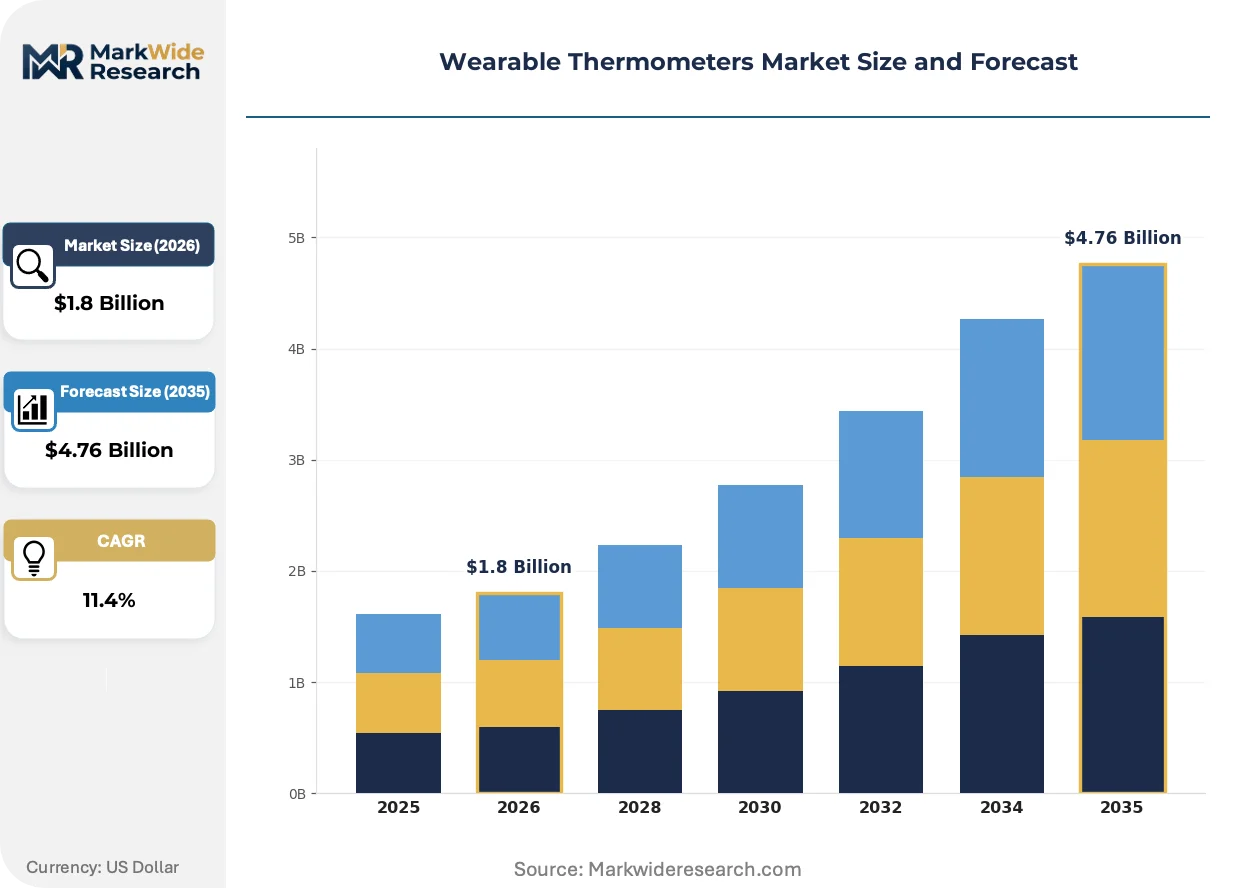
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Bands, Patches, Ear Thermometers, Wearable Health Monitors Technology: Infrared, Bluetooth, Thermocouple, Thermal Imaging End User: Consumers, Hospitals, Clinics, Sports Teams Distribution Channel: Online Retail, Pharmacies, Direct Sales, Health Stores |
| Companies Covered | VivaLNK, Blue Spark Technologies, Masimo, GreenTEG, Analog Devices Inc., Texas Instruments Inc., STMicroelectronics NV, Silicon Laboratories Inc., Melexis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Thermometers Market Evolving Landscape
Sensor miniaturization and adhesive-integrated wireless transmission are collapsing the distinction between consumer wellness devices and clinical-grade monitors, opening new procurement categories that did not exist five years ago.
Thermistor-based skin-contact sensors are modularizing into standardized form factors that separate the sensing element from the data-transmission module. Hospital-at-home programs in the United States are adopting these interchangeable architectures to swap disposable adhesives while retaining reusable Bluetooth cores. This architecture is modularizing supply chains, allowing contract manufacturers to compete on adhesive biocompatibility while semiconductor specialists capture converter value.
EU Medical Device Regulation's post-market surveillance requirements are mandating real-world performance tracking for Class IIa thermometry devices. Manufacturers must now maintain active complaint-handling systems and periodic safety update reports, increasing fixed compliance costs. European distributors are responding by consolidating vendor portfolios to reduce audit complexity, favoring suppliers with established notified body relationships.
Pediatric telehealth kits are displacing standalone pharmacy thermometers through bundled subscription models that combine hardware with fever-management apps. Parents in Japan and Germany are purchasing these kits through insurer-subsidized channels rather than retail. This channel migration is most visible in Germany, where statutory health insurance funds have begun reimbursing connected thermometry for chronic condition monitoring.
Wearable Thermometers Market Segmentation
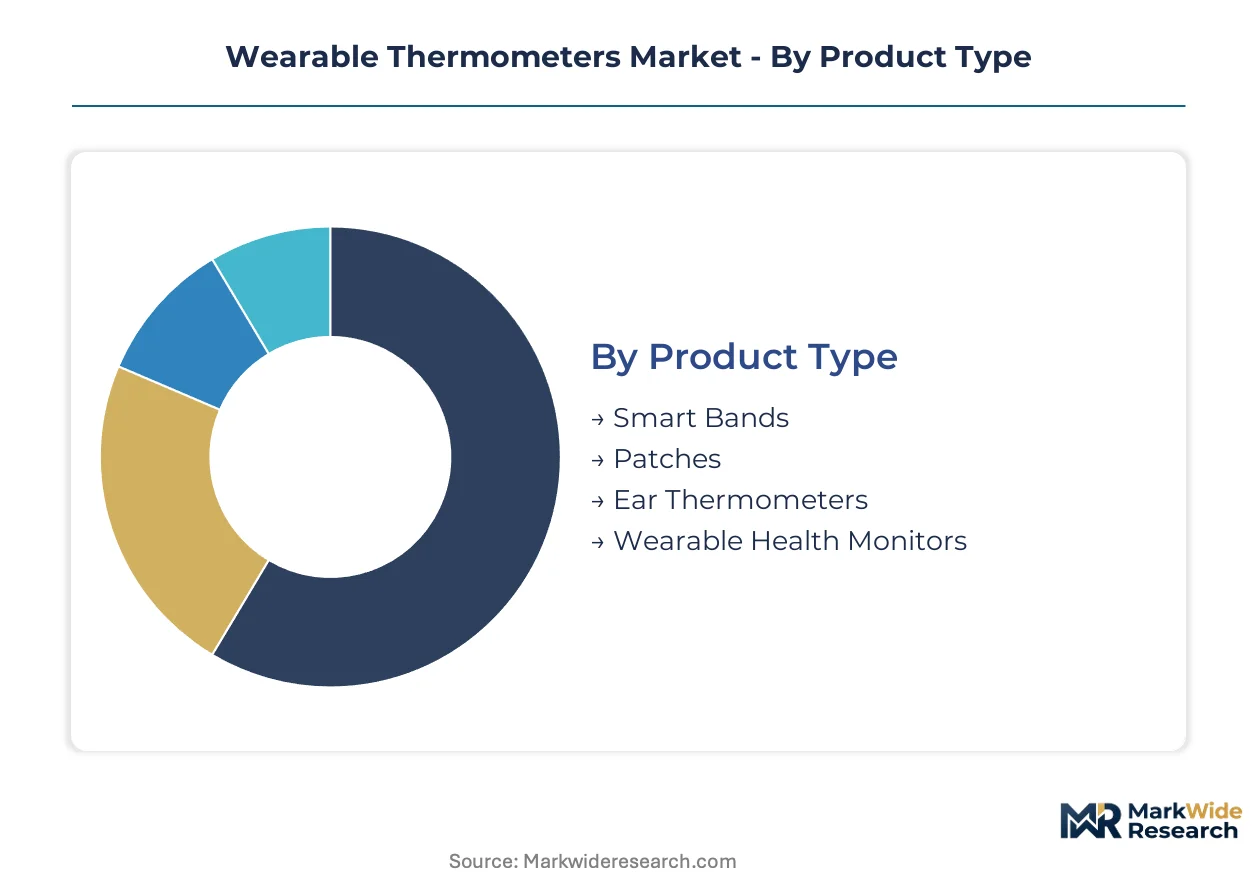
Wearable thermometer segmentation reveals divergent regulatory pathways across product architectures. FDA 510(k) clearance requirements split the addressable market between consumer wellness devices and clinical-grade monitors with distinct certification burdens and margin structures.
Product Type:
Smart bands require FCC electromagnetic certification plus FDA 510(k) for clinical claims, while patches face additional biocompatibility testing under ISO 10993 standards. Ear thermometers navigate the lightest regulatory load when marketed for home use only.
- Smart Bands:Wrist-worn devices integrate temperature sensing with accelerometry and optical heart-rate monitoring. Demand concentrates in United States sports-medicine programs where collegiate athletic departments procure multi-parameter units for heat-stress protocols. Bluetooth synchronization with team analytics platforms drives replacement cycles.
- Patches:Adhesive-integrated sensors with disposable skin-contact layers and reusable transmission cores. Hospital-at-home programs in Germany and Japan are standardizing these for post-surgical fever surveillance, with reimbursement codes emerging for continuous remote patient monitoring.
- Ear Thermometers:Instant-read infrared devices dominate consumer pharmacy channels. Lower price points and familiar form factors sustain volume despite limited connectivity.
- Wearable Health Monitors:Multi-parameter chest-worn or clothing-integrated systems. Professional sports teams in Japan represent the primary procurement channel.
Ear thermometers sit at the top of the volume ranking, with patches climbing the fastest.
Technology:
Technology selection determines unit economics and regulatory capital intensity. Infrared and thermal imaging platforms demand precision calibration documentation for FDA clearance, while thermocouple architectures leverage existing 510(k) predicates.
- Infrared:Non-contact temperature estimation through emitted radiation detection. Dominates ear and forehead applications with sub-second read times. United States pediatric telehealth kits are displacing standalone units through bundled subscription models.
- Bluetooth:Wireless transmission protocol enabling continuous data streaming to smartphones and EHR systems. Hospital-at-home procurement specifications now mandate Bluetooth 5.0 or higher for range and security.
- Thermocouple:Junction-based sensors with millivolt output proportional to temperature differential. Skin-contact patches in Germany favor this architecture for stability across adhesive wear durations.
- Thermal Imaging:Array-based non-contact core-temperature estimation. Nascent adoption in Japanese industrial athlete management where coaches demand perimeter monitoring without sensor attachment.
Infrared technology commands the highest shipment volumes, with thermal imaging expanding most quickly from a small base.
End User:
End-user segmentation maps directly to procurement authority and reimbursement pathways. Hospital and clinic procurement operates through group purchasing organizations with quality management system audits, while consumer and sports channels reward brand recognition and app ecosystem integration.
- Consumers:Individual purchasers through retail and online channels. Parents in Japan and Germany are migrating from pharmacy spot-check devices to connected telehealth kits with fever-management apps.
- Hospitals:Inpatient and perioperative workflows requiring EHR integration. Masimo leverages its pulse-oximetry installed base to cross-sell thermal monitoring in United States acute care settings.
- Clinics:Outpatient and urgent care facilities with lighter IT infrastructure. Bluetooth-enabled units with standalone tablet compatibility dominate this channel.
- Sports Teams:Collegiate, professional, and industrial athletic programs. Heat-stress prevention mandates in United States NCAA programs are embedding sensors into standard training equipment.
Consumers represent the largest addressable population, with sports teams gaining share fastest as heat-safety regulations tighten.
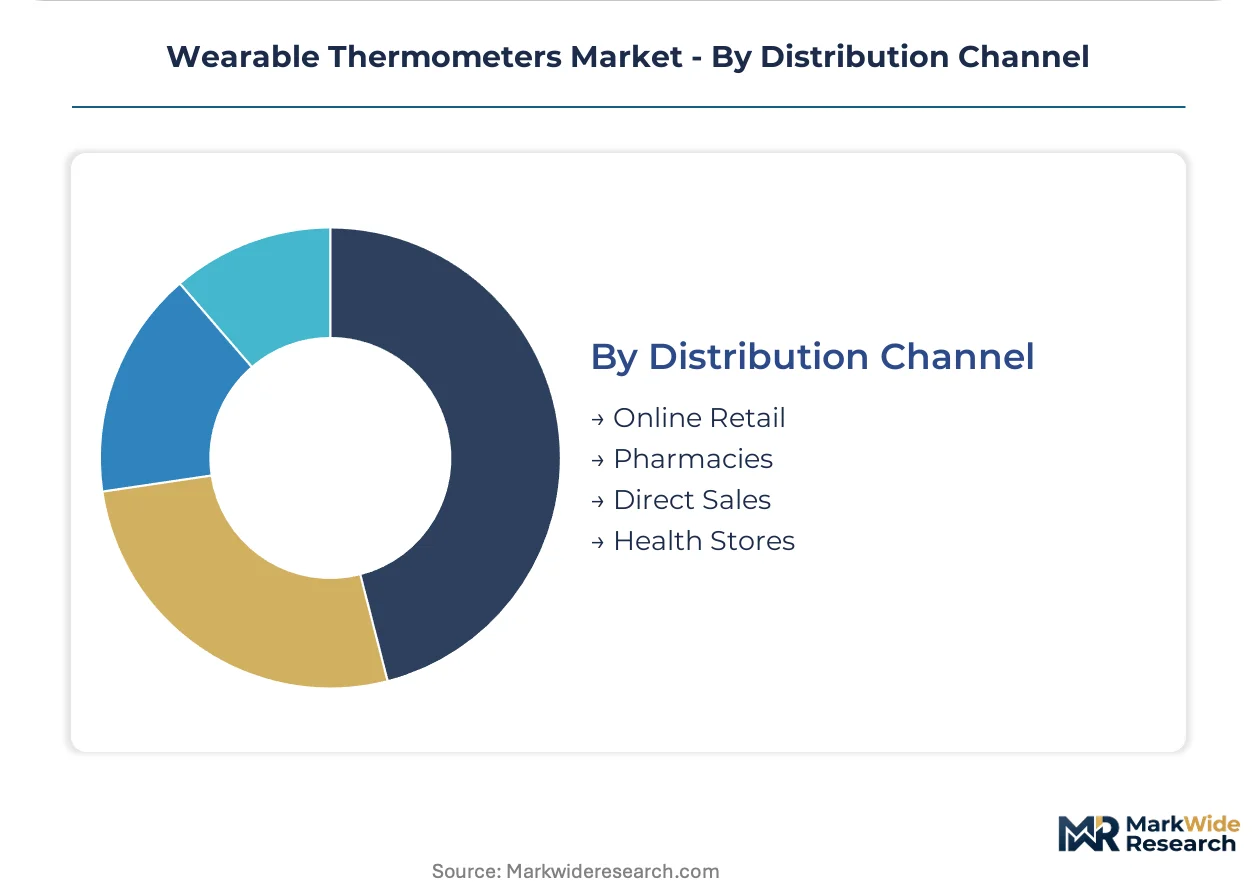
Distribution Channel:
Channel selection determines margin capture and customer acquisition cost. Direct sales to hospital systems yield the highest per-unit margins but require dedicated clinical specialist teams, while online retail scales efficiently with limited regulatory overhead.
- Online Retail:E-commerce platforms and direct-to-consumer brand sites. German statutory health insurance funds are piloting reimbursement for connected thermometry purchased through approved online channels.
- Pharmacies:Brick-and-mortar drugstore chains with pharmacy staff recommendation influence. Infrared ear thermometers retain dominance here due to instant-gratification purchasing behavior.
- Direct Sales:Manufacturer-led clinical specialist teams calling on hospital purchasing committees. Required for Class II medical device procurement with EHR integration requirements.
- Health Stores:Wellness-focused retail with educated staff. Niche positioning for fertility-tracking and ovulation-monitoring applications.
Pharmacies maintain volume leadership, with direct sales expanding most quickly as hospital-at-home programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as medical-grade fabrication migrates toward jurisdictions with streamlined biocompatibility certification pathways. Foundries in Germany and Japan absorb premium-tier production, while assembly operations concentrate in cost-optimized zones with harmonized ISO 13485 recognition.
United States
Pediatric home monitoring and sports-medicine procurement drive demand clusters in California and Massachusetts. FDA's tightened 510(k) data-validation requirements for wireless sensors compress margins for mid-tier entrants. Boston's medical device corridor anchors perioperative workflow integration development.
Germany
Statutory health insurance reimbursement for connected thermometry is accelerating hospital-at-home program adoption. EU Medical Device Regulation post-market surveillance obligations favor suppliers with established notified body relationships. Baden-Württemberg's precision engineering cluster concentrates MEMS-integrated temperature sensor fabrication.
Japan
Aging demographics and industrial athlete management programs sustain dual demand channels. PMDA requires thermal-sensor biocompatibility testing under JIS T 10993 standards, adding certification cost for foreign entrants. Tokyo-Osaka corridor dominates adhesive-integrated smart patch procurement for post-surgical recovery monitoring.
China
Domestic semiconductor self-sufficiency initiatives are expanding local medical-grade ADC and MEMS foundry capacity. NMPA medical device registration timelines remain unpredictable for foreign thermometer vendors. Yangtze River Delta manufacturing hubs supply contract assembly for modular patch architectures.
South Korea
Digital health infrastructure investments and telemedicine platform expansion create procurement slots for Bluetooth-enabled thermometry. MFDS medical device approval pathways are harmonizing with FDA predicate device recognition. Seoul Capital Area health systems pilot multi-parameter wearable integration into electronic health records.
Wearable Thermometers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue MEMS-inertial convergence and hospital-at-home program slots. Market structure consolidates around semiconductor foundries with dedicated medical-grade fabrication lines and device vendors with pulse-oximetry installed bases. Three archetypes dominate: precision analog component suppliers, adhesive-integrated patch specialists, and multi-parameter vital signs platform vendors. Competitive moves concentrate on cross-selling thermal monitoring into existing hospital workflows and backward integration into captive MEMS fabrication.
Within the precision analog tier, Texas Instruments Inc. and Analog Devices Inc. anchor North American supply for skin-contact thermometry converters. STMicroelectronics NV exemplifies the MEMS integration archetype, embedding temperature sensing within broader inertial measurement units for multi-parameter athlete monitoring. Masimo occupies a position leveraging pulse-oximetry hospital installed bases to cross-sell wearable thermal monitoring into perioperative workflows.
| Leading Market Players |
|---|
| VivaLNK |
| Blue Spark Technologies |
| Masimo |
| GreenTEG |
| Analog Devices Inc. |
| Texas Instruments Inc. |
| STMicroelectronics NV |
| Silicon Laboratories Inc. |
| Melexis |
| Others |
Value Network & Pricing Analysis
Clinical-grade versus consumer wellness certification divergence splits the wearable thermometers market into parallel pricing architectures with distinct supply chain configurations. Premium-tier adhesive-integrated patches command hospital-at-home procurement slots through FDA 510(k) validation and biocompatibility documentation, while commodity infrared ear units flow through pharmacy retail with minimal regulatory overhead. This bifurcation concentrates margin capture among semiconductor foundries with medical-grade fabrication lines and fragments downstream assembly across contract manufacturers competing on adhesive cost.
Pricing Analysis
Distributor margins in European markets absorb the heaviest compression as notified body audit costs cascade through vendor consolidation. Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-enabled smart patches with EHR integration from standalone infrared units and basic thermistor bands. Price differentiation hinges on FDA clearance tier and ISO 10993 biocompatibility grade. Pricing pressure stems from tightened 510(k) data-validation requirements extending review timelines. Consumer pharmacy channels exhibit highest price sensitivity; hospital procurement committees prioritize interoperability over unit cost.
Supply Chain Analysis
Refurbishment flows for reusable Bluetooth transmission cores are emerging as German hospital-at-home programs standardize modular patch architectures. Precision analog-to-digital converter fabrication concentrates in the United States, Taiwan, and South Korea, with MEMS-integrated temperature sensing anchored in European and Japanese foundries. Raw material dependencies center on medical-grade silicon wafers, biocompatible adhesives, and lithium-polymer cells. Single-source vulnerability at Texas Instruments and STMicroelectronics medical-grade lines constitutes the dominant structural risk. Distribution runs through group purchasing organizations for hospital procurement and direct-to-consumer online channels for pediatric telehealth kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wearable thermometers market has entered a late-cycle quality phase where reimbursement-aligned clinical validation displaces consumer wellness positioning. Demand is concentrating toward continuous monitoring specifications that satisfy CMS remote patient monitoring codes and German statutory health insurance reimbursement pathways.
For Market Incumbents: Acquire MEMS fabrication capacity or captive semiconductor packaging capability to secure converter supply against foundry concentration risk. Defensive consolidation should prioritize backward integration into medical-grade ADC production and deepen ISO 13485 quality management certifications ahead of EU MDR surveillance mandates. Threats from emerging patch specialists with adhesive biocompatibility expertise require preemptive channel control through exclusive hospital-at-home program partnerships. For New Entrants and Emerging Players: Thermal imaging array miniaturization offers a technology-first wedge into Japanese industrial athlete management programs where non-contact core-temperature estimation remains underpenetrated. White-space targets include insurer-subsidized pediatric telehealth kits in Germany and Bluetooth 5.0-enabled units for United States collegiate sports-medicine procurement. Go-to-market execution should leverage direct clinical specialist teams calling on hospital purchasing committees rather than retail pharmacy distribution. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA 510(k) clearance moats and hospital installed bases overlap with deteriorating R&D capitalization among mid-tier entrants. Long-term viability over a multi-year horizon favors platform vendors with pulse-oximetry cross-selling capability and established GPO contract relationships. Acquisition target archetypes include adhesive-integrated patch specialists with notified body relationships and modular architecture IP. Signal to monitor: CMS reimbursement code expansion for continuous thermometry in post-surgical recovery monitoring.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Pre-investing in wireless sensor validation data compresses review cycles against tightened scrutiny. |
| Hospital System Partnership | Masimo-style cross-selling into perioperative workflows leverages existing pulse-oximetry installed base. |
| Backward Integration into MEMS Fabrication | Captive temperature sensor production insulates against STMicroelectronics and Texas Instruments concentration risk. |
| Reimbursement Strategy Development | German statutory health insurance pilot programs for connected thermometry open sustainable procurement channels. |
| Software Companion Development | Fever-management apps bundled with pediatric telehealth kits displace standalone pharmacy thermometers through subscription retention. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and South Korea, with primary inputs from each market's regulatory and procurement stakeholders. The analysis combines structured interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, PMDA registration records, and CMS reimbursement code databases. Bottom-up demand modeling across patient monitoring applications triangulates against top-down semiconductor foundry capacity assessments.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. The analytical framework models wearable thermometer demand through product type segmentation (smart bands, patches, ear thermometers, wearable health monitors), technology architecture (infrared, Bluetooth, thermocouple, thermal imaging), end-user category (consumers, hospitals, clinics, sports teams), and distribution channel configuration. CAGRs derive from patient population growth, reimbursement policy shifts, and sports-medicine infrastructure investment trajectories. Industry-specific forecast inputs include FDA digital health guidance evolution and EU MDR post-market surveillance compliance cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry capacity allocation decisions and regulatory harmonization timelines. Forecasts reflect documented assumptions regarding reimbursement code stability and wireless sensor accuracy validation standards. Practitioners should monitor FDA 510(k) review cycle duration, German statutory health insurance reimbursement pilot expansions, and MEMS foundry medical-grade line investments for early signals of trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Potentiometer Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
US Pressure Sensors Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Asia-Pacific Wireless Brain Sensors Market
Sensors and Controls
Digital Temperature Gauge Market
Sensors and Controls
US Temperature Sensors Market
Sensors and Controls
Electric Vehicle (EV) Sensor Market
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Global Proximity and Displacement Sensors Market
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market
Sensors and Controls
Inductive Encoder Market
Sensors and Controls
Aeroderivative Sensor Market