
 Asia Pacific Material Handling Equipment Market | 2026-2036
Asia Pacific Material Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Material Handling Equipment Market Intelligence
The capital-intensity divergence between automated system providers and conventional equipment makers is redrawing vendor rankings in the Asia Pacific material handling equipment sector. DAIFUKU Co. Ltd. leverages its integrated conveyor and automated storage portfolio to dominate airport baggage and semiconductor cleanroom logistics across Japan and Southeast Asia. XCMG Construction Machinery Co., Ltd. anchors heavy-lift crane and port equipment sales through state-backed infrastructure tenders in China and Belt and Road port developments. Geekplus Technology Co., Ltd. differentiates its mobile robot fleet by specializing in shelf-to-person systems for e-commerce warehouses, competing directly with established forklift networks.
Asia Pacific material handling equipment encompasses powered and non-powered machinery engineered to transport, store, control, and protect materials throughout manufacturing, distribution, and disposal operations, with load capacities spanning kilogram-scale parcel sortation to hundred-tonne container crane lifts. Conveyors form the backbone of high-throughput distribution centers and mining bulk-handling operations where continuous flow dictates operational efficiency. Automated guided vehicles represent the fastest-expanding technology segment as warehousing applications shift from manual forklift fleets to autonomous mobile platforms. Industrial trucks retain the largest installed base across manufacturing units, though margin pools increasingly concentrate in electric drive variants replacing hydraulic and pneumatic systems under tightening emissions protocols.
China's MIIT enforces GB standards on industrial truck energy efficiency and electromagnetic compatibility, while Japan's METI administers JIS certification for crane safety and automated system reliability. India's BIS mandates equipment testing for construction and mining material handlers under the CEA's electrical safety framework. Stakeholders must monitor how China's SAMR integrates dual carbon goals into equipment procurement rules and whether India's PLI scheme extends subsidies to domestic automated guided vehicle production.
Market Dynamics
China's dual carbon goals are compressing equipment replacement cycles across Asia Pacific, forcing port operators and e-commerce fulfillment centers to retire diesel-powered forklifts and cranes ahead of depreciation schedules.
Growth Catalysts
- India's PLI scheme for manufacturing:Domestic production incentives for advanced manufacturing are stimulating capital expenditure on automated guided vehicles and conveyor systems in Gujarat and Tamil Nadu industrial corridors.
- Semiconductor cleanroom logistics:Japan's METI-backed chip fabrication expansion is generating specialized demand for ultra-clean automated storage and retrieval systems with particulate contamination controls.
- Yangtze River Delta cluster concentration:Shanghai-Ningbo port automation and Hangzhou e-commerce fulfillment density are driving synchronized procurement of robotic sortation and autonomous mobile platforms.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing and cell manufacturing concentrate in China's Fujian and Sichuan provinces, exposing automated vehicle fleets to input cost volatility and export restriction risk.
- GB standard compliance friction:China's MIIT electromagnetic compatibility testing requirements for industrial trucks extend certification timelines by four to six months for non-domestic suppliers.
- Manual forklift residual value:Secondary markets for liquid petroleum gas and diesel equipment across Southeast Asia are delaying fleet electrification decisions among cost-sensitive third-party logistics providers.
Strategic Opportunities
- Vietnam's northern industrial zone expansion:Samsung and Foxconn supplier park development around Bac Ninh and Hai Phong is creating greenfield demand for integrated conveyor and robotic palletizing systems without legacy infrastructure displacement.
- Battery-swapping infrastructure:Convergence of automated guided vehicle fleets with standardized battery exchange protocols is enabling 24-hour continuous operation models in high-throughput e-commerce warehouses.
- Japan's carbon border alignment:METI incentives for energy-efficient equipment procurement are opening premium pricing windows for European and Korean automated system vendors with certified low-carbon manufacturing footprints.
Industry Challenges
- Mechatronics technician scarcity:Maintenance and programming of autonomous mobile robot fleets requires cross-trained personnel fluent in both mechanical systems and fleet management software, a combination rarely available in Indonesian and Philippine labor markets.
- Legacy warehouse management system integration:Automated guided vehicle deployment in established Japanese and Korean distribution centers faces middleware compatibility gaps with 1990s-era inventory databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Material Handling Equipment Market |
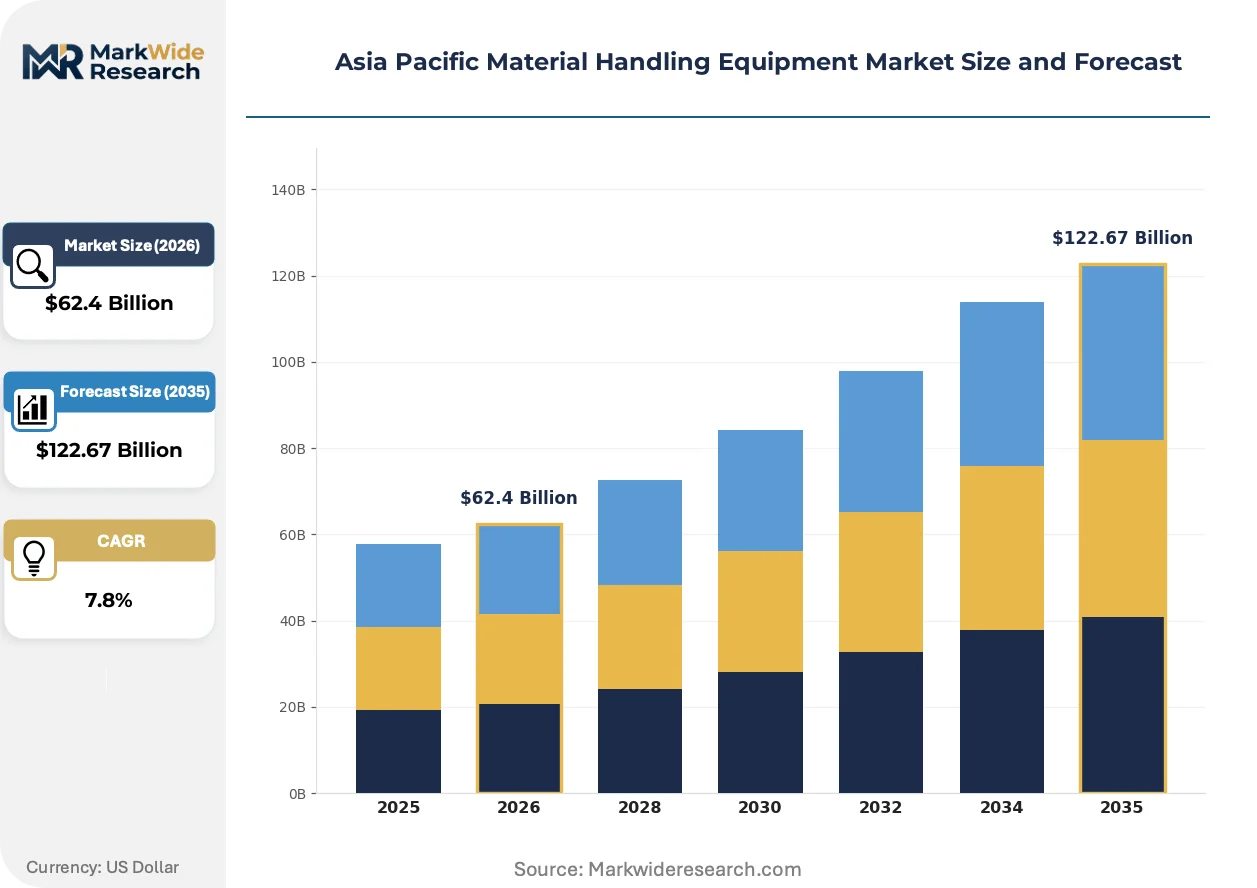
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $122.67 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyors, Industrial Trucks, Automated Guided Vehicles, Hoists, Cranes Technology: Electric Drives, Hydraulic Drives, Pneumatic Systems, Manual Operation Application: Warehousing, Manufacturing Units, Distribution Centers, Port Terminals, Mining Operations End User: Logistics Providers, Construction Firms, Mining Companies, Food Processing Plants, Automotive Manufacturers |
| Companies Covered | XCMG Construction Machinery Co., Ltd., Mitsubishi Logisnext Co., Ltd., DAIFUKU Co. Ltd., Jungheinrich AG, KION Group AG, Murata Machinery Ltd., Noblelift Intelligent Equipment Co. Ltd., Geekplus Technology Co., Ltd., Toyota Industries Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Material Handling Equipment Market Strategic Shifts & Innovations
Autonomous navigation architectures are fragmenting competitive boundaries between traditional forklift manufacturers and robotics specialists across Asia Pacific warehousing operations.
Vision-guided autonomous mobile robots are fragmenting the material handling technology landscape by substituting camera-based localization for laser reflector and magnetic tape guidance systems. E-commerce fulfillment centers in China's Pearl River Delta are deploying these platforms at trial-to-production velocity of under ninety days. The technology is fragmenting vendor hierarchies by enabling electronics contract manufacturers without mechanical engineering heritage to enter warehouse automation.
China's SAMR is integrating dual carbon goals into mandatory government procurement rules for port and airport material handling equipment, effective for tenders above specified capital thresholds. Industrial consequence includes automatic technical disqualification of diesel-powered crane and tractor offerings in state-backed infrastructure projects. Port operators in Qingdao and Tianjin are responding by accelerating electric rubber-tired gantry crane orders and requesting battery-swapping compatibility in specifications.
Equipment-as-a-service contracting is displacing capital purchase models among mid-scale third-party logistics providers in India and Southeast Asia. Monthly per-robot or per-pallet-position pricing bundles maintenance, software updates, and fleet optimization analytics that previously required separate vendor relationships. This shift is most visible in Bangalore and Jakarta urban logistics networks where warehouse tenancy cycles compress below five years.
Asia Pacific Material Handling Equipment Market Segmentation
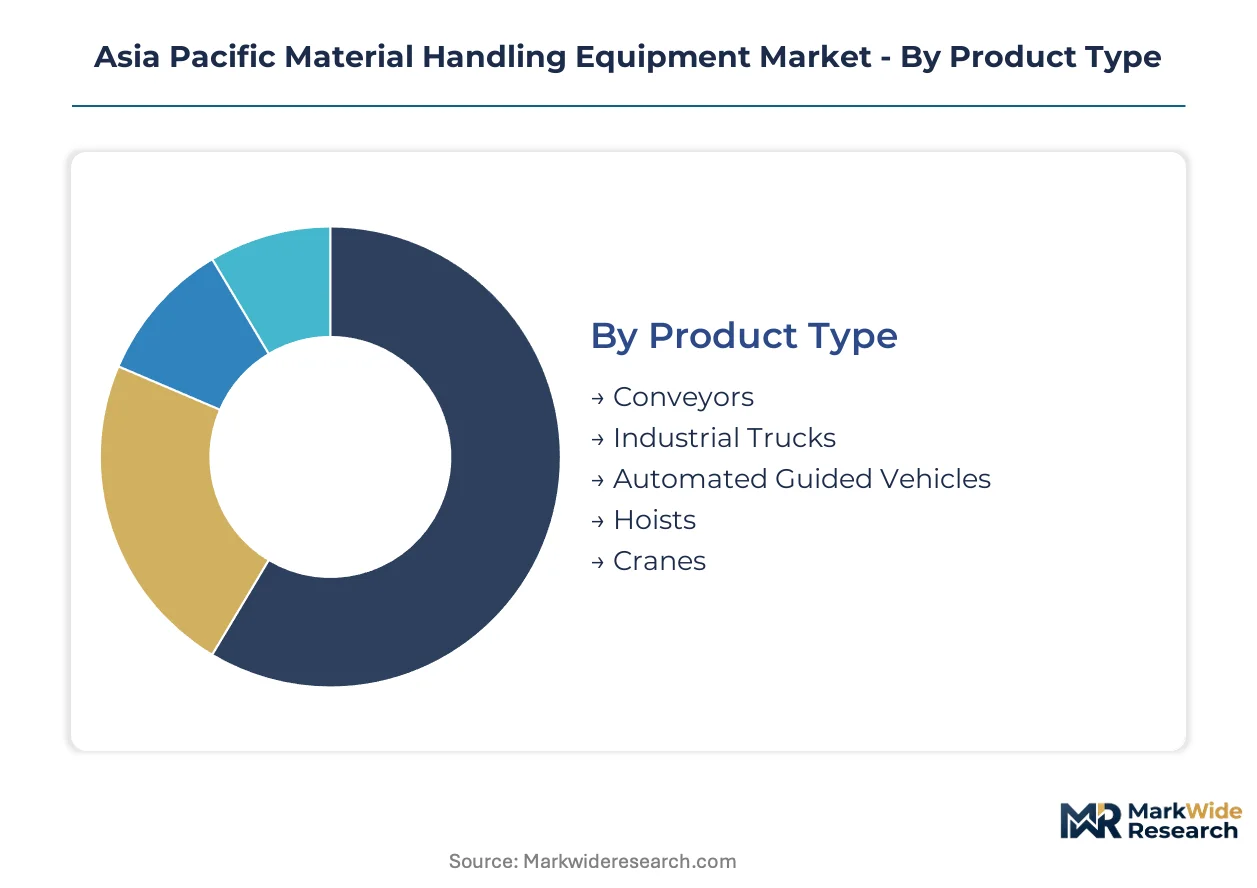
Equipment substitution dynamics across Asia Pacific are fragmenting traditional category boundaries as electric drives displace hydraulic systems and autonomous platforms challenge forklift incumbency. Segment-level procurement decisions increasingly hinge on carbon compliance timelines rather than depreciation cycles alone.
Product Type:
Automated platforms face the strongest substitution pressure from vision-guided robotics, while legacy hoists and cranes confront accelerated replacement under China's dual carbon procurement rules.
- Conveyors:Continuous-flow systems integrate belt, roller, and chain configurations for high-throughput parcel sortation and bulk mineral transport. Demand clusters in Yangtze River Delta e-commerce fulfillment centers where Hangzhou and Shanghai operators synchronize procurement with automated storage retrieval systems.
- Industrial Trucks:Counterbalance and reach trucks powered by lithium-ion batteries are displacing liquid petroleum gas fleets in Japanese automotive plants and Korean electronics assembly lines. Fleet managers in Toyota City and Hwaseong prioritize fast-charge compatibility to maintain two-shift operational continuity.
- Automated Guided Vehicles:Laser-guided and vision-based mobile robots execute pallet transport and shelf-to-person retrieval without fixed infrastructure. China's MIIT electromagnetic compatibility testing extends certification timelines for foreign suppliers deploying in Qingdao port automation projects.
- Hoists:Wire rope and chain hoists handle vertical lifting in construction and maintenance applications across Southeast Asian infrastructure developments.
- Cranes:Rubber-tired gantry and overhead bridge cranes service port terminals and heavy manufacturing in Tianjin and Busan industrial zones.
Industrial Trucks retain volume leadership; Automated Guided Vehicles hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium electric drive systems from legacy hydraulic alternatives, with pneumatic equipment occupying a narrowing mid-market position in food-grade applications.
- Electric Drives:AC motor and battery-electric configurations deliver zero-emission operation with regenerative braking and precision speed control. Port operators in Ningbo and Shenzhen specify battery-swapping compatibility in rubber-tired gantry crane tenders to satisfy SAMR dual carbon procurement thresholds.
- Hydraulic Drives:Fluid power systems retain installed base in heavy-lift mining and construction equipment across Indonesian coal terminals and Australian iron ore handling facilities.
- Pneumatic Systems:Compressed-air actuation powers cleanroom-compatible handling in semiconductor fabrication logistics where particulate contamination controls are mandatory.
- Manual Operation:Hand trucks and pallet jacks serve cost-sensitive last-mile distribution in Philippine and Vietnamese urban logistics networks with limited electrification infrastructure.
Electric Drives command premium pricing tiers; Manual Operation maintains penetration in fragmented third-party logistics segments.
Application:
Geographic concentration patterns reveal divergent automation maturity, with coastal China and Japan leading platform deployment while inland Southeast Asian markets remain equipment-constrained.
- Warehousing:Automated storage and retrieval systems with robotic palletizing serve e-commerce fulfillment density in China's Pearl River Delta. Geekplus and domestic competitors deploy shelf-to-person mobile robots with ninety-day trial-to-production cycles in Shenzhen and Dongguan facilities.
- Manufacturing Units:Just-in-time conveyor networks and autonomous tugger trains link assembly stations in Toyota City and Hyundai Motor's Ulsan complex. METI incentives for energy-efficient equipment procurement favor certified low-carbon system vendors.
- Distribution Centers:Cross-dock sortation systems handle high-velocity parcel flows for third-party logistics providers in Bangalore and Jakarta urban networks.
- Port Terminals:Automated stacking cranes and straddle carriers manage container throughput in Shanghai-Ningbo hub operations.
- Mining Operations:Bulk-handling conveyors and heavy-lift excavators extract and transport coal and iron ore across Queensland and Kalimantan extraction sites.
Manufacturing Units anchor equipment installed base; Warehousing applications are expanding most quickly.
End User:
Customer type differentiation separates capital-intensive automation adopters from price-sensitive equipment renters, with logistics providers leading platform deployment and construction firms lagging in fleet electrification.
- Logistics Providers:Third-party operators in India and Southeast Asia are shifting from capital purchase to equipment-as-a-service models with per-robot monthly pricing. Bangalore and Jakarta warehouse tenancy cycles below five years favor bundled maintenance and software update contracts over ownership.
- Construction Firms:Tower crane and mobile hoist procurement concentrates in state-backed infrastructure tenders across China's Belt and Road port developments and Vietnam's northern industrial zone expansion around Bac Ninh.
- Mining Companies:Bulk material handling systems face tightening emissions protocols in Australian and Indonesian extraction operations.
- Food Processing Plants:Stainless steel conveyors and hygienic design automated guided vehicles comply with FSSAI and local food safety mandates in Maharashtra and Gujarat processing corridors.
- Automotive Manufacturers:Assembly line conveyor synchronization and automated guided vehicle fleet management support just-in-sequence parts delivery in Chennai and Chakan supplier parks.
Logistics Providers drive autonomous platform adoption; Automotive Manufacturers maintain the deepest vertical integration into material handling system design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing power in automated port equipment procurement while Vietnam absorbs cost-sensitive conveyor and robotic palletizing demand from manufacturers relocating supply chains. This asymmetry shapes capital allocation across the region's material handling value chain.
China
Shanghai-Ningbo port automation and Hangzhou e-commerce fulfillment density drive synchronized procurement of robotic sortation and autonomous mobile platforms. MIIT enforces GB standards on industrial truck energy efficiency and electromagnetic compatibility, compressing equipment replacement cycles. Qingdao and Tianjin port operators accelerate electric rubber-tired gantry crane orders with battery-swapping specifications to satisfy SAMR dual carbon procurement thresholds.
Japan
METI-backed semiconductor fabrication expansion generates specialized demand for ultra-clean automated storage and retrieval systems with particulate contamination controls. JIS certification governs crane safety and automated system reliability across Toyota City and Nagoya industrial corridors. Kanto region electronics manufacturers prioritize fast-charge lithium-ion forklift compatibility to maintain two-shift operational continuity.
India
PLI scheme incentives stimulate capital expenditure on automated guided vehicles and conveyor systems in Gujarat and Tamil Nadu industrial corridors. BIS mandates equipment testing for construction and mining material handlers under CEA electrical safety frameworks. Bangalore third-party logistics providers shift to equipment-as-a-service models with per-robot monthly pricing as warehouse tenancy cycles compress below five years.
Vietnam
Samsung and Foxconn supplier park development around Bac Ninh and Hai Phong creates greenfield demand for integrated conveyor and robotic palletizing systems without legacy infrastructure displacement. National industrial zone policies favor automated material handling in export-oriented manufacturing. Northern industrial corridor concentration enables trial-to-production deployment cycles under ninety days for vision-guided mobile robots.
South Korea
Hyundai Motor's Ulsan complex and Hwaseong electronics assembly lines deploy just-in-time conveyor networks and autonomous tugger trains linking production stations. MFDS alignment with METI energy-efficiency incentives favors certified low-carbon automated system vendors. Busan industrial zone crane procurement concentrates in state-backed port automation tenders with electric drive specifications.
Asia Pacific Material Handling Equipment Market Key Industry Players
Concentration sits with diversified industrial conglomerates and specialized automation providers rather than pure-play forklift manufacturers. Japanese and German engineering groups anchor premium-tier automated storage and retrieval systems through integrated software-hardware portfolios. Chinese construction equipment specialists dominate heavy-lift port crane procurement via state-backed infrastructure tenders. Korean electronics-focused material handling vendors occupy mid-market conveyor and mobile robot segments. Strategic moves center on battery-swapping infrastructure partnerships and equipment-as-a-service contracting models that displace traditional capital sales.
Among China-based equipment specialists, XCMG Construction Machinery Co., Ltd. and Noblelift Intelligent Equipment Co., Ltd. occupy positions in heavy-lift and industrial truck categories respectively. Japanese automation specialists DAIFUKU Co. Ltd. and Murata Machinery Ltd. exemplify integrated system providers serving semiconductor cleanroom and airport baggage handling applications. Geekplus Technology Co., Ltd. represents the mobile robot specialist archetype competing with established forklift networks in e-commerce fulfillment deployments.
| Leading Market Players |
|---|
| XCMG Construction Machinery Co., Ltd. |
| Mitsubishi Logisnext Co., Ltd. |
| DAIFUKU Co. Ltd. |
| Jungheinrich AG |
| KION Group AG |
| Murata Machinery Ltd. |
| Noblelift Intelligent Equipment Co. Ltd. |
| Geekplus Technology Co., Ltd. |
| Toyota Industries Corporation |
| Others |
Cost & Logistics Intelligence
China's SAMR dual carbon procurement thresholds gate both supplier qualification and price differentiation simultaneously, compressing margins for diesel equipment makers while opening premium windows for certified electric-drive vendors serving Qingdao and Tianjin port automation tenders. Equipment-as-a-service contracting is displacing capital purchase models among third-party logistics providers, bundling maintenance and software updates into per-robot monthly pricing that reshapes lifetime value calculations.
Pricing Analysis
Configured-to-order pricing for automated guided vehicles with battery-swapping compatibility commands spreads over standard forklift configurations. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified cleanroom systems from GB-compliant industrial trucks and manual pallet jacks. Cost compression in mid-tier electric drives is intensifying because lithium-ion cathode material processing concentrates in Fujian and Sichuan provinces. Third-party logistics providers in India and Southeast Asia exhibit highest price sensitivity; semiconductor fabs in Japan's Kanto region show lowest.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell manufacturing and automated vehicle component fabrication for Asia Pacific material handling equipment. Cathode material processing draws from nickel laterite deposits in Indonesia and cobalt concentrates from the DRC. Single-source vulnerability in rare earth magnet supply from China's Inner Mongolia region threatens permanent-motor production for electric drives. Distribution runs through authorized dealer networks for industrial trucks and direct OEM relationships for port crane systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers are expanding faster than hardware sales as equipment-as-a-service contracts bundle predictive maintenance, fleet optimization analytics, and software updates into recurring per-robot pricing across Bangalore and Jakarta urban logistics networks.
For Market Incumbents: Shield installed base relationships by embedding battery-swapping infrastructure partnerships that raise switching costs for automated guided vehicle fleets. Deepen backward integration into lithium-ion pack assembly to offset cathode material cost volatility from Fujian and Sichuan supply concentration. Accelerate JIS and GB certification investments to maintain technical disqualification barriers against non-compliant entrants in semiconductor cleanroom and port automation segments. For New Entrants and Emerging Players: Lead with vision-guided mobile robot platforms targeting Vietnam's northern industrial zones around Bac Ninh and Hai Phong, where greenfield deployment avoids legacy warehouse management system integration friction. Prioritize ninety-day trial-to-production velocity as the go-to-market angle against established forklift networks. Target food processing corridors in Maharashtra and Gujarat with stainless steel conveyor configurations compliant with FSSAI mandates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed forklift rental networks in Southeast Asia facing fleet electrification capital demands. Long-term viability hinges on conversion to equipment-as-a-service models with software-enabled fleet management. Watch for SAMR procurement threshold expansions beyond current port and airport equipment categories as the inflection signal for accelerated replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Swapping Infrastructure Partnership | Enables 24-hour continuous operation models in Hangzhou e-commerce fulfillment centers. |
| Equipment-as-a-Service Platform Launch | Captures recurring revenue from Bangalore logistics providers with sub-five-year warehouse tenancy cycles. |
| JIS Cleanroom Certification Investment | Opens METI-backed semiconductor fabrication expansion opportunities in Toyota City corridors. |
| Backward Integration into Lithium-Ion Packs | Reduces exposure to cathode material volatility from China's Fujian province concentration. |
| Vision-Guided Mobile Robot Product Line | Fragments vendor hierarchies by enabling electronics contract manufacturers to enter warehouse automation. |
Research Approach
Two parallel data streams informed the analysis: structured interviews with warehouse operations directors, fleet managers at third-party logistics providers, port automation engineers, and aftermarket service heads; and secondary validation through customs trade records, MIIT GB standard filings, METI procurement disclosure databases, and SEC 10-K equipment segment disclosures. Bottom-up equipment shipment tallies and top-down industrial capital expenditure estimates were triangulated across the analysis window.
Across the modeling period, forecasts were constructed by segmenting equipment demand across product type, technology architecture, application intensity, and end-user procurement sophistication. CAGRs were derived from regression analysis against industrial production indices, e-commerce fulfillment center build-out pipelines, and port container throughput trajectories. Battery chemistry cost curves and electromagnetic compatibility certification timelines fed directly into automated guided vehicle adoption modeling.
Forecasts assume regulatory continuity in China's SAMR procurement rules, Japan's METI energy-efficiency incentives, and India's PLI scheme structures; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in dual carbon threshold enforcement, lithium-ion supply contract renegotiations, and warehouse management system middleware compatibility breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Surface Contact Wire Rope Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
High-Precision Gear Reducer Market
Material Handling Equipment
Loader Bucket Attachments Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Global Forklift Market
Material Handling Equipment
North America Utility Locator Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Slag Handling Equipment Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Rotary Indexer Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Global Elevator Market
Material Handling Equipment
Asia-Pacific Forklift Rental Market
Material Handling Equipment
Container Handling Equipment Market