
 Port Equipment Market | 2026-2036
Port Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Port Equipment Market Analysis
Terminal operators is rotating share toward automated equipment procurement as shipping lines defer capital commitments amid fleet overcapacity. Konecranes Oyj leverages its automation software stack to anchor long-term service contracts at major transshipment hubs. ZPMC sustains manufacturing scale through captive steel fabrication and integrated ship-to-shore crane delivery. Liebherr Group differentiates via custom engineering for heavy-lift applications in Arctic and tropical environments.
Port equipment encompasses mobile and fixed machinery engineered for cargo handling, vessel servicing, and yard logistics at maritime and inland terminals, typically rated by lifting capacity, outreach meters, and twenty-foot equivalent unit throughput per hour. Crane systems dominate capital allocation due to super-post-Panamax vessel compatibility requirements, while automated technology segments capture the fastest expansion as labor costs and safety standards tighten. Electric propulsion variants are gaining share in medium-capacity forklifts and stackers where battery energy density now supports continuous shift operations without thermal exhaust constraints.
Federal Maritime Commission oversight in the United States shapes tariff structures and equipment leasing terms at gateway ports, while EU Green Deal emissions benchmarks enforced by national regulators mandate shore power connectivity and electrified yard fleets. China's MIIT issues GB standards for crane structural integrity and operator cabin ergonomics that determine domestic certification and export eligibility. Stakeholders must monitor how divergent carbon accounting rules across the European Union, United States, and China reshape total cost of ownership calculations for electrified versus conventional equipment portfolios.
Market Dynamics
Terminal operators are consolidating procurement around automated stacking systems as vessel dimensions breach 24,000 TEU capacity thresholds, forcing yard reconfiguration and crane replacement cycles at major transshipment hubs.
Growth Catalysts
- EU Green Deal emissions mandates:Shore power connectivity requirements and electrified yard fleet quotas are accelerating equipment replacement at Rotterdam, Hamburg, and Antwerp terminals.
- Super-post-Panamax vessel compatibility:Shipping lines deploying 400-meter-plus vessels are compelling port authorities to extend crane outreach and lifting height specifications.
- State-backed port modernization in China:Central government infrastructure allocations through MIIT are driving bulk orders for automated guided vehicles and remote-operated gantry systems.
Market Restraints
- Steel price volatility:Crane structural components consume high-grade steel alloys whose input costs fluctuate with commodity markets, compressing manufacturer margins.
- Specialized fabrication concentration:Heavy-lift crane production clusters in China and Germany, creating geographic supply risk and extended lead times for non-captive buyers.
- Lithium-ion energy density ceilings:Battery chemistry limitations restrict continuous operation of electric reach stackers beyond single-shift duty cycles without mid-shift charging infrastructure.
Strategic Opportunities
- Retrofit automation kits:Software and sensor packages that convert manual ship-to-shore cranes to semi-automated operation are opening service revenue streams at mature European terminals.
- Arctic port infrastructure:Ice-class crane specifications for Russia's Northern Sea Route and Canadian Arctic gateways represent underserved engineering demand.
- Digital twin integration:Convergence of IoT sensor networks with predictive maintenance platforms is creating differentiated service contract offerings.
Industry Challenges
- Certification timeline compression:EU machinery directive compliance and GB standard alignment for Chinese exports are extending type-approval cycles, delaying revenue recognition.
- Legacy system interoperability:Terminal operating software from multiple vendors creates integration friction when deploying unified automation architectures.
- Remote operator certification gaps:Automated crane control rooms require specialized training protocols that existing maritime academies have not standardized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Port Equipment Market |
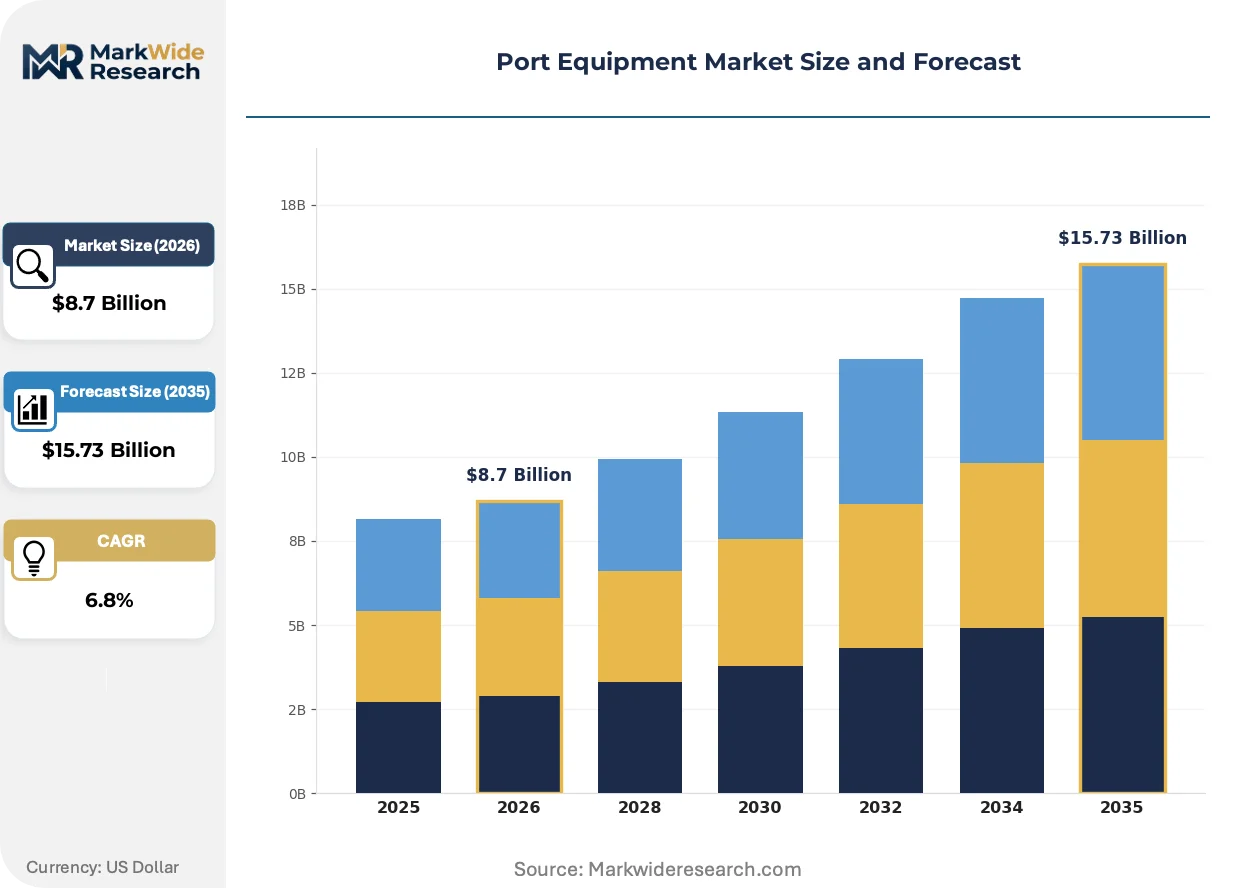
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Crane, Stacker, Forklift, Conveyor Capacity: Low Capacity, Medium Capacity, High Capacity, Heavy-Duty Technology: Electric, Hydraulic, Pneumatic, Automated End User: Shipping Lines, Freight Forwarders, Ports Authorities, Terminal Operators |
| Companies Covered | Shanghai Zhenhua Heavy Industries (ZPMC), Terex Corporation, Konecranes Oyj, Hyster-Yale Materials Handling, Inc., TTS Group ASA, Cargotec Corporation, Sany Heavy Industry Co., Ltd., Mitsubishi Logisnext Co., Ltd., Liebherr Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Port Equipment Market Emerging Trajectories
Automation architectures are displacing conventional manual operating models across cargo handling workflows, with sensor fusion and machine vision systems enabling yard equipment to function without direct human intervention in controlled environments.
Hybrid diesel-electric propulsion is displacing pure mechanical drive systems in rubber-tired gantry cranes. Mediterranean and Southeast Asian terminal operators are retrofitting existing fleets to reduce fuel consumption and comply with port authority emissions tariffs. The technology is compressing total cost of ownership calculations for mid-life crane assets that would otherwise face premature replacement.
China's MIIT GB standards for crane structural integrity and operator cabin ergonomics are tightening certification requirements for both domestic deployment and export eligibility. Manufacturers must now submit finite element analysis documentation and fatigue testing protocols that exceed previous self-certification norms. European suppliers with established testing infrastructure are accelerating compliance documentation to maintain access to Chinese procurement tenders.
Buying patterns are consolidating around performance-based service agreements rather than discrete equipment transactions. Major transshipment operators in Singapore and the UAE are unbundling maintenance, spare parts, and software updates into multi-year contracts with uptime guarantees. This shift compresses capital expenditure recognition for manufacturers while extending revenue visibility through contractual service obligations.
Port Equipment Market Segmentation
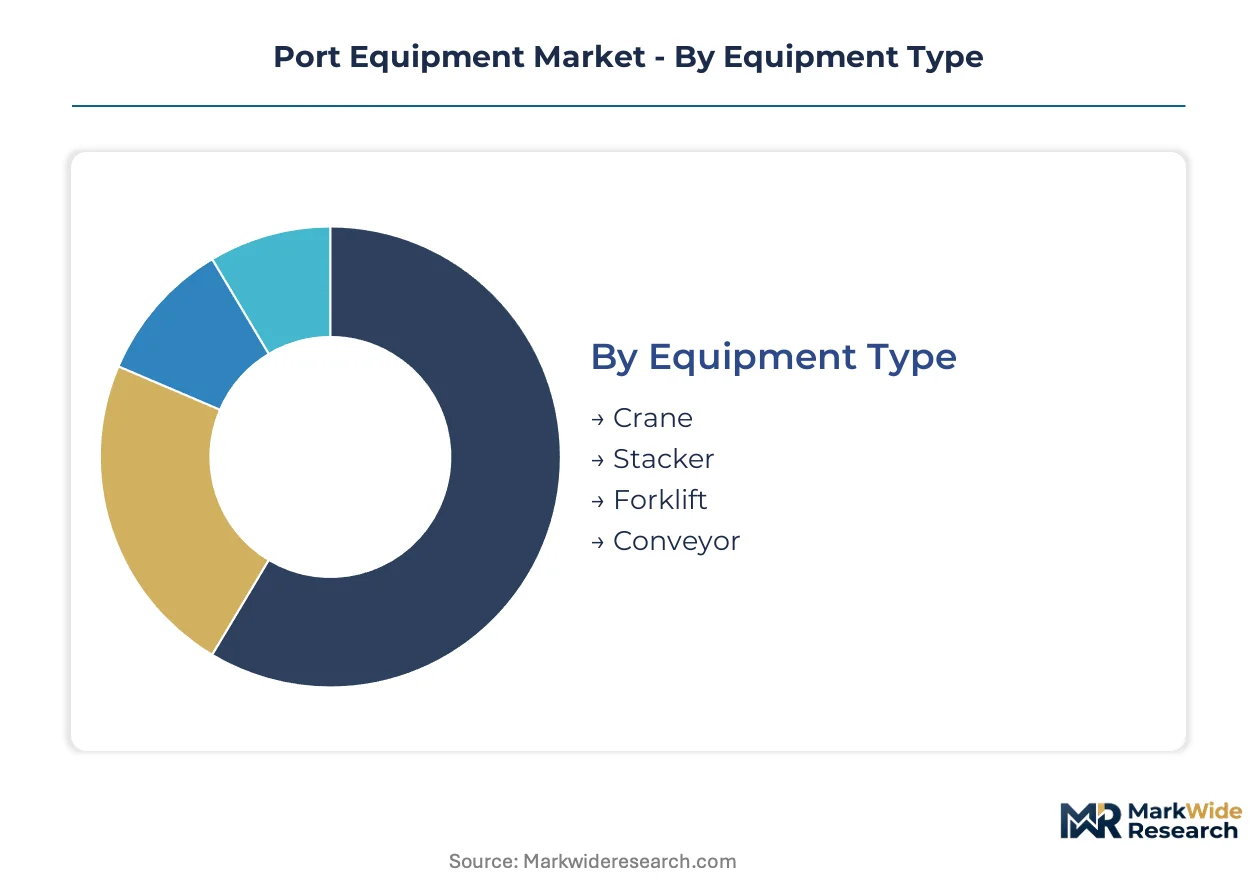
Segmentation in port equipment reveals how capital allocation splits between vessel-facing crane systems and yard logistics machinery. Understanding these divisions helps manufacturers align R&D spending with where procurement budgets are concentrating across automation retrofits and electrification mandates.
Equipment Type:
Margin pools concentrate in crane systems where super-post-Panamax compatibility requirements sustain premium pricing, while yard equipment segments compete on operational efficiency metrics.
- Crane:Ship-to-shore and gantry systems engineered for 400-meter-plus vessel outreach specifications dominate capital expenditure at transshipment hubs. Rotterdam, Singapore, and Shanghai port authorities are mandating extended lifting heights as container volumes climb.
- Stacker:Rubber-tired and rail-mounted variants handle yard container positioning with automated stacking cranes capturing replacement cycles at European terminals facing EU Green Deal labor cost pressures.
- Forklift:Medium-capacity electric models with lithium-ion battery packs are displacing diesel equivalents at Hamburg and Antwerp facilities.
- Conveyor:Bulk material handling systems serve grain and mineral terminals at Dalian and Newcastle harbors.
Crane systems hold installed capacity. Automated stackers are rotating up the share rankings.
Capacity:
Volume concentration sits with medium-capacity equipment where electrification economics first reached parity with diesel propulsion.
- Medium Capacity:Electric forklifts and reach stackers rated for 20-40 tonne loads are penetrating Mediterranean terminals where shift patterns accommodate battery charging windows. Barcelona and Valencia operators are consolidating procurement around this tier.
- High Capacity:Ship-to-shore cranes exceeding 65 tonne lifting ratings serve 24,000 TEU vessel calls at Busan and Jebel Ali, requiring structural reinforcement of quay walls.
- Low Capacity:Light yard tractors and utility vehicles handle inter-terminal transfers at secondary harbors.
- Heavy-Duty:Specialized bulk unloaders and project cargo gantries serve Arctic port development at Murmansk and Churchill.
Medium-capacity units hold installed capacity. High-capacity systems are rotating up the share rankings.
Technology:
Customer type determines technology selection with terminal operators prioritizing automation while freight forwarders favor proven electric platforms.
- Automated:Sensor fusion and machine vision architectures enable remote-operated gantry systems at Singapore and Rotterdam without direct human intervention in container yards. Terminal operators are unbundling maintenance into multi-year performance contracts.
- Electric:Battery-electric propulsion variants eliminate exhaust constraints at Hamburg and Los Angeles terminals facing emissions tariffs. Shore power connectivity requirements are accelerating fleet conversion timelines.
- Hydraulic:Conventional fluid power systems persist in heavy-lift applications where electrification energy density remains insufficient.
- Pneumatic:Compressed air systems serve specialized bulk handling at grain terminals.
Electric systems hold installed capacity. Automated platforms are rotating up the share rankings.
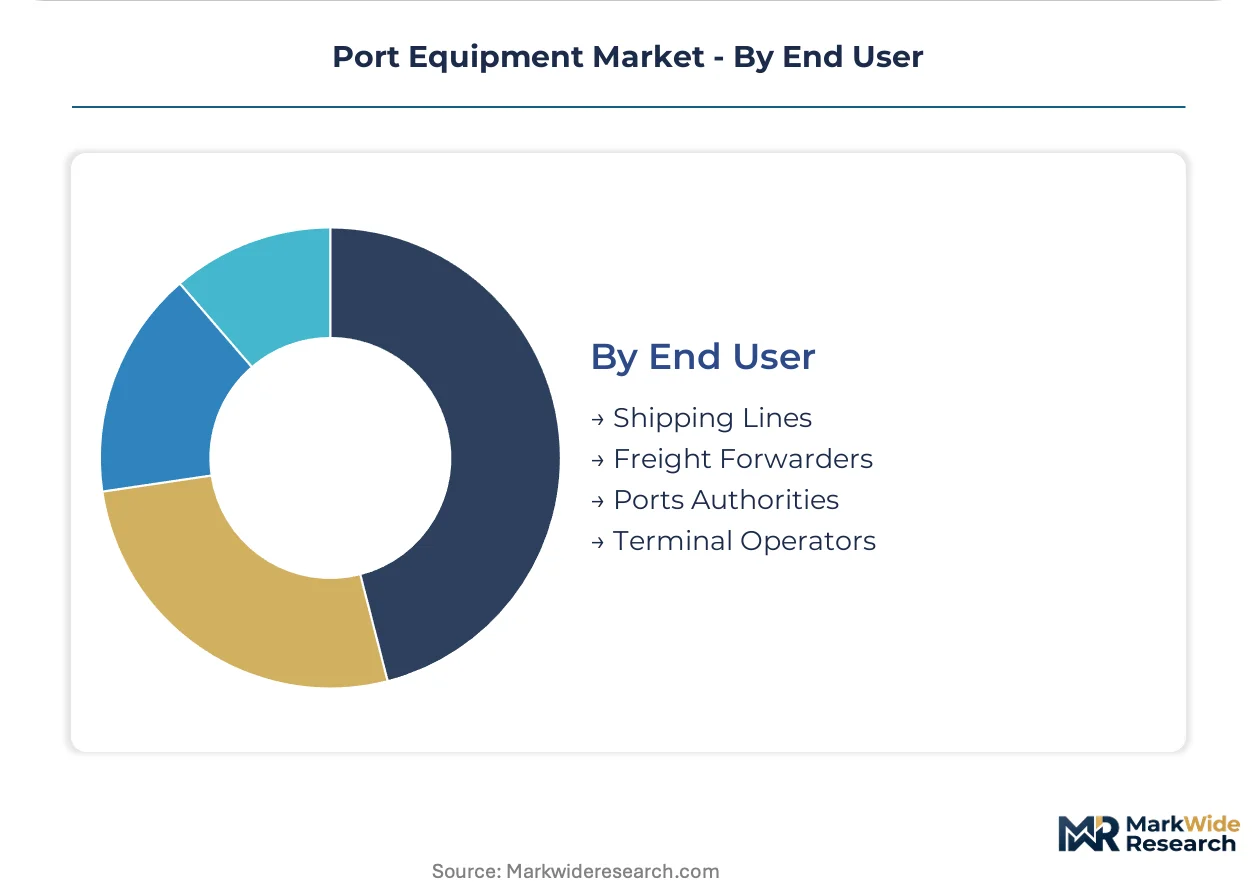
End User:
Supply concentration aligns with terminal operator consolidation as shipping lines defer capital commitments amid fleet overcapacity.
- Terminal Operators:PSA International and DP World are driving automated stacking crane procurement at Jebel Ali and Singapore with performance-based service agreements replacing discrete equipment purchases.
- Ports Authorities:Public harbor administrations at Los Angeles and Long Beach are mandating shore power infrastructure and electrified yard fleet quotas through tariff structures.
- Shipping Lines:Maersk and MSC are deferring dedicated terminal equipment investments.
- Freight Forwarders:Logistics intermediaries lease mobile handling equipment at secondary facilities.
Terminal operators hold installed capacity. Ports authorities are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Terminal operators in China, Germany, the United States, the Netherlands, and Singapore concentrate procurement budgets for automated stacking systems and electrified yard fleets. State-backed infrastructure programs and emissions mandates are reshaping equipment replacement cycles across these harbors.
China
Central government infrastructure allocations through MIIT are driving bulk orders for automated guided vehicles and remote-operated gantry systems at Shanghai and Ningbo-Zhoushan. GB standards for crane structural integrity are tightening certification requirements for domestic deployment and export eligibility. Yangtze River Delta terminals are consolidating procurement around super-post-Panamax compatible ship-to-shore cranes.
Germany
Hamburg and Bremerhaven terminal operators are retrofitting rubber-tired gantry cranes with hybrid diesel-electric propulsion to comply with EU Green Deal emissions benchmarks. The KBA enforces machinery directive compliance for automated crane control systems entering service. North Rhine-Westphalia harbors are mandating shore power connectivity for vessel servicing equipment.
United States
Los Angeles and Long Beach port authorities are enforcing electrified yard fleet quotas through tariff structures shaped by Federal Maritime Commission oversight. EPA emissions standards are accelerating battery-electric forklift deployment at Pacific gateway terminals. California's CARB regulations are compressing payback calculations for diesel-to-electric conversions.
Netherlands
Rotterdam terminal operators are unbundling maintenance and software updates into multi-year performance contracts for automated stacking cranes. EU Green Deal mandates require shore power infrastructure and electrified yard equipment at Maasvlakte facilities. Randstad port clusters are extending crane outreach specifications to accommodate 24,000 TEU vessel calls.
Singapore
PSA International is driving procurement of sensor-fusion-enabled yard equipment without direct human intervention in container operations. The Maritime and Port Authority of Singapore enforces safety standards for remote crane control rooms. Tuas mega-port development is concentrating demand for integrated automation architectures.
Port Equipment Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive steel fabrication and integrated crane delivery capabilities. The vendor base clusters around three strategic tiers: automation software specialists anchoring long-term service contracts, scale-driven manufacturers with backward integration into structural components, and custom engineering houses serving heavy-lift applications. Competitive moves center on retrofit automation kit development and performance-based service agreement expansion.
Within the automation software tier, Konecranes Oyj and Cargotec Corporation represent the service-contract anchoring archetype. ZPMC and Sany Heavy Industry Co., Ltd. exemplify scale-driven manufacturers with integrated supply chains. Liebherr Group occupies a position among custom engineering specialists addressing Arctic and tropical environment specifications.
| Leading Market Players |
|---|
| Shanghai Zhenhua Heavy Industries (ZPMC) |
| Terex Corporation |
| Konecranes Oyj |
| Hyster-Yale Materials Handling, Inc. |
| TTS Group ASA |
| Cargotec Corporation |
| Sany Heavy Industry Co., Ltd. |
| Mitsubishi Logisnext Co., Ltd. |
| Liebherr Group |
| Others |
Supply Flow & Price Mechanics
EU machinery directive compliance gates both supplier qualification and price differentiation in European procurement, forcing manufacturers to absorb certification costs that separate certified from non-certified equipment tiers. Terminal operators at Rotterdam and Hamburg now bundle compliance documentation into total cost of ownership calculations, compressing margins for unprepared vendors while rewarding pre-certified suppliers with contract premiums.
Pricing Analysis
Cost-plus contracts indexed to steel alloy price indices dominate crane system procurement at major transshipment hubs. Price differentiation rests on automation software integration depth and GB standard certification tier for Chinese export eligibility. Pricing pressure stems from state-backed procurement consolidation at Shanghai and Ningbo-Zhoushan, where volume aggregation squeezes per-unit margins. Freight forwarders leasing mobile equipment exhibit highest price sensitivity; terminal operators with performance-based service agreements prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Strategic stockpiling of high-grade steel alloys characterizes manufacturer inventory strategy given commodity price volatility, contrasting with just-in-time component sourcing for automation electronics. Production concentrates in China, Germany, and South Korea, with crane structural fabrication anchored in Yangtze River Delta facilities. Supply chains draw from specialized steel alloys, lithium-ion battery packs, and sensor fusion modules. Single-source vulnerability persists in precision gearbox manufacturing. Distribution runs through port authority tender processes and terminal operator direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified remote crane operators and finite element analysis documentation capabilities constrains manufacturer expansion, creating defensive moats for incumbents with established testing infrastructure.
For Market Incumbents: Shield service revenue streams by anchoring multi-year performance contracts with uptime guarantees at Singapore and Rotterdam terminals. Accelerate GB standard compliance documentation to maintain Chinese tender access against domestic challengers. Prioritize automation software stack deepening over hardware margin defense. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany opens European retrofit automation kit segments underserved by legacy crane manufacturers. Target Arctic port infrastructure specifications at Murmansk and Churchill where engineering customization requirements deter scale players. Pursue joint development agreements with regional steel fabricators to bypass captive supply advantages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated stacking crane segments as software development costs displace pure hardware manufacturing. Five-to-ten year viability favors manufacturers with backward integration into structural steel and integrated ship-to-shore delivery capabilities. Monitor lithium-ion energy density breakthroughs as inflection signal for electric reach stacker market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Automation Kit Development | Software and sensor packages convert manual cranes at European terminals, opening recurring service revenue. |
| GB Standard Compliance Acceleration | Finite element analysis documentation maintains Chinese tender access against domestic certification advantages. |
| Arctic Engineering Specialization | Ice-class crane specifications for Northern Sea Route ports create underserved premium pricing tiers. |
| Performance-Based Service Agreements | Uptime guarantees at PSA International and DP World terminals extend revenue visibility beyond equipment sales. |
| Hybrid Propulsion Retrofit Programs | Diesel-electric conversions at Mediterranean terminals compress payback periods for mid-life crane assets. |
Methodological Framework
A spread of perspectives from terminal operations directors, port authority procurement officers, crane manufacturer engineering leads, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined with secondary validation from customs trade records, EU machinery directive filings, MIIT GB standard publications, and SEC equipment manufacturer disclosures. Bottom-up equipment shipment tracking and top-down port infrastructure investment analysis provided triangulation.
Segmentation dimensions modeled across the projection horizon include equipment type, capacity tier, technology platform, and end-user category, with vessel size compatibility requirements as an additional port-specific dimension. CAGRs were derived from installed base replacement cycles and new automation deployment trajectories. Forecast inputs incorporated steel price index projections and shore power infrastructure rollout schedules at EU and US gateway ports.
The analysis sits within stated boundaries; outcomes outside sustained state-backed infrastructure allocations in China or accelerated EU Green Deal enforcement timelines would require recalibration. Forecasts reflect assumptions about lithium-ion energy density evolution and automation software interoperability standards. Revision becomes warranted when battery chemistry breakthroughs cross commercial viability thresholds for heavy-duty continuous operation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Log Loaders Market
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Gas Connectors and Gas Hoses Market
Material Handling Equipment
Global Conveyor System Market
Material Handling Equipment
Decoiler Machine Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Overhead Hoist Transport (OHT) Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Vertical Platform Lift Market
Material Handling Equipment
Middle East Conveyor Belts Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Jaw Crushers Market