
 Pipe Belt Conveyor Market | 2026-2036
Pipe Belt Conveyor Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Belt Conveyor Market Insights
Mining transport is restructuring demand patterns across extraction facilities worldwide, with operators favoring enclosed systems that eliminate spillage and reduce environmental exposure. Continental AG leverages its polymer expertise to dominate high-tensile steel cord belt supply for deep-pit operations. BEUMER Group anchors its position through integrated system design spanning fixed and modular installations. Metso competes by extending its minerals processing franchise into downstream bulk handling infrastructure.
A pipe belt conveyor forms a fully enclosed tubular cross-section by overlapping belt edges around rollers, typically achieving diameters of 150 to 850 millimeters and conveying capacities exceeding 10,000 tons per hour across distances surpassing 20 kilometers. This geometry prevents material loss, protects payloads from weather, and permits steep inclines up to 30 degrees, serving primarily mining transport and bulk material handling in environmentally sensitive or space-constrained sites. Steel cord belt configurations command premium positioning due to their tensile strength and extended service intervals in abrasive ore service. Fixed installation types remain the mature revenue base, while modular setup designs represent the fastest-expanding segment as remote mining camps prioritize rapid redeployment and reduced civil works.
OSHA dust exposure limits and EPA particulate matter standards in the United States compel cement manufacturing and power generation facilities to adopt enclosed conveying, while REACH compliance in Europe restricts certain rubber plasticizers and accelerates belt formulation changes. China's MEE enforces stricter ambient air quality benchmarks in industrial clusters, directly stimulating pipe belt retrofits across Shanxi and Inner Mongolia coal corridors. Stakeholders must monitor evolving polymer regulations and assess captive fabrication capacity against supply chain exposure to specialized steel cord and rubber compound sourcing.
Market Dynamics
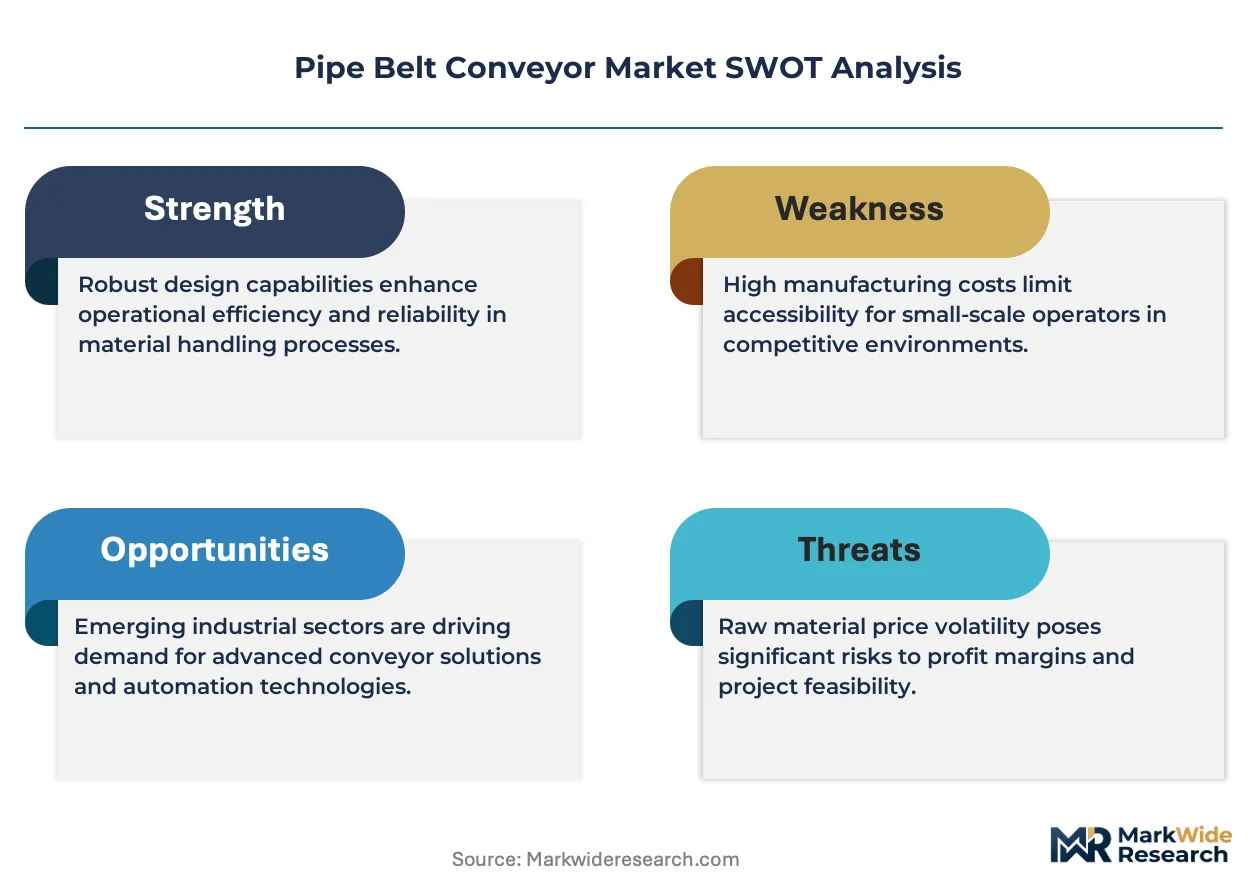
Mining operators are replacing open trough conveyors with enclosed pipe belt systems to meet dust-emission mandates and reduce material loss across extraction sites. This equipment shift is restructuring capital allocation priorities in bulk material handling.
Growth Catalysts
- EU Industrial Emissions Directive:Operators across Germany, Poland, and Spain must retrofit open systems with enclosed pipe belt designs to comply with particulate matter limits, accelerating replacement cycles.
- Steel cord belt technology:High-tensile configurations extend service intervals in abrasive ore applications, reducing downtime costs for deep-pit copper and iron ore operations.
- Australia's Pilbara corridor:Iron ore handlers prioritize spillage elimination and environmental compliance, concentrating demand for 300-850 millimeter diameter systems.
Market Restraints
- Specialized rubber compound sourcing:REACH restrictions on certain plasticizers limit European formulation options and extend qualification timelines for new belt suppliers.
- Steel cord supply concentration:Premium steel cord reinforcement depends on concentrated Asian metallurgical supply, exposing procurement to raw material volatility.
- Technical limitation in sharp curves:Pipe belt geometry requires minimum bend radii of 300-500 times belt diameter, constraining retrofit options at legacy sites with tight footprints.
Strategic Opportunities
- Modular installation designs:Remote mining camps in Canada's Athabasca oil sands and Chile's Atacama copper belt prioritize rapid redeployment and reduced civil works.
- China's MEE ambient air quality benchmarks:Stricter enforcement across Shanxi and Inner Mongolia coal corridors stimulates retrofit demand for enclosed conveying systems.
- Digital monitoring convergence:Integration of IoT sensors with predictive maintenance platforms creates service revenue streams beyond equipment supply.
Industry Challenges
- Specialized belting technician shortage:Splicing and vulcanizing steel cord pipe belts requires certified technicians, with training programs lagging installation demand in remote mining regions.
- Legacy system integration complexity:Retrofitting pipe belts into existing crushing and stacking circuits demands custom transition chutes and tensioning systems, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Belt Conveyor Market |
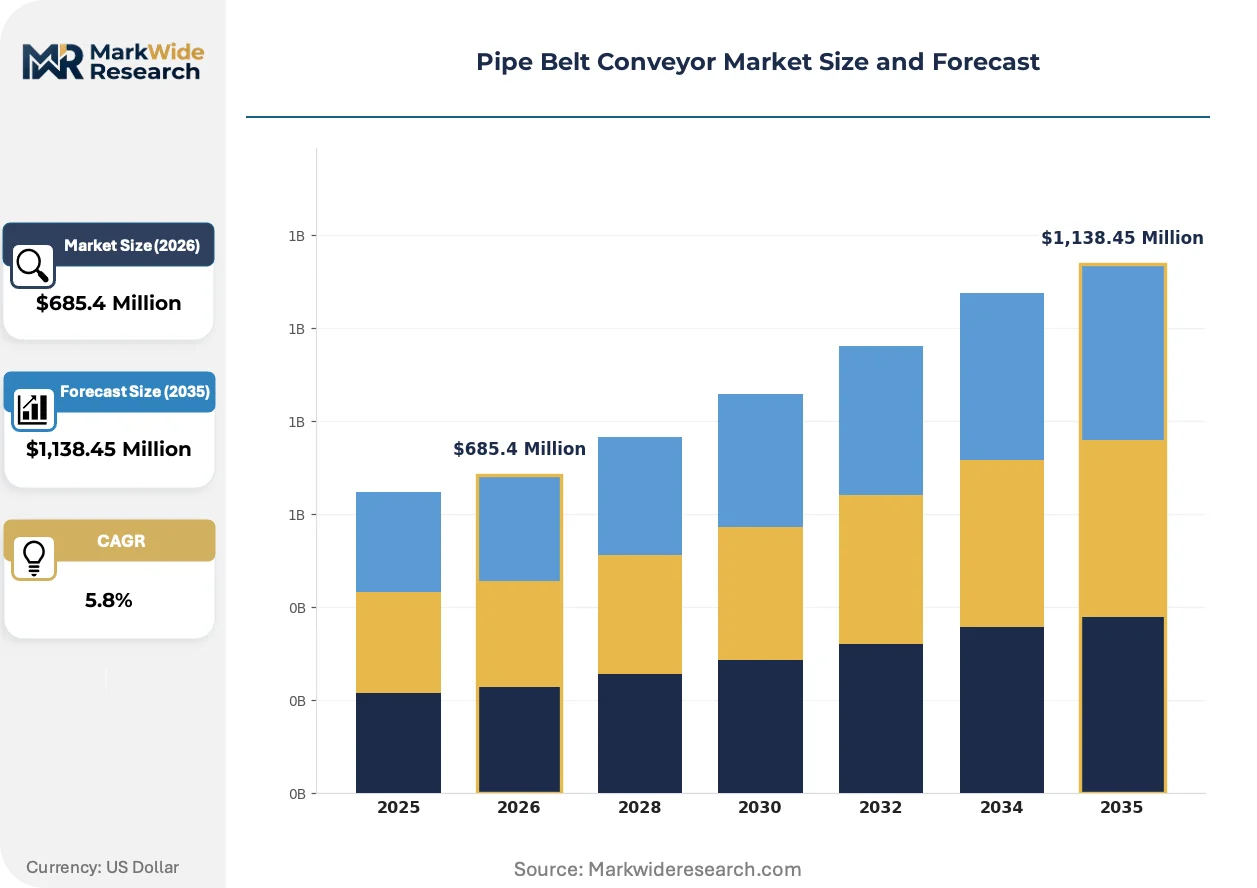
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Belt, Modular Belt, Cleated Belt, Steel Cord Belt, PVC Belt Application: Mining Transport, Bulk Material Handling, Cement Manufacturing, Power Generation, Grain Handling Installation Type: Fixed Setup, Portable Setup, Modular Setup, Telescopic Setup End User Industry: Extraction Facilities, Building Materials Plants, Energy Producers, Agricultural Processing Units |
| Companies Covered | Continental AG, FLSmidth A/S, Metso, BEUMER Group, Fenner Dunlop, Sempertrans, Bridgestone Corporation, ABB, Fives, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Belt Conveyor Market Trends and Innovations
Equipment manufacturers are embedding sensing and automation into pipe belt systems while reformulating compounds to meet evolving chemical regulations. These shifts are compressing maintenance intervals and expanding addressable applications.
Steel cord reinforcement with specialized zinc-coated wires is consolidating market share in high-abrasion mining service. Copper and iron ore operators in Chile and Western Australia specify these configurations for 20+ kilometer overland routes. The technology is consolidating supplier margins by extending replacement cycles and reducing total cost of ownership calculations against fabric alternatives.
REACH compliance deadlines for rubber plasticizers are forcing compound reformulations across European supply chains. ECHA restrictions on specific accelerators and softeners are accelerating qualification of bio-based and non-aromatic alternatives. Belt manufacturers serving EU cement and power generation facilities are restructuring formulation R&D to maintain certification continuity.
Service contract unbundling is fragmenting traditional procurement relationships. Mining operators in Brazil's Carajás iron ore district and South Africa's platinum belt are separating equipment purchase from installation and maintenance, creating openings for specialized regional service providers. This pattern is most visible in jurisdictions with mature mining codes and established contractor ecosystems.
Pipe Belt Conveyor Market Segmentation
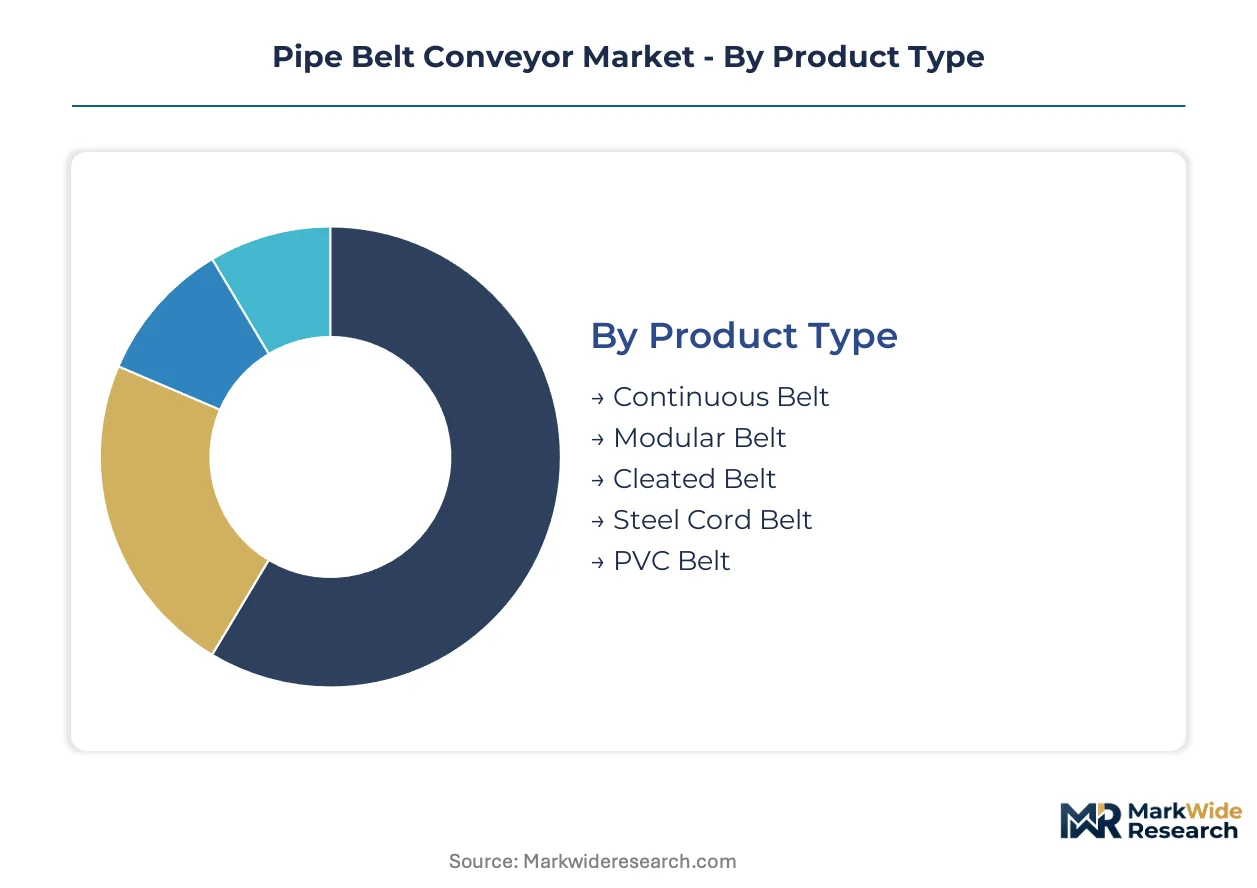
Pipe belt conveyor procurement varies sharply by material specification, operational intensity, and deployment flexibility. Technology selection determines capital outlay, maintenance burden, and regulatory compliance exposure across mining and industrial installations.
Product Type:
Material composition and tensile architecture define performance limits in abrasive service environments.
- Steel Cord Belt:Zinc-coated steel cord reinforcement delivers tensile strength exceeding 10,000 N/mm for 20+ kilometer overland routes. Pilbara iron ore operators specify these configurations to minimize replacement cycles in high-abrasion copper and iron ore transport.
- Continuous Belt:Homogeneous rubber construction without mechanical joints suits moderate-duty applications requiring seamless operation. Cement plants in Germany and Poland favor continuous designs for dust-tight compliance under EU Industrial Emissions Directive mandates.
- Modular Belt:Interlocking plastic or metal segments enable rapid section replacement and directional flexibility.
- Cleated Belt:Molded longitudinal ribs prevent rollback on inclines exceeding 20 degrees.
- PVC Belt:Thermoplastic construction resists moisture and chemical exposure in grain handling and agricultural processing.
Mature deployment sits with continuous belt configurations. Newer deployment is concentrated in steel cord systems.
Application:
End-use intensity shapes specification requirements and replacement frequency.
- Mining Transport:Deep-pit extraction demands 300-850 millimeter diameter systems with 10,000+ ton per hour capacity. Shanxi coal corridor operators prioritize spillage elimination and MEE air quality compliance through enclosed tubular geometry.
- Bulk Material Handling:Multi-commodity terminals require rapid belt changeout and cross-contamination prevention. Australia's port infrastructure operators specify pipe belts to protect sensitive mineral concentrates from moisture and wind loss.
- Cement Manufacturing:Clinker and raw meal conveying demands heat-resistant compounds and dust containment.
- Power Generation:Coal and biomass feed systems prioritize fire-resistant specifications and continuous operation reliability.
- Grain Handling:Food-grade belting with moisture barriers protects agricultural commodities during extended transport.
Volume concentration favors mining transport. Steepest expansion trajectory appears in cement manufacturing retrofits.
Installation Type:
Capital commitment and redeployment flexibility create distinct procurement segments.
- Fixed Setup:Permanent foundations with engineered tensioning systems dominate established mining districts. Germany's lignite belt and Spain's limestone quarries deploy fixed installations for decades-long service horizons.
- Modular Setup:Prefabricated sections with minimal civil works enable rapid relocation. Canada's Athabasca oil sands and Chile's Atacama copper belt prioritize modular designs for camp mobility and reduced environmental disturbance.
- Portable Setup:Skid-mounted or trailer-based systems serve temporary stockpiling and construction material handling.
- Telescopic Setup:Extendable discharge booms adapt to variable stacking geometries and vessel loading configurations.
Revenue weight rests with fixed installations. Share expansion is fastest in modular configurations.
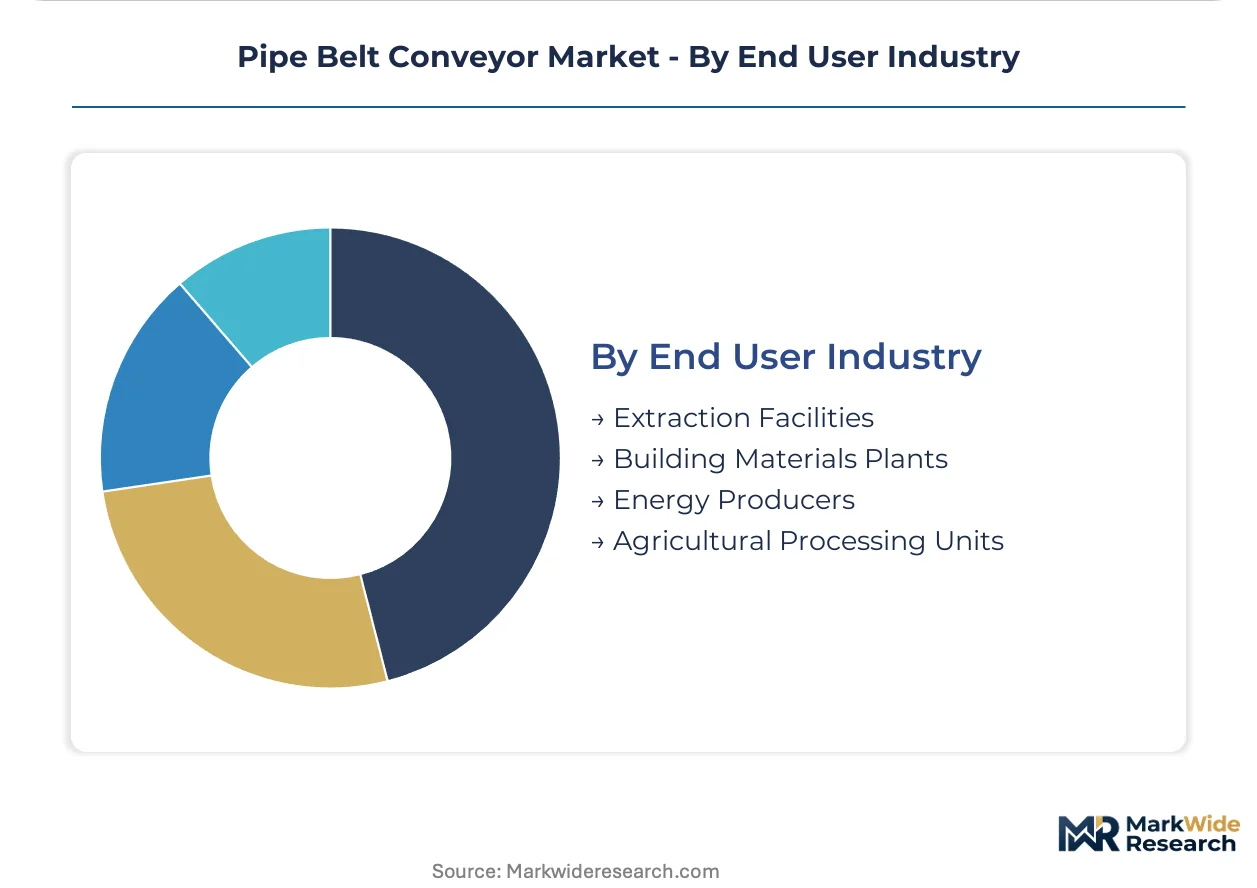
End User Industry:
Operational scale and regulatory exposure differentiate buyer requirements.
- Extraction Facilities:Open-pit and underground mining operations specify heavy-duty steel cord configurations for 24-hour continuous duty. Western Australian iron ore handlers demand 30-degree incline capability and weatherproof enclosure.
- Building Materials Plants:Cement and aggregate producers balance dust containment with abrasive material wear. Polish and Spanish facilities retrofit pipe belts to meet EU particulate matter limits while handling limestone and clinker.
- Energy Producers:Coal-fired and biomass power stations require fire-resistant belting and reliable fuel feed continuity.
- Agricultural Processing Units:Grain elevators and oilseed processors prioritize food-grade certification and moisture protection.
Procurement scale peaks with extraction facilities. Emerging demand concentrates in building materials retrofit projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in Germany and China, while consumption gravitates toward Australia's Pilbara iron ore corridor and China's Shanxi coal belt. This geographic split shapes procurement patterns and regulatory compliance requirements across extraction facilities worldwide.
Australia
Pilbara iron ore handlers drive specification requirements for 300-850 millimeter diameter systems with 10,000+ ton per hour capacity. The country's environmental protection frameworks mandate spillage elimination across remote extraction sites. Western Australian operators prioritize weatherproof enclosure and steep incline capability for deep-pit copper transport.
China
Shanxi and Inner Mongolia coal corridors generate concentrated retrofit demand as MEE ambient air quality benchmarks tighten enforcement. The country's dual carbon goals accelerate replacement of open trough systems with enclosed tubular designs. Domestic steel cord supply chains reduce procurement exposure for high-tensile belt configurations in abrasive ore service.
Germany
Lignite belt operators and cement manufacturers retrofit pipe belts to comply with EU Industrial Emissions Directive particulate matter limits. ECHA restrictions on rubber plasticizers force compound reformulations across European supply chains. Bavarian and North Rhine-Westphalian facilities balance dust containment with abrasive limestone and clinker wear.
Chile
Atacama copper belt mining camps prioritize modular installation designs for rapid redeployment and reduced civil works. The country's mining code maturity supports service contract unbundling between equipment purchase and maintenance. Northern extraction districts specify zinc-coated steel cord reinforcement for 20+ kilometer overland routes.
Canada
Athabasca oil sands operations demand prefabricated sections with minimal environmental disturbance for camp mobility. Provincial regulators enforce tailings management protocols that favor enclosed conveying systems. Alberta's remote mining infrastructure prioritizes rapid belt changeout capabilities and cross-contamination prevention.
Pipe Belt Conveyor Market Competitive Landscape
Top-tier vendors anchor premium steel cord supply, while mid-tier fabricators compete on modular system integration and regional service density. The vendor landscape stratifies around polymer expertise, minerals processing heritage, and fixed-installation engineering capability. Three archetypes dominate: diversified industrial conglomerates with captive belting divisions, specialized conveying system integrators, and rubber compound specialists extending into finished belt fabrication. Consolidation pressure runs through backward integration into steel cord supply and geographic expansion into Australia's Pilbara corridor.
Within the diversified industrial tier, Continental AG represents polymer-to-system integration, while Metso exemplifies minerals processing heritage extending into downstream bulk handling. BEUMER Group occupies a position as a specialized system integrator spanning fixed and modular installations. These three anchors illustrate how competitive positioning depends on whether vendors control formulation chemistry, mechanical integration, or full-system design.
| Leading Market Players |
|---|
| Continental AG |
| FLSmidth A/S |
| Metso |
| BEUMER Group |
| Fenner Dunlop |
| Sempertrans |
| Bridgestone Corporation |
| ABB |
| Fives |
| Others |
Pricing and Supply Chain Analysis
EU Industrial Emissions Directive compliance gates qualified supply for pipe belt conveyor procurement, restricting premium-tier pricing access to vendors with REACH-certified rubber formulations and zinc-coated steel cord integration capabilities. Mining operators in Germany and Poland face extended qualification timelines that compress buyer negotiation leverage while elevating compliant suppliers' pricing power.
Pricing Analysis
Margin tightening in steel cord configurations reflects concentrated Asian metallurgical supply and REACH-driven compound reformulation costs. Three-tier pricing structure across premium, standard, and economy levels differentiates zinc-coated reinforcement grades, MEE certification status, and bundled installation services. Cost-down pressure on continuous belt alternatives accelerates as Chinese domestic supply expands. Cement manufacturers in Poland exhibit highest price sensitivity due to retrofit budget constraints, while Pilbara iron ore operators prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Refurbishment flows for steel cord pipe belts create secondary supply channels that moderate raw material demand volatility in Germany, China, and Japan. Manufacturing draws from concentrated Asian steel cord production, specialized rubber compound blending in Germany, and modular fabrication in Canada. Single-source vulnerability in zinc-coated wire metallurgy exposes procurement to commodity price swings. Distribution runs through direct OEM relationships for large mining contracts and regional belting distributors for retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified steel cord splicing technician scarcity props pricing power for vendors with captive training infrastructure, constraining supply expansion regardless of fabrication capacity additions.
For Market Incumbents: Anchor market position through backward integration into specialized rubber compound formulation and captive steel cord supply arrangements. Defend against modular system integrators by embedding IoT-enabled predictive maintenance platforms into long-term service contracts. Prioritize certification investment for MEE and REACH compliance continuity. For New Entrants and Emerging Players: Mid-tier cement retrofit contractors in Poland and Spain represent an underserved buyer archetype with unconsolidated procurement relationships. White-space concentration appears in rapid-deployment modular designs for Canada's Athabasca oil sands and Chile's Atacama copper belt. Pursue regional service density buildout ahead of equipment manufacturing scale. For Investors and Strategic Acquirers: ECHA accelerator restriction announcements are the leading indicator that compound reformulation R&D capabilities will command acquisition premiums. Long-term viability hinges on polymer chemistry expertise rather than mechanical fabrication scale. Target belting specialists with captive zinc-coated steel cord sourcing relationships. Monitor MEE enforcement intensity across Shanxi and Inner Mongolia for demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Cord Supply | Captive metallurgical sourcing insulates margin compression from Asian supply concentration. |
| REACH-Compliant Compound Reformulation | ECHA accelerator restrictions force R&D restructuring to maintain EU market access. |
| Modular System Design Expansion | Prefabricated sections capture Athabasca and Atacama camp mobility requirements. |
| IoT-Enabled Predictive Maintenance Platform | Sensor integration creates recurring service revenue beyond equipment sale. |
| Regional Service Network Density Buildout | Certified splicing technician proximity reduces downtime for remote mining operators. |
Research Methodology
Multi-period observation of MEE enforcement intensity, REACH compliance deadlines, and steel cord import patterns anchored the trend analysis, supplemented by interviews with maintenance directors at Pilbara iron ore operations, plant engineers in Germany's lignite belt, procurement leads at Shanxi coal corridor facilities, and aftermarket service heads at Canadian oil sands camps. Secondary validation drew from EU ECHA restriction proposals, China's MEE ambient air quality bulletins, German customs trade data, and SEC filings of listed industrial conglomerates. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators.
Segment-weighting across belt material type, installation configuration, and end-use intensity shaped the analytical framework throughout the projection horizon. Modeled dimensions included steel cord versus continuous belt specifications, fixed versus modular deployment, and mining transport versus cement manufacturing applications. CAGRs derived from elasticity-adjusted demand curves incorporating regulatory compliance cost pass-through assumptions. Industry-specific inputs captured REACH plasticizer substitution timelines and MEE enforcement escalation patterns.
Revisions become necessary when ECHA expands accelerator restrictions, MEE suspends enforcement in key provinces, or steel cord supply concentration shifts through new metallurgical capacity. Forecasts reflect documented assumptions regarding regulatory continuity and raw material supply stability. Practitioners should monitor ECHA consultation timelines, MEE inspection frequency reports, and Asian steel cord export licensing changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Bop Handling Systems Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Tube Rotator Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Global Precision Gearboxes Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Air/Pneumatic Balancers Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Europe Port Equipment Market