
 Wagon Tipplers Market | 2026-2036
Wagon Tipplers Market Size, Share, and Industry Trends Forecast 2026-2036
Wagon Tipplers Market Analysis
ISO 9001 certification for quality management systems in heavy bulk-material handling is redrawing the competitive threshold for new entrants. Thyssenkrupp Industrial Solutions leverages its captive steelmaking heritage to sustain in-house fabrication of high-load tipping platforms. TRF Limited anchors its position through deep relationships with Indian Railways and domestic mining conglomerates. Elecon Engineering competes on geographic density, with manufacturing and service networks concentrated across India's industrial corridors.
Wagon tipplers are heavy-duty railcar unloading machines engineered to rotate entire freight wagons up to 175 degrees, discharging bulk commodities through gravity discharge at rates exceeding 25 cycles per hour. The equipment integrates reinforced steel frames, hydraulic or electromechanical drive systems, and wagon clamping mechanisms designed to handle axle loads surpassing 32 tons in modern unit-train configurations. Mechanical tipplers retain the largest installed base across mature mining districts, though hydraulic systems command premium positioning where dust suppression and precision control justify higher capital outlay. Automated technology segments attract disproportionate interest from power generation end users seeking to reduce cycle times and labor exposure at coal receipt yards. Mining applications dominate current procurement volumes, while waste management represents an emerging specification pathway as landfill operators adopt rail-fed transfer stations.
The Ministry of Environment, Forest and Climate Change in India mandates dust-control enclosures at coal handling plants, directly influencing tippler hood and suppression-system specifications. CE marking under the EU Machinery Directive shapes export-design protocols for manufacturers serving European bulk terminals or EEA-linked mining operations. OSHA fall-protection standards in the United States dictate platform guarding and access-ladder configurations for tippler installations at North American aggregate facilities. Stakeholders must weigh the capital trade-off between retrofitting legacy mechanical units and specifying fully automated hydraulic systems that align with tightening safety and emissions protocols across multiple jurisdictions.
Market Dynamics
Coal-fired power utilities across India and Southeast Asia are accelerating replacement cycles for aging mechanical tipplers, forcing suppliers to reconcile legacy platform compatibility with automated hydraulic specifications demanded by tightening environmental and safety protocols.
Growth Catalysts
- CE marking compliance:European bulk terminal operators require machinery certified under the EU Machinery Directive, elevating specification standards for export-oriented manufacturers and filtering out uncertified competitors from cross-border procurement.
- India's eastern mineral belt:State-run coal loaders in Jharkhand, Odisha, and Chhattisgarh are modernizing unloading infrastructure at a pace unmatched by private mining operators, concentrating near-term demand in public sector tenders.
- Dust suppression integration:The Ministry of Environment, Forest and Climate Change mandates enclosure systems at coal handling plants, directly expanding the addressable market for hooded tippler configurations with integrated suppression.
Market Restraints
- Specialized steel input volatility:High-grade structural steel for load-bearing platforms faces price swings tied to scrap metal markets and energy-intensive production costs, compressing fabrication margins for equipment builders without captive metallurgical capacity.
- Fabrication concentration:Heavy-duty tipping platform welding and machining capabilities cluster in Germany, India, and select Chinese industrial zones, creating geographic supply risk for projects requiring rapid turnaround or custom engineering.
- Extended replacement cycles:Mechanical tipplers installed in the 1990s remain operational with component-level refurbishment, delaying full-system replacement demand and elongating sales pipelines for integrated hydraulic alternatives.
Strategic Opportunities
- Waste management rail transfer:Landfill operators in Germany and the Netherlands are adopting rail-fed transfer stations for municipal solid waste, opening a specification pathway distinct from traditional mining and power generation procurement.
- ISO 9001 certification arbitrage:Mid-tier fabricators in Eastern Europe and Turkey can capture share from uncertified Asian competitors by investing in quality management systems that satisfy European bulk terminal pre-qualification requirements.
- Automated-hydraulic convergence:Integration of precision position sensors with variable-frequency drive systems enables cycle-time optimization and predictive maintenance contracts, shifting revenue models toward performance-guaranteed service agreements.
Industry Challenges
- Welding certification bottlenecks:ASME and EN 1090 qualified welders for thick-section structural steel remain scarce in emerging manufacturing hubs, constraining production scaling for complex tippler platform assemblies.
- Legacy system integration:Retrofitting automated clamping and rotation controls onto 1980s-era mechanical tipplers requires custom mechanical adapters and control system overlays, extending project timelines and eroding margin on modernization contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wagon Tipplers Market |
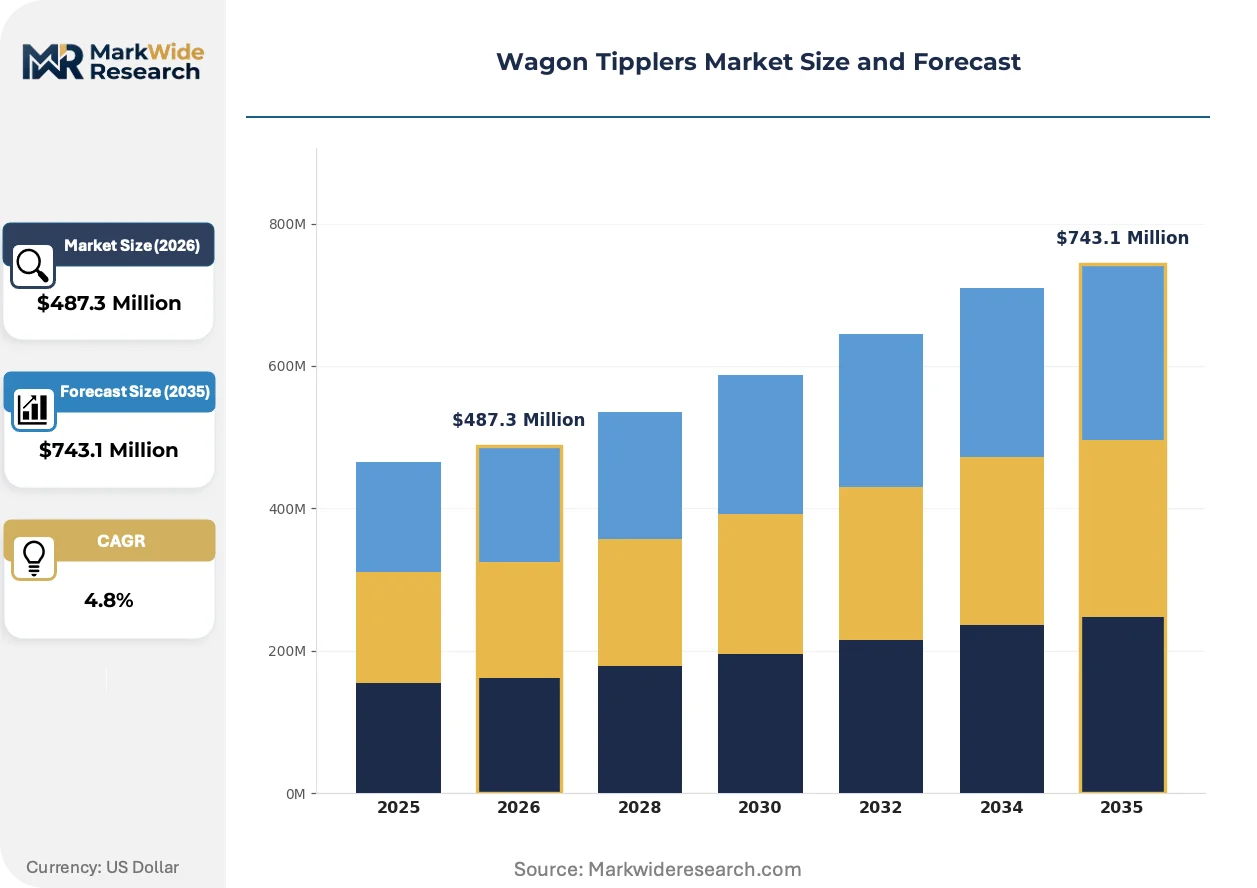
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Hydraulic, Pneumatic, Electric Technology: Automated, Manual, Semi-Automated, Remote-Controlled End User: Mining, Construction, Power Generation, Cement Application: Bulk Material Handling, Coal Transportation, Aggregate Loading, Waste Management |
| Companies Covered | Thyssenkrupp Industrial Solutions, TRF Limited, Elecon Tipplers, Tenova TAKRAF, FLSmidth, Metso Outotec, Elecon Engineering, Tecpro Systems Limited, Heyl & Patterson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wagon Tipplers Market Emerging Trajectories
Automation architectures and regulatory enclosure mandates are converging to redefine equipment specifications, while procurement patterns shift toward performance-based contracting that bundles hardware with guaranteed throughput outcomes.
Electromechanical drive systems with integrated regenerative braking are decomposing the historical dominance of pure hydraulic power transmission in high-cycle coal receipt yards. Indian power generation operators are specifying these hybrid configurations for new installations at rates exceeding prior procurement patterns. The technology is decomposing capital cost structures by reducing hydraulic fluid infrastructure and enabling modular maintenance protocols that compress downtime windows.
India's Ministry of Environment, Forest and Climate Change enforcement of dust-control enclosures at coal handling plants is mandating hooded tippler specifications that integrate pneumatic suppression and negative-pressure containment. Equipment fabricators must now engineer structural frames that accommodate enclosure loads without compromising rotation dynamics or maintenance access. Mining operators in Jharkhand and Odisha are responding by bundling enclosure specifications into single-source procurement packages rather than retrofitting post-installation.
After-sales service unbundling is fragmenting traditional maintenance relationships as power utilities separate preventive maintenance contracts from original equipment supply agreements. Independent service providers with regional stocking depots are displacing manufacturer-direct service organizations in India's industrial corridors. This pattern is most visible among state-run coal loaders in eastern India seeking to reduce long-term vendor lock-in and accelerate response times for critical component failures.
Wagon Tipplers Market Segmentation
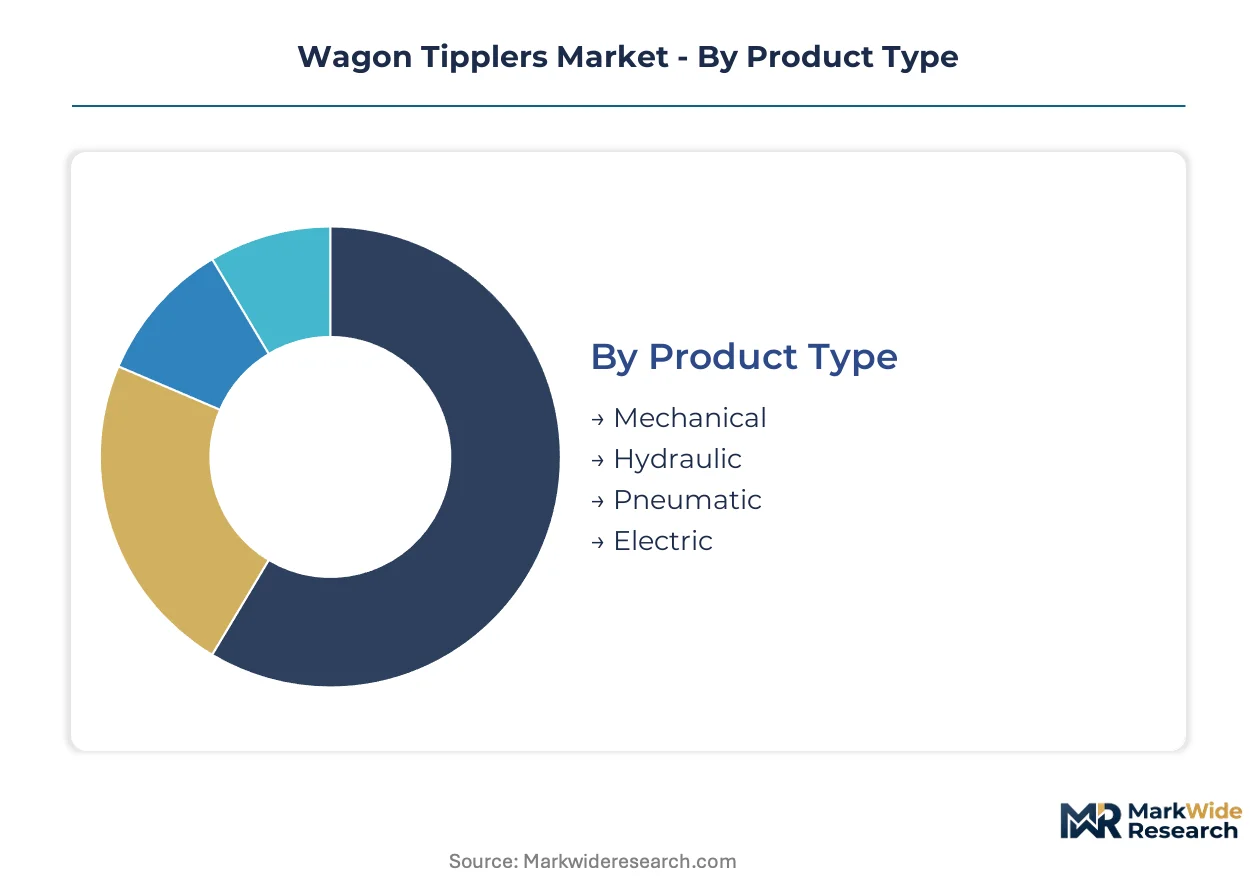
Segmentation in the wagon tipplers market reveals how procurement channels align with operational intensity and regulatory exposure. Buyers route high-specification orders through engineering-procurement-construction contractors, while direct manufacturer relationships dominate replacement cycles and component sourcing.
Product Type:
Channel mix varies sharply by drive mechanism, with hydraulic and electric systems flowing through specialized bulk-material handling integrators while mechanical units move through domestic fabrication networks and mining equipment distributors.
- Mechanical:Gear-driven rotation systems with electromechanical clamping dominate legacy installations across Indian coal belts and Australian iron ore districts. State-run loaders in Jharkhand and Odisha favor mechanical tipplers for refurbishment projects where existing civil foundations constrain capital replacement budgets.
- Hydraulic:Precision fluid-power drives enable variable rotation speeds and integrated dust-suppression actuation. Power generation utilities in Southeast Asia specify hydraulic configurations to meet Ministry of Environment, Forest and Climate Change enclosure mandates at greenfield coal receipt yards.
- Pneumatic:Compressed-air actuation serves niche applications in explosive atmospheres and remote sites lacking electrical infrastructure.
- Electric:Servomotor-driven systems with regenerative braking reduce energy consumption at high-cycle operations.
Mechanical tipplers dominate installed base. Hydraulic configurations are where expansion concentrates.
Technology:
Cost tier stratification separates premium automated systems from mid-market semi-automated units and economy-grade manual installations.
- Automated:Programmable logic controllers with position feedback sensors enable unmanned operation and predictive maintenance scheduling. Indian power utilities deploy automated tipplers at ultra-mega power plants to minimize labor exposure and optimize cycle times against dispatch commitments.
- Manual:Operator-controlled rotation and clamping persists at small-scale mining operations and temporary construction sites with low throughput requirements.
- Semi-Automated:Partial mechanization with manual override capabilities bridges upgrade pathways for mid-life mechanical tipplers.
- Remote-Controlled:Radio-frequency operation from protected command centers addresses OSHA fall-protection requirements at North American aggregate facilities.
Manual systems anchor legacy infrastructure. Automated technology is climbing the fastest as procurement shifts toward performance-guaranteed contracting.
End User:
Application maturity drives specification divergence, with mining and power generation demanding heavy-duty platforms while construction and cement users prioritize mobility and rapid deployment.
- Mining:High-axle-load configurations exceeding 32 tons handle iron ore, bauxite, and coal unit trains. Australian and Brazilian bulk exporters specify mining-grade tipplers with reinforced frames for 24-hour continuous operation.
- Power Generation:Enclosed hood designs with pneumatic dust suppression satisfy environmental compliance at coal-fired plants. Indian state electricity boards concentrate procurement in the eastern mineral belt where rail-fed generation capacity clusters.
- Construction:Portable or skid-mounted tipplers serve temporary aggregate unloading at infrastructure project sites.
- Cement:Moderate-duty rotation systems handle limestone, clinker, and petcoke receipt at integrated cement plants.
Mining commands current procurement volume. Power generation represents the steepest expansion trajectory as coal-fired capacity additions proceed in South and Southeast Asia.
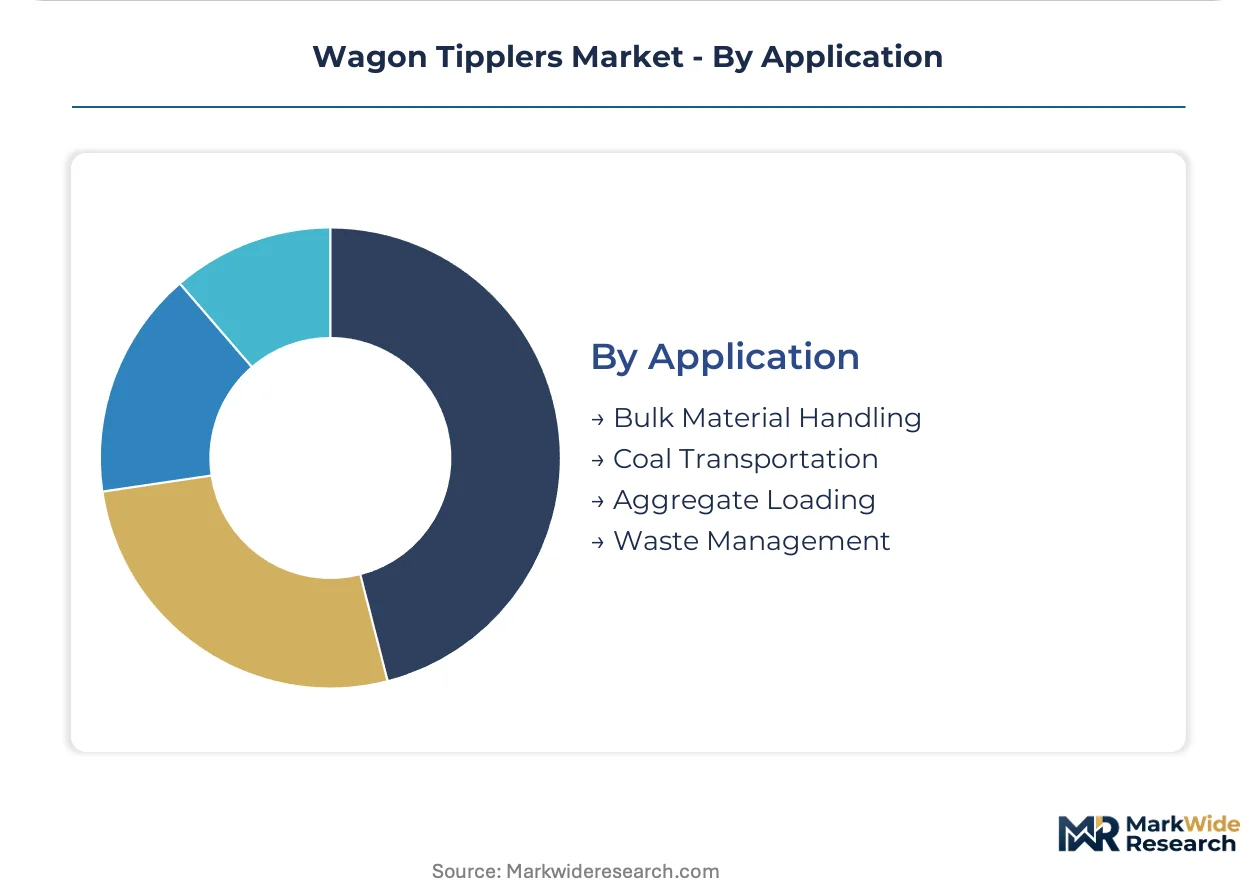
Application:
Geographic supply concentration shapes specification standards, with bulk material handling and coal transportation following mining and power generation demand clusters while waste management emerges in European municipal infrastructure.
- Bulk Material Handling:Generic-purpose tipplers serve multi-commodity terminals handling iron ore, grains, and fertilizers. Port authorities in India and Australia specify versatile configurations to maximize equipment utilization across cargo cycles.
- Coal Transportation:Dedicated high-cycle systems with dust enclosures dominate procurement from Indian and Indonesian coal-fired utilities. CE marking compliance filters supplier pools for European coal terminal modernization.
- Aggregate Loading:Construction-material tipplers with rapid clamp-release mechanisms serve crushed stone and sand operations.
- Waste Management:Sealed containment designs with negative-pressure ventilation address odor and leachate control at rail-fed landfill transfer stations in Germany and the Netherlands.
Coal transportation anchors near-term demand. Waste management is gaining share fastest as European municipalities expand circular economy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Ministry of Environment, Forest and Climate Change mandates dust-control enclosures at coal handling plants, concentrating procurement in the eastern mineral belt where state-run loaders modernize aging infrastructure. Germany's CE marking requirements under the EU Machinery Directive filter supplier pools for European bulk terminal modernization. Australia's mining-grade specifications for 24-hour continuous operation drive demand for reinforced high-axle-load configurations.
India
State-run coal loaders in Jharkhand, Odisha, and Chhattisgarh drive replacement demand for aging mechanical tipplers. The Ministry of Environment, Forest and Climate Change mandates dust-control enclosures at coal handling plants, directly influencing hooded tippler specifications. Manufacturing and service networks concentrate across India's industrial corridors, with fabrication capabilities clustered in Gujarat and Maharashtra supporting eastern belt deployment.
Germany
Landfill operators adopt rail-fed transfer stations for municipal solid waste, opening specification pathways distinct from traditional mining procurement. CE marking under the EU Machinery Directive shapes export-design protocols for manufacturers serving European bulk terminals. Heavy-duty tipping platform welding and machining capabilities concentrate in the Ruhr industrial region, creating geographic supply advantages for rapid-turnaround projects.
Australia
Bulk exporters specify mining-grade tipplers with reinforced frames for iron ore unit trains operating 24-hour continuous cycles. The country's national occupational health and safety regulator mandates fall-protection standards that dictate platform guarding configurations. Port authorities in Western Australia specify versatile multi-commodity configurations to maximize equipment utilization across iron ore, grains, and fertilizer cargo cycles.
United States
OSHA fall-protection standards dictate platform guarding and access-ladder configurations at North American aggregate facilities. Power generation utilities in the Powder River Basin accelerate replacement cycles for aging mechanical tipplers. Engineering-procurement-construction contractors in the Midwest handle high-specification orders for enclosed hood designs at coal-fired plants.
China
State-owned mining conglomerates modernize unloading infrastructure in Shanxi and Inner Mongolia coal districts. The Ministry of Ecology and Environment enforces dust-emission controls at bulk material handling facilities, driving specification upgrades. Fabrication capabilities cluster in Shandong and Jiangsu provinces, supporting domestic supply chains for high-load tipping platforms.
Wagon Tipplers Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded industrial conglomerates leveraging captive steelmaking heritage against focused fabrication houses. The vendor base stratifies into three tiers: integrated industrial groups with in-house metallurgical capacity, regional specialists with deep domestic procurement relationships, and mid-tier fabricators competing on quality management certification arbitrage. Dominant competitive moves include strategic partnerships with state-run coal loaders for long-term service contracts and geographic expansion through regional stocking depots that displace manufacturer-direct service organizations.
Within the integrated industrial tier, Thyssenkrupp Industrial Solutions and Tenova TAKRAF occupy positions anchored by captive steelmaking heritage and in-house fabrication of high-load tipping platforms. Among India-based specialists, TRF Limited exemplifies deep relationship positioning with Indian Railways and domestic mining conglomerates, while Elecon Engineering represents geographic density strategies with manufacturing and service networks concentrated across industrial corridors. These three companies illustrate how competitive positioning diverges between metallurgical integration and domestic procurement channel control.
| Leading Market Players |
|---|
| Thyssenkrupp Industrial Solutions |
| TRF Limited |
| Elecon Tipplers |
| Tenova TAKRAF |
| FLSmidth |
| Metso Outotec |
| Elecon Engineering |
| Tecpro Systems Limited |
| Heyl & Patterson |
| Others |
Supply Flow & Price Mechanics
Fourteen-week lead times for high-grade structural steel platforms concentrate pricing power among fabricators with captive metallurgical capacity, while buyers without long-term offtake agreements absorb spot-market volatility in scrap-dependent input costs. This inventory compression rewards vertically integrated suppliers who internalize fabrication throughput and penalizes project-based bidders exposed to energy-intensive production cost swings.
Pricing Analysis
Certification level creates the primary spread between premium CE-marked hydraulic systems and uncertified mechanical alternatives. Three-tier pricing structure separates ISO 9001-compliant integrated packages from standard-grade domestic fabrications and economy refurbishment kits. Cost compression in the mid-tier is intensifying because Indian state-run loaders bundle enclosure specifications into single-source procurement, squeezing margin on post-installation retrofitting. Price-sensitive buyers in temporary construction applications favor portable mechanical units, while power generation utilities demonstrate lowest sensitivity due to performance-guaranteed contracting models.
Supply Chain Analysis
Port congestion on Hamburg-Mumbai trade lanes elevates inbound logistics costs for German-engineered drive systems and precision hydraulic components. Supply concentrates in Germany, India, and Shandong province, with heavy-duty platform welding capabilities anchored in the Ruhr industrial region and Gujarat manufacturing clusters. Fabrication rests on high-grade structural steel, specialized hydraulic actuators, and EN 1090-certified welding consumables. Single-source vulnerability runs through qualified welder pools for thick-section assemblies. Distribution runs through engineering-procurement-construction contractors for greenfield projects and direct manufacturer relationships for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASME and EN 1090 qualified welders for thick-section structural steel remain scarce across emerging manufacturing hubs, constraining production scaling and consolidating margin capture among incumbents with certified fabrication workforces.
For Market Incumbents: Shield installed-base relationships by converting preventive maintenance contracts into performance-guaranteed service agreements with predictive maintenance telemetry. Expand regional stocking depots across India's industrial corridors to displace independent service providers encroaching on aftermarket revenue. Certification investment in ISO 9001 and CE marking compliance elevates specification barriers against uncertified Asian competitors bidding on European bulk terminal modernization. For New Entrants and Emerging Players: After-sales service fragmentation in India's eastern mineral belt offers white-space entry where state-run coal loaders unbundle maintenance from original equipment supply. Target waste management rail transfer stations in Germany and the Netherlands, where landfill operators adopt specifications distinct from mining procurement channels. Pursue ISO 9001 certification arbitrage to capture share from uncertified competitors in European bulk terminal pre-qualification. For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle infrastructure play because mechanical tipplers installed in the 1990s remain operational only through component-level refurbishment, elongating pipelines for integrated hydraulic alternatives. Acquisition targets should prioritize mid-tier fabricators with quality management certification gaps addressable through capital injection. Monitor enforcement intensity of India's Ministry of Environment, Forest and Climate Change dust-control mandates as inflection indicator for hooded tippler specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steelmaking | Captive metallurgical capacity insulates Thyssenkrupp and Tenova TAKRAF from scrap-price volatility compressing fabrication margins. |
| Regional Stocking Depot Expansion | Elecon Engineering's geographic density across Indian industrial corridors accelerates response times for critical component failures. |
| CE Marking Certification Investment | Mid-tier Eastern European fabricators capture European bulk terminal share from uncertified Asian competitors. |
| Predictive Maintenance Platform Development | Integration of position sensors with variable-frequency drives enables performance-guaranteed service agreements shifting revenue models. |
| Waste Management Specification Pathway | Landfill operators in Germany and Netherlands adopt rail-fed transfer stations opening procurement distinct from mining channels. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with maintenance directors at coal-fired utilities, plant engineers at Indian state-run loaders, OEM procurement teams, and aftermarket service heads; alongside secondary validation through customs and trade data, SEC filings of listed industrial conglomerates, and project tender databases. Bottom-up triangulation of unit shipment estimates against top-down value reconstructions anchored market sizing.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning drive mechanism, automation technology tier, end-use application intensity, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis of 1990s-era mechanical installations and greenfield procurement patterns at Southeast Asian power generation capacity additions. Forecast inputs incorporated Ministry of Environment, Forest and Climate Change enforcement trajectories and EN 1090 welding certification bottlenecks constraining supply elasticity.
Forecasts assume regulatory continuity in Indian environmental enforcement and EU Machinery Directive certification requirements; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Low Clearance Loaders Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Electric Tugger Market
Material Handling Equipment
Drum Dumper Market
Material Handling Equipment
Lifting Machinery Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Global Submersible Slurry Pumps Market
Material Handling Equipment
Slag Handling Equipment Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Telescopic Crane Market