
 Circular Stacker and Reclaimer Market | 2026-2036
Circular Stacker and Reclaimer Market Size, Share, and Industry Trends Forecast 2026-2036
Circular Stacker and Reclaimer Market Insights
Digital twin integration with predictive maintenance algorithms is rewriting how circular stacker and reclaimer systems are engineered and commissioned. FLSmidth leverages its Minerals Technology Centre in Copenhagen to anchor advanced simulation capabilities for port and mining clients. Thyssenkrupp competes through its extensive service network across European bulk terminals. Dalian Huarui Heavy Industry Group dominates domestic procurement for Chinese power generation facilities.
A circular stacker and reclaimer is a continuous bulk material handling machine that combines radial stacking with slewing reclaiming operations, typically achieving throughput rates from 500 to over 10,000 tons per hour depending on boom length and bucket wheel configuration. The equipment serves to homogenize raw material piles while minimizing ground footprint through circular storage geometry. Stacker-reclaimer combination units command the largest installed base in greenfield mining projects where capital efficiency favors integrated systems. Bucket wheel technology leads in high-abrasion applications such as iron ore and coal handling due to its proven digging force and wear resistance. Conveyor system segments face margin pressure from modular belt suppliers but retain value through integration complexity.
ISO 5049 governs mechanical design and safety requirements for bulk handling equipment, while China's GB standards enforce structural welding qualifications for heavy machinery fabrication. Australia's national regulator mandates compliance with AS 4024 for machine guarding on port equipment, directly influencing procurement specifications for TAKRAF GmbH and Tidfore exports. Stakeholders must weigh automation retrofit economics against full system replacement cycles as labor costs and uptime guarantees reshape contract structures.
Market Dynamics
China's MIIT energy efficiency mandates for heavy industrial equipment are forcing simultaneous upgrades across cement, power, and port sectors, compressing replacement cycles for legacy circular stacker and reclaimer systems while elevating automation specifications in procurement tenders.
Growth Catalysts
- Clinker capacity expansion:Indian cement manufacturers are commissioning new production lines requiring high-throughput bulk material handling infrastructure to feed kilns operating above 10,000 tons per day.
- ISO 5049 harmonization:Unified mechanical design and safety standards are reducing engineering validation costs for exporters serving multiple regulatory jurisdictions simultaneously.
- Iron ore export terminal modernization:Australian port operators are replacing aging bucket wheel systems to maintain competitiveness in seaborne bulk commodity logistics.
Market Restraints
- Structural steel price volatility:Boom fabrication consumes 40-60% of total equipment mass, exposing project margins to commodity input swings.
- Fabrication concentration:Heavy machinery welding capacity clusters in China's northeastern industrial corridor, creating single-source vulnerability for non-domestic buyers.
- Bucket wheel wear limitations:High-abrasion iron ore applications demand quarterly component replacement, elevating total cost of ownership versus alternative stacking technologies.
Strategic Opportunities
- Southeast Asian greenfield cement:Vietnamese and Indonesian producers are building integrated clinker-grinding complexes lacking legacy equipment constraints.
- Digital twin commissioning:Virtual simulation environments are compressing site acceptance timelines and reducing startup risk for complex slewing systems.
- Australia AS 4024 compliance services:Mandated machine guarding standards create recurring revenue streams for retrofit engineering and certification documentation.
Industry Challenges
- Slewing bearing specialist scarcity:Fewer than twelve global suppliers manufacture the large-diameter roller bearings required for 60+ meter boom rotation, extending lead times to 26 weeks.
- Legacy DCS integration friction:Brownfield sites running proprietary control architectures face protocol translation complexity when adding modern automation layers.
- Commissioning engineer mobility:Visa processing delays for specialized erection supervisors are stretching project handover schedules across multiple continents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circular Stacker and Reclaimer Market |
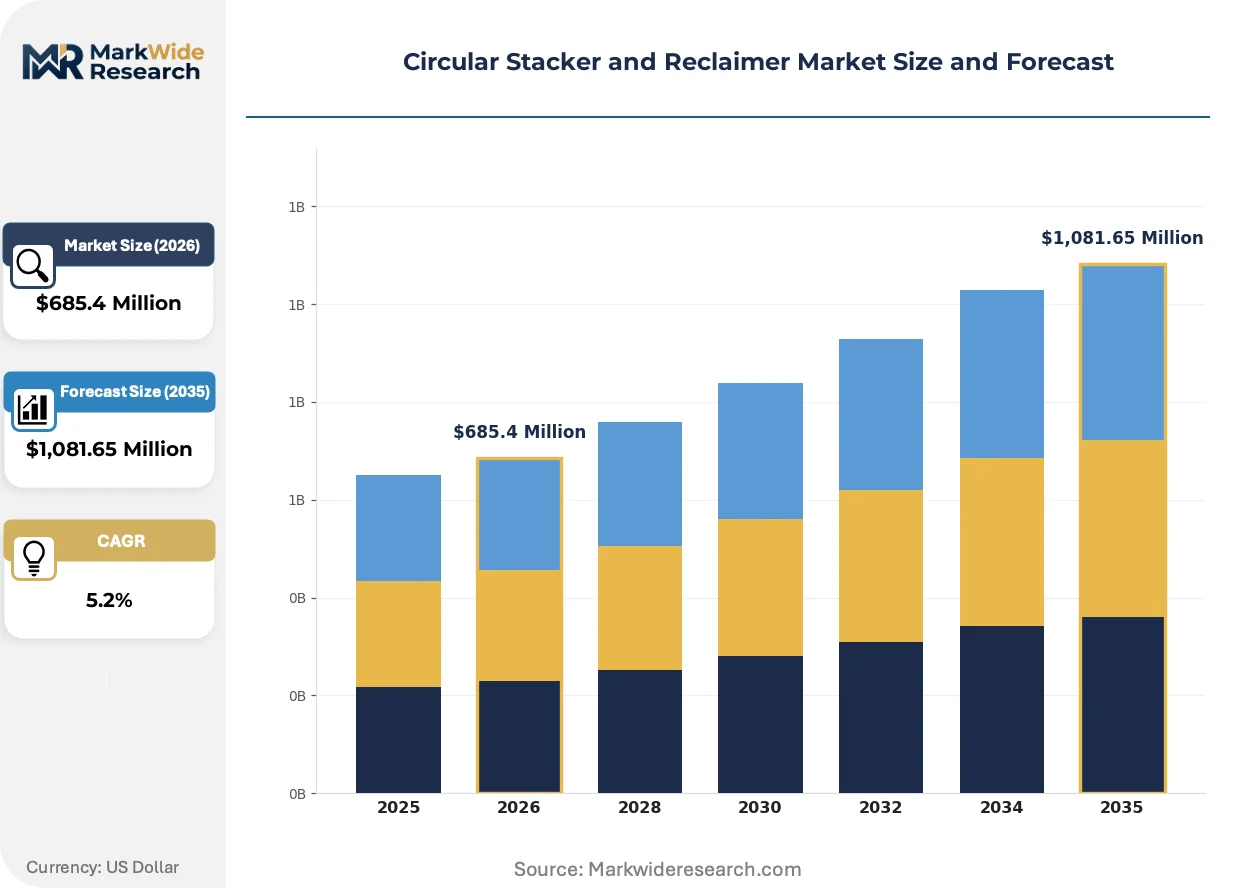
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Stacker, Reclaimer, Stacker-Reclaimer Combination, Conveyor System Technology: Cable Reel, Scraper Conveyor, Walking Beam, Bucket Wheel, Bridge Type, Portal Type Application: Coal Handling, Mineral Processing, Bulk Material Storage, Cement Manufacturing, Steel Production End User: Mining Operations, Bulk Terminals, Heavy Industry Plants, Power Generation Facilities |
| Companies Covered | FLSmidth, Metso Outotec, Thyssenkrupp, TAKRAF GmbH, Dalian Huarui Heavy Industry Group, Tidfore, Dalian SDA Heavy Industries, Changzhong Machinery, Nantong Rainbow Heavy Machineries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circular Stacker and Reclaimer Market Trends and Innovations
Automation architectures are migrating from centralized programmable logic controllers to distributed edge computing nodes, enabling real-time pile modeling without proprietary hardware lock-in. This shift is compressing the value capture traditionally held by integrated system vendors.
Machine vision pile profiling combined with LiDAR-based boom positioning is rendering obsolete manual surveyor-assisted stacking operations in high-throughput export terminals. Australian iron ore ports adopted this sensor fusion approach during their most recent capacity expansion wave. The technology is compressing homogenization accuracy variance from ±8% to ±3%, eliminating re-blending penalties in contract settlements.
China's GB standards enforcement for structural welding qualifications is tightening fabrication access for non-certified suppliers serving power generation clients. The MIIT inspection regime now requires third-party witness of critical seam radiography. European and Australian procurement specifications are incorporating these same qualification requirements by reference, extending Beijing's regulatory influence beyond its domestic market.
Performance-based maintenance contracting is displacing time-and-materials service agreements in mining sector procurements. Equipment availability guarantees now transfer operational risk from site operators to original manufacturers. This model is most visible in Western Australian iron ore hubs where labor cost inflation has made captive maintenance crews economically unsustainable.
Circular Stacker and Reclaimer Market Segmentation
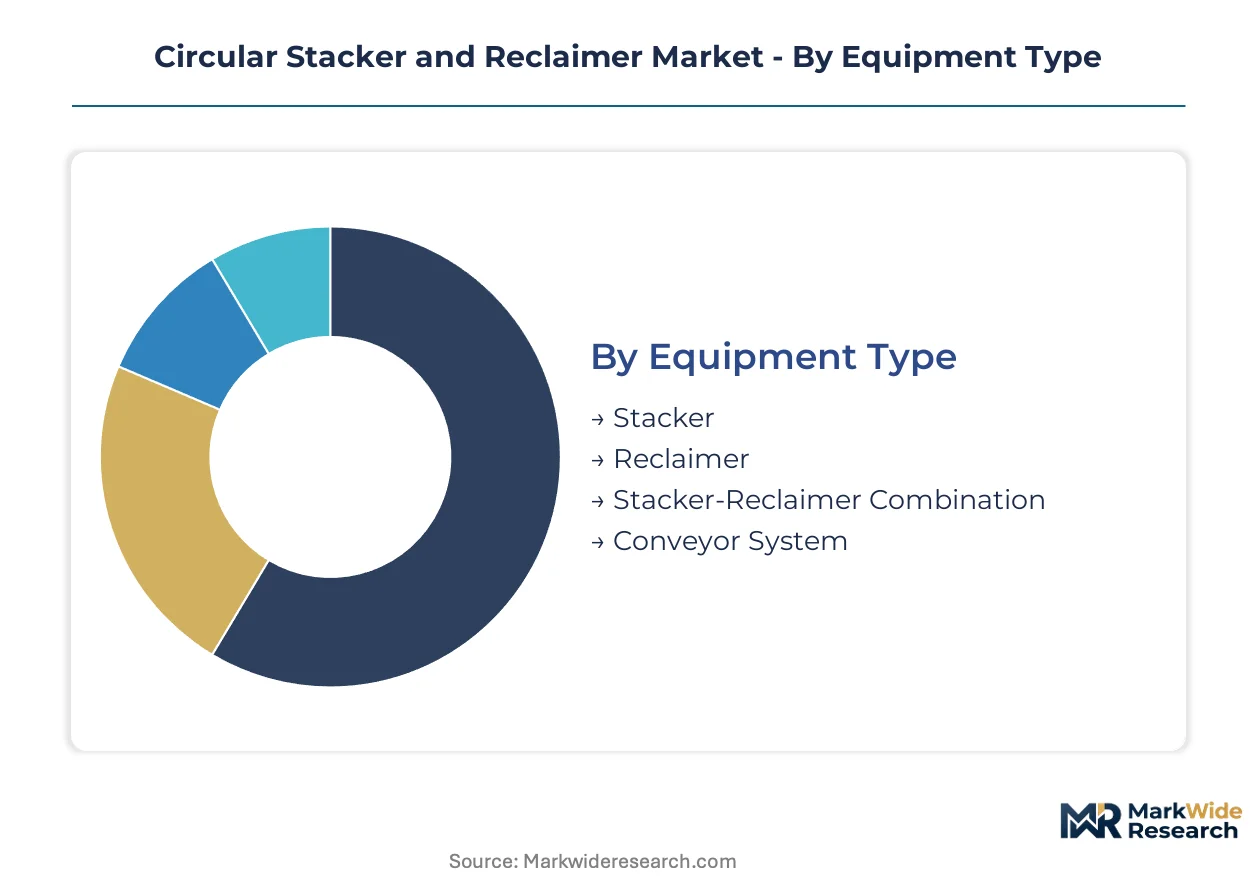
Circular stacker and reclaimer procurement patterns diverge sharply across equipment configurations, technology choices, and end-use environments. Understanding these segment boundaries clarifies where capital deployment concentrates and which specifications command premium engineering investment.
Equipment Type:
Mature integrated systems dominate greenfield mining budgets while standalone units serve retrofit flexibility needs.
- Stacker:Dedicated radial stacking machines achieve pile heights exceeding 20 meters through luffing boom mechanisms. Australian iron ore export terminals specify these for dedicated stacking lanes where reclaiming occurs through separate bucket wheel units.
- Reclaimer:Slewing bridge reclaimers with bucket wheel cutting heads deliver throughputs above 5,000 tons per hour in high-volume coal handling. India's power generation sector procures these for coastal import terminals feeding coastal thermal plants.
- Stacker-Reclaimer Combination:Integrated units reduce civil foundation costs by 30-40% versus separate machines. Chinese cement producers favor these for circular storage yards where footprint constraints override operational specialization.
- Conveyor System:Modular belt and pipe conveyor segments face margin compression from specialized suppliers but retain value through integration complexity with slewing mechanisms.
Stacker-reclaimer combination units retain volume leadership; conveyor system segments hold the steepest expansion curve through retrofit automation integration.
Technology:
Cost tiers separate proven mechanical digging systems from emerging automated positioning architectures.
- Bucket Wheel:Proven cutting technology handles iron ore abrasiveness through replaceable lip segments and hardened tooth configurations. Western Australian port operators mandate this technology for contractually guaranteed availability exceeding 90%.
- Portal Type:Gantry-mounted structures span 60-meter pile diameters with central column support minimizing ground loading. Chinese power utilities specify portal configurations for coastal coal terminals exposed to typhoon wind loading.
- Cable Reel:Power and control cable management systems enable continuous rotation without slip-ring maintenance.
- Scraper Conveyor:Chain-and-flight mechanisms reclaim fine materials below 50mm particle size with minimal degradation.
- Walking Beam:Linear pile advance systems suit longitudinal storage geometries at steel mill raw material yards.
- Bridge Type:Twin-girder structures carry counter-rotating bucket wheels for simultaneous stacking and reclaiming.
Bucket wheel technology retains volume leadership; portal type configurations hold the steepest expansion curve in coastal wind-load environments.
Application:
Customer type differentiation separates continuous-process industries from batch-handling terminals.
- Coal Handling:High-moisture thermal coal requires covered storage domes with circular stacker-reclaimer systems achieving 360-degree pile rotation. Indonesian export terminals commission these for 10,000+ ton per hour loading rates to capesize vessels.
- Cement Manufacturing:Pre-homogenization of limestone and corrective materials demands blending accuracy within ±5% chemical variance. Vietnamese clinker producers specify automated pile profiling to reduce kiln feed variability.
- Mineral Processing:Concentrate handling at copper and nickel operations requires corrosion-resistant coatings on boom structures.
- Bulk Material Storage:Multi-commodity terminals serving grain, ore, and coal need quick-change bucket configurations.
- Steel Production:Sinter plant feed yards handle abrasive iron ore fines with hardened reclaiming mechanisms.
Coal handling retains volume leadership; cement manufacturing holds the steepest expansion curve through Asian capacity additions.
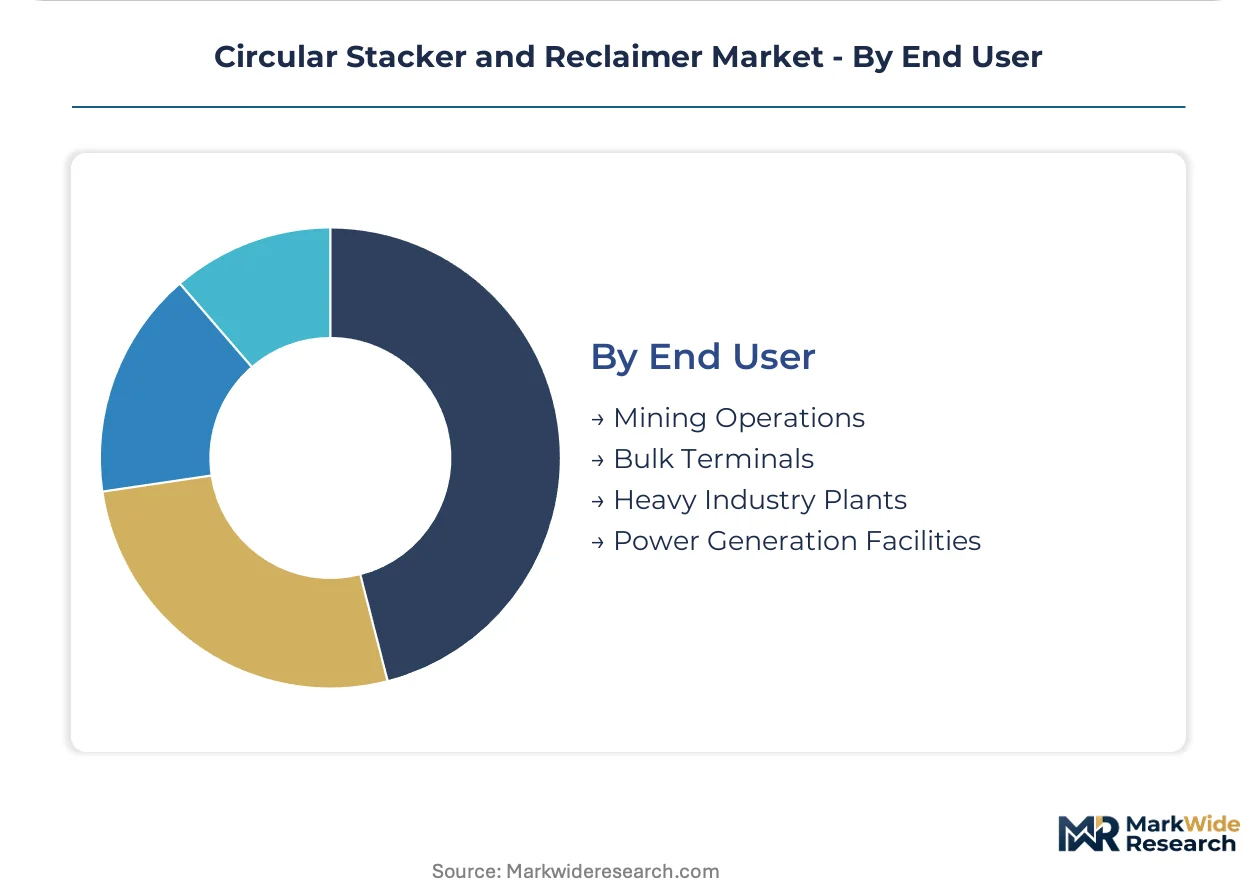
End User:
Volume scale separates dedicated mining operators from multi-commodity terminal utilities.
- Mining Operations:Captive mine-to-port systems prioritize equipment commonality across stacking and reclaiming functions to reduce spare parts inventory. Pilbara iron ore producers standardize on 70-meter boom configurations for fleet interchangeability.
- Power Generation Facilities:Coastal import-dependent plants require high-availability systems with redundant drive trains to prevent generation curtailment. India's Ultra Mega Power Projects specify dual-motor bucket wheel drives.
- Bulk Terminals:Third-party logistics operators demand flexible equipment handling multiple commodities with quick tooling changeover.
- Heavy Industry Plants:Integrated steel and aluminum producers prioritize homogenization accuracy over absolute throughput rates.
Mining operations retain volume leadership; power generation facilities hold the steepest expansion curve through import dependency growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration clusters around mining export terminals, coastal power import facilities, and integrated cement manufacturing complexes. Buyer archetypes span Australian iron ore operators, Indian Ultra Mega Power Projects, and Vietnamese clinker producers expanding homogenization capacity.
Australia
Pilbara iron ore producers drive demand for 70-meter boom configurations with 90% availability guarantees. The national regulator mandates AS 4024 machine guarding compliance for all port equipment, elevating certification requirements for imported systems. Port Hedland and Dampier terminals are replacing legacy bucket wheel reclaimers to maintain seaborne export competitiveness.
China
MIIT energy efficiency mandates compress replacement cycles across cement, power, and port sectors simultaneously. GB standards enforce third-party witness of critical seam radiography for structural welding qualifications. Dalian and Shenyang fabrication clusters dominate heavy machinery welding capacity for domestic power generation procurement.
India
Cement manufacturers commission clinker lines above 10,000 tons per day requiring high-throughput bulk handling infrastructure. CEA regulations govern coastal thermal plant equipment specifications for import-dependent generation facilities. Gujarat and Maharashtra coastal corridors concentrate Ultra Mega Power Project developments with redundant drive train requirements.
Vietnam
Greenfield clinker-grinding complexes lack legacy equipment constraints, enabling integrated stacker-reclaimer specifications. National construction standards incorporate ISO 5049 mechanical design references for bulk handling equipment. Ha Long Bay and Thanh Hoa industrial zones attract cement producers targeting ASEAN export markets.
Indonesia
Thermal coal export terminals commission covered storage domes with 10,000+ ton per hour loading rates for capesize vessels. The country's national mining regulator encloses environmental compliance specifications for port material handling equipment. Kalimantan export corridors concentrate high-moisture coal handling infrastructure investments.
Circular Stacker and Reclaimer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across differentiated procurement channels. System integrators with captive service networks capture premium positions in mining sector tenders, while fabrication-focused suppliers compete on delivery timelines for standardized power utility specifications. Two strategic archetypes dominate: vertically integrated heavy machinery conglomerates with in-house bearing and drive manufacturing, and modular equipment specialists leveraging distributed fabrication partnerships. Competitive moves concentrate on automation retrofit service contracting and geographic licensing of digital twin commissioning platforms.
Among European engineering groups, FLSmidth and Thyssenkrupp occupy positions anchoring premium-tier procurement through Copenhagen-based simulation capabilities and extensive service networks respectively. TAKRAF GmbH represents the German fabrication archetype competing on structural engineering specifications for high-wind-load coastal environments. Chinese fabricators including Dalian Huarui Heavy Industry Group and Dalian SDA Heavy Industries exemplify the domestic-market-focused tier serving state-backed power generation procurement with GB-certified welding qualifications.
| Leading Market Players |
|---|
| FLSmidth |
| Metso Outotec |
| Thyssenkrupp |
| TAKRAF GmbH |
| Dalian Huarui Heavy Industry Group |
| Tidfore |
| Dalian SDA Heavy Industries |
| Changzhong Machinery |
| Nantong Rainbow Heavy Machineries |
| Others |
Pricing and Supply Chain Analysis
Dalian and Shenyang fabrication clusters anchor heavy machinery welding capacity for circular stacker and reclaimer production, concentrating pricing leverage among GB-certified suppliers serving domestic Chinese power generation procurement while elevating entry barriers for non-certified exporters seeking access to coastal Asian cement and port developments.
Pricing Analysis
Cost-plus contracts with steel indexation dominate project procurement, insulating fabricators from raw material volatility while compressing margins for engineering-intensive automation packages. Pricing stratifies across premium, standard, and economy tiers based on automation sophistication and after-sales service bundling. Cost compression in standard-tier equipment intensifies as modular belt suppliers erode conveyor segment margins. Mining operators exhibit lowest price sensitivity due to availability guarantee requirements, while third-party bulk terminal operators prioritize capital efficiency.
Supply Chain Analysis
Contract manufacturing concentrates at Dalian Huarui Heavy Industry Group, Dalian SDA Heavy Industries, and Changzhong Machinery facilities in China's northeastern industrial corridor. Structural steel plate and large-diameter slewing bearings constitute critical inputs, with fewer than twelve global suppliers capable of producing rotation bearings for 60+ meter booms. Single-source vulnerability in bearing supply creates extended lead time exposure. Distribution runs through EPC contractors and direct OEM procurement channels for mining and power generation end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The circular stacker and reclaimer market rewards specialized engineering capabilities that resist rapid commoditization, with scarcity concentrated in slewing bearing manufacturing and certified structural welding qualifications that constrain competitive entry.
For Market Incumbents: Pre-empt automation retrofit service contracting displacement by anchoring digital twin commissioning platforms through Copenhagen and Perth engineering centers. Secure captive supply of large-diameter slewing bearings through exclusive supplier agreements before fabrication capacity tightens further. Defend against modular belt supplier encroachment by embedding conveyor integration complexity into turnkey system specifications. For New Entrants and Emerging Players: Pursue Vietnamese and Indonesian greenfield cement markets lacking legacy equipment constraints and incumbent service relationships. Target coastal power generation procurement in Gujarat and Maharashtra where CEA regulations mandate redundant drive trains that favor specialized engineering over commodity supply. Enter through AS 4024 compliance certification services for Australian port equipment retrofit demand. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automation-integrated fabricators with captive bearing supply relationships over standalone mechanical equipment producers. Long-term viability hinges on digital twin platform licensing recurring revenue rather than project-based equipment margins. Watch for MIIT enforcement intensity as the inflection signal determining replacement cycle compression across Chinese cement and power sectors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slewing Bearing Supply | Captive supply of large-diameter rotation bearings reduces lead time exposure from 26-week specialist queues. |
| Digital Twin Commissioning Platform Licensing | Copenhagen-based simulation capabilities compress site acceptance timelines for complex slewing systems. |
| AS 4024 Compliance Certification Services | Australian regulator mandates create recurring retrofit engineering revenue streams at Port Hedland and Dampier terminals. |
| Performance-Based Maintenance Contracting | Equipment availability guarantees transfer operational risk from Pilbara iron ore operators to original manufacturers. |
| Joint Venture with GB-Certified Welding Facilities | Third-party witness of critical seam radiography satisfies MIIT inspection regime for power generation procurement. |
Research Methodology
A standing panel of maintenance directors at Australian iron ore terminals, plant engineers at Indian Ultra Mega Power Projects, OEM procurement teams at European bulk handling integrators, and aftermarket service heads at Chinese fabrication clusters provided ongoing calibration. Primary interviews combined with secondary validation from customs trade data, SEC filings of listed heavy machinery producers, ISO 5049 technical documentation, and MIIT regulatory bulletins. Bottom-up equipment shipment tracking and top-down infrastructure investment pipeline analysis enabled triangulation across the analysis window.
Scenario bracketing anchored the analytical framework across equipment type, technology tier, application environment, and end-user scale dimensions throughout the projection horizon. CAGRs derived from regression analysis against clinker capacity expansion timelines, iron ore export volume forecasts, and coastal power generation commissioning schedules. Industry-specific inputs included slewing bearing supplier capacity utilization rates and GB standards enforcement intensity metrics.
Macroeconomic conditions sit as an overlay; deviation in steel price volatility, maritime freight rates, or visa processing timelines for specialized erection supervisors would shift the trajectory. Forecasts reflect documented assumptions regarding MIIT mandate implementation pace and Australian port replacement cycle timing. Quarterly review of fabrication cluster capacity utilization, bearing supplier order backlogs, and cement clinker line commissioning announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Reach Stacker Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Electric Hoist Market
Material Handling Equipment
Electric Tugger Market
Material Handling Equipment
Europe Port Equipment Market
Material Handling Equipment
Crane Mats Market
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Retractable Lift Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Torque Limiting Couplings Market
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Precision Ballscrews Market