

Steel Coil Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Coil Handling Equipment Market Insights
High-capacity overhead crane specifications above fifty tons is collapsing the legacy mid-tier equipment segment as steel producers demand integrated lifting and transport systems. Konecranes leverages its electromagnetic technology leadership to dominate premium coil handling contracts in Nordic steel mills. SMS group sustains its position through captive engineering of custom turntable systems for integrated flat-steel plants. Primetals Technologies anchors its competitive stance with digital twin integration across crane and coil car fleets.
Steel coil handling equipment encompasses mechanical systems engineered to lift, transport, rotate, and position hot-rolled and cold-rolled steel coils weighing ten to forty-five tons across production and logistics workflows. Primary configurations include overhead cranes with specialized C-hooks or electromagnetic lifters, automated coil cars with load capacities exceeding sixty tons, and hydraulic tongs designed for temperature-resistant operation up to six hundred degrees Celsius in hot mill environments. Overhead cranes command the largest installed base among product types due to universal deployment across steel mill melt shops and finishing lines. Electric and electro-mechanical technology segments are expanding fastest as operators phase out pneumatic systems to reduce energy intensity and maintenance cycles. Coil lifters and tongs represent concentrated margin pools where forged alloy construction and custom jaw geometry command premium pricing against standard catalog offerings.
OSHA crane safety standards in the United States mandate load testing and operator certification protocols that elevate compliance costs for equipment purchasers. The EU Machinery Directive and CE marking requirements enforce integrated safety systems and electromagnetic compatibility testing for coil handling equipment sold across European member states. India's BIS certification scheme imposes structural and electrical safety benchmarks on imported crane systems entering domestic steel facilities. Stakeholders must monitor regulatory divergence between prescriptive load-testing regimes and performance-based safety standards as they evaluate supplier qualification and aftermarket service commitments.
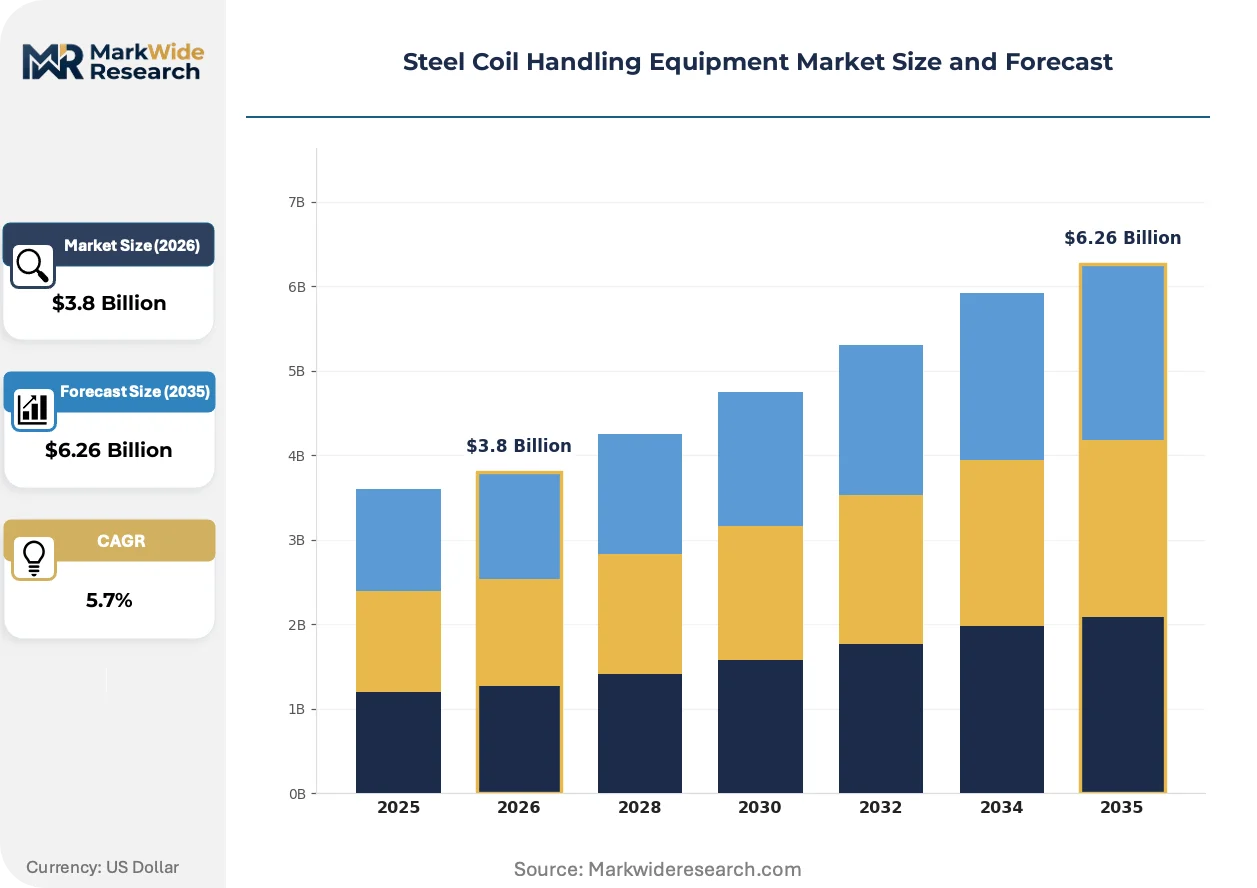
Market Dynamics
Steel coil handling equipment procurement is compressing around integrated automation stacks as mills eliminate standalone mechanical systems in favor of unified crane-car-lifter command architectures. European fabricators and Indian integrated steel plants are driving this specification shift through safety-mandated modernization programs.
Growth Catalysts
- EU Machinery Directive safety mandates:CE marking requirements for integrated safety systems are forcing replacement cycles in German and Italian metal fabrication facilities.
- Hot mill automation:Temperature-resistant hydraulic tongs rated to 600°C are expanding deployment across continuous casting-to-rolling lines.
- Ruhr industrial cluster concentration:Heavy-duty overhead crane installations above fifty tons are concentrating demand in Germany's legacy steel corridor.
Market Restraints
- Forged alloy input volatility:Specialized alloy steel prices for C-hook and tong construction create margin pressure on equipment fabricators.
- Electromagnetic lifter supply concentration:Premium electromagnetic subsystems rely on a narrow supplier base in Nordic industrial zones.
- OSHA load-testing compliance:Mandatory operator certification and load-testing protocols in the United States extend sales-to-commissioning timelines.
Strategic Opportunities
- India BIS certification pipeline:Structural and electrical safety benchmarks on imported crane systems create qualified supplier scarcity for early certifiers.
- Digital twin convergence:Integration of crane fleet telemetry with coil car positioning systems enables predictive maintenance contracts.
- Electric crane displacement:Electro-mechanical technology segments are capturing share from pneumatic systems in energy-intensive European installations.
Industry Challenges
- Electromagnetic compatibility certification:CE marking testing for coil handling equipment sold across European member states requires specialized laboratory capacity with limited throughput.
- Legacy hydraulic integration:Retrofitting automated coil cars into existing melt shop layouts demands custom turntable engineering that extends project delivery.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Coil Handling Equipment Market Trends and Innovations
Sensor-embedded lifting hardware and edge-computing control architectures are displacing centralized PLC systems in premium coil handling installations. This shift is compressing response times for load stabilization while generating operational data streams that enable predictive service models.
Electromagnetic lifter control systems are miniaturizing through solid-state power electronics that eliminate bulky transformer assemblies. Nordic steel mills are specifying these compact units for tight-headroom crane retrofits. The technology is compressing installation footprints while enabling precise load modulation that reduces coil surface damage.
India's BIS certification scheme is mandating structural load testing and electrical isolation protocols that exceed prior import requirements. Domestic steel facilities must verify compliance through accredited laboratories before commissioning. Integrated flat-steel plants are responding by pre-qualifying suppliers with established certification histories.
Buyers are unbundling after-sales service from initial equipment contracts to secure multi-vendor maintenance coverage. German automotive steel processors are leading this shift, negotiating separate crane and coil car service agreements. The practice is most visible in the Ruhr industrial cluster where equipment density supports specialized third-party service providers.
Steel Coil Handling Equipment Market Segmentation
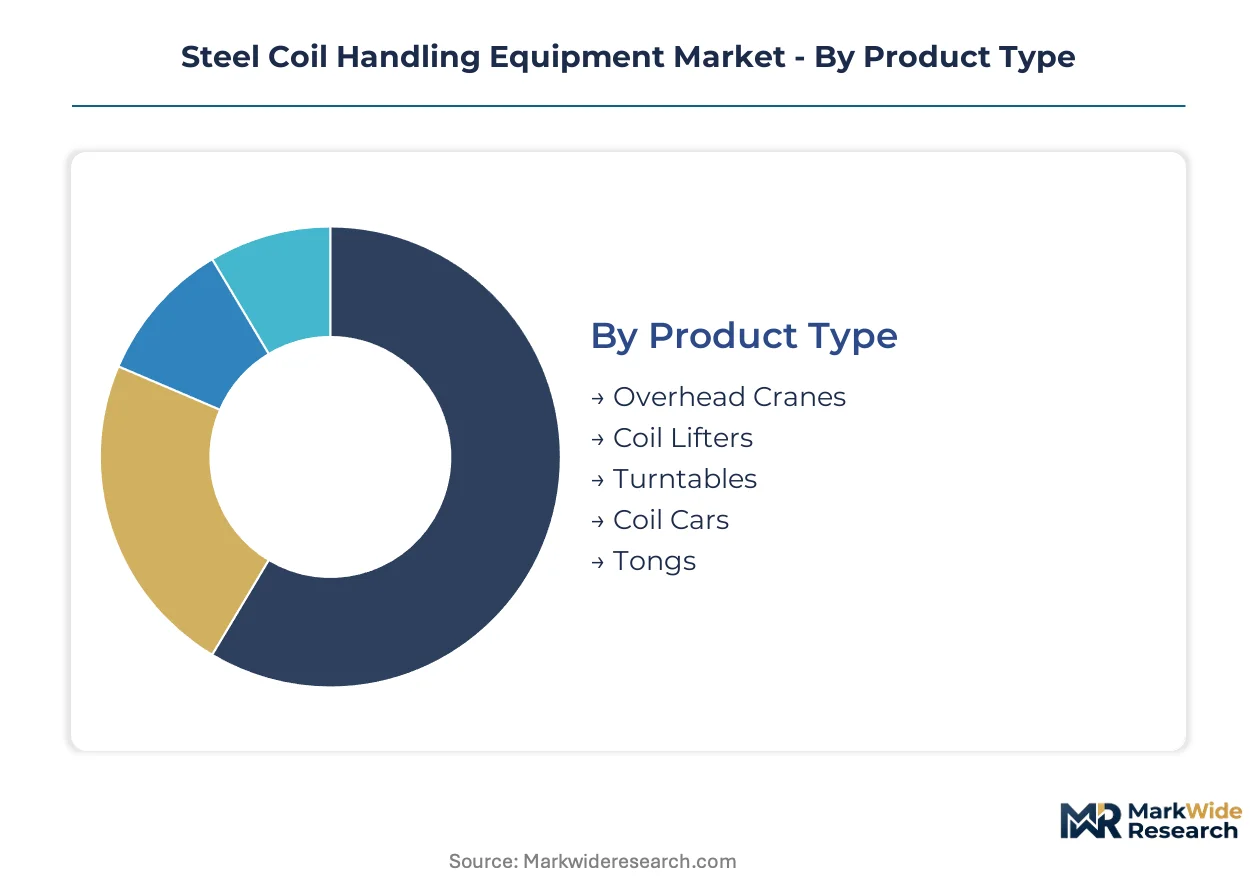
Equipment specification in steel coil handling diverges sharply by production environment. Hot mill operators demand temperature-rated systems that survive continuous thermal cycling, while cold finishing lines prioritize precision positioning over thermal resilience. Channel strategy must align with these divergent technical requirements.
Product Type:
Channel distribution varies by product complexity, with integrated crane systems flowing through direct mill relationships and standalone components moving through distributor networks.
- Overhead Cranes:Bridge-mounted systems with specialized C-hooks or electromagnetic lifters dominate melt shop and finishing line deployments. German steel producers in the Ruhr corridor are specifying units above fifty tons with integrated automation stacks. Overhead cranes command the largest installed base among all product configurations due to universal deployment requirements.
- Coil Lifters:Forged alloy C-hooks and telescoping lifters engineered for ten to forty-five ton coils represent concentrated margin pools. Custom jaw geometry and temperature-rated construction command premium positioning against standard catalog offerings. Demand concentrates in Indian integrated flat-steel plants modernizing under BIS safety mandates.
- Turntables:Rotational positioning systems for coil orientation in tight footprint layouts.
- Coil Cars:Automated rail-mounted transporters with load capacities exceeding sixty tons.
- Tongs:Hydraulic gripping systems rated to six hundred degrees Celsius for hot mill environments.
Overhead cranes dominate installed base. Coil lifters are where expansion concentrates.
Technology:
Cost tier stratification separates legacy pneumatic installations from premium electro-mechanical systems commanding maintenance contract premiums.
- Electric:Motor-driven winch and trolley systems displacing hydraulic units in European metal fabrication. Reduced energy intensity and compressed maintenance cycles drive specification shifts in energy-intensive installations. Electric segments are expanding fastest as operators phase out pneumatic alternatives.
- Electro-Mechanical:Hybrid architectures combining electric drive with mechanical braking and precision positioning. Nordic steel mills specify these systems for tight-headroom crane retrofits where solid-state power electronics eliminate bulky transformer assemblies. Miniaturized control systems enable precise load modulation that reduces coil surface damage.
- Hydraulic:Fluid-power systems retained for high-force hot mill applications.
- Pneumatic:Compressed-air systems facing phase-out due to energy intensity.
- Magnetic:Electromagnetic lifter subsystems reliant on narrow Nordic supplier bases.
Electro-mechanical systems claim the steepest expansion trajectory. Hydraulic retains defensive position in hot mill niches.
Application:
Volume concentration tracks steel consumption patterns, with metal fabrication absorbing the highest equipment density per ton of steel processed.
- Metal Fabrication:Cut-to-length and slitting operations requiring precision coil positioning. German and Italian facilities drive replacement cycles under EU Machinery Directive safety mandates. CE marking requirements for integrated safety systems force modernization of legacy mechanical installations.
- Heavy Machinery:Equipment manufacturing with thick-gauge coil requirements. Defense contractors and construction equipment producers specify heavy-duty overhead crane installations with load capacities above fifty tons. Procurement concentrates around integrated automation stacks eliminating standalone mechanical systems.
- Shipbuilding:Plate forming and section assembly with large coil formats.
- Construction Equipment:Structural component manufacturing with medium-gauge specifications.
- HVAC Manufacturing:Thin-gauge coil processing for ductwork and heat exchanger fabrication.
Metal fabrication leads equipment density. Heavy machinery anchors premium system specifications.
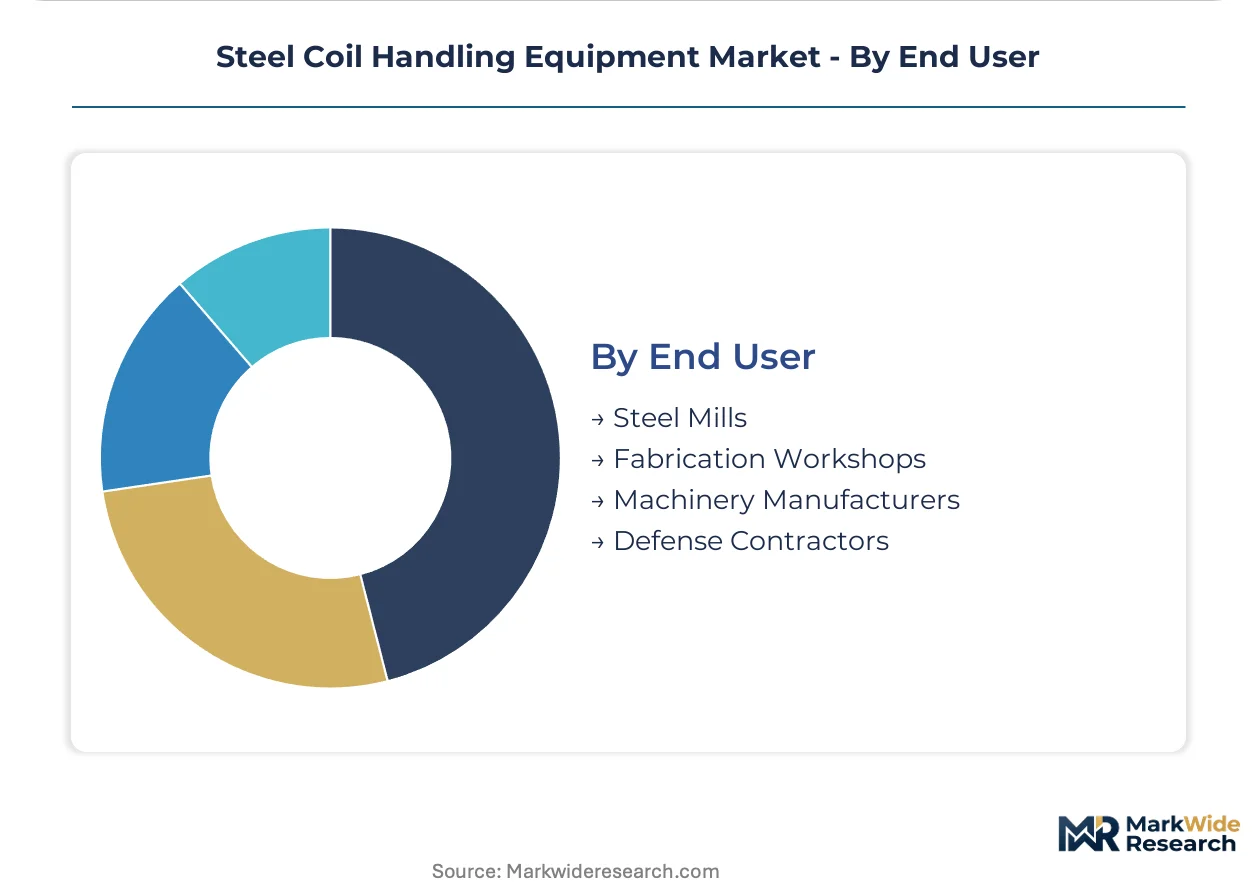
End User:
Customer type determines procurement modality, with steel mills favoring turnkey integration and fabrication workshops unbundling after-sales service.
- Steel Mills:Integrated producers from melt shop through finishing lines requiring unified crane-car-lifter command architectures. Indian mills expanding automated coil handling lines under BIS structural and electrical safety benchmarks. Pre-qualification of suppliers with established certification histories compresses vendor pools.
- Fabrication Workshops:Independent processors negotiating separate crane and coil car service agreements. German automotive steel processors in the Ruhr cluster lead unbundling of after-sales coverage from initial equipment contracts. Equipment density supports specialized third-party service providers.
- Machinery Manufacturers:OEMs integrating coil handling into production line designs.
- Defense Contractors:Security-sensitive procurement with specialized compliance requirements.
Steel mills anchor capital expenditure volume. Fabrication workshops are diversifying service provider relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabricators concentrate capacity in Germany, India, and the United States, with secondary supply nodes in Japan and South Korea. Demand fragmentation across these markets reflects divergent regulatory modernization cycles and steel industry capital expenditure patterns.
Germany
CE marking requirements under the EU Machinery Directive are accelerating replacement cycles in metal fabrication facilities. The Ruhr industrial cluster anchors heavy-duty overhead crane installations above fifty tons. Integrated automation stacks are displacing standalone mechanical systems across legacy steel corridors.
India
BIS certification mandates for structural and electrical safety are pre-qualifying suppliers with established compliance histories. Domestic steel mills are expanding automated coil handling lines under tightened import verification protocols. Integrated flat-steel plants in Gujarat and Maharashtra are compressing vendor pools through pre-commissioning laboratory accreditation.
United States
OSHA crane safety standards mandate load testing and operator certification protocols that extend sales-to-commissioning timelines. Defense contractors and construction equipment producers specify heavy-duty installations with load capacities above fifty tons. Procurement concentrates in the Midwest industrial belt where equipment density supports specialized service networks.
Japan
METI industrial efficiency guidelines are driving electro-mechanical displacement of legacy pneumatic systems. Automotive steel processors in the Chubu region are unbundling after-sales service from initial equipment contracts. Precision positioning requirements in cold finishing lines favor sensor-embedded lifting hardware.
South Korea
MFDS-equivalent industrial safety benchmarks and energy efficiency regulations are shaping equipment specification. Shipbuilding and heavy machinery sectors in the Busan-Ulsan corridor demand temperature-rated systems for thick-gauge coil processing. Domestic fabricators are capturing share in mid-capacity overhead crane segments.
Steel Coil Handling Equipment Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized crane engineering houses. The vendor base stratifies across three tiers: integrated automation providers commanding premium contracts, regional fabricators serving price-sensitive replacement cycles, and component specialists capturing margin pools in electromagnetic subsystems. Dominant competitive moves include backward integration into forged alloy supply and technology licensing partnerships for solid-state power electronics.
Among Nordic-based engineering groups, Konecranes occupies a position exemplifying electromagnetic technology leadership in premium coil handling contracts. SMS group represents the captive engineering archetype, anchoring competitive stance through custom turntable systems. Primetals Technologies sits within the digital integration tier, with its positioning reflecting predictive maintenance convergence across crane and coil car fleets.
| Leading Market Players |
|---|
| Konecranes |
| SMS group |
| ANDRITZ AG |
| Fives Group |
| Primetals Technologies |
| Toyota Industries Corporation |
| Henan Weihua Heavy Machinery |
| EMH |
| Bushman Equipment |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between steel mills and crane fabricators lock in both forged alloy supply access and price visibility across multi-year commissioning cycles. These contracts insulate equipment vendors from nickel and chromium volatility while binding buyers to fixed escalation clauses tied to BIS certification milestones.
Pricing Analysis
CE marking dictates the pricing tier structure across European coil handling procurement. Three-tier pricing structure across premium, standard, and economy levels separates electromagnetic-integrated systems from electro-mechanical retrofits and legacy hydraulic units. Price differentiation hinges on certification grade and after-sales bundling. Cost compression in the standard tier is intensifying because Indian fabricators are capturing mid-capacity crane share. Fabrication workshops in Germany's Ruhr cluster exhibit highest price sensitivity; integrated steel mills in India show least.
Supply Chain Analysis
Nordic electromagnetic subsystem production underwrites premium lifter availability across global steel corridors. Manufacturing concentrates in Germany, India, and Japan. Forged alloy C-hooks, solid-state power electronics, and temperature-rated hydraulic seals constitute critical input dependencies. Single-source vulnerability in electromagnetic coil winding creates exposure. Distribution runs through direct mill relationships for integrated systems and regional distributor networks for standalone components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel coil handling equipment operates as a regulatory-entrenchment defensive moat. BIS certification timelines and CE marking laboratory capacity constraints create sticky supplier relationships that resist displacement.
For Market Incumbents: Compound electromagnetic technology leadership through captive R&D in solid-state power electronics. Backward integration into forged alloy supply secures margin pools against nickel price spikes. SMS group and Konecranes anchor positioning through custom turntable engineering and Nordic lifter dominance respectively. Capacity addition in Gujarat addresses Indian BIS certification pipeline demand. For New Entrants and Emerging Players: Lead with digital twin integration as a service-layer wedge. Mid-capacity overhead crane segments in South Korea's Busan-Ulsan corridor present the most penetrable white space. After-sales unbundling in German automotive steel processing creates third-party maintenance entry points. Target predictive maintenance contracts as the primary go-to-market angle. For Investors and Strategic Acquirers: Component specialists with electromagnetic subsystem expertise represent the priority acquisition archetype. Long-term viability rests on regulatory certification entrenchment deepening across Indian and European safety mandates. Watch BIS laboratory accreditation backlogs as the inflection signal indicating qualified supplier scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forged Alloy Supply | Captures margin pools in C-hook and tong construction against nickel volatility. |
| Digital Twin Integration | Enables predictive maintenance contracts across crane and coil car fleets for steel mills. |
| BIS Certification Pre-Qualification | Creates qualified supplier scarcity in Indian automated coil handling line expansion. |
| Electro-Mechanical Technology Transition | Displaces pneumatic systems in European energy-intensive installations under efficiency mandates. |
| After-Sales Service Unbundling | Supports specialized third-party providers in Germany's Ruhr equipment density cluster. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across steel mill maintenance directors, plant engineers at integrated flat-steel facilities, OEM procurement teams, and aftermarket service heads. Secondary validation drew from customs trade data, BIS certification registries, SEC filings of listed crane manufacturers, and EU Machinery Directive implementation reports. Bottom-up equipment shipment analysis triangulated against top-down steel production capacity expansion tracking.
Across the analysis window, volume and value outputs reflect modeling across product type, technology segment, application environment, and end-user procurement modality. CAGRs were derived from segment-level growth rate reconciliation against macro steel output projections. Hot mill automation intensity and electromagnetic lifter penetration curves served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained steel capacity expansion in India and Germany would require recalibration. Forecasts reflect assumptions on BIS laboratory throughput and CE marking approval timelines. Practitioners should keep alternative scenarios live as electromagnetic subsystem supply concentration and forged alloy price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.